
 Europe Military Satellite Market | 2026-2036
Europe Military Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military Satellite Market Insights
Modular payload configurations is broadening buyer choice across the Europe military satellite landscape. Thales leverages its end-to-end satellite systems integration to anchor large-scale national programs in France and beyond. Airbus SE sustains dual-use manufacturing scale across civil and defense orbits, while OHB System AG specializes in compact platform architectures that compete for medium-class government contracts.
Europe military satellites comprise spacecraft purpose-built for defense applications, typically operating in geostationary, medium, or low Earth orbits with hardened electronics, anti-jam payloads, and encrypted cross-links to survive contested electromagnetic environments. Their primary purpose is to deliver sovereign, uninterrupted capabilities for surveillance, navigation, and secure communications independent of commercial infrastructure. Communications satellites command the largest share of procurement budgets due to persistent bandwidth requirements for deployed forces, while Low Earth Orbit Systems represent the fastest-expanding technology category as proliferated constellations promise reduced latency and enhanced resilience against adversarial threats.
European Defence Agency coordination, EU Space Programme governance, and national procurement frameworks such as France's LPM military programming law collectively shape demand patterns and technology roadmaps across member states. CE marking for dual-use components and emerging EU space traffic management standards further constrain supplier eligibility and product configurations. Stakeholders must monitor PESCO project maturation and national budget commitments to anticipate which capability gaps will attract consolidated funding versus fragmented national investments.
Market Dynamics
The EU Space Programme and PESCO framework are consolidating fragmented national procurement into collaborative capability development, redirecting sovereign satellite investments toward interoperable architectures rather than isolated national programs.
Growth Catalysts
- Secure communications bandwidth:Deployed European defense forces require persistent encrypted data links for command-and-control operations, pulling procurement toward hardened geostationary platforms.
- PESCO project maturation:The Permanent Structured Cooperation framework pools member state resources for shared satellite constellations, reducing per-nation capital barriers.
- Low Earth Orbit proliferation:Constellation architectures promise reduced signal latency and enhanced electromagnetic resilience against adversarial jamming.
Market Restraints
- Launch cost volatility:Dependence on Ariane and limited European heavy-lift capacity constrains deployment schedules and program budgeting.
- Component supply concentration:Radiation-hardened electronics and specialized propulsion systems source from a narrow supplier base concentrated in France and Germany.
- Dual-use export controls:EU and national licensing frameworks restrict technology transfer, complicating subcontractor selection and partner nation access.
Strategic Opportunities
- Poland and Baltic states:These NATO frontline members lack indigenous satellite manufacturing and present captive demand for hosted payload arrangements.
- Space-based missile early warning:Emerging requirement for hypersonic threat detection creates new sensor payload categories beyond traditional communications.
- Quantum key distribution:Integration of quantum encryption into optical cross-links offers sovereign key management independent of terrestrial infrastructure.
Industry Challenges
- Cleared workforce scarcity:Security-cleared satellite systems engineers and program managers remain concentrated at established primes, constraining new entrant scaling.
- Legacy ground segment integration:New space assets must interface with decades-old terrestrial command networks, adding interface complexity and test burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military Satellite Market |
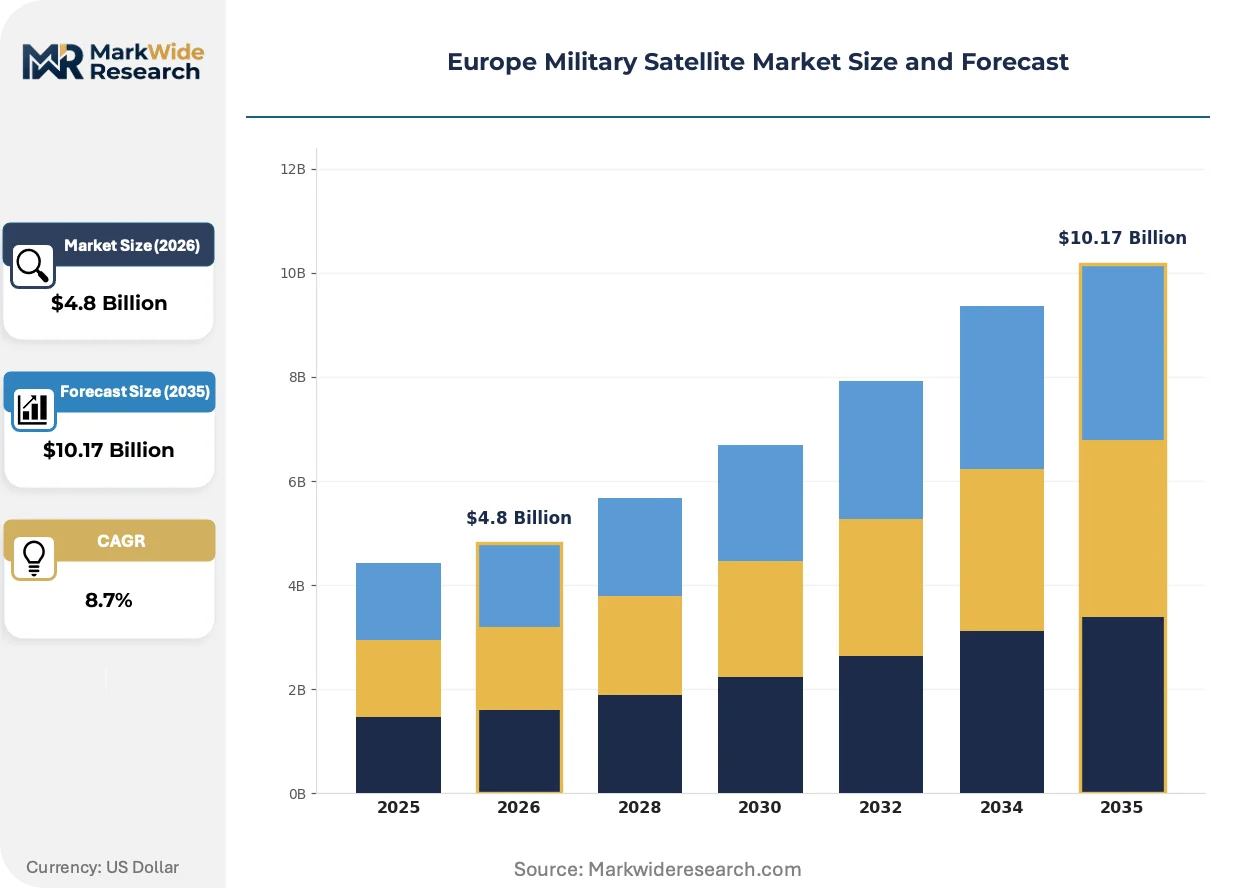
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communications Satellites, Earth Observation Satellites, Navigation Satellites, Reconnaissance Satellites Technology: High Throughput Satellites, Low Earth Orbit Systems, Geostationary Systems, Optical Communications Application: Surveillance, Secure Communications, Intelligence, Search & Rescue End User: Defense Forces, Government Agencies, Contractors, International Organizations |
| Companies Covered | Centre National D'études Spatiales (CNES), Thales, Airbus SE, OHB System AG, Information Satellite Systems Reshetnev, GomSpace ApS, ROSCOSMOS, BAE Systems, RSC Energia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military Satellite Market Trends and Innovations
Software-defined payload architectures are displacing fixed-function satellite designs, enabling orbit-reconfigurable missions that adapt to shifting threat environments without spacecraft replacement.
Artificial intelligence-driven autonomous satellite operations is automating routine station-keeping, anomaly detection, and cross-link handovers. French and German defense procurement offices are mandating AI-ready avionics in new solicitations. This compression of ground crew requirements is reshaping operational cost structures and enabling denser constellation management with fixed personnel.
CE marking for dual-use components under evolving EU space traffic management standards is tightening supplier eligibility criteria. Manufacturers must now demonstrate debris mitigation and end-of-life disposal compliance to access member state procurement channels. Small satellite specialists in Italy and Spain face particular adaptation pressure against these certification timelines.
Consolidated multi-year service contracts are replacing discrete satellite purchases among anchor nations. France's LPM military programming law now emphasizes throughput guarantees rather than asset ownership, transferring operational risk to prime contractors. This preference shift is most visible in secure communications segments, where Thales and Airbus compete on availability metrics rather than unit cost.
Europe Military Satellite Market Segmentation
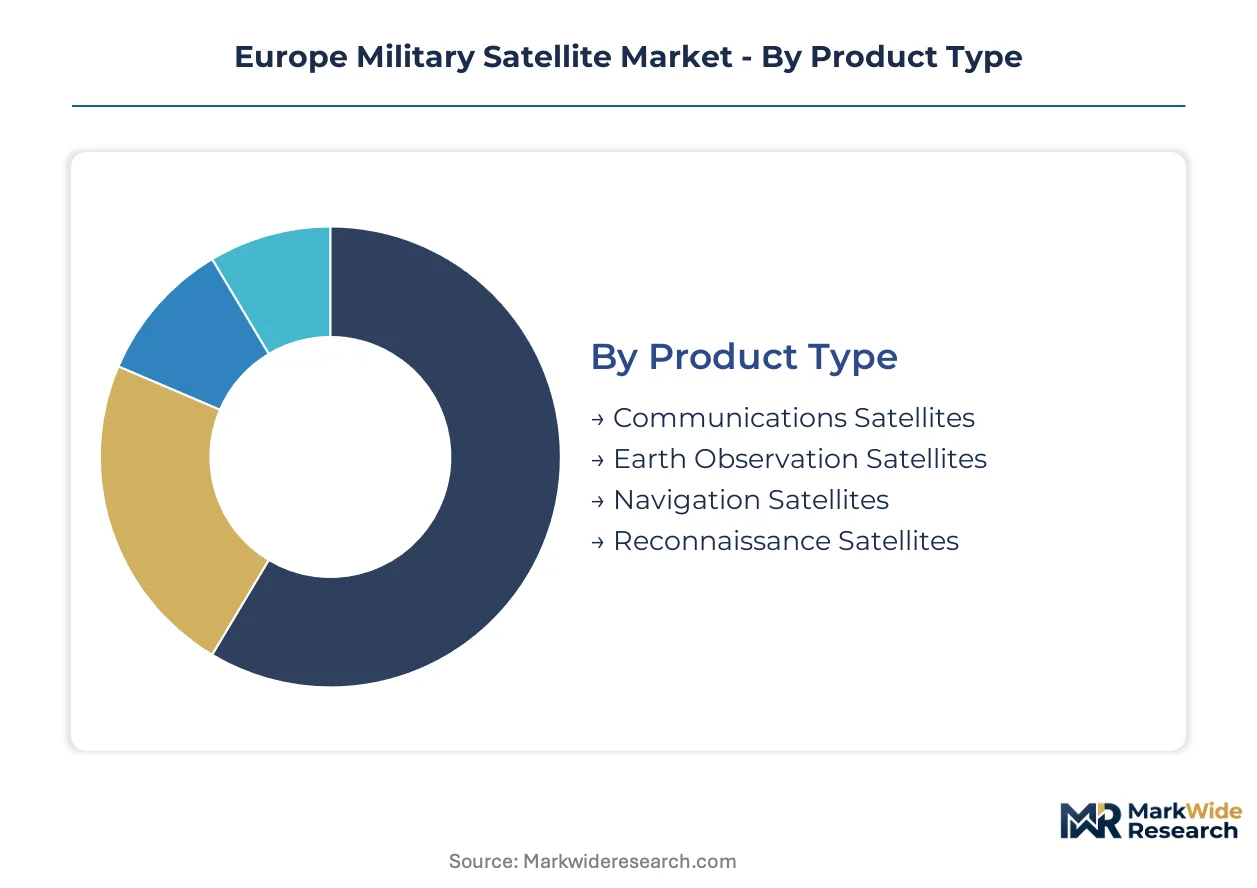
Segmentation in the Europe military satellite market reveals how procurement priorities diverge across mission requirements and operational environments. Buyers select architectures based on orbital mechanics, threat resilience, and interoperability mandates rather than unit economics alone.
Product Type:
Defense ministries differentiate spacecraft investments by mission persistence versus revisit frequency, with communications dominance reflecting bandwidth-hungry deployed operations.
- Communications Satellites:Hardened geostationary platforms deliver persistent encrypted data links for command-and-control across French and German expeditionary forces. Procurement concentrates on sovereign throughput guarantees under multi-year service contracts rather than asset ownership.
- Earth Observation Satellites:Synthetic aperture radar and electro-optical payloads provide all-weather terrain monitoring for Baltic border surveillance. Polish and Romanian defense ministries drive demand for hosted payload arrangements lacking indigenous manufacturing.
- Navigation Satellites:Military-grade signal augmentation for Galileo PRS service enables encrypted positioning independent of GPS.
- Reconnaissance Satellites:High-resolution imaging platforms support strategic target identification with limited operational disclosure.
Volume sits with Communications Satellites; growth tilts toward Earth Observation Satellites.
Technology:
Orbital altitude selection determines latency, coverage footprint, and survivability against kinetic and electronic threats.
- Low Earth Orbit Systems:Proliferated constellations of small satellites promise reduced signal latency and distributed resilience against adversarial jamming. PESCO collaborative frameworks pool member state resources for shared LEO architectures.
- Geostationary Systems:Traditional large platforms anchor sovereign communications with predictable coverage footprints. France's LPM military programming law sustains procurement of hardened GEO assets for strategic command.
- High Throughput Satellites:Spot-beam architectures multiply bandwidth density for theater operations.
- Optical Communications:Laser cross-links enable terabit-class data relay with minimal detectable footprint.
Procurement mass rests with Geostationary Systems; capability investment is climbing fastest in Low Earth Orbit Systems.
Application:
Mission type dictates payload configuration, with bandwidth-intensive applications commanding premium platform specifications.
- Secure Communications:Encrypted voice, data, and video transmission for deployed headquarters and naval task forces absorbs the largest share of national space budgets. Thales and Airbus compete on availability metrics under France's throughput-based contracting model.
- Surveillance:Persistent area monitoring for border integrity and maritime domain awareness relies on integrated radar and optical sensors. Baltic and Mediterranean littoral states prioritize this application for frontline situational awareness.
- Intelligence:Signals interception and measurement collection require specialized ELINT payloads with classified processing chains.
- Search & Rescue:Distress beacon detection and localization leverages hosted payloads on multi-mission platforms.
Budget concentration favors Secure Communications; capability gaps are widening fastest in Intelligence.
End User:
Institutional buyer type shapes contracting mechanisms, with defense ministries driving sovereign requirements and international bodies enabling cost-sharing.
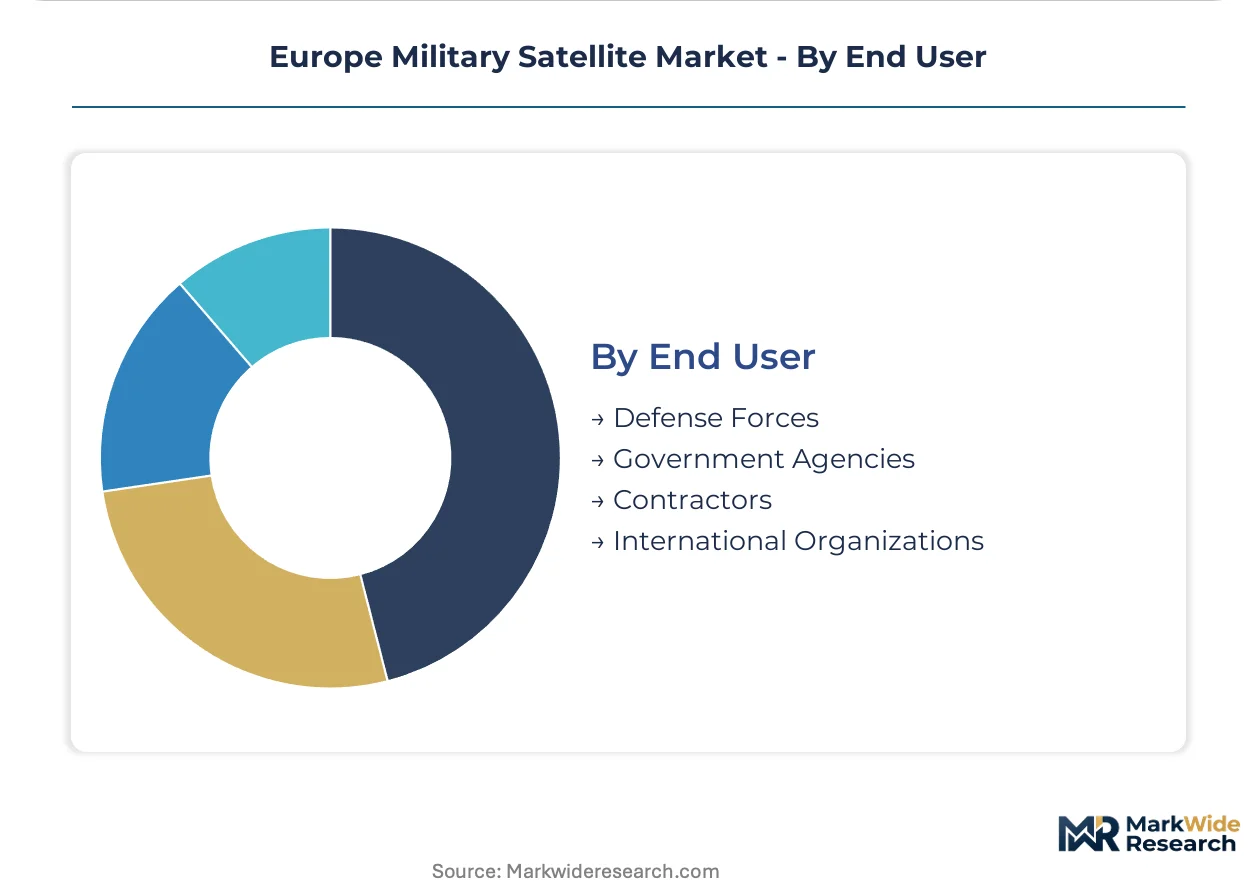
- Defense Forces:National military services specify hardened, interoperable assets aligned with NATO standards. French, German, and British armed forces anchor demand as anchor nations for European sovereign capabilities.
- Government Agencies:Civil-military dual-use procurement by space agencies and interior ministries expands addressable demand beyond pure defense budgets.
- Contractors:Prime systems integrators absorb operational risk under availability-based service contracts.
- International Organizations:NATO and EDA coordination mechanisms enable pooled procurement for smaller member states.
Contract flow concentrates with Defense Forces; institutional expansion is broadening fastest through Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Germany manufacture the majority of European military satellite platforms, while demand distributes across NATO's eastern flank where indigenous production remains absent. This production-consumption asymmetry creates hosted payload opportunities and collaborative procurement mechanisms.
France
France's LPM military programming law funds sovereign geostationary communications satellites and AI-ready avionics mandates. The country's national space agency CNES coordinates with defense procurement offices under EU Space Programme governance. Toulouse anchors continental satellite systems integration, with Thales and Airbus SE competing on throughput-based service contracts rather than asset sales.
Germany
German defense forces drive demand for compact platform architectures and radiation-hardened electronics sourced from a concentrated supplier base. The country's federal procurement office aligns national investments with PESCO collaborative frameworks. Bremen hosts OHB System AG's manufacturing operations, specializing in medium-class government contracts that compete against French prime offerings.
United Kingdom
British armed forces anchor demand for interoperable NATO-standard assets alongside sovereign Skynet communications capabilities. UK export control regulations and dual-use licensing frameworks constrain technology transfer to partner nations. Stevenage and Portsmouth clusters sustain BAE Systems' satellite integration and ground segment operations for military and intelligence applications.
Poland
Polish defense ministries lack indigenous satellite manufacturing and present captive demand for Earth observation hosted payloads on Baltic border surveillance missions. The country's national procurement office channels NATO and EU funding toward collaborative constellation participation. Warsaw coordinates frontline situational awareness requirements with PESCO project maturation timelines for shared LEO architectures.
Italy
Italian defense procurement expands through civil-military dual-use arrangements under space agency coordination. CE marking compliance and EU space traffic management standards tighten supplier eligibility for small satellite specialists. Rome and Turin industrial clusters adapt compact platform manufacturing to debris mitigation certification timelines required for member state access.
Europe Military Satellite Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Europe military satellite landscape. The vendor base organizes into three tiers: prime contractors absorbing operational risk under availability-based contracts, component specialists supplying radiation-hardened electronics, and emerging small satellite manufacturers competing on constellation density. Strategic moves concentrate on multi-year service contract conversion and PESCO collaborative procurement participation.
Within the prime contractor tier, Thales and Airbus SE exemplify end-to-end systems integration capabilities. Thales anchors large-scale national programs in France through sovereign throughput guarantees. Airbus SE sustains dual-use manufacturing scale across civil and defense orbits. OHB System AG occupies a specialist position in compact platform architectures that compete for medium-class government contracts against established prime offerings.
| Leading Market Players |
|---|
| Centre National D'études Spatiales (CNES) |
| Thales |
| Airbus SE |
| OHB System AG |
| Information Satellite Systems Reshetnev |
| GomSpace ApS |
| ROSCOSMOS |
| BAE Systems |
| RSC Energia |
| Others |
Pricing and Supply Chain Analysis
Security-cleared satellite systems engineers concentrated in Toulouse and Bremen drive labor-cost differentials that widen pricing-tier spreads between prime contractors and emerging small satellite manufacturers. This workforce scarcity feeds into availability-based service premiums for hardened geostationary platforms while compressing margins on compact platform architectures.
Pricing Analysis
Margin tightening in medium-class government contracts reflects Thales and Airbus SE competing on throughput guarantees rather than unit asset sales. Three-tier pricing structure across premium sovereign platforms, standard collaborative PESCO architectures, and economy hosted-payload arrangements differentiates by certification grade and operational risk absorption. Cost-down pressure on compact platforms accelerates because Polish and Baltic defense ministries channel NATO funding toward collaborative constellation participation. Government agencies exhibit highest price sensitivity due to civil-military dual-use budget constraints, while defense forces prioritize availability metrics over capital expenditure minimization.
Supply Chain Analysis
Freight costs for radiation-hardened electronics and specialized propulsion systems remain contained given the high value-to-weight ratio of satellite components, though launch scheduling delays at Kourou introduce program-level cost volatility. Manufacturing concentrates in France, Germany, and the United Kingdom, with Bremen and Toulouse anchoring prime contractor integration facilities. Raw material dependencies center on gallium arsenide semiconductors, xenon propellant, and carbon-fiber composite structures. Single-source vulnerability in Ariane heavy-lift capacity constrains deployment schedules. Distribution runs through national procurement offices coordinating with EDA and NATO pooling mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe military satellite market has become a vertical-integration race, with prime contractors pursuing backward integration into radiation-hardened component manufacturing to secure cleared workforce pipelines and reduce export-control dependencies.
For Market Incumbents: Extend sovereign throughput guarantee contracts into multi-decade service arrangements that transfer operational risk and lock out emerging small satellite competitors. Anchor manufacturing scale in Toulouse and Bremen clusters to exploit security-cleared engineering concentration, while investing in AI-ready avionics certification to meet French LPM procurement mandates. Consolidate component supply through captive production of specialized propulsion systems to mitigate single-source vulnerability. For New Entrants and Emerging Players: Direct-to-government digital procurement portals offer bypass routes around established prime contractor relationships for Polish and Romanian hosted payload demand. Target Baltic border surveillance applications as the most penetrable segment, where NATO frontline members lack indigenous manufacturing and prioritize rapid capability fielding over platform ownership. Position on constellation density and debris mitigation compliance to meet tightening EU space traffic management standards. For Investors and Strategic Acquirers: Re-rating potential sits with compact platform specialists given PESCO collaborative procurement maturation and pooled member state resource commitments. Long-term viability favors manufacturers with demonstrated CE marking compliance and end-of-life disposal certification for member state access. Monitor French LPM budget commitment timelines as the inflection signal for consolidated funding versus fragmented national investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Radiation-Hardened Electronics | Secures cleared component supply against French and German supplier concentration. |
| PESCO Collaborative Constellation Participation | Pools Polish and Baltic demand into shared LEO architectures with reduced per-nation capital barriers. |
| AI-Ready Avionics Certification Investment | Meets French defense procurement mandates for autonomous satellite operations. |
| Multi-Year Availability-Based Service Contracts | Transfers operational risk to primes under France's throughput-guarantee contracting model. |
| Debris Mitigation Compliance Certification | Enables access to EU member state procurement channels under evolving space traffic management standards. |
Research Methodology
Multi-period observation of PESCO project maturation timelines, national LPM budget commitments, and Ariane launch scheduling anchored the trend analysis, supplemented by interviews with satellite systems engineers at prime contractors, defense procurement officers in France and Germany, EDA coordination staff, and NATO capability planners. Secondary validation drew from EU Space Programme governance documents, national military programming laws, EDA capability development reports, and Ariane launch manifests. Bottom-up segment sizing triangulated against top-down European defense space expenditure aggregates.
Segment-weighting across product type, orbital technology, application mission, and end-user institutional category structured the analytical framework. CAGRs were derived from trajectory fitting to documented procurement commitments and capability gap assessments across the projection horizon. Industry-specific forecast inputs included PESCO collaborative funding allocations and French LPM multi-year service contract conversion rates.
Inputs from defense ministry procurement offices and EDA coordination mechanisms were available through the study window; gaps in classified payload specifications and intelligence satellite program details introduce uncertainty bands around reconnaissance segment sizing. Forecasts reflect documented procurement commitments and collaborative framework assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Earth Observation Satellite Market
Satellite
India Satellite Connectivity Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
Europe Satellite Connectivity Market
Satellite
Advanced Satellite Market
Satellite
Satellite Data Analytics Services Market
Satellite
Global Satellite Propulsion System Market
Satellite
M2M Satellite Communication Market
Satellite
North America Small Satellite Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Israel Satellite Communications Market
Satellite
Germany Satellite Communications Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Europe Satellite Manufacturing Market