
 India Satellite Communication Market | 2026-2036
India Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
India Satellite Communication Market Insights
India's net-zero 2070 commitment under the updated NDC is hardening procurement criteria for low-carbon satellite ground infrastructure, pushing operators toward energy-efficient gateway designs. Antrix Corporation Limited leverages ISRO's launch vehicle integration for captive transponder capacity, while Reliance Jio Infocomm Limited anchors enterprise broadband through its JioSpaceFiber rollout. Hughes Communications India Ltd. specializes in VSAT networks across banking and rural connectivity verticals, sustaining managed-service depth.
India Satellite Communication covers RF transmission across C-band, Ku-band, and Ka-band frequencies through orbital relays, supporting bidirectional data, voice, and broadcast payloads with link budgets engineered for monsoon-belt rain fade. The system serves connectivity gaps where terrestrial backhaul fails commercial viability tests. Broadband services lead service-type revenue pools, while IoT connectivity records the steepest expansion curve. Within technology layers, Geostationary platforms hold mature margin pools, with Low Earth Orbit constellations capturing fresh capacity demand.
The Department of Telecommunications, IN-SPACe, and TRAI jointly govern spectrum allocation, gateway licensing, and orbital slot coordination, with the Indian Space Policy 2023 codifying private operator entry. Compliance with WPC clearances determines market access for foreign constellation operators. Stakeholders must track spectrum auction frameworks for satellite broadband and ground-station co-location norms shaping deployment economics across coastal and Himalayan service zones.
Market Dynamics
IN-SPACe licensing reforms and orbital-slot allocation transparency are redefining market entry economics for private satellite operators, while monsoon-belt rain-fade mitigation in Ka-band systems concentrates engineering spend across gateway infrastructure.
Growth Catalysts
- BharatNet Phase III Rural Connectivity Mandate:Government-funded fiber-to-village targets in Arunachal Pradesh, Chhattisgarh, and island territories are channeling VSAT demand where terrestrial backhaul construction timelines exceed five years.
- Maritime Safety Communication Compliance:Coastal surveillance and fishing-fleet tracking requirements under the Indian Coast Guard's vessel-monitoring mandate are expanding L-band and C-band transponder leasing across offshore zones.
- Low Earth Orbit Constellation Deployment:Multi-satellite mesh architectures are compressing latency below fifty milliseconds for real-time telemedicine and remote-education applications in Ladakh and North-East hill states.
Market Restraints
- Spectrum Auction Uncertainty:Delayed finalization of satellite-broadband frequency allocation frameworks under TRAI consultation is stalling long-term transponder procurement commitments and ground-station co-location investments.
- Launch Vehicle Capacity Bottlenecks:Domestic payload-to-orbit availability constraints are extending satellite deployment schedules, forcing operators to queue for ISRO's GSLV and PSLV launch windows or incur premium foreign-launch costs.
- Fiber-to-the-Home Substitution:Accelerated urban and peri-urban fiber rollouts by terrestrial broadband providers are eroding addressable subscriber pools in tier-two cities where satellite economics previously held competitive parity.
Strategic Opportunities
- IoT Sensor Mesh Expansion:Agricultural soil-moisture monitoring, livestock tracking, and cold-chain logistics across Punjab, Haryana, and Maharashtra are opening narrowband satellite connectivity verticals beyond traditional broadband services.
- Defense and Paramilitary Secure Networks:Border-area encrypted communication requirements for the Border Security Force and Indo-Tibetan Border Police are generating dedicated transponder leasing demand in X-band and Ku-band frequencies.
- Disaster-Recovery Backup Circuits:Cyclone-prone coastal states and earthquake-vulnerable Himalayan regions are mandating satellite-based redundancy for critical banking, healthcare, and government networks under state-level resilience policies.
Industry Challenges
- Ground-Station Technician Shortages:Specialized RF engineering and antenna-alignment expertise remains concentrated in metropolitan hubs, delaying commissioning timelines for remote gateway installations in Jammu and Kashmir and Andaman and Nicobar Islands.
- Monsoon Rain-Fade Mitigation Costs:Ka-band link-budget engineering for sustained uptime during June-to-September monsoon periods requires adaptive coding and modulation systems, raising per-site capital expenditure by thirty to forty percent over C-band equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Satellite Communication Market |
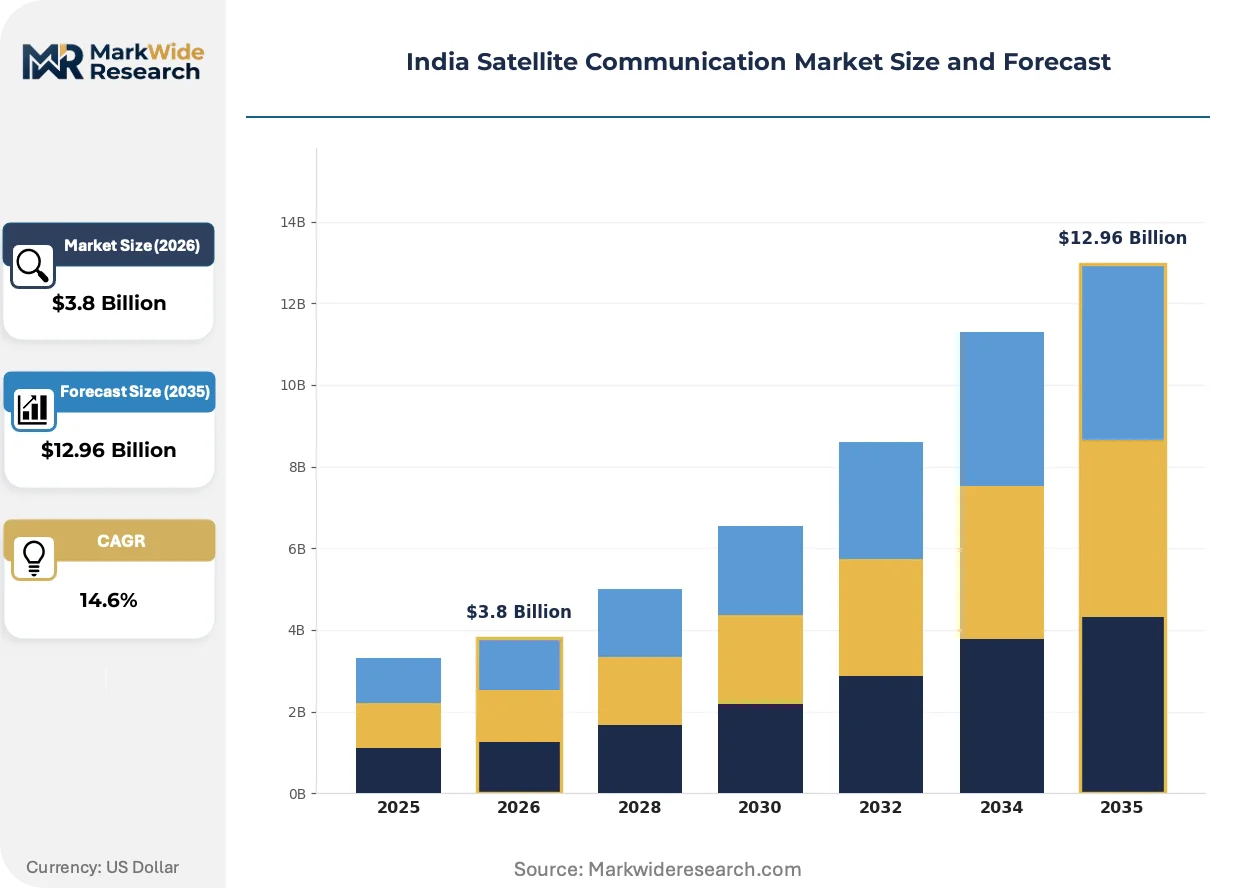
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Television, Telephony, IoT Application: Government, Military, Disaster Management, Maritime Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Space-Based End User: Aerospace, Telecommunications, Transportation, Research |
| Companies Covered | Antrix Corporation Limited, Bharti Airtel Limited, Reliance Jio Infocomm Limited, Tata Communications Limited, Hughes Communications India Ltd., Viasat Inc., SES, Intelsat, Eutelsat OneWeb, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Satellite Communication Market Trends and Innovations
Adaptive beamforming and software-defined payloads are reconfiguring orbital capacity allocation in real time, while regulatory harmonization across Department of Space and Department of Telecommunications is compressing gateway-licensing approval cycles.
Electronically steered phased-array antennas are absorbing legacy parabolic-reflector installations across enterprise VSAT networks. Banks, oil-and-gas exploration sites, and rural ATM clusters are deploying flat-panel terminals that eliminate mechanical tracking and reduce roof-loading constraints. This shift is absorbing maintenance budgets previously allocated to motor-driven positioners, compressing total cost of ownership over five-year refresh cycles.
The Indian Space Policy 2023 codifies non-discriminatory spectrum access for private constellation operators, ending exclusive reliance on ISRO-managed transponder pools. Foreign low-Earth-orbit providers must now secure WPC clearances and demonstrate ground-station co-location with Indian partners. Banking, insurance, and e-governance verticals are responding by diversifying transponder contracts across geostationary and non-geostationary platforms to hedge against single-orbit dependency.
Enterprise buyers are disaggregating satellite connectivity from managed IT services, negotiating direct transponder leases and outsourcing only network operations. Oil refineries in Gujarat, mining operations in Odisha, and power utilities in Rajasthan are terminating bundled VSAT contracts to capture wholesale pricing on raw bandwidth. This unbundling is most visible in energy and extractive industries, where dedicated private networks justify in-house RF engineering teams and eliminate service-provider margin stacking.
India Satellite Communication Market Segmentation
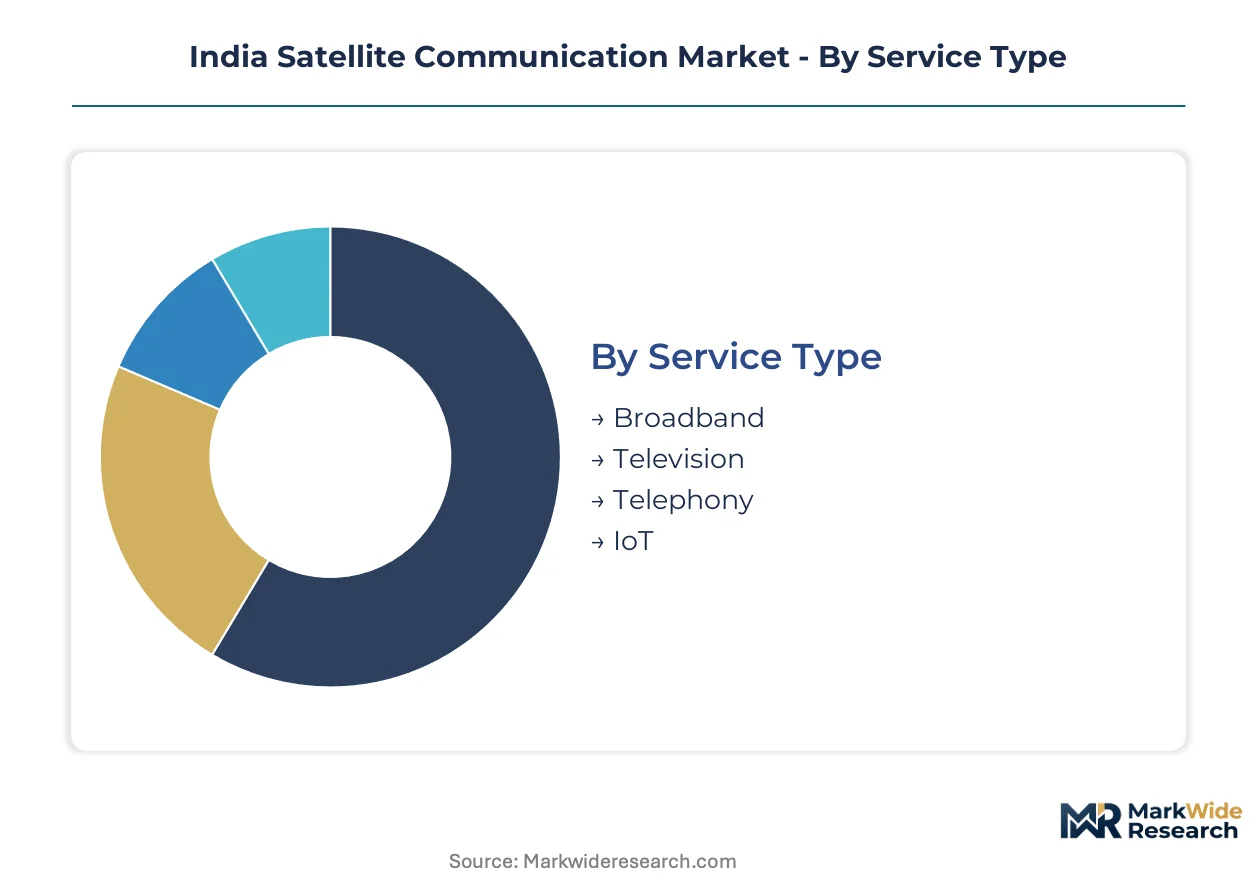
Segmentation in India's satellite communication landscape reveals divergent infrastructure economics and regulatory clearance pathways across service models, orbital architectures, and end-user verticals. Transponder leasing strategies, gateway co-location requirements, and spectrum allocation frameworks vary sharply by application domain and technology platform. Operators must align capacity procurement with segment-specific link-budget constraints and latency tolerances to optimize capital deployment across BharatNet corridors and offshore maritime zones.
Service Type:
Revenue concentration and subscriber acquisition costs differ fundamentally across connectivity modalities.
- Broadband:High-throughput Ka-band systems deliver asymmetric data rates exceeding fifty megabits per second to enterprise campuses and rural BharatNet Phase III villages. Demand is concentrating in Arunachal Pradesh and Ladakh, where fiber-to-the-home deployment timelines exceed seven years and VSAT economics achieve parity with terrestrial alternatives under government subsidy frameworks.
- Television:Direct-to-home broadcast transponders in C-band and Ku-band frequencies serve linear-channel distribution across tier-two and tier-three cities. Adoption is stabilizing as over-the-top streaming platforms absorb urban viewership, while rural households in Bihar and Uttar Pradesh sustain demand for regional-language bouquets beyond terrestrial cable footprints.
- Telephony:Legacy voice circuits persist across offshore oil platforms and remote Border Security Force outposts where cellular coverage remains absent.
- IoT:Narrowband satellite mesh networks connect agricultural soil-moisture sensors in Punjab and cold-chain logistics trackers across Maharashtra, bypassing terrestrial IoT gateway buildouts.
Broadband commands the largest revenue pool; IoT is climbing the fastest on sensor-mesh deployments.
Application:
Mission-critical uptime requirements and encryption mandates segment procurement patterns.
- Government:E-governance backbone circuits under the National Informatics Centre and rural telemedicine links under Ayushman Bharat digital health programs require VSAT redundancy in cyclone-prone Odisha and earthquake-vulnerable Uttarakhand. Procurement follows GeM portal frameworks, with preference for ISRO-managed transponder pools to satisfy data-sovereignty criteria under the Indian Space Policy 2023.
- Military:Encrypted X-band and Ku-band transponder leases serve Border Security Force installations along the Line of Actual Control in Ladakh and Indo-Tibetan Border Police posts in Sikkim. Defense-grade ground stations demand WPC clearances for frequency coordination and comply with Ministry of Defence spectrum-sharing protocols to avoid interference with radar installations.
- Disaster Management:National Disaster Response Force mobile terminals deploy during monsoon floods in Assam and cyclone evacuations in Andhra Pradesh, requiring rapid-deployment antennas with adaptive coding for rain-fade mitigation.
- Maritime:Indian Coast Guard vessel-monitoring systems and fishing-fleet tracking mandates under the Pradhan Mantri Matsya Sampada Yojana drive L-band and C-band transponder demand across offshore zones beyond twelve nautical miles.
Government applications anchor steady-state capacity; military contracts deliver the highest per-transponder margins.
Technology:
Orbital altitude determines latency performance and launch-cost amortization schedules.
- Geostationary:Thirty-six-thousand-kilometer equatorial satellites provide continuous coverage across the Indian subcontinent with single-hop latencies near five hundred milliseconds. ISRO's GSAT constellation and leased Intelsat transponders dominate banking ATM networks and oil-refinery SCADA systems in Gujarat, where proven uptime records justify premium pricing over non-geostationary alternatives despite higher round-trip delays.
- Low Earth Orbit:Multi-satellite constellations at altitudes below two thousand kilometers compress latency below fifty milliseconds, enabling real-time telemedicine consultations in remote Jammu and Kashmir health centers and interactive distance-learning sessions in North-East hill states. Deployment requires phased-array ground terminals and dynamic beam-switching to track satellite handoffs, raising terminal costs but eliminating mechanical pointing.
- Medium Earth Orbit:Intermediate-altitude platforms balance latency and satellite count for regional navigation augmentation and precision-agriculture applications.
- Space-Based:Experimental inter-satellite optical links under ISRO's technology demonstration missions support future mesh architectures bypassing terrestrial gateways.
Geostationary platforms hold mature capacity pools; Low Earth Orbit constellations are expanding share fastest.
End User:
Vertical-specific uptime thresholds and procurement cycles shape contract structures.
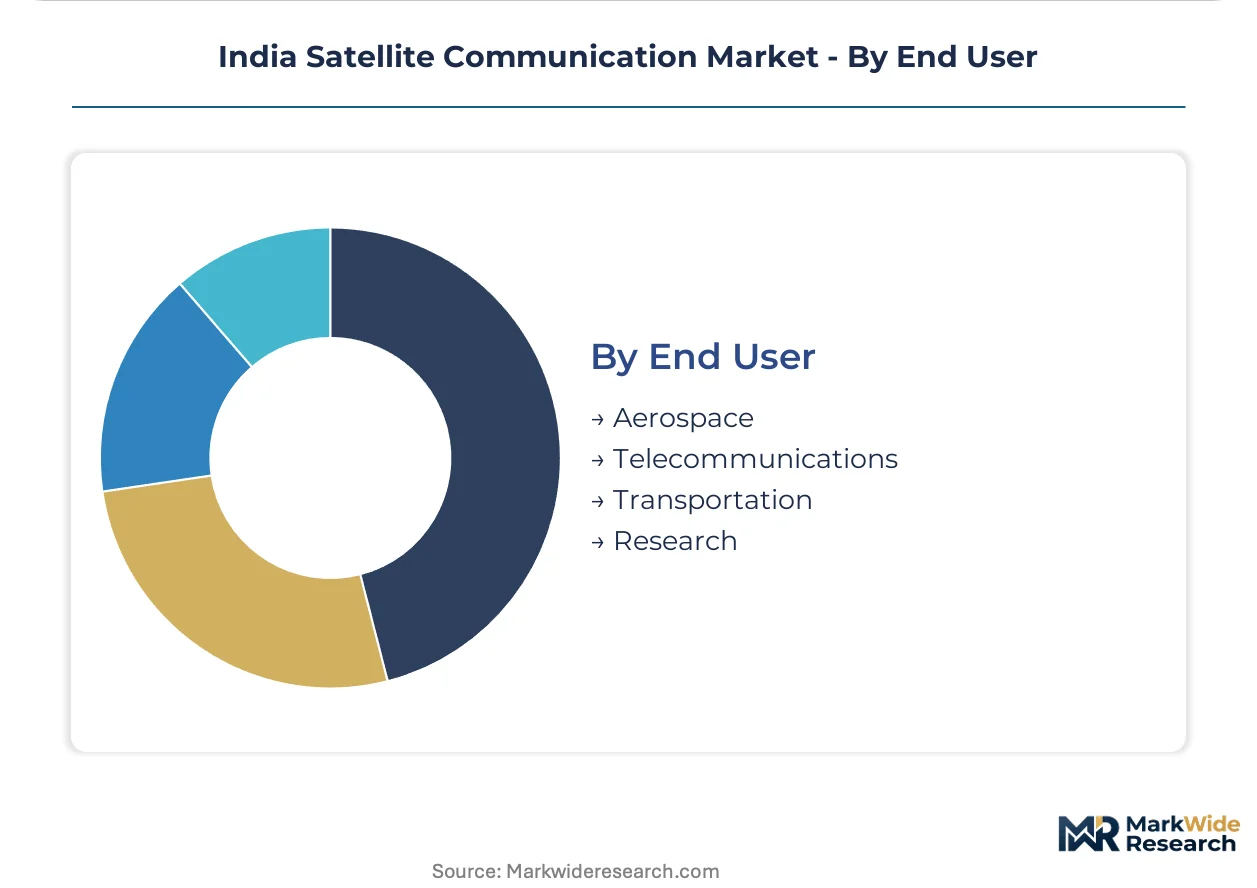
- Aerospace:ISRO telemetry and tracking stations in Sriharikota and Thiruvananthapuram lease dedicated S-band and X-band transponders for launch-vehicle monitoring and satellite health data relay. Contracts follow multi-year orbital-slot reservations with failover redundancy across multiple geostationary satellites to meet mission-critical availability targets exceeding ninety-nine-point-nine percent.
- Telecommunications:Reliance Jio Infocomm Limited and Bharti Airtel Limited deploy satellite backhaul for cellular towers in Andaman and Nicobar Islands and remote Rajasthan districts where fiber trenching costs exceed economic thresholds. Operators negotiate wholesale transponder pricing tied to committed information rates, bypassing managed-service margins to control network operations in-house.
- Transportation:Railways and highway authorities install VSAT terminals for ticket-reservation systems and toll-plaza connectivity across routes where terrestrial fiber suffers frequent cable cuts.
- Research:Academic institutions and meteorological departments access remote-sensing downlinks and climate-monitoring data streams under collaborative agreements with ISRO's Space Applications Centre.
Telecommunications end users drive the largest transponder volumes; aerospace contracts sustain the highest service-level commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian Space Research Organisation's GSAT constellation deployment in the 1990s established transponder capacity pools that anchored early VSAT adoption across banking and government verticals. BharatNet Phase III rural connectivity mandates are now channeling satellite broadband demand into states where terrestrial fiber construction timelines exceed commercial viability thresholds, while offshore maritime surveillance requirements under coastal security frameworks expand L-band and C-band transponder leasing across exclusive economic zones.
North-East Hill States
Arunachal Pradesh, Nagaland, and Manipur concentrate VSAT gateway installations where mountainous terrain blocks fiber-to-the-home rollouts and cellular tower density remains below national averages. IN-SPACe orbital-slot allocation transparency under the Indian Space Policy 2023 is compressing licensing approval cycles for private constellation operators targeting telemedicine and distance-education applications. Guwahati and Shillong anchor ground-station co-location hubs serving adaptive beamforming terminals across border-area government networks and paramilitary encrypted communication circuits.
Ladakh and Jammu & Kashmir
Border Security Force installations along the Line of Actual Control drive X-band and Ku-band transponder demand for encrypted voice and data relay where terrestrial backhaul suffers frequent cable cuts during winter months. The Department of Telecommunications WPC clearance framework mandates frequency coordination with Ministry of Defence radar installations to avoid interference across high-altitude deployment zones. Leh and Srinagar concentrate phased-array antenna commissioning for low-Earth-orbit constellation handoffs supporting real-time video surveillance and disaster-recovery backup circuits under state-level resilience policies.
Andaman and Nicobar Islands
Cellular tower backhaul across Port Blair, Car Nicobar, and remote island clusters relies exclusively on satellite links where subsea fiber cable economics fail commercial thresholds for populations below five thousand per island. Indian Coast Guard vessel-monitoring systems under the Pradhan Mantri Matsya Sampada Yojana fishing-fleet tracking mandate expand C-band transponder leasing across offshore zones beyond twelve nautical miles. Monsoon rain-fade mitigation in Ka-band systems requires adaptive coding and modulation infrastructure, raising per-site capital expenditure by thirty-five percent over C-band equivalents deployed in mainland coastal states.
Gujarat and Rajasthan
Oil refineries in Jamnagar and power utilities in Jodhpur are disaggregating satellite connectivity from managed IT services, negotiating direct transponder leases to capture wholesale pricing on raw bandwidth for SCADA systems and remote-substation monitoring. The Petroleum and Natural Gas Regulatory Board's pipeline-integrity monitoring requirements drive dedicated private network deployments that justify in-house RF engineering teams. Ahmedabad and Udaipur anchor VSAT terminal manufacturing clusters supplying flat-panel electronically steered antennas that eliminate mechanical tracking and reduce roof-loading constraints across enterprise campuses and rural ATM installations.
Maharashtra and Karnataka
Agricultural soil-moisture sensor meshes across Nashik and Pune districts connect through narrowband satellite IoT platforms bypassing terrestrial gateway buildouts, while cold-chain logistics trackers monitor temperature-controlled freight across Mumbai-Bengaluru highway corridors. TRAI spectrum auction frameworks for satellite broadband are stalling long-term transponder procurement commitments, delaying ground-station co-location investments in Navi Mumbai and Bengaluru technology parks. Banking sector ATM networks and insurance branch offices sustain geostationary transponder demand where proven uptime records justify premium pricing over non-geostationary alternatives despite higher round-trip latencies near five hundred milliseconds.
India Satellite Communication Market Competitive Landscape
Capital-heavy geostationary satellite operators compete with asset-light low-Earth-orbit constellation providers that lease launch capacity and outsource ground-station operations to third-party gateway aggregators. The vendor base separates into three strategic archetypes: ISRO-affiliated transponder lessors leveraging domestic launch-vehicle integration, global constellation operators securing WPC clearances for Indian gateway co-location, and specialized VSAT managed-service providers targeting rural connectivity and enterprise backup circuits. Dominant competitive moves concentrate on orbital-slot acquisition through IN-SPACe licensing reforms and phased-array terminal deployments that compress commissioning timelines across remote gateway installations in Jammu and Kashmir and North-East hill states.
Among ISRO-affiliated entities, Antrix Corporation Limited represents the archetype anchoring captive transponder capacity through domestic launch-vehicle integration and government procurement preference under data-sovereignty criteria. Reliance Jio Infocomm Limited and Bharti Airtel Limited exemplify telecommunications operators deploying satellite backhaul for cellular towers in Andaman and Nicobar Islands where fiber trenching costs exceed economic thresholds, negotiating wholesale transponder pricing tied to committed information rates. Hughes Communications India Ltd. occupies a position within the managed-service tier, specializing in VSAT networks across banking ATM installations and rural BharatNet Phase III connectivity corridors where turnkey deployment models absorb RF engineering and maintenance complexity for enterprise buyers lacking in-house satellite operations expertise.
| Leading Market Players |
|---|
| Antrix Corporation Limited |
| Bharti Airtel Limited |
| Reliance Jio Infocomm Limited |
| Tata Communications Limited |
| Hughes Communications India Ltd. |
| Viasat Inc. |
| SES |
| Intelsat |
| Eutelsat OneWeb |
| Others |
Pricing and Supply Chain Analysis
Government procurement programs under BharatNet Phase III and defense transponder leasing contracts concentrate buyer power among state-owned enterprises that negotiate multi-year committed information rate agreements, flattening pricing across geostationary and low-Earth-orbit capacity pools. Wholesale transponder pricing follows long-term offtake contracts tied to orbital-slot reservations, while enterprise VSAT managed services layer margin on turnkey deployment and maintenance bundles. Cost compression in Ka-band gateway infrastructure stems from phased-array antenna commoditization and adaptive coding modulation standardization, though monsoon rain-fade mitigation requirements sustain premium pricing across coastal and North-East deployment zones.
Pricing Analysis
Long-term transponder lease agreements dominate pricing for government and defense buyers, with three-year to five-year contracts locking committed information rates and orbital-slot access. Price differentiation hinges on frequency band allocation—C-band commands lower per-megahertz pricing than Ka-band due to rain-fade resilience and legacy terminal compatibility—and service-level commitments, where defense-grade encrypted X-band transponders sustain forty-percent premiums over commercial Ku-band equivalents. Pricing pressure intensifies across enterprise VSAT managed services as telecommunications operators disaggregate raw bandwidth procurement from network operations, capturing wholesale rates and eliminating service-provider margin stacking. Rural BharatNet connectivity buyers exhibit highest price sensitivity, anchoring procurement to government subsidy ceilings, while Border Security Force installations prioritize uptime guarantees over per-transponder cost.
Supply Chain Analysis
Direct-to-government channels handle BharatNet Phase III rural connectivity demand through GeM portal procurement frameworks, bypassing distributor tiers to satisfy data-sovereignty criteria under the Indian Space Policy 2023. Supply concentrates in ISRO-managed GSAT transponder pools and foreign constellation operators securing WPC clearances for Indian gateway co-location, with phased-array antenna manufacturing drawing from Ahmedabad and Bengaluru electronics clusters. Dependencies rest on ISRO launch-vehicle capacity for domestic satellite deployment and foreign launch-service availability for constellation operators, exposing schedules to GSLV and PSLV queue delays. Single-source vulnerability persists across X-band defense transponders where ISRO remains the sole domestic provider, while spectrum auction uncertainty stalls long-term ground-station co-location investments in Navi Mumbai and Bengaluru technology parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
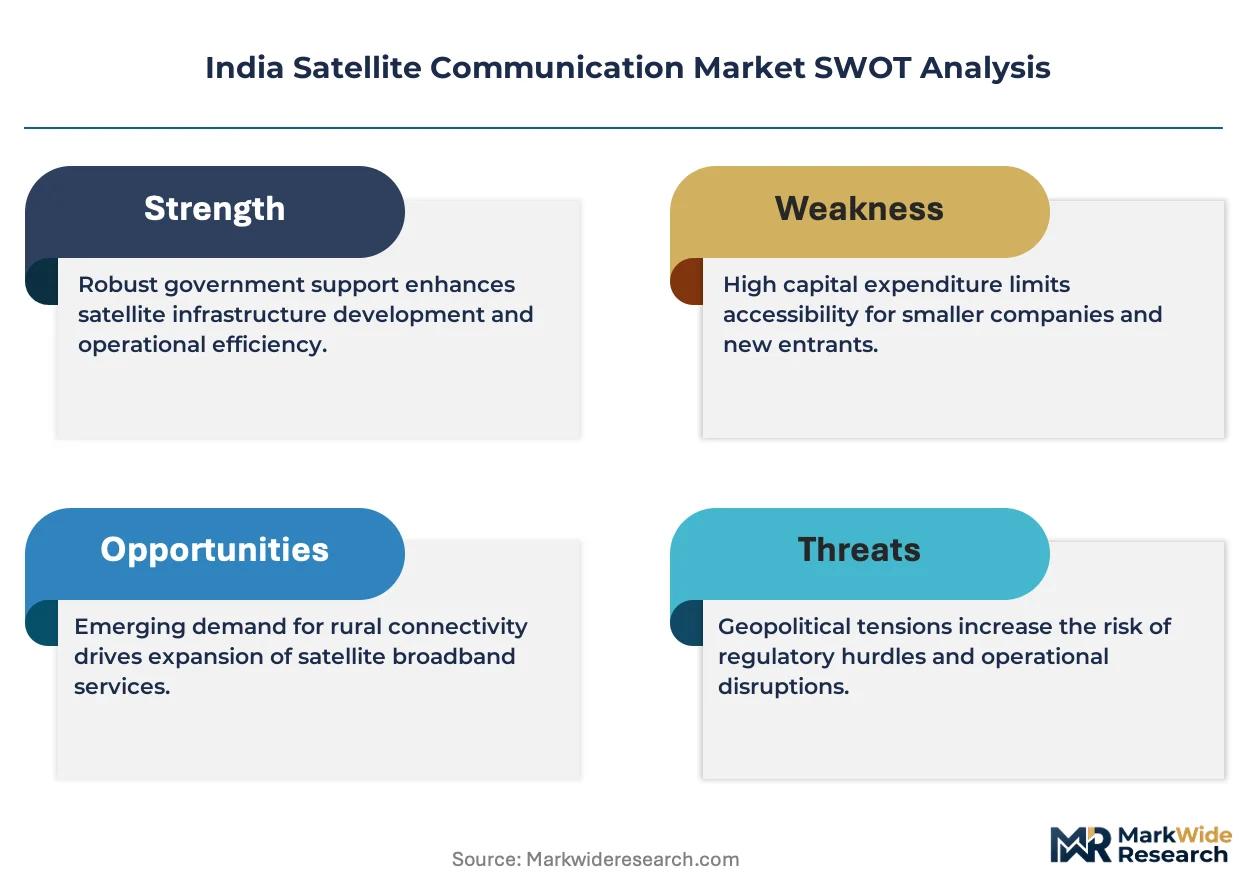
Spectrum allocation clarity under TRAI frameworks will separate operators securing multi-year orbital-slot commitments from those deferring gateway investments, favoring entities with captive launch-vehicle integration and government procurement relationships. Defense transponder leasing and rural BharatNet Phase III connectivity mandates anchor steady-state demand pools insulated from fiber-to-the-home substitution pressures in urban corridors.
For Market Incumbents: To counter low-Earth-orbit constellation entry threatening geostationary transponder utilization rates, expand phased-array ground-terminal deployment across enterprise VSAT networks to enable hybrid orbital-platform switching and preserve customer retention during latency-sensitive application migration. Backward integration into gateway operations in Ladakh and North-East hill states compresses third-party co-location fees and secures spectrum coordination approvals ahead of WPC clearance bottlenecks. Certification investment in monsoon rain-fade adaptive coding systems defends Ka-band pricing premiums against C-band substitution in coastal deployment zones.
For New Entrants and Emerging Players: The Indian Space Policy 2023 non-discriminatory spectrum access provision opens a window for foreign constellation operators to secure WPC clearances and gateway co-location agreements with domestic partners holding existing orbital-slot allocations. Target IoT sensor-mesh applications across agricultural soil-moisture monitoring and cold-chain logistics tracking in Punjab and Maharashtra, where narrowband satellite connectivity bypasses terrestrial gateway buildouts and locks in multi-year service contracts before cellular IoT coverage expands. Partner with state-level disaster-management authorities in cyclone-prone Odisha and earthquake-vulnerable Uttarakhand to deploy rapid-response mobile terminals under resilience policy mandates.
For Investors and Strategic Acquirers: Telecommunications operators expanding satellite backhaul for cellular towers in Andaman and Nicobar Islands represent the most active acquirer category, seeking VSAT managed-service providers with proven gateway operations and transponder lease portfolios. Acquisition targets holding WPC clearances and multi-year government procurement contracts under BharatNet Phase III sustain defensible revenue visibility across the projection horizon. Watch IN-SPACe orbital-slot allocation approvals for private constellation operators as the inflection signal indicating spectrum auction finalization and long-term transponder procurement commitment resumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Low Earth Orbit Constellation Gateway Co-location | Secures WPC clearances and spectrum coordination approvals ahead of regulatory bottlenecks in Bengaluru and Navi Mumbai technology parks. |
| Phased-Array Antenna Manufacturing Capacity | Absorbs legacy parabolic-reflector terminal replacement demand across banking ATM networks and rural BharatNet Phase III VSAT deployments. |
| Defense Transponder Lease Extension | Locks multi-year X-band and Ku-band capacity commitments for Border Security Force installations along the Line of Actual Control. |
| IoT Narrowband Satellite Platform Launch | Captures agricultural sensor-mesh connectivity demand in Punjab and Maharashtra before cellular IoT gateway coverage expands. |
| Monsoon Rain-Fade Mitigation System Certification | Defends Ka-band pricing premiums in coastal states by demonstrating adaptive coding uptime guarantees during June-to-September monsoon periods. |
Research Methodology
Coverage spans India's North-East hill states, Ladakh, Andaman and Nicobar Islands, Gujarat, and Maharashtra, with primary inputs from each geography validating segment-level adoption patterns and regulatory compliance pathways. The study combines primary interviews with satellite gateway operations managers, VSAT network deployment engineers, government procurement officers under BharatNet Phase III programs, and defense communication specialists at Border Security Force installations, cross-referenced against secondary data from Department of Space orbital-slot allocation records, TRAI spectrum consultation documents, WPC frequency clearance databases, and customs import records for phased-array antenna shipments. Bottom-up transponder capacity modeling and top-down end-user connectivity demand triangulation anchor quantitative outputs.
The analytical framework decomposes growth across service type, application, technology platform, and end-user vertical throughout the forecast period, with segment-level expansion rates derived from BharatNet Phase III village connectivity targets, Indian Coast Guard vessel-monitoring mandate rollout schedules, and low-Earth-orbit constellation deployment timelines. Modeling integrates frequency band allocation patterns, gateway co-location approval cycles, and monsoon rain-fade mitigation capital expenditure requirements as industry-specific forecast inputs. Compound annual growth rates reflect weighted aggregation of government procurement pipeline visibility, private constellation WPC clearance progression, and enterprise VSAT terminal refresh cycles.
Revisions become necessary when TRAI spectrum auction frameworks finalize allocation methodologies or IN-SPACe orbital-slot coordination timelines compress beyond current approval-cycle assumptions. Forecasts incorporate assumptions around ISRO launch-vehicle capacity availability, foreign constellation operator WPC clearance success rates, and fiber-to-the-home substitution velocity in tier-two cities, each subject to regulatory policy shifts and terrestrial infrastructure deployment acceleration. Periodic stress-testing of base assumptions against Department of Space licensing reform announcements and Department of Telecommunications spectrum policy updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Small Satellite Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Satellite Photography Service Market
Satellite
China Satellite Communication Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Satellite Communication Subsystem Market
Satellite
Germany Satellite Connectivity Market
Satellite
North America Military Satellite Market
Satellite
Satellite Broadband Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Commercial LEO Satellite Market
Satellite
Satellite Signal Meter Market
Satellite
Low-Cost Satellite Market
Satellite
Remote Sensing Satellite Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market