
 Deep Space Exploration Market | 2026-2036
Deep Space Exploration Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Space Exploration Market Analysis
United States launch infrastructure is narrowing the gap between national security and commercial deep space objectives. SpaceX leverages reusable super-heavy lift capacity to dominate lunar logistics bidding. Lockheed Martin Corporation anchors crewed deep space habitat development through Orion program continuity. Blue Origin competes in lunar lander and heavy-lift engine segments with sustained capital commitment from its founder.
Deep space exploration encompasses robotic and human missions beyond geostationary orbit, utilizing spacecraft with specific impulse exceeding chemical propulsion baselines and radiation-hardened avionics rated for multi-year transit durations. Rockets and rovers capture the dominant share of technology investment as Artemis and Mars Sample Return missions drive hardware procurement. Government agencies remain the primary end user, though private companies represent the fastest-expanding buyer category as SpaceX, Blue Origin, and Rocket Lab book commercial lunar payload contracts.
NASA's Artemis Accords framework, FAA launch licensing requirements, and Department of Commerce space situational awareness standards collectively shape market access and technology transfer protocols for participants. The European Space Agency's Moonlight initiative and Japan's METI space industrialization roadmap introduce parallel compliance layers for international consortium bids. Stakeholders must monitor evolving export control classifications under International Traffic in Arms Regulations and their intersection with commercial space treaty obligations.
Market Dynamics
Reusable heavy-lift rocketry is collapsing the per-kilogram economics of lunar logistics, forcing legacy cost-plus contracting models into obsolescence and compressing mission procurement cycles from decade-long programs to annual flight manifests.
Growth Catalysts
- Artemis Accords framework:The United States-led multilateral agreement establishes standardized lunar resource extraction protocols, reducing legal uncertainty for commercial payload providers seeking access to polar ice deposits.
- In-situ resource utilization:Oxygen extraction technologies from lunar regolith are maturing rapidly, enabling refueling infrastructure that extends mission durations without Earth-origin propellant resupply.
- Space Force procurement:United States national security demand for cislunar domain awareness is generating sustained funding for deep space sensor networks and responsive launch capabilities.
Market Restraints
- Plutonium-238 scarcity:Radioisotope thermoelectric generator fuel stockpiles are concentrated at United States Department of Energy facilities, creating single-source dependency for outer-planet missions requiring nuclear power.
- Radiation-hardened electronics:Domestic foundry capacity for qualified semiconductors is limited to a handful of United States and European suppliers, constraining spacecraft avionics procurement timelines.
- International Traffic in Arms Regulations:United States export control classifications treat most deep space propulsion and guidance technologies as munitions, fragmenting international consortium formation and technology transfer.
Strategic Opportunities
- Australian ground station networks:Southern hemisphere tracking infrastructure remains underdeveloped relative to northern facilities, creating first-mover advantage for telemetry and command services supporting lunar far-side missions.
- On-orbit servicing:Robotic refueling and spacecraft life extension capabilities represent nascent demand from geostationary operators seeking to pivot hardware toward cislunar applications.
- Japan METI industrialization roadmap:Subsidized lunar resource extraction pilot programs offer anchor tenancy for foreign equipment providers meeting domestic content requirements.
Industry Challenges
- Deep space systems engineering talent:United States universities produce insufficient graduates with combined expertise in orbital mechanics, radiation effects, and long-duration life support integration.
- Human-rating certification timelines:NASA's crew safety verification protocols for novel spacecraft designs extend development schedules beyond commercial capital deployment horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Space Exploration Market |
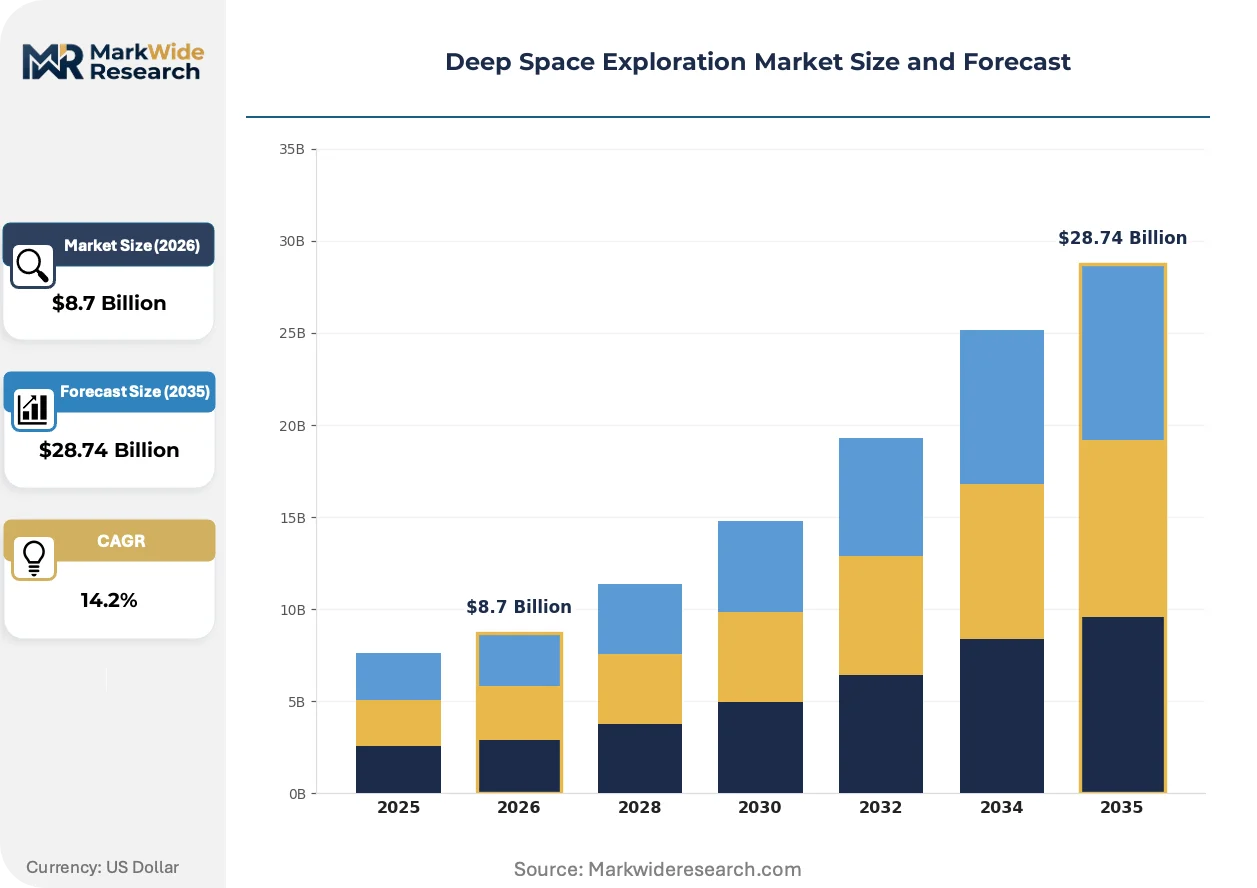
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Rockets, Rovers, Satellites, Space Probes Mission Type: Research, Human Exploration, Space Mining, Planetary Defense Payload Type: Scientific Instruments, Communication Equipment, Power Systems, Life Support Systems End User: Government Agencies, Private Companies, Academic Institutions, Research Organizations |
| Companies Covered | SpaceX, Blue Origin, Lockheed Martin Corporation, Northrop Grumman, Boeing, Rocket Lab, Thales Alenia Space, Airbus, NEC Space Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Space Exploration Market Emerging Trajectories
Propulsion architecture diversification and manufacturing automation are actively redrawing the competitive map for interplanetary mission hardware, with implications for supplier qualification and contract award patterns.
Storable electric propulsion systems utilizing iodine rather than xenon are collapsing the propellant cost structure for deep space transit stages. Small satellite manufacturers are adopting these thrusters for lunar orbit insertion missions previously requiring chemical propulsion. The shift is collapsing the minimum viable spacecraft mass for cislunar operations, enabling rideshare aggregators to book secondary payloads on commercial lunar landers.
The European Space Agency's Moonlight initiative mandates interoperability standards for lunar communication and navigation services. Member state procurement now requires compliance with open interface definitions for ground segment integration. Prime contractors are responding by modularizing payload adapters to accommodate multi-mission reuse across ESA, national, and commercial flight opportunities.
Fixed-price milestone contracting is displacing cost-plus arrangements for lunar logistics services. NASA's Commercial Lunar Payload Services program established the template; defense agencies are adopting similar structures for responsive space demonstrations. The United States exhibits the most pronounced shift, with Space Development Agency and Space Force Space Systems Command both issuing firm-fixed-price solicitations for beyond-LEO capabilities.
Deep Space Exploration Market Segmentation
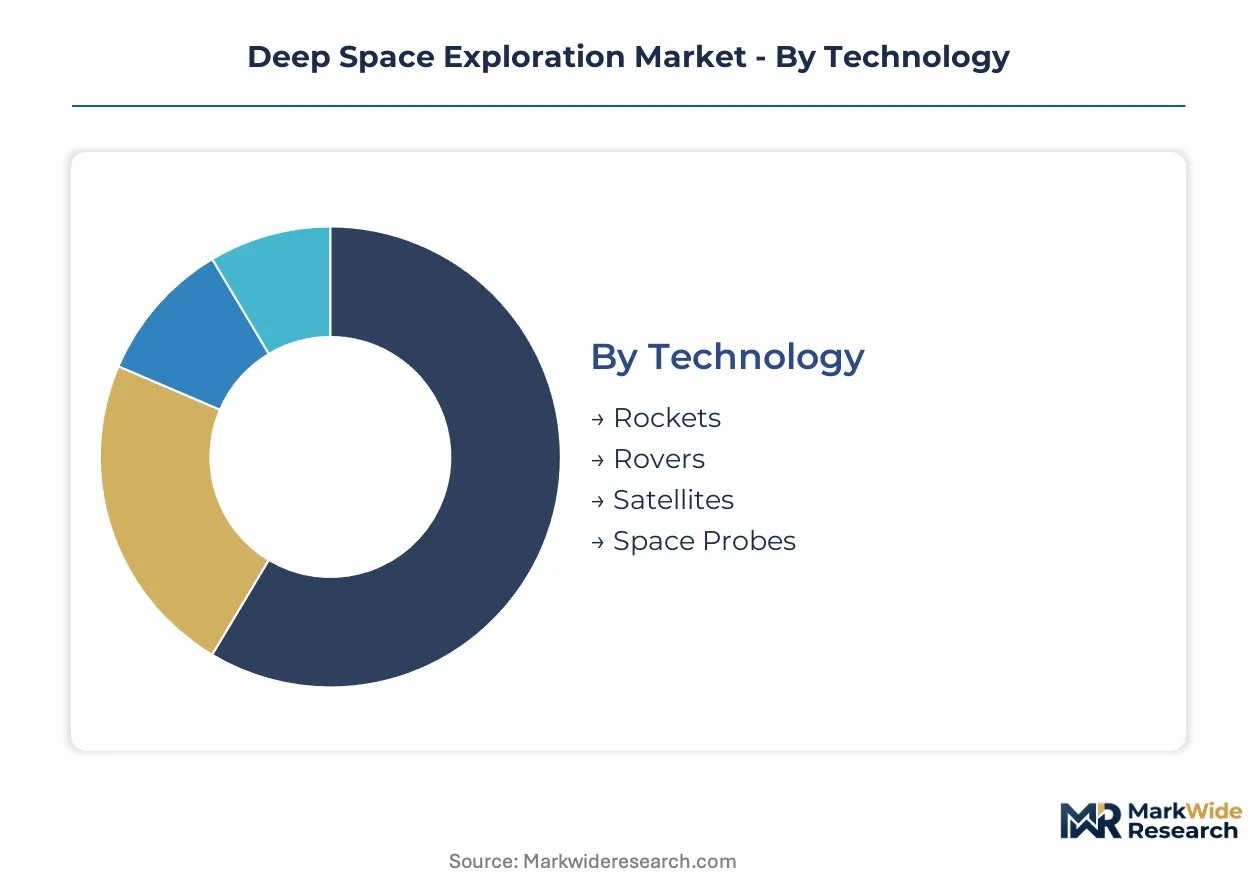
Segmentation in deep space exploration reveals how procurement priorities diverge across mission architectures and funding sources. Technology choices determine propulsion economics, while end-user identity shapes contracting structures from cost-plus to fixed-price milestones.
Technology:
Hardware spans the full mission lifecycle from Earth departure through surface operations and data return.
- Rockets:Heavy-lift launch vehicles with reusable first stages dominate cislunar logistics economics. SpaceX's Starship and NASA's Space Launch System anchor United States government and commercial procurement, with demand concentrating in lunar cargo delivery and crew transport missions.
- Rovers:Mobile surface platforms carry scientific payloads across planetary terrain. NASA's Artemis and Mars Sample Return programs drive hardware investment, with autonomous navigation systems and radiation-hardened avionics qualifying suppliers to a narrow tier.
- Satellites:Orbital platforms provide communication relay, navigation, and remote sensing infrastructure. ESA's Moonlight initiative and planned lunar constellations expand demand for interoperable spacecraft buses.
- Space Probes:Interplanetary spacecraft execute flyby, orbiter, and sample-return missions beyond cislunar space. Plutonium-238 scarcity constrains outer-planet mission cadence to Department of Energy fuel availability.
The dominant share belongs to Rockets, while Rovers is closing the gap fastest.
Mission Type:
Contracting models vary sharply across mission objectives, from open-science data release to proprietary resource extraction.
- Research:Robotic missions pursuing astrophysics, heliophysics, and planetary science objectives. NASA's Discovery and New Frontiers programs and ESA's Cosmic Vision framework sustain steady procurement of competed mission opportunities.
- Human Exploration:Crewed missions to lunar surface and Mars requiring life support, radiation protection, and abort capability. Artemis program schedules compress development timelines for habitat and mobility systems.
- Space Mining:In-situ resource utilization for propellant production and construction materials. Polar ice extraction pilots attract private capital seeking anchor tenancy for commercial lunar propellant depots.
- Planetary Defense:Asteroid detection, tracking, and deflection mission architectures. NASA's DART mission validation and Space Force cislunar domain awareness requirements expand sensor and kinetic interceptor demand.
Research commands the largest contract volume, though Space Mining is expanding most quickly as regulatory frameworks mature.
Payload Type:
Instrument and subsystem selection determines spacecraft mass, power, and thermal budgets.
- Scientific Instruments:Spectrometers, imagers, and sample analysis tools producing mission primary data. Mass and power constraints favor miniaturization, with academic principal investigators driving requirements definition.
- Communication Equipment:High-gain antennas, transponders, and optical terminals for deep space telemetry. NASA's Deep Space Network capacity limitations push demand for relay satellites and autonomous communication protocols.
- Power Systems:Solar arrays, radioisotope thermoelectric generators, and energy storage for multi-year missions. Plutonium-238 supply constraints force Mars missions toward solar-battery hybrids despite dust degradation risks.
- Life Support Systems:Closed-loop environmental control for crewed missions, including air revitalization, water recovery, and waste processing. Human-rating certification extends development schedules beyond commercial capital horizons.
Scientific Instruments retains the largest addressable base, while Communication Equipment is gaining share fastest with constellation deployments.
End User:
Buyer identity determines risk tolerance, schedule pressure, and intellectual property terms.
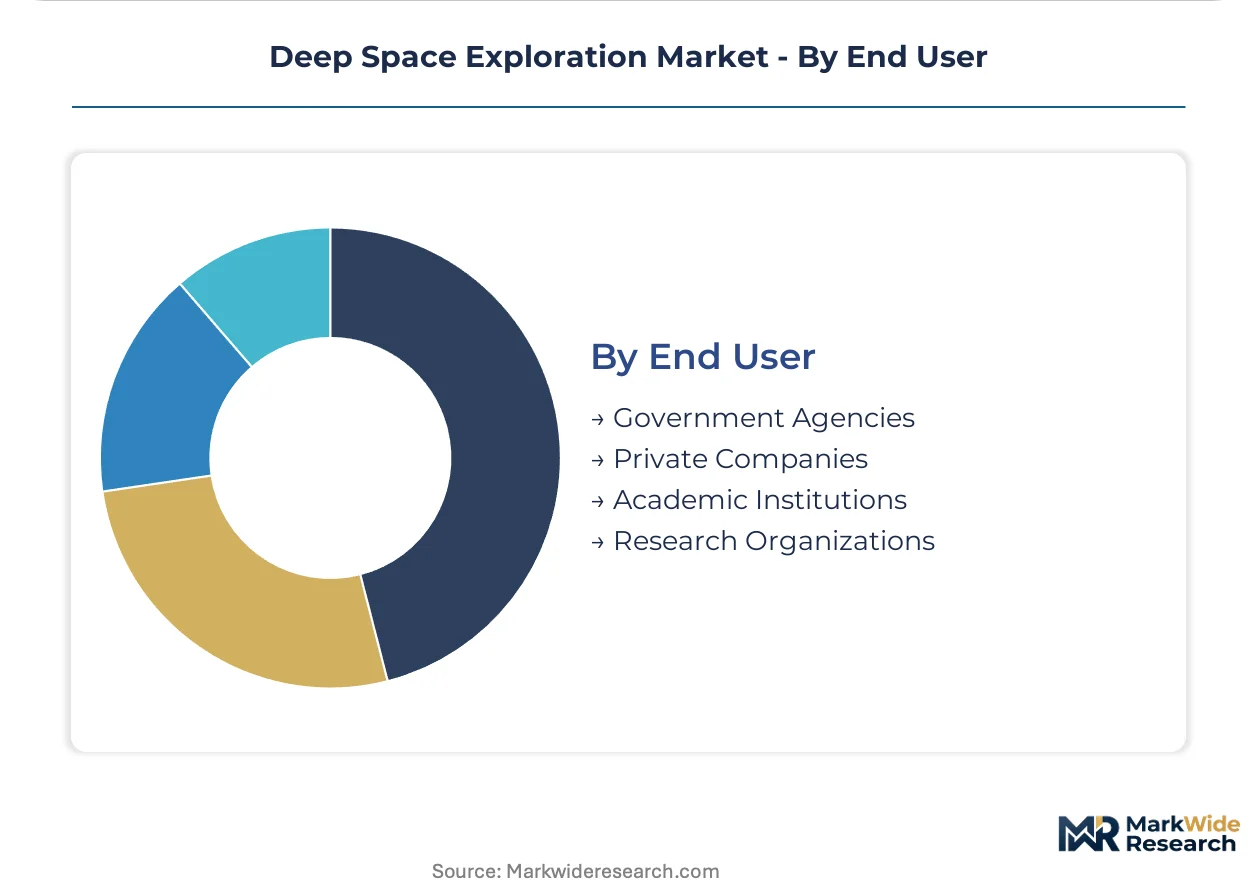
- Government Agencies:NASA, ESA, and national space agencies with multi-year appropriated budgets. Artemis and Mars Sample Return anchor procurement volume, with cost-plus contracting giving way to fixed-price service agreements.
- Private Companies:SpaceX, Blue Origin, and emerging lunar logistics providers booking commercial payload capacity. Commercial Lunar Payload Services contracts established the template for milestone-based procurement.
- Academic Institutions:University-led instrument development and mission science teams. Principal investigator roles on competed missions provide entry points for technology demonstration.
- Research Organizations:Federally funded laboratories and international consortium participants. Johns Hopkins Applied Physics Laboratory and similar entities bridge government and academic mission execution.
Government Agencies still account for the dominant procurement volume, though Private Companies are climbing the fastest as lunar logistics markets commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy-lift launch infrastructure and mission control networks cluster in a handful of nations with sustained government investment and established aerospace industrial bases. National space agencies anchor procurement volume, while commercial operators expand ground segment and manufacturing footprints across allied territories.
United States
NASA's Artemis program and Space Force cislunar budgets drive procurement of lunar landers, crew habitats, and deep space sensors. FAA launch licensing and State Department export controls under ITAR shape market access for foreign partners. Houston, Huntsville, and Cape Canaveral host concentrated mission operations, manufacturing, and launch facilities.
France
CNES and ESA headquarters in Paris anchor European deep space mission planning and Galileo navigation integration. EU space surveillance and tracking regulations mandate interoperability standards for debris monitoring networks. Toulouse hosts Airbus Defence and Space manufacturing for orbital platforms and planetary science payloads.
Germany
DLR institutes in Cologne and Munich advance in-situ resource utilization and robotic exploration technologies under ESA Cosmic Vision frameworks. National space legislation aligns with EU Green Deal sustainability criteria for launch operations. Bremen concentrates spacecraft bus manufacturing and payload integration for interplanetary missions.
Japan
JAXA's Martian moons exploration program and METI's lunar industrialization roadmap generate demand for sample return technologies and polar resource extraction pilots. Space Activity Act amendments streamline commercial launch licensing and on-orbit servicing permissions. Tsukuba and Tanegashima host mission control and launch infrastructure.
Australia
Southern hemisphere ground station gaps create first-mover opportunity for lunar far-side telemetry and command services. Australian Space Agency grants and defense cislunar domain awareness contracts fund tracking network expansion. South Australia hosts the Woomera range and emerging Adelaide manufacturing cluster for small satellite components.
Deep Space Exploration Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion, avionics, and thermal management. The market exhibits tiered consolidation: a narrow band of prime contractors capture government flagship missions, while a broader base of subsystem vendors and launch service providers compete for fixed-price logistics contracts. Two archetypes dominate—vertically integrated heavy-lift operators and modular payload specialists. Competitive moves center on reusable launch cadence acceleration and fixed-price milestone contracting displacement of cost-plus arrangements.
Among United States-based platform integrators, SpaceX and Lockheed Martin Corporation exemplify divergent strategies within the same procurement environment. SpaceX occupies a position defined by reusable super-heavy lift capacity and direct NASA lunar logistics awards. Lockheed Martin Corporation anchors crewed deep space habitat development through sustained Orion program continuity. Blue Origin represents the sustained-capital archetype, competing in lunar lander and heavy-lift engine segments with founder-backed investment horizons beyond typical commercial cycles.
| Leading Market Players |
|---|
| SpaceX |
| Blue Origin |
| Lockheed Martin Corporation |
| Northrop Grumman |
| Boeing |
| Rocket Lab |
| Thales Alenia Space |
| Airbus |
| NEC Space Technologies |
| Others |
Supply Flow & Price Mechanics
Plutonium-238 scarcity at United States Department of Energy facilities creates single-source dependency for outer-planet missions, compressing pricing spreads between solar-battery hybrid systems and nuclear-powered alternatives while forcing procurement timelines to synchronize with federal fuel allocation cycles.
Pricing Analysis
International Traffic in Arms Regulations dictates the pricing tier structure by fragmenting international consortium participation and imposing compliance premiums on technology transfer. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant domestic suppliers from allied-nation vendors with bilateral agreements and from non-aligned foreign providers facing exclusion. Cost compression in standard-tier lunar logistics is intensifying because SpaceX reusable heavy-lift capacity collapses per-kilogram baselines. Government agencies exhibit least price sensitivity due to appropriated mission budgets, while academic institutions face greatest constraint from fixed grant ceilings.
Supply Chain Analysis
Radiation-hardened semiconductor feedstock draws from United States, European, and limited Asian foundry capacity qualified for space-grade manufacturing. Plutonium-238, high-purity xenon propellant, and carbon-carbon composite thermal protection systems anchor raw material dependencies. Single-source vulnerability concentrates in Department of Energy radioisotope fuel stockpiles and domestic radiation-hardened electronics fabrication. Distribution runs through prime contractor integration hubs in Houston, Bremen, and Toulouse before final spacecraft assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
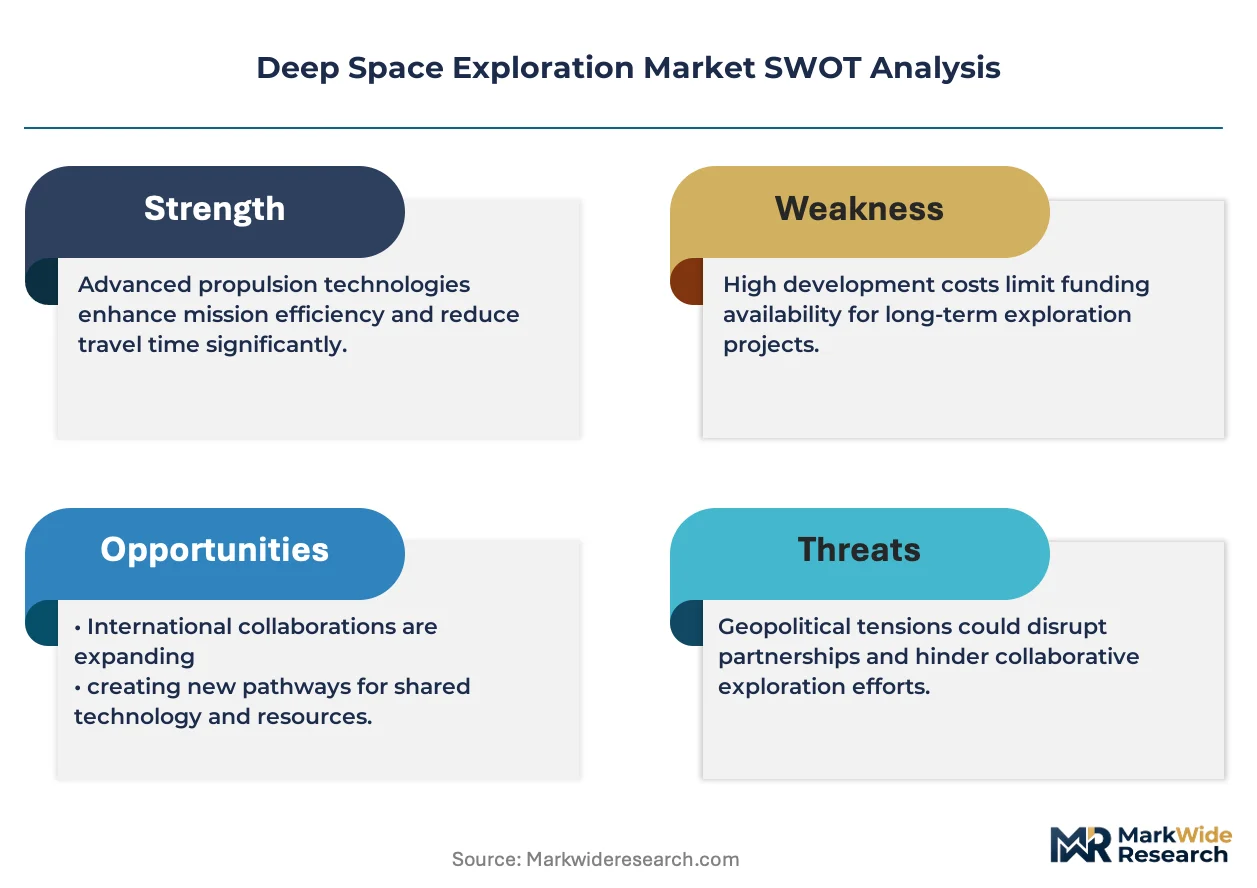
Deep space exploration procurement hinges on a shallow talent pool combining orbital mechanics, radiation effects engineering, and long-duration life support integration—capabilities that United States universities produce in insufficient volume to match mission cadence acceleration.
For Market Incumbents: Build certification moats by accelerating human-rating validation pipelines for novel spacecraft designs before commercial capital horizons expire. Secure anchor tenancy in Artemis lunar logistics contracts through fixed-price milestone performance. Counter emerging iodine electric propulsion specialists by integrating storable thruster variants into established satellite bus offerings. For New Entrants and Emerging Players: Australian southern hemisphere ground station networks represent the most penetrable entry point for lunar far-side telemetry services, with first-mover advantage in underdeveloped tracking infrastructure. Japan METI-subsidized lunar resource extraction pilots offer anchor tenancy for foreign equipment providers meeting domestic content thresholds. Partner with rideshare aggregators booking secondary payloads on commercial lunar landers to bypass prime contractor qualification barriers. For Investors and Strategic Acquirers: The market sits at a fixed-price contracting transition phase that favors vertically integrated heavy-lift operators with demonstrated milestone execution. Long-term viability rests on capture of recurring lunar logistics services rather than one-off science mission hardware. Monitor NASA Commercial Lunar Payload Services award cadence as inflection indicator for commercial demand validation.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Heavy-Lift Certification | FAA launch licensing for Starship and SLS alternatives compresses Artemis cargo economics. |
| In-Situ Resource Utilization Pilot | Polar ice extraction demonstration under METI roadmap anchors commercial propellant depot viability. |
| Radiation-Hardened Foundry Investment | Domestic semiconductor capacity expansion reduces ITAR-constrained avionics procurement timelines. |
| Australian Ground Station Network | Southern hemisphere telemetry infrastructure captures lunar far-side mission control premiums. |
| Iodine Electric Propulsion Adoption | Xenon alternative thrusters collapse minimum viable spacecraft mass for cislunar rideshare. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with spacecraft program managers, propulsion engineering directors, national space agency procurement officers, and commercial lunar payload specialists; and secondary validation against NASA budget justifications, ESA Cosmic Vision framework documents, FAA launch licensing records, and Department of Energy plutonium-238 allocation reports. Bottom-up segment sizing triangulated with top-down government appropriation analysis across the analysis window.
Forecast inputs considered mission type segmentation by research, human exploration, space mining, and planetary defense; technology segmentation across rockets, rovers, satellites, and space probes; and end-user segmentation spanning government agencies, private companies, academic institutions, and research organizations. CAGRs derived from procurement pipeline analysis and reusable launch cadence acceleration curves. Plutonium-238 availability constraints and ITAR export classification evolution fed scenario-weighted projections.
Practitioners should monitor Department of Energy fuel allocation schedules and FAA commercial launch licensing velocity for early signals of forecast revision triggers. Cross-checking against NASA Artemis milestone achievement rates and Space Force cislunar domain awareness budget trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Spacecraft Market
Space
Space Wheel Market
Space
Space on Board Computing Platform Market
Space
Space Burial Service Market
Space
Space Sensors Market
Space
UK Space Electronics Market
Space
Canada Space Electronics Market
Space
Asia-Pacific Space Electronics Market
Space
Space Management Solutions Market
Space
Space Designing Market
Space
Japan Space Electronics Market
Space
Space Robots Market
Space
India Space Electronics Market
Space
US Space Electronics Market
Space
Africa Space Electronics Market
Space
Space Mobile Service Market