
 Global Naval Vessel MRO Market | 2026-2036
Global Naval Vessel MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Naval Vessel MRO Market Outlook
Coastal defense ministries are redrawing procurement priorities toward lifecycle sustainment over new-build programs. BAE Systems leverages its Portsmouth facility dominance to capture Royal Navy surface ship overhaul work. Huntington Ingalls Industries sustains the US nuclear aircraft carrier refueling complex overhaul monopoly through Newport News operations. Naval Group anchors European submarine MRO demand with its Cherbourg and Toulon yards.
Naval vessel MRO encompasses the inspection, repair, replacement, and upgrade of hull structures, propulsion plants, combat systems, and auxiliary machinery to restore operational readiness and extend service life beyond original design thresholds. Dry-docking intervals for steel-hulled frigates typically require cathodic protection renewal, turbine blade refurbishment, and combat management system software validation over six-to-nine-month cycles. Maintenance and overhaul services by vessel type generate the deepest revenue pools, with aircraft carrier refits absorbing disproportionate man-hours relative to hull count. Predictive analytics by technology represents the fastest-expanding segment, as sensor-based condition monitoring displaces calendar-driven maintenance schedules for propulsion and power distribution equipment.
The US Navy's Naval Sea Systems Command (NAVSEA) sets hull integrity and nuclear propulsion certification standards that dictate private shipyard access to military contracts. The EU's MDR and CE marking regimes, alongside NATO's Standardization Office (NSO) maintenance protocols, shape cross-border subcontracting eligibility for European naval primes. Stakeholders must monitor how classified cybersecurity mandates for combat system upgrades reshape contractor qualification thresholds and foreign participation rules in allied overhaul programs.
Market Dynamics
Naval vessel MRO operators confront a structural squeeze between aging fleet demographics and tightening certification windows for hull integrity and nuclear propulsion systems. Dry-docking capacity constraints at sovereign shipyards are extending turnaround timelines and compressing contractor margins across NATO-aligned maintenance networks.
Growth Catalysts
- US Navy shipyard recapitalization:NAVSEA's multi-site infrastructure investments are expanding private yard access to nuclear carrier refueling contracts, redirecting maintenance volume toward certified commercial facilities.
- PESCO maritime readiness framework:The EU's defense cooperation mechanism is harmonizing technical standards for cross-border submarine overhaul work, enabling pooled procurement across French, Italian, and Dutch naval bases.
- Sensor-based condition monitoring:Predictive analytics platforms are displacing calendar-driven maintenance schedules for propulsion equipment, reducing unplanned dry-docking incidents and extending operational deployment cycles.
Market Restraints
- Specialized steel alloy scarcity:HY-80 and HY-100 submarine hull steels face concentrated sourcing from legacy US and Japanese mills, creating input cost volatility and qualification delays for non-traditional suppliers.
- Nuclear certification barriers:NAVSEA's reactor safety protocols limit private shipyard participation in aircraft carrier refueling complex overhauls, preserving Huntington Ingalls Industries' effective monopoly at Newport News.
- Skilled welder pipeline collapse:Military-grade hull welding certifications require multi-year apprenticeship tracks that civilian maritime academies have deprioritized, constraining workforce scalability across European and Indo-Pacific repair yards.
Strategic Opportunities
- Australian nuclear submarine transition:The AUKUS pact's Virginia-class acquisition pathway creates demand for reactor compartment maintenance training and infrastructure development at Adelaide's Osborne Naval Shipyard.
- Digital twin integration:Convergence of 3D hull scanning with finite element analysis software is enabling virtual dry-docking simulations that reduce physical inspection man-hours for surface combatants.
- South Korean diesel-electric submarine exports:Changbogo III-class sales to Indonesia and Vietnam are extending K-shipyard MRO service agreements into third-country maintenance networks, capturing lifecycle revenue beyond original build contracts.
Industry Challenges
- Combat system cybersecurity recertification:NATO's classified network integration standards for Aegis and PAAMS upgrades impose 18-24 month validation timelines that delay revenue recognition and strain project cash flows.
- Legacy mechanical-electrical interface complexity:Steam turbine propulsion plants on Ticonderoga-class cruisers resist seamless integration with modern integrated power systems, forcing bespoke engineering solutions that erode standardization economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Naval Vessel MRO Market |
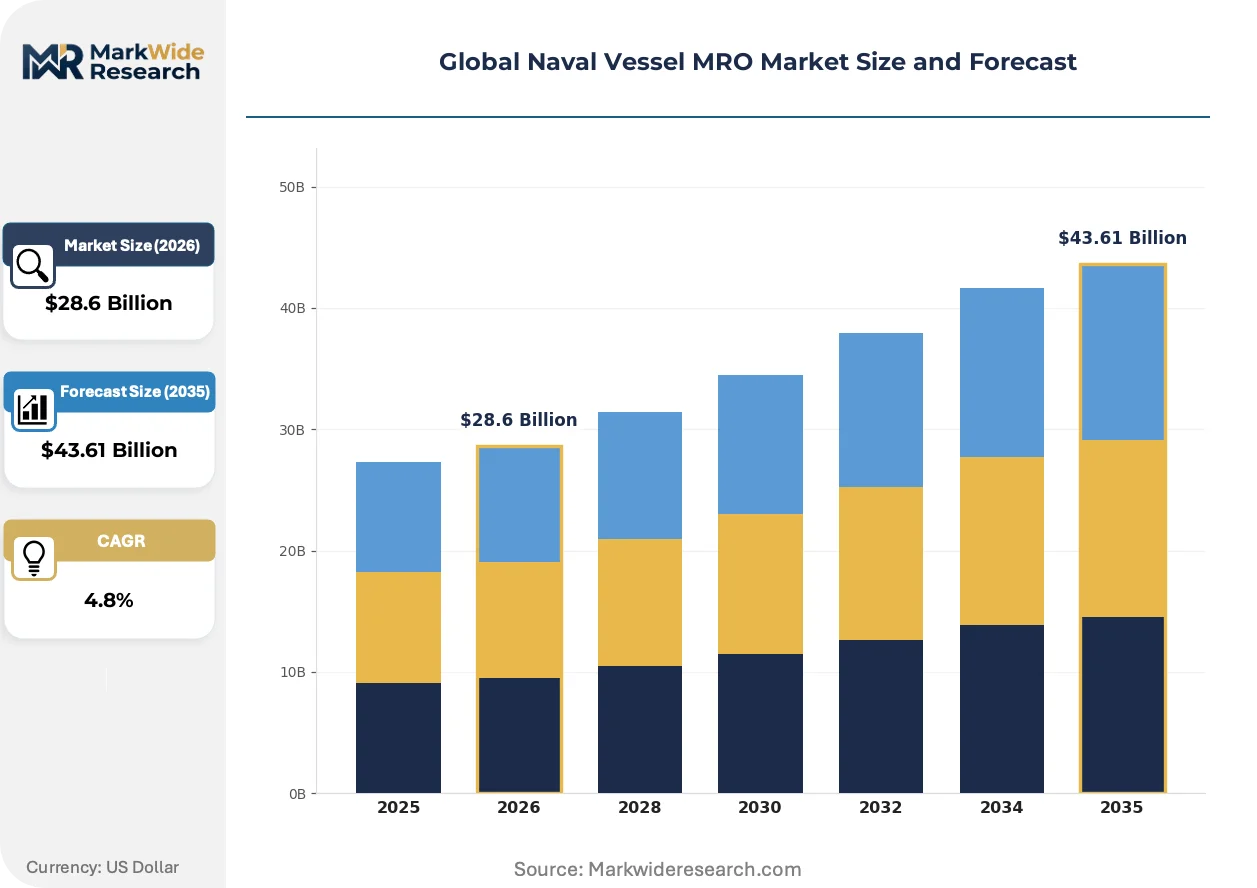
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Refurbishment Vessel Type: Submarine, Destroyer, Frigate, Aircraft Carrier Technology: Automation, Simulation, Predictive Analytics, Cybersecurity Client Type: Government, Military, Private Sector, Contractors |
| Companies Covered | Northrop Grumman, Raytheon Technologies, BAE Systems, Thales Group, Naval Group, General Dynamics, Lockheed Martin, Saab, Huntington Ingalls Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Naval Vessel MRO Market Strategic Shifts
Digitalization is compressing maintenance cycles while regulatory fragmentation across allied naval standards complicates cross-border contractor mobility. Three developments are restructuring competitive positioning in naval vessel overhaul services.
Additive manufacturing is penetrating naval MRO through directed energy deposition repairs for submarine propeller shafts and turbine blade restoration. US and British naval engineers are qualifying wire-arc processes for in-situ hull crack remediation, reducing dry-docking duration for emergency repairs. Metal powder fusion technology is miniaturizing repair footprints, enabling underway replenishment vessels to carry mobile fabrication units for at-sea component replacement.
The EU's MDR and CE marking regimes are tightening material traceability requirements for hull steel and cathodic protection anodes installed on European-flagged naval auxiliaries. Shipyards in France and Italy must now document alloy composition back to smelter batch codes, extending procurement lead times for specialty corrosion-resistant materials. German and Dutch surface combatant programs are responding by pre-qualifying integrated suppliers with existing medical-device-grade metallurgical certification.
Lifecycle availability contracting is displacing transactional repair orders among Indo-Pacific navies facing fleet expansion constraints. Japanese and Australian defense procurement offices now specify operational readiness guarantees rather than discrete work packages, transferring performance risk to prime contractors. South Korea's Defense Acquisition Program Administration has piloted this model on Daegu-class frigate sustainment, with Hyundai Heavy Industries assuming full responsibility for hull, mechanical, electrical, and combat system availability across ten-year terms.
Global Naval Vessel MRO Market Segmentation
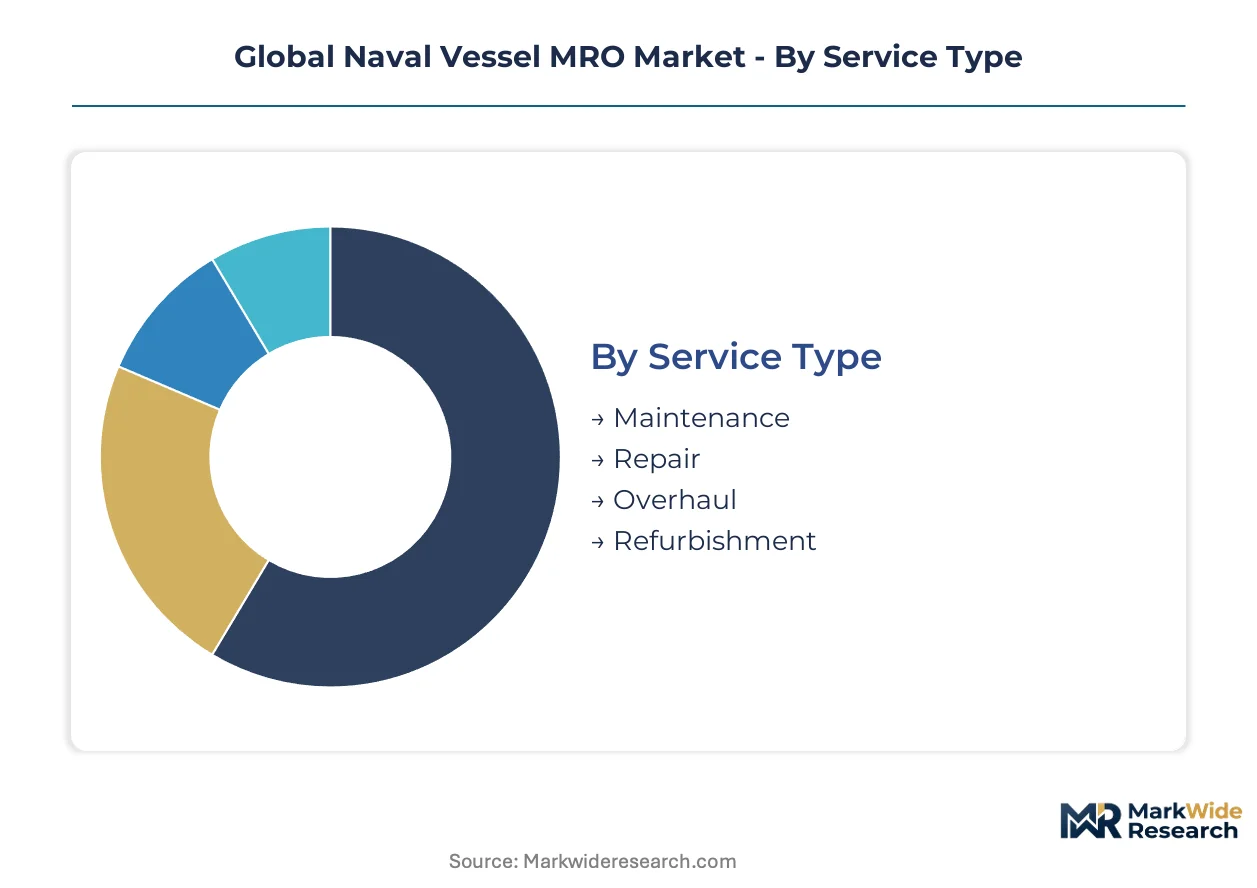
Segmentation in naval vessel MRO reveals where capital deployment concentrates across contract structures and technical capabilities. Each dimension exposes distinct margin dynamics, from sovereign procurement rules to emerging digital service lines.
Service Type:
Margin pools concentrate in overhaul and refit work, where technical complexity creates pricing power unavailable in routine maintenance.
- Maintenance:Scheduled hull preservation, lubrication systems servicing, and corrosion prevention on steel-hulled surface combatants. Demand clusters in Indo-Pacific sovereign yards where Japan, Australia, and South Korea extend dry-docking cycles for diesel-electric submarine fleets.
- Repair:Unscheduled damage remediation, emergency hull welding, and propulsion system restoration following mechanical failure. Royal Navy and US Navy surface ship contracts at Portsmouth and Norfolk facilities absorb disproportionate man-hours relative to contract frequency.
- Overhaul:Deep structural intervention including turbine blade refurbishment, reactor compartment work, and combat management system recertification.
- Refurbishment:Lifecycle extension programs integrating new sensor arrays and power distribution architectures into legacy hulls.
The dominant share belongs to Overhaul, while Predictive Analytics-enabled maintenance contracts are closing the gap fastest.
Vessel Type:
Cost tier stratification separates nuclear-powered capital ships from conventionally propelled surface combatants, with submarine work commanding specialized premiums.
- Submarine:HY-80 and HY-100 hull steel welding, reactor compartment maintenance, and periscope/optical system overhaul. French and British nuclear deterrent patrol schedules at Cherbourg and Faslane sustain continuous demand for pressure hull recertification.
- Aircraft Carrier:Flight deck resurfacing, catapult system refurbishment, and nuclear refueling complex overhaul. NAVSEA certification requirements limit qualified yards to Newport News and select sovereign facilities, preserving concentrated contractor relationships.
- Destroyer:Aegis combat system upgrades, gas turbine replacement, and vertical launch system maintenance.
- Frigate:Diesel-electric propulsion servicing, sonar dome replacement, and medium-caliber gun mount overhaul.
Submarine work retains the steepest pricing tier, though Aircraft Carrier refits capture the largest absolute contract values.
Technology:
Application focus distinguishes operational technologies from infrastructure systems, with revenue migrating toward data-driven service models.
- Predictive Analytics:Sensor-based condition monitoring for propulsion plants, finite element analysis of hull stress patterns, and algorithmic dry-docking scheduling. US and Japanese naval engineers deploy these platforms to displace calendar-driven maintenance on Aegis-equipped destroyers.
- Cybersecurity:Combat system network hardening, classified data link certification, and NATO STANAG compliance validation. EU PESCO frameworks impose 18-24 month recertification timelines that reshape contractor qualification thresholds.
- Automation:Robotic hull inspection crawlers and automated welding systems for confined-space propulsion compartment work.
- Simulation:Digital twin hull modeling and virtual dry-docking environments for pre-maintenance planning.
Predictive Analytics is expanding most quickly, while Cybersecurity commands the highest contract premiums per man-hour.
Client Type:
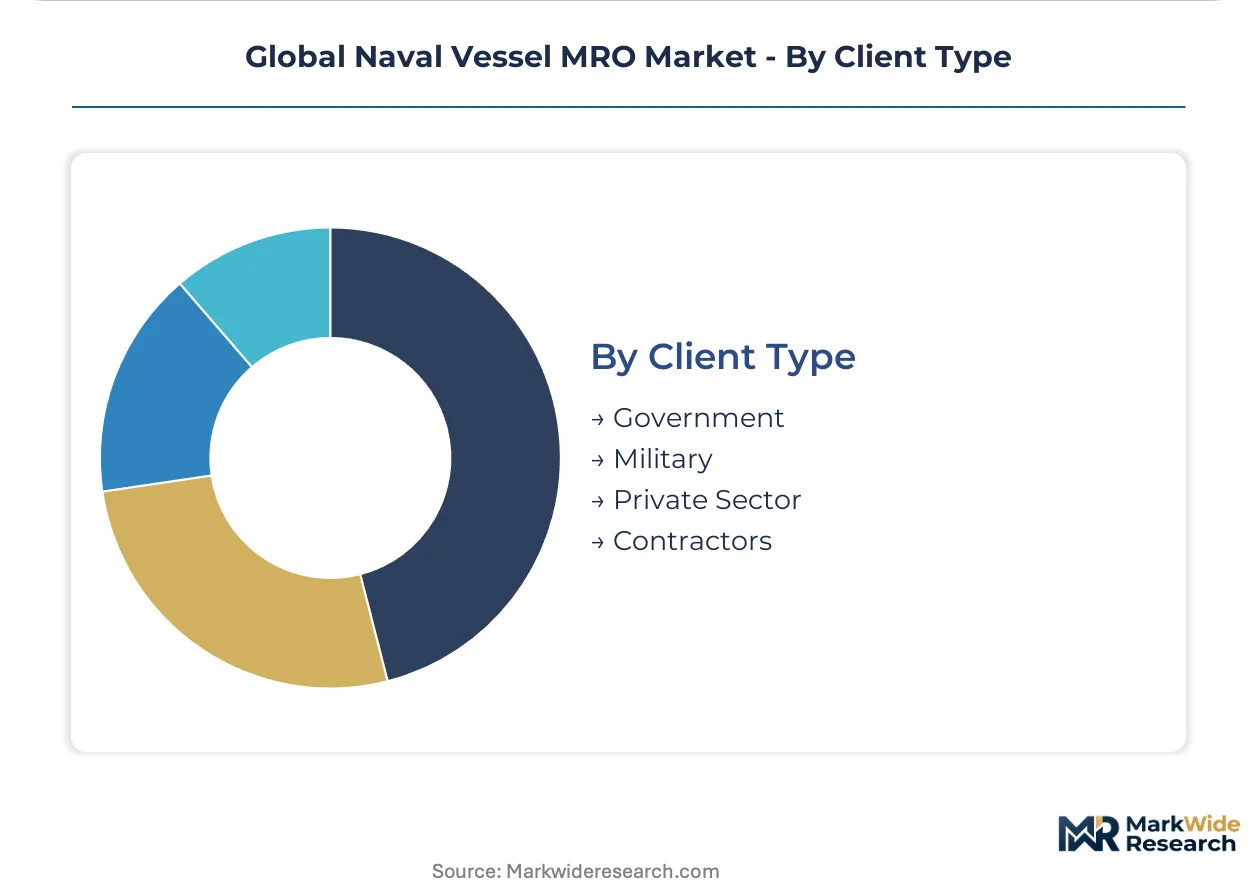
Customer type determines procurement rigidity, with sovereign defense ministries imposing certification barriers that private sector clients cannot replicate.
- Government:National defense ministries specifying lifecycle availability guarantees and operational readiness thresholds. Australian and Japanese procurement offices now transfer performance risk to prime contractors through decade-long sustainment terms.
- Military:Service-specific commands with dedicated maintenance budgets and organic shipyard capabilities. US Navy NAVSEA sets hull integrity standards that dictate private yard access to nuclear propulsion contracts.
- Private Sector:Commercial ship operators and research vessel owners requiring non-military grade hull certification.
- Contractors:Prime defense integrators subcontracting specialized welding, electronics, or nuclear work to certified third parties.
Government clients dominate committed spend, though Contractors are capturing expanding scope as availability-based contracting proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Navy's four public shipyards at Norfolk, Puget Sound, Pearl Harbor, and Portsmouth constitute the backbone of Western naval maintenance infrastructure, underwriting American capacity to service nuclear aircraft carriers and ballistic missile submarines through 2040.
United States
NAVSEA's shipyard recapitalization program drives demand for private nuclear certification, with Newport News and select Gulf Coast facilities absorbing overflow from congested public yards. The Jones Act preserves domestic hull repair mandates for military and commercial fleets alike. Norfolk Naval Shipyard in Virginia and Puget Sound Naval Shipyard in Washington concentrate skilled welder pools for HY-80 pressure hull work.
United Kingdom
Royal Navy submarine deterrent patrol schedules at Faslane sustain continuous pressure hull recertification demand, while surface ship overhauls concentrate at BAE Systems' Portsmouth facility. The UK Ministry of Defence's National Shipbuilding Strategy directs maintenance investment toward Scottish and English clusters. Barrow-in-Furness and Portsmouth anchor the UK's nuclear and conventional vessel overhaul capacity respectively.
France
Naval Group's Cherbourg and Toulon yards capture continuous ballistic missile submarine and aircraft carrier refit cycles under the Direction Générale de l'Armement's long-term planning. EU PESCO maritime readiness frameworks enable cross-border subcontracting with Italian and Dutch facilities. The Brittany and Mediterranean coasts host Europe's most concentrated sovereign submarine maintenance infrastructure.
Japan
Maritime Self-Defense Force diesel-electric submarine dry-docking cycles at Kure and Yokosuka naval bases extend operational availability for Soryu and Taigei-class boats. METI's defense production base maintenance policies preserve domestic steel alloy sourcing for hull work. The Seto Inland Sea industrial corridor concentrates Mitsubishi Heavy Industries and Kawasaki shipyard capacity for surface combatant overhaul.
Australia
The AUKUS nuclear submarine transition generates reactor compartment maintenance training demand at Adelaide's Osborne Naval Shipyard, with infrastructure expansion underway through 2030. The Australian Defence Force's shift toward lifecycle availability contracting transfers performance risk to prime contractors. South Australia's Osborne precinct represents the Indo-Pacific's fastest-growing naval maintenance investment zone.
Global Naval Vessel MRO Market Competitive Environment
Concentration sits with sovereign-integrated primes possessing nuclear certification and classified facility clearances. Huntington Ingalls Industries maintains effective monopoly positioning on US aircraft carrier refueling complex overhauls through Newport News operations, while European demand fragments across Naval Group, BAE Systems, and Thales Group facilities with divergent national procurement rules. Strategic archetypes divide between nuclear-certified sovereign yards, combat system integrators with cybersecurity clearances, and predictive analytics platform vendors displacing calendar-driven maintenance schedules. Competitive moves center on reactor compartment infrastructure partnerships and digital twin capability acquisitions.
Within the nuclear-certified sovereign tier, Huntington Ingalls Industries and BAE Systems exemplify archetypes of geographically concentrated monopoly maintenance providers. Naval Group occupies a comparable position in European submarine overhaul. Among combat system specialists, Northrop Grumman, Raytheon Technologies, and Lockheed Martin sit within the classified electronics integration segment where NATO STANAG compliance and Aegis certification create qualification barriers that preserve incumbent positioning across allied fleet upgrade programs.
| Leading Market Players |
|---|
| Northrop Grumman |
| Raytheon Technologies |
| BAE Systems |
| Thales Group |
| Naval Group |
| General Dynamics |
| Lockheed Martin |
| Saab |
| Huntington Ingalls Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term availability contracting locks in HY-80 steel allocation and skilled welder capacity years ahead of dry-docking windows, giving Australian and Japanese defense ministries price visibility while transferring performance risk to Huntington Ingalls Industries and BAE Systems. This structure concentrates pricing power with nuclear-certified primes that control scarce certification pathways.
Pricing Analysis
Three-tier pricing structure across nuclear-certified, conventional sovereign, and commercial-grade maintenance levels segments the market by technical barrier height. NAVSEA reactor safety protocols and NATO STANAG compliance tiers differentiate price floors, with cybersecurity-cleared combat system work commanding premiums over hull preservation. Cost compression in conventional surface ship refits intensifies as South Korean yards expand third-country service agreements. Government clients show lowest price sensitivity given operational readiness mandates, while private sector vessel operators face acute budget constraints.
Supply Chain Analysis
The United States and Japan anchor submarine-grade HY-80 and HY-100 steel production through legacy mills with multi-decade qualification histories. Specialized alloy sourcing draws from concentrated smelter batch codes tracked under EU MDR traceability regimes, while cathodic protection anodes and turbine blade castings feed from German and Italian metallurgical suppliers. Single-source vulnerability runs through Japanese HY-steel mills facing capacity constraints. Distribution runs through sovereign shipyard networks with classified facility clearances, limiting commercial channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle availability platforms are displacing transactional repair economics, with Australian and Japanese procurement offices now mandating decade-long operational readiness guarantees that mirror software-as-a-service interoperability models across allied naval maintenance networks.
For Market Incumbents: Shield reactor compartment certification monopolies through accelerated infrastructure partnerships at Adelaide's Osborne Naval Shipyard and expanded Newport News capacity. Combat system cybersecurity recertification delays threaten margin stability; prioritize NAVSEA and NATO STANAG pre-clearance investments to compress 18-24 month validation timelines. For New Entrants and Emerging Players: NAVSEA nuclear welder certification fast-tracks offer entry into aircraft carrier refueling overflow work as US public shipyards face congestion. Target predictive analytics platform deployment for Aegis-equipped destroyer fleets, where sensor-based condition monitoring displaces calendar-driven maintenance with lower capital requirements than hull infrastructure. For Investors and Strategic Acquirers: Combat system integrators with classified network clearances represent durable acquisition targets given NATO cybersecurity mandate expansion. Long-term viability hinges on AUKUS infrastructure buildout completion and PESCO cross-border subcontracting harmonization. Watch South Korean diesel-electric submarine export volumes as third-country MRO service agreement penetration signals.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Compartment Certification Partnership | NAVSEA pre-qualification at Newport News unlocks nuclear carrier refueling contract access. |
| Predictive Analytics Platform Deployment | Sensor-based condition monitoring displaces calendar-driven schedules for Japanese Aegis destroyers. |
| AUKUS Infrastructure Development | Osborne Naval Shipyard expansion captures Virginia-class maintenance training demand. |
| Cybersecurity Clearance Acquisition | NATO STANAG compliance enables Aegis and PAAMS upgrade contract eligibility. |
| HY-Steel Supplier Integration | Backward integration into Japanese and US legacy mills secures alloy traceability under EU MDR. |
Study Parameters
The analysis maps maintenance-overhaul-refit service tiers, each validated through shipyard operations directors, defense ministry procurement officers, and naval engineering program managers. Primary fieldwork combined with secondary validation from NAVSEA technical directives, NATO Standardization Office protocols, EU PESCO framework documents, and sovereign defense budget appropriations. Bottom-up contract value aggregation triangulates against top-down fleet size and dry-docking cycle assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include vessel type, service complexity tier, technology application, and client procurement structure. CAGRs derive from dry-docking frequency projections, fleet age demographics, and availability contracting penetration rates. Nuclear certification pipeline constraints and skilled welder apprenticeship completion rates feed directly into capacity-limited growth assumptions.
Underlying assumptions cover sovereign defense budget continuity, HY-steel mill capacity stability, and NAVSEA certification protocol consistency, with deviation risk concentrated in AUKUS timeline acceleration and EU PESCO implementation scope. Recalibration cycles align with material shifts in allied naval modernization program announcements and submarine fleet transition milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Military Frigate Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Combat Management System Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Naval Artillery System Market