
 High Altitude Pseudo Satellites Market | 2026-2036
High Altitude Pseudo Satellites Market Size, Share, and Industry Trends Forecast 2026-2036
High Altitude Pseudo Satellites Market Outlook
European airship manufacturing capacity is shifting toward heavier-than-air platforms with multi-week endurance. Airbus SE leverages its stratospheric program heritage to anchor development of solar-powered pseudo-satellites for telecommunications and Earth observation. Thales Group competes through integrated payload and communications systems that extend platform utility across defense and civilian missions. Prismatic (BAE Systems) specializes in lightweight structures that reduce launch and operational costs for persistent altitude operations.
High altitude pseudo satellites are unmanned aerial platforms operating at 18-25 kilometer altitudes, where atmospheric density permits extended loiter using solar-electric or hybrid propulsion while positioning above commercial air traffic and below orbital regimes. These systems function as geostationary relay points for telecommunications backhaul, wide-area surveillance, and environmental data collection without the launch economics of traditional satellites. Airship systems currently lead in payload capacity and mission duration, though drone platforms represent the fastest-growing category as battery energy density improves and autonomous navigation technology matures. Solar power technology dominates current deployments, while hybrid systems are emerging where continuous operations must survive extended night duration at high latitudes.
FAA regulations in the United States govern airspace integration and operational certification for stratospheric platforms, while EASA in Europe develops analogous frameworks under the EU drone regulatory package. The UK Civil Aviation Authority has established specific operating conditions for high altitude long endurance trials, influencing where manufacturers conduct flight testing and early commercial deployment. Stakeholders must monitor evolving spectrum allocation decisions by national regulators and the ITU, as pseudo-satellite constellations will compete with terrestrial and orbital systems for Ka-band and V-band frequencies essential for broadband connectivity.
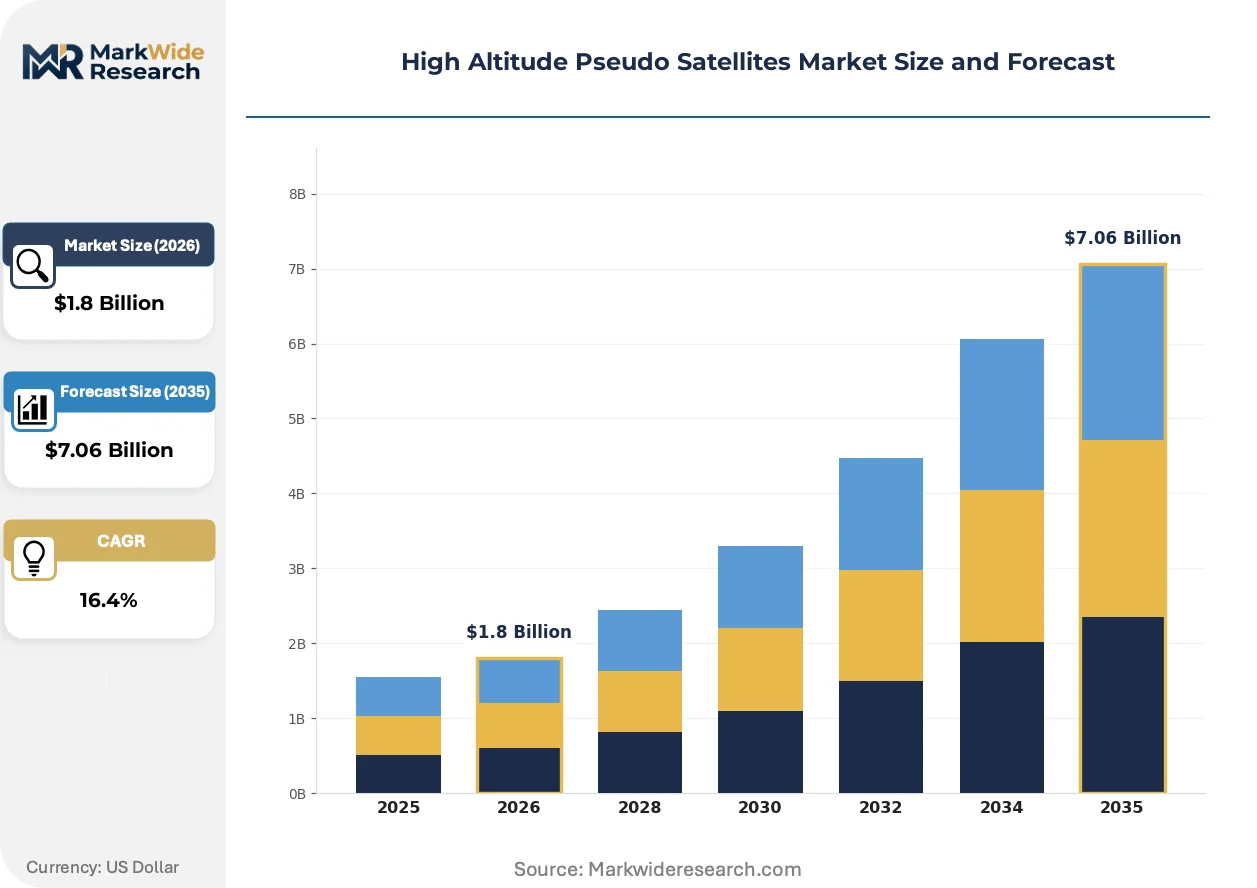
Market Dynamics
Defense procurement cycles in the United States, United Kingdom, and Japan are compressing development timelines for stratospheric platforms while solar-electric propulsion advances extend operational endurance thresholds.
Growth Catalysts
- Defense Modernization Budgets:Military surveillance programs across NATO member states prioritize persistent intelligence platforms capable of weeks-long station-keeping above contested airspace.
- FAA Certification Pathways:The United States aviation regulator's stratospheric airspace integration framework reduces regulatory uncertainty for commercial telecom trials and Earth observation missions.
- Lightweight Composite Materials:Carbon fiber and polymer matrix advances cut platform mass by double-digit percentages, directly improving payload capacity and power-to-weight ratios for solar-electric systems.
Market Restraints
- Stratospheric Weather Volatility:Jet stream turbulence and seasonal wind shear at 20-kilometer altitudes impose structural loading requirements that inflate airframe engineering costs.
- Helium Supply Concentration:Lighter-than-air platforms depend on helium extraction concentrated in Qatar, Algeria, and the United States, creating input cost vulnerability and geopolitical exposure.
- Orbital Satellite Substitution:Low Earth orbit constellation deployments by SpaceX and competitors threaten pseudo-satellite addressable market for broadband backhaul applications.
Strategic Opportunities
- Arctic Telecommunications:Extended polar night conditions exclude pure solar platforms, creating demand for hybrid propulsion systems in Norway, Canada, and Alaska.
- EASA Regulatory Tailwind:The European Union's drone regulatory package creates harmonized certification pathways for cross-border stratospheric operations spanning multiple member states.
- Environmental Data Collection:Climate monitoring agencies seek persistent altitude platforms for methane tracking and wildfire detection, opening civilian application expansion beyond defense and telecom.
Industry Challenges
- Stratospheric Flight Crew Certification:Licensed operators capable of managing autonomous systems through upper-atmosphere weather transitions remain scarce, constraining fleet scaling.
- Ka-band Spectrum Coordination:ITU allocation processes for pseudo-satellite constellations lag platform deployment timelines, creating operational uncertainty for broadband service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Altitude Pseudo Satellites Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tethered Systems, Airships, Drones, Balloon Systems Technology: Solar Power, Hybrid Systems, Autonomous Navigation, Communication Systems End User: Government Agencies, Telecommunications, Defense, Remote Sensing Application: Disaster Management, Surveillance, Environmental Monitoring, Connectivity |
| Companies Covered | AeroVironment, Inc., Airbus SE, Prismatic (BAE Systems), Thales Group, Aurora Flight Sciences (The Boeing Company), SoftBank Corp., World View Enterprises, Inc., Kea Aerospace, Sceye Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Altitude Pseudo Satellites Market Strategic Shifts
Solid-state battery chemistry improvements and autonomous navigation algorithms are converging to expand mission profiles beyond the endurance limits that currently constrain operational economics.
Solid-state lithium-metal batteries are rewriting the operational calculus for high-altitude drone platforms by delivering energy density improvements that compress the performance gap with airship endurance. Defense contractors and commercial telecom operators are accelerating procurement evaluations of battery-electric systems for missions under 90 days. This chemistry shift is rewriting supplier competitive positions by elevating cell manufacturers to tier-one platform partnerships previously dominated by airframe integrators.
EASA's EU drone regulatory package establishes type-certification baselines for unmanned aircraft operating above 500 feet, directly enabling cross-border stratospheric trials that national aviation authorities previously fragmented. The framework mandates detect-and-avoid capabilities and command-link redundancy that inflate development costs but reduce operational insurance premiums. European manufacturers are responding by consolidating flight testing in Spain and Germany where CAA implementation timelines align with platform readiness.
Telecom operators are unbundling connectivity service contracts from hardware ownership, shifting procurement toward availability-based leasing models that transfer platform risk to manufacturers and specialized fleet operators. This restructuring concentrates buyer power among tier-one mobile network operators while displacing traditional satellite bandwidth resellers. The United States and Japan exhibit the most advanced contracting sophistication, with European carriers trailing by approximately 18-24 months in adoption velocity.
High Altitude Pseudo Satellites Market Segmentation
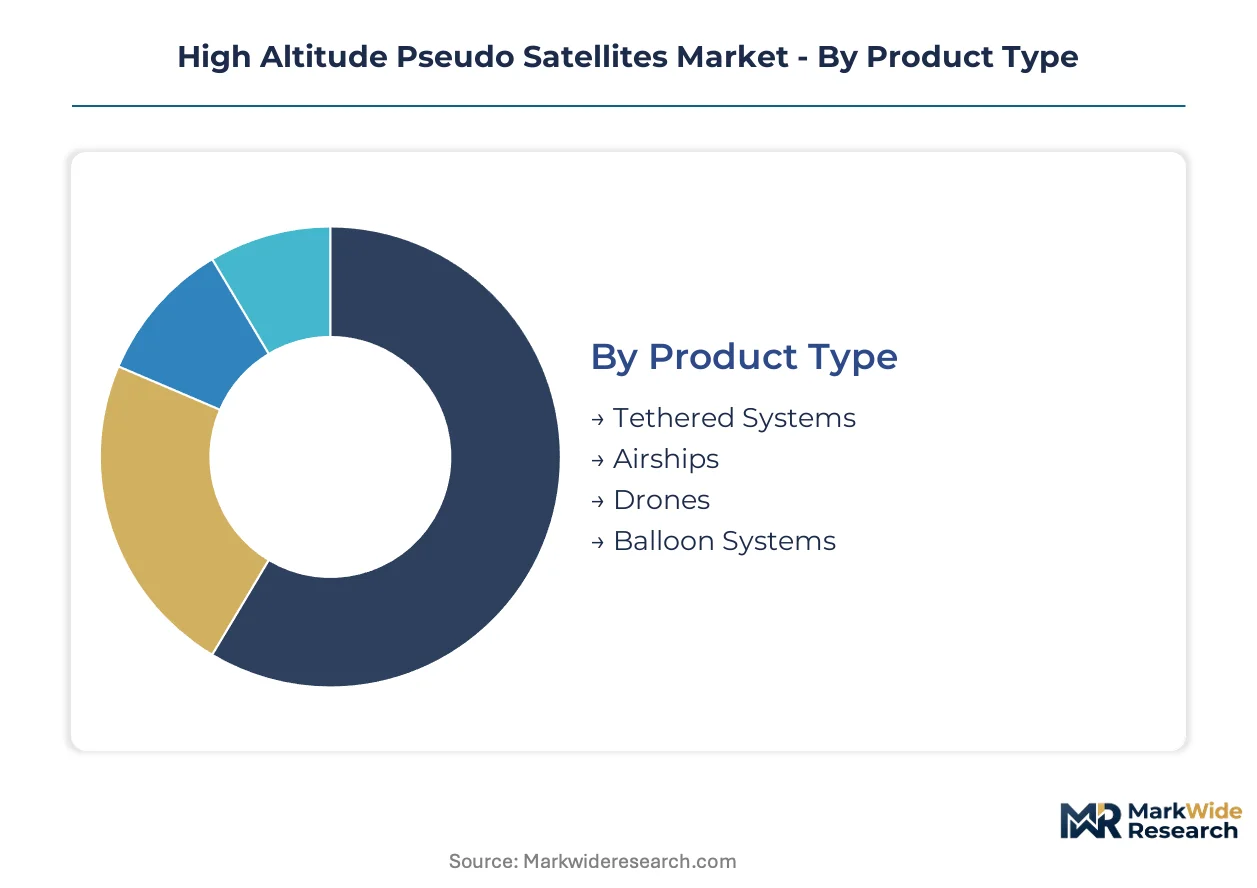
Platform architecture and energy systems define competitive positioning in the High Altitude Pseudo Satellites Market. Segmentation reveals how payload capacity, endurance economics, and regulatory pathways cluster around distinct technical configurations.
Product Type:
Structural engineering choices determine altitude persistence and operational flexibility across competing platform designs.
- Airships:Lighter-than-air envelopes deliver the highest payload fractions and multi-month endurance for persistent surveillance missions. Defense procurement in the United States and Japan concentrates here for contested airspace intelligence gathering.
- Drones:Fixed-wing and multi-rotor configurations leverage solid-state battery advances to compress endurance gaps with buoyant systems. Commercial telecom trials in the United States and United Kingdom favor this category for rapid deployment cycles.
- Tethered Systems:Ground-connected platforms provide localized coverage with unlimited power duration for disaster response scenarios.
- Balloon Systems:High-altitude latex and Mylar envelopes offer lowest-cost entry for short-duration environmental monitoring campaigns.
Mature deployment sits with Airships. Newer deployment is concentrated in Drones.
Technology:
Energy architecture and autonomy systems differentiate operational envelopes across latitude and seasonality requirements.
- Solar Power:Photovoltaic arrays integrated with lightweight airframes enable indefinite daytime operations and regenerative battery cycling. Equatorial and mid-latitude telecom backhaul missions in the United States and Japan rely on this dominant configuration.
- Hybrid Systems:Combined solar-hydrogen or solar-diesel architectures sustain operations through extended polar night conditions. Norwegian and Canadian Arctic connectivity trials are expanding this segment's commercial relevance.
- Autonomous Navigation:Machine learning flight control reduces operator burden for station-keeping in stratospheric wind shear.
- Communication Systems:Integrated Ka-band and V-band payloads transform platforms into geostationary relay alternatives.
Solar Power anchors current fleet economics. Hybrid Systems are gaining share fastest where seasonal darkness excludes pure electric platforms.
End User:
Procurement sophistication and contracting models diverge sharply across institutional buyer categories.
- Defense:Military surveillance programs prioritize weeks-long persistence above denied airspace with hardened command links. NATO member state modernization budgets in the United States and United Kingdom dominate contract volume.
- Telecommunications:Mobile network operators pursue availability-based leasing to transfer platform risk and avoid capital intensity. Japanese carriers lead contracting sophistication with 18-24 month adoption advantage over European counterparts.
- Government Agencies:Civilian environmental and disaster response missions seek persistent altitude for methane tracking and wildfire detection.
- Remote Sensing:Commercial Earth observation operators demand sub-meter resolution with rapid revisit cycles.
Defense procurement commands premium platform specifications. Telecommunications is climbing the fastest as service-based models displace hardware ownership.
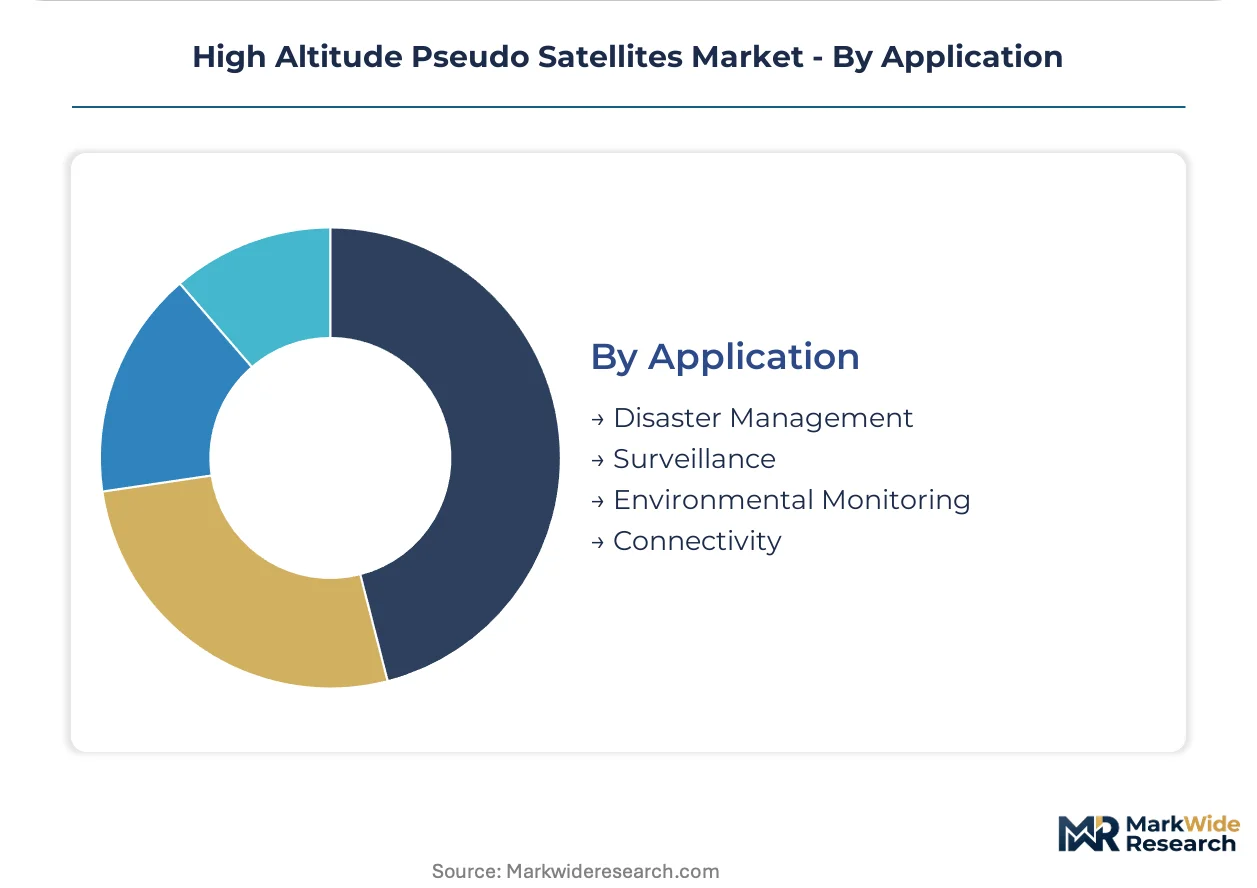
Application:
Mission requirements dictate payload integration priorities and regulatory coordination intensity.
- Surveillance:Wide-area motion imagery and signals intelligence demand stabilized gimbal systems and high-bandwidth downlinks. United States Indo-Pacific Command operations drive specification standards.
- Connectivity:Broadband backhaul for underserved regions requires seamless spectrum coordination with terrestrial and orbital systems. FAA certification pathways in the United States accelerate commercial trials.
- Environmental Monitoring:Atmospheric chemistry sensors and thermal imaging support climate science and emissions verification.
- Disaster Management:Rapid-deploy communications restoration follows infrastructure damage with temporary cellular and internet relay.
Surveillance applications anchor defense procurement. Connectivity represents the steepest expansion trajectory as telecom operators unbundle service contracts from hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction concentrates in Qatar, Algeria, and the United States, creating geographic dependencies that shape where stratospheric platforms deploy and where manufacturers establish flight-testing infrastructure.
United States
Defense procurement from the Pentagon and Indo-Pacific Command drives demand for persistent surveillance platforms capable of weeks-long station-keeping. FAA certification pathways for stratospheric airspace integration reduce regulatory uncertainty for commercial telecom trials. Flight testing concentrates in Arizona and New Mexico where military ranges and clear airspace permit extended endurance missions.
United Kingdom
Stratospheric intelligence programs prioritize denied-airspace persistence above contested regions. The UK Civil Aviation Authority has established specific operating conditions for high-altitude long-endurance trials. Manufacturing activity clusters in southern England where BAE Systems heritage and aerospace supply chains support platform development.
Japan
Mobile network operators pursue availability-based leasing models that transfer platform risk to manufacturers. METI coordinates national broadband backhaul initiatives targeting rural and maritime coverage gaps. Tokyo-based carriers lead contracting sophistication with advanced procurement frameworks for pseudo-satellite services.
Germany
EASA regulatory harmonization enables cross-border stratospheric operations spanning multiple member states. The EU drone regulatory package mandates detect-and-avoid capabilities that inflate development costs but reduce insurance premiums. Flight testing consolidates in Bavaria and Baden-Württemberg where aviation authorities align implementation timelines with platform readiness.
Norway
Extended polar night conditions exclude pure solar platforms, creating demand for hybrid propulsion systems in Arctic telecommunications trials. National regulators coordinate spectrum allocation for Ka-band connectivity in high-latitude regions. Tromsø and northern testing ranges host endurance validation for combined solar-hydrogen architectures.
High Altitude Pseudo Satellites Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in environmental monitoring and disaster response applications. The vendor base spans defense primes with stratospheric heritage, aerospace conglomerates leveraging platform integration capabilities, and specialized lightweight structure fabricators. Three archetypes dominate: airship envelope specialists, solar-electric propulsion integrators, and communications payload providers. Competitive moves concentrate on strategic partnerships for spectrum coordination and capacity expansion in flight-testing infrastructure.
Among defense-heritage integrators, Airbus SE and Prismatic anchor positions shaped by military surveillance program requirements and lightweight structure specialization. Thales Group exemplifies the communications-systems archetype, occupying a position where integrated payload and relay capabilities extend platform utility across dual-use missions. These three entities represent distinct competitive vectors: European conglomerate scale, BAE Systems-affiliated fabrication expertise, and French electronics integration heritage.
| Leading Market Players |
|---|
| AeroVironment, Inc. |
| Airbus SE |
| Prismatic (BAE Systems) |
| Thales Group |
| Aurora Flight Sciences (The Boeing Company) |
| SoftBank Corp. |
| World View Enterprises, Inc. |
| Kea Aerospace |
| Sceye Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive integration into helium extraction and stratospheric flight-testing infrastructure anchors both supply security and pricing power for lighter-than-air platform manufacturers. This vertical control over scarce noble gas sourcing and restricted airspace access creates asymmetric leverage against buyers seeking multi-month endurance missions.
Pricing Analysis
Availability-based leasing models unbundle hardware ownership from connectivity service delivery, transferring platform risk to manufacturers while compressing upfront capital requirements for telecom operators. Price differentiation rests on endurance guarantees and payload customization tiers, with defense procurement absorbing premium specifications while civilian environmental monitoring drives cost compression. Pricing pressure stems from solid-state battery advances narrowing the endurance gap with buoyant systems. Mobile network operators exhibit highest price sensitivity, whereas military surveillance programs prioritize mission persistence over unit economics.
Supply Chain Analysis
Domestic-content mandates in the United States and Japan are reshaping sourcing patterns for stratospheric platform components, pressuring manufacturers to qualify alternative suppliers outside traditional European aerospace clusters. Helium extraction concentrates in Qatar, Algeria, and the United States, while carbon fiber airframe fabrication draws from Japan, Germany, and the United States. Single-source vulnerability in noble gas supply creates exposure to geopolitical disruption and extraction quota constraints. Distribution runs through defense prime contractors and specialized fleet operators who manage platform lifecycle logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Altitude Pseudo Satellites Market sits in a technology-transition phase where solid-state lithium-metal chemistry displaces legacy solar-battery architectures for missions under 90 days.
For Market Incumbents: Deepen backward integration into helium storage and stratospheric launch infrastructure to defend against emerging battery-electric entrants eroding endurance advantages. Secure long-term offtake agreements with Qatari and Algerian extraction facilities to lock in input cost positions. Prioritize FAA type-certification investment to maintain regulatory moats against European competitors leveraging EASA harmonization. For New Entrants and Emerging Players: Arctic telecommunications operators in Norway, Canada, and Alaska represent an underserved buyer archetype where hybrid propulsion requirements exclude pure solar incumbents. Environmental data collection agencies seeking methane tracking and wildfire detection capabilities offer fastest penetration pathways outside defense procurement. Pursue availability-based contracting to align revenue models with telecom operator risk-transfer preferences. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime consolidation and telecom infrastructure fund roll-ups rather than standalone IPO liquidity. Long-term viability hinges on spectrum allocation clarity and ITU Ka-band coordination timelines. Watch for FAA certification batch approvals as inflection indicators signaling commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Coordination Partnership | ITU-aligned Ka-band allocation secures broadband backhaul operational certainty for telecom trials. |
| Helium Supply Diversification | Multi-source noble gas sourcing mitigates Qatar concentration risk for lighter-than-air endurance. |
| Hybrid Propulsion Development | Solar-hydrogen architectures unlock polar night missions in Norwegian and Canadian Arctic trials. |
| Flight-Testing Infrastructure Expansion | Arizona and New Mexico range access accelerates FAA certification timelines for commercial deployment. |
| Availability-Based Service Model | Risk-transfer contracting aligns manufacturer incentives with mobile network operator capital constraints. |
Study Parameters
Independent corroboration across platform engineering directors, defense procurement officers, and telecom infrastructure planners underwrites the qualitative findings in this study. Primary fieldwork with stratospheric flight-test engineers, helium supply specialists, and FAA certification consultants combined with secondary validation from FAA airspace integration filings, EASA drone regulatory package documentation, and ITU spectrum allocation records. Bottom-up unit economics modeling and top-down defense budget allocation analysis triangulate market sizing across the analysis window.
Comparable-period anchoring to historical endurance mission records and solar-electric propulsion deployment timelines structured the forecast framework. Segmentation dimensions modeled include platform architecture, energy system configuration, end-user procurement sophistication, and geographic regulatory cluster. CAGRs derive from installed base growth trajectories and replacement cycle compression. Forecast inputs incorporate solid-state battery energy density improvement curves and stratospheric weather pattern volatility indices.
Revisions become necessary when ITU spectrum allocation decisions diverge from platform deployment timelines or when helium extraction disruptions materialize from geopolitical supply constraints. Forecasts reflect documented assumptions regarding FAA certification velocity and EASA cross-border harmonization implementation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
US Satellite Connectivity Market
Satellite
Canada Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
North America Mobile Satellite Services Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Satellite Payload Market
Satellite
Satellite Communication Subsystem Market
Satellite
Satellite Data Service Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Medium and Large Satellite Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Israel Satellite Communications Market
Satellite
EMEA Satellite Antenna Market
Satellite
India Satellite Communication Market
Satellite
Satellite Market
Satellite
India Satellite-Based Earth Observation Market