
 Israel Satellite-Based Earth Observation Market | 2026-2036
Israel Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Satellite-Based Earth Observation Market Insights
ISO 9001 and AS9100 certification requirements for satellite component suppliers is collapsing the vendor pool to a handful of qualified integrators. Israel Aerospace Industries leverages decades of government heritage contracts to anchor domestic manufacturing capacity. ImageSat International competes on commercial imagery exports across selective international markets. Elbit Systems specializes in sensor-to-shooter data chains that differentiate its payload offerings from pure-play satellite operators.
Satellite-based earth observation encompasses the acquisition, processing, and distribution of geospatial data from orbital platforms carrying electro-optical, radar, or hyperspectral instruments operating at altitudes between 400 and 36,000 kilometers, with spatial resolutions ranging from sub-meter to tens of meters depending on mission design. The primary purpose spans defense intelligence, agricultural yield prediction, urban sprawl tracking, and environmental anomaly detection. Optical Satellites occupy the mature revenue base due to established defense procurement rhythms, while Synthetic Aperture Radar represents the fastest-expanding technology segment as all-weather, day-night imaging capabilities attract defense and disaster-response budgets. Remote Sensing technology leads current deployment volumes, though Machine Learning integration in downstream analytics is where margin pools are concentrating as customers demand automated feature extraction rather than raw imagery delivery.
The Israel Space Agency governs launch licensing and orbital slot coordination, while the Ministry of Defense controls classified payload approvals and cross-border data transfer restrictions under national security guidelines. These frameworks create a bifurcated market structure where civilian environmental monitoring operates under lighter oversight while defense and surveillance applications face stringent compartmentalization requirements. Stakeholders must monitor whether loosening of export control thresholds for commercial SAR products will unlock new regional customer bases or trigger tighter countermeasures from competing suppliers.
Market Dynamics
Defense procurement concentration around Tel Aviv and Beersheba is compressing vendor qualification timelines while the Israel Space Agency tightens orbital slot coordination protocols, creating a dual-speed market structure.
Growth Catalysts
- Synthetic Aperture Radar adoption:All-weather imaging capabilities are attracting disaster-response budgets from the Ministry of Defense and civilian emergency agencies alike.
- Machine Learning integration:Automated feature extraction pipelines are displacing raw imagery delivery contracts across agricultural monitoring applications.
- Central Israel aerospace corridor:Talent density around Tel Aviv and Beersheba is accelerating payload-to-orbit development cycles for qualified integrators.
Market Restraints
- ISO 9001 and AS9100 certification barriers:Compliance costs are collapsing the qualified vendor pool to a handful of heritage integrators.
- Cross-border data transfer restrictions:Ministry of Defense national security guidelines compartmentalize commercial SAR export opportunities.
- Optical sensor weather dependency:Cloud cover limitations in Mediterranean climate zones restrict reliable revisit rates for electro-optical missions.
Strategic Opportunities
- Negev Desert calibration facilities:Underutilized test ranges offer expansion capacity for hyperspectral sensor validation before orbital deployment.
- Sensor-to-shooter data chains:Convergence of orbital platforms with tactical edge networks opens defense contracts beyond pure imagery provision.
- Environmental anomaly detection mandates:Israel Space Agency civilian monitoring protocols are creating procurement channels separate from classified defense workflows.
Industry Challenges
- AS9100 certification timelines:Supplier qualification periods extend 18-24 months, delaying new entrant market access.
- Orbital slot coordination complexity:Israel Space Agency licensing queues create mission scheduling uncertainty for commercial operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Satellite-Based Earth Observation Market |
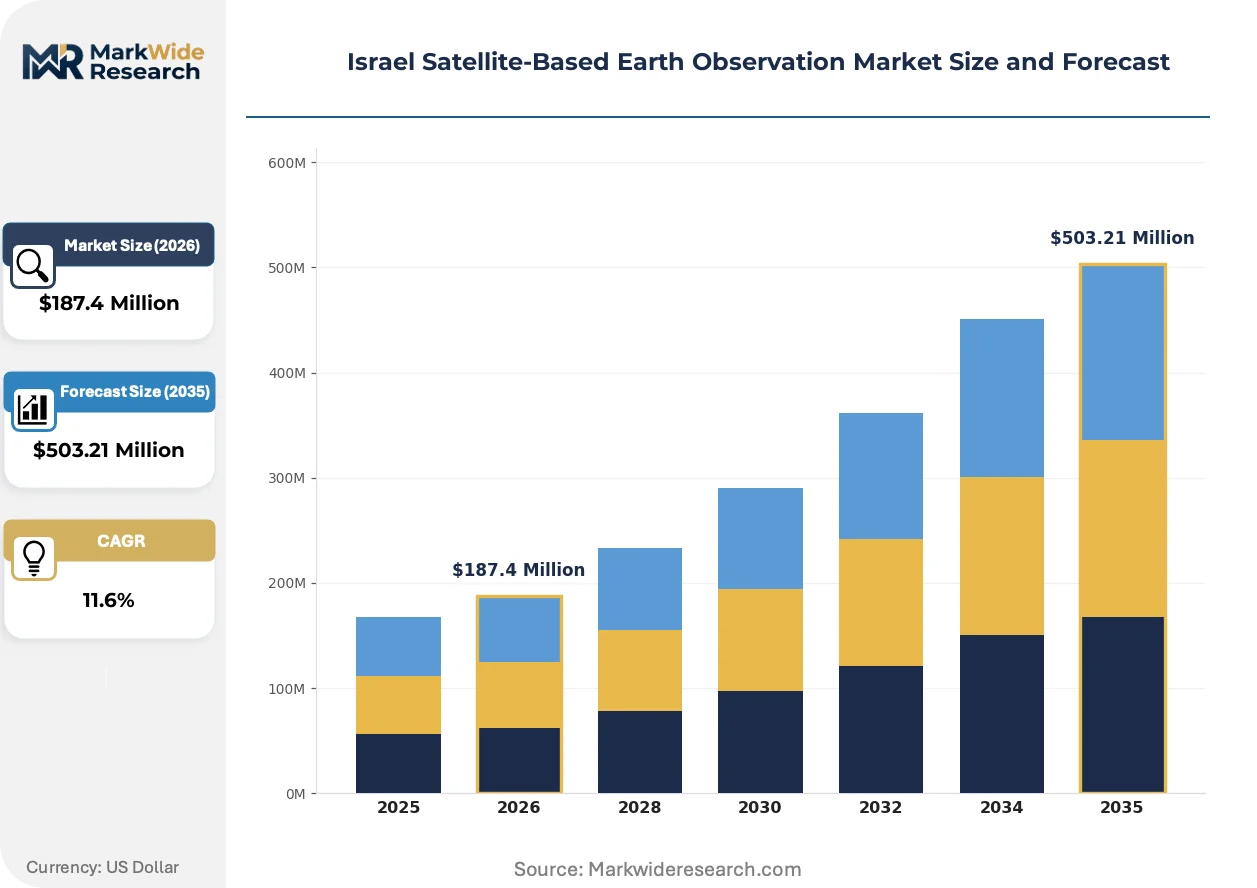
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Hyperspectral Satellites, Synthetic Aperture Radar End User: Agriculture, Defense, Forestry, Urban Planning Technology: Remote Sensing, Data Analytics, Machine Learning, Cloud Computing Application: Environmental Monitoring, Disaster Management, Resource Management, Surveillance |
| Companies Covered | Israel Aerospace Industries, ImageSat International, AMOS Spacecom, Gilat Satellite Networks, Elbit Systems, Rafael Advanced Defense Systems, SES S.A., Orbit Communication Systems, SpaceIL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Satellite-Based Earth Observation Market Trends and Innovations
Payload miniaturization and downstream analytics automation are compressing traditional value chains, while regulatory frameworks bifurcate between civilian environmental monitoring and compartmentalized defense applications.
CubeSat and smallsat form factors are miniaturizing electro-optical and SAR payloads without sacrificing spatial resolution. Agricultural monitoring consortia in the Jezreel Valley are adopting these platforms for weekly crop health surveys. The technology is miniaturizing capital barriers to orbital deployment, enabling university and mid-tier commercial operators to bypass legacy prime contractor relationships.
Israel Space Agency licensing protocols are tightening orbital debris mitigation requirements for new mission approvals. Operators must now demonstrate end-of-life deorbit plans before receiving launch authorization. Smallsat constellations with shorter design lifespans face disproportionate compliance burdens compared to single large-platform missions.
Defense agencies are unbundling raw imagery procurement from analytics services, creating separate contract vehicles for each layer. System integrators like Elbit Systems are capturing sensor-to-shooter data chain contracts while pure-play satellite operators compete on unit image pricing. This pattern concentrates margin pools in Tel Aviv-based software houses with defense security clearances rather than hardware manufacturers.
Israel Satellite-Based Earth Observation Market Segmentation
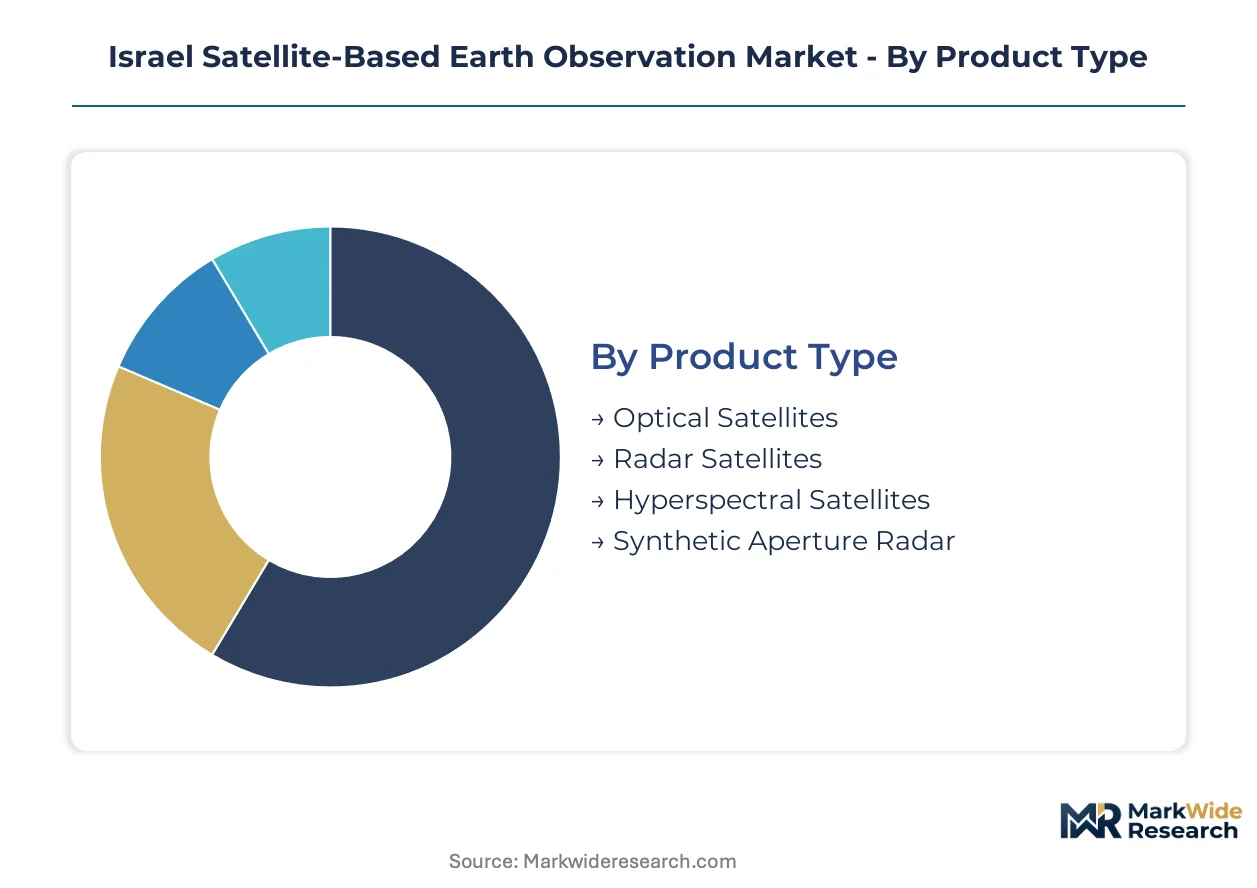
Segmentation in Israel's satellite-based earth observation market reveals how defense procurement rhythms, certification barriers, and technology maturation create divergent margin profiles across product categories. Understanding these fault lines exposes where qualified integrators can defend pricing power versus where commoditization pressures concentrate.
Product Type:
Margin pools in Israel's product type segmentation bifurcate sharply between heritage defense platforms and emerging commercial form factors, with certification requirements acting as the gatekeeping mechanism.
- Optical Satellites:Electro-optical payloads operating in visible and near-infrared spectra deliver sub-meter resolution imagery for defense intelligence and urban mapping. Israeli defense agencies in Tel Aviv anchor procurement volumes, though Mediterranean cloud cover constrains reliable revisit rates during winter months.
- Synthetic Aperture Radar:Active microwave imaging systems penetrate cloud cover and darkness, enabling all-weather surveillance and disaster response coordination. The Ministry of Defense and civilian emergency agencies are redirecting budgets toward SAR capabilities as climate volatility intensifies operational demands.
- Radar Satellites:Broader-category radar platforms encompass altimetry and scatterometry missions beyond pure imaging. These systems serve maritime monitoring applications off Israel's Mediterranean coastline.
- Hyperspectral Satellites:Instruments capturing contiguous spectral bands enable mineral identification and crop stress detection. Agricultural consortia in the Jezreel Valley are piloting these platforms for precision farming applications.
Optical Satellites hold installed capacity. Synthetic Aperture Radar is rotating up the share rankings.
End User:
End user segmentation in Israel tracks the country's bifurcated regulatory structure, with defense applications operating under stringent compartmentalization while civilian monitoring faces lighter oversight.
- Defense:Military intelligence, border surveillance, and targeting support dominate procurement volumes through classified budget channels. The Ministry of Defense controls payload approvals and cross-border data transfer restrictions under national security guidelines.
- Agriculture:Yield prediction, irrigation optimization, and crop health monitoring drive adoption among kibbutzim and commercial farming operations. Weekly survey contracts are displacing seasonal satellite tasking as automated analytics reduce per-image costs.
- Urban Planning:Municipal authorities in central Israel leverage imagery for sprawl tracking, infrastructure development, and zoning enforcement. Tel Aviv metropolitan expansion creates recurring demand for high-resolution update cycles.
- Forestry:Limited forest cover restricts this segment's scale, though fire risk monitoring in Jerusalem corridor woodlands generates niche procurement.
Defense commands absolute revenue share. Agriculture is climbing the fastest as analytics automation opens mid-tier customer access.
Technology:
Technology segmentation reveals where value capture is shifting from hardware manufacturing toward software-enabled analytics pipelines.
- Remote Sensing:Core orbital data acquisition capabilities including sensor calibration, georectification, and atmospheric correction. This mature layer faces margin compression as sensor commoditization accelerates.
- Machine Learning:Automated feature extraction algorithms transform raw pixels into actionable intelligence without human analyst intervention. Tel Aviv-based software houses with defense security clearances are capturing margin pools as agencies unbundle analytics from imagery procurement.
- Data Analytics:Structured processing workflows for trend identification and change detection across temporal image stacks. Agricultural monitoring consortia demand these services for operational decision support.
- Cloud Computing:Distributed storage and processing infrastructure enabling scalable downstream service delivery. Smallsat operators leverage these architectures to bypass legacy prime contractor relationships.
Remote Sensing holds installed capacity. Machine Learning is rotating up the share rankings.
Application:
Application segmentation maps directly onto Israel's dual-speed regulatory environment, separating compartmentalized defense workflows from civilian environmental monitoring channels.
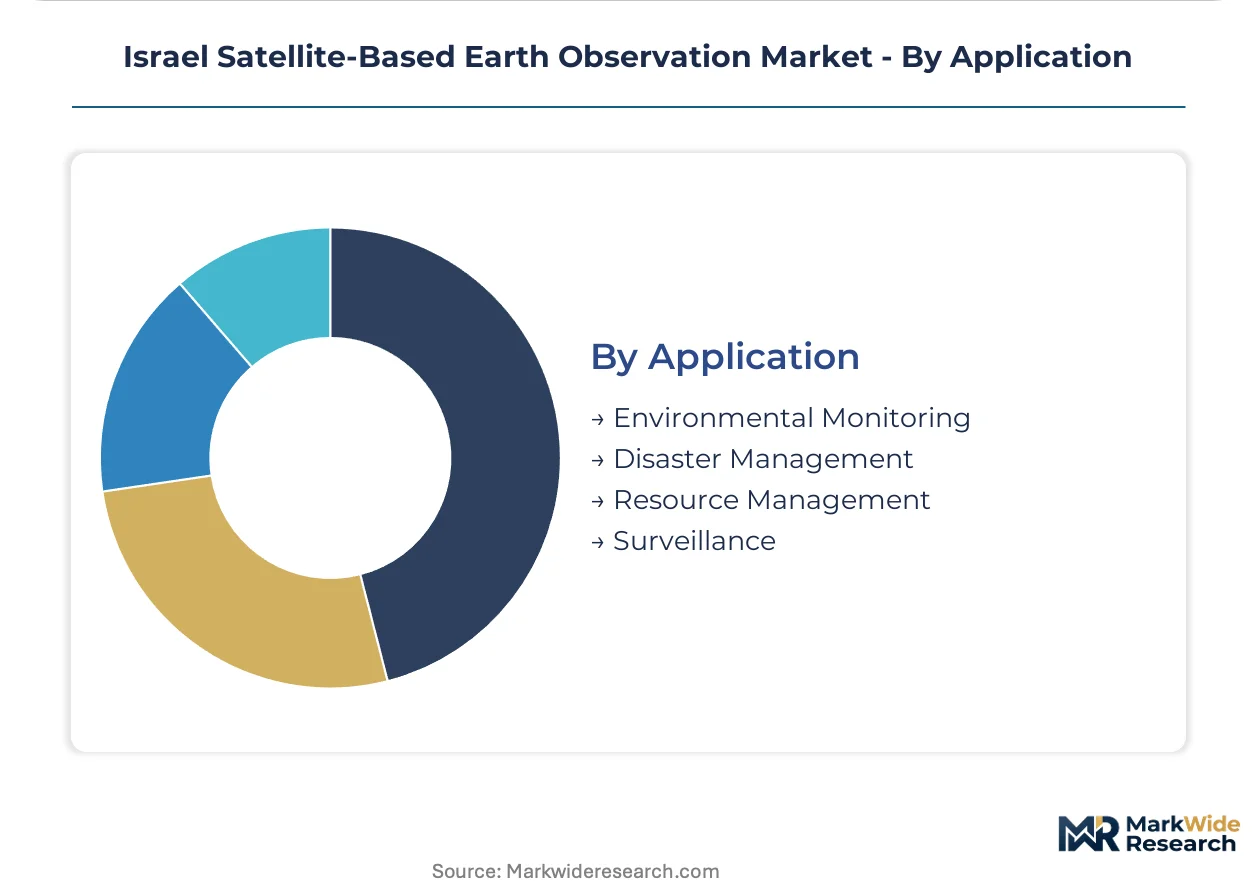
- Surveillance:Persistent monitoring of borders, maritime zones, and regional areas of interest for national security purposes. Cross-border data transfer restrictions under Ministry of Defense guidelines compartmentalize commercial export opportunities.
- Environmental Monitoring:Air quality tracking, coastal erosion measurement, and ecosystem health assessment under Israel Space Agency civilian protocols. These procurement channels operate separately from classified defense workflows.
- Disaster Management:Rapid damage assessment and response coordination for earthquakes, floods, and wildfire events. All-weather SAR capabilities are attracting emergency agency budgets.
- Resource Management:Water allocation monitoring, mineral exploration support, and energy infrastructure planning. The Negev Desert calibration facilities offer expansion capacity for validation before orbital deployment.
Surveillance holds installed capacity. Environmental Monitoring is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Israel Space Agency's civilian monitoring protocols and Ministry of Defense procurement frameworks are concentrating satellite earth observation activity in central Israel's aerospace corridor. Defense budgets in Tel Aviv and Beersheba anchor domestic demand while export licensing restrictions shape commercial reach.
Tel Aviv Metropolitan Area
Defense intelligence agencies and aerospace primes drive procurement volumes for high-resolution surveillance imagery. The Ministry of Defense controls classified payload approvals and cross-border data transfer restrictions under national security guidelines. Tel Aviv's software houses with defense security clearances capture margin pools in automated analytics pipelines.
Beersheba and the Negev Desert
The Negev Desert calibration facilities offer underutilized test range capacity for hyperspectral sensor validation before orbital deployment. Israel Space Agency licensing protocols require end-of-life deorbit plans for new mission approvals. Beersheba's talent density accelerates payload-to-orbit development cycles for qualified integrators.
Haifa and Northern Israel
Maritime monitoring applications off Israel's Mediterranean coastline generate demand for radar altimetry and scatterometry missions. The country's national space regulator coordinates orbital slot allocation for commercial operators. Haifa's industrial base supports maritime surveillance payload integration for coastal security applications.
Jerusalem Corridor
Fire risk monitoring in limited woodland areas generates niche procurement for environmental anomaly detection. Israel Space Agency civilian protocols create procurement channels separate from classified defense workflows. Jerusalem-based research institutions pilot agricultural monitoring consortia for precision farming applications.
Jezreel Valley
Agricultural yield prediction and irrigation optimization drive adoption among kibbutzim and commercial farming operations. Weekly survey contracts displace seasonal satellite tasking as automated analytics reduce per-image costs. The valley's farming cooperatives pilot CubeSat-based crop health surveys for operational decision support.
Israel Satellite-Based Earth Observation Market Competitive Landscape
Listed leaders compete with private specialists across certification-qualified manufacturing tiers, compressing the vendor pool to heritage integrators with government contracts. ISO 9001 and AS9100 requirements collapse supplier qualification timelines to 18-24 months. Three archetypes dominate: state-linked primes with decades of defense heritage, commercial imagery exporters navigating cross-border restrictions, and sensor-to-shooter integrators converging orbital platforms with tactical networks. Competitive moves center on strategic partnerships for orbital slot access and portfolio diversification into downstream analytics.
Within the state-linked prime tier, Israel Aerospace Industries anchors domestic manufacturing capacity through government heritage contracts. ImageSat International occupies a position as a commercial imagery exporter serving selective international markets. Elbit Systems exemplifies the sensor-to-shooter integration archetype, differentiating payload offerings through data chain convergence rather than pure satellite operations. These three entities represent the qualified integrator core that certification barriers protect from new entrant displacement.
| Leading Market Players |
|---|
| Israel Aerospace Industries |
| ImageSat International |
| AMOS Spacecom |
| Gilat Satellite Networks |
| Elbit Systems |
| Rafael Advanced Defense Systems |
| SES S.A. |
| Orbit Communication Systems |
| SpaceIL |
| Others |
Pricing and Supply Chain Analysis
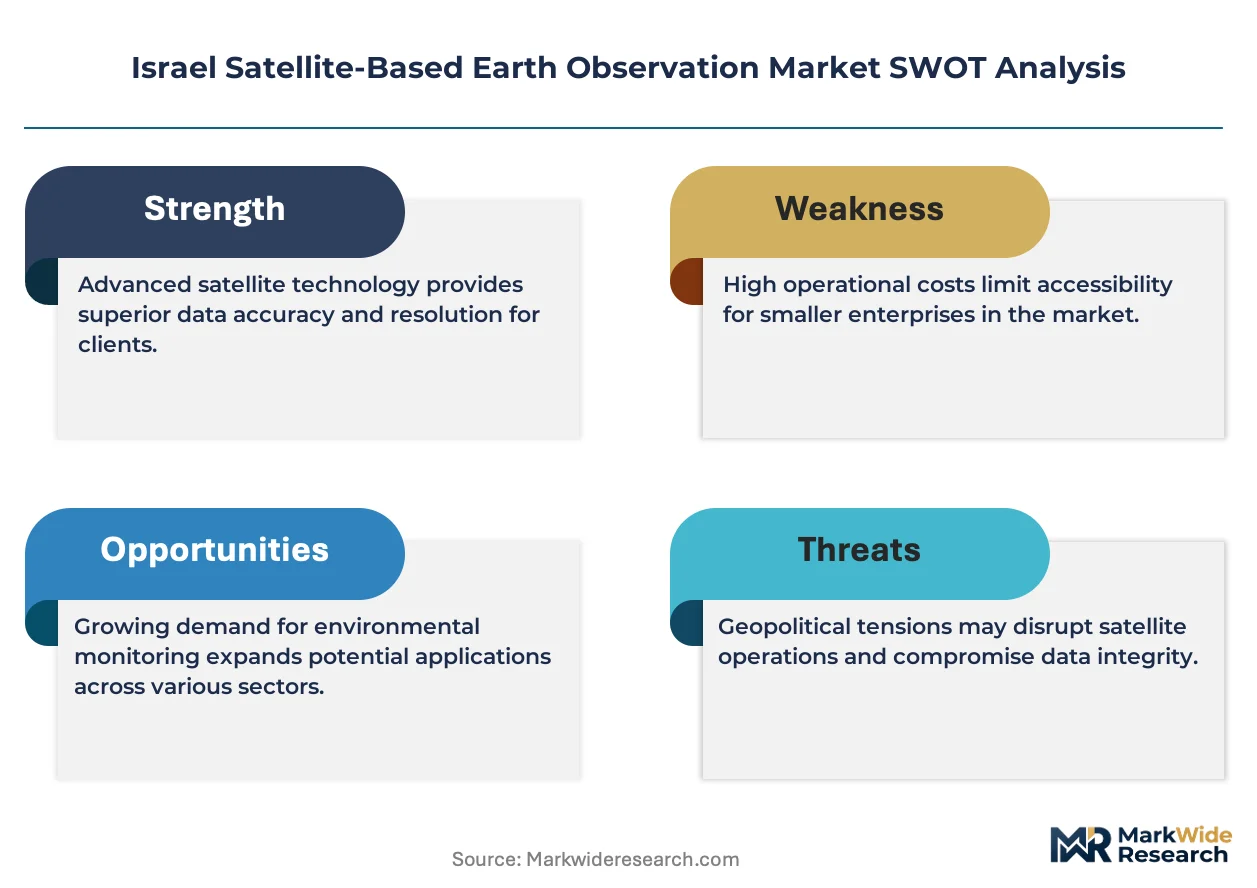
AS9100 certification timelines function as simultaneous gatekeepers of supply qualification and price stratification in Israel's satellite earth observation sector. The 18-24 month supplier qualification periods compress the vendor pool to heritage integrators while enabling these qualified players to command premium pricing tiers unavailable to uncertified competitors.
Pricing Analysis
Certification level creates the primary spread between heritage prime contractors and emerging smallsat operators. Three-tier pricing structure across defense-grade, commercial-grade, and research-grade levels segments buyers by security clearance requirements and mission criticality. Cost compression in the commercial imagery tier is intensifying because CubeSat operators are bypassing traditional prime contractor relationships. Agricultural consortia in the Jezreel Valley exhibit the highest price sensitivity, while Ministry of Defense intelligence programs demonstrate minimal elasticity due to mission-critical requirements and classified procurement channels.
Supply Chain Analysis
Inbound logistics costs for precision optical components and radar subsystems flow through Mediterranean port corridors with periodic congestion at Haifa container terminals. Manufacturing concentration centers on Israel, with secondary sourcing from the United States and select European aerospace clusters for specialized sensor components. The supply chain rests on gallium arsenide substrates, precision optics, and radiation-hardened electronics as critical inputs. Single-source vulnerability in synthetic aperture radar transmitter modules creates procurement risk for qualified integrators. Distribution runs through direct defense contracting vehicles for classified payloads and commercial service agreements for civilian environmental monitoring applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's satellite earth observation market is entering a cyclical upswing as defense procurement rhythms normalize following pandemic-era budget distortions. The Ministry of Defense's sustained commitment to all-weather SAR capabilities provides the cyclical anchor for vendor planning horizons.
For Market Incumbents: Compound certification moats by accelerating AS9100 auditor training partnerships with the Israel Space Agency to extend qualification timelines for prospective entrants. Deepen backward integration into radiation-hardened electronics manufacturing to capture margin pools currently flowing to U.S. suppliers. The emerging threat of university-based CubeSat consortia accessing commercial launch slots demands proactive engagement with agricultural monitoring cooperatives before automated analytics commoditize raw imagery procurement. For New Entrants and Emerging Players: Downstream analytics automation represents the service-layer gap where heritage primes under-serve mid-tier agricultural buyers. The Jezreel Valley farming cooperatives offer the most penetrable entry point given their weekly survey requirements and price sensitivity to incumbent prime contractor rates. A go-to-market angle anchored on crop-specific feature extraction algorithms—delivered through cloud-native platforms—circumvents the capital barriers of orbital hardware ownership. For Investors and Strategic Acquirers: Loosening of Ministry of Defense export control thresholds for commercial SAR products reshapes the acquisition landscape by expanding addressable market boundaries for qualified operators. Long-term viability over a multi-year horizon hinges on portfolio positioning toward sensor-to-shooter data chain convergence rather than pure-play satellite manufacturing. The acquisition target archetype centers on Tel Aviv-based software houses with defense security clearances and automated analytics pipelines. The signal to watch is Israel Space Agency licensing queue depth for smallsat constellation approvals, as acceleration would indicate regulatory accommodation of new entrant form factors.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Acceleration | Shortens supplier qualification timelines to 12-18 months for heritage integrators defending market position. |
| Sensor-to-Shooter Data Chain Integration | Elbit Systems and Rafael capture defense contracts beyond pure imagery provision through tactical edge convergence. |
| CubeSat Constellation Deployment | University and mid-tier operators bypass legacy prime relationships for agricultural monitoring applications. |
| Hyperspectral Sensor Validation Partnership | Negev Desert test ranges enable pre-orbital calibration for precision farming consortia in the Jezreel Valley. |
| Machine Learning Analytics Platform | Tel Aviv software houses with security clearances capture margin pools as agencies unbundle analytics from imagery. |
Research Methodology
A spread of perspectives from satellite program managers at Israel Aerospace Industries, procurement officers within the Ministry of Defense, agricultural cooperative technology leads in the Jezreel Valley, and regulatory affairs specialists at the Israel Space Agency converged on the working assumptions. These primary interviews were validated against secondary sources including Israel Space Agency licensing disclosure records, Ministry of Defense budget appropriation documents, and customs data on aerospace component imports. Bottom-up triangulation across individual program budgets and top-down reconciliation against national space expenditure aggregates anchored the market sizing.
Segmentation dimensions modeled include product type, end user, technology, and application across the analysis window. The analytical framework disaggregated defense procurement rhythms from civilian environmental monitoring channels to capture divergent growth trajectories. CAGRs were derived through regression analysis of historical budget cycles and projected mission deployment schedules. Industry-specific forecast inputs incorporated orbital slot allocation queues and smallsat deorbit compliance timelines under tightening Israel Space Agency protocols.
Forecasts assume regulatory continuity in Israel Space Agency civilian monitoring protocols and Ministry of Defense cross-border data transfer restrictions; material policy shifts would require re-modeling. Specific risk factors include acceleration of export control loosening for commercial SAR products and potential orbital debris mitigation requirement tightening for short-lifespan constellations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Link Emulator Market
Satellite
North America Remote Sensing Satellites Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Commercial LEO Satellite Market
Satellite
Satellite Broadband Market
Satellite
Middle East Satellite Communications Market
Satellite
ASEAN Satellite Communications Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
LEO Satellite Constellation Market
Satellite
Satellite Internet Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Satellite Payload Market
Satellite
Military Satellite Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Satellite Connectivity Market