
 US Satellite-Based Earth Observation Market | 2026-2036
US Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
US Satellite-Based Earth Observation Market Insights
California's aerospace corridor is fragmenting as new launch providers and satellite operators challenge incumbent geographic concentration. Maxar Technologies anchors geospatial intelligence contracts through its high-resolution optical constellation and direct government relationships. Planet Labs Inc. differentiates via daily global coverage from its Dove and SkySat fleets, leveraging rapid revisit rates for commercial agriculture and defense monitoring. L3Harris Technologies, Inc. competes across the full sensing stack, from payload design to ground segment analytics, sustaining integrated program execution for classified missions.
US satellite-based earth observation encompasses orbital platforms carrying electro-optical, synthetic aperture radar, hyperspectral, or lidar sensors that collect geospatial data for downstream analytics, with spatial resolutions ranging from sub-meter panchromatic to 30-meter multispectral depending on mission design and orbital altitude. These systems serve defense reconnaissance, environmental compliance verification, infrastructure monitoring, and climate science through standardized data products delivered via commercial ground stations or direct downlink to user terminals. Optical satellites dominate current revenue given mature supply chains and established defense procurement pathways, while radar satellites represent the fastest-expanding product type due to all-weather, day-night imaging capabilities that penetrate cloud cover over maritime and tropical zones. Cloud-based deployment architectures are displacing on-premises ground infrastructure as hyperscale providers offer elastic compute for petabyte-scale imagery archives, concentrating margin pools in analytics software rather than raw data distribution.
FAA licensing governs commercial launch operations under 14 CFR Part 450, while NOAA's Commercial Remote Sensing Regulatory Affairs office controls satellite imaging resolution and shutter control for national security purposes, with NGA certification requirements filtering which vendors qualify for federal procurement programs. FCC spectrum allocations for telemetry, tracking, and command links constrain constellation density and create competitive moats for operators holding priority Ka-band and X-band authorizations. Stakeholders must monitor evolving NOAA license processing timelines and FCC orbital debris mitigation rules as these regulatory levers determine market entry speed and operational lifecycle economics for new constellation ventures.
Market Dynamics
Federal defense procurement reforms are compressing commercial satellite imagery into classified mission workflows faster than ground infrastructure can adapt, forcing operators to rearchitect data pipelines for security-cleared environments.
Growth Catalysts
- NOAA Commercial Data Licensing:Streamlined resolution approvals for private operators are accelerating federal agency adoption of commercial constellations for weather monitoring and climate science applications.
- Defense Mission Planning:Intelligence community demand for unclassified geospatial intelligence is pulling commercial radar and hyperspectral data into operational planning cycles.
- Synthetic Aperture Radar:All-weather imaging capabilities are penetrating cloud-covered maritime zones and tropical regions where optical satellites face persistent coverage gaps.
Market Restraints
- Launch Capacity Bottlenecks:Vandenberg Space Force Base scheduling constraints and limited polar orbit launch slots are throttling constellation deployment timelines for new entrants.
- Spectrum Authorization Moats:FCC priority Ka-band and X-band allocations for telemetry, tracking, and command links are concentrating operational control among incumbent license holders.
- Debris Mitigation Compliance:Evolving FCC orbital debris rules are extending satellite design cycles and raising end-of-life disposal costs for constellation operators.
Strategic Opportunities
- California Aerospace Corridor Expansion:Secondary manufacturing and integration facilities in Texas and Florida are diversifying supply chain geography beyond Vandenberg-dependent clusters.
- Cloud-Native Analytics:Hyperscale provider partnerships for petabyte-scale imagery processing are shifting margin capture from raw data distribution to software-layer subscriptions.
- Hyperspectral Agriculture:Crop health monitoring and yield prediction applications are opening commercial revenue streams outside defense-dependent customer bases.
Industry Challenges
- Security Clearance Pipeline:Cleared engineering talent shortages are delaying classified ground segment deployments and restricting vendor participation in restricted programs.
- Multi-Sensor Integration:Fusing electro-optical, radar, and lidar data streams into unified analytics products requires specialized expertise that outpaces current workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Satellite-Based Earth Observation Market |
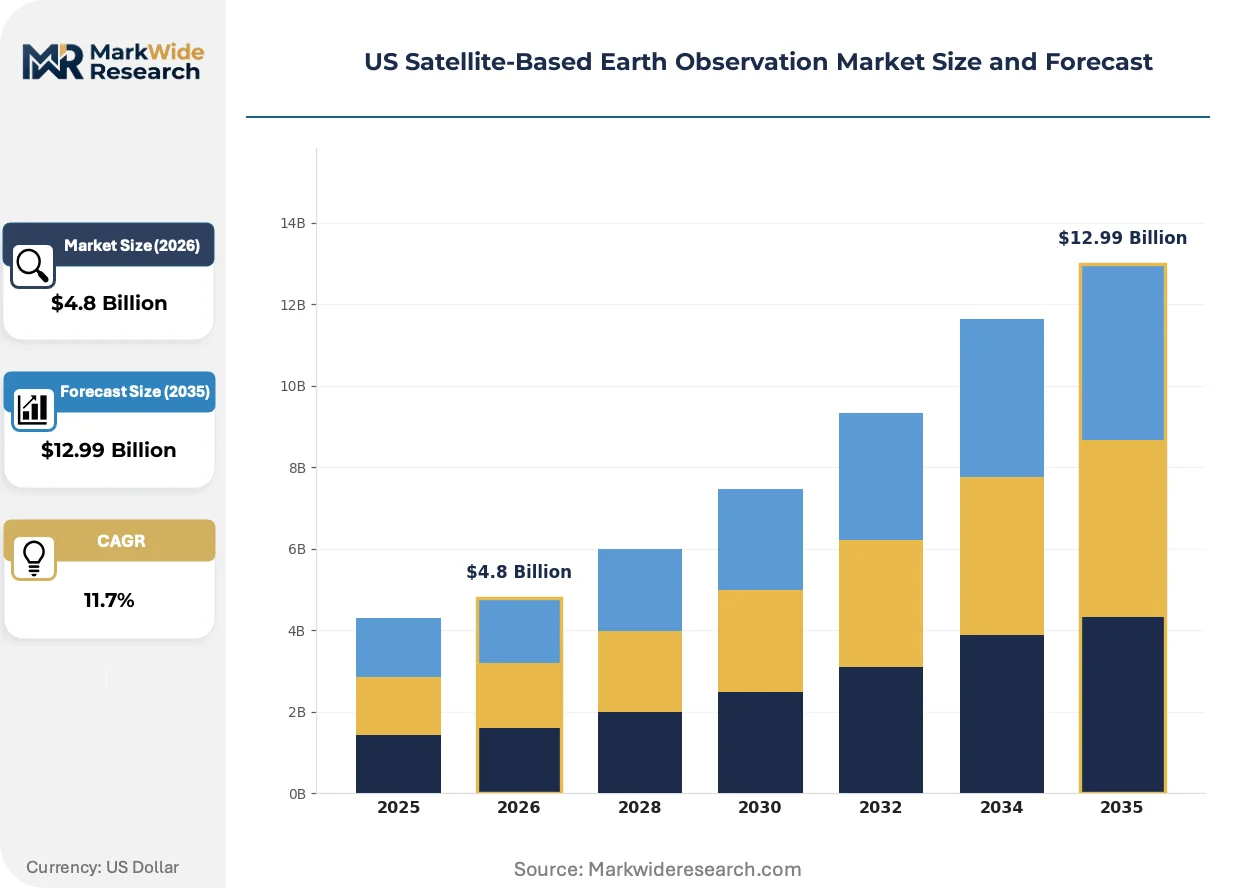
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Hyperspectral Satellites, Lidar Satellites End User: Agriculture, Marine, Forestry, Urban Planning Application: Disaster Management, Environmental Monitoring, Climate Research, Resource Management Deployment: On-Premises, Cloud-Based, Hybrid, Dedicated |
| Companies Covered | Airbus Defense and Space, Planet Labs Inc., Maxar Technologies, L3Harris Technologies, Inc., Raytheon Technologies Corporation, Thales Group, GeoOptics Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Satellite-Based Earth Observation Market Trends and Innovations
Three forces are restructuring how satellite operators capture value: cloud infrastructure is commoditizing raw imagery storage, federal procurement is forcing security architecture redesigns, and sensor diversification is fragmenting technical specialization requirements.
Software-defined radio payloads are collapsing the traditional hardware-software boundary in satellite design. Operators are adopting reconfigurable signal processors that shift functionality via firmware updates rather than physical replacement. Defense agencies are accelerating procurement of these platforms to extend operational lifespans without launch replacement costs.
FAA's 14 CFR Part 450 streamlined launch licensing is compressing approval timelines for new orbital vehicles. The regulation's performance-based safety framework replaces prescriptive requirements with operator-certified risk profiles. California-based launch providers are exploiting this flexibility to increase flight cadence from Vandenberg while reducing per-mission compliance overhead.
Subscription-based analytics contracts are displacing per-image procurement across agricultural and infrastructure monitoring segments. Buyers in the Midwest grain belt are consolidating vendor relationships around annual data service agreements rather than transactional imagery purchases. This shift is compressing customer acquisition costs while raising retention requirements for platform stickiness.
US Satellite-Based Earth Observation Market Segmentation
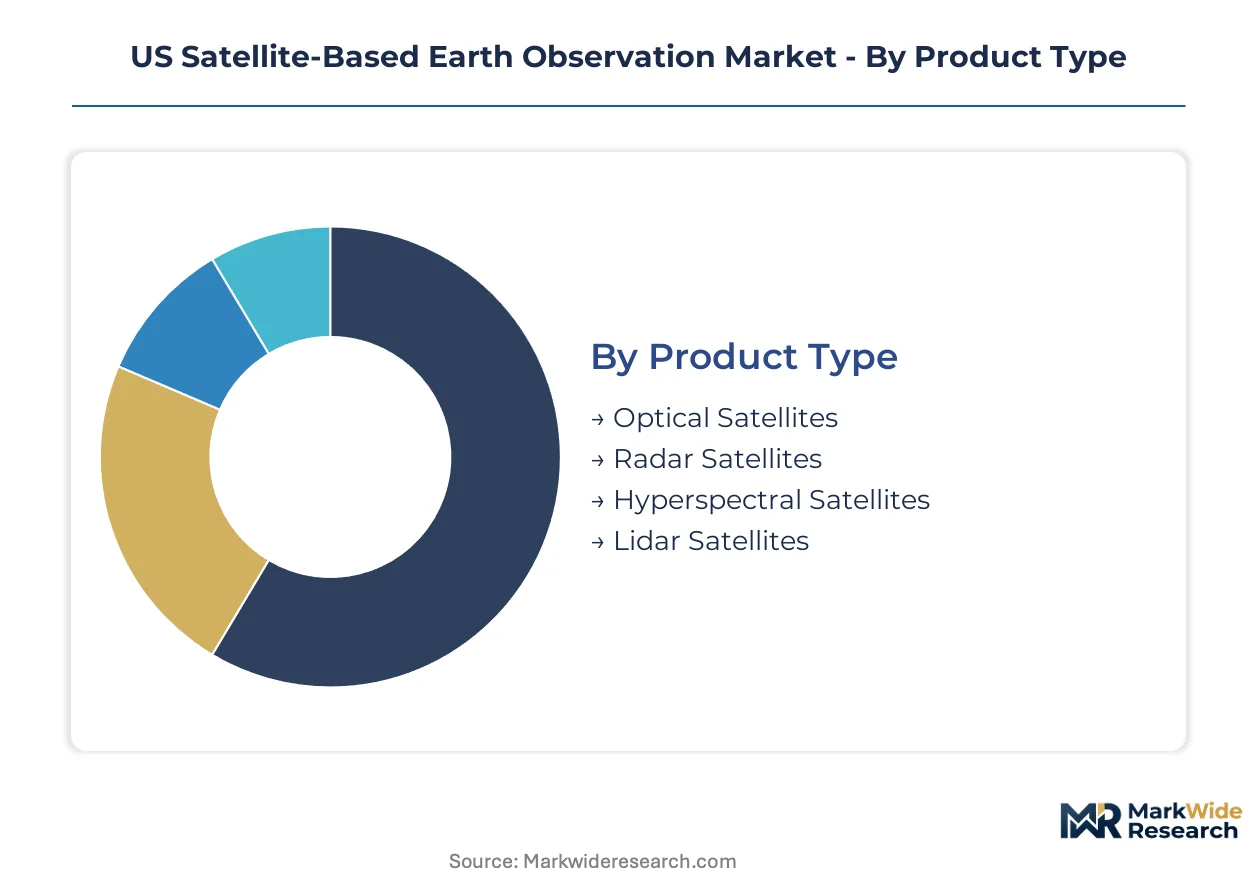
Segmentation reveals how sensor modality, customer workflow, and infrastructure architecture shape procurement patterns across defense, commercial, and scientific user bases. Each dimension carries distinct margin structures and regulatory exposure that determine vendor positioning strategy.
Product Type:
After-sales service intensity varies sharply across sensor modalities, with radar platforms demanding continuous calibration support and optical systems requiring less intensive ground segment maintenance.
- Optical Satellites:Electro-optical sensors capture panchromatic and multispectral imagery at resolutions from sub-meter to 30-meter depending on orbital altitude and aperture design. Defense reconnaissance contracts in California's aerospace corridor concentrate procurement here, though cloud cover limitations over maritime zones constrain coverage reliability. Optical satellites hold the largest share; momentum sits with radar platforms.
- Radar Satellites:Synthetic aperture radar transmits microwave signals and processes return echoes to construct all-weather, day-night imagery independent of atmospheric conditions. Maritime surveillance and tropical zone monitoring drive federal demand, with NOAA licensing reforms accelerating operational deployment for hurricane tracking and illegal fishing detection.
- Hyperspectral Satellites:Instruments sample narrow contiguous spectral bands across visible to shortwave infrared wavelengths, enabling material identification and vegetation health assessment.
- Lidar Satellites:Laser altimetry systems measure precise surface elevations through time-of-flight calculations, supporting topographic mapping and infrastructure deformation monitoring.
Optical platforms dominate current revenue given mature supply chains; radar satellites are climbing the fastest as all-weather capabilities penetrate previously inaccessible coverage zones.
End User:
Customer archetypes span precision-dependent commercial agriculture to mission-critical defense workflows, each imposing distinct data latency and security requirements.
- Agriculture:Commodity crop producers and agritech platforms leverage multispectral and hyperspectral data for yield prediction, irrigation optimization, and early pest detection. Midwest grain belt operations are consolidating around subscription-based analytics contracts rather than transactional imagery purchases, compressing customer acquisition costs while raising retention requirements.
- Marine:Fisheries management agencies, offshore energy operators, and naval commands require synthetic aperture radar for vessel detection, oil spill monitoring, and exclusive economic zone enforcement. Persistent cloud cover over oceanic regions makes radar the dominant sensor choice, with FCC spectrum allocations for telemetry links creating competitive moats for incumbent license holders.
- Forestry:Timber companies and carbon credit verification bodies utilize lidar and radar for biomass estimation and deforestation monitoring.
- Urban Planning:Municipal governments and real estate developers deploy high-resolution optical and elevation data for zoning compliance, infrastructure assessment, and flood risk modeling.
Agriculture commands the broadest commercial footprint; marine applications are expanding most quickly as maritime domain awareness priorities intensify.
Application:
Use case maturity determines pricing architecture, with established environmental compliance workflows supporting premium data products while emerging climate science applications compete on volume.
- Disaster Management:Rapid response protocols for wildfire, flood, and earthquake events demand sub-hourly revisit rates and automated change detection pipelines. Federal emergency management agencies are integrating commercial radar constellations into classified workflows faster than ground infrastructure can adapt, forcing operators to rearchitect data pipelines for security-cleared environments.
- Environmental Monitoring:Regulatory compliance verification for mining, construction, and land use change relies on standardized historical imagery archives. EPA enforcement divisions and state environmental agencies procure commercial data to document permit violations and restoration progress, with cloud-based deployment architectures displacing on-premises infrastructure.
- Climate Research:Long-term trend analysis requires radiometrically calibrated data records spanning decades.
- Resource Management:Water allocation, mineral exploration, and energy infrastructure planning integrate multi-sensor fusion for subsurface and surface feature detection.
Environmental monitoring anchors commercial revenue; disaster management is gaining share fastest as federal procurement reforms accelerate unclassified geospatial intelligence adoption.
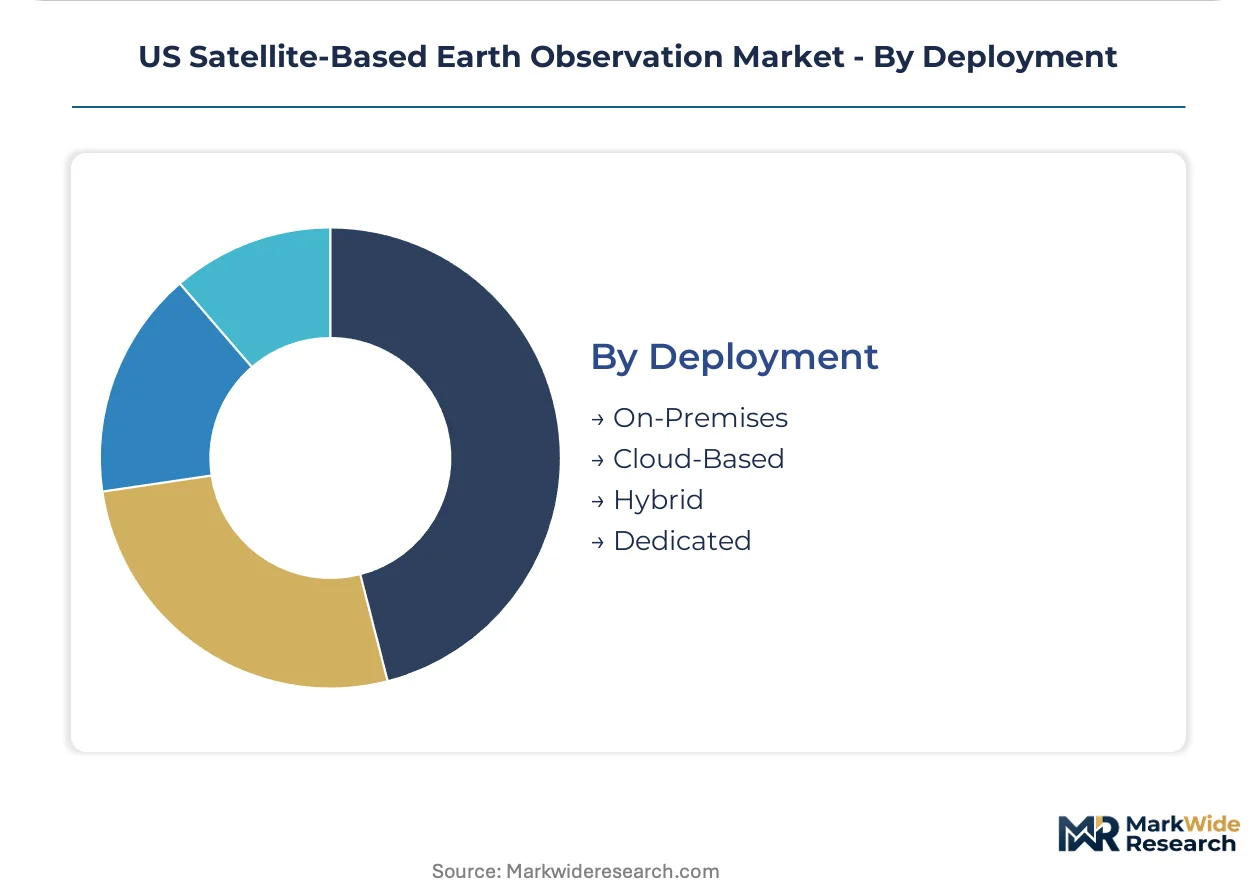
Deployment:
Infrastructure architecture choices reflect data sovereignty requirements, processing latency constraints, and hyperscale provider partnership strategies.
- Cloud-Based:Hyperscale provider partnerships for petabyte-scale imagery processing enable elastic compute for automated feature extraction and change detection. Defense agencies are accelerating procurement of these architectures despite security clearance pipeline constraints, with margin pools concentrating in analytics software rather than raw data distribution.
- On-Premises:Classified ground segment installations at secure facilities support intelligence community workflows with air-gapped processing environments. Cleared engineering talent shortages are delaying these deployments and restricting vendor participation in restricted programs.
- Hybrid:Architectures partition sensitive processing on-premises while leveraging cloud elasticity for non-classified analytics workloads.
- Dedicated:Single-tenant infrastructure deployments serve large enterprise and government customers with stringent data residency requirements.
Cloud-based deployment holds the largest share; hybrid architectures are expanding most quickly as security-cleared cloud environments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA licensing under 14 CFR Part 450 anchors US commercial launch operations, with California's aerospace corridor serving as the primary satellite manufacturing and deployment hub. Vandenberg Space Force Base polar orbit launch slots constrain national constellation deployment timelines.
California
Defense reconnaissance contracts and commercial imagery procurement drive demand concentration along the central coast. NOAA's Commercial Remote Sensing Regulatory Affairs office processes resolution approvals for operators headquartered in this corridor. Maxar Technologies and Planet Labs anchor geospatial intelligence production near Vandenberg launch facilities, though secondary manufacturing is diversifying toward Texas.
Texas
Launch provider migration and satellite integration facility expansion are reducing California dependency for new constellation ventures. FAA streamlined licensing enables increased flight cadence from Gulf Coast launch sites. Houston and Austin aerospace clusters are capturing engineering talent and ground segment operations previously concentrated on the West Coast.
Colorado
Intelligence community ground station infrastructure and geospatial analytics software development concentrate demand in the Denver metro area. NGA certification requirements filter vendor participation in classified programs through facilities in this region. The state's aerospace workforce supports security-cleared data pipeline architectures for defense mission planning.
Florida
Equatorial launch access and Space Coast infrastructure support commercial radar constellation deployment for maritime surveillance applications. FCC spectrum allocations for telemetry links create operational moats for incumbent license holders with facilities near Cape Canaveral. The state's launch cadence growth is compressing approval timelines for new orbital vehicles.
Virginia
Mid-Atlantic ground segment operations and federal procurement headquarters proximity attract disaster management and environmental monitoring contract awards. NOAA's weather data licensing reforms accelerate private sector participation through offices in the DC metro corridor. Wallops Flight Facility supports small satellite launch services for rapid constellation replenishment.
US Satellite-Based Earth Observation Market Competitive Landscape
Integrated defense contractors and commercial imagery specialists split the market along classified versus unclassified workflow boundaries. The vendor base concentrates around established government procurement relationships rather than pure technology differentiation. Three archetypes dominate: legacy aerospace primes with security-cleared infrastructure, commercial constellation operators with rapid revisit capabilities, and sensing stack integrators spanning payload through analytics. Competitive moves center on cloud-native ground segment partnerships and hybrid security architecture certifications.
Among defense-anchored primes, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions within classified program execution, while Planet Labs Inc. exemplifies the commercial imagery archetype with daily global coverage capabilities. These entities represent contrasting approaches to federal procurement reform—traditional cleared infrastructure versus rapid commercial data integration.
| Leading Market Players |
|---|
| Airbus Defense and Space |
| Planet Labs Inc. |
| Maxar Technologies |
| L3Harris Technologies, Inc. |
| Raytheon Technologies Corporation |
| Thales Group |
| GeoOptics Inc. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
FCC spectrum authorization bottlenecks for Ka-band and X-band telemetry links determine both tiered pricing spreads across optical, radar, and hyperspectral data products and the geographic clustering of satellite manufacturing around incumbent license holders in California and Texas.
Pricing Analysis
California-based operators command premium subscription rates for sub-meter optical imagery, while Texas and Florida providers compete on standard-tier radar data pricing. Three-tier pricing structure across premium, standard, and economy levels separates defense-cleared analytics from commercial agriculture subscriptions and raw data feeds. Cost compression in standard-tier optical products is intensifying because cloud-native processing commoditizes storage infrastructure. Federal defense agencies show least price sensitivity given mission-critical requirements; Midwest grain belt agricultural buyers exhibit highest sensitivity, consolidating around annual service agreements.
Supply Chain Analysis
Extended payment terms from prime contractors to component suppliers stretch cash conversion cycles for sensor payload manufacturers. Supply concentrates in the United States for satellite bus integration, draws from Germany and Japan for precision optical components, and sources from South Korea for solid-state power amplifiers. Single-source vulnerability persists for synthetic aperture radar chipsets and radiation-hardened processors. Distribution runs through direct federal procurement channels, commercial ground station networks, and hyperscale cloud provider marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement reforms fragmenting classified and unclassified workflow boundaries create specialized vendor niches across security-cleared ground segment operators, rapid-revisit commercial constellations, and multi-sensor fusion analytics platforms.
For Market Incumbents: Build spectrum license moats by securing FCC priority allocations for next-generation telemetry bands before regulatory windows narrow. Incumbents should deepen backward integration into radiation-hardened component manufacturing to offset single-source supplier risk. Cloud-native ground segment partnerships represent the critical lever for retaining federal contracts as security-cleared environments mature. For New Entrants and Emerging Players: Build out hyperspectral agriculture monitoring capabilities across the Midwest grain belt, where subscription consolidation creates vendor-switching opportunities. Maritime domain awareness applications for illegal fishing detection and exclusive economic zone enforcement offer the most penetrable defense-adjacent segment. A direct-to-analyst go-to-market angle bypasses incumbent procurement relationships by targeting operational intelligence units with unclassified rapid-delivery products. For Investors and Strategic Acquirers: The market sits at a defense-integration phase that favors commercial constellation operators with security architecture certifications. Long-term viability across the next decade hinges on hybrid cloud-on-premises deployment capabilities rather than pure technology differentiation. Acquisition targets should demonstrate existing NGA certification pathways or NOAA commercial data licensing relationships. The signal to watch is FCC debris mitigation rule finalization, which would accelerate consolidation among capital-constrained constellation ventures.| Strategic Initiative | Industry Significance |
|---|---|
| Security-Cleared Cloud Partnership | Enables federal agency adoption of commercial radar constellations through FedRAMP-authorized hyperscale environments. |
| Multi-Sensor Fusion Platform Development | Integrates electro-optical, SAR, and lidar streams into unified analytics products for defense mission planning workflows. |
| Spectrum License Portfolio Expansion | Secures FCC priority Ka-band and X-band allocations that constrain competitor constellation density and create operational moats. |
| Midwest Agricultural Subscription Consolidation | Captures annual data service agreements from grain belt operators shifting from transactional imagery purchases. |
| Software-Defined Radio Payload Deployment | Extends operational lifespans via firmware-updatable signal processors, reducing launch replacement costs for defense agencies. |
Research Methodology
A standing panel of satellite program executives, defense procurement officers, NOAA licensing specialists, and cloud infrastructure architects provided ongoing calibration throughout the study period. Primary interviews with constellation operators, ground segment engineers, and federal agency geospatial analysts combined with secondary validation against FCC spectrum allocation databases, FAA 14 CFR Part 450 licensing records, and NOAA Commercial Remote Sensing Regulatory Affairs filings. Bottom-up unit economics for constellation deployment and top-down federal budget appropriation analysis triangulated market sizing.
Scenario-bracketing around launch capacity constraints, spectrum authorization timelines, and security clearance pipeline bottlenecks bounded high and low growth paths across the projection horizon. Segmentation modeling covered sensor modality, end-user workflow, deployment architecture, and application maturity. CAGRs derived from deployed constellation capacity projections, federal procurement trend extrapolation, and commercial agriculture subscription penetration curves. Hyperscaler partnership announcements and NGA certification award velocity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized launch providers or hyperscale cloud entrants would shift outcomes beyond modeled ranges. Macroeconomic pressure on federal discretionary spending, regulatory acceleration of debris mitigation compliance, or breakthroughs in low-cost synthetic aperture radar manufacturing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Europe Small Satellite Market
Satellite
High-Throughput Satellite Market
Satellite
Earth Observation Satellite Market
Satellite
Satellite Compass Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Satellite Operation Service Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Global Small Satellite Service Market
Satellite
France Satellite Connectivity Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Israel Satellite Imagery Services Market
Satellite
North America Small Satellite Market
Satellite
Global Enterprise VSAT System Market
Satellite
China Satellite Communication Market
Satellite
Europe Satellite Launch Vehicle Market