
 France Satellite Connectivity Market | 2026-2036
France Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
France Satellite Connectivity Market Insights
Platform licensing revenue is rewriting profitability expectations across the France satellite connectivity value chain. Thales Alenia Space leverages its dual-use heritage to anchor government and export contracts for secure payload systems. Eutelsat competes through geostationary capacity dominance over Europe, the Middle East, and Africa. Airbus sustains vertical integration from satellite manufacturing through ground segment operations, controlling critical supply nodes.
France satellite connectivity encompasses orbital and ground-based systems transmitting voice, video, and data via radio frequency links operating across L-band through Ka-band spectra, with orbital altitudes spanning 600 km in low Earth orbit to 35,786 km in geostationary arc. These networks serve defense coordination, maritime safety, broadcast distribution, and enterprise backhaul where terrestrial infrastructure proves uneconomical or physically impossible. Low Earth Orbit deployments are attracting the fastest capital allocation as latency-sensitive enterprise and defense applications multiply. Geostationary capacity retains margin density in video broadcasting and rural internet trunking where orbital persistence reduces ground terminal complexity. Hybrid Systems architectures are emerging as the structural compromise, blending LEO responsiveness with GEO reliability for government customers demanding operational flexibility.
ANSM and CNIL frameworks govern data sovereignty and cybersecurity certification for satellite operators handling French citizen information, while EU Space Programme regulations under EUSPA mandate Galileo signal compatibility and interference standards. These compliance layers elevate barriers for non-European service providers and incentivize domestic ground segment investment. Stakeholders must monitor spectrum allocation proceedings at ARCEP and ESA funding commitments for sovereign constellation infrastructure as decisive variables shaping competitive access.
Market Dynamics
Sovereign constellation mandates under the French Ministry of Armed Forces are forcing a bifurcation between defense-secure and commercial satellite architectures, reshaping capital allocation across orbital altitudes and spectrum bands.
Growth Catalysts
- Defense procurement directives:The Ministry of Armed Forces accelerates sovereign low Earth orbit deployments for beyond-line-of-sight military communications, mandating domestic payload integration.
- Maritime safety corridors:English Channel and Mediterranean operators require resilient connectivity for vessel tracking and emergency response, driving dedicated bandwidth leases.
- Galileo signal compatibility:EUSPA mandates under the EU Space Programme force ground segment upgrades, creating captive demand for European-certified terminal manufacturers.
Market Restraints
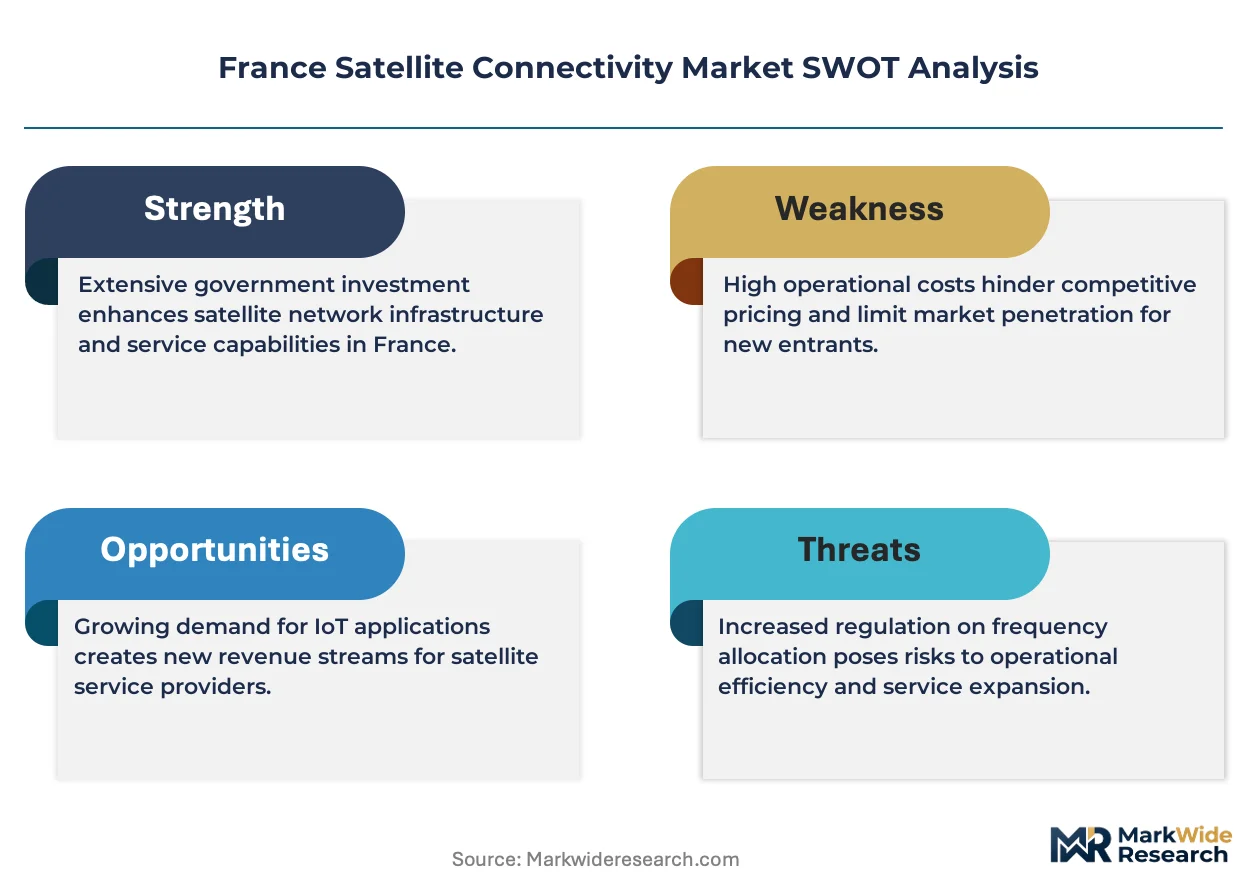
- Spectrum scarcity at ARCEP:Ka-band allocation proceedings create multi-year licensing delays for new market entrants, privileging incumbents with grandfathered rights.
- Launch capacity concentration:French operators depend on Arianespace and limited alternative European launch providers, exposing deployment schedules to queue bottlenecks.
- Optical fiber substitution:Submarine cable expansions along Atlantic and Mediterranean routes undercut price positioning for geostationary backhaul in coastal zones.
Strategic Opportunities
- Overseas territory connectivity:French Polynesia, New Caledonia, and Guiana present underpenetrated demand for low Earth orbit broadband where terrestrial infrastructure remains economically unviable.
- Hybrid constellation architectures:Convergence of geostationary persistence with low Earth orbit responsiveness enables government customers to consolidate vendor relationships.
- CNIL cybersecurity certification:Accelerated compliance pathways for satellite operators handling citizen data create first-mover advantages in public sector contracting.
Industry Challenges
- RF engineer scarcity:Specialized talent for phased array antenna design and inter-satellite link optimization commands premium compensation, constraining ground segment scaling.
- Legacy integration friction:Defense customers require backward compatibility with existing geostationary terminals, complicating low Earth orbit system rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Satellite Connectivity Market |
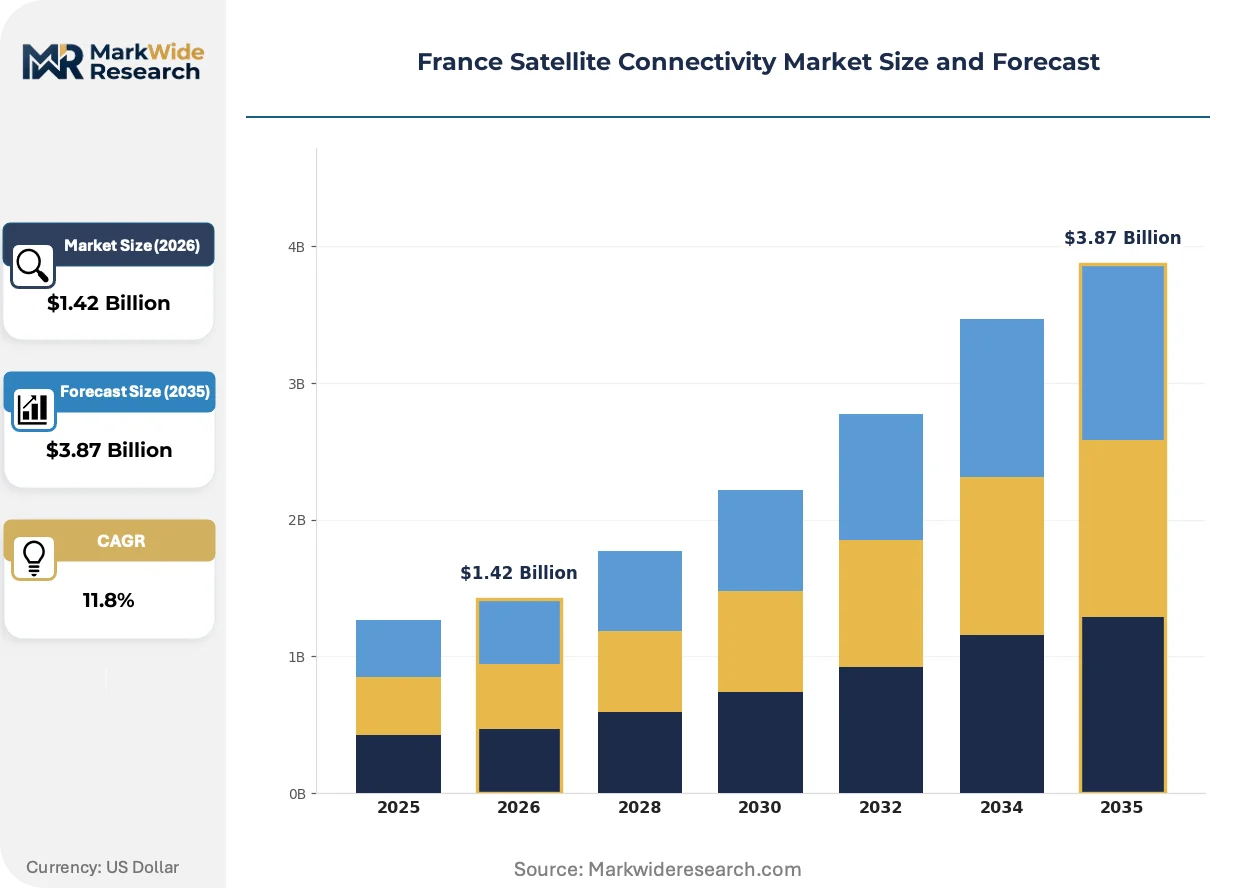
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Internet Connectivity, Video Broadcasting, Telephony, Data Communication End User: Aerospace, Maritime, Government, Telecommunications Technology: Low Earth Orbit, Geostationary, Hybrid Systems, Software Defined Application: Emergency Services, Rural Internet, Broadcasting, Enterprise Solutions |
| Companies Covered | Airbus, Thales Alenia Space, Eutelsat, SES, Intelsat, SpaceX, Viasat, Telesat, L3Harris Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Satellite Connectivity Market Trends and Innovations
Electronically steered flat-panel antennas are collapsing the traditional trade-off between terminal mobility and link performance, enabling new mobility use cases across maritime and aeronautical segments.
Software-defined radio payloads are rendering obsolete rigid frequency-planning architectures that locked operators into fixed spectrum assignments. Maritime integrators along Brittany and Normandy coastlines are adopting these reconfigurable systems fastest. The technology is compressing time-to-market for new service launches from years to months.
France's ANSM and CNIL frameworks now mandate end-to-end encryption certification for satellite operators processing health and personal data. This elevates compliance costs for non-European service providers while creating procurement preference for domestic ground segment vendors. Defense and emergency response agencies are the segments most affected, rewriting vendor qualification criteria.
Service unbundling is fragmenting traditional long-term capacity leases. Enterprise customers in Provence-Alpes-Côte d'Azur and Occitania now procure satellite connectivity through managed service providers rather than direct operator relationships. This channel shift is most visible in agricultural IoT and remote energy monitoring verticals, where buyers prioritize operational expenditure models over capital-intensive terminal ownership.
France Satellite Connectivity Market Segmentation
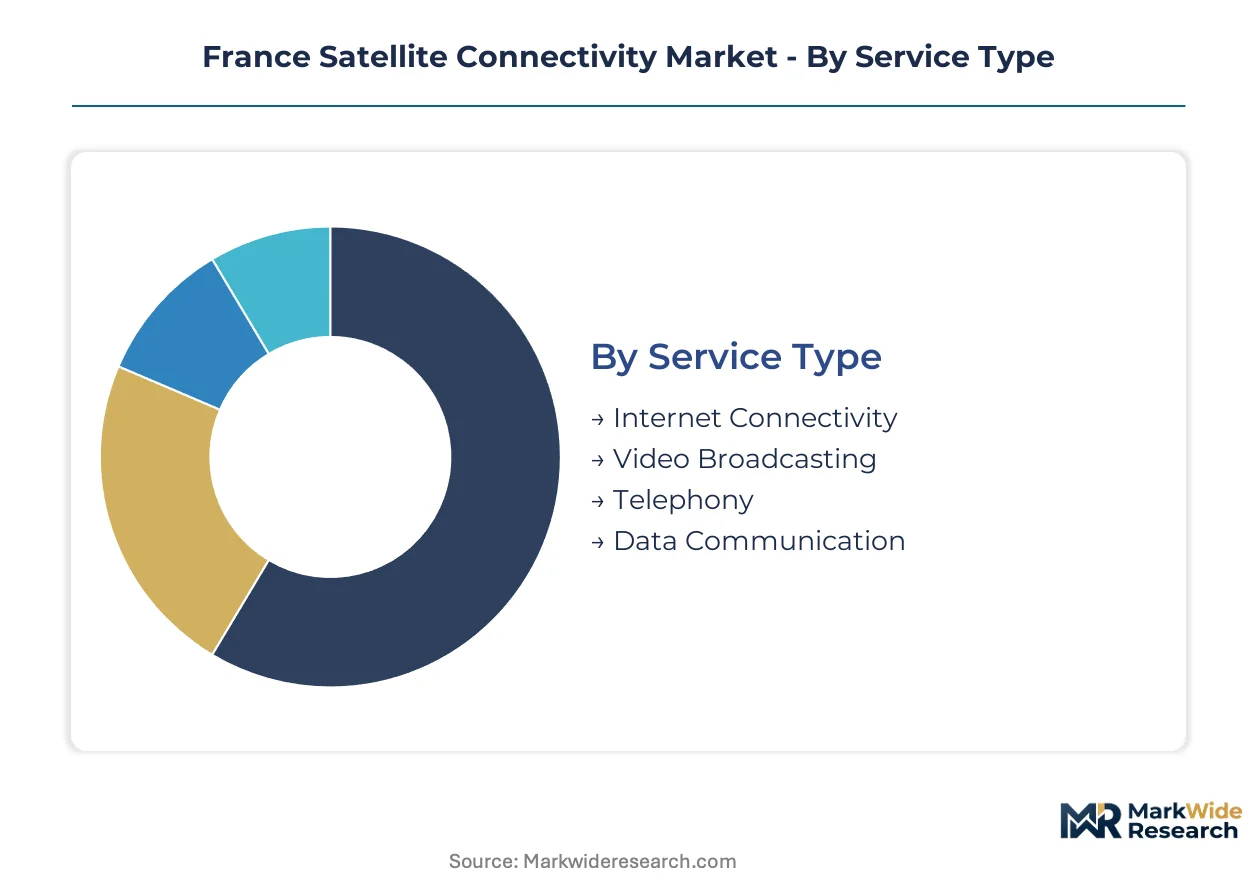
France satellite connectivity segmentation reveals how orbital altitude, service architecture, and end-user mission profiles dictate procurement patterns. Regulatory frameworks from ANSM and CNIL further stratify vendor qualification across each dimension, creating distinct competitive arenas.
Service Type:
Use-case spectrum spans consumer broadband to mission-critical defense communications, with each service tier commanding different latency tolerances and encryption standards.
- Internet Connectivity:Low Earth Orbit constellations deliver sub-50ms latency for enterprise cloud access and maritime vessel operations. Demand concentrates in Brittany fishing fleets and Provence-Alpes-Côte d'Azur yachting corridors where fiber backhaul remains uneconomical.
- Video Broadcasting:Geostationary capacity dominates sports and news distribution across metropolitan France and overseas territories. Established volume favors this segment; emerging adoption favors Internet Connectivity as flat-panel terminals reduce mobility penalties.
- Telephony:Narrowband voice services persist in emergency response and remote industrial sites. Rural fire brigades in Auvergne-Rhône-Alpes maintain dedicated satellite links for disaster coordination.
- Data Communication:Machine-to-machine telemetry for energy infrastructure and agricultural IoT drives recurring revenue models. Occitania solar farms and Grand Est wind parks deploy these links for SCADA backhaul.
Service unbundling is fragmenting traditional long-term leases as managed service providers capture enterprise procurement relationships.
End User:
Customer-type concentration determines pricing power, with defense and aerospace procurement mandating domestic payload integration while commercial maritime buyers prioritize terminal mobility.
- Aerospace:In-flight connectivity for narrow-body fleets operating from Charles de Gaulle and Orly drives Ka-band terminal demand. Airline procurement specifications now require Galileo signal compatibility under EUSPA mandates.
- Maritime:Container shipping lines and English Channel ferry operators require resilient beyond-line-of-sight communications. Established volume favors this segment; emerging adoption favors Government as sovereign constellation deployments accelerate.
- Government:Ministry of Armed Forces contracts mandate secure low Earth Orbit architectures with domestic manufacturing content. CNIL cybersecurity certification creates procurement preference for French ground segment vendors.
- Telecommunications:Mobile network operators lease satellite capacity for rural 4G/5G backhaul in Corsica and mountainous Alpine zones where terrestrial microwave links fail.
Defense procurement directives are forcing bifurcation between security-cleared and commercial satellite architectures.
Technology:
Orbital altitude selection trades latency performance against coverage persistence, with hybrid architectures emerging as the structural compromise for mission-flexible government customers.
- Low Earth Orbit:Constellations at 600-1200km altitude enable real-time defense coordination and high-frequency trading connectivity. ARCEP spectrum allocation proceedings for Ka-band create licensing bottlenecks for new entrants.
- Geostationary:Fixed orbital position at 35,786km simplifies ground terminal design for broadcast distribution and rural internet trunking. Established volume favors this segment; emerging adoption favors Low Earth Orbit as latency-sensitive applications multiply.
- Hybrid Systems:Blended architectures combine LEO responsiveness with GEO reliability for customers demanding operational flexibility. French Polynesia and New Caledonia deployments favor this approach.
- Software Defined:Reconfigurable radio payloads compress service launch timelines from years to months. Maritime integrators along Normandy coastlines adopt these systems fastest.
Software-defined architectures are displacing rigid frequency-planning systems that locked operators into fixed spectrum assignments.
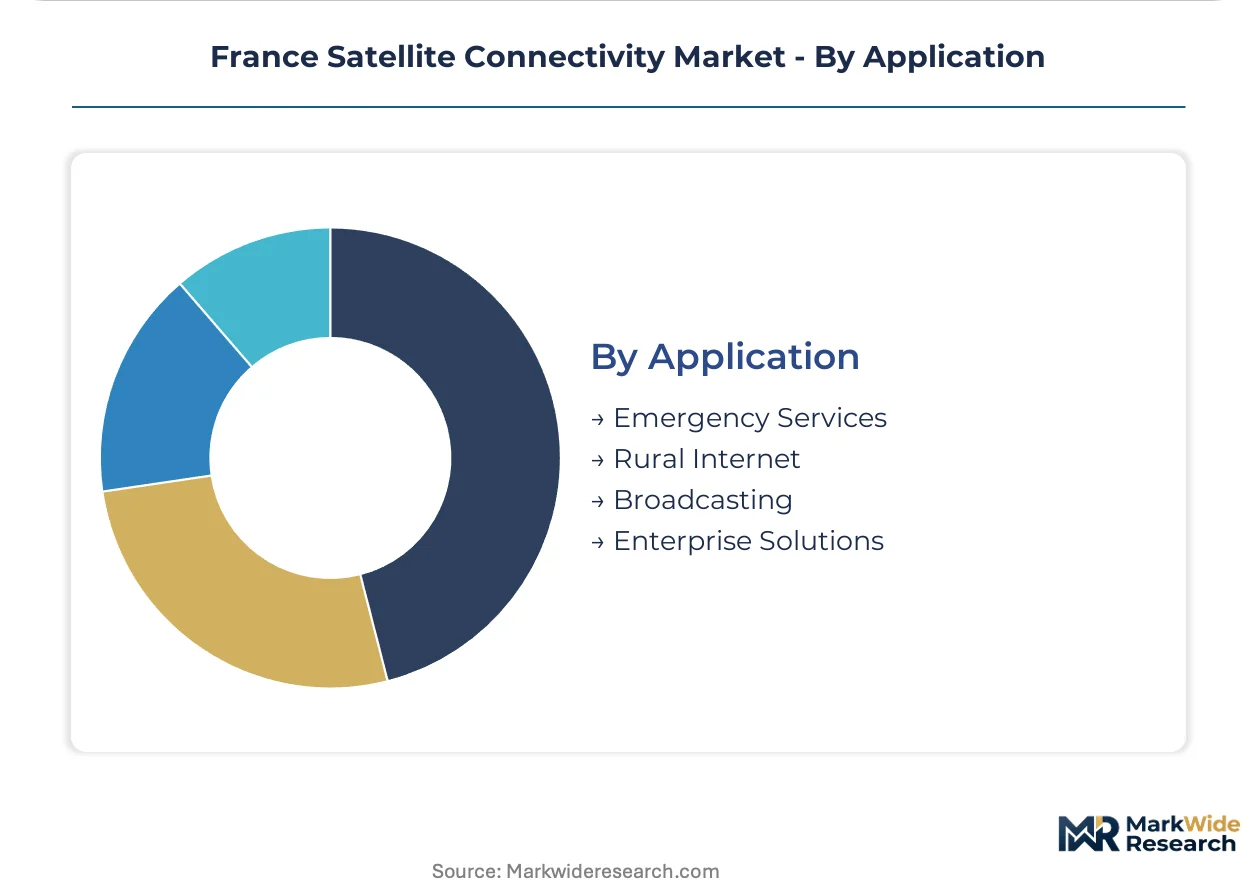
Application:
Application maturity varies sharply, with broadcasting representing legacy revenue pools while enterprise solutions and rural internet drive capital allocation toward low Earth Orbit infrastructure.
- Emergency Services:Gendarmerie and Sécurité Civile require encrypted satellite links for disaster response in seismic zones and Alpine terrain. ANSM mandates govern health data transmission over these networks.
- Rural Internet:Government-subsidized connectivity programs target unserved communes in Centre-Val de Loire and Bourgogne-Franche-Comté. Established volume favors Broadcasting; emerging adoption favors this segment as LEO terminal costs decline.
- Broadcasting:Traditional DTH television distribution retains margin density but faces fiber substitution along coastal zones. Eutelsat maintains geostationary dominance over European video markets.
- Enterprise Solutions:Agricultural IoT and remote energy monitoring shift procurement toward operational expenditure models. Managed service providers in Occitania capture this channel transformation.
Enterprise verticals are climbing the fastest as service unbundling enables pay-per-use satellite connectivity without capital-intensive terminal ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France consumes satellite connectivity differently than peripheral regions, prioritizing defense coordination and aerospace applications over rural internet trunking that dominates inland demand patterns.
Île-de-France
Defense procurement and aerospace manufacturing concentrate satellite connectivity demand around Paris-Saclay and Toulouse-adjacent supply chains. ANSM cybersecurity certification requirements shape vendor selection for government contracts. Thales Alenia Space anchors sovereign payload production in this corridor.
Auvergne-Rhône-Alpes
Alpine terrain drives emergency services demand for encrypted satellite links in seismic response zones. CNIL data sovereignty mandates govern health data transmission over these networks. Rural fire brigades in Grenoble and Lyon peripheries maintain dedicated disaster coordination infrastructure.
Provence-Alpes-Côte d'Azur
Yachting corridors and Mediterranean maritime traffic generate concentrated beyond-line-of-sight bandwidth leases. EUSPA Galileo compatibility requirements force ground segment upgrades. Marseille-based integrators adopt software-defined radio payloads fastest.
Brittany
Fishing fleets and offshore energy platforms require low-latency connectivity where fiber backhaul fails. ARCEP Ka-band allocation proceedings create licensing bottlenecks for new entrants. Maritime operators along Brest and Saint-Malo coastlines represent resilient demand pockets.
French Polynesia
Terrestrial infrastructure economics favor hybrid LEO-GEO architectures across dispersed archipelagos. EU Space Programme regulations mandate Galileo signal compatibility for overseas territory deployments. Tahiti-based operations drive underpenetrated demand for sovereign constellation services.
France Satellite Connectivity Market Competitive Landscape
Capability concentration sits with defense-heritage manufacturers; scale advantage sits with commercial constellation operators. The market structures around three tiers: sovereign payload specialists, geostationary capacity incumbents, and low Earth orbit disruptors. Dominant competitive moves include strategic partnerships for ground segment integration and hybrid architecture offerings that blend orbital altitudes.
Within the sovereign payload tier, Airbus and Thales Alenia Space exemplify vertically integrated manufacturers controlling critical supply nodes from satellite production through ground operations. Eutelsat occupies a position among geostationary capacity providers leveraging orbital persistence over European video markets. These three French-anchored entities represent distinct archetypes: dual-use heritage manufacturers, geostationary incumbents, and integrated platform operators.
| Leading Market Players |
|---|
| Airbus |
| Thales Alenia Space |
| Eutelsat |
| SES |
| Intelsat |
| SpaceX |
| Viasat |
| Telesat |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
English Channel maritime freight corridors carry satellite terminal hardware from Rotterdam and Hamburg distribution hubs into French Atlantic ports, with container rates fluctuating against supply concentration in German antenna manufacturing and Chinese RF component fabrication. This logistics cost dynamic feeds into downstream price differentiation between defense-certified sovereign payloads and commercial off-the-shelf terminals.
Pricing Analysis
Long-term offtake contracts dominate defense procurement under Ministry of Armed Forces directives, while spot capacity leases serve maritime operators in the English Channel and Mediterranean. Price differentiation separates ANSM-certified secure payloads from standard commercial terminals, with cybersecurity compliance commanding substantial premiums. Cost compression in commercial broadband tiers intensifies as LEO constellation capacity expands. Government buyers exhibit the lowest price sensitivity due to sovereign mandate requirements, whereas agricultural IoT adopters in Occitania prioritize operational expenditure models over capital ownership.
Supply Chain Analysis
Extended payment terms from prime contractors to ground segment vendors reflect working capital pressure across the value chain. Satellite manufacturing concentrates in France, Germany, and Italy, with RF semiconductor fabrication anchored in Taiwan, South Korea, and the United States. Critical dependencies include gallium nitride amplifiers, phased array substrates, and radiation-hardened processors. Single-source vulnerability in Ka-band filter components creates procurement bottlenecks during ARCEP licensing windows. Distribution runs through Toulouse-based systems integrators and Paris-Saclay engineering clusters for defense contracts, with commercial maritime sales channeling through Marseille and Brest port authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service unbundling fragments traditional procurement relationships, creating white-space opportunities for specialized ground segment vendors and managed service providers across French overseas territories and rural mainland zones.
For Market Incumbents: Harden sovereign payload production capabilities through captive manufacturing of radiation-hardened components, reducing exposure to Taiwan semiconductor foundry queues. Deepen backward integration into antenna calibration and ground station operations to defend margin position against LEO constellation price erosion. Prioritize CNIL cybersecurity certification maintenance as regulatory barriers escalate for non-European competitors. For New Entrants and Emerging Players: Pursue hybrid LEO-GEO architecture deployments in French Polynesia and New Caledonia, where terrestrial infrastructure economics remain unfavorable and incumbent presence is thin. Target managed service provider relationships in Occitania agricultural IoT and Grand Est renewable energy monitoring, bypassing direct operator competition. Position around software-defined radio payloads to compress service launch timelines against legacy frequency-planning systems. For Investors and Strategic Acquirers: Dual-use heritage manufacturers with established Ministry of Armed Forces contracting relationships present acquisition targets with embedded regulatory moats. Long-term viability hinges on sovereign constellation deployment schedules and ESA funding commitments for European space infrastructure. Watch ARCEP spectrum allocation proceedings as an inflection indicator for new entrant licensing capacity and competitive intensity in Ka-band services.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Constellation Deployment | Blends LEO responsiveness with GEO reliability for government flexibility demands. |
| CNIL Cybersecurity Certification | Creates procurement preference for French ground segment vendors handling citizen data. |
| Software-Defined Radio Integration | Compresses service launch timelines from years to months for maritime integrators. |
| Overseas Territory Expansion | Captures underpenetrated demand in Polynesia and New Caledonia archipelagos. |
| Galileo Signal Compatibility | Mandates ground segment upgrades under EUSPA regulations for aerospace procurement. |
Research Methodology
Desk research of ESA funding disclosures, ARCEP spectrum allocation records, and EU Space Programme regulatory filings preceded structured interviews with satellite payload engineers, ground segment procurement managers, maritime fleet operations directors, and defense acquisition officers. Secondary validation drew from Eutelsat capacity lease disclosures, Thales Alenia Space contract announcements, and customs data tracking terminal hardware imports through French Atlantic ports. Bottom-up segment sizing triangulated against top-down market value estimates from sovereign constellation budget allocations.
Assumptions around Arianespace launch cadence, ARCEP licensing timelines, and Ministry of Armed Forces procurement acceleration were held fixed across the analysis window, while LEO constellation deployment schedules and terminal cost decline curves were stress-tested through sensitivity scenarios. Segmentation modeling incorporated orbital altitude, service architecture, end-user mission profiles, and regulatory compliance tiers. CAGRs were derived from installed base growth in defense secure communications and enterprise broadband adoption, cross-referenced against ESA infrastructure investment trajectories and Galileo ground segment upgrade cycles.
Macroeconomic conditions sit as an overlay; deviation in European defense spending commitments, launch vehicle availability, or semiconductor supply continuity would shift the trajectory. Forecasts reflect documented assumptions regarding spectrum allocation timelines and constellation deployment schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Healthcare Satellite Connectivity Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
LEO Satellite System Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Global Small Satellite Service Market
Satellite
Satellite Services Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Satellite Compass Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Sudan Satellite Transponder Market
Satellite
Russia Satellite Imagery Services Market