
 Satellite Data Service Market | 2026-2036
Satellite Data Service Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Data Service Market Intelligence
Multi-source procurement of satellite imagery and analytics is consolidating as the dominant sourcing pattern across defense and commercial buyers. Planet Labs leverages its daily-coverage constellation to sustain market presence in environmental and agricultural monitoring. Viasat anchors its position through integrated broadband and data-relay services for government and maritime clients. SpaceX competes via Starship-enabled deployment economics and Starlink's expanding earth-observation datalink architecture.
Satellite data service denotes the commercial provision of raw imagery, derived analytics, and continuous monitoring streams generated by earth-observation and communications satellites, typically delivered through cloud-based platforms with revisit frequencies ranging from sub-daily to weekly depending on orbital configuration and sensor payload. Its primary purpose is converting orbital sensor outputs into decision-ready intelligence for resource management, security operations, and infrastructure planning. Imagery and analytics together command the largest revenue share within service-type segmentation, while cloud-based deployment models capture the fastest growth trajectory as hyperscale providers integrate satellite feeds into enterprise workflows. Government agencies represent the deepest customer-type revenue pool, though energy operators and financial analysts are emerging as high-margin segments for predictive monitoring products.
The Federal Communications Commission and the National Oceanic and Atmospheric Administration jointly shape US market access through spectrum licensing and remote-sensing regulatory frameworks, while the EU Space Surveillance and Tracking programme imposes collision-avoidance and debris-mitigation obligations on constellation operators seeking European orbital slots. These regulatory layers elevate compliance costs for new entrants but simultaneously create certification barriers that favor established providers with dedicated policy teams and heritage flight systems. Stakeholders must monitor evolving orbital-slot allocation rules and cross-border data-sovereignty requirements as determinants of scalable market participation.
Market Dynamics
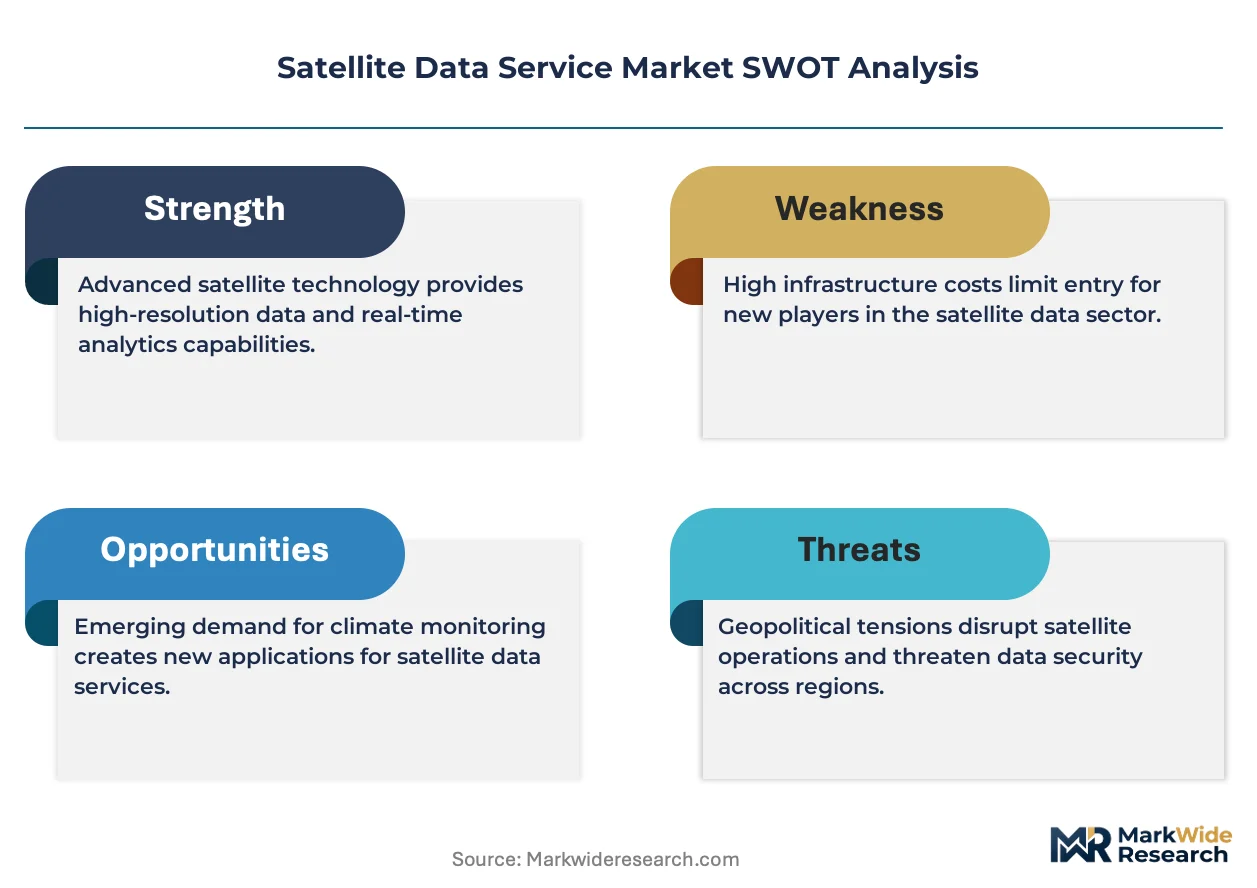
Constellation operators face mounting pressure from the EU Space Surveillance and Tracking framework and parallel national debris-mitigation mandates, which are compressing deployment timelines and elevating compliance spend for new orbital assets.
Growth Catalysts
- Defense procurement acceleration:Federal agencies in the United States are expanding commercial satellite imagery contracts for geospatial intelligence operations. This demand pull is tightening revisit requirements and stimulating sensor diversification across low-earth orbit fleets.
- EU orbital-debris compliance:The EU Space Surveillance and Tracking programme mandates collision-avoidance protocols and end-of-life disposal plans for constellation operators. Certification under this framework unlocks access to European orbital slots and government data-service tenders.
- Cloud-native delivery architectures:Hyperscale platform integration is embedding satellite data streams directly into enterprise resource planning and infrastructure management workflows. Energy operators and agricultural traders now consume sub-daily imagery through API-connected dashboards.
Market Restraints
- Launch capacity concentration:Heavy reliance on a limited set of launch providers creates bottleneck risk for constellation refresh cycles. Deployment delays cascade into revenue recognition gaps for operators with fixed-coverage commitments.
- Spectral licensing friction:The FCC and NOAA jointly administer spectrum allocation and remote-sensing licensing in the United States. Dual-agency review timelines extend market entry by 18-24 months for new sensor payloads.
- Ground segment cost inflation:Antenna networks and downlink facilities in remote geographies require sustained capital outlay. Terrestrial fiber backhaul shortages in Africa and South America inflate operational expenditure for real-time service delivery.
Strategic Opportunities
- Predictive monitoring for financial services:Commodity traders and insurance underwriters represent an underpenetrated demand pool for crop-yield and infrastructure-damage analytics. Subscription pricing for predictive datasets commands margin premiums over raw imagery sales.
- Maritime domain awareness expansion:Port authorities and coast guards in Southeast Asia are procuring automatic identification system fusion with synthetic aperture radar tracking. This application layer builds recurring revenue atop hardware-agnostic data feeds.
- Dual-use technology convergence:Earth-observation sensors are integrating with communications relay payloads on unified satellite buses. This convergence reduces per-unit manufacturing cost and opens blended service contracts spanning imagery and connectivity.
Industry Challenges
- Orbital mechanics talent scarcity:Constellation design and station-keeping optimization require specialized astrodynamics expertise. Universities in the United States and Europe produce insufficient graduates to match operator hiring targets.
- Cross-border data-sovereignty compliance:National restrictions on imagery resolution and geographic coverage create fragmented licensing requirements. Operators must maintain jurisdiction-specific data residency architectures that duplicate infrastructure spend.
- Sensor calibration standardization gaps:Absence of unified radiometric and geometric calibration protocols complicates multi-source analytics fusion. Interoperability friction elevates preprocessing cost for downstream application developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Data Service Market |
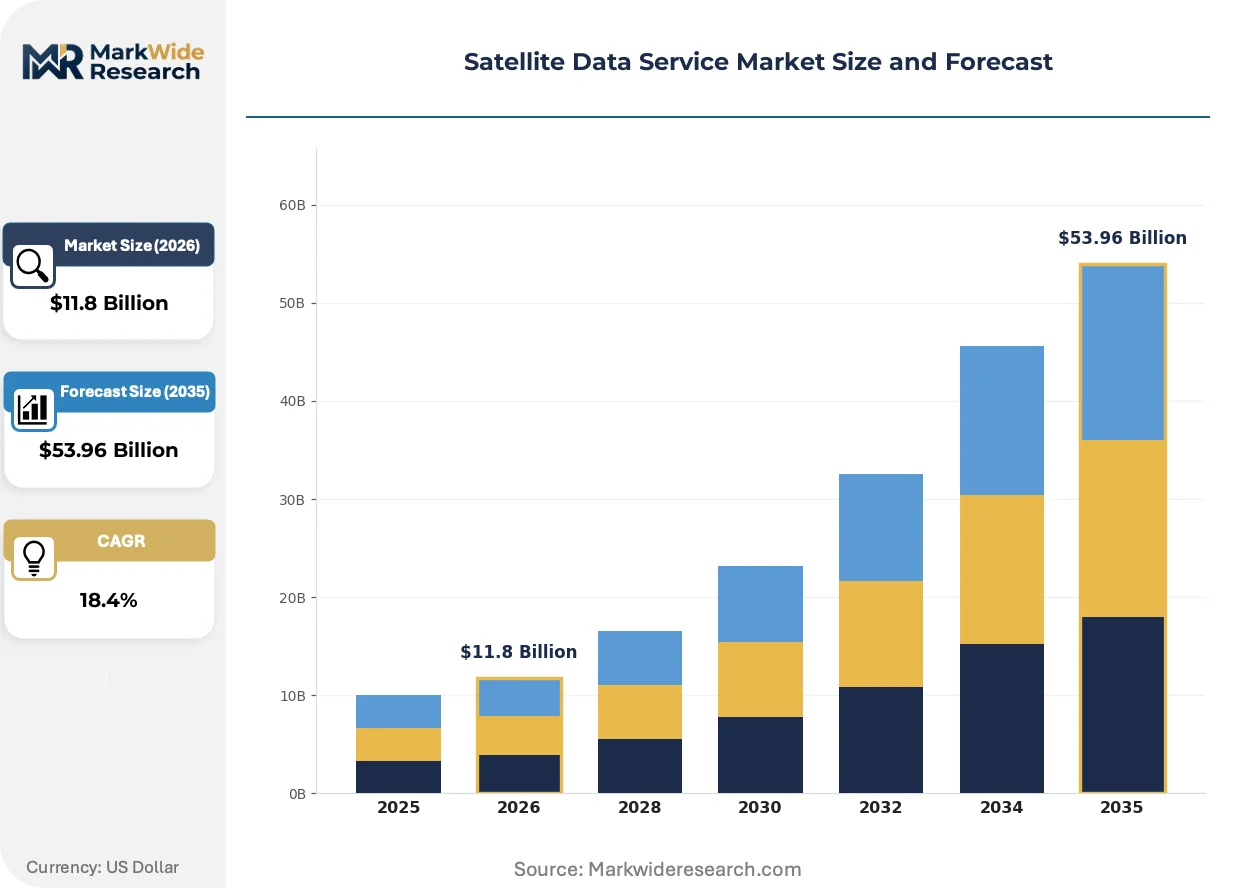
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $53.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Imagery, Analytics, Data Processing, Monitoring, Forecasting Application: Environmental Monitoring, Agriculture Optimization, Maritime Surveillance, Disaster Management, Urban Planning Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Computing Customer Type: Government Agencies, Research Institutes, Telecommunications Providers, Energy Operators, Financial Analysts |
| Companies Covered | IonQ, Viasat, SpaceX, Iridium Communications, ArkEdge Space, Planet Labs, Telesat, Globalstar, Capella Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Data Service Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is compressing the latency between raw sensor capture and decision-ready intelligence, reshaping how defense and commercial buyers consume orbital data.
Onboard processing architectures are integrating machine-learning accelerators directly into satellite payloads. Defense agencies and maritime surveillance operators are adopting these capabilities fastest, driven by contested-environment requirements for reduced ground-dependency. This compression of the analytics pipeline is integrating edge intelligence with existing command-and-control systems, displacing centralized cloud processing for time-sensitive applications.
The EU Space Surveillance and Tracking programme is hardening debris-mitigation standards for constellation operators seeking European orbital registration. Operators must now demonstrate collision-avoidance autonomy and post-mission disposal reliability to secure licensing. Small-satellite manufacturers in Germany and France are responding with modular propulsion systems and standardized de-orbit kits.
Subscription-based consumption models are displacing perpetual licensing for imagery and analytics. Energy majors and agricultural conglomerates are consolidating vendor relationships around multi-year service agreements with guaranteed refresh frequencies. This preference shift is most visible in the United States, where federal procurement templates now prioritize usage-based pricing over capital-intensive satellite ownership.
Satellite Data Service Market Segmentation
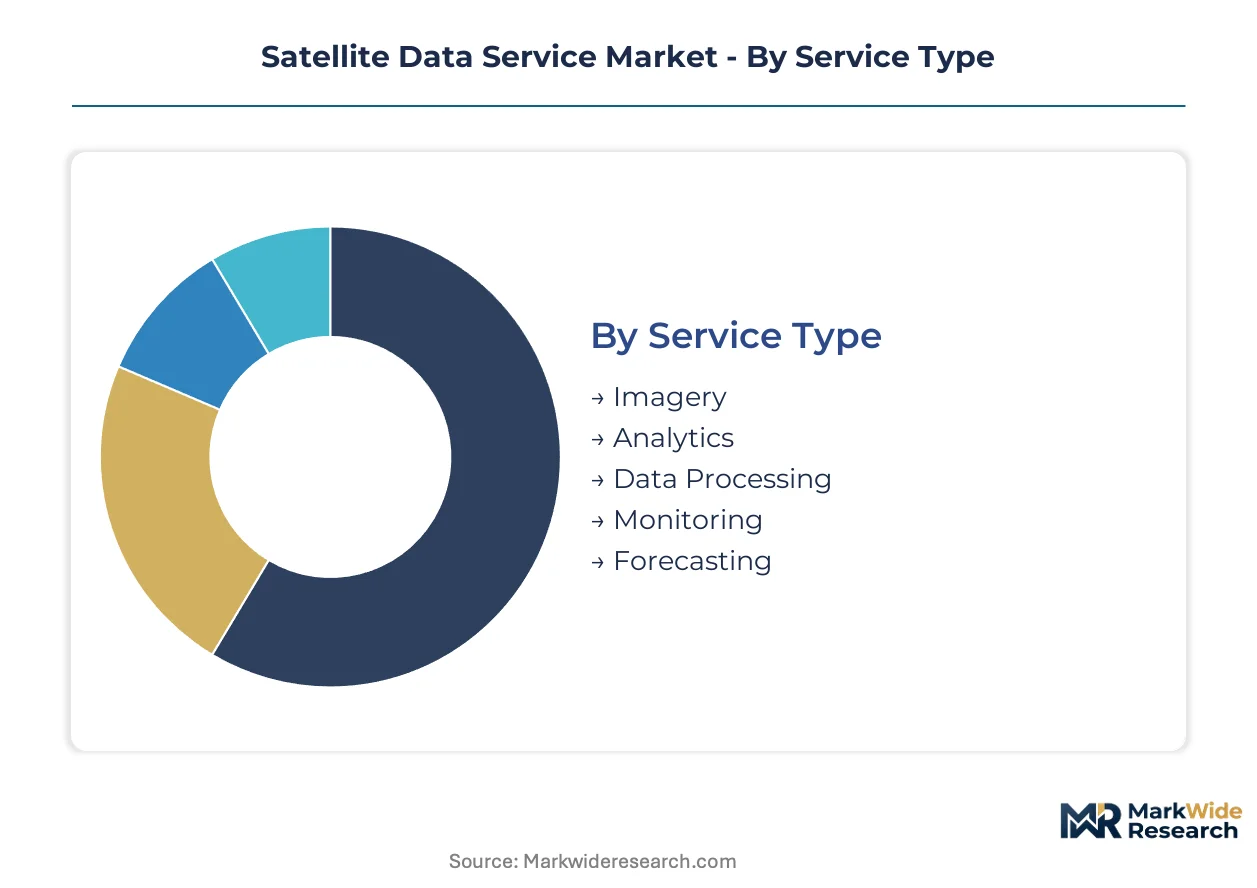
Segmentation in satellite data services reveals how procurement patterns split between integrated enterprise systems and standalone departmental subscriptions. Understanding these fault lines exposes where margin concentrates and which integration paths drive contract renewals.
Service Type:
Integration depth varies sharply across this category, with some services embedding directly into operational workflows while others remain isolated analytical tools.
- Imagery:Raw multispectral and synthetic aperture radar captures delivered through standardized formats. Defense agencies in the United States consume this through multi-vendor procurement vehicles that mandate sub-daily revisit frequencies for contested-area coverage.
- Analytics:Derived intelligence products including change detection and object classification algorithms. Agricultural traders in the US Midwest and commodity funds now embed these directly into automated trading systems, compressing decision latency from days to hours.
- Data Processing:Radiometric correction, orthorectification, and atmospheric compensation pipelines. Processing demand clusters where ground segment infrastructure remains underdeveloped.
- Monitoring:Continuous surveillance subscriptions with guaranteed refresh frequencies. Maritime authorities in Southeast Asia procure these for port security and exclusive economic zone enforcement.
- Forecasting:Predictive models combining satellite inputs with ground-truth validation. Insurance underwriters leverage this for crop-yield and flood-risk pricing.
Imagery leads volumes today; analytics is gaining share fastest.
Application:
Cost tiers separate mission-critical government programs from price-sensitive commercial pilots, with mid-market segments showing the steepest expansion trajectory.
- Environmental Monitoring:Forest carbon tracking, emissions verification, and ecosystem health assessment. European compliance markets under the EU Green Deal drive subscription growth for verified deforestation alerts.
- Agriculture Optimization:Precision irrigation, yield prediction, and crop health mapping. Large-scale operators in Brazil and Argentina integrate these with autonomous machinery fleets.
- Maritime Surveillance:Vessel tracking, illegal fishing detection, and port congestion monitoring. Coast guards in Indonesia and Vietnam fuse automatic identification system data with synthetic aperture radar for dark-ship identification.
- Disaster Management:Rapid damage assessment and resource allocation support. Federal Emergency Management Agency contracts in the United States prioritize 24-hour guaranteed delivery for hurricane and wildfire response.
- Urban Planning:Infrastructure growth tracking and informal settlement mapping. Municipal governments in India deploy these for property tax base expansion and zoning enforcement.
Environmental monitoring commands premium pricing; agriculture optimization shows the broadest addressable market expansion.
Deployment Model:
Customer technical maturity determines adoption patterns, with sophisticated buyers demanding hybrid architectures while smaller users accept pure-cloud delivery.
- Cloud-Based:Fully managed delivery through hyperscale provider infrastructure. Energy majors and agricultural conglomerates in the United States consolidate vendor relationships around multi-year agreements with API-connected dashboards.
- On-Premise:Dedicated hardware installations within customer data centers. Defense and intelligence agencies mandate these for classified imagery handling, requiring air-gapped processing environments.
- Hybrid:Split architectures with raw data on-premise and derived analytics in cloud. Research institutes with mixed sensitivity datasets prefer this for grant-funded projects spanning public and restricted data.
- Edge Computing:Onboard satellite processing with reduced ground dependency. Maritime surveillance operators adopt these capabilities fastest for contested-environment requirements.
Cloud-based deployments dominate new contract value; edge computing is climbing the fastest among defense applications.
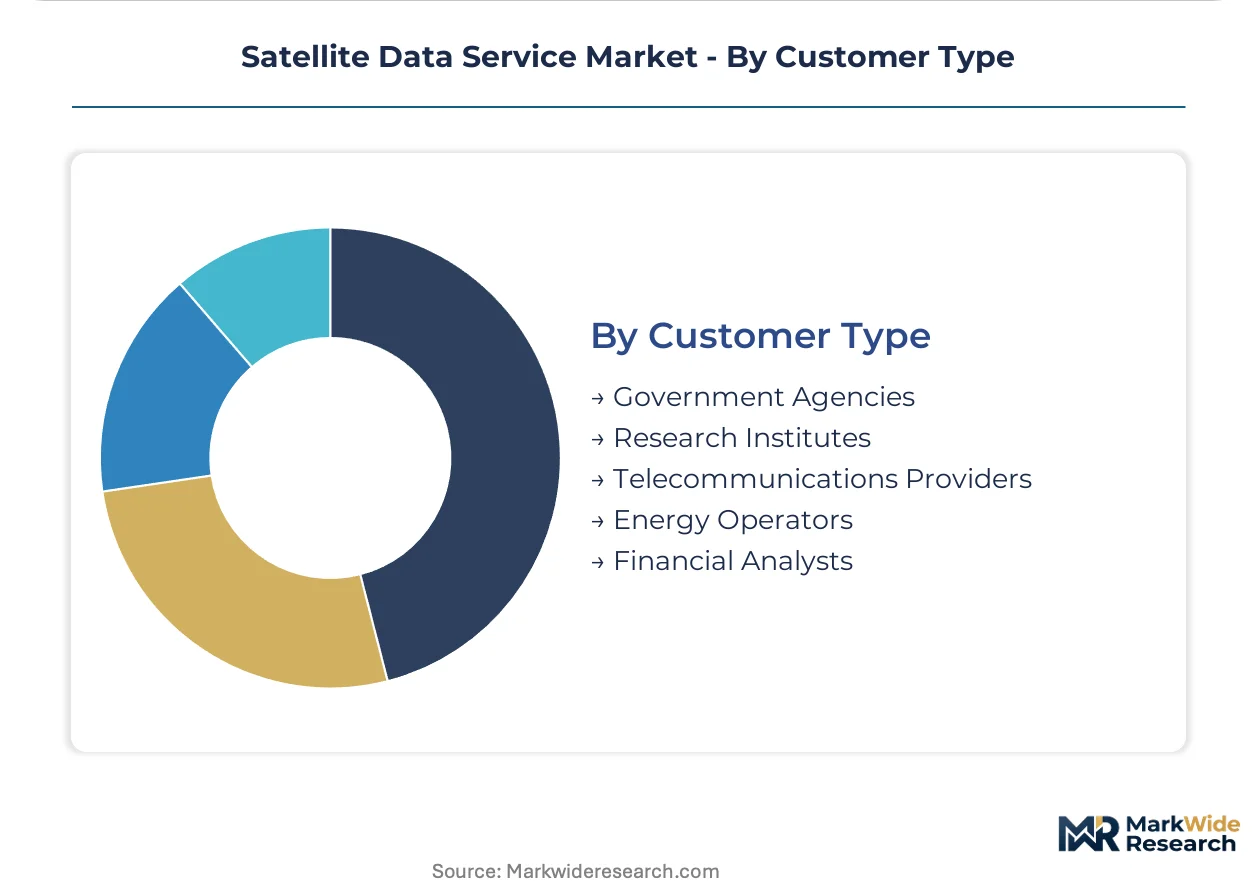
Customer Type:
Procurement sophistication separates entities with dedicated satellite data offices from those purchasing through general IT budgets.
- Government Agencies:Federal civilian and defense departments with established remote-sensing procurement frameworks. National Reconnaissance Office commercial imagery programs in the United States set pricing benchmarks globally.
- Research Institutes:Universities and national laboratories with grant-funded access requirements. Calibration and validation partnerships with these entities reduce sensor standardization costs for operators.
- Telecommunications Providers:Network operators seeking infrastructure monitoring and expansion planning support. Tower companies use this for vegetation encroachment and line-of-sight verification.
- Energy Operators:Oil majors and renewable developers with pipeline and facility surveillance needs. Permian Basin operators subscribe to methane leak detection services for regulatory compliance.
- Financial Analysts:Commodity traders, hedge funds, and insurance underwriters consuming predictive datasets. Crop-yield analytics for agricultural futures trading commands subscription premiums over raw imagery.
Government agencies anchor revenue stability; financial analysts deliver the highest marginal returns per contract.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting constellation deployment capital toward jurisdictions with streamlined licensing timelines. Operators face divergent compliance costs across orbital-registration regimes, reshaping where manufacturing and ground-segment infrastructure concentrate.
United States
Federal procurement of commercial satellite imagery has tightened revisit requirements for geospatial intelligence contracts. The FCC and NOAA jointly administer spectrum allocation and remote-sensing licensing, extending dual-agency review timelines. Colorado's Front Range corridor hosts concentrated ground-segment operations serving defense and energy-sector clients.
China
State-directed investment in earth-observation constellations supports domestic agricultural monitoring and maritime surveillance demand. MIIT coordinates spectrum allocation with national security review requirements for foreign sensor operators. The Yangtze River Delta cluster manufactures small-satellite buses for both civil and dual-use deployment programs.
Germany
Industrial automation and precision agriculture drive commercial uptake of sub-daily imagery analytics. The EU Space Surveillance and Tracking programme imposes collision-avoidance and end-of-life disposal mandates on constellation operators seeking European orbital slots. Munich and Stuttgart anchor a manufacturing corridor producing modular propulsion systems and standardized de-orbit kits.
Japan
Maritime domain awareness requirements from coast guard and fisheries agencies sustain demand for synthetic aperture radar monitoring. METI coordinates national space policy with commercial data-service promotion. The Tokyo-Osaka corridor integrates satellite data streams into supply-chain risk management systems for automotive and electronics exporters.
United Arab Emirates
Sovereign wealth deployment into earth-observation infrastructure supports regional environmental monitoring and urban planning applications. The country's national space agency administers orbital-slot coordination with neighboring Gulf jurisdictions. Dubai's technology free zones host ground-station operations serving Middle East and African markets with reduced data-residency friction.
Satellite Data Service Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue edge-computing payloads and predictive analytics specialization. The vendor base spans vertically integrated constellation operators, hyperscale platform integrators, and application-layer analytics specialists. Three archetypes dominate: daily-coverage imagery providers, broadband-anchored data-relay platforms, and launch-integrated deployment services. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and portfolio diversification into dual-use sensor payloads.
Within the constellation-operator tier, Planet Labs and Viasat exemplify divergent scale strategies, while SpaceX represents launch-integrated vertical control. IonQ and Capella Space occupy positions in specialized sensing and on-orbit processing segments. These entities anchor competitive dynamics around deployment economics, revisit frequency guarantees, and regulatory certification speed rather than pure technology differentiation.
| Leading Market Players |
|---|
| IonQ |
| Viasat |
| SpaceX |
| Iridium Communications |
| ArkEdge Space |
| Planet Labs |
| Telesat |
| Globalstar |
| Capella Space |
| Others |
Cost & Logistics Intelligence
Onboard edge-computing architectures are compressing ground-segment expenditure while concentrating manufacturing among propulsion-integrated satellite bus producers, simultaneously lowering per-unit service delivery costs and elevating supplier bargaining power for radiation-hardened components.
Pricing Analysis
Direct-to-government contracting eliminates distributor margins that inflate commercial analytics pricing. Subscription-based consumption models dominate, with price differentiation hinging on revisit-frequency guarantees and sensor-resolution tiers. Pricing pressure stems from hyperscale cloud providers bundling satellite feeds into enterprise platform licenses, compressing standalone imagery margins. Defense agencies exhibit lowest price sensitivity; agricultural cooperatives in emerging markets show highest elasticity.
Supply Chain Analysis
Regional ground-station distribution centers in Colorado, Bavaria, and the UAE route downlinked data through hub-and-spoke fiber backhaul networks. Satellite manufacturing concentrates in the United States, Germany, and China. Supply chains draw from gallium arsenide solar cells, radiation-hardened semiconductors, and xenon propellant. Single-source vulnerability persists for heavy-lift launch capacity. Distribution runs through cloud API gateways for commercial buyers and dedicated military networks for classified payloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation operators can arbitrage regulatory compliance costs by manufacturing in Germany for EU orbital-slot access while locating ground segments in Dubai's free zones to bypass data-residency restrictions.
For Market Incumbents: Lock in long-term launch agreements with Starship-class providers before capacity constraints tighten. Secure FCC and NOAA licensing pipelines ahead of dual-agency review backlog expansion. Prioritize backward integration into propulsion system manufacturing to defend against German and French component supplier consolidation. For New Entrants and Emerging Players: Hyperscale cloud integrators represent the most penetrable channel for predictive analytics distribution. Target commodity traders and insurance underwriters with crop-yield forecasting subscriptions. Pursue white-space in Southeast Asian maritime domain awareness through AIS-SAR fusion products. For Investors and Strategic Acquirers: Valuations sit cheapest among edge-computing payload specialists lacking constellation scale. Long-term viability favors operators with demonstrated collision-avoidance autonomy under EU SST frameworks. Monitor FCC licensing queue depth as inflection signal for new entrant market access constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Payload Convergence | Earth-observation and communications integration reduces per-unit manufacturing cost for defense contractors. |
| EU SST Certification Investment | Collision-avoidance protocol compliance unlocks European orbital-slot allocation and government tender access. |
| Hyperscale Cloud Partnership | API integration with AWS and Azure embeds satellite streams into enterprise ERP workflows for energy majors. |
| Predictive Analytics Specialization | Crop-yield and infrastructure-damage models command subscription premiums from commodity traders and underwriters. |
| Maritime Domain Awareness Expansion | Indonesian and Vietnamese coast guard contracts build recurring revenue atop hardware-agnostic SAR feeds. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from constellation operations directors, defense procurement officers at the National Reconnaissance Office, cloud platform integration engineers, maritime surveillance commanders, and agricultural commodity trading analysts. Secondary validation drew from FCC licensing databases, NOAA remote-sensing regulatory filings, EU SST compliance registries, and hyperscaler capital expenditure disclosures. Bottom-up service-type demand modeling and top-down macroeconomic anchoring were cross-checked for triangulation.
Comparable historical periods anchored the projection horizon across deployment-model and customer-type dimensions, with additional segmentation by orbital altitude and sensor payload class. CAGRs were derived from fitted growth curves against validated baseline spending patterns. Forecast inputs incorporated launch cost elasticity, spectrum licensing timeline assumptions, and ground-segment infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to launch provider concentration risk and cross-border data-sovereignty fragmentation. Outputs reflect documented assumptions around regulatory review timelines and debris-mitigation technology maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
India Satellite Connectivity Market
Satellite
High-Throughput Satellite Market
Satellite
UK Satellite Imagery Services Market
Satellite
France Satellite Connectivity Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Satellite Gateway Market
Satellite
Russia Satellite Imagery Services Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Nanosatellite Market
Satellite
North America Remote Sensing Services Market
Satellite
4K Satellite Broadcasting Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Italy Satellite Communication Market