
 Europe Satellite Launch Vehicle Market | 2026-2036
Europe Satellite Launch Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Satellite Launch Vehicle Market Insights
Performance pricing for heavy-lift missions is decoupling from small-lift commodity launches across Europe. ArianeGroup anchors the premium segment through Ariane 6 development and French Guiana infrastructure control. Isar Aerospace competes aggressively on small-lift economics from its Bavarian manufacturing base. PLD Space differentiates via dedicated suborbital and orbital small-payload services from Spain.
A satellite launch vehicle is a propulsion system designed to deliver payloads to orbital or suborbital trajectories, typically employing staged chemical rockets with specific impulse ratings exceeding 300 seconds in upper stages. Its primary purpose is to transport satellites, crewed spacecraft, or experimental payloads from Earth's surface to designated orbital altitudes and velocities. Rocket configurations dominate the European landscape, with small payload capacity vehicles attracting the most new entrant investment. Ground-based launch platforms retain structural dominance due to established European spaceport infrastructure in French Guiana and emerging sites in Scotland and Norway.
ESA procurement frameworks and French national space regulations shape launcher development priorities across member states. REACH chemical restrictions and EU Green Deal emissions targets are forcing propellant formulation changes and supply chain requalification. Stakeholders must monitor how ITAR-aligned export controls and emerging EU strategic autonomy mandates reshape component sourcing and cross-border manufacturing partnerships.
Market Dynamics
European sovereign launch mandates are compressing procurement cycles for military satellite constellations while REACH chemical restrictions force propellant reformulation across supply chains. This dual pressure is restructuring competitive positioning between established heavy-lift programs and emerging small-lift entrants.
Growth Catalysts
- EU Space Programme acceleration:The EU Space Programme and national security directives mandate domestic production quotas for defense satellite launches. Member states must demonstrate launch autonomy for classified payloads.
- France:French Guiana's Kourou spaceport infrastructure anchors heavy-lift capacity expansion through sovereign control of launch range operations and propulsion testing facilities.
- Green propellant transition:EU Green Deal emissions targets and REACH restrictions on hydrazine derivatives are accelerating investment in non-toxic propellant families and reusable stage technologies.
Market Restraints
- Input cost volatility:Titanium alloy and carbon fiber prepreg prices fluctuate with aerospace demand cycles, squeezing margins for small-lift vehicle producers without captive supply.
- Supply concentration risk:Ukrainian-built first-stage engines and Russian-sourced titanium sponge previously supplied European programs; requalification of alternative sources extends development timelines.
- Regulatory friction:ITAR-aligned export controls on US-origin avionics and propulsion components complicate cross-border manufacturing partnerships and component sourcing.
Strategic Opportunities
- Norway:Andøya Spaceport and Svalbard polar launch corridors offer underutilized orbital inclinations for sun-synchronous reconnaissance satellites, with infrastructure investment accelerating through 2030.
- Scotland:SaxaVord and Sutherland spaceports target dedicated small-lift missions for commercial constellation deployment, capturing demand from UK-based satellite operators.
- CSRD alignment:The Corporate Sustainability Reporting Directive creates procurement preference for launch services with verified carbon accounting and stage recovery programs.
Industry Challenges
- Propulsion engineering scarcity:Liquid oxygen-methane turbopump design expertise concentrates at ArianeGroup and a handful of German research institutes, constraining new entrant hiring.
- Range certification timelines:ESA and national space agency safety approvals for new launch sites require multi-year environmental impact assessments and flight termination system validations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Satellite Launch Vehicle Market |
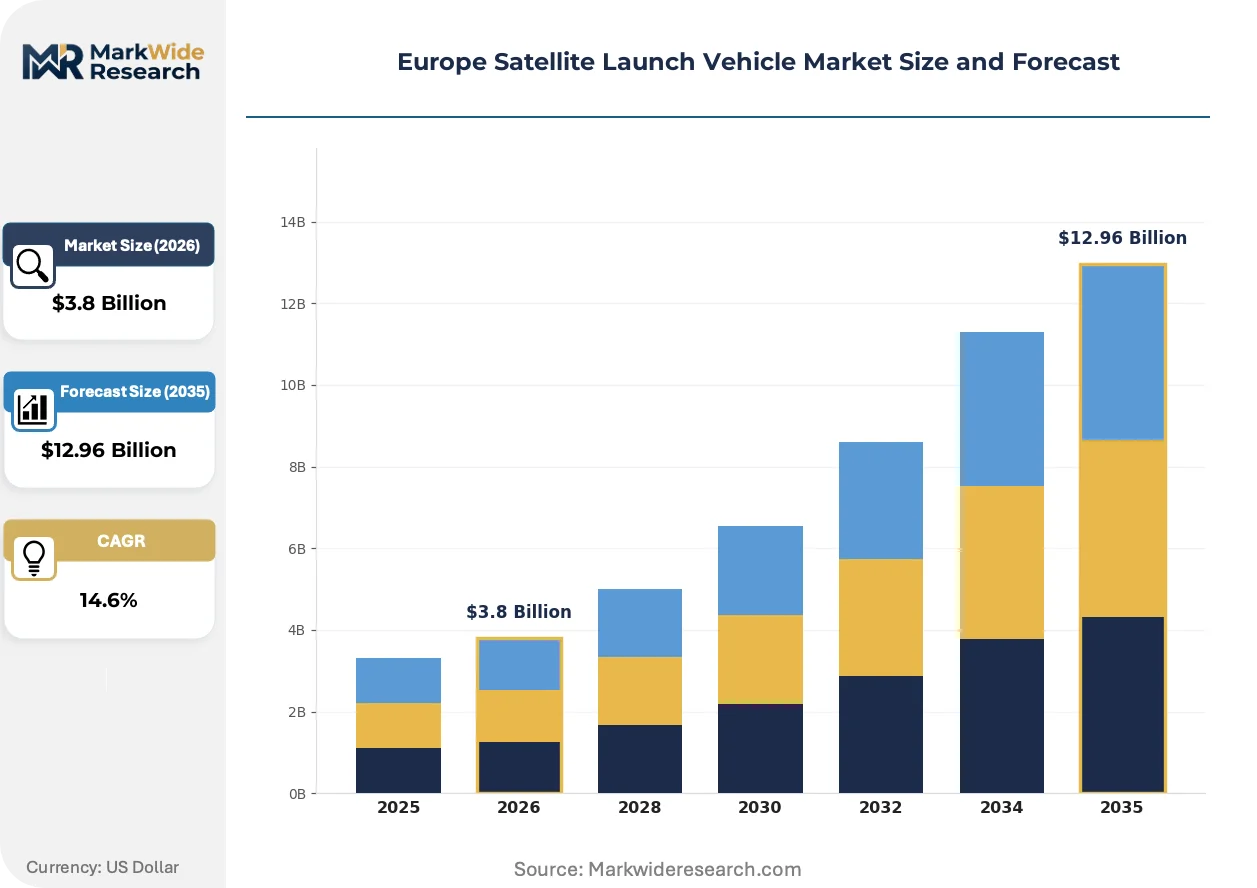
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Rocket, Spaceplane, Airborne, Hybrid Payload Capacity: Small, Medium, Large, Extra Large Launch Platform: Ground-Based, Sea-Based, Air-Launched, Mobile Application: Telecommunication, Earth Observation, Scientific Research, Military |
| Companies Covered | ArianeGroup, Avio, Isar Aerospace, Rocket Factory Augsburg, MaiaSpace, PLD Space, Orbex, Bayern, Arianespace, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Satellite Launch Vehicle Market Trends and Innovations
Modular payload integration and software-defined mission planning are compressing launch preparation cycles. European programs now prioritize rapid reconfigurability over bespoke hardware customization.
Reusable first-stage technology is decentralizing launch economics across the European landscape. Isar Aerospace and PLD Space are adopting propulsive landing architectures for orbital small-lift vehicles. This approach enables higher launch cadence from continental spaceports and reduces per-mission capital recovery requirements for commercial constellation operators.
REACH chemical restrictions are forcing propellant formulation changes across member state programs. The European Chemicals Agency's authorization requirements for hydrazine derivatives are accelerating adoption of green monopropellants and liquid oxygen-methane blends. Small-lift developers in Germany and Spain are responding with dedicated test campaigns for non-toxic ignition systems.
Consolidated procurement by defense agencies is displacing fragmented commercial booking patterns. France's Direction Générale de l'Armement and Germany's BAAINBw now negotiate block-purchase agreements for military satellite launches. This concentration favors launch providers with demonstrated range access and established security clearance frameworks.
Europe Satellite Launch Vehicle Market Segmentation
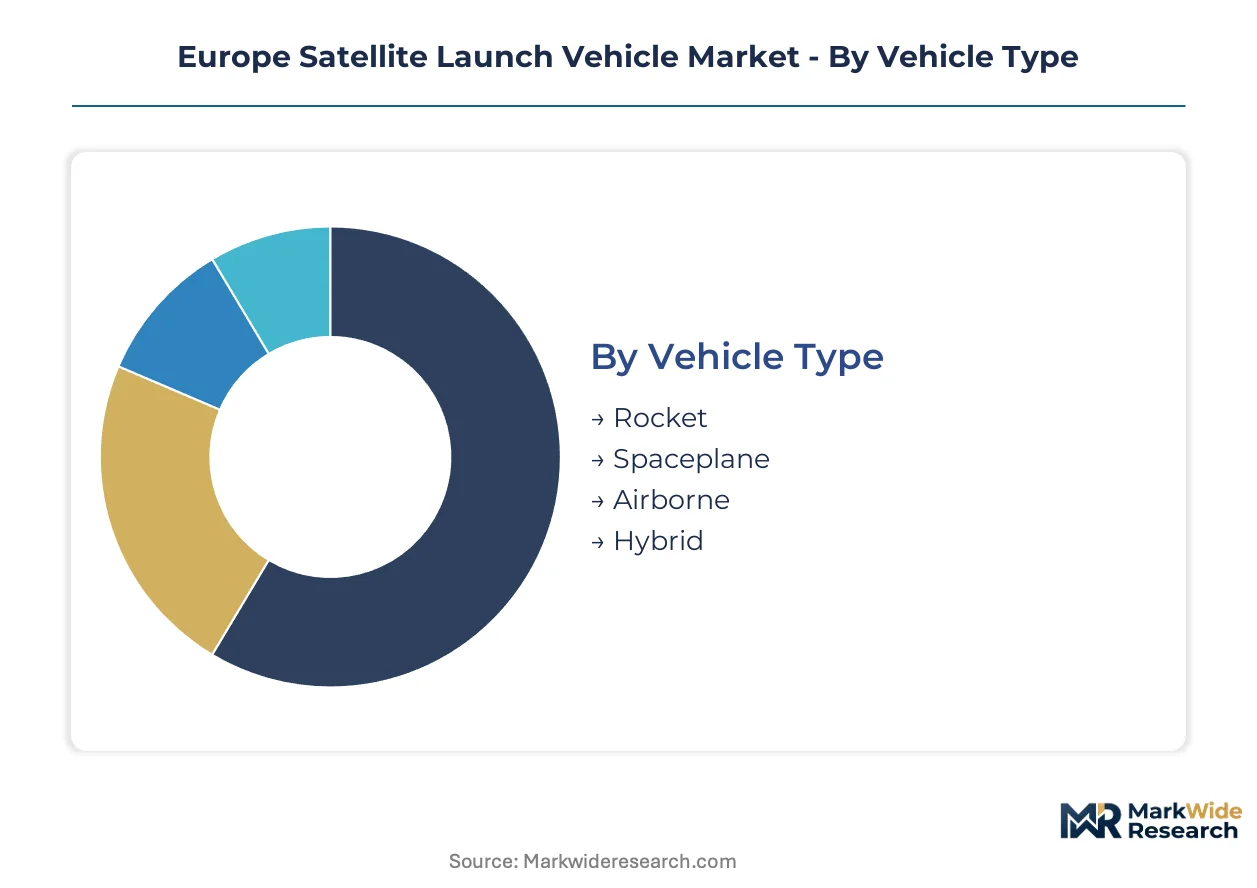
European launch service procurement follows distinct technical and operational criteria across defense, commercial, and institutional buyers. Payload specifications, range access, and sovereign control requirements fragment demand into specialized supplier tiers.
Vehicle Type:
Buyers select propulsion architecture based on mission velocity requirements and payload integration complexity.
- Rocket:Staged chemical propulsion systems with specific impulse ratings exceeding 300 seconds in upper stages. Demand concentrates in France and Germany for ESA institutional missions and military constellation deployment, constrained by REACH chemical restrictions on hydrazine derivatives forcing propellant reformulation.
- Spaceplane:Reusable winged vehicles with horizontal landing capabilities and runway-independent recovery options. Spanish and Italian research programs are advancing suborbital demonstrators for microgravity experimentation, driven by EU Green Deal emissions targets favoring reusable architectures.
- Airborne:Carrier aircraft with underwing or internal payload deployment at altitude. Brief treatment: Limited European operational history; French defense studies evaluate rapid-response orbital insertion for reconnaissance satellites.
- Hybrid:Combined rocket-airbreathing propulsion with altitude-compensating nozzles. Brief treatment: German institutes lead scramjet integration research for future high-speed transport applications.
Volume sits with Rocket configurations; growth tilts toward Spaceplane demonstrators.
Payload Capacity:
Mission economics scale nonlinearly with mass-to-orbit requirements, creating distinct procurement pools.
- Small:Vehicles delivering under 500 kilograms to low Earth orbit. Bavarian manufacturing clusters and Scottish spaceport development are attracting venture investment for commercial constellation deployment, compressed by sovereign launch mandates requiring domestic production quotas.
- Medium:Systems with 500 to 5,000 kilogram lift capacity. French Guiana infrastructure anchors this segment for ESA scientific missions, though Ariane 6 delays are redirecting some institutional demand toward emerging alternatives.
- Large:Heavy-lift vehicles exceeding 5,000 kilograms to geostationary transfer orbit. Brief treatment: ArianeGroup retains structural control through sovereign range operations and propulsion testing facilities.
- Extra Large:Super-heavy configurations for lunar or deep-space trajectories. Brief treatment: Limited European operational demand; ESA studies evaluate international partnership architectures for future crewed exploration.
Procurement concentrates in Small capacity; Medium bookings are climbing the fastest.
Launch Platform:
Range infrastructure availability and orbital inclination access determine platform selection.
- Ground-Based:Fixed-site vertical launch installations with established range safety systems. Kourou and emerging Scottish sites dominate European operational tempo, though environmental impact assessments extend new site certification timelines.
- Sea-Based:Floating launch platforms with equatorial access advantages. Brief treatment: No active European programs; conceptual studies evaluate North Sea deployment for polar orbit missions.
- Air-Launched:Carrier aircraft with payload release at altitude. Brief treatment: Limited European adoption; French defense procurement examines rapid-reconstitution scenarios for damaged satellite constellations.
- Mobile:Transportable launch systems with reduced infrastructure dependency. Brief treatment: German and Norwegian military studies evaluate dispersed launch options for resilience against range targeting.
Ground-Based infrastructure captures current volume; Mobile concepts are gaining share fastest for defense applications.
Application:
End-use mission profiles dictate reliability requirements and payload integration protocols.
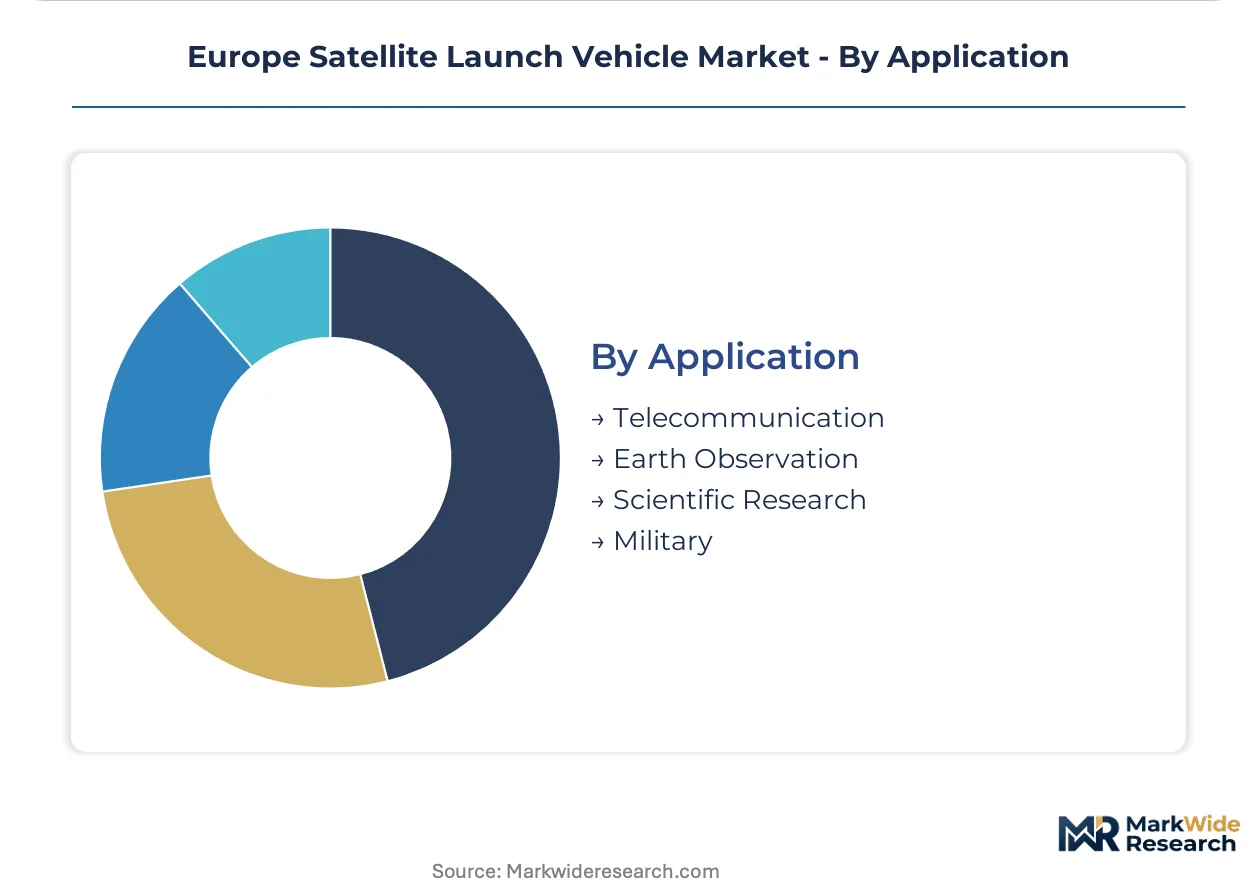
- Telecommunication:Geostationary and medium Earth orbit insertion for commercial broadband constellations. French and Luxembourg-based operators are consolidating procurement through block-purchase agreements, favoring providers with demonstrated range access and security clearance frameworks.
- Earth Observation:Sun-synchronous and polar orbit deployment for imaging constellations. Norwegian Andøya and Svalbard corridors offer underutilized inclinations for reconnaissance satellites, with infrastructure investment accelerating through national space agency commitments.
- Scientific Research:Dedicated missions for ESA, national space agencies, and university payloads. Brief treatment: Institutional procurement prioritizes launch schedule certainty over per-kilogram cost optimization.
- Military:Classified payloads requiring sovereign launch autonomy and end-to-end supply chain control. Brief treatment: French Direction Générale de l'Armement and German BAAINBw negotiate consolidated block purchases, displacing fragmented commercial booking patterns.
Telecommunication missions dominate booked capacity; Military procurement is expanding most quickly under EU strategic autonomy directives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kourou in French Guiana anchors European heavy-lift operations through sovereign control of the Guiana Space Centre. National space agencies and defense procurement offices across member states are accelerating launch infrastructure investment to meet EU strategic autonomy mandates.
France
French military constellation deployment and ESA scientific missions drive sustained demand for medium and heavy-lift capacity. The Direction Générale de l'Armement negotiates consolidated block purchases under national security directives requiring end-to-end supply chain control. ArianeGroup's propulsion testing facilities in Vernon and Les Mureaux anchor liquid hydrogen-oxygen engine development.
Germany
Bavarian manufacturing clusters concentrate venture-backed small-lift vehicle production for commercial constellation operators. The BAAINBw procurement office mandates domestic production quotas for defense satellite launches under EU Space Programme acceleration. Isar Aerospace and Rocket Factory Augsburg operate from Ottobrunn and Augsburg respectively, exploiting regional aerospace engineering density.
Spain
Suborbital research missions and dedicated small-payload orbital services attract institutional and commercial bookings. PLD Space operates from El Arenosillo Test Centre in Andalusia, leveraging national space agency range certification. The Instituto Nacional de Técnica Aeroespacial coordinates propellant reformulation testing for REACH-compliant green monopropellants.
Norway
Polar orbit reconnaissance satellite deployment drives infrastructure investment at Andøya Spaceport and Svalbard launch corridors. The Norwegian Space Agency accelerates range certification timelines for sun-synchronous missions. Kongsberg Defence & Aerospace anchors avionics and flight termination system supply from its Oslo-region facilities.
United Kingdom
Scottish spaceport development at SaxaVord and Sutherland targets dedicated small-lift missions for UK-based satellite operators. The UK Space Agency coordinates environmental impact assessments and safety approvals under national space legislation. Orbex operates from Forres in the Scottish Highlands, exploiting underutilized polar inclinations for Earth observation constellations.
Europe Satellite Launch Vehicle Market Competitive Landscape
Premium-margin players sit above commodity-margin players across vehicle reliability certification and range access tiers. Established heavy-lift programs with sovereign infrastructure control capture defense and institutional procurement, while venture-backed entrants compete on small-lift economics and rapid launch cadence. Three archetypes dominate: state-affiliated primes with captive launch sites, venture-funded scale players with reusable stage architectures, and subscale specialists targeting dedicated payload niches. Competitive moves concentrate on strategic partnerships for propulsion component sourcing and geographic expansion into underutilized polar launch corridors.
Within the state-affiliated prime tier, ArianeGroup and Arianespace occupy positions anchored by French Guiana infrastructure control and ESA procurement frameworks. Among venture-funded scale players, Isar Aerospace exemplifies the Bavarian manufacturing cluster model, while PLD Space represents the southern European specialist archetype targeting suborbital and small-orbital payload services. These named entities illustrate how competitive positioning stratifies across sovereign range access, reusable technology maturation, and green propellant transition timelines.
| Leading Market Players |
|---|
| ArianeGroup |
| Avio |
| Isar Aerospace |
| Rocket Factory Augsburg |
| MaiaSpace |
| PLD Space |
| Orbex |
| Bayern |
| Arianespace |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers with captive launch range infrastructure anchor supply discipline across the European satellite launch vehicle market, compressing margin variability for commercial entrants while reinforcing premium capture for defense-classified missions. State-affiliated primes leverage French Guiana infrastructure control to maintain pricing power on heavy-lift institutional bookings, even as Bavarian venture-funded scale players erode small-lift economics through reusable stage architectures.
Pricing Analysis
Mission-success pricing anchors the European launch services market, with ArianeGroup commanding premium rates tied to demonstrated range access and ESA institutional certification tiers. Price differentiation separates sovereign-defense premiums from commercial-constellation commodity tiers, with reliability-grade certification and end-to-end supply chain traceability driving spreads between segments. Cost compression in small-lift categories is intensifying because Isar Aerospace and PLD Space are racing reusable-technology maturation timelines. Commercial constellation operators exhibit highest price sensitivity, while French Direction Générale de l'Armement and German BAAINBw procurement offices prioritize schedule certainty and security clearance frameworks over per-kilogram optimization.
Supply Chain Analysis
Regional distribution centers for propulsion components cluster around Vernon and Les Mureaux in France, Ottobrunn in Germany, and El Arenosillo in Spain, creating hub-and-spoke patterns for liquid hydrogen-oxygen and liquid oxygen-methane engine subsystems. Supply draws from French aerospace forging facilities, German precision-machining clusters, and Spanish composite manufacturing plants for carbon fiber prepreg structures. Ukrainian-built first-stage engines and Russian-sourced titanium sponge previously fed European programs; requalification of alternative sources extends development timelines and concentrates procurement risk. Distribution runs through ESA-coordinated procurement frameworks and national space agency supply agreements, with REACH chemical restrictions forcing propellant reformulation across member state qualification pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European satellite launch vehicle market sits in a liquid oxygen-methane propulsion transition phase, with green monopropellants and reusable first-stage architectures displacing hydrazine derivatives and expendable legacy systems. This technology inflection compresses competitive timelines and restructures procurement preferences across defense, commercial, and institutional buyer segments.
For Market Incumbents: Deepen backward integration into titanium alloy and carbon fiber prepreg supply through captive French aerospace forging partnerships, insulating against input cost volatility that squeezes small-lift venture competitors. Accelerate range certification timelines for emerging Scottish and Norwegian spaceport infrastructure to preempt entrant capture of polar orbit reconnaissance demand. Investment in liquid oxygen-methane turbopump design expertise retention anchors defensive positioning against German and Spanish new entrant hiring pressure. For New Entrants and Emerging Players: Reusable first-stage technology with propulsive landing architectures offers the most penetrable wedge for commercial constellation operators seeking rapid launch cadence from continental European spaceports. Target Norwegian Andøya and Svalbard polar launch corridors for sun-synchronous Earth observation missions, where infrastructure investment accelerates through national space agency commitments but established primes lack operational history. A go-to-market angle anchored on CSRD-aligned carbon accounting and verified stage recovery programs captures procurement preference from sustainability-mandated institutional buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor Bavarian manufacturing cluster assets with demonstrated liquid oxygen-methane test campaigns and ESA pathway relationships, where venture funding constraints are compressing valuation expectations for scale players. Long-term viability across the analysis window hinges on sovereign launch mandate durability under EU strategic autonomy directives and defense procurement consolidation trends. The signal to watch is block-purchase agreement award velocity from French Direction Générale de l'Armement and German BAAINBw, as these consolidated procurements displace fragmented commercial booking patterns and concentrate revenue visibility for qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Stage Development | Propulsive landing architectures reduce per-mission capital recovery requirements for commercial constellation operators. |
| Green Propellant Transition | REACH-compliant non-toxic monopropellant families unlock ESA and national space agency procurement pathways. |
| Polar Launch Infrastructure | Andøya and Svalbard spaceport certification captures underutilized sun-synchronous reconnaissance satellite demand. |
| Sovereign Range Control | French Guiana infrastructure ownership anchors premium pricing on defense and institutional heavy-lift missions. |
| Propulsion Engineering Acquisition | Liquid oxygen-methane turbopump expertise scarcity constrains new entrant hiring and consolidates talent at established primes. |
Research Methodology
ESA procurement databases, EU Space Programme policy filings, and REACH chemical authorization records formed the secondary backbone, supplemented by customs trade data on titanium sponge and carbon fiber prepreg flows. Primary interviews with launch vehicle program directors, national space agency procurement officers, propulsion test facility managers, and defense satellite constellation planners validated demand assumptions and competitive positioning claims. Bottom-up vehicle production forecasts and top-down ESA budget allocation analysis were triangulated against member state defense procurement disclosures.
Historical trendline analysis of Ariane launch cadence, institutional mission booking patterns, and venture-funded entrant capital deployment informed the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, payload capacity tier, launch platform configuration, and application category, with sovereign-mandate intensity and green propellant qualification status as industry-specific forecast inputs. CAGRs were derived from demand elasticity estimates tied to defense procurement consolidation and commercial constellation deployment schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption of Ukrainian or Russian supply alternatives, abrupt ITAR export control tightening on US-origin avionics, and unanticipated ESA budget reallocation. Forecasts reflect documented assumptions on REACH compliance timelines and reusable technology maturation curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Antenna Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
LEO Satellite Constellation Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Remote Sensing Satellite Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Japan Satellite Communication Market
Satellite
Satellite Transponder Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Low-Cost Satellite Market
Satellite
Satellite Data Analytics Services Market