
 Ground-Based Aircraft and Missile Defense Systems Market | 2026-2036
Ground-Based Aircraft and Missile Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ground-Based Aircraft and Missile Defense Systems Market Foresight
Modular interceptor packaging is rebalancing procurement economics for defense ministries. Lockheed Martin leverages its PAC-3 MSE production footprint to anchor regional supply arrangements. Raytheon Technologies sustains competitive pressure through vertically integrated seeker manufacturing.
Ground-based aircraft and missile defense systems encompass fixed and mobile platforms that detect, track, intercept, and destroy airborne threats including ballistic missiles, cruise missiles, and hostile aircraft; these systems integrate phased-array radars with hit-to-kill interceptors operating at closure velocities exceeding Mach 5 to protect critical infrastructure and military installations. Surface-to-Air Missiles command the largest revenue pool due to recurring procurement by tier-one militaries, while Command and Control Systems represent the fastest expansion trajectory as network-centric warfare architectures proliferate. Early Warning Systems occupy a mature margin position where upgrade cycles rather than new deployments drive replacement demand.
The US Department of Defense's Joint All-Domain Command and Control framework compels interoperability standards that reshape vendor qualification pathways. Israel's Ministry of Defense and South Korea's Defense Acquisition Program Administration enforce localized content requirements that constrain pure foreign participation. Stakeholders must monitor how counter-hypersonic performance specifications rewrite technical baselines before next-generation procurement cycles finalize.
Market Dynamics
The Joint All-Domain Command and Control framework from the US Department of Defense is forcing interoperability standards that reshape vendor qualification pathways across the entire contractor base. Defense ministries now mandate open-architecture protocols that break proprietary lock-in.
Growth Catalysts
- Counter-hypersonic specifications:NATO member states are expanding procurement of layered air defense architectures to address maneuverable reentry vehicles. Technical baselines for interceptor velocity and sensor fusion are tightening procurement criteria.
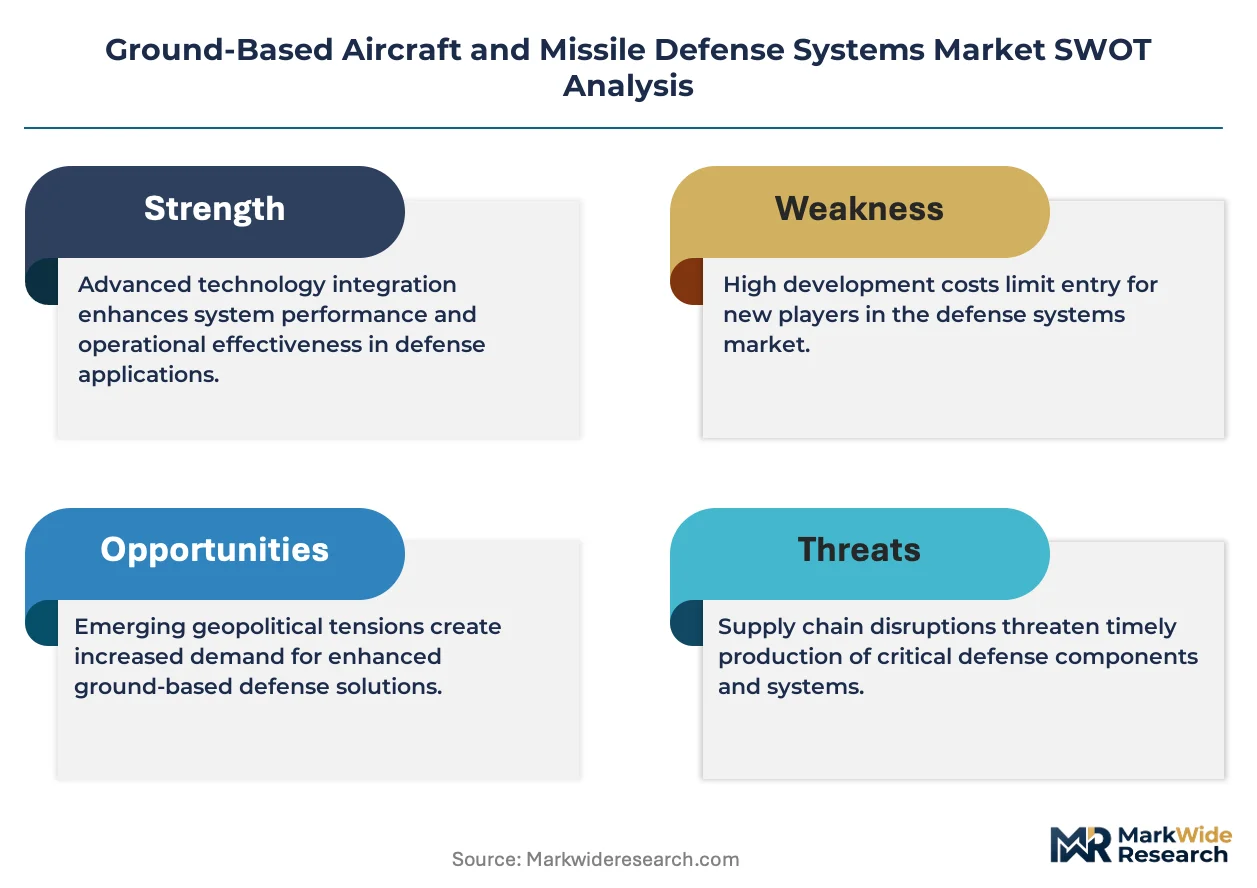
- Israeli localization mandates:The Ministry of Defense enforces domestic content requirements that create captive supply chains for radar components and seeker manufacturing within Israeli defense industrial zones.
- Counter-UAS prioritization:South Korea's Defense Acquisition Program Administration is accelerating fielding of short-range interceptors against drone swarms. Urban air defense requirements are expanding the addressable platform base.
Market Restraints
- Gallium nitride foundry concentration:Active electronically scanned array radar production depends on specialized semiconductor fabrication concentrated in East Asian supply nodes. Disruption cascades through seeker and fire-control subsystem availability.
- Hit-to-kill propellant chemistry:Solid rocket motor formulations rely on constrained domestic supply of ammonium perchlorate and specialized aluminum powder. Input cost volatility compresses margin on interceptor production lots.
- Technology transfer thresholds:International Traffic in Arms Regulations create licensing friction for subsystem exports to non-NATO partners. Foreign military sales timelines extend qualification cycles for integrated fire units.
Strategic Opportunities
- Poland's Wisla program:The country's medium-range air defense gap creates white space for integrated battle command systems with indigenous radar integration. Offset agreements favor technology insertion over turnkey procurement.
- Directed energy convergence:Solid-state laser and high-power microwave systems are converging with kinetic interceptors in layered architectures. Hybrid fire units offer magazine depth without reload logistics.
- Australian sovereign guided weapons enterprise:The Department of Defence's domestic production mandate creates channel opportunity for component suppliers establishing regional maintenance and integration facilities.
Industry Challenges
- Systems engineering talent scarcity:Model-based systems engineering and digital thread expertise sits with a narrow cohort of defense primes. Workforce pipeline constraints delay program milestones.
- Legacy radar integration complexity:Phased-array upgrades must interface with analog-era command interfaces and proprietary data buses. Retrofit engineering consumes non-recurring engineering budgets.
- Security clearance throughput:Personnel vetting backlogs restrict cleared labor availability for classified subsystem development. Program staffing plans assume clearance timelines that clearance authorities cannot meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground-Based Aircraft and Missile Defense Systems Market |
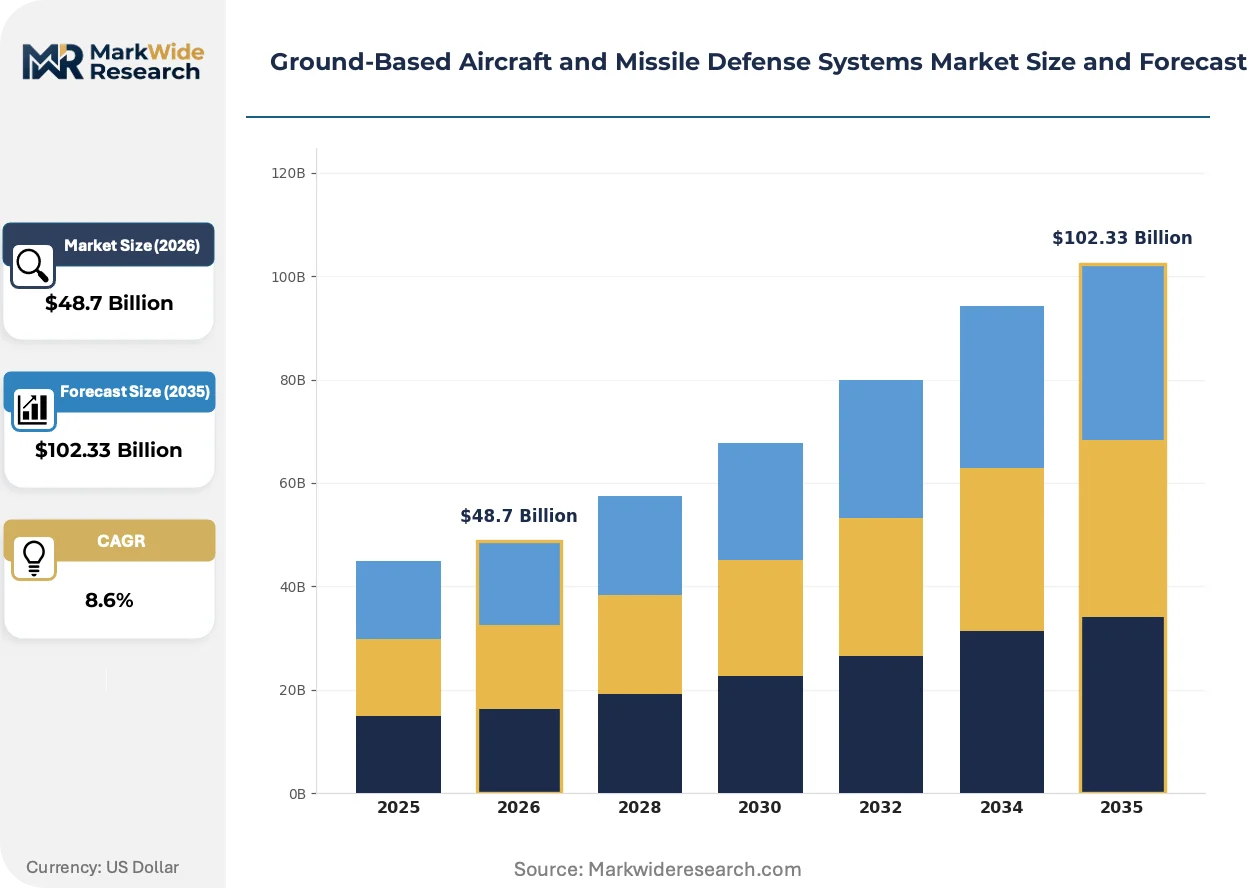
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface-to-Air Missiles, Interceptor Missiles, Early Warning Systems, Command and Control Systems Application: Military Defense, Air Traffic Management, Homeland Security, Civil Aviation End User: Military Forces, Government Agencies, Defense Contractors, Security Services Technology: Active Radar, Passive Radar, Infrared, Electro-Optical |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, The Boeing Company, Thales Group, Israel Aerospace Industries, Northrop Grumman Corporation, Leonardo S.p.A., Saab AB, Rafael Advanced Defense Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground-Based Aircraft and Missile Defense Systems Market Shifts & Advancements
Modular interceptor packaging is rebalancing procurement economics for defense ministries seeking magazine flexibility without platform replacement. Digital engineering and model-based acquisition are compressing development cycles for fire-control software.
Gallium nitride transmit-receive modules are overtaking gallium arsenide in phased-array radar construction. The US Missile Defense Agency and Israeli Ministry of Defense are fielding GaN-based fire-control radars for improved power-aperture product and electronic counter-countermeasure resilience. This material transition is compressing the performance gap between fixed-site and mobile radar configurations, enabling expeditionary deployment of capabilities previously restricted to hardened installations.
The US Department of Defense's Cybersecurity Maturity Model Certification framework is mandating supply-chain security attestations for contractors handling controlled unclassified information. Prime integrators are flowing down compliance requirements to tier-three component suppliers, restructuring subcontractor qualification pathways. Small enterprises without dedicated security infrastructure face exclusion from future procurement cycles as CMMC Level 2 certification becomes a gate for contract award.
Allied defense ministries are consolidating procurement authority under centralized acquisition agencies rather than service-specific program offices. The UK's Defence Equipment and Support and Australia's Capability Acquisition and Sustainment Group are negotiating enterprise-wide munitions contracts that aggregate demand across air, land, and maritime domains. This buyer concentration is compressing supplier margins while extending contract duration and performance-based logistics obligations.
Ground-Based Aircraft and Missile Defense Systems Market Segmentation
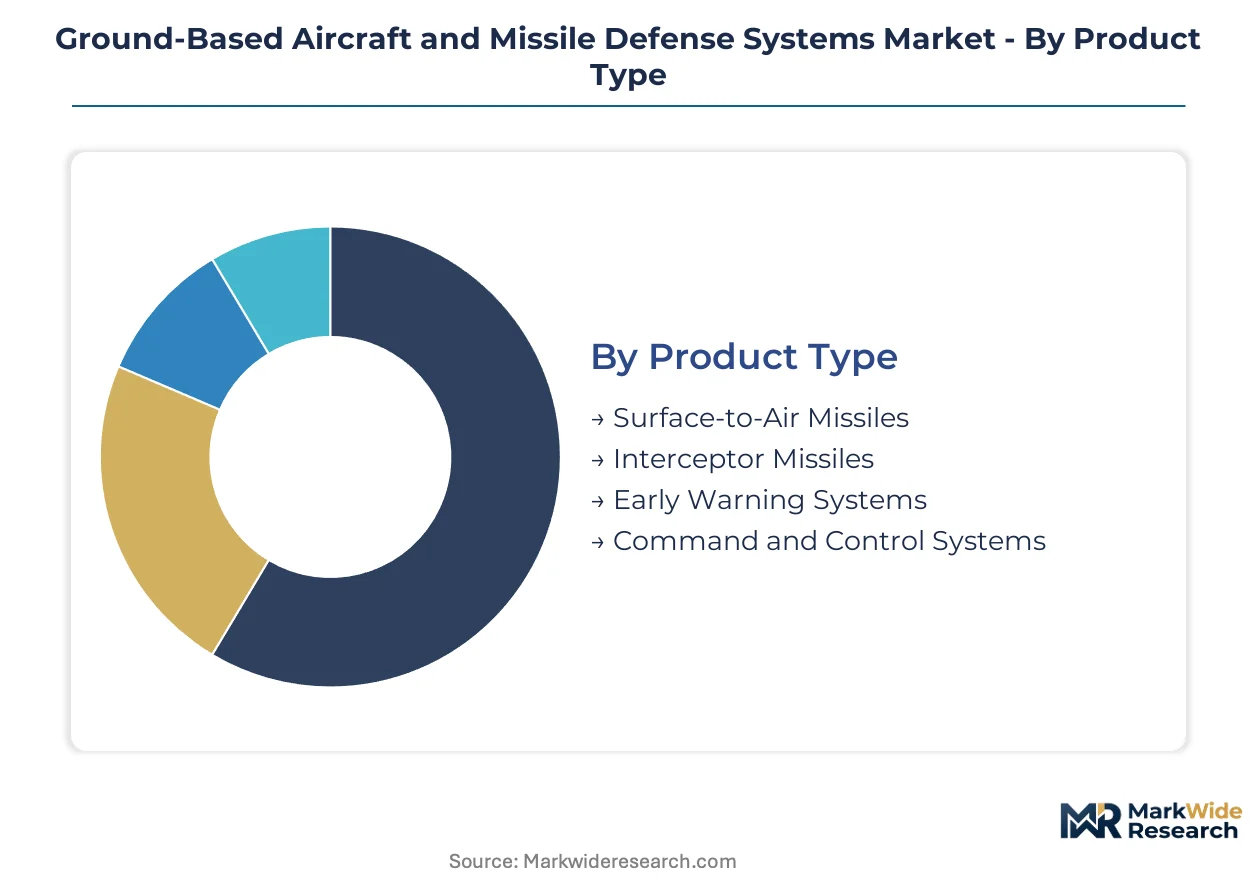
Defense procurement cycles favor modular architectures that allow incremental capability insertion without platform replacement. Segmentation in this market tracks where upgrade investments concentrate versus where next-generation specifications are rewriting technical baselines.
Product Type:
Replacement cycles vary sharply by subsystem maturity, with legacy radar upgrades competing against greenfield interceptor deployments for budget share.
- Surface-to-Air Missiles:Solid-fuel interceptors with hit-to-kill seekers operating at Mach 5+ closure velocities. Procurement concentrates in the United States, Israel, and South Korea as layered air defense architectures expand against cruise missile and UAS threats; recurring production lots sustain the largest revenue pool.
- Command and Control Systems:Network-centric fire-control software integrating multi-sensor fusion with distributed engagement coordination. The fastest expansion trajectory belongs here as Joint All-Domain Command and Control mandates force interoperability upgrades across NATO inventories.
- Interceptor Missiles:Specialized counter-ballistic and counter-hypersonic kill vehicles with exo-atmospheric discrimination capabilities. Demand clusters around US Missile Defense Agency test programs and Israeli tiered defense deployments.
- Early Warning Systems:Phased-array and over-the-horizon radars providing target acquisition cueing for fire-control networks. Upgrade cycles rather than new deployments dominate procurement as analog-era installations receive digital back-end retrofits.
Volume placements concentrate in Surface-to-Air Missiles; the faster expansion belongs to Command and Control Systems.
Application:
Threat environment differentiation shapes procurement specifications, with military requirements setting performance baselines that cascade into adjacent segments.
- Military Defense:Integrated air and missile defense protecting maneuver forces and fixed installations against aircraft, ballistic missiles, cruise missiles, and UAS swarms. Procurement in the United States, Poland, and South Korea drives specification tightening for counter-hypersonic and counter-UAS performance.
- Homeland Security:Fixed-site protection of critical infrastructure and population centers against asymmetric airborne threats. Israeli urban air defense requirements and US northern border surveillance needs expand the addressable platform base.
- Air Traffic Management:Cooperative and non-cooperative aircraft detection for civilian-military airspace integration. European and Australian programs mandate secondary surveillance radar upgrades with military-grade identification capabilities.
- Civil Aviation:Airport perimeter defense and approach corridor monitoring against drone incursions. Regulatory pressure from the FAA and EASA accelerates counter-UAS sensor deployment at major hubs.
Procurement value clusters in Military Defense; Homeland Security applications are climbing the fastest as urban air defense requirements proliferate.
End User:
Contracting authority consolidation under centralized acquisition agencies is compressing supplier margins while extending performance obligations.
- Military Forces:Service-specific program offices and joint commands operating layered defense architectures. The US Department of Defense, Israeli Ministry of Defense, and South Korean Defense Acquisition Program Administration anchor demand with localized content mandates.
- Government Agencies:Civil defense and emergency management authorities requiring interoperable warning and coordination systems. Australia's Department of Defence and the UK's Defence Equipment and Support aggregate demand across domains.
- Defense Contractors:Prime integrators and subsystem suppliers performing depot maintenance and spiral upgrades. Cybersecurity Maturity Model Certification requirements from the US Department of Defense restructure subcontractor qualification pathways.
- Security Services:National police and critical infrastructure protection units fielding short-range counter-UAS capabilities. South Korean and Israeli urban deployments expand this user category beyond traditional military customers.
Military Forces account for dominant placement volumes; Security Services represent the steepest expansion trajectory as counter-UAS missions migrate to law enforcement authorities.
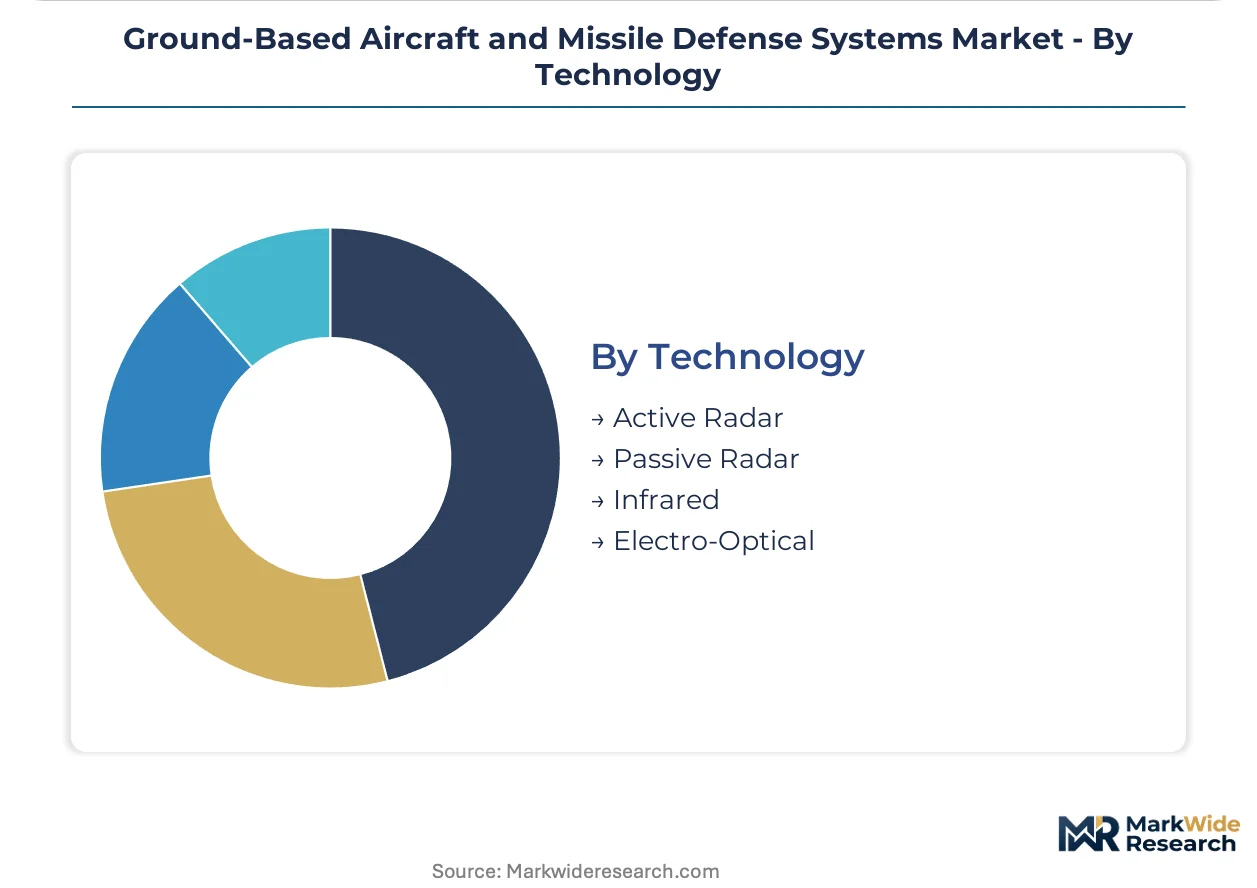
Technology:
Material transitions in radio-frequency components are compressing performance gaps between fixed-site and expeditionary radar configurations.
- Active Radar:Gallium nitride transmit-receive modules enabling improved power-aperture product and electronic counter-countermeasure resilience. The US Missile Defense Agency and Israeli Ministry of Defense field GaN-based fire-control radars that displace legacy gallium arsenide systems.
- Passive Radar:Non-emitting detection exploiting commercial broadcast and communications signals for covert target tracking. European research programs and Australian sovereign guided weapons initiatives explore passive architectures for electromagnetic signature reduction.
- Infrared:Thermal imaging seekers and staring arrays for terminal guidance and surveillance. Hit-to-kill interceptor production depends on cooled infrared focal plane arrays with constrained domestic supply chains.
- Electro-Optical:Visible-spectrum and multi-spectral sensors for target identification and battle damage assessment. Integration with directed energy fire control creates hybrid engagement architectures.
Active Radar dominates current procurement volumes; Passive Radar is gaining share fastest as electromagnetic survivability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones in Huntsville, Alabama, and Tel Aviv anchor production concentration for ground-based aircraft and missile defense systems. These tax-advantaged clusters concentrate radar manufacturing, seeker assembly, and systems integration capabilities. Procurement authority consolidation under centralized acquisition agencies is reshaping regional competitive dynamics.
United States
The Missile Defense Agency's test programs and Joint All-Domain Command and Control mandates drive demand for integrated fire-control networks. The Department of Defense enforces Cybersecurity Maturity Model Certification requirements that restructure subcontractor qualification pathways. Huntsville's Cummings Research Park concentrates PAC-3 MSE production and GaN radar module integration for expeditionary deployments.
Israel
Tiered defense architectures against regional missile threats sustain procurement for Iron Dome and Arrow system upgrades. The Ministry of Defense imposes domestic content requirements that create captive supply chains for radar components within Israeli defense industrial zones. Rafael Advanced Defense Systems and Israel Aerospace Industries anchor production clusters around Haifa and the Negev.
South Korea
Counter-UAS prioritization and urban air defense requirements accelerate fielding of short-range interceptors against drone swarms. The Defense Acquisition Program Administration mandates localized production through offset agreements with foreign primes. The Seoul Capital Area concentrates L-SAM and M-SAM system integration facilities with indigenous radar development.
Poland
The Wisla program's medium-range air defense gap creates white space for integrated battle command systems with indigenous radar integration. Poland's Armament Agency negotiates offset agreements favoring technology insertion over turnkey procurement. The Ośrodek Badawczo-Rozwojowy Centrum Techniki Wojskowej in Warsaw coordinates domestic subsystem development for layered architectures.
Australia
The Department of Defence's sovereign guided weapons enterprise mandate drives domestic production requirements for component suppliers. Australia's Capability Acquisition and Sustainment Group aggregates demand across domains through enterprise-wide munitions contracts. The Edinburgh Defence Precinct in South Australia anchors regional maintenance and integration facilities for guided weapons.
Ground-Based Aircraft and Missile Defense Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across subsystem tiers. The vendor base concentrates around prime integrators with established defense ministry relationships and cleared manufacturing facilities. Three archetypes dominate: vertically integrated primes controlling seeker-to-launcher production, radar specialists supplying fire-control subsystems, and regional champions serving captive domestic markets. Competitive moves center on backward integration into GaN semiconductor fabrication and strategic partnerships for directed energy convergence.
Within the prime integrator tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify vertically integrated production architectures. Lockheed Martin leverages its PAC-3 MSE production footprint to anchor regional supply arrangements, while Raytheon Technologies sustains competitive pressure through in-house seeker manufacturing. Rafael Advanced Defense Systems Ltd. occupies a position as a regional champion serving Israeli localization mandates and export markets with technology transfer constraints.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| The Boeing Company |
| Thales Group |
| Israel Aerospace Industries |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Saab AB |
| Rafael Advanced Defense Systems Ltd. |
| Others |
Supply & Pricing Matrix
Performance-tier divergence between GaN-enabled fire-control radars and legacy gallium arsenide systems manifests in both procurement premiums and captive supply arrangements. Defense ministries enforce certification ladders that tie price bands to CMMC compliance levels and domestic content thresholds.
Pricing Analysis
Short lead-time premiums for ammonium perchlorate and specialized aluminum powder compress margins on expedited interceptor production lots. Three-tier pricing structure across CMMC Level 3 certified, Level 2 compliant, and uncertified supplier tiers reflects cybersecurity attestation costs. Price differentiation hinges on GaN module integration depth and seeker manufacturing location. Tier-three component suppliers face the steepest price sensitivity as prime integrators flow down compliance costs.
Supply Chain Analysis
Direct-to-prime channels handle classified subsystem demand while foreign military sales flow through licensed export frameworks. GaN foundry capacity concentrates in Taiwan, South Korea, and the United States. Solid rocket motor production draws from constrained domestic ammonium perchlorate supply and specialized aluminum powder feedstock. Single-source vulnerability in East Asian semiconductor fabrication cascades through radar and seeker availability. Distribution runs through defense ministry program offices and centralized acquisition agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride transmit-receive modules are displacing legacy gallium arsenide architectures across phased-array radar procurement. This material transition rewrites technical baselines and vendor qualification pathways.
For Market Incumbents: Extend GaN foundry partnerships into captive supply arrangements before raw material allocation tightens. Backward integration into seeker manufacturing insulates against Raytheon's vertically integrated cost position. Lockheed Martin's PAC-3 MSE regional supply footprint offers a template for anchoring long-term ministry relationships. For New Entrants and Emerging Players: Capture Poland's Wisla program white space through offset-compliant radar integration partnerships. Australia's sovereign guided weapons enterprise creates channel opportunity for component suppliers establishing regional maintenance facilities. Position around CMMC Level 2 certification as a contract-award gate. For Investors and Strategic Acquirers: Exit pathways concentrate in prime-integrator acquisition of GaN semiconductor specialists and directed energy convergence plays. Long-term viability favors suppliers with cleared manufacturing facilities and established defense ministry relationships. Watch counter-hypersonic specification finalization as procurement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Captive supply of transmit-receive modules insulates against East Asian concentration risk. |
| CMMC Level 3 Certification | Cybersecurity attestation unlocks classified subsystem development contracts with US primes. |
| Offset Agreement Structuring | Technology insertion clauses in Poland and South Korea enable market entry without turnkey burden. |
| Directed Energy Convergence | Hybrid fire units combining kinetic interceptors with solid-state lasers address magazine depth constraints. |
| Regional Maintenance Hub | Australian sovereign guided weapons mandate creates recurring revenue through depot-level integration. |
Research Methodology
Defense contract announcements, Missile Defense Agency test program disclosures, and Israeli Ministry of Defense procurement bulletins formed the secondary backbone. Primary interviews with program office acquisition leads, radar systems engineers, and solid rocket motor procurement directors validated production capacity and technology transition timelines. Bottom-up segmentation modeling triangulated against top-down defense budget allocation analysis across the analysis window.
Historical production lot data and ministry expenditure patterns established baseline trendlines for interceptor and radar procurement. Segmentation dimensions included product type, application, end user, and technology tier across the projection horizon. CAGR derivation incorporated Joint All-Domain Command and Control mandate implementation schedules and counter-hypersonic specification development trajectories.
The model holds under sustained defense budget authorization and stable International Traffic in Arms Regulations licensing timelines; deviation in congressional appropriation cycles or export control tightening would shift procurement phasing. Forecasts reflect assumptions regarding GaN foundry capacity expansion and cleared labor pipeline throughput. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Airborne Fire Control Radar Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Global Missile Interceptor Market
Air Defense
Americas Air Defense Systems Market
Air Defense
North America Missiles and Missile Defense Systems Market