
 Satellite Communication Equipment Market | 2026-2036
Satellite Communication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communication Equipment Market Outlook
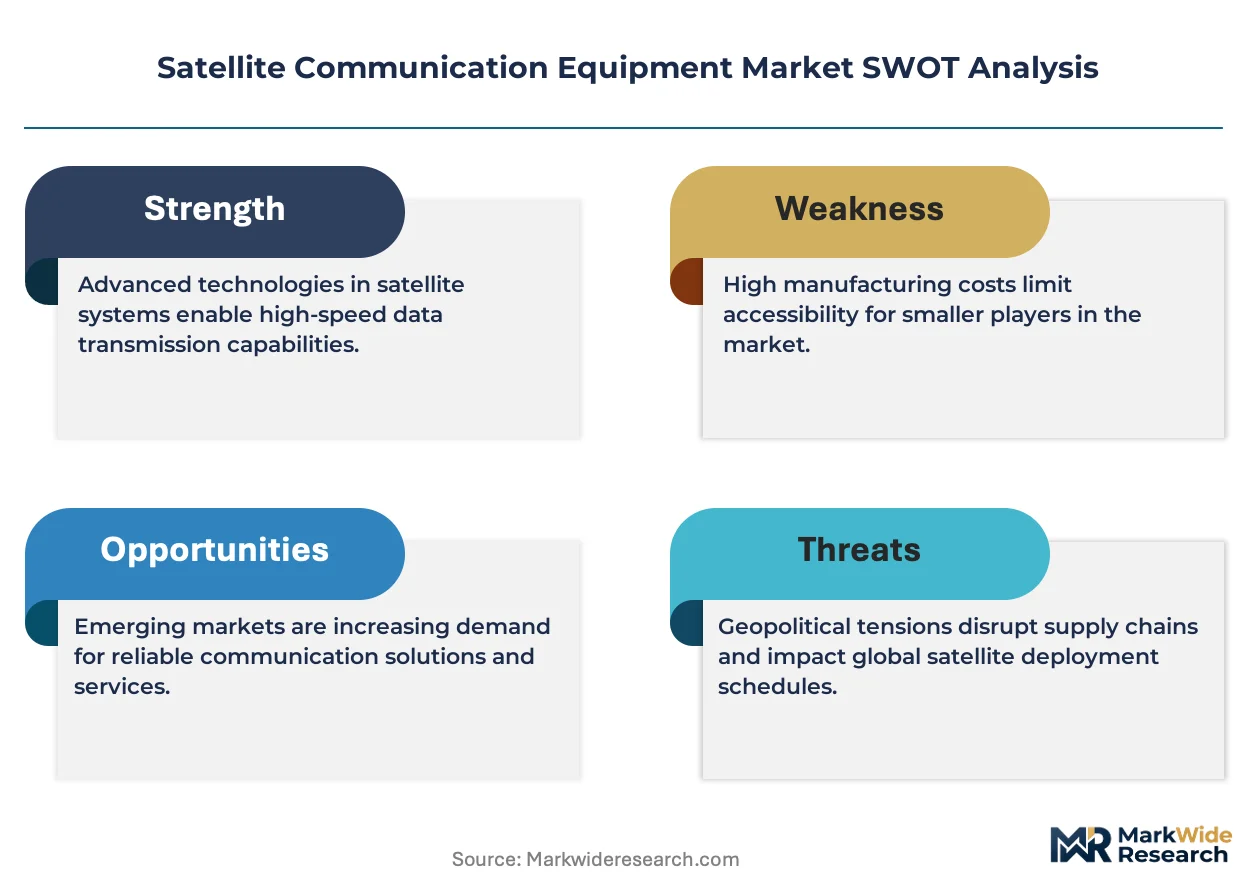
RF engineering talent is rotating from legacy broadcast infrastructure toward satellite modem and phased-array antenna design, tightening labor supply for ground station manufacturers. Starlink leverages in-house semiconductor fabrication to control terminal costs. SES anchors European orbital capacity through its mPOWER constellation program. Thales Alenia Space specializes in military-grade payload integration for sovereign satellite programs.
Satellite communication equipment encompasses ground-based and space-borne systems that modulate, amplify, transmit, and receive radio frequency signals across L-band through Ka-band frequencies, typically operating at altitudes from 300 km to 35,786 km depending on orbital regime. These systems enable bidirectional data relay for applications where terrestrial fiber or cellular infrastructure proves economically or physically impractical. Transmitters and receivers capture the majority of equipment value in broadcasting and military application segments, where redundancy requirements and radiation-hardening specifications elevate unit costs. Low Earth Orbit technology is displacing geostationary dominance in internet access applications, though geostationary platforms retain margin advantages in maritime and fixed broadcasting due to simpler antenna tracking requirements.
The FCC governs spectrum licensing and orbital debris mitigation standards for U.S.-based operators, while the EU's Radio Equipment Directive and IRIS² constellation funding framework shape European procurement criteria. ITU coordination procedures for frequency allocation increasingly determine market access timelines for new constellation entrants. Stakeholders must monitor national security-driven supply chain restrictions on semiconductor components and satellite payload sourcing as these rules reshape vendor qualification requirements.
Market Dynamics
Low Earth Orbit constellation deployment is compressing equipment refresh cycles as military and commercial buyers demand flat-panel phased-array terminals capable of tracking multiple satellites simultaneously. This orbital shift rewrites procurement specifications across defense, maritime, and aviation verticals.
Growth Catalysts
- Defense procurement acceleration:NATO-aligned militaries are mandating multi-orbit resilience in satellite communications, requiring redundant ground terminals and radiation-hardened payloads for contested environments.
- FCC spectrum reallocation:Updated rules for non-geostationary orbit systems are opening competitive access windows for new constellation entrants, expanding addressable equipment demand.
- Ka-band adoption:Higher frequency operation enables greater throughput per transponder, driving ground station and terminal replacement cycles among enterprise and government users.
Market Restraints
- Semiconductor supply concentration:Gallium nitride and silicon germanium foundry capacity clusters in East Asia, creating single-source vulnerability for high-power amplifier modules.
- ITU coordination timelines:Frequency allocation procedures extend market entry timelines by 24-48 months for new constellation operators, freezing equipment pre-orders.
- Optical fiber substitution:Submarine cable deployments across the Atlantic and Pacific are capturing fixed terrestrial traffic that previously relied on satellite backhaul.
Strategic Opportunities
- African connectivity gaps:Terrestrial infrastructure deficits in the Sahel and Central Africa create addressable demand for low-cost satellite terminals and community ground stations.
- EU IRIS² constellation funding:The European Union's sovereign satellite program mandates European-sourced payload and ground equipment, redirecting procurement toward qualified regional vendors.
- LEO-GEO convergence:Multi-orbit terminals combining electronically steered arrays with parabolic backup are opening unified equipment platforms for maritime and aviation integrators.
Industry Challenges
- RF engineering scarcity:Specialized talent for phased-array antenna design and satellite modem architecture is rotating toward LEO constellation operators, starving legacy GEO ground station manufacturers.
- Debris mitigation compliance:FCC and ITU end-of-life disposal mandates require propulsion system integration on small satellites, complicating payload-equipment interfaces and qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communication Equipment Market |
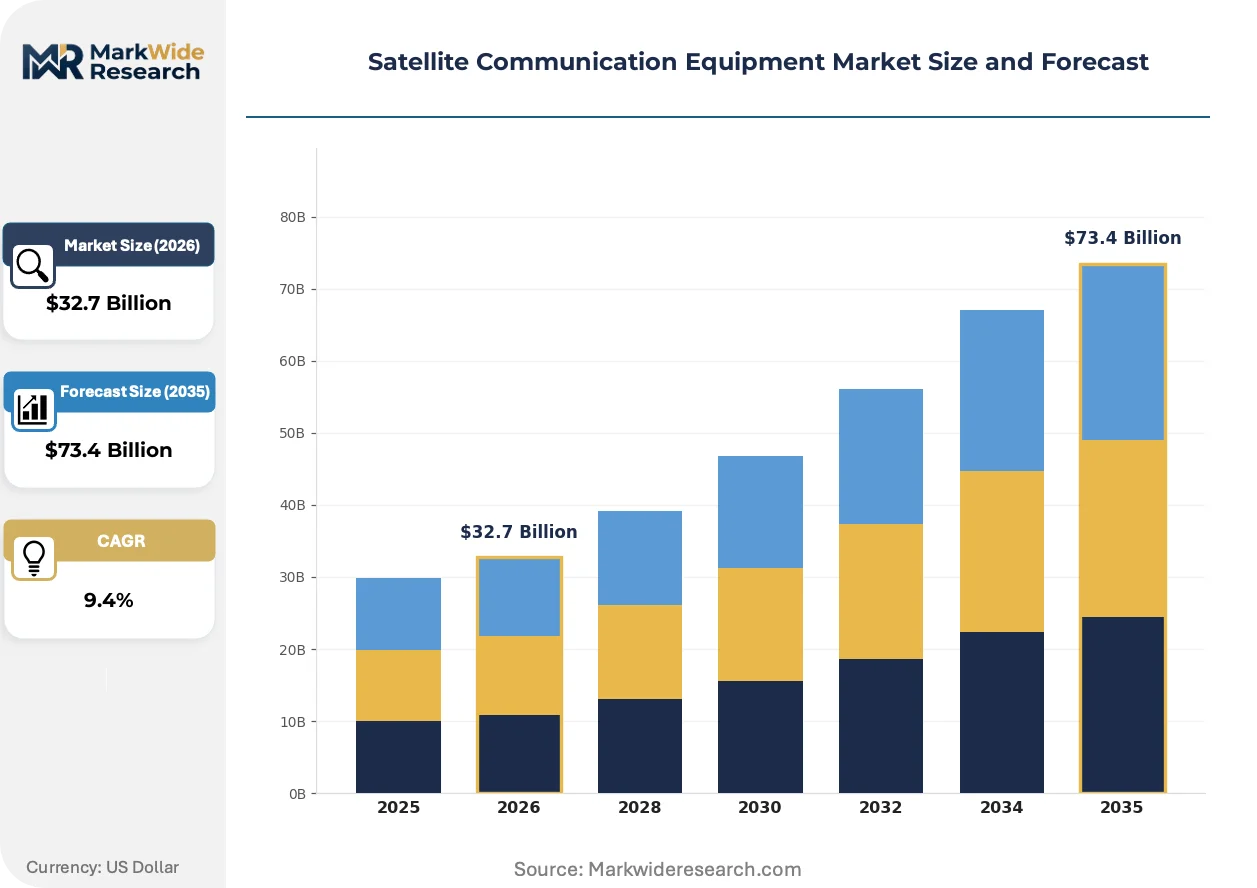
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $73.4 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitters, Receivers, Antennas, Modems Application: Broadcasting, Internet Access, Military, Maritime Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Non-Geostationary End User: Aerospace, Government, Commercial, Educational |
| Companies Covered | Starlink, SES, Viasat Inc., Thales Alenia Space, Lockheed Martin, Intelsat, Globalstar Inc, Airbus Defence and Space, Telesat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communication Equipment Market Strategic Shifts
Terminal architecture is converging around software-defined radios and electronically steered arrays, collapsing the distinction between consumer, enterprise, and military form factors. Equipment vendors are reconfiguring product lines around modular building blocks rather than purpose-built platforms.
Silicon-based beamforming integrated circuits are miniaturizing phased-array antenna elements from military-exclusive systems into mass-market consumer terminals. Starlink's in-house semiconductor fabrication has demonstrated sub-$500 terminal cost structures, forcing incumbent suppliers to abandon gallium arsenide designs. The structural consequence is collapsing margin tiers between commercial and defense-grade equipment categories.
REACH substance restrictions and EU Green Deal circularity mandates are forcing equipment redesigns to eliminate hexavalent chromium in thermal coatings and lead in solder joints. European ground station manufacturers face 18-month requalification cycles for modified thermal management systems. Military payload integrators serving NATO programs are most affected, as dual-use equipment must satisfy both environmental and operational specifications simultaneously.
Buying organizations are consolidating vendor relationships around integrated ground-space service contracts rather than discrete equipment purchases. Maritime operators now lease terminal capacity with guaranteed uptime rather than owning depreciating hardware. This pattern is most visible among Greek and Singaporean shipping fleets, where operating lease structures now dominate new fleet deployments and retrofits.
Satellite Communication Equipment Market Segmentation
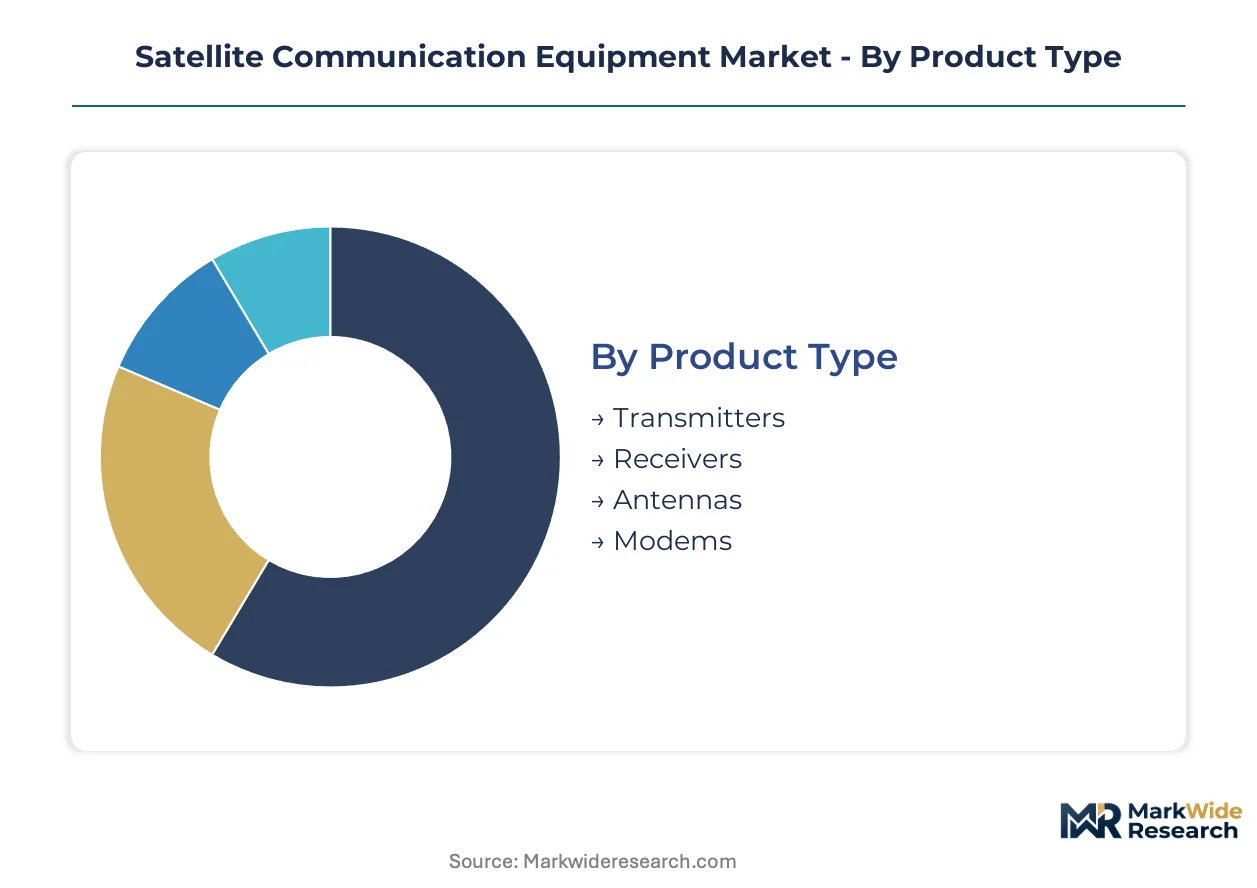
Equipment specifications diverge sharply across orbital regimes and end-use security classifications. Procurement channels route through defense integrators, maritime leasing platforms, and direct-to-consumer retail depending on segment technical complexity.
Product Type:
Transmitters and receivers flow primarily through defense procurement channels with multi-year qualification cycles, while antennas and modems reach commercial markets via distributor networks and direct manufacturer sales.
- Transmitters:High-power amplifier modules generating RF output across L-band through Ka-band frequencies, with gallium nitride and silicon germanium semiconductor architectures. Pentagon satellite service contracts and NATO-aligned military programs concentrate demand for radiation-hardened variants with redundant thermal management.
- Receivers:Low-noise block downconverters and demodulation subsystems capturing satellite signals for signal processing chains. Maritime operators in Greek and Singaporean shipping fleets drive replacement demand through operating lease structures that bundle receiver hardware with guaranteed uptime service level agreements.
- Antennas:Parabolic reflector and phased-array configurations for signal acquisition and tracking.
- Modems:Baseband processing units handling modulation, coding, and protocol conversion for satellite links.
Transmitters dominate installed base value through military redundancy requirements. Receivers are where expansion concentrates as maritime leasing models proliferate.
Application:
Cost tiers separate purpose-built military systems from mass-market consumer terminals, with enterprise and maritime segments occupying intermediate price-performance positions.
- Broadcasting:Geostationary-dependent content distribution infrastructure for direct-to-home television and radio programming. SES anchors European orbital capacity through its mPOWER constellation program, sustaining demand for high-reliability transponder chains in fixed broadcasting applications where simpler antenna tracking requirements preserve margin advantages.
- Internet Access:Consumer and enterprise broadband connectivity via satellite constellations. Starlink's constellation deployments in the United States compress equipment refresh cycles as flat-panel phased-array terminals displace legacy parabolic installations.
- Military:Secure tactical communications and strategic command-and-control networks.
- Maritime:Shipboard connectivity for commercial shipping and naval vessels.
Broadcasting retains the largest installed base of geostationary-linked equipment. Internet access is climbing the fastest as LEO constellation deployment accelerates terminal replacement cycles.
Technology:
Supply concentration for beamforming integrated circuits and phased-array components favors vertically integrated constellation operators over independent equipment vendors.
- Geostationary:Synchronous orbit at 35,786 km altitude with fixed earth-pointing coverage footprints. Maritime and fixed broadcasting applications sustain procurement as simpler antenna tracking requirements reduce terminal complexity and maintenance burden.
- Low Earth Orbit:Constellation architectures operating at 300-2,000 km altitudes with reduced latency. FCC's updated spectrum allocation rules for non-geostationary orbit systems are opening competitive access windows for new constellation entrants, expanding addressable equipment demand for multi-orbit-capable terminals.
- Medium Earth Orbit:Intermediate altitude regimes balancing coverage and latency performance.
- Non-Geostationary:Umbrella category encompassing all non-synchronous orbital configurations including inclined and polar orbits.
Geostationary technology dominates current installed base. Low Earth Orbit is where expansion concentrates as electronically steered arrays miniaturize from military-exclusive systems into mass-market consumer terminals.
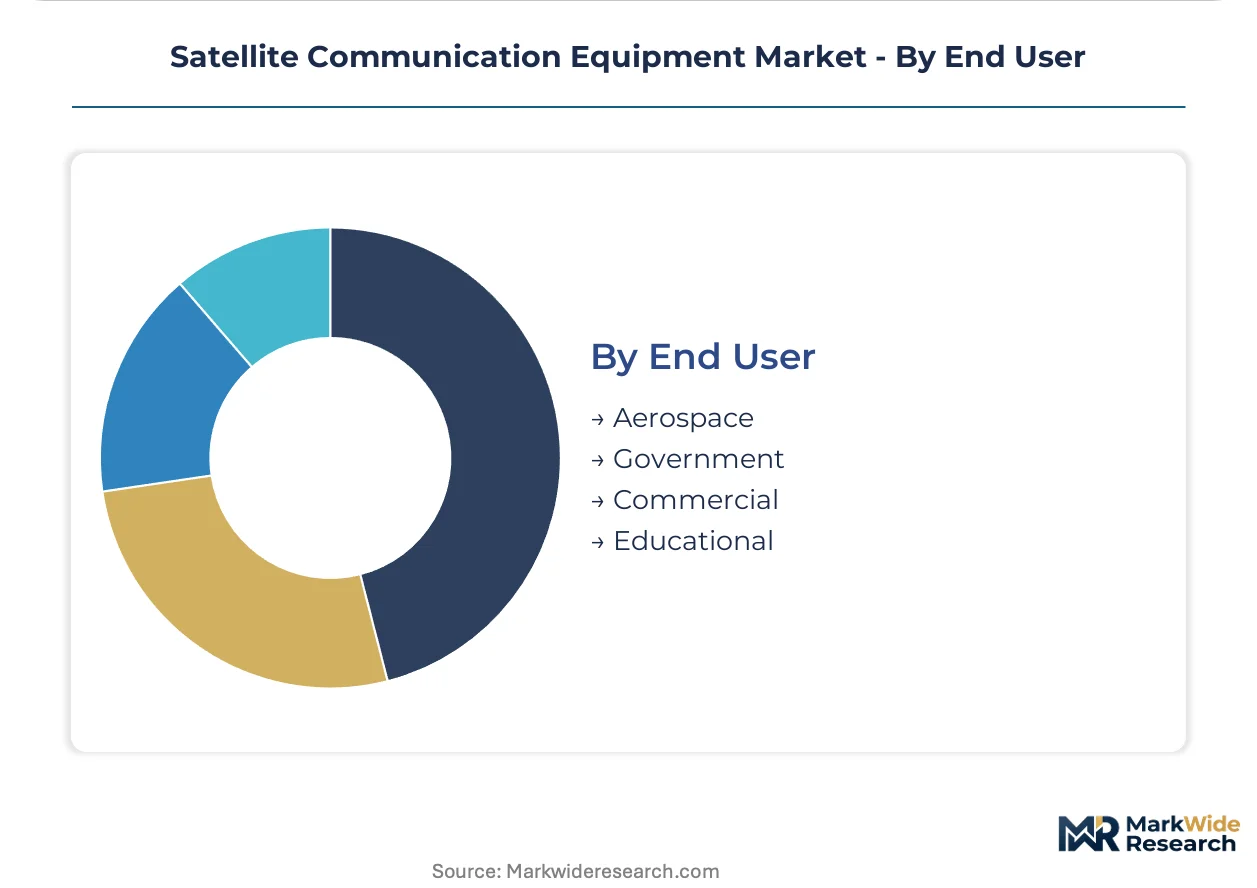
End User:
Customer type determines qualification burden, with aerospace and government segments requiring extended certification cycles that commercial and educational buyers bypass.
- Aerospace:Satellite operators and launch service providers procuring space-borne and ground station equipment. Thales Alenia Space specializes in military-grade payload integration for sovereign satellite programs, serving this segment with dual-use equipment satisfying both environmental and operational specifications.
- Government:Civil agencies and defense departments acquiring secure communications infrastructure. African connectivity gaps in the Sahel and Central Africa create addressable demand for low-cost satellite terminals and community ground stations funded through development finance mechanisms.
- Commercial:Enterprise and consumer markets for broadband, media, and IoT connectivity.
- Educational:Research institutions and university programs for space science and communications engineering.
Government end users dominate value concentration through sovereign satellite program procurement. Commercial segments are gaining share fastest as equipment-as-a-service models reduce capital barriers for enterprise adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply across geographies, with NATO-aligned militaries driving multi-orbit terminal demand while emerging economies prioritize low-cost community ground stations over sovereign satellite programs.
United States
Pentagon satellite service contracts and Starlink constellation deployments concentrate demand for flat-panel phased-array terminals. The FCC governs spectrum licensing and orbital debris mitigation standards for U.S.-based operators. California hosts the densest cluster of terminal manufacturers and semiconductor fabricators serving both commercial and defense procurement channels.
United Kingdom
Airbus Defence and Space anchors sovereign satellite manufacturing capacity through military-grade payload integration programs. The UK Space Agency coordinates national space policy and procurement frameworks for dual-use equipment. Harwell Campus in Oxfordshire concentrates satellite technology R&D facilities serving NATO and commercial constellation operators.
Germany
Thales Alenia Space and regional payload integrators serve European sovereign satellite demand through the EU IRIS² constellation funding framework. REACH substance restrictions and EU Green Deal circularity mandates force 18-month requalification cycles for modified thermal management systems. Munich and Stuttgart host the primary clusters of ground station manufacturers adapting to multi-orbit terminal specifications.
France
Thales Alenia Space specializes in military-grade payload integration for sovereign satellite programs serving government end users. The national space agency CNES coordinates frequency allocation procedures with ITU for French constellation operators. Toulouse anchors European orbital capacity development through integrated satellite manufacturing and test facilities.
Japan
METI drives national space industrial policy supporting domestic satellite equipment manufacturers competing in regional maritime connectivity markets. JIS standards govern equipment qualification for government and commercial procurement. Tokyo-Yokohama corridor concentrates RF engineering talent and satellite modem architecture development for phased-array systems.
Satellite Communication Equipment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with vertically integrated constellation operators controlling terminal cost structures through captive semiconductor fabrication. The market structure separates constellation owners who bundle equipment with service contracts from independent ground station vendors serving legacy geostationary platforms. Three archetypes dominate: vertically integrated LEO operators, defense-focused payload integrators, and regional equipment specialists serving sovereign satellite programs. Competitive moves concentrate on M&A for RF engineering talent and strategic partnerships for multi-orbit terminal certification.
Among integrated constellation operators, Starlink exemplifies the vertically integrated archetype through in-house semiconductor fabrication controlling terminal economics. SES and Viasat occupy positions spanning both space-borne capacity and ground equipment distribution, representing the hybrid service-equipment model. Thales Alenia Space anchors the defense-specialist tier through military-grade payload integration for NATO-aligned sovereign programs.
| Leading Market Players |
|---|
| Starlink |
| SES |
| Viasat Inc. |
| Thales Alenia Space |
| Lockheed Martin |
| Intelsat |
| Globalstar Inc |
| Airbus Defence and Space |
| Telesat |
| Others |
Value Chain & Pricing Dynamics
FCC spectrum licensing and orbital debris mitigation standards gate both supplier qualification timelines and price differentiation across defense, maritime, and commercial buyer segments. Equipment vendors must absorb multi-year certification costs for radiation-hardened payloads while competing against vertically integrated constellation operators who bypass external procurement markups through captive semiconductor fabrication.
Pricing Analysis
Long-term offtake contracts dominate defense procurement, while spot purchases and project-based structures govern commercial maritime retrofits and enterprise broadband deployments. Three-tier pricing structure across premium, standard, and economy levels separates NATO-mandated multi-orbit terminals from mass-market consumer flat panels and low-cost African community ground stations. Cost compression in consumer terminals intensifies because Starlink's in-house fabrication has demonstrated sub-dollar thresholds that force gallium arsenide incumbents to abandon legacy designs. Government buyers exhibit lowest price sensitivity due to sovereign security requirements, while African development finance mechanisms drive highest sensitivity for basic connectivity infrastructure.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for gallium nitride and silicon germanium foundry outputs clustered in Taiwan, South Korea, and Japan. The supply chain draws from concentrated East Asian semiconductor fabrication for high-power amplifier modules, with secondary dependencies on European thermal management subsystems and North American phased-array antenna assemblies. Single-source vulnerability for GaN foundry capacity creates structural exposure to export control disruptions. Distribution runs through defense integrator channels for military programs, maritime leasing platforms for commercial shipping, and direct-to-consumer retail for broadband terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment vendors face substitution defense against vertically integrated constellation operators who bundle terminal hardware with service contracts, eroding standalone equipment margins across maritime and enterprise segments.
For Market Incumbents: Compound defensive positioning through backward integration into beamforming integrated circuit design and captive qualification of multi-orbit terminal architectures. Acquire RF engineering talent pools in Munich, Stuttgart, and Tokyo-Yokohama corridors to offset scarcity pressures from LEO constellation operators. Prioritize certification investment for FCC debris mitigation compliance to maintain defense procurement eligibility against emerging sovereign satellite programs.
For New Entrants and Emerging Players: Anchor in African connectivity gaps across the Sahel and Central Africa, where terrestrial infrastructure deficits create white-space demand for low-cost community ground stations funded through development finance mechanisms. Target EU IRIS² constellation procurement criteria by qualifying European-sourced payload components ahead of mandated vendor restrictions. Pursue maritime leasing platform partnerships as the dominant go-to-market channel bypassing capital-intensive fleet ownership models.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across consumer terminal manufacturing as silicon-based beamformers displace gallium arsenide architectures, compressing margin tiers between commercial and defense grades. Acquisition targets should exhibit dual-use equipment capabilities satisfying both REACH environmental mandates and NATO operational specifications. Watch ITU frequency allocation timeline extensions as the inflection signal for constellation operator pre-order freezes that cascade to equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-orbit Terminal Certification | FCC rule updates for non-geostationary systems open competitive access windows for qualified vendors. |
| RF Engineering Talent Acquisition | Rotation from legacy broadcast infrastructure toward satellite modem design tightens labor supply for ground station manufacturers. |
| EU IRIS² Supplier Qualification | European sovereign satellite program mandates redirect procurement toward regional payload and ground equipment vendors. |
| In-house Semiconductor Fabrication | Captive production of beamforming integrated circuits enables sub-threshold terminal cost structures against incumbent suppliers. |
| Maritime Operating Lease Expansion | Greek and Singaporean shipping fleets now dominate new deployments through guaranteed uptime service structures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs data, and constellation operator technical disclosures. Primary interviews engaged satellite equipment procurement officers at NATO defense integrators, maritime fleet operations managers, RF engineering directors at ground station manufacturers, and regulatory affairs leads navigating FCC and ITU coordination procedures. Secondary validation drew from FCC spectrum allocation dockets, EU IRIS² funding framework documentation, ITU frequency coordination records, and satellite operator technical specifications. Bottom-up equipment shipment analysis triangulates against top-down constellation deployment capacity modeling.
Segmentation dimensions modeled include orbital regime, product type, application vertical, end-user classification, and geographic procurement cluster across the analysis window. CAGRs derive from equipment replacement cycle compression tied to LEO constellation deployment rates, military procurement acceleration patterns, and maritime lease structure proliferation. Industry-specific forecast inputs incorporate phased-array terminal miniaturization curves and REACH substance restriction compliance timelines affecting thermal management system requalification.
Underlying assumptions cover sustained defense procurement prioritization of multi-orbit resilience, with deviation risk concentrated in ITU coordination timeline extensions and gallium nitride foundry export control disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Satellite Link Emulator Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Cubesat Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
North America Mobile Satellite Services Market
Satellite
China Satellite Imagery Services Market
Satellite
Global LEO Satellite Market
Satellite
Global Maritime Satellite Communication Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
LEO and GEO Satellite Market
Satellite
4K Satellite Broadcasting Market
Satellite
Middle East Satellite Communications Market