
 United Arab Emirates Satellite-Based Earth Observation Market | 2026-2036
United Arab Emirates Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Satellite-Based Earth Observation Market Insights
The UAE Space Agency's National Space Strategy is pivoting procurement toward climate-resilient infrastructure monitoring. Yahsat leverages its geostationary fleet to anchor government contracting for earth observation data services. Bayanat AI specializes in AI-driven geospatial analytics, differentiating its offering for smart city operators across the emirates. MBRSC dominates indigenous satellite manufacturing, controlling the KhalifaSat program and subsequent imaging payloads.
Satellite-based earth observation encompasses the acquisition, processing, and distribution of geospatial data from orbiting platforms carrying optical, radar, multispectral, or hyperspectral sensors, typically operating at altitudes between 400 and 36,000 kilometers with spatial resolutions ranging from sub-meter to several hundred meters. These systems generate imagery and derived analytics for terrain mapping, resource management, infrastructure surveillance, and environmental assessment across commercial and sovereign applications. Environmental Monitoring leads application demand as the UAE intensifies coastal zone and desertification tracking, while Data Analysis commands premium pricing within service types due to the complexity of transforming raw satellite feeds into decision-ready intelligence. Government end users sustain the largest procurement volumes, though Commercial Enterprises represent the fastest-expanding segment as logistics, insurance, and agriculture buyers adopt subscription-based imagery platforms.
MOHAP oversees space-related health and safety protocols for UAE astronaut programs and ground station operations, while the Telecommunications and Digital Government Regulatory Authority manages spectrum allocation for satellite downlink frequencies. The country's national space regulator coordinates with international bodies to align remote sensing activities with the UAE's obligations under the UN Remote Sensing Principles. Stakeholders must monitor how evolving spectrum licensing frameworks and data sovereignty requirements reshape competitive access to federal and municipal contracts.
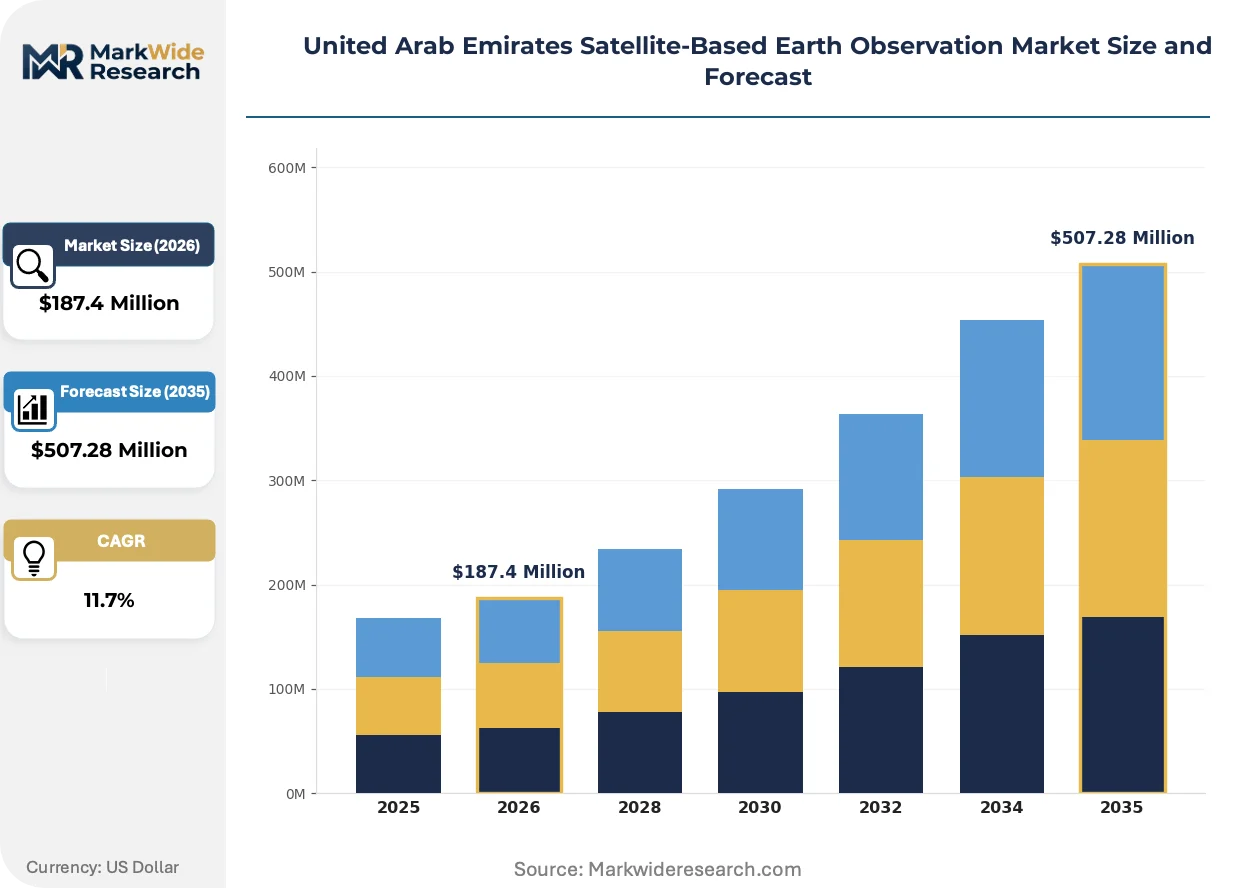
Market Dynamics
The UAE Satellite-Based Earth Observation Market is being fundamentally restructured by sovereign procurement centralization. Federal agencies are consolidating imagery acquisition through the UAE Space Agency's National Space Strategy, compressing vendor fragmentation and privileging domestic payload manufacturers with established ground station networks.
Growth Catalysts
- National Space Strategy procurement mandates:Federal requirements prioritize indigenous satellite manufacturing and data sovereignty, directing municipal budgets toward domestic payload operators.
- Synthetic aperture radar (SAR) maturation:All-weather imaging capabilities unlock year-round monitoring for coastal zone management and desertification tracking across the emirates.
- Abu Dhabi-Dubai infrastructure concentration:Smart city investments in these two emirates generate concentrated demand for high-resolution terrain mapping and construction surveillance.
Market Restraints
- Launch cost volatility:Propellant price fluctuations and limited domestic launch capacity force operators to absorb foreign pad access premiums.
- Spectrum licensing friction:Telecommunications and Digital Government Regulatory Authority frequency allocation delays compress operational timelines for new satellite deployments.
- Optical sensor substitution:High-altitude platform stations and drone-based photogrammetry capture sub-meter resolution demand in localized surveillance contracts.
Strategic Opportunities
- Ras Al Khaimah and Fujairah underpenetration:Northern and eastern emirates lack dedicated municipal mapping programs, creating first-mover openings for regional data service providers.
- AI-driven geospatial analytics convergence:Machine learning integration with hyperspectral imaging enables predictive maintenance for utilities and transportation infrastructure.
- Environmental compliance tailwinds:Federal coastal zone protection mandates require continuous satellite monitoring, generating recurring subscription revenue for persistent surveillance operators.
Industry Challenges
- Specialized workforce scarcity:Remote sensing engineering and orbital mechanics expertise remains concentrated in Dubai and Abu Dhabi, constraining expansion capacity.
- Ground station capex intensity:Ka-band downlink infrastructure and data processing centers require substantial capital deployment before revenue generation.
- Data sovereignty certification complexity:Federal cloud residency requirements for classified imagery create integration friction with international analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Satellite-Based Earth Observation Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Urban Planning, Disaster Management, Environmental Monitoring End User: Government, Research Institutions, Commercial Enterprises, NGOs Technology: Optical, Radar, Multispectral, Hyperspectral Service Type: Data Analysis, Mapping, Consulting, Monitoring |
| Companies Covered | Al Yah Satellite Communications Company PJSC (Yahsat), Bayanat AI, Airbus, Thales, ViaSat Inc., Mohammed bin Rashid Space Centre (MBRSC), Thuraya Telecommunications Company, Space42, UAE Space Agency, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Satellite-Based Earth Observation Market Trends and Innovations
Active technological and regulatory forces are compressing traditional value chains in UAE earth observation. Sovereign data requirements and edge computing maturation are redistributing analytical capabilities across the supply stack.
Small satellite constellation architectures are decentralizing the UAE's historically concentrated imaging supply. These distributed platforms enable daily revisit rates over critical infrastructure corridors. Logistics operators and agricultural insurers in Dubai are adopting subscription feeds from these networks. The shift is decentralizing procurement power from single-payload government contracts toward diversified commercial data marketplaces.
MOHAP safety protocols for ground station operations are tightening personnel certification requirements. These regulations extend deployment timelines for new receiving facilities. Operators are responding by embedding health and safety compliance into early-stage site selection, prioritizing locations with established infrastructure over greenfield developments.
Subscription-based imagery platforms are displacing traditional transactional procurement in commercial segments. Insurance underwriters and commodity traders in Abu Dhabi now demand continuous data feeds rather than episodic acquisitions. This behavioral shift is most pronounced in agricultural monitoring, where crop health analytics require temporal consistency that spot purchases cannot deliver.
United Arab Emirates Satellite-Based Earth Observation Market Segmentation
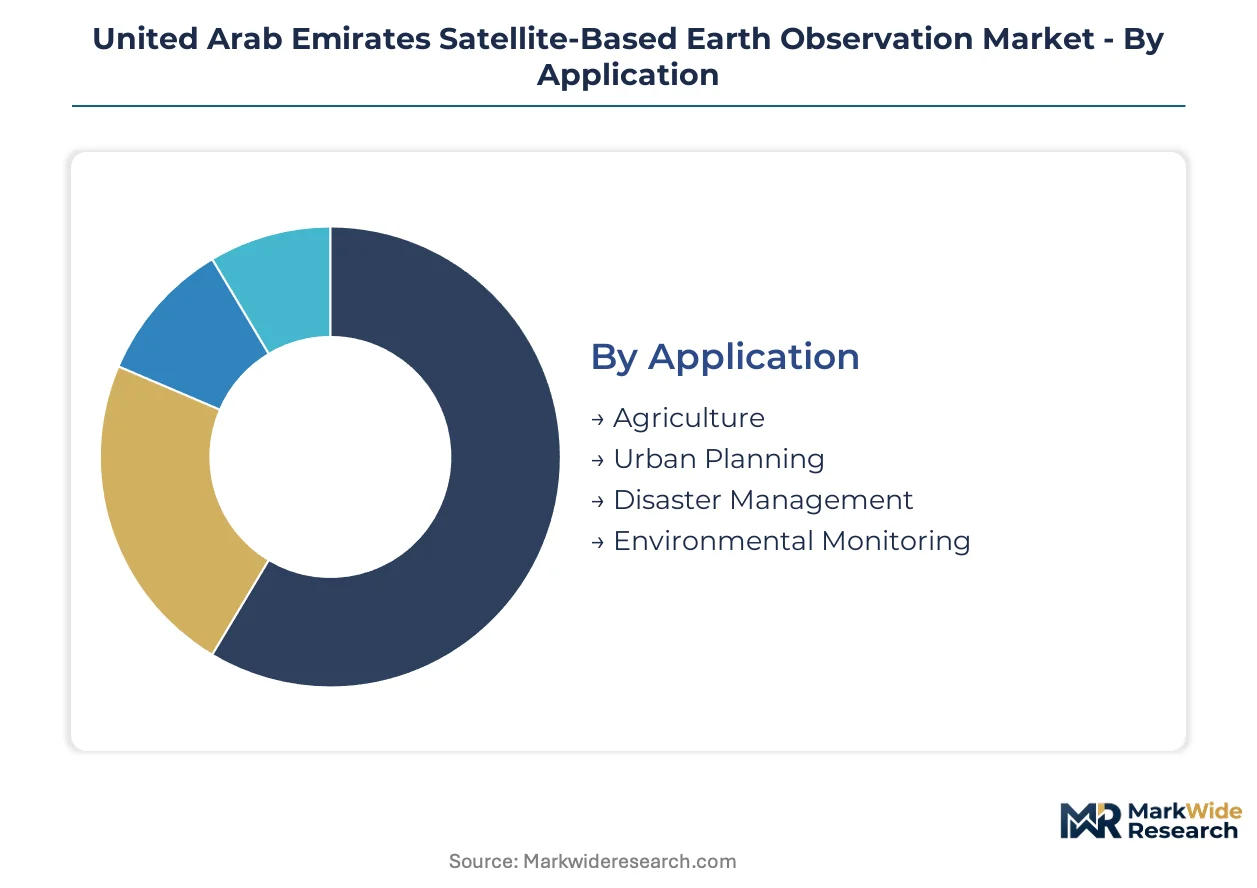
Segmentation in UAE satellite-based earth observation reveals how procurement authority, sensor technology, and service delivery models allocate revenue across sovereign and commercial buyers. Understanding these divisions exposes where federal mandates concentrate spending and where private subscription models are displacing traditional contracting.
Application:
Certification burdens vary sharply across applications, with Environmental Monitoring requiring MOHAP safety protocols for ground station operations and Disaster Management demanding Telecommunications and Digital Government Regulatory Authority spectrum licenses for emergency downlink frequencies.
- Environmental Monitoring:Coastal zone surveillance and desertification tracking utilize multispectral and SAR payloads to generate continuous coverage of maritime boundaries and inland erosion zones. Abu Dhabi and Dubai municipal governments procure these services through the UAE Space Agency's consolidated frameworks, prioritizing domestic payload operators with established ground infrastructure.
- Urban Planning:High-resolution terrain mapping supports smart city development across federal infrastructure corridors, with sub-meter optical imagery enabling construction surveillance and transportation corridor design. Dubai's municipal mapping programs concentrate demand here, compressing vendor access to established satellite operators.
- Agriculture:Crop health analytics and irrigation monitoring leverage hyperspectral signatures to assess vegetation stress and water distribution efficiency. Commercial insurers and commodity traders in Abu Dhabi are adopting subscription feeds for temporal consistency.
- Disaster Management:Rapid-response imagery acquisition for flood assessment and infrastructure damage evaluation requires all-weather SAR capabilities. Federal emergency protocols prioritize pre-negotiated data access agreements with domestic operators.
Leading the category by volume: Environmental Monitoring. Growing fastest: Urban Planning.
End User:
Cost tier stratification separates sovereign procurement from commercial subscription models, with Government buyers absorbing capital-intensive payload development while Commercial Enterprises adopt SaaS-based analytics platforms.
- Government:Federal agencies and municipal authorities dominate procurement volume through the National Space Strategy's consolidated acquisition frameworks. These buyers prioritize data sovereignty and indigenous manufacturing, directing budgets toward MBRSC and Yahsat for sovereign imaging capabilities.
- Commercial Enterprises:Logistics operators, agricultural insurers, and commodity traders represent the fastest-expanding demand segment, adopting subscription-based imagery platforms for continuous rather than episodic data access. These buyers favor AI-integrated analytics from providers like Bayanat AI.
- Research Institutions:Universities and technical centers access archived imagery through academic licensing agreements, generating lower per-transaction revenue but supporting workforce development in remote sensing engineering.
- NGOs:Environmental and humanitarian organizations operate on constrained budgets, typically accessing open-data initiatives or subsidized government imagery for conservation and relief monitoring.
Highest procurement volume sits with Government buyers. Commercial Enterprises are expanding most quickly.
Technology:
Application requirements dictate technology selection, with maritime and desert surveillance demanding all-weather radar while urban mapping prioritizes optical resolution.
- Radar:Synthetic aperture radar enables year-round imaging independent of cloud cover or solar illumination, critical for coastal zone management and desertification tracking across the emirates. SAR maturation is unlocking persistent surveillance contracts from federal environmental agencies.
- Optical:Panchromatic and multispectral sensors deliver sub-meter resolution for urban infrastructure mapping and construction surveillance. Dubai's smart city investments concentrate demand for high-resolution optical payloads.
- Multispectral:Discrete band imaging supports vegetation analysis and land-use classification, bridging agricultural monitoring and environmental assessment applications.
- Hyperspectral:Continuous spectral signature capture enables mineral identification and precise crop stress detection, commanding premium pricing in specialized commercial analytics.
Dominant by deployment volume: Radar. Steepest expansion trajectory: Hyperspectral.
Service Type:
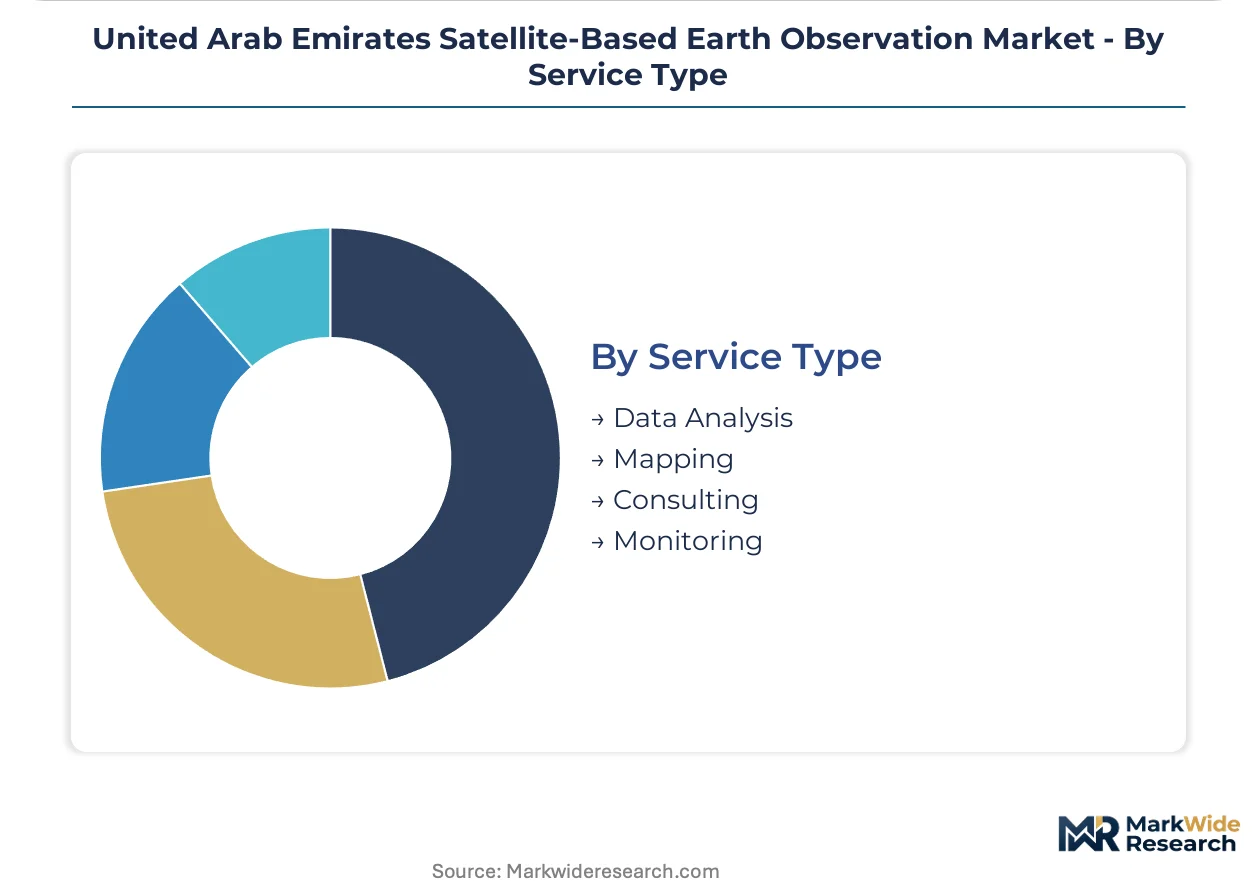
Margin structures separate raw data provision from value-added analytics, with Data Analysis capturing premium pricing for decision-ready intelligence transformation.
- Data Analysis:Machine learning integration with satellite feeds generates predictive maintenance insights and automated change detection for utilities and transportation infrastructure. Bayanat AI specializes in this segment, differentiating through AI-driven geospatial analytics.
- Mapping:Orthorectified imagery and digital elevation model production supports municipal planning and engineering design. Abu Dhabi and Dubai infrastructure programs sustain recurring demand.
- Monitoring:Subscription-based persistent surveillance services deliver continuous coverage of critical assets and environmental zones, displacing transactional procurement in commercial segments.
- Consulting:Advisory services on imagery selection, integration, and regulatory compliance address specialized requirements from international operators entering UAE federal contracting.
Premium pricing concentrates in Data Analysis. Monitoring services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE concentrates domestic satellite manufacturing in Dubai and Abu Dhabi while procuring foreign imagery services from European and American operators. Federal procurement mandates favor indigenous payload development, compressing vendor access for international providers without established ground station partnerships.
Dubai
Dubai's smart city investments generate concentrated demand for high-resolution terrain mapping and construction surveillance. The Telecommunications and Digital Government Regulatory Authority manages spectrum allocation for satellite downlink frequencies, shaping deployment timelines. Dubai hosts Bayanat AI's geospatial analytics operations and anchors commercial subscription demand from logistics and insurance buyers.
Abu Dhabi
Abu Dhabi federal agencies dominate sovereign procurement through the UAE Space Agency's National Space Strategy. The emirate prioritizes climate-resilient infrastructure monitoring and coastal zone surveillance. MBRSC controls indigenous satellite manufacturing here, directing KhalifaSat program payloads toward government imaging contracts.
Sharjah
Sharjah's research institutions access archived imagery through academic licensing agreements, supporting workforce development in remote sensing engineering. The emirate lacks dedicated municipal mapping programs, creating openings for regional data service providers. Sharjah University anchors technical training pipelines for orbital mechanics expertise.
Northern Emirates
Ras Al Khaimah and Fujairah remain underpenetrated in municipal earth observation services. Federal environmental compliance mandates for coastal zone protection extend satellite monitoring requirements to these emirates. First-mover providers are establishing ground station infrastructure to capture recurring subscription revenue from persistent surveillance contracts.
United Arab Emirates Satellite-Based Earth Observation Market Competitive Landscape
The competitive structure tilts toward sovereign-indigenous operators with established ground station networks and federal contracting relationships. Vendor fragmentation compresses around domestic payload manufacturers privileged by procurement centralization. Three archetypes dominate: state-linked satellite operators, AI-integrated analytics specialists, and international system integrators. Capacity expansion in small satellite constellations and strategic partnerships for spectrum access represent the primary competitive vectors.
Within the sovereign-indigenous tier, Al Yah Satellite Communications Company PJSC and Mohammed bin Rashid Space Centre occupy anchor positions. Bayanat AI exemplifies the analytics-specialist archetype, differentiating through machine learning integration with satellite feeds. Airbus and Thales represent international system integrators competing for federal contracts requiring foreign technology partnerships. These operators collectively illustrate how procurement centralization privileges domestic manufacturing while creating tiered access for foreign providers with compliant data sovereignty frameworks.
| Leading Market Players |
|---|
| Al Yah Satellite Communications Company PJSC (Yahsat) |
| Bayanat AI |
| Airbus |
| Thales |
| ViaSat Inc. |
| Mohammed bin Rashid Space Centre (MBRSC) |
| Thuraya Telecommunications Company |
| Space42 |
| UAE Space Agency |
| Others |
Pricing and Supply Chain Analysis
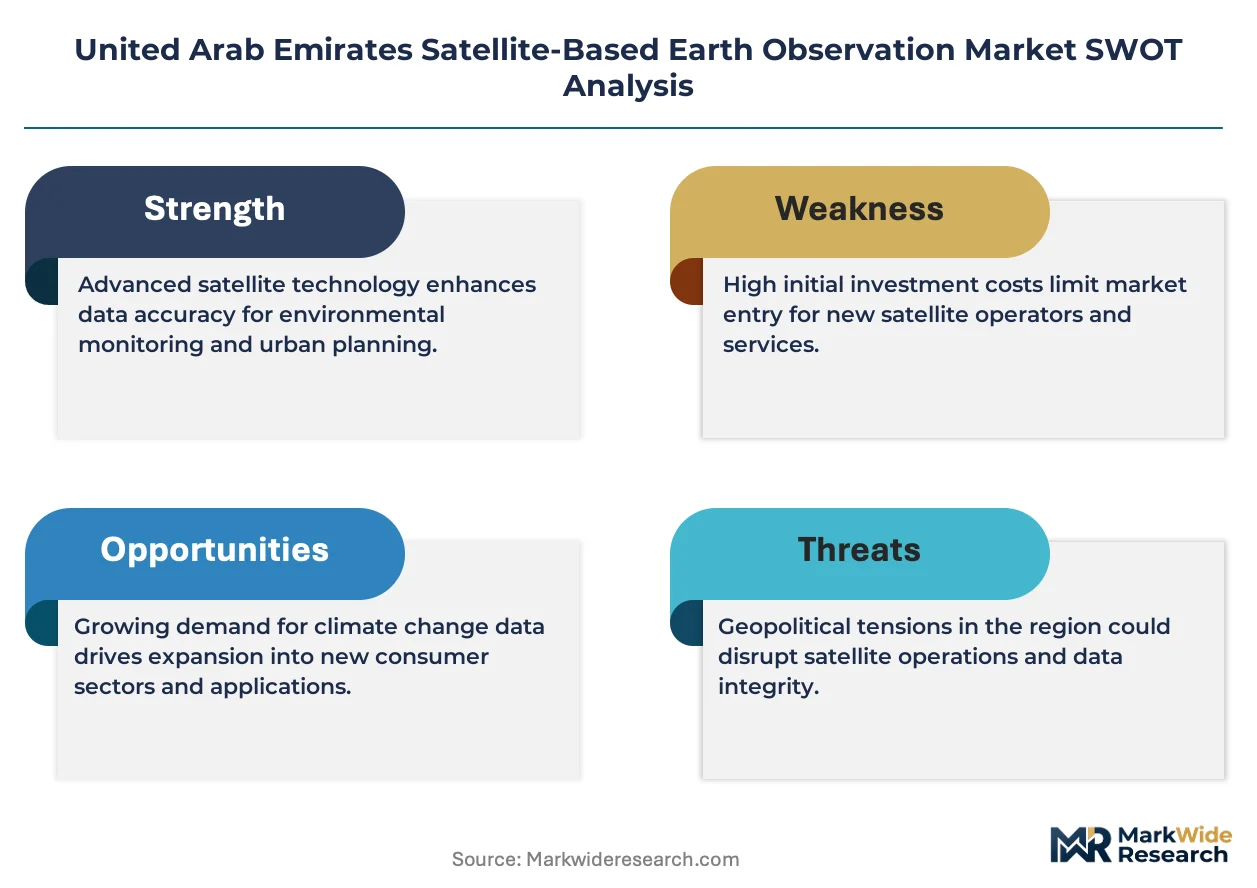
Captive ground station infrastructure anchors both supply security and pricing power for UAE satellite operators. Vertical integration into Ka-band downlink facilities and data processing centers insulates domestic providers from foreign pad access premiums while enabling subscription-based pricing models that commercial buyers now demand.
Pricing Analysis
Margin tightening in raw data provision reflects the shift toward AI-integrated analytics as the value capture point. Three-tier pricing structure across premium hyperspectral, standard multispectral, and economy radar tiers separates government buyers with sovereign procurement mandates from commercial enterprises adopting SaaS platforms. Price differentiation traces to certification grade for federal cloud residency and volume scale for municipal mapping contracts. Commercial insurers in Abu Dhabi exhibit highest price sensitivity, while federal agencies absorb premium pricing for indigenous manufacturing compliance.
Supply Chain Analysis
Domestic-content mandates under the UAE Space Agency's National Space Strategy are reshaping sourcing toward indigenous payload manufacturers. Satellite bus components draw from South Korea, Japan, and the United States, while sensor arrays and optical assemblies rest on German and French suppliers. Single-source vulnerability concentrates in synthetic aperture radar subsystems from European defense integrators. Distribution runs through federal procurement frameworks that privilege MBRSC and Yahsat with established ground station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where ground station infrastructure and AI analytics capabilities determine competitive position. Players are pursuing downstream control over subscription-based data platforms to capture recurring revenue from commercial buyers.
For Market Incumbents: Acquire hyperspectral imaging startups to close the technology gap with international specialists. Consolidate ground station assets across northern emirates before first-movers establish regional presence. Drone-based photogrammetry substitution threatens localized surveillance contracts, requiring certification investment in MOHAP safety protocols to defend federal market access.
For New Entrants and Emerging Players: Cloud-native analytics platforms offer the lowest-friction entry path into UAE federal contracting. White-space opportunities concentrate in Ras Al Khaimah and Fujairah municipal mapping programs, where environmental compliance mandates outpace infrastructure deployment. Target agricultural insurers with subscription crop health monitoring to bypass sovereign procurement barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in sovereign-indigenous operators with established Telecommunications and Digital Government Regulatory Authority spectrum licenses. Long-term viability hinges on data sovereignty certification and persistent surveillance contract renewals. Watch for AI-driven geospatial analytics convergence as the inflection signal for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Ground Station Network Expansion | Captures recurring subscription revenue from federal environmental monitoring mandates across coastal zones. |
| AI Analytics Platform Integration | Enables Bayanat AI-style differentiation for smart city operators demanding predictive maintenance insights. |
| SAR Payload Manufacturing Scale-Up | Reduces dependency on European defense suppliers for all-weather imaging capabilities. |
| Spectrum Licensing Pre-Positioning | Accelerates deployment timelines by securing Telecommunications and Digital Government Regulatory Authority approvals early. |
| Regional Data Service Partnership | Opens first-mover access to underpenetrated northern emirates before federal procurement centralization completes. |
Research Methodology
UAE Space Agency procurement disclosures, Telecommunications and Digital Government Regulatory Authority spectrum allocation records, and MBRSC technical documentation formed the secondary backbone. Primary interviews with satellite program directors, ground station operations managers, and municipal mapping procurement officers combined with customs data on sensor component imports. Bottom-up triangulation across subscription revenue models and top-down validation against federal budget allocations anchored the analytical framework.
Historical trendline analysis of National Space Strategy procurement volumes established baseline trajectories across the projection horizon. Segmentation dimensions modeled include application type, end-user archetype, sensor technology, and service delivery model, with domestic-content share as an industry-specific overlay. CAGRs derived from fitted growth curves adjusted for sovereign procurement cycle timing and commercial subscription adoption rates. Forecast inputs incorporated SAR technology maturation curves and AI analytics penetration assumptions.
The model holds under stable federal procurement centralization and spectrum licensing continuity; deviation in launch cost volatility or international data sovereignty disputes would shift trajectory bounds. Forecasts reflect documented assumptions on small satellite constellation deployment timelines and municipal budget allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
Satellite Communications Service Market
Satellite
Global LEO Satellite Market
Satellite
Global Satellite Modem Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Satellite GPS Receivers Market
Satellite
North America Satellite IoT Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
North America Satellite Manufacturing Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Europe Satellite IoT Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Satellite Antenna Market
Satellite
Global Satellite Propulsion System Market
Satellite
US Satellite Connectivity Market