
 Remote Sensing Satellite Market | 2026-2036
Remote Sensing Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Sensing Satellite Market Outlook
Multi-source payload procurement is broadening across government and commercial operators. Maxar Technologies leverages its high-resolution electro-optical constellation to anchor defense and intelligence contracts in North America. Airbus Defence and Space competes through dual-use manufacturing scale, sustaining European institutional demand while extending commercial Earth observation services. Planet Labs operates the largest commercial CubeSat fleet, differentiating through daily global coverage frequency that traditional geostationary platforms cannot match.
Remote sensing satellites are spacecraft equipped with sensors that detect and measure electromagnetic radiation reflected or emitted from Earth's surface, typically operating in orbital altitudes between 400 and 700 kilometers with revisit cycles ranging from hours to days depending on sensor type and orbital configuration. Their primary commercial purpose is to generate actionable geospatial intelligence for resource management, security operations, and environmental monitoring without requiring physical ground presence. Earth observation payloads command the largest revenue share within product type segmentation, while hyper-spectral technology is expanding fastest as mineral exploration and precision agriculture buyers demand narrower spectral bands for material identification. Government end users currently dominate procurement volume, though agriculture is emerging as the highest-margin growth vertical as farm operators shift from subsidized public imagery to paid subscription models for sub-meter resolution data.
The U.S. Federal Communications Commission regulates spectrum allocation for satellite downlink operations, while NOAA licenses private Earth observation systems under the Land Remote Sensing Policy Act, creating compliance thresholds that shape market entry for new constellation operators. The EU Space Programme and its associated security regulations mandate European data sovereignty, directing institutional procurement toward Airbus and Thales Alenia Space for sensitive government applications. Stakeholders must monitor evolving orbital debris mitigation standards from the FCC and emerging national space laws across Asia-Pacific markets, as these frameworks will determine which operators can secure launch licenses and frequency coordination for next-generation synthetic aperture radar constellations.
Market Dynamics
Synthetic aperture radar payloads are compressing revisit cycles below six hours for commercial operators, forcing electro-optical incumbents to defend resolution advantages against all-weather competitors.
Growth Catalysts
- Copernicus expansion mandates:EU Space Programme regulations require member states to procure sovereign Earth observation capacity, directing institutional budgets toward domestic manufacturers.
- Variable-rate agriculture:Midwestern US growers now subscribe to sub-meter imagery for input management, converting public data dependence into paid commercial relationships.
- Water stress monitoring:Indian state governments deploy satellite-based crop surveillance to allocate irrigation subsidies and detect drought stress in agricultural districts.
Market Restraints
- Launch capacity bottlenecks:Heavy-lift vehicle availability constrains constellation deployment schedules, with rideshare manifests booking eighteen months forward.
- Spectrum coordination complexity:FCC and ITU filing requirements create eighteen-to-twenty-four-month licensing timelines that delay revenue generation for new operators.
- Ground segment capital intensity:Downlink station networks require fifteen-million-dollar minimum investments per polar and mid-latitude site for global coverage.
Strategic Opportunities
- Carbon credit verification:Forest monitoring and methane leak detection create new revenue streams as compliance markets expand voluntary offset verification demand.
- Hyperspectral mineral mapping:Narrow spectral band sensors enable direct ore body identification for exploration teams in undermapped jurisdictions.
- Defense-as-a-service models:NATO allies and Five Eyes partners seek commercial synthetic aperture radar tasking without dedicated national constellation ownership.
Industry Challenges
- Orbital debris mitigation compliance:FCC and emerging national space laws mandate post-mission disposal and collision avoidance systems that add engineering cost and mass penalties.
- Frequency interference adjudication:C-band and X-band congestion between civil, military, and commercial operators requires complex ITU coordination procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Sensing Satellite Market |
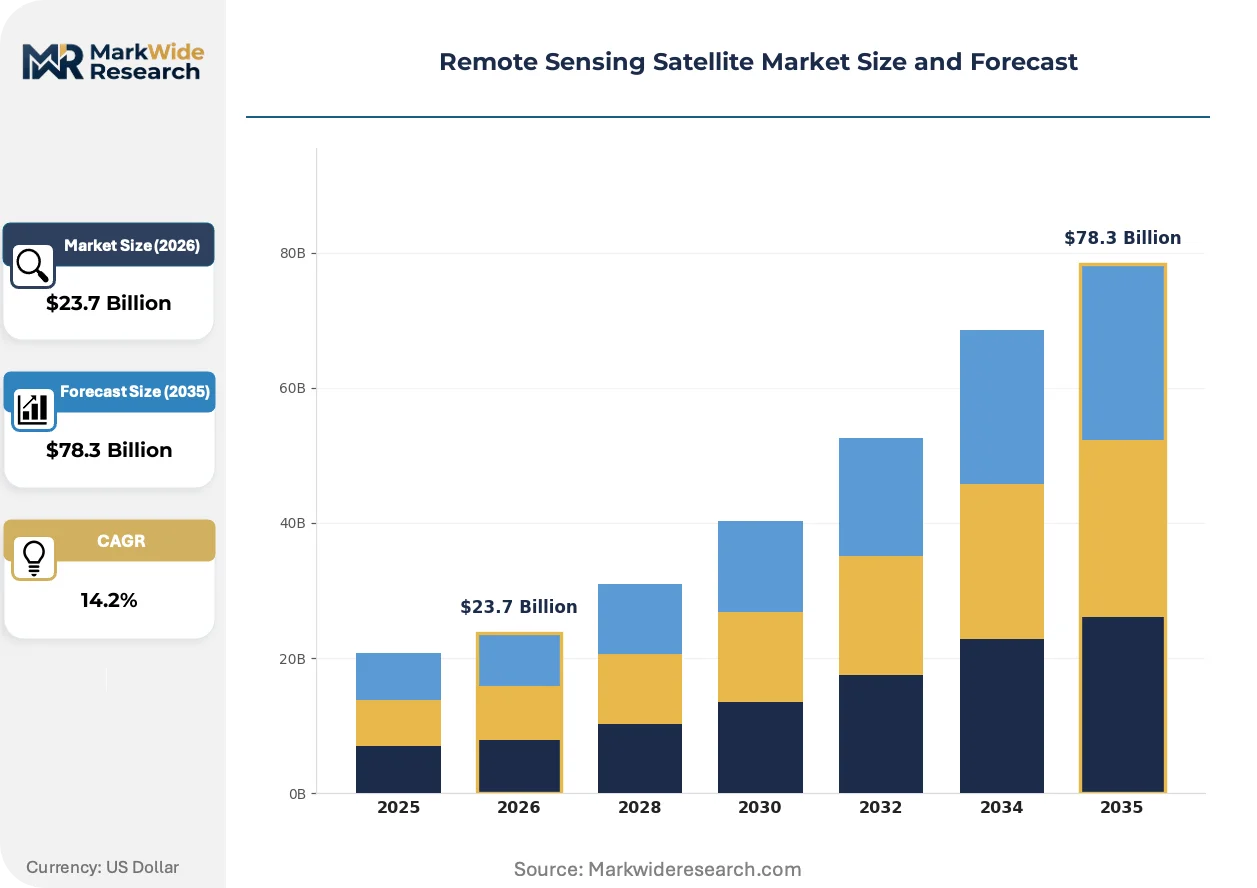
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earth Observation, Communication, Weather Monitoring, Reconnaissance End User: Aerospace, Government, Environmental Agencies, Agriculture Technology: Active Radar, Passive Microwave, Multi-Spectral, Hyper-Spectral Application: Disaster Management, Urban Planning, Climate Research, Land Use |
| Companies Covered | SpaceX, Maxar Technologies, Airbus Defence and Space, Lockheed Martin, Northrop Grumman, Planet Labs, Thales Alenia Space, Boeing, L3 Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Sensing Satellite Market Strategic Shifts
Satellite miniaturization and software-defined payloads are collapsing the traditional trade-off between spatial resolution and temporal coverage, enabling business models that were technically infeasible five years ago.
Synthetic aperture radar is overtaking electro-optical dominance in commercial Earth observation. SAR payloads penetrate cloud cover and darkness, delivering all-weather intelligence. Agricultural insurers and maritime surveillance operators now specify SAR as primary procurement. This capability is compressing the addressable market for optical-only constellations.
EU AI Act and CSRD disclosure requirements are mandating geospatial audit trails for environmental claims. Corporations must verify supply chain deforestation and emissions data. Satellite imagery providers are positioning as compliance infrastructure. European industrial and consumer goods sectors represent the initial demand concentration.
Subscription-based tasking APIs are replacing traditional imagery catalog purchases. Farm management software platforms and commodity traders now integrate direct satellite feeds through standardized interfaces. This disintermediation bypasses traditional value-added resellers. The transformation is most advanced in North American precision agriculture and commodity finance verticals.
Remote Sensing Satellite Market Segmentation
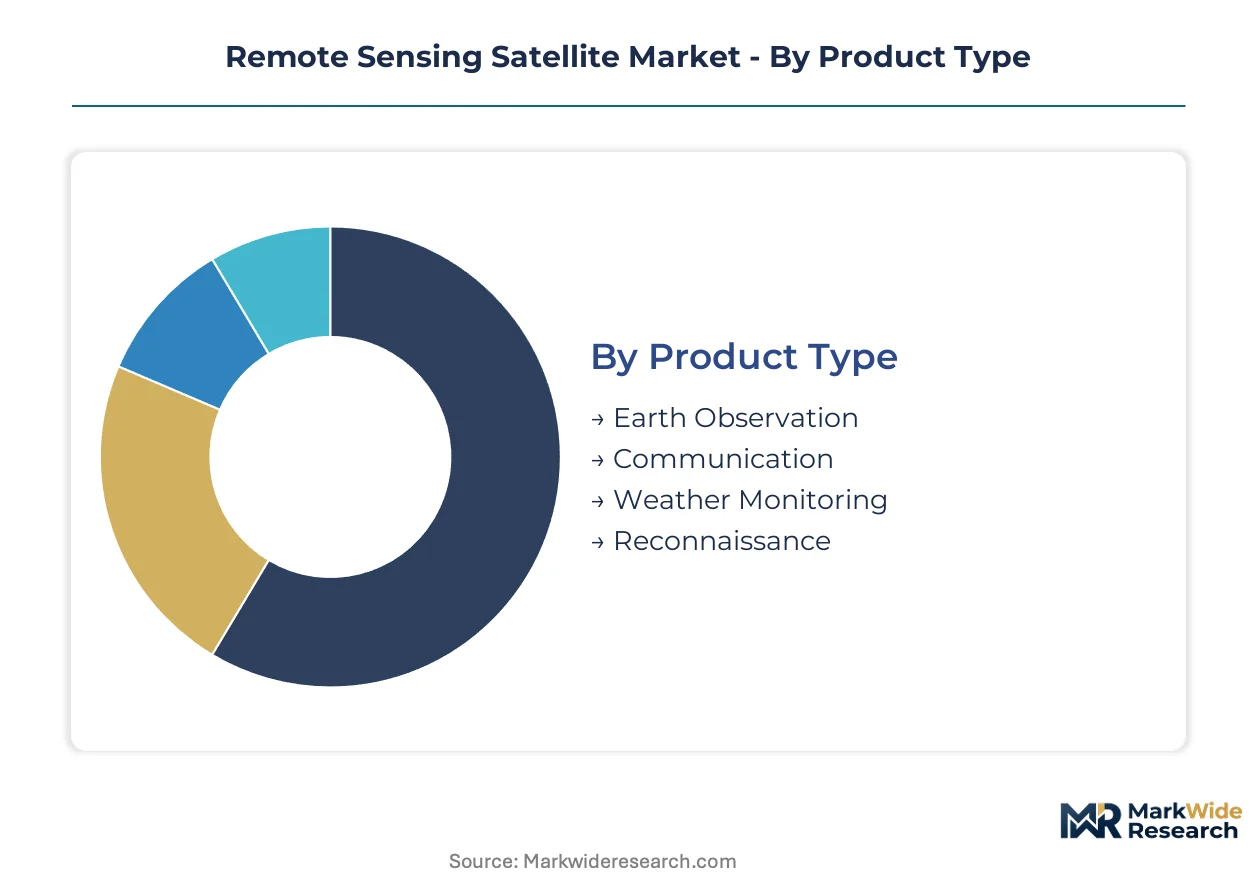
Remote sensing satellite procurement varies dramatically by payload complexity and operational requirements. Capital allocation decisions across product types, end users, and sensing technologies determine which operators capture institutional budgets versus commercial subscriptions.
Product Type:
Earth observation payloads demand the heaviest upfront investment in precision optics and stabilization systems, while reconnaissance platforms require hardened components for classified missions.
- Earth Observation:Electro-optical and synthetic aperture radar sensors capture terrain, vegetation, and infrastructure data at sub-meter resolution. State governments in India deploy these platforms for agricultural subsidy verification, converting raw imagery into administrative decisions. Most installed capacity flows through Earth Observation. Expansion is steepest in Reconnaissance.
- Communication:Data relay satellites bridge the gap between low-Earth-orbit sensors and ground stations, enabling real-time tasking and download. Maritime surveillance operators in the Mediterranean basin rely on these links for continuous vessel tracking without terrestrial coverage gaps.
- Weather Monitoring:Geostationary and polar-orbiting meteorological payloads carry radiometers and sounders for atmospheric profiling. National meteorological services in Japan and South Korea operate dedicated constellations for typhoon forecasting and aviation routing.
- Reconnaissance:Signals intelligence and high-resolution imaging platforms serve defense and intelligence communities with enhanced encryption and maneuverability. NATO members are procuring commercial synthetic aperture radar tasking through service models rather than owning dedicated assets.
Earth observation commands the largest share of deployed mass and launch frequency. Reconnaissance contracts carry the highest per-kilogram pricing due to security requirements.
End User:
Government agencies anchor procurement volume through multi-year constellation programs, while agriculture buyers are shifting fastest from subsidized public data to paid commercial subscriptions.
- Government:Defense, intelligence, and civilian agencies fund sovereign capacity through classified and unclassified budget lines. The EU Space Programme mandates member-state procurement from domestic manufacturers, directing institutional spending toward Airbus and Thales Alenia Space.
- Agriculture:Farm operators and cooperatives subscribe to sub-meter imagery for variable-rate input management. Midwestern United States growers now pay for commercial data rather than relying on free USDA CropScape products, creating recurring revenue pools.
- Environmental Agencies:Forestry departments and climate monitoring bodies track deforestation, wetland loss, and carbon stock changes. Brazil's space agency INPE operates a dedicated Amazon monitoring constellation to detect illegal clearing in near-real-time.
- Aerospace:Satellite operators and launch providers purchase remote sensing data for orbital debris tracking and conjunction assessment. Commercial space situational awareness services integrate radar and optical observations for collision avoidance.
Government budgets dominate absolute spending. Agriculture subscriptions are climbing fastest as precision farming software platforms embed imagery APIs.
Technology:
Active sensing modalities require onboard power generation and processing hardware, while passive systems trade energy efficiency for weather dependency.
- Active Radar:Synthetic aperture radar transmits microwave pulses and processes return signals to build terrain maps through cloud cover and darkness. Maritime insurers in the North Sea specify SAR for ice floe detection during winter navigation seasons.
- Hyper-Spectral:Narrow-band sensors capture hundreds of spectral channels for material identification and mineral mapping. Exploration teams in undermapped jurisdictions use these payloads to detect alteration zones associated with ore deposits.
- Multi-Spectral:Broad-band visible and near-infrared sensors support vegetation index calculation and land cover classification. Commercial agriculture platforms standardize on four-to-eight-band configurations for crop health monitoring.
- Passive Microwave:Radiometers measure naturally emitted radiation for soil moisture and sea surface temperature retrieval. Hydrological agencies in the Nile basin integrate these observations into flood forecasting models.
Multi-spectral systems account for the majority of operational spacecraft. Hyper-spectral adoption is expanding most quickly as mining and precision agriculture buyers demand material-specific detection.
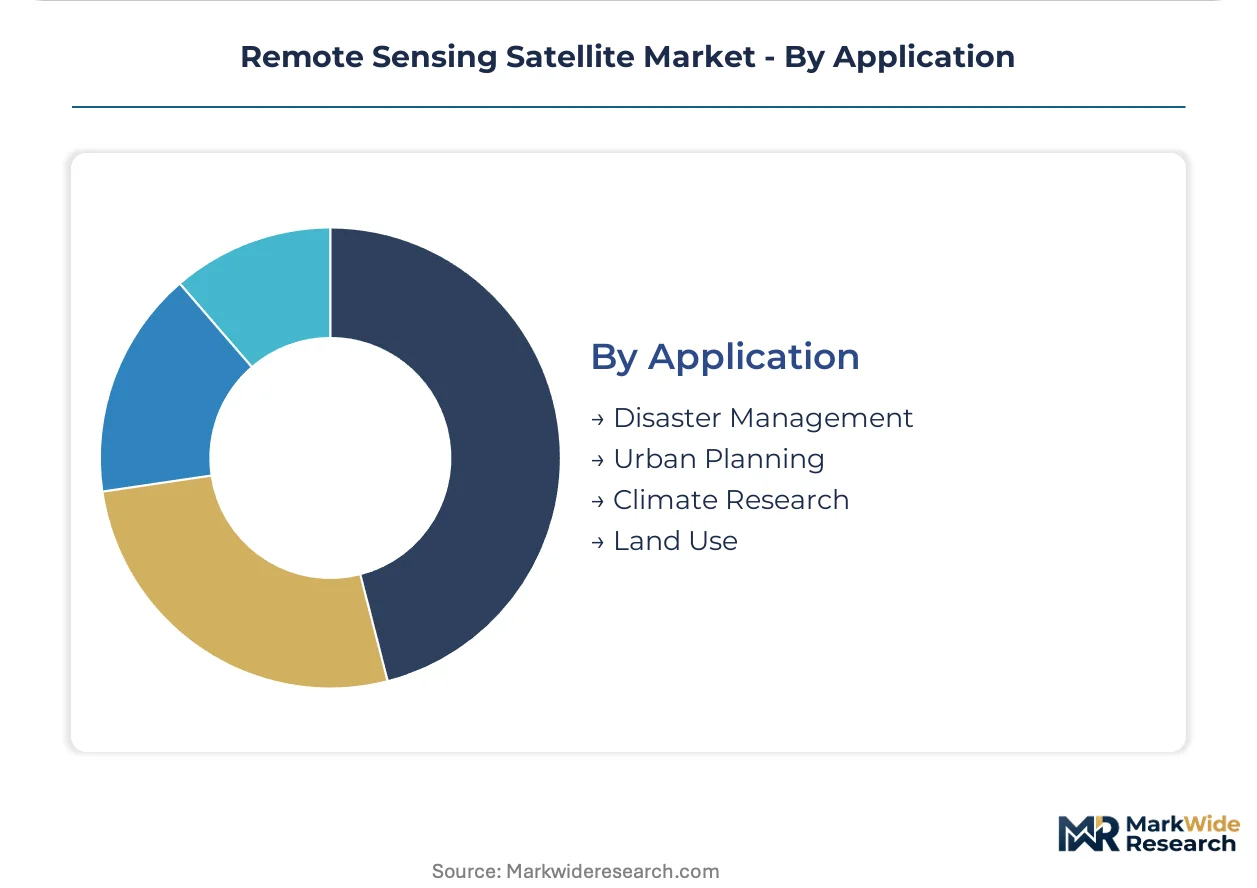
Application:
Disaster response commands premium pricing for rapid tasking, while climate research relies on long-duration archival data continuity.
- Disaster Management:Rapid damage assessment and logistics planning require same-day imagery delivery after earthquakes, floods, and wildfires. The International Charter on Space and Major Disasters coordinates free satellite tasking for affected nations.
- Land Use:Zoning enforcement, property taxation, and infrastructure planning depend on updated cadastral maps. Municipal governments in rapidly urbanizing regions subscribe to annual change detection services.
- Urban Planning:Three-dimensional building models and transportation network analysis support density and mobility decisions. Singapore's land authority operates a dedicated interferometric SAR program for millimeter-scale subsidence monitoring.
- Climate Research:Decadal ice sheet, glacier, and sea level observations require radiometrically calibrated long-term data archives. Antarctic and Greenland research programs coordinate satellite acquisitions across multiple agencies.
Land use applications generate the steadiest recurring demand. Disaster management contracts deliver the highest margins for surge-tasking capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Space Coast anchors procurement concentration, with Cape Canaveral launch density and Denver-Boulder aerospace corridors shaping operator headquarters placement. National security demand and precision agriculture commercialization drive regional specialization patterns.
United States
Defense intelligence contracts and Midwestern agricultural subscriptions dominate procurement volume. FCC spectrum licensing under the Land Remote Sensing Policy Act creates compliance thresholds for private constellation operators. The Denver-Boulder corridor concentrates satellite manufacturers and ground segment providers serving both government and commercial end users.
European Union
Copernicus program mandates direct institutional spending toward domestic manufacturers for sovereign Earth observation capacity. EU Space Programme regulations require member states to procure from Airbus and Thales Alenia Space for sensitive applications. Toulouse and Munich host competing manufacturing clusters for dual-use payload production.
India
State government agricultural monitoring programs and water stress management drive satellite imagery procurement across agricultural districts. ISRO's commercial arm Antrix coordinates frequency coordination with TRAI for private operator market entry. Bengaluru's aerospace cluster hosts emerging constellation operators targeting domestic precision farming demand.
China
Dual-use Earth observation capacity expansion serves both civilian resource management and security applications. MIIT spectrum allocation and GB standards for satellite manufacturing shape operator compliance requirements. Beijing-Tianjin-Hebei corridor concentrates state-owned constellation operators and downstream analytics providers.
Japan
Maritime surveillance and disaster response applications anchor government procurement for synthetic aperture radar tasking. METI coordinates commercial operator licensing through national space legislation implementation. Tokyo-Yokohama aerospace corridor hosts component suppliers and ground segment integrators serving regional operators.
Remote Sensing Satellite Market Competitive Environment
Global majors compete with regional champions across sovereign capacity requirements and commercial subscription models. The vendor base separates into three tiers: defense-anchored primes with classified contract access, commercial constellation specialists with high-temporal-coverage fleets, and emerging national champions serving protected domestic markets. Strategic archetypes include vertically integrated manufacturers controlling payload-to-ground-segment stacks, pure-play operators leasing capacity through tasking APIs, and dual-use producers balancing institutional and commercial revenue. Dominant competitive moves involve spectrum filing races for C-band and X-band coordination rights, plus ground station network expansion for reduced downlink latency.
Among defense-anchored primes, Lockheed Martin and Northrop Grumman exemplify classified contract specialists with hardened payload integration capabilities. Within commercial constellation operators, Planet Labs occupies a position representing high-frequency CubeSat fleet deployment. At the sovereign capacity tier, Thales Alenia Space anchors European institutional demand through EU Space Programme compliance positioning.
| Leading Market Players |
|---|
| SpaceX |
| Maxar Technologies |
| Airbus Defence and Space |
| Lockheed Martin |
| Northrop Grumman |
| Planet Labs |
| Thales Alenia Space |
| Boeing |
| L3 Harris Technologies |
| Others |
Value Chain & Pricing Dynamics
EU CSRD disclosure mandates gate qualified supply and premium-tier pricing access for satellite imagery providers serving European industrial buyers. Compliance with geospatial audit trail requirements separates certified operators from commodity resellers, concentrating margin capture among firms with established ground segment infrastructure and frequency coordination rights.
Pricing Analysis
Input-cost pass-through from launch services and ground station capital shapes contract structures across the market. Three-tier pricing separates defense-classified tasking from commercial subscription APIs and economy catalog purchases. Price differentiation rests on resolution grade and spectral band count, with hyperspectral providers commanding premiums over multi-spectral alternatives. Cost compression in commercial Earth observation is intensifying because rideshare launch manifests and standardized CubeSat platforms reduce constellation deployment barriers. Agriculture buyers exhibit highest price sensitivity, while defense intelligence contracts show least elasticity due to mission-critical requirements.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate multi-supplier qualification for critical payload components. Manufacturing concentrates in the United States, France, and Germany for precision optics and stabilization systems. Raw material dependencies include germanium substrates for infrared sensors, radiation-hardened electronics for orbital environments, and specialty alloys for thermal management. Single-source vulnerability in heavy-lift launch capacity creates deployment scheduling risk for constellation operators. Distribution runs through direct government procurement channels and API-integrated software platforms serving commercial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The remote sensing satellite market reads as a late-cycle quality story. Farm operators in the Midwestern United States now demand sub-meter resolution as baseline specification, shifting procurement from subsidized public data toward paid commercial subscriptions with embedded analytics.
For Market Incumbents: Deploy spectrum filing acceleration as the priority lever. Lock C-band and X-band coordination rights ahead of emerging constellation operators. Secure polar ground station sites in Alaska and Norway to reduce downlink latency for defense customers. Consolidate position against SAR-based substitutes by emphasizing all-weather tasking partnerships or captive radar payload development. For New Entrants and Emerging Players: Precision agriculture software platforms represent the most penetrable channel partner type for API integration. Target Indian state government water stress monitoring programs where domestic manufacturing preferences create procurement openings for local constellation operators. Pursue carbon credit verification services as a white-space application with compliance-driven demand expansion. Anchor initial revenue through subscription tasking models rather than capital-intensive constellation ownership. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play commercial operators with high-temporal-coverage fleets but limited defense contract exposure. Five-to-ten year viability hinges on successful navigation of orbital debris mitigation compliance and frequency coordination bottlenecks. Acquisition target archetype: regional constellation operators with established ITU filings and domestic regulatory relationships in protected markets. Watch FCC licensing timeline compression as the signal indicating inflection toward revenue generation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Radar Constellation Deployment | All-weather imaging capability displaces electro-optical incumbents in maritime and agricultural insurance verticals. |
| Ground Station Network Expansion | Polar and mid-latitude downlink sites in Alaska and Norway reduce latency for defense intelligence tasking. |
| API-First Subscription Platform | Direct software integration bypasses traditional value-added resellers in North American precision agriculture. |
| Hyperspectral Payload Development | Narrow spectral band sensors enable direct ore body identification for mining exploration teams. |
| Carbon Credit Verification Service Launch | Forest monitoring and methane detection align with EU CSRD disclosure requirements for supply chain geospatial audit trails. |
Study Parameters
Multiple input streams — constellation operator technical directors, defense procurement officers at NATO member agencies, precision agriculture software platform engineers, and satellite component procurement leads — were reconciled against regulatory filings and launch manifest databases. Primary interviews with ground segment integrators and frequency coordination specialists validated secondary data from FCC licensing records, ITU satellite network filings, and ESA Copernicus program documentation. Bottom-up unit economics for CubeSat and traditional bus platforms were triangulated against top-down institutional budget allocations.
Cross-reference between historical launch cadence patterns and expert panel input anchored the projection framework across the analysis window. Segmentation modeling incorporated payload type, end-user category, sensing technology modality, and regional regulatory cluster. CAGRs were derived from reconciled growth assumptions across government constellation programs and commercial subscription expansion. Industry-specific forecast inputs included rideshare launch capacity expansion curves and ITU filing queue progression timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to orbital debris mitigation standard evolution and national space law implementation across Asia-Pacific markets. Assumptions regarding FCC licensing timeline compression and heavy-lift vehicle availability underpin the outlook. Deviation in launch capacity bottlenecks or spectrum coordination adjudication delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Latin America Satellite Connectivity Market
Satellite
Sudan Satellite Transponder Market
Satellite
Germany Satellite Connectivity Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Satellite Data Service Market
Satellite
US Satellite Connectivity Market
Satellite
Europe Small Satellite Market
Satellite
Communication Satellite Launch Services Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
France Satellite Imagery Services Market
Satellite
North America Satellite Bus Market
Satellite
Global Remote Sensing Services Market
Satellite
Global Maritime Satellite Communication Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Africa Satellite Connectivity Market