
 Global Railway Wiring Harness Market | 2026-2036
Global Railway Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Global Railway Wiring Harness Market Intelligence
Multi-source procurement is pivoting toward captive harness production among tier-one train builders. TE Connectivity leverages its sensor-integrated cable portfolio to anchor European high-speed programs. Leoni sustains margin through vertical control over copper processing and jacket extrusion. Furukawa Electric specializes in fiber optic harness architectures for Japanese Shinkansen signaling upgrades.
A railway wiring harness is an engineered assembly of conductors, connectors, and protective sleeving designed to transmit power, signals, and data across rolling stock subsystems, typically rated for continuous operation between minus 40 degrees Celsius and 85 degrees Celsius with fire-retardant halogen-free insulation. Power wiring harnesses dominate revenue owing to heavy-gauge copper requirements and stringent flame-resistance certifications, while data wiring harnesses represent the fastest-expanding margin pool as Ethernet-based train control networks displace legacy fieldbus architectures. Fiber optic wiring technology leads in new high-speed train platforms where electromagnetic immunity and bandwidth density override copper economics.
EU F-Gas Regulation and REACH compliance in Europe, NHTSA fire-safety guidelines for passenger rail in the United States, and China's GB standards for rolling stock electrical equipment collectively elevate material specifications and testing burdens for harness suppliers. Japan's METI railway modernization directives further tighten electromagnetic compatibility thresholds for urban transit networks. Stakeholders must monitor how regional certification divergence affects platform standardization strategies and supplier qualification timelines.
Market Dynamics
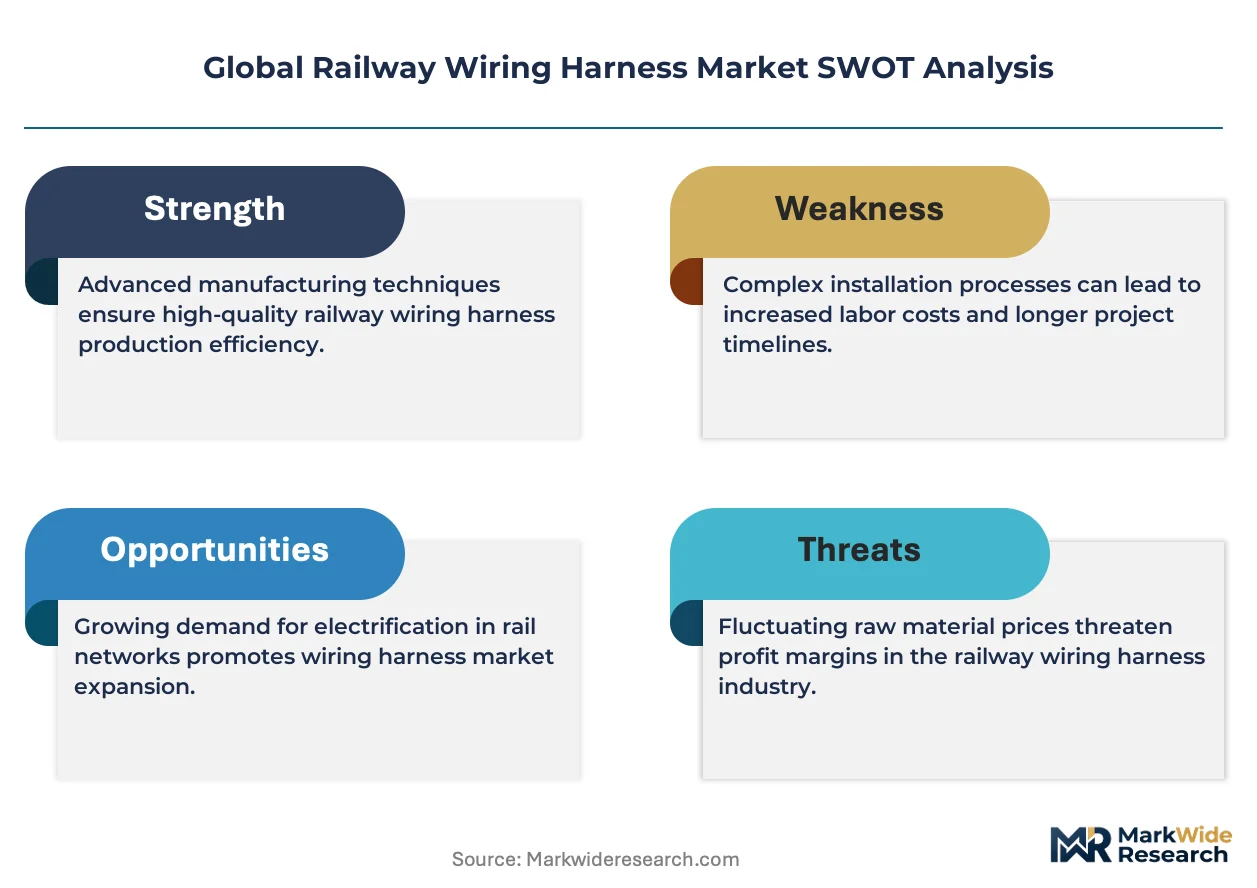
Fire-resistant material mandates and Ethernet-based train control architectures are compressing supplier qualification timelines while fragmenting procurement authority across rolling stock OEMs and their subsystem integrators.
Growth Catalysts
- EU F-Gas Regulation:Halogen-free insulation requirements are accelerating material transitions across European high-speed rail programs, expanding addressable demand for LSZH-certified harness suppliers.
- Japanese Shinkansen signaling upgrades:Fiber optic harness architectures for electromagnetic immunity are penetrating urban transit networks under METI railway modernization directives.
- Ruhr industrial corridor concentration:Dense supplier ecosystems around Siemens and Alstom maintenance facilities are generating recurring aftermarket demand for power harness assemblies.
Market Restraints
- Copper price volatility:Heavy-gauge copper requirements in power wiring harnesses expose margins to London Metal Exchange fluctuations without effective hedging mechanisms for mid-tier suppliers.
- REACH compliance burden:European chemical substance restrictions extend supplier qualification timelines by months, freezing out smaller harness assemblers lacking dedicated regulatory affairs functions.
- Legacy fieldbus substitution limits:Ethernet-based train control networks face integration friction with decades-old rolling stock fleets, slowing replacement cycles in cost-constrained transit authorities.
Strategic Opportunities
- Chinese high-speed rail expansion:Fire-resistant harness procurement from CRRC and its subsidiaries is outpacing domestic supplier capacity, creating entry points for certified foreign manufacturers.
- Sensor-integrated cable convergence:Combining power distribution with condition monitoring diagnostics opens premium pricing in predictive maintenance contracts for European operators.
- US NHTSA fire-safety guideline tightening:Enhanced passenger rail standards are disqualifying uncertified imports, consolidating procurement toward UL-listed harness providers with domestic extrusion capabilities.
Industry Challenges
- Electromagnetic compatibility certification backlog:Japan's METI threshold tightening for urban transit networks is straining testing laboratory capacity, delaying platform approvals.
- Halogen-free compound processing expertise:LSZH jacket extrusion requires specialized twin-screw compounding knowledge that concentrates among a handful of European and Japanese compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Railway Wiring Harness Market |
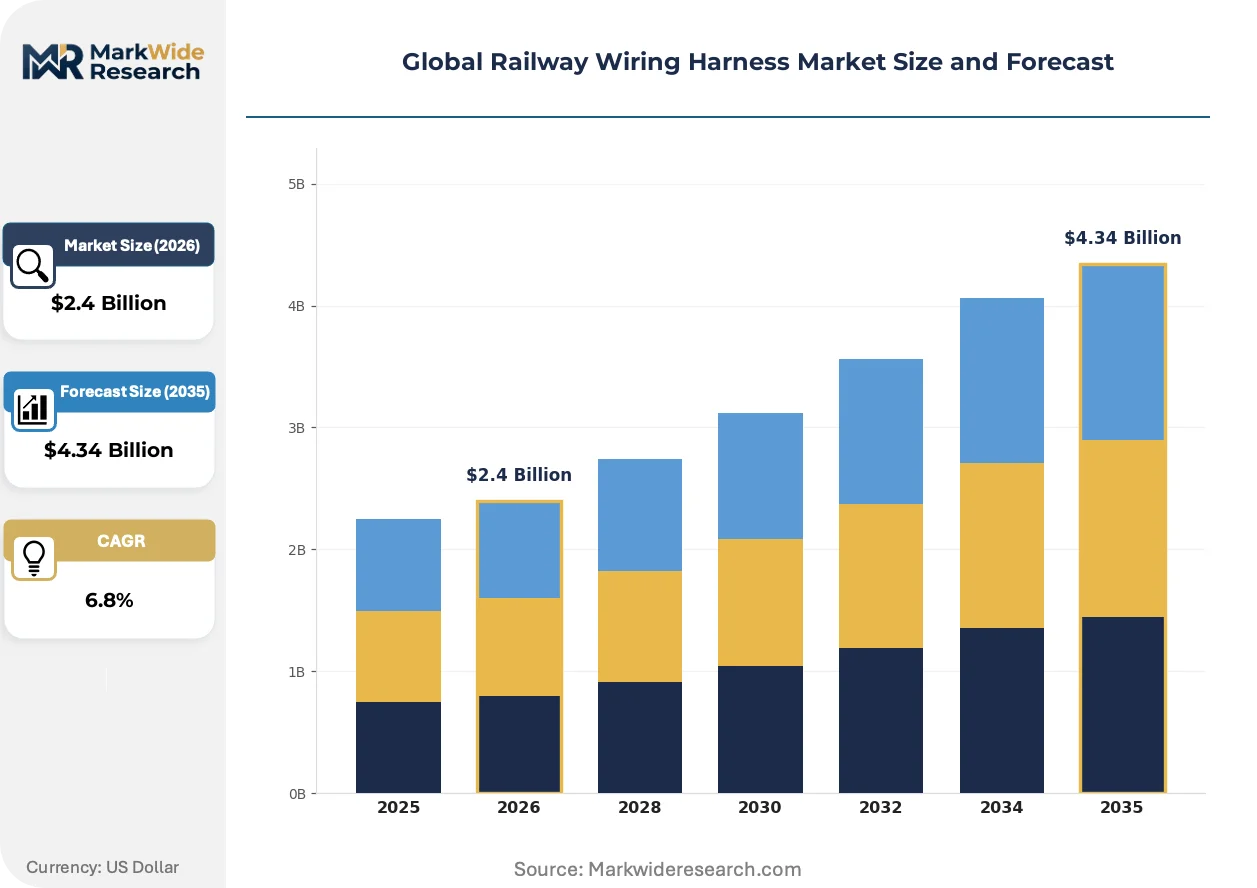
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Wiring Harness, Signal Wiring Harness, Data Wiring Harness, Lighting Wiring Harness Technology: Shielded Cabling, Fiber Optic Wiring, Coaxial Wiring, Twisted Pair Cabling Application: High-Speed Trains, Metro Transit, Freight Transport, Light Rail Systems End User: Train Manufacturers, Maintenance Providers, Infrastructure Operators, Transit Authorities |
| Companies Covered | TE Connectivity, Leoni, Furukawa Electric, Prysmian Group, Nexans, Hitachi, Samvardhana Motherson, HUBER+SUHNER, Sumitomo Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Railway Wiring Harness Market Strategic Shifts & Innovations
Ethernet-based train control networks are compressing the data harness upgrade cycle from decades to years, while regulatory divergence between EU, US, and Asian fire-safety standards is fragmenting supplier certification strategies.
Fiber optic wiring technology is rewriting competitive positioning in new high-speed train platforms. Japanese Shinkansen operators are mandating optical harnesses for signaling immunity at speeds exceeding commercial copper limits. This technology is compressing the addressable market for traditional electromagnetic shielding solutions while opening premium niches for specialized fiber termination providers.
The EU F-Gas Regulation is tightening material specifications across rolling stock electrical equipment. Low-smoke zero-halogen insulation is becoming mandatory for passenger-accessible spaces, disqualifying PVC-jacketed legacy harnesses from new platform bids. German and French operators are responding by consolidating procurement toward compounders with verified REACH-compliant supply chains.
Buying patterns among tier-one train builders are pivoting toward captive harness production. Siemens and Alstom are absorbing previously outsourced cable assembly functions to protect intellectual property around integrated sensor architectures. This verticalization is most visible in Germany's Ruhr corridor, where maintenance depots now specify supplier-owned extrusion assets as a qualification threshold for long-term service contracts.
Global Railway Wiring Harness Market Segmentation
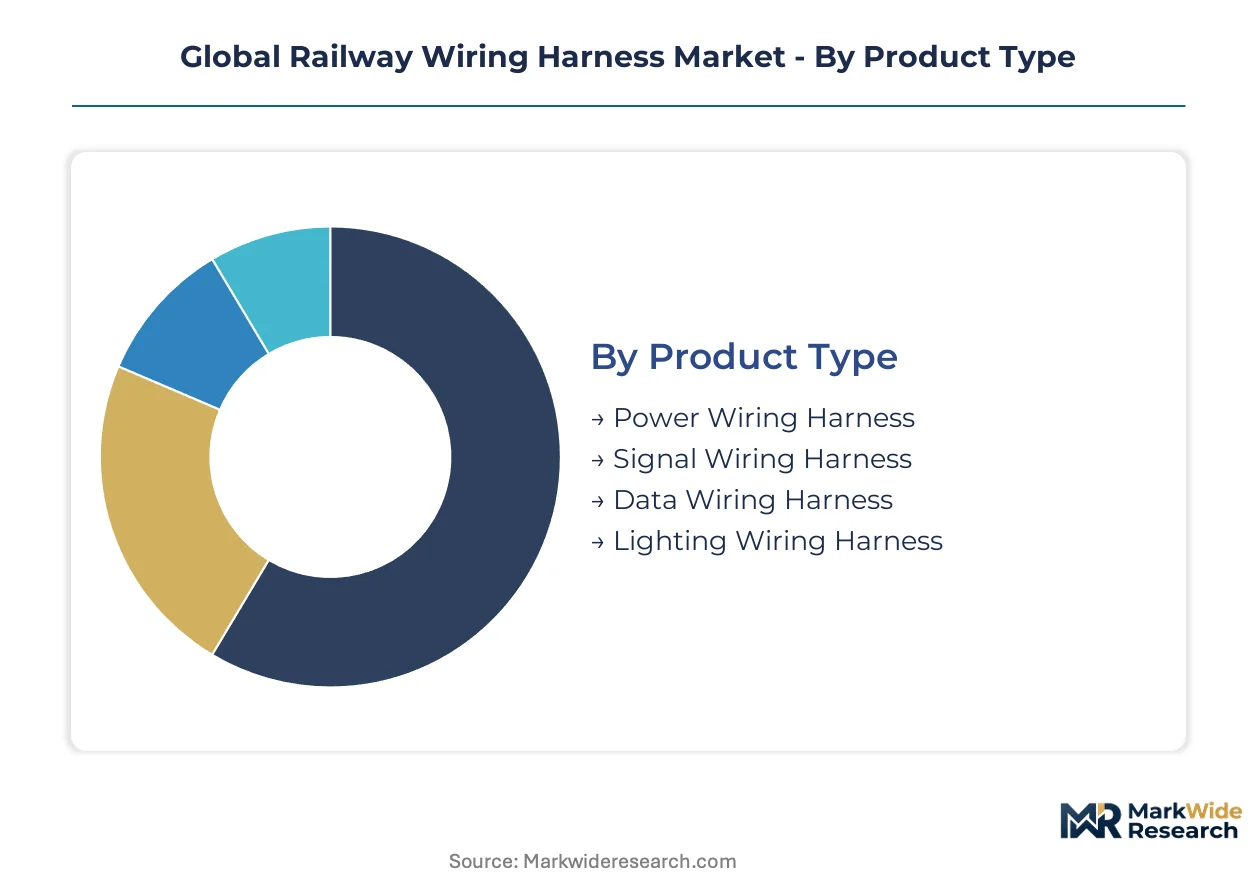
Railway wiring harness segmentation reflects divergent capital requirements across power transmission, signal integrity, and data networking functions. Material specifications, certification burdens, and integration complexity vary sharply between segments, reshaping supplier economics and procurement patterns across rolling stock platforms.
Product Type:
Power wiring harnesses demand the heaviest upfront investment due to heavy-gauge copper procurement, flame-resistance certification, and specialized extrusion equipment for halogen-free insulation.
- Power Wiring Harness:Heavy-gauge copper conductors with fire-retardant halogen-free insulation rated for continuous high-current transmission. Procurement concentrates among Chinese high-speed rail operators expanding fire-resistant harness assemblies under GB standards. Copper price volatility and REACH compliance burdens compress margins for mid-tier suppliers lacking hedging mechanisms.
- Data Wiring Harness:Ethernet-based conductor assemblies enabling train control network migration from legacy fieldbus architectures. Demand clusters in European high-speed programs where TE Connectivity anchors sensor-integrated cable portfolios. Regulatory divergence between EU F-Gas mandates and US NHTSA guidelines fragments supplier qualification strategies.
- Signal Wiring Harness:Electromagnetic-compatible cabling for track-to-train communication and safety-critical control loops.
- Lighting Wiring Harness:Low-voltage distribution assemblies for passenger compartment and exterior illumination systems.
Power wiring harnesses absorb the bulk of installed capacity; data wiring harnesses are expanding most quickly.
Technology:
Shielded cabling dominates current procurement volumes, though fiber optic architectures command premium positioning in next-generation platforms where bandwidth density and electromagnetic immunity override legacy copper economics.
- Fiber Optic Wiring:Glass-fiber transmission cores with specialized termination hardware for immunity-critical signaling applications. Japanese Shinkansen operators mandate optical harnesses for electromagnetic compatibility at speeds exceeding commercial copper limits under METI railway modernization directives. Furukawa Electric specializes in these architectures for urban transit network upgrades.
- Shielded Cabling:Multi-layer conductor assemblies with metallic braid or foil shielding for electromagnetic interference suppression. Deployment concentrates in Germany's Ruhr industrial corridor, where Siemens and Alstom maintenance facilities generate recurring aftermarket demand. LSZH jacket extrusion expertise concentrates among European and Japanese compounders with verified REACH-compliant supply chains.
- Coaxial Wiring:Central conductor with dielectric insulator and outer shield for radio frequency signal transmission.
- Twisted Pair Cabling:Paired conductors with controlled twist rates for noise cancellation in analog and digital signaling.
Shielded cabling maintains the largest installed base; fiber optic wiring is gaining share fastest.
Application:
High-speed trains impose the most stringent certification requirements, while metro transit offers volume scale through fleet standardization across urban networks.
- High-Speed Trains:Integrated harness systems spanning power distribution, signaling, and passenger information networks at speeds above commercial copper thresholds. Chinese procurement from CRRC and subsidiaries outpaces domestic supplier capacity, creating entry points for certified foreign manufacturers. Fire-resistant material mandates compress qualification timelines while fragmenting procurement authority.
- Metro Transit:High-density harness architectures for frequent-stop urban rail with standardized fleet configurations. Demand concentrates in European and Asian networks modernizing under tightening electromagnetic compatibility thresholds. Predictive maintenance contracts open premium pricing for sensor-integrated cable convergence.
- Freight Transport:Ruggedized power and control harnesses for locomotive-hauled cargo operations.
- Light Rail Systems:Lower-voltage distribution assemblies for tram and streetcar platforms with mixed-traffic operation.
High-speed trains command the highest unit values; metro transit delivers the steepest volume expansion.
End User:
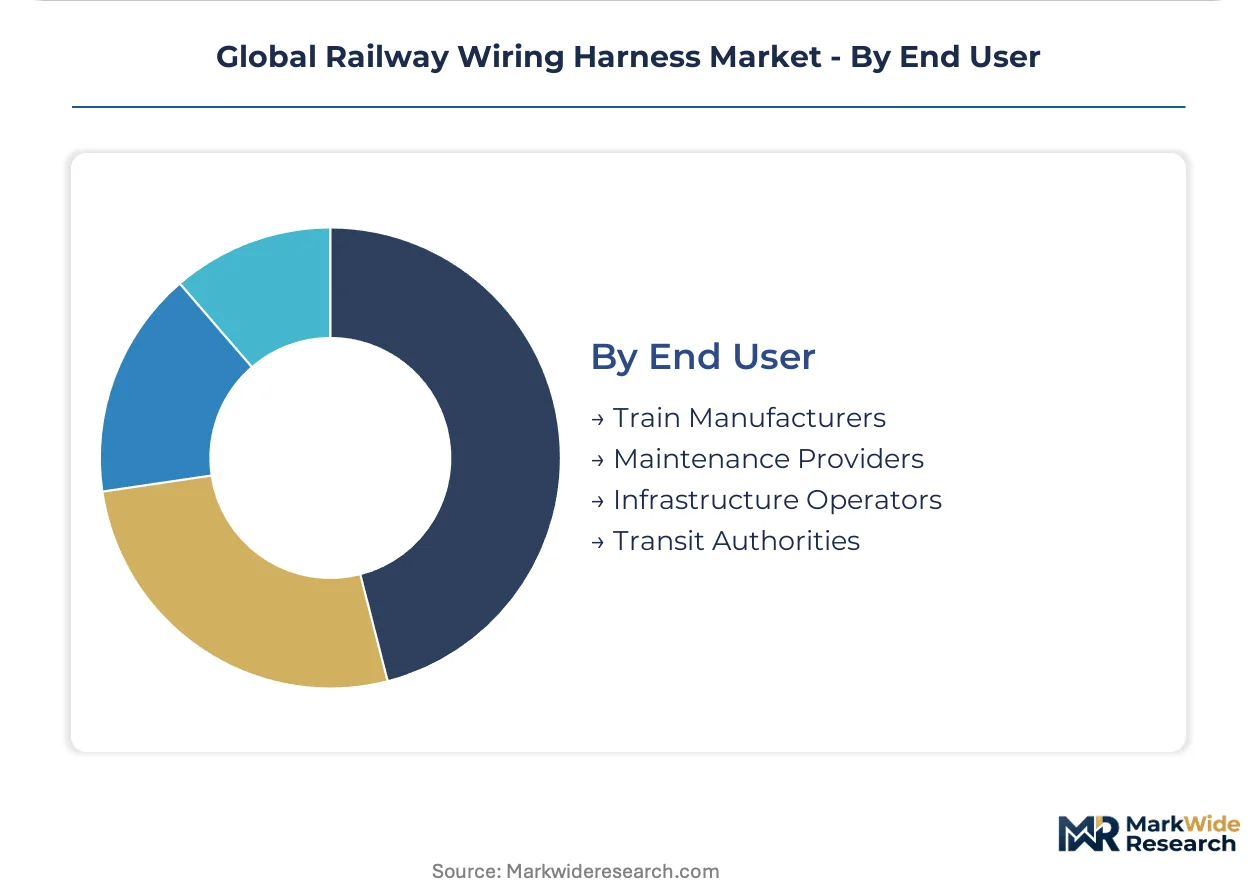
Train manufacturers are absorbing previously outsourced harness production to protect intellectual property around integrated sensor architectures, reshaping supplier relationships across the value chain.
- Train Manufacturers:Tier-one rolling stock OEMs including Siemens and Alstom specifying harness assemblies for new platform development. Captive production pivots concentrate in Germany's Ruhr corridor, where supplier-owned extrusion assets now serve as qualification thresholds for long-term service contracts. Vertical control over copper processing and jacket extrusion sustains margin for integrated producers.
- Maintenance Providers:Aftermarket harness replacement and refurbishment services for in-service rolling stock fleets. Dense supplier ecosystems around Siemens and Alstom facilities generate recurring demand for power harness assemblies in European maintenance depots.
- Infrastructure Operators:Trackside and wayside harness procurement for signaling and power distribution networks.
- Transit Authorities:Public procurement entities specifying harness standards for fleet modernization and expansion programs.
Train manufacturers dominate upfront platform investment; maintenance providers are climbing the fastest as fleet ages expand aftermarket addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity in Chile and Zambia anchors raw-material security for harness manufacturers serving electrified rail networks across three continents.
China
CRRC and its subsidiaries are outpacing domestic harness supplier capacity, creating procurement openings for certified foreign manufacturers. GB standards for rolling stock electrical equipment mandate fire-resistant material specifications that compress qualification timelines. Procurement concentrates in the Yangtze River Delta, where high-speed rail operators are expanding fire-resistant harness assembly orders.
Germany
Siemens and Alstom maintenance facilities in the Ruhr industrial corridor generate recurring aftermarket demand for power harness assemblies. The EU F-Gas Regulation accelerates transitions to low-smoke zero-halogen insulation materials across European high-speed programs. Dense supplier ecosystems around Düsseldorf and Essen now specify supplier-owned extrusion assets as qualification thresholds.
United States
Transit authorities face integration friction when deploying Ethernet-based train control networks alongside decades-old rolling stock fleets. NHTSA fire-safety guidelines for passenger rail are disqualifying uncertified imports, consolidating procurement toward UL-listed providers. Maintenance depots in the Northeast Corridor generate concentrated demand for harness refurbishment services.
Japan
Shinkansen operators mandate fiber optic harness architectures for electromagnetic immunity at speeds exceeding commercial copper limits. METI railway modernization directives tighten electromagnetic compatibility thresholds for urban transit networks in Tokyo and Osaka. Furukawa Electric specializes in these optical termination systems for signaling upgrades.
India
Urban metro expansion in Delhi, Mumbai, and Bengaluru is driving fleet standardization across high-density harness architectures. BIS certification requirements for rolling stock electrical equipment elevate testing burdens for foreign suppliers entering the market. Manufacturing clusters in Maharashtra and Gujarat are developing captive copper processing capabilities to reduce import dependency.
Global Railway Wiring Harness Market Key Industry Players
Backward integration into copper processing and jacket extrusion dominates the current landscape among tier-one suppliers seeking margin protection. The vendor base organizes around three strategic archetypes: integrated material compounders with verified REACH-compliant supply chains, sensor-integrated cable specialists anchoring European high-speed programs, and optical termination providers serving Japanese signaling upgrades. M&A activity and captive production absorption by train builders represent the two dominant competitive moves reshaping supplier relationships.
Within the integrated compounder tier, Leoni exemplifies vertical control over copper processing and jacket extrusion. TE Connectivity occupies a position among sensor-integrated cable specialists, while Furukawa Electric represents the optical termination archetype serving electromagnetic immunity requirements. These three anchors illustrate how geographic specialization and material expertise stratify competitive positioning across regional procurement clusters.
| Leading Market Players |
|---|
| TE Connectivity |
| Leoni |
| Furukawa Electric |
| Prysmian Group |
| Nexans |
| Hitachi |
| Samvardhana Motherson |
| HUBER+SUHNER |
| Sumitomo Electric |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap compounders with decades of LSZH formulation heritage anchor supply-side discipline, translating REACH-compliant material scarcity into sustained pricing power against price-sensitive transit authorities.
Pricing Analysis
Warranty-bundled service contracts separate premium harness suppliers from commodity assemblers in European high-speed programs. Three-tier pricing structure across REACH-certified premium, GB-standard mid-grade, and economy PVC-jacketed tiers reflects certification investment amortization. Pricing pressure stems from copper LME volatility squeezing mid-tier suppliers without hedging desks. Transit authorities in cost-constrained emerging markets exhibit highest price sensitivity; Japanese Shinkansen operators show lowest sensitivity due to electromagnetic immunity mandates.
Supply Chain Analysis
Refurbishment flows from Germany's Ruhr maintenance depots to Eastern European reprocessors extend copper recovery economics across harness lifecycle stages. Raw material supply concentrates in Chile and Zambia for copper cathode, Germany and Japan for halogen-free compounds, and China for connector stampings. The chain draws from single-source vulnerability in specialized twin-screw LSZH compounding equipment. Distribution runs through tier-one train builder captive production facilities and authorized aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation and REACH substance restrictions erect qualification barriers that freeze out smaller harness assemblers, consolidating procurement toward compounders with verified supply chain documentation.
For Market Incumbents: Deepen backward integration into copper rod casting and in-house jacket extrusion to defend margins against commodity volatility. Secure long-term service contracts with Siemens and Alstom maintenance depots in the Ruhr corridor by deploying supplier-owned extrusion assets as qualification thresholds. Invest in fiber optic termination capacity to counter electromagnetic immunity substitution threats from Japanese signaling architectures. For New Entrants and Emerging Players: Capture white-space in Chinese high-speed rail procurement where CRRC demand outpaces domestic supplier capacity. Target fire-resistant power harness assemblies for Yangtze River Delta operators seeking certified foreign manufacturers under GB standards. Lead with UL-listed domestic extrusion capabilities to penetrate US Northeast Corridor maintenance depots facing NHTSA guideline tightening. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European harness assemblers with REACH-compliant compound libraries and established rail OEM relationships in Germany. Long-term viability hinges on consolidation plays that aggregate certification assets across fragmented national supplier bases. Monitor METI electromagnetic compatibility threshold announcements for Japanese urban transit networks as inflection signal for fiber optic harness demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Processing | Leoni's captive rod casting insulates margins from LME volatility in power harness production. |
| Sensor-Integrated Cable Convergence | TE Connectivity anchors European high-speed programs by embedding condition monitoring diagnostics. |
| Fiber Optic Termination Capacity Expansion | Furukawa Electric captures Japanese Shinkansen signaling upgrades under METI modernization directives. |
| REACH-Compliant Supply Chain Certification | German compounders with verified substance documentation consolidate procurement from disqualified PVC-jacketed legacy suppliers. |
| Captive Production Absorption by Train Builders | Siemens and Alstom verticalize harness assembly to protect intellectual property around integrated sensor architectures. |
Research Approach
Multi-period observation of harness procurement volumes, certification timeline compressions, and copper price volatility anchored the trend analysis, supplemented by interviews with rolling stock OEM procurement directors, maintenance depot operations managers, LSZH compounder technical directors, and railway authority specification engineers. Secondary validation drew from EU F-Gas regulatory filings, REACH substance restriction updates, GB standard revision notices, and customs trade data for copper conductor imports. Bottom-up segment sizing triangulated against top-down rolling stock production forecasts.
Input-output matrices mapped power harness copper intensity, data harness Ethernet migration rates, and fiber optic content per high-speed train platform across the projection horizon. Segmentation dimensions included product type, insulation technology, application speed tier, and end-user captive versus outsourced procurement mode. CAGRs derived from rolling stock fleet expansion schedules, regulatory mandate implementation timelines, and material substitution elasticity estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price regime shifts, electromagnetic compatibility threshold accelerations, and train builder verticalization pace. Practitioners should monitor CRRC procurement tender announcements, METI testing laboratory capacity expansions, and UL certification backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Railway Li-Ion Battery Market