
 Overhead Catenary System Market | 2026-2036
Overhead Catenary System Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Catenary System Market Outlook
Buyer concentration among national rail operators is decoupling from traditional equipment procurement patterns as municipal tramway authorities and mining conglomerates fragment demand across smaller, specialized contracts. Alstom leverages its integrated signaling-electrification portfolio to anchor premium system deployments across European high-speed corridors. Siemens competes through digital twin-enabled catenary design services that reduce commissioning timelines for complex terrain installations. CREC sustains manufacturing scale through captive steel and copper processing capabilities that lower component costs for emerging market projects.
An overhead catenary system comprises tensioned copper or copper-alloy contact wires suspended from messenger wires via droppers, supported by cantilever or portal structures, delivering continuous electrical power at voltages ranging from 750V DC to 25kV AC for moving vehicles. The system eliminates onboard fuel storage and enables regenerative braking energy recovery across rail transport, tramway, and heavy industrial haulage applications. AC system types dominate installed base value due to 25kV standardization on mainline railways, while hybrid configurations represent the fastest-growing segment as operators bridge legacy DC infrastructure with modern AC traction. Component-level margin pools concentrate in catenary wires and precision tensioning hardware where metallurgical specifications and fatigue resistance create supplier stickiness.
EU F-Gas Regulation and REACH compliance frameworks restrict fluorinated insulator chemistries and mandate material traceability across catenary component supply chains. Germany's KBA enforces interoperability standards that shape product design for cross-border rolling stock compatibility. China's MIIT issues GB standards governing high-voltage catenary performance in extreme climate zones. Stakeholders must monitor how diverging national electrification roadmaps and local content requirements reshape supplier qualification criteria across priority rail corridors.
Market Dynamics
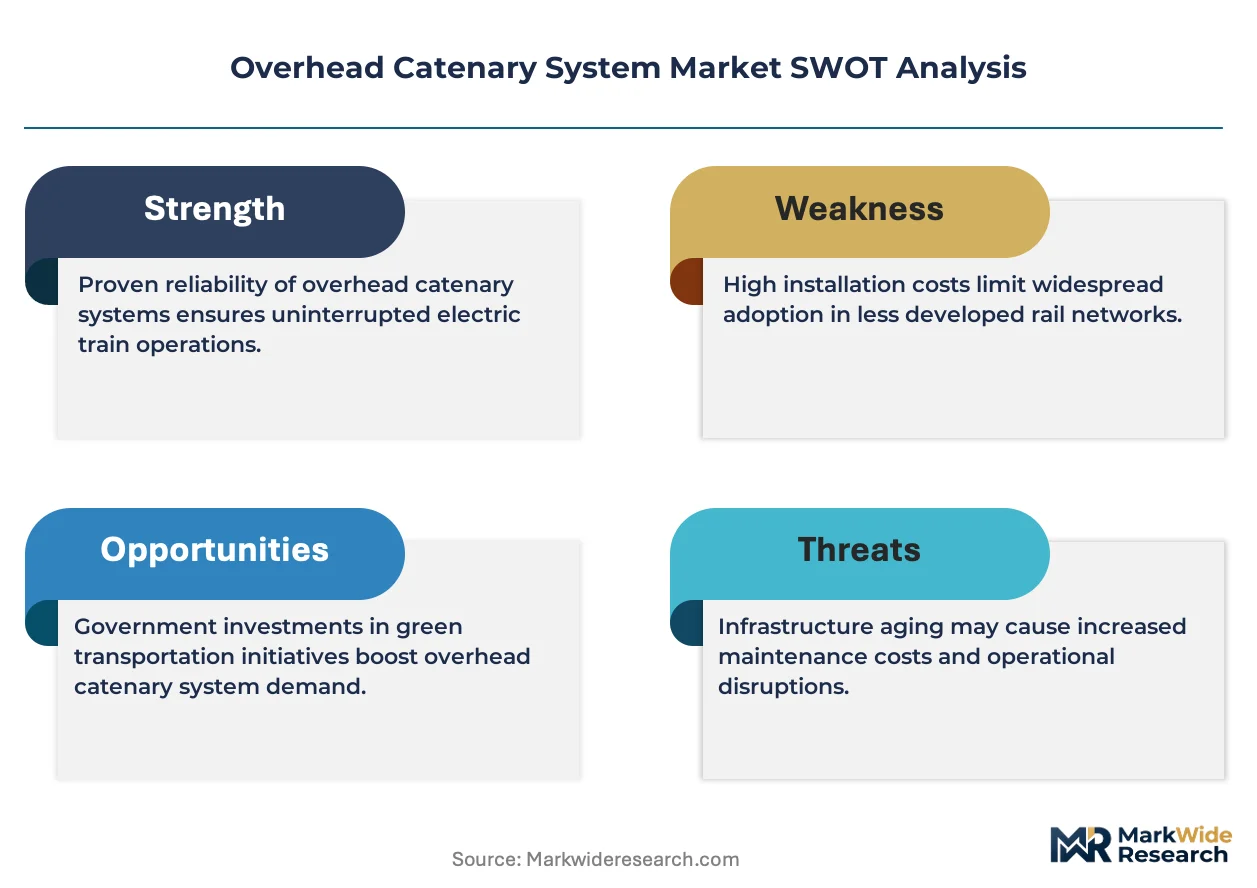
Electrification mandates across European rail corridors are compressing procurement cycles as operators retrofit legacy diesel routes with 25kV AC infrastructure, forcing component suppliers to accelerate certification timelines and expand messenger wire production capacity ahead of network-wide standardization deadlines.
Growth Catalysts
- EU F-Gas Regulation:Bans on fluorinated greenhouse gases in electrical insulation are accelerating demand for dry-type transformers and silicone-based insulators in catenary substations across Germany, France, and Poland.
- Urban mass transit electrification:Metro and tramway authorities in Spain, Italy, and the Netherlands are awarding bundled catenary-signaling contracts that expand addressable market scope beyond traditional mainline operators.
- 750V DC to 25kV AC conversion:Hybrid traction systems enable freight corridors to bridge legacy infrastructure with modern high-voltage standards, opening retrofit opportunities on cross-border Alpine routes.
Market Restraints
- Copper price volatility:Contact wire production consumes high-purity copper cathode, exposing margin structures to London Metal Exchange price swings that compress fixed-price contract profitability.
- Specialized installation labor scarcity:Tensioning equipment operators and catenary geometry specialists concentrate in Central European contractor pools, creating bottleneck risk for concurrent corridor projects.
- REACH compliance burden:Material traceability requirements for cadmium-free alloys and conflict-free copper sourcing extend procurement lead times by 8-14 weeks for non-European suppliers.
Strategic Opportunities
- Battery-electric hybrid traction:Mining haulage operators in Australia and Chile are piloting partial catenary coverage for heavy transport corridors, creating demand for modular, rapid-deployment overhead systems.
- Digital twin commissioning:Physics-based simulation of wire dynamics and pantograph interaction reduces field calibration time, enabling suppliers to bid aggressive timeline guarantees on mountainous terrain projects.
- Polish corridor modernization:PKP PLK's priority rail investment program targets 2,000km of new electrification by 2030, representing concentrated demand for cantilever assemblies and auto-tensioning devices.
Industry Challenges
- Interoperability certification delays:Germany's KBA mandates rolling stock compatibility testing that extends product approval cycles for new contact wire alloys and dropper configurations.
- Legacy DC system integration:Urban tram networks in Belgium and the Czech Republic require hybrid substation designs that complicate engineering resource allocation and dilute standardization benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Catenary System Market |
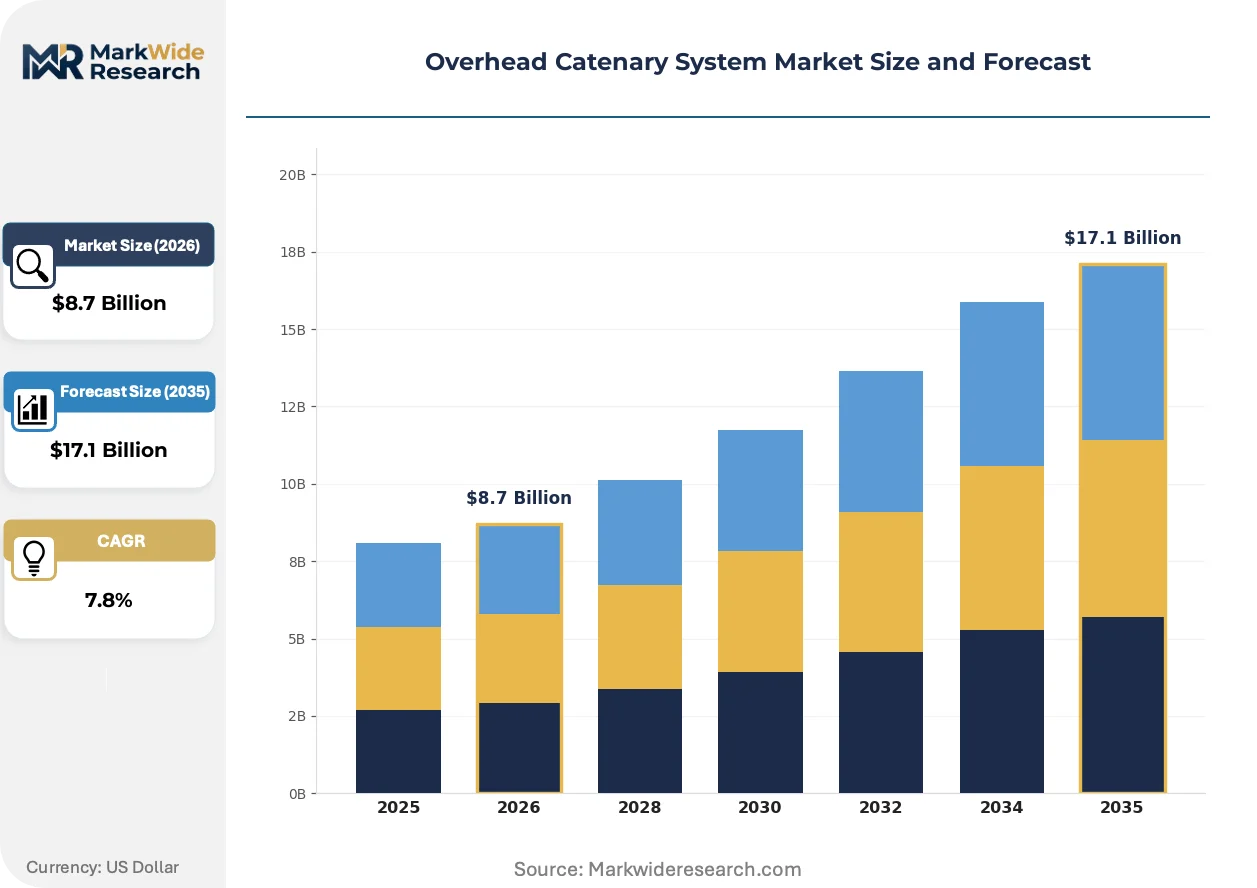
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: AC, DC, Hybrid, High-Voltage Component: Catenary Wires, Insulators, Support Structures, Feeders Application: Rail Transport, Tramway Systems, Mining Operations, Industrial Use Installation Type: Fixed, Temporary, Upgraded, Modular |
| Companies Covered | Alstom, Cobra, CRCC, Colas Rail, Tianjin Keyvia, CREC, Engie Ineo, Kummler+Matter, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Catenary System Market Strategic Shifts
Active pantograph monitoring and predictive tensioning algorithms are displacing scheduled maintenance protocols across high-speed corridors, compressing lifecycle cost models and reshaping supplier service revenue streams toward performance-based contracts.
Carbon fiber composite cantilever arms are integrating into portal structures on the Channel Tunnel Rail Link and Scandinavian high-speed routes. Network Rail and Banedanmark specify these components for coastal installations where salt corrosion degrades traditional galvanized steel. The material substitution is integrating aerodynamic profiling with electromagnetic interference shielding, enabling slimmer support geometries that reduce visual impact in protected landscapes.
REACH and the EU F-Gas Regulation are tightening material specifications for insulator housings and cable terminations. ECHA's restriction roadmap targets per- and polyfluoroalkyl substances used in weatherproof coatings, compelling suppliers to qualify ceramic and silicone rubber alternatives. Catenary wire manufacturers serving the French and German markets are restructuring supply chains to document substance volumes through SCIP database entries, adding compliance overhead that favors integrated producers with in-house polymer compounding.
Performance-based maintenance contracts are displacing unit-price spare parts purchasing among Scandinavian and Benelux operators. Stockholm's SL and Amsterdam's GVB now specify availability guarantees rather than component replacement schedules, transferring operational risk to electrification contractors. This reconfiguration concentrates aftermarket revenue with vendors possessing remote diagnostic capabilities and regional service depot networks, marginalizing pure equipment manufacturers without field engineering presence.
Overhead Catenary System Market Segmentation
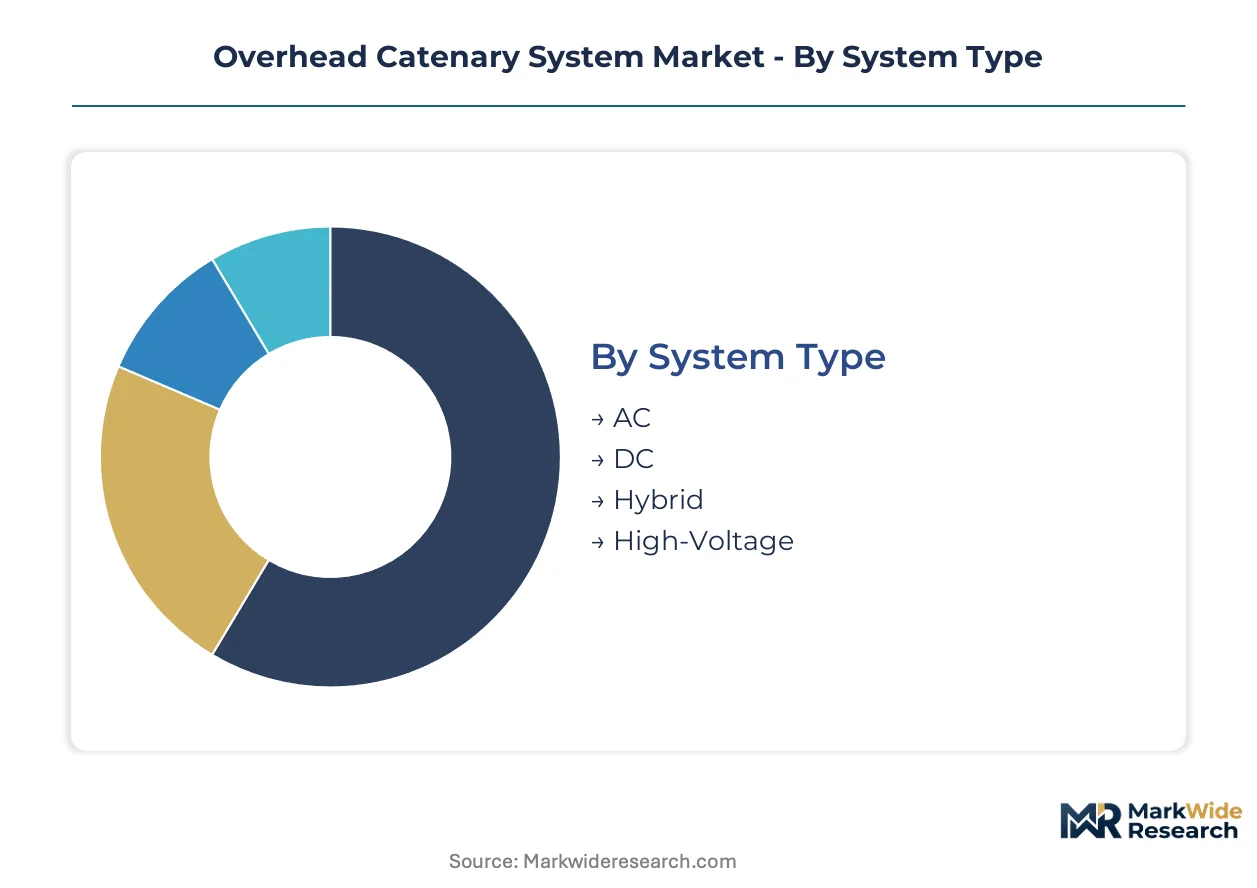
Overhead catenary system procurement diverges sharply between integrated rail infrastructure and standalone industrial deployments. Component specification, voltage architecture, and installation methodology each reshape supplier qualification requirements and contract profitability across these distinct demand clusters.
System Type:
Standalone AC and DC architectures serve established rail corridors with dedicated electrical substations, while hybrid and high-voltage systems embed into transitional or specialized infrastructure requiring interoperability across voltage zones.
- AC:25kV alternating current configurations deliver power through standard European mainline electrification protocols. Deutsche Bahn's corridor modernization concentrates demand for AC catenary across Germany's Rhine-Alpine freight routes, where KBA interoperability mandates enforce strict rolling stock compatibility testing.
- Hybrid:Dual-voltage architectures bridge legacy 750V DC tram networks with modern AC traction standards. Belgian and Czech urban operators deploy these systems to extend electrified reach without wholesale infrastructure replacement, though engineering complexity dilutes standardization benefits.
- DC:Direct current systems at 750V and 1500V serve dense urban tramway networks with frequent stops and regenerative braking cycles.
- High-Voltage:Elevated voltage configurations above 25kV address heavy-haul mining corridors and alpine freight routes with extended substation spacing.
Volume placements concentrate in AC; the faster expansion belongs to Hybrid.
Component:
Margin distribution across component categories tracks metallurgical complexity and regulatory compliance burden rather than unit volume alone.
- Catenary Wires:Copper and copper-alloy contact wires carry continuous electrical supply to pantograph collectors. REACH substance restrictions and conflict-free copper sourcing mandates from ECHA extend procurement lead times for non-European suppliers serving French and German markets.
- Support Structures:Cantilever arms and portal frames suspend messenger wire assemblies above track infrastructure. Carbon fiber composite variants specified by Network Rail and Banedanmark for Scandinavian coastal routes command premium positioning against salt-corrosion degradation of galvanized steel alternatives.
- Insulators:Polymer and ceramic housings isolate energized conductors from grounded support elements.
- Feeders:Distribution cables transmit substation output to catenary contact wires across extended corridor distances.
Revenue pools concentrate in Catenary Wires; Insulators face the steepest compliance cost escalation.
Application:
End-use concentration determines contract scale, with national rail operators anchoring large-project procurement while fragmented industrial users demand modular deployment flexibility.
- Rail Transport:Mainline passenger and freight corridors require continuous electrification with redundancy protocols for high-availability service. PKP PLK's Polish corridor program targets extensive new electrification, concentrating demand for cantilever assemblies and auto-tensioning devices through 2030.
- Tramway Systems:Urban light rail networks operate at lower voltages with frequent acceleration cycles and tight curvature geometry. Spanish, Italian, and Dutch municipal authorities now bundle catenary-signaling contracts, expanding addressable scope beyond traditional mainline operators.
- Mining Operations:Heavy-haul extraction corridors in Australia and Chile pilot partial catenary coverage for battery-electric hybrid haulage.
- Industrial Use:Manufacturing facilities and port terminals deploy localized electrification for automated guided vehicles and crane systems.
Contract value concentrates in Rail Transport; Mining Operations are climbing the fastest.
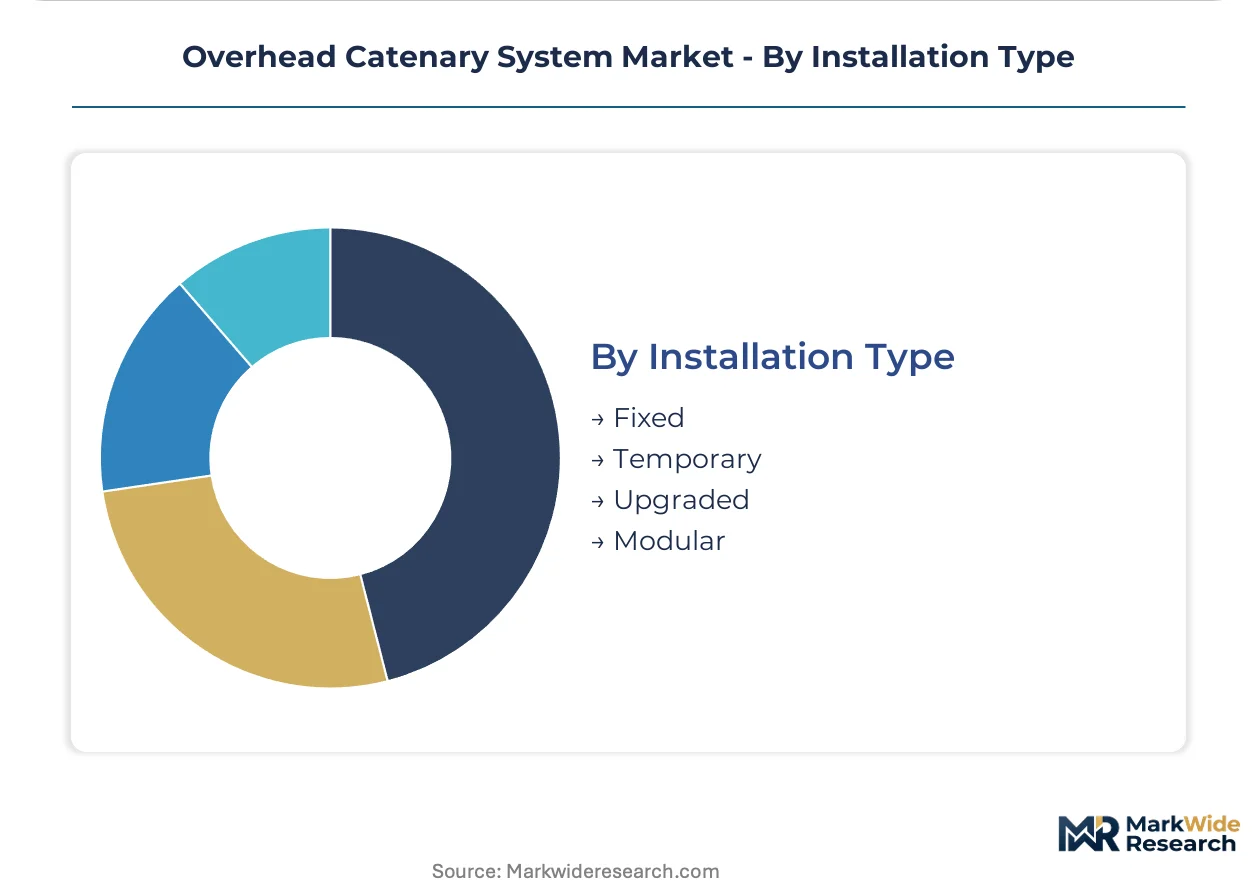
Installation Type:
Deployment methodology shapes supplier capability requirements, distinguishing engineered permanent infrastructure from rapid-response temporary systems.
- Fixed:Permanent installations with poured foundations and anchored masts serve established corridors with predictable traffic volumes. Siemens leverages digital twin-enabled catenary design services to reduce commissioning timelines for complex terrain fixed installations.
- Modular:Prefabricated cantilever and tensioning assemblies enable rapid deployment without specialized on-site fabrication. Mining operators in Chile and Australia specify these systems for phased electrification of heavy-haul routes where traffic patterns remain unproven.
- Temporary:Portable catenary systems support construction phases, maintenance windows, and event-based traffic surges.
- Upgraded:Retrofit installations replace legacy DC infrastructure with AC standards while preserving existing civil works and right-of-way.
Project pipelines concentrate in Fixed; Modular systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail electrification corridors concentrate procurement volumes in Germany, where Deutsche Bahn's corridor programs anchor European demand. Fragmented municipal tramway authorities across Southern Europe and mining operators in South America reshape geographic distribution patterns.
Germany
Deutsche Bahn's Rhine-Alpine freight corridor electrification drives concentrated demand for 25kV AC infrastructure. KBA interoperability mandates enforce strict rolling stock compatibility testing that extends product approval cycles. Engineering clusters in Berlin and Munich host specialized tensioning equipment operators and catenary geometry specialists.
Poland
PKP PLK's priority rail investment program targets extensive new electrification through 2030, creating concentrated demand for cantilever assemblies. EU cohesion funds channel infrastructure investment into cross-border corridor modernization. Industrial activity concentrates in Warsaw and Krakow metropolitan zones where contractor pools execute concurrent installation projects.
France
SNCF Réseau advances high-speed line extensions and legacy route electrification under decarbonization mandates. ECHA's SCIP database requirements for substance traceability restructure supply chain documentation obligations. Lyon and Lille corridor hubs anchor procurement for hybrid traction systems bridging regional networks.
China
MIIT-issued GB standards govern high-voltage catenary performance specifications for extreme climate zone deployments. State-backed railway construction corporations sustain manufacturing scale through captive steel and copper processing capabilities. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate domestic electrification project execution.
Australia
Mining haulage operators in Western Australia and Queensland pilot partial catenary coverage for battery-electric hybrid heavy transport corridors. Modular rapid-deployment overhead systems address unproven traffic patterns across phased electrification routes. Perth and Brisbane engineering offices coordinate specialized installation labor for remote site deployments.
Overhead Catenary System Market Competitive Environment
European producers anchor the integrated systems tier; Chinese fabricators hold manufacturing scale advantages through captive material processing. Market structure exhibits tiered consolidation with national rail operator relationships concentrating around full-service electrification portfolios. Three archetypes dominate: integrated signaling-electrification providers, component-specialized wire manufacturers, and mining-focused modular system deployers. Competitive moves center on digital twin-enabled design service expansion and carbon fiber composite cantilever qualification for coastal corrosion environments.
Among European integrated providers, Alstom and Siemens occupy positions exemplifying full-service electrification portfolio anchoring. Alstom represents the signaling-catenary bundling archetype across high-speed corridor deployments. Siemens sits within the digital twin-enabled commissioning tier, reducing field calibration timelines through physics-based simulation capabilities. CREC anchors Chinese manufacturing scale advantages through upstream control over steel and copper component production for emerging market project cost positioning.
| Leading Market Players |
|---|
| Alstom |
| Cobra |
| CRCC |
| Colas Rail |
| Tianjin Keyvia |
| CREC |
| Engie Ineo |
| Kummler+Matter |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Specialized tensioning equipment operators concentrated in Central European contractor pools create labor-cost differentials that widen pricing spreads between premium integrated deployments and economy modular installations. German engineering clusters anchor high-value fixed-system pricing, while emerging market projects absorb lower-cost installation methodologies.
Pricing Analysis
Volume concentrates in standard AC catenary wire shipments while margins pool in precision tensioning hardware and carbon fiber composite cantilever arms. Three-tier pricing structure across premium, standard, and economy levels separates KBA-certified German corridor deployments from Polish modernization contracts and Chilean mining modular systems. Cost compression in standard copper-alloy contact wire is intensifying because LME price volatility exposes fixed-price contract profitability. Municipal tramway authorities in Southern Europe exhibit highest price sensitivity, while Deutsche Bahn's corridor programs demonstrate lowest sensitivity given interoperability mandates and availability guarantee requirements.
Supply Chain Analysis
Refurbishment flows for tensioning devices and auto-tensioning hardware concentrate service revenue with vendors maintaining regional depot networks. Manufacturing gravity centers on China, Germany, and Poland, with CREC's captive steel and copper processing capabilities anchoring cost positioning for emerging market projects. High-purity copper cathode, carbon fiber composite feedstock, and silicone-based insulator polymers constitute critical input dependencies. Single-source vulnerability in specialized catenary geometry engineering talent creates bottleneck risk for concurrent corridor electrification programs. Distribution runs through national rail operator procurement frameworks and mining conglomerate direct contracts, with bundled catenary-signaling packages expanding addressable scope.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH compliance burdens and KBA interoperability certification timelines force capital-constrained component suppliers toward acquisition or exit.
For Market Incumbents: Hedge copper price exposure through long-term cathode supply agreements with Chilean and Zambian mining operators. Expand digital twin-enabled commissioning capabilities to compress field calibration timelines on mountainous terrain projects, defending margin position against pure equipment manufacturers lacking physics-based simulation assets.
For New Entrants and Emerging Players: Launch via modular rapid-deployment systems targeting Australian and Chilean mining haulage corridors where traffic patterns remain unproven and incumbent integrated providers lack specialized installation labor for remote site deployments. Prioritize battery-electric hybrid traction pilot programs as the most penetrable white-space segment.
For Investors and Strategic Acquirers: Re-rating potential sits with carbon fiber composite cantilever specialists given Network Rail and Banedanmark coastal corrosion specifications driving material substitution. Long-term viability favors producers with in-house polymer compounding capabilities to absorb REACH compliance overhead. Monitor PKP PLK electrification award timelines as inflection indicator for Central European demand concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Cathode Supply | CREC's captive processing capabilities lower component costs for emerging market projects. |
| Digital Twin Commissioning Capability Buildout | Siemens reduces field calibration time through physics-based pantograph-wire interaction simulation. |
| Carbon Fiber Composite Cantilever Qualification | Network Rail specifications enable premium positioning against salt-corrosion degradation of steel alternatives. |
| Performance-Based Maintenance Contract Transition | Stockholm's SL and Amsterdam's GVB transfer operational risk to electrification contractors with remote diagnostic assets. |
| Hybrid Traction System Engineering Investment | Belgian and Czech urban operators bridge legacy 750V DC infrastructure with modern AC traction standards. |
Study Parameters
Independent corroboration across catenary system procurement directors at national rail operators, electrification engineering leads at municipal tramway authorities, mining haulage operations managers, tensioning equipment specialists, and polymer compounding technical directors underwrites the qualitative findings. Primary interview data triangulates against Deutsche Bahn corridor investment disclosures, PKP PLK priority rail program documentation, ECHA SCIP database structure specifications, and LME copper price series. Bottom-up segment sizing and top-down macro validation converge across the analysis window.
Rate-of-change decomposition separates electrification mandate acceleration effects from copper price volatility impacts and labor scarcity constraints across the projection horizon. The analytical framework models system type, component category, application, and installation methodology dimensions alongside voltage architecture and regional regulatory cluster segmentation. CAGRs derive from corridor-level procurement pipeline aggregation and mining operator pilot program scaling assumptions, with climate zone performance specifications and interoperability certification timelines as industry-specific forecast inputs.
Copper price volatility, specialized installation labor availability, and REACH substance restriction scope expansion are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding electrification program execution timelines and mining operator adoption curves for partial catenary coverage. Practitioners should monitor corridor award announcements, ECHA restriction roadmap updates, and LME forward curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Radiator Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
China-Europe Rail Freight Transport Market