
 China-Europe Rail Freight Transport Market | 2026-2036
China-Europe Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
China-Europe Rail Freight Transport Market Outlook
Intermodal service bundling is consolidating around fixed-schedule block trains with guaranteed slot commitments. Deutsche Post DHL Group leverages its European terminal network to control last-mile handoffs from Polish rail hubs. China Railway Corporation anchors eastbound capacity through direct ownership of trunk line infrastructure across the Kazakhstan corridor. Sinotrans Limited specializes in consolidating SME cargo into scheduled departures from Xi'an and Chengdu.
China-Europe rail freight transport denotes scheduled container movement on standard-gauge and broad-gauge networks spanning approximately 11,000 kilometers, typically requiring bogie exchanges at Kazakhstan-Russia borders due to track gauge differentials. The primary commercial purpose is to deliver manufactured goods and industrial components between Chinese production centers and European distribution hubs at transit times intermediate between ocean freight and air cargo. Full Container Load services dominate westbound volumes, while Less than Container Load offerings attract smaller shippers seeking predictable lead times without vessel chartering complexity. GPS Tracking and Cloud Solutions segments are expanding fastest as shippers demand real-time visibility across multiple national rail operators.
China's MIIT and SAMR coordinate cross-border rail standards with Kazakhstan's national railway regulator and the EU's ERA through the Intergovernmental Organisation for International Carriage by Rail. REACH and China's GB standards jointly govern hazardous materials documentation, while the EU F-Gas Regulation affects refrigerated container certification for eastbound chemical and pharmaceutical cargo. Stakeholders must monitor gauge conversion investments and customs pre-clearance pilots to assess which corridors will capture incremental volume shifts from maritime alternatives.
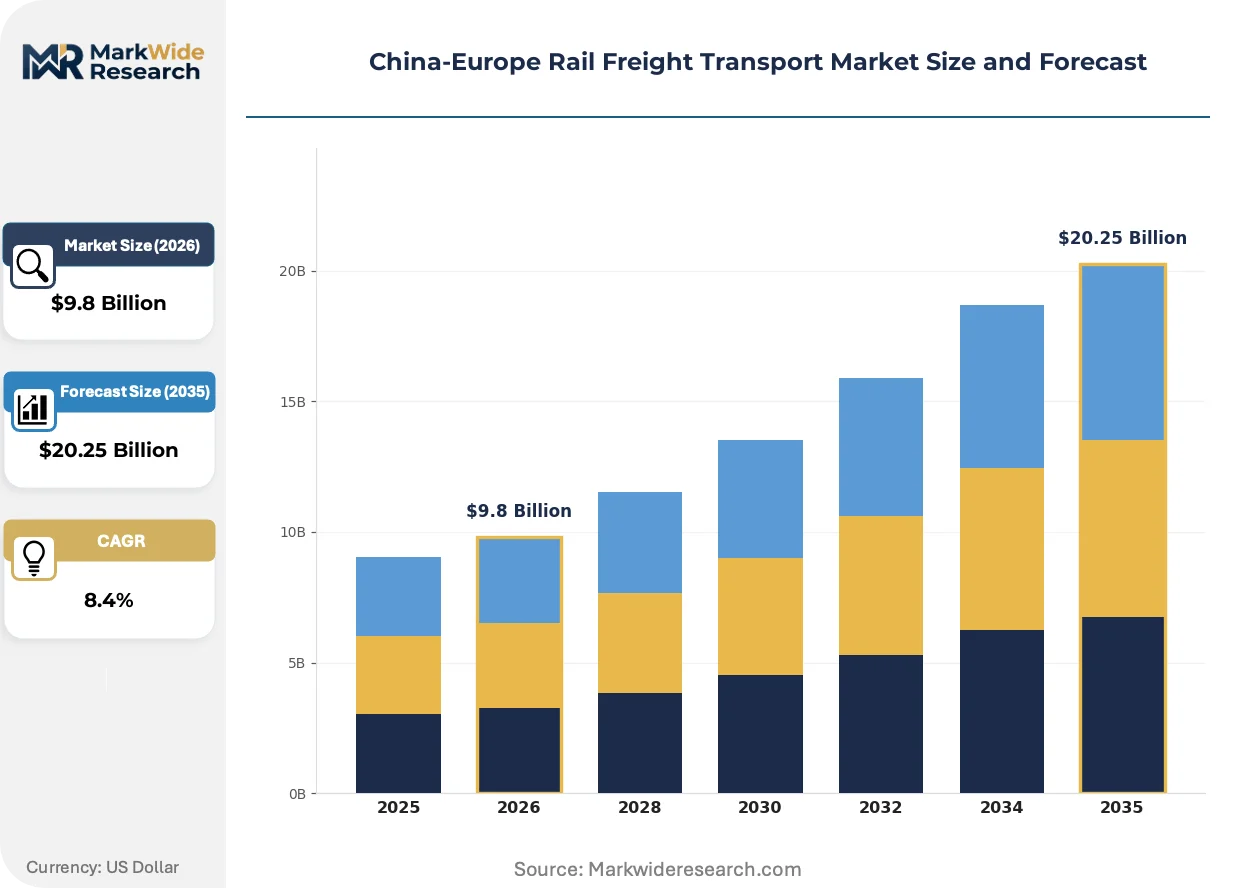
Market Dynamics
The China-Europe rail freight market is compressing around fixed-schedule block trains as shippers abandon flexible routing in favor of guaranteed slot commitments and predictable lead times.
Growth Catalysts
- E-commerce cargo consolidation:Cross-border platforms are diverting high-value consumer electronics from air freight to scheduled rail departures. Westbound container volumes from Xi'an and Chengdu now carry substantial last-mile inventory for European distribution centers.
- EU Green Deal compliance pressure:The EU's emissions trading scheme and carbon border adjustment mechanism are penalizing maritime shippers with heavy fuel oil exposure. Rail freight offers measurable CO2 reductions that satisfy corporate sustainability reporting under CSRD.
- GPS-IoT integration:Real-time tracking platforms are eliminating information asymmetries across Kazakh, Russian, Belarusian and Polish national rail operators. Shippers now demand cloud-based visibility as a standard service component.
Market Restraints
- Bogie exchange bottlenecks:The 1,520mm/1,435mm gauge differential at Dostyk and Brest forces mechanical reloading or axle swaps. These technical stops add 18-24 hours to nominal transit times and concentrate disruption risk at border infrastructure.
- Diesel locomotive dependency:Electrification gaps across the Kazakh steppe and Russian trunk segments expose operators to fuel price volatility. The Trans-Siberian corridor retains substantial diesel-hauled segments despite Chinese electrification standards.
- Sanctions-driven corridor fragmentation:Financial restrictions on Russian rail entities are forcing volume shifts toward the Middle Corridor via Kazakhstan-Azerbaijan-Georgia-Turkey. This southern routing extends transit distances and fragments capacity planning.
Strategic Opportunities
- Polish hub expansion:Małaszewicze and Sławków terminals are adding dedicated e-commerce sorting facilities. These investments position Poland as the primary European deconsolidation point for China-origin container flows.
- Refrigerated pharmaceutical corridors:Temperature-controlled block trains for active pharmaceutical ingredients are opening under EU F-Gas Regulation compliance frameworks. This segment commands premium pricing against air freight alternatives.
- Digital customs pre-clearance:China's SAMR and Kazakhstan's customs authority are piloting blockchain-based documentation exchange. Successful deployment would compress dwell times at Alashankou and Khorgos gateways.
Industry Challenges
- Multimodal coordination complexity:Synchronizing Chinese trunk rail schedules with European last-mile trucking requires precision in Polish terminal handoffs. Deutsche Post DHL Group and other integrators struggle with dwell time variability at Małaszewicze.
- Cross-border certification fragmentation:REACH documentation for chemical cargoes, GB standards for Chinese-origin hazardous materials, and ERA technical approvals for rolling stock create compliance layering. Each additional jurisdiction adds documentation burden without harmonized digital submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China-Europe Rail Freight Transport Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Container Load, Less than Container Load, Intermodal Services, Transit Services End User: Manufacturers, Retailers, E-commerce, Logistics Providers Technology: GPS Tracking, RFID, Automated Systems, Cloud Solutions Packaging Type: Standard Containers, Refrigerated Containers, Specialized Equipment, Bulk Packaging |
| Companies Covered | DSV A/S, Kerry Logistics Network, China Railway Corporation, Russian Railways (RZD), Crane Worldwide Logistics, Deutsche Post DHL Group, Kuehne + Nagel, Sinotrans Limited, DB Cargo (Deutsche Bahn AG), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China-Europe Rail Freight Transport Market Strategic Shifts
Digital infrastructure investments are compressing information asymmetries across the 11,000-kilometer corridor, while regulatory pressure and buyer behavior shifts are reconfiguring service bundling and capacity allocation.
Telematics platforms integrating GPS, temperature sensors and customs documentation are unifying visibility across Chinese, Kazakh, Russian, Belarusian and Polish rail networks. Pharmaceutical and automotive shippers are mandating these systems as baseline requirements. The technology is unifying previously fragmented national operator data into single-dashboard interfaces that compress claims resolution and exception management.
China's dual carbon goals and the EU Green Deal are tightening emissions disclosure requirements for cross-border freight corridors. The EU F-Gas Regulation now governs refrigerated container certification, forcing reefer fleet upgrades. Chemical and pharmaceutical eastbound cargoes face heightened scrutiny, with operators investing in electric shore power and low-GWP refrigeration units to maintain corridor access.
Shippers are consolidating procurement around annual slot commitments rather than spot market flexibility. Large automotive and electronics manufacturers now contract directly with China Railway Corporation for dedicated block train capacity. This concentration is visible most acutely in the Xi'an-Duisburg corridor, where fixed-schedule services have displaced ad hoc routing for high-value industrial components.
China-Europe Rail Freight Transport Market Segmentation
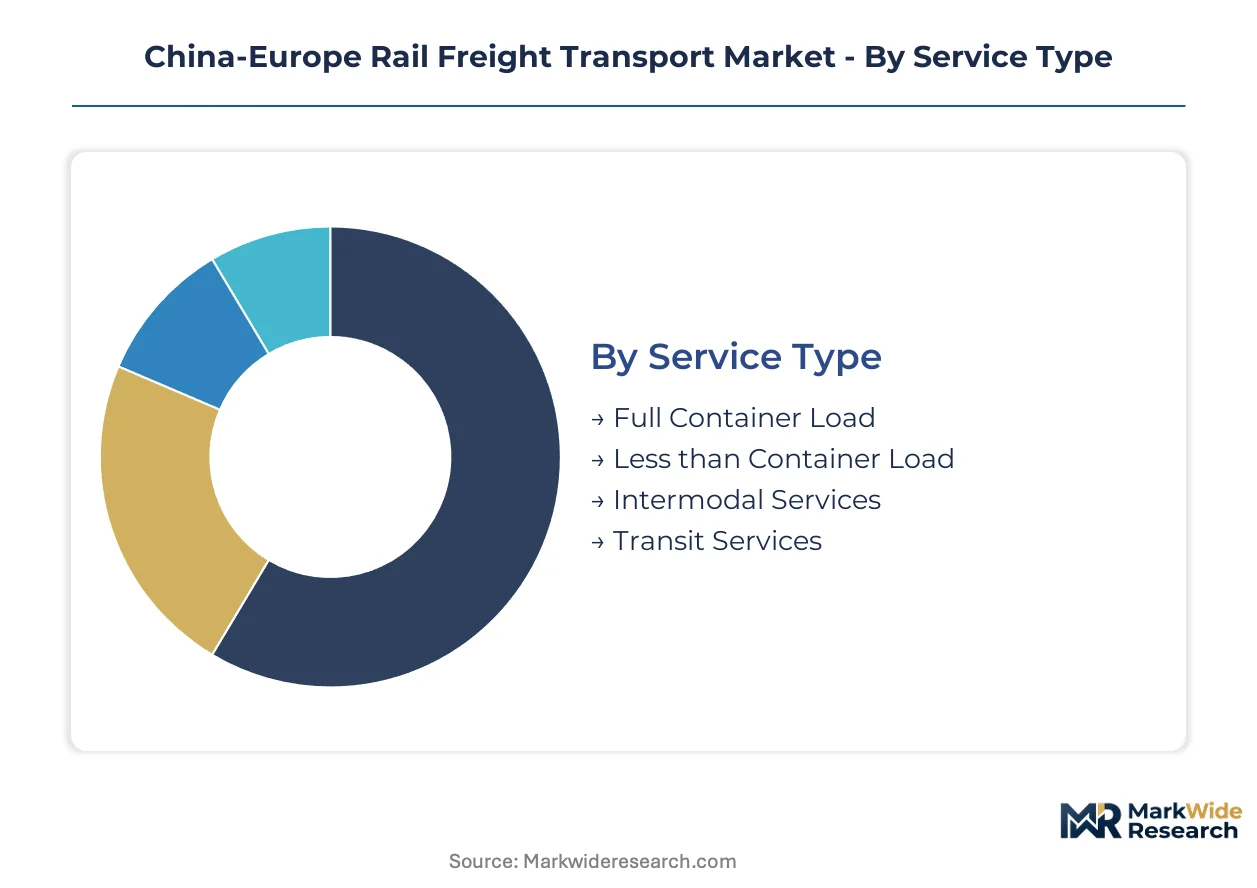
Shippers select rail freight services based on cargo scale, visibility requirements, and temperature sensitivity across the 11,000-kilometer corridor. Segmentation reveals where premium pricing commands sustainable margins versus commodity competition.
Service Type:
Procurement decisions hinge on cargo scale certainty and schedule reliability rather than routing flexibility.
- Full Container Load:Dedicated container capacity for single-shipper volumes moving automotive components and industrial machinery. Westbound flows from Xi'an and Chengdu concentrate here as manufacturers seek locked-in departure slots without consolidation delays.
- Less than Container Load:Consolidated cargo from multiple SME shippers sharing container space. Sinotrans Limited and similar operators aggregate fragmented demand into scheduled departures, attracting retailers unable to fill standalone units.
- Intermodal Services:Bundled rail-truck coordination with guaranteed last-mile handoffs. Deutsche Post DHL Group leverages Polish terminal networks to control European distribution from Małaszewicze railheads.
- Transit Services:Cross-border forwarding through Kazakhstan-Russia-Belarus corridors with bogie exchange handling. Demand shifts toward Middle Corridor alternatives via Azerbaijan-Georgia-Turkey amid sanctions fragmentation.
Volume sits with Full Container Load; growth tilts toward Intermodal Services.
End User:
Customer scale determines contract structure, with large manufacturers commanding dedicated block trains while smaller shippers accept consolidation terms.
- Manufacturers:Automotive and electronics producers contracting annual capacity directly with China Railway Corporation. These shippers prioritize transit time predictability over per-container cost minimization for just-in-line supply chains.
- E-commerce:Cross-border platforms diverting consumer electronics from air freight to scheduled rail. Xi'an and Chengdu departures now carry substantial inventory for European fulfillment centers seeking faster replenishment than ocean freight permits.
- Retailers:Department stores and specialty chains sourcing seasonal merchandise through LCL consolidations. These buyers accept longer lead times in exchange for avoiding vessel chartering complexity.
- Logistics Providers:Third-party forwarders purchasing capacity for resale to shipper clients. These intermediaries absorb demand volatility and aggregate fragmented cargo into trainload quantities.
Manufacturers anchor current volume; e-commerce climbs the fastest as platform logistics integrate rail into omnichannel fulfillment.
Technology:
Visibility infrastructure now functions as competitive table stakes rather than premium add-on.
- GPS Tracking:Real-time location monitoring across Chinese, Kazakh, Russian, Belarusian and Polish rail networks. Pharmaceutical and automotive shippers mandate these systems for exception management and claims resolution.
- Cloud Solutions:Unified dashboards integrating data from multiple national operators into single interfaces. These platforms compress information asymmetries that previously delayed customs clearance and handoff coordination.
- RFID:Automated container identification at border gateways and terminal yards. Deployment concentrates at Dostyk, Brest, and Polish hub facilities to accelerate gauge exchange and customs processing.
- Automated Systems:Robotic handling and smart yard management at major terminals. Chinese electrified trunk lines deploy these technologies more extensively than diesel-dependent Kazakh and Russian segments.
GPS Tracking dominates current installations; Cloud Solutions gain share fastest as shippers demand unified visibility across fragmented national networks.
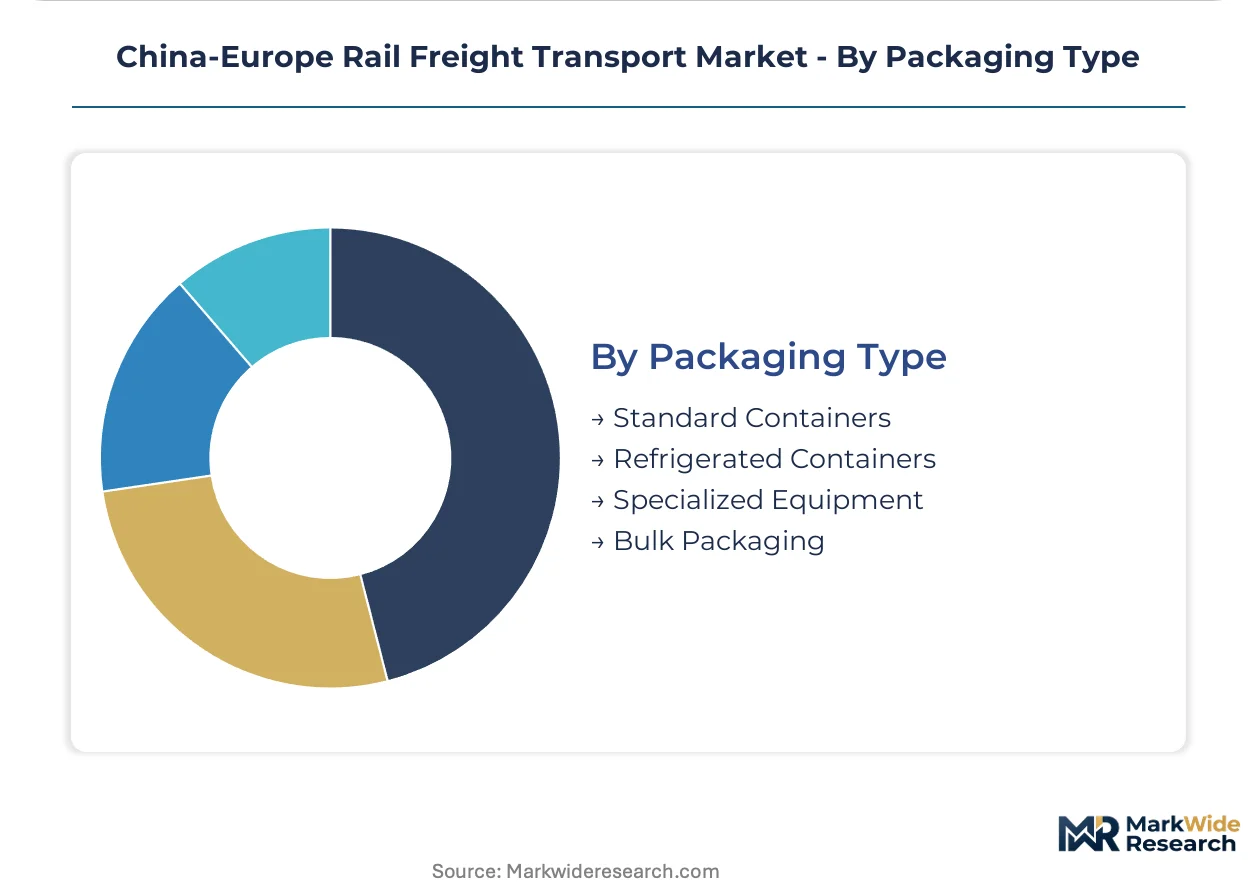
Packaging Type:
Temperature control and cargo security requirements drive equipment selection and pricing differentiation.
- Standard Containers:Dry van units for manufactured goods and non-perishable components. These units constitute the baseline fleet across all major corridors with minimal regulatory complexity.
- Refrigerated Containers:Temperature-controlled units governed by EU F-Gas Regulation certification requirements. Active pharmaceutical ingredient shipments command premium positioning against air freight alternatives.
- Specialized Equipment:Open-top, flat-rack, and tank containers for oversized machinery and liquid chemicals. REACH documentation and GB standards jointly govern hazardous materials certification for these units.
- Bulk Packaging:Commodity flows in hopper cars and gondolas for raw materials and agricultural products. Eastbound volumes from Europe concentrate here for Chinese industrial input supply.
Standard Containers hold volume concentration; refrigerated units expand most quickly under pharmaceutical corridor development and emissions compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters generate westbound container volumes, while European distribution hubs concentrate deconsolidation demand. Poland functions as the primary European gateway, absorbing rail arrivals for redistribution across the continent.
China
Xi'an and Chengdu dispatch fixed-schedule block trains carrying automotive components and consumer electronics. MIIT coordinates cross-border rail standards with Kazakhstan's national railway regulator. The Sichuan-Chongqing economic circle anchors westbound capacity through direct state investment in trunk line infrastructure.
Kazakhstan
Dostyk and Khorgos border terminals handle gauge conversion for 1,520mm to 1,435mm transitions. The country's customs authority pilots blockchain-based documentation exchange with China's SAMR. Almaty-based logistics clusters coordinate Middle Corridor routing via Azerbaijan-Georgia-Turkey as sanctions fragment northern alternatives.
Poland
Małaszewicze and Sławków terminals add dedicated e-commerce sorting facilities for China-origin container flows. EU F-Gas Regulation governs refrigerated container certification for pharmaceutical cargo passing through these hubs. Warsaw logistics zones coordinate last-mile trucking handoffs under CSRD emissions disclosure requirements.
Germany
Duisburg and Hamburg absorb block train arrivals for redistribution into European industrial supply chains. Deutsche Bahn AG operates DB Cargo services connecting Polish railheads to German manufacturing centers. Bavaria-based automotive producers contract annual capacity directly for just-in-time component delivery.
Russia
The Trans-Siberian corridor retains substantial diesel-hauled segments despite electrification gaps. Financial restrictions on Russian rail entities are forcing volume shifts toward southern alternatives. Belarus-Poland border infrastructure at Brest concentrates disruption risk from gauge exchange bottlenecks.
China-Europe Rail Freight Transport Market Competitive Environment
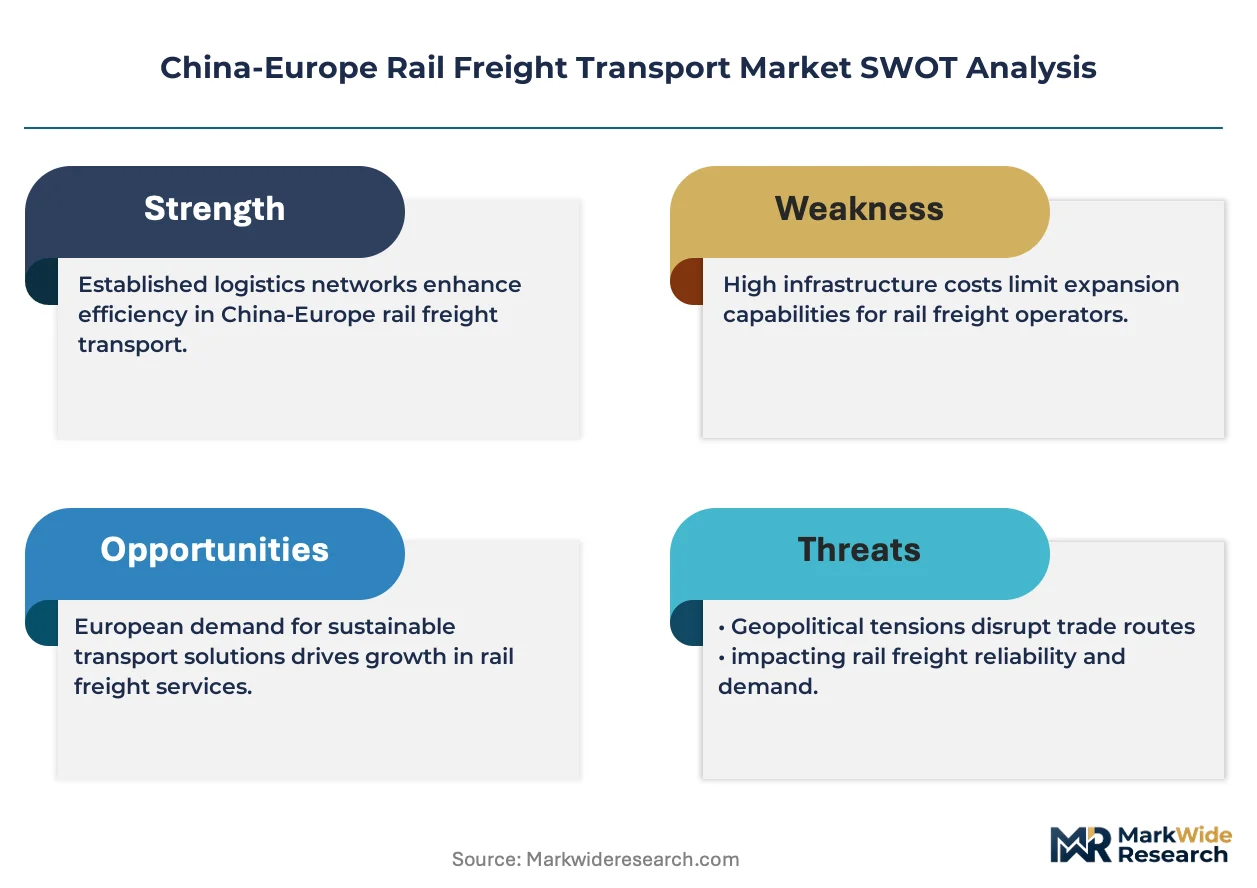
Top-tier vendors anchor trunk line infrastructure and terminal networks, while mid-tier forwarders aggregate fragmented SME demand into trainload quantities. State-owned rail incumbents control gauge-conversion corridors and cross-border scheduling coordination. Strategic archetypes include integrated European logistics networks, Chinese state rail operators, and intermodal consolidators. Competitive moves concentrate on Polish hub expansion and digital customs pre-clearance partnerships.
Within the integrated logistics tier, Deutsche Post DHL Group and Kuehne + Nagel exemplify European operators leveraging terminal control for last-mile coordination. China Railway Corporation anchors the state-operator archetype through direct infrastructure ownership across the Kazakhstan corridor. Sinotrans Limited occupies a position among consolidators specializing in scheduled departures from Chinese manufacturing clusters.
| Leading Market Players |
|---|
| DSV A/S |
| Kerry Logistics Network |
| China Railway Corporation |
| Russian Railways (RZD) |
| Crane Worldwide Logistics |
| Deutsche Post DHL Group |
| Kuehne + Nagel |
| Sinotrans Limited |
| DB Cargo (Deutsche Bahn AG) |
| Others |
Value Chain & Pricing Dynamics
Automotive and electronics manufacturers contracting annual block train capacity dominate pricing power through locked-in slot commitments rather than spot market flexibility. Their procurement concentration around fixed-schedule departures from Xi'an and Chengdu compresses margin capture for operators unable to secure long-term offtake agreements.
Pricing Analysis
Margin tightening in Less than Container Load services traces to Sinotrans Limited and consolidators competing for fragmented SME cargo with minimal differentiation beyond schedule reliability. Three-tier pricing structure across premium refrigerated pharmaceutical corridors, standard dry container industrial flows, and economy-grade bulk commodity shipments governs contract structures. Cost compression in spot market segments accelerates because sanctions-driven corridor fragmentation forces capacity shifts toward extended Middle Corridor routings. Manufacturers exhibit lowest price sensitivity due to just-in-time supply chain requirements, while retailers sourcing seasonal merchandise through LCL arrangements demonstrate highest elasticity to per-container rates.
Supply Chain Analysis
Freight cost volatility concentrates around diesel-dependent segments across the Kazakh steppe and Russian trunk lines where electrification gaps expose operators to fuel price swings. Supply concentration centers on China for manufacturing origination, Kazakhstan for gauge conversion infrastructure, and Poland for European distribution hubbing. Rolling stock components, locomotive fuel, and container equipment feed from industrial supply chains in Germany, China, and Russia. Single-source vulnerability sits with Dostyk and Brest border terminals where bogie exchange bottlenecks create 18-24 hour mechanical delays. Distribution runs through Polish railheads at Małaszewicze and Sławków for last-mile trucking handoffs across the continent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Block train slot scarcity at Polish gateway terminals props pricing power for operators with committed annual capacity, constraining volume growth to infrastructure expansion rates rather than demand curves.
For Market Incumbents: Deepen terminal control at Małaszewicze and Sławków through dedicated e-commerce sorting facility investments that capture deconsolidation margin from China-origin flows. Anchor capacity commitments with China Railway Corporation for eastbound trunk line access, insulating against Middle Corridor volume shifts triggered by sanctions on Russian rail entities. Prioritize refrigerated container fleet upgrades under EU F-Gas Regulation compliance to maintain pharmaceutical corridor premium positioning against air freight alternatives. For New Entrants and Emerging Players: EU Green Deal emissions disclosure requirements under CSRD open a window for digital visibility platforms integrating GPS-IoT tracking across Kazakh, Russian, Belarusian and Polish national rail networks. Target cloud-based customs documentation solutions for the SME shipper segment where Sinotrans Limited currently dominates LCL consolidation with minimal technology differentiation. Pursue blockchain-based pre-clearance pilots with Kazakhstan's customs authority and China's SAMR as a go-to-market wedge against incumbent forwarders. For Investors and Strategic Acquirers: The window for entry favors intermodal consolidators with established Chinese manufacturing cluster relationships and Polish terminal access agreements. Long-term viability hinges on corridor diversification capability as sanctions fragmentation accelerates Middle Corridor development through Azerbaijan-Georgia-Turkey routings. Monitor gauge conversion investment announcements at Alashankou and Khorgos as inflection indicators for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Polish Hub Terminal Expansion | Małaszewicze and Sławków investments capture e-commerce deconsolidation margin from China-origin block trains. |
| Refrigerated Fleet Certification Upgrade | EU F-Gas Regulation compliance maintains pharmaceutical corridor access against premium air freight alternatives. |
| Digital Customs Pre-clearance Deployment | Blockchain documentation exchange with SAMR and Kazakhstan customs compresses dwell times at border gateways. |
| Middle Corridor Capacity Diversification | Azerbaijan-Georgia-Turkey routing builds resilience against sanctions-driven fragmentation of northern corridors. |
| Annual Slot Commitment Structuring | Fixed-schedule contracts with automotive manufacturers lock in predictable revenue streams against spot volatility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with rail operations managers, intermodal forwarders, terminal operators, and automotive procurement leads. Bottom-up volume modeling from corridor-specific container flow data combined with top-down market sizing from MIIT and ERA regulatory disclosures. Secondary sources included China Railway Corporation scheduling publications, Polish terminal throughput statistics, EU F-Gas Regulation implementation guidance, and Kazakhstan national railway customs pilot documentation.
Data-stream reconciliation across shipper contract structures, operator capacity disclosures, and terminal expansion announcements informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompass service type, end user vertical, technology deployment, and packaging requirements across the corridor network. CAGRs derived from trend extrapolation of fixed-schedule block train deployments, e-commerce cargo diversion rates from air freight, and refrigerated pharmaceutical corridor development. Forecast inputs included gauge conversion infrastructure investment pipelines and diesel-to-electric locomotive transition timelines.
The model assumes a particular technology adoption path for GPS-IoT integration and cloud-based visibility platforms; alternative pathways for blockchain customs documentation or automated gauge exchange systems would alter the outlook for transit time compression and corridor competitiveness. Forecasts reflect assumptions regarding sanctions stability, EU emissions regulation enforcement intensity, and Chinese state rail investment continuity. Stakeholders should weight assumptions against their own operating context and corridor-specific risk exposures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Brazil Rail Freight Transport Market