
 Automotive Wiring Harness Market | 2026-2036
Automotive Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wiring Harness Market Intelligence
The direct procurement channel from harness specialists to automotive OEMs is narrowing the space for non-specialized intermediaries. This shift favors large-scale suppliers with deep engineering capabilities. Yazaki Corporation leverages its extensive manufacturing footprint to secure long-term contracts. Aptiv PLC differentiates through its advanced technology portfolio in high-voltage and data connectivity solutions, while Lear Corporation sustains its market position through integrated seating and e-systems offerings.
An automotive wiring harness is an engineered assembly of cables, connectors, and terminals that routes power and information throughout a vehicle. These systems are custom-designed for each vehicle platform, using specific gauges of copper or aluminum wire to manage electrical loads and data signals. High-voltage wiring, essential for electric vehicles, is the most dynamic technology segment. Body and chassis wiring harnesses constitute a significant portion of the market, driven by the sheer volume of connections required in modern passenger cars.
Compliance with international standards such as ISO 26262 for functional safety is mandatory for market access. Regulations including the EU's RoHS directive restrict hazardous materials, while vehicle safety rules from bodies like the NHTSA in the United States influence harness durability and fire resistance. Suppliers must continually balance the pressure to reduce weight and cost using materials like aluminum against the stringent performance and safety mandates of global automotive regulators.
Market Dynamics
The transition to electric and software-defined vehicles is the central force shaping the market. This shift elevates the wiring harness from a simple component to a critical, high-voltage, high-data-rate nervous system, demanding new materials and architectures for vehicle operation.
Growth Catalysts
- EV Mandates:Regulations including the EU Green Deal directly stimulate demand for the complex high-voltage harnesses required for electric vehicle powertrains and battery management.
- ADAS Integration:The proliferation of cameras and sensors for driver-assistance systems necessitates sophisticated harnesses capable of high-speed, shielded data transmission.
- Production Nearshoring:Investment in automotive manufacturing hubs in Mexico and Central Europe favors harness suppliers with local production to shorten OEM supply chains.
Market Restraints
- Raw Material Volatility:Price fluctuations in copper and aluminum directly impact harness production costs, creating pricing instability for both suppliers and automotive OEMs.
- Signal Integrity Limits:High-speed data transmission for ADAS faces technical limits from signal degradation and electromagnetic interference, complicating harness design.
- Mass-Complexity Paradox:Adding electronic features increases harness weight, directly conflicting with OEM mandates for vehicle lightweighting to improve overall efficiency.
Strategic Opportunities
- Zonal Architectures:The move to zonal electrical architectures creates demand for modular harness segments, simplifying vehicle assembly and reducing wiring complexity.
- Aluminum Alloy Development:Developing new aluminum alloys for wiring provides a path to meet OEM weight reduction targets without compromising conductivity or durability.
- Commercial Vehicle Electrification:The electrification of commercial trucks in North America and Europe opens a market for highly durable and high-power wiring systems.
Industry Challenges
- High-Voltage Talent Scarcity:A shortage of engineers skilled in high-voltage system design and electromagnetic compatibility constrains new product development for electric vehicles.
- Automation Capex:The high capital cost of automated cutting and testing equipment required for complex harnesses acts as a barrier for smaller suppliers.
- ISO 26262 Compliance:Achieving and documenting compliance with the ISO 26262 functional safety standard is a resource-intensive process for every new vehicle platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wiring Harness Market |
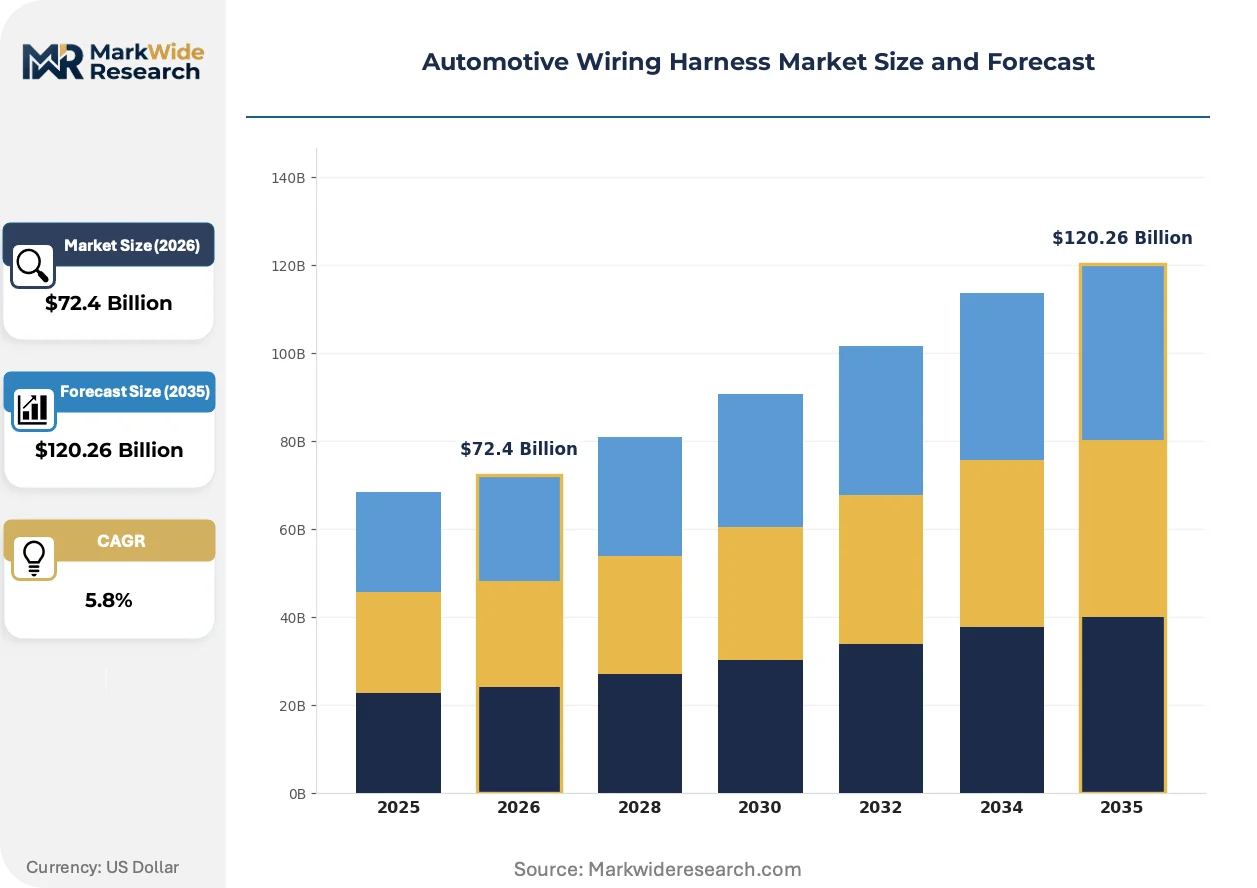
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $120.26 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Wiring Harness, Chassis Wiring Harness, Body Wiring Harness, Transmission Wiring Harness, Dashboard Wiring Harness Technology: Shielded Wiring, Flat Wiring, Digital Wiring, Fiber Optic Wiring, High-Voltage Wiring Application: Passenger Vehicles, Commercial Vehicles, Off-Highway Vehicles, Two-Wheelers, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Auto Repair Shops |
| Companies Covered | Yazaki Corporation, Sumitomo Electric Industries, Aptiv PLC, Lear Corporation, Leoni AG, Furukawa Electric, Fujikura Ltd., THB Group, Kromberg & Schubert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wiring Harness Market Strategic Shifts & Innovations
The industry is undergoing a fundamental re-architecture of the vehicle's nervous system. This evolution is driven by the dual imperatives of managing immense data flows from connected systems and distributing high-voltage power for electric propulsion.
Aluminum wiring serves to reduce vehicle weight and material costs compared to copper. Automakers are steadily adopting it for static, large-gauge power cables to meet efficiency goals. The market's material foundation is migrating from a sole reliance on copper to a hybrid model, demanding new solutions for termination and corrosion prevention.
A complex web of global regulations governs harness design. The EU's RoHS directive restricts hazardous materials, while safety rules from bodies like the NHTSA in the US mandate specific fire resistance and durability properties. The body and chassis harness segment is most affected, forcing suppliers to innovate with compliant materials that do not compromise performance.
Automotive OEMs are altering their purchasing strategies, moving toward sourcing complete electrical distribution systems instead of discrete harnesses. This model favors large, systems-focused suppliers over smaller component specialists. The trend is most visible in North America and Europe, where vehicle platform complexity and integration demands are highest.
Automotive Wiring Harness Market Segmentation
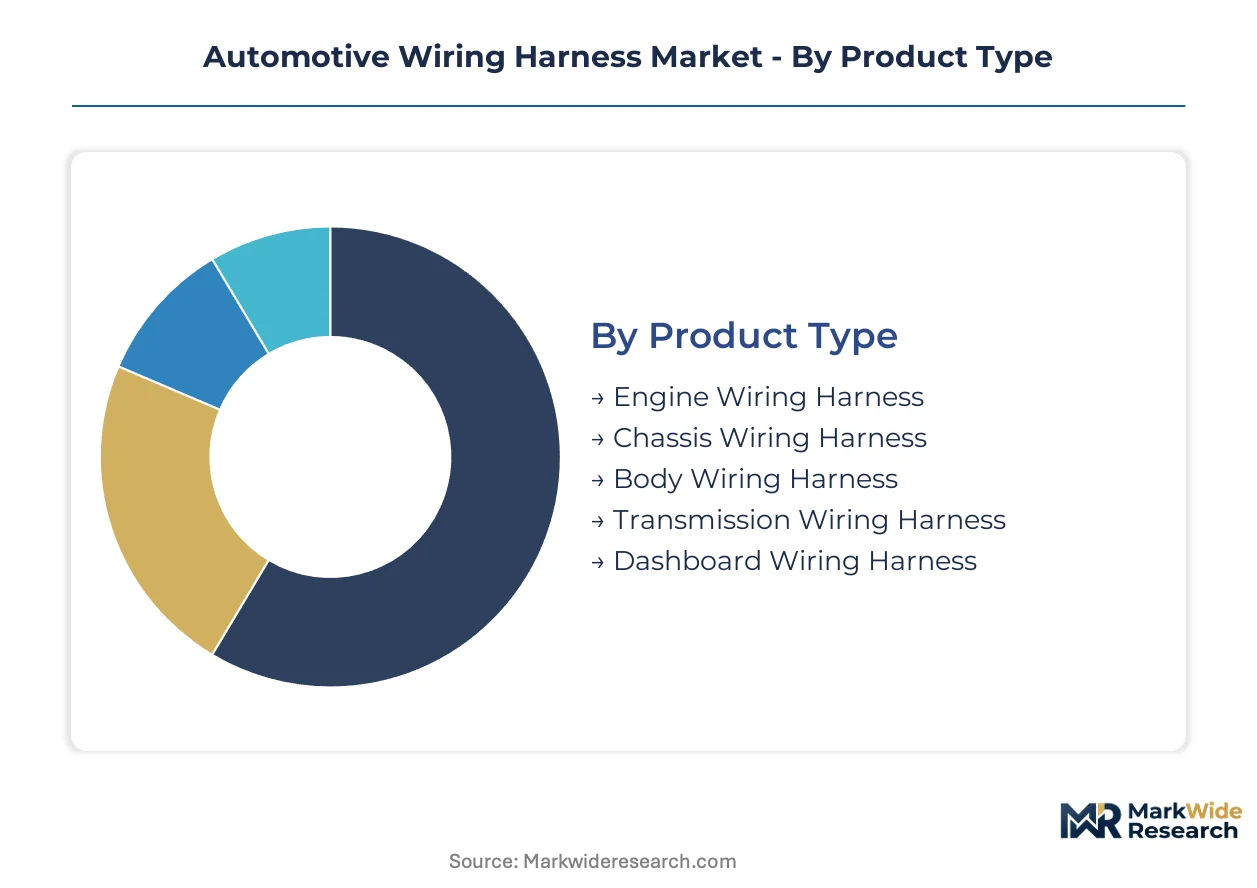
The automotive wiring harness market is functionally diverse, driven by the intricate electrical demands of modern vehicles. Understanding these segmentations helps to clarify where innovation and investment are concentrating, particularly with the transition to electric and software-defined architectures.
Product Type:
The functional classification of wiring harnesses by their installation location defines distinct product types within vehicles.
- Engine Wiring Harness:This harness manages power and data for critical engine components, including fuel injectors, ignition systems, and various sensors. Demand is concentrating in high-performance and hybrid vehicles, where precise engine control systems require robust, high-temperature resistant wiring.
- Body Wiring Harness:This extensive assembly routes power and signals for interior features like lighting, infotainment, power windows, and door locks. The proliferation of electronic features in passenger vehicles, particularly in Europe and North America, drives demand for complex body harnesses.
- Chassis Wiring Harness:This type provides electrical connectivity for underbody components such as braking systems, suspension sensors, and wheel speed sensors. Vehicle safety regulations from bodies like the NHTSA influence the durability and reliability requirements for chassis harnesses.
- Transmission Wiring Harness:This specialized harness connects the transmission control unit to various sensors and actuators within the gearbox. The increasing complexity of automatic and automated manual transmissions mandates precise and durable wiring.
- Dashboard Wiring Harness:This harness integrates the instrument cluster, human-machine interface, and other cabin controls. Advanced digital cockpits and infotainment systems elevate the data transmission requirements for dashboard harnesses.
Body Wiring Harness holds installed capacity. Engine Wiring Harness is rotating up the share rankings.
Technology:
The evolving technological landscape within vehicles necessitates specialized wiring solutions to manage power distribution and data transmission.
- High-Voltage Wiring:Designed for electric vehicle powertrains, this technology handles substantial power loads for battery management and electric motors. Global EV mandates, including the EU Green Deal, directly stimulate demand for high-voltage wiring systems.
- Shielded Wiring:This wiring incorporates a protective layer to prevent electromagnetic interference, crucial for sensitive data transmission in ADAS and autonomous driving systems. The proliferation of cameras and sensors for driver-assistance systems necessitates sophisticated shielded harnesses.
- Flat Wiring:This compact wiring solution offers space-saving benefits and can simplify packaging in constrained vehicle areas. Automakers seek flat wiring to optimize vehicle interior space and reduce overall harness bulk.
- Digital Wiring:Facilitating high-speed data communication, digital wiring supports advanced infotainment systems and vehicle-to-everything (V2X) connectivity. The shift towards software-defined vehicles increases the reliance on digital wiring for network stability.
- Fiber Optic Wiring:Offering superior bandwidth and immunity to electromagnetic interference, fiber optic wiring is emerging for ultra-high-speed data networks within vehicles. Future autonomous driving platforms will increasingly rely on fiber optic technology for sensor data processing.
High-Voltage Wiring is experiencing significant innovation. Shielded Wiring is expanding most quickly in advanced vehicle platforms.
Application:
Vehicle type dictates the complexity and power requirements for wiring harnesses, influencing design and material choices.
- Electric Vehicles:These applications demand robust high-voltage harnesses for battery packs, electric motors, and charging systems, along with advanced data networks. Regulations pushing for greater vehicle electrification, such as those from the US EPA, drive demand for EV-specific harnesses.
- Passenger Vehicles:This segment represents the largest volume, requiring harnesses for diverse functions from basic power to advanced infotainment and safety systems. The constant addition of electronic features in modern cars increases the complexity and length of passenger vehicle harnesses.
- Commercial Vehicles:Applications in trucks and buses require highly durable and robust harnesses capable of withstanding harsh operating conditions and heavy loads. The electrification of commercial trucks in North America and Europe opens a market for high-power commercial vehicle wiring systems.
- Off-Highway Vehicles:This category includes construction, agricultural, and mining equipment, where harnesses must endure extreme environments and vibrations. Specialized sealing and ruggedization are critical for off-highway vehicle harness performance.
- Two-Wheelers:Motorcycles and scooters utilize simpler harness designs, primarily for ignition, lighting, and basic electronic controls. Cost-effectiveness and weather resistance are primary considerations for two-wheeler wiring harnesses.
Electric Vehicles represent the fastest-growing trajectory in harness application. Passenger Vehicles maintain the largest market share.
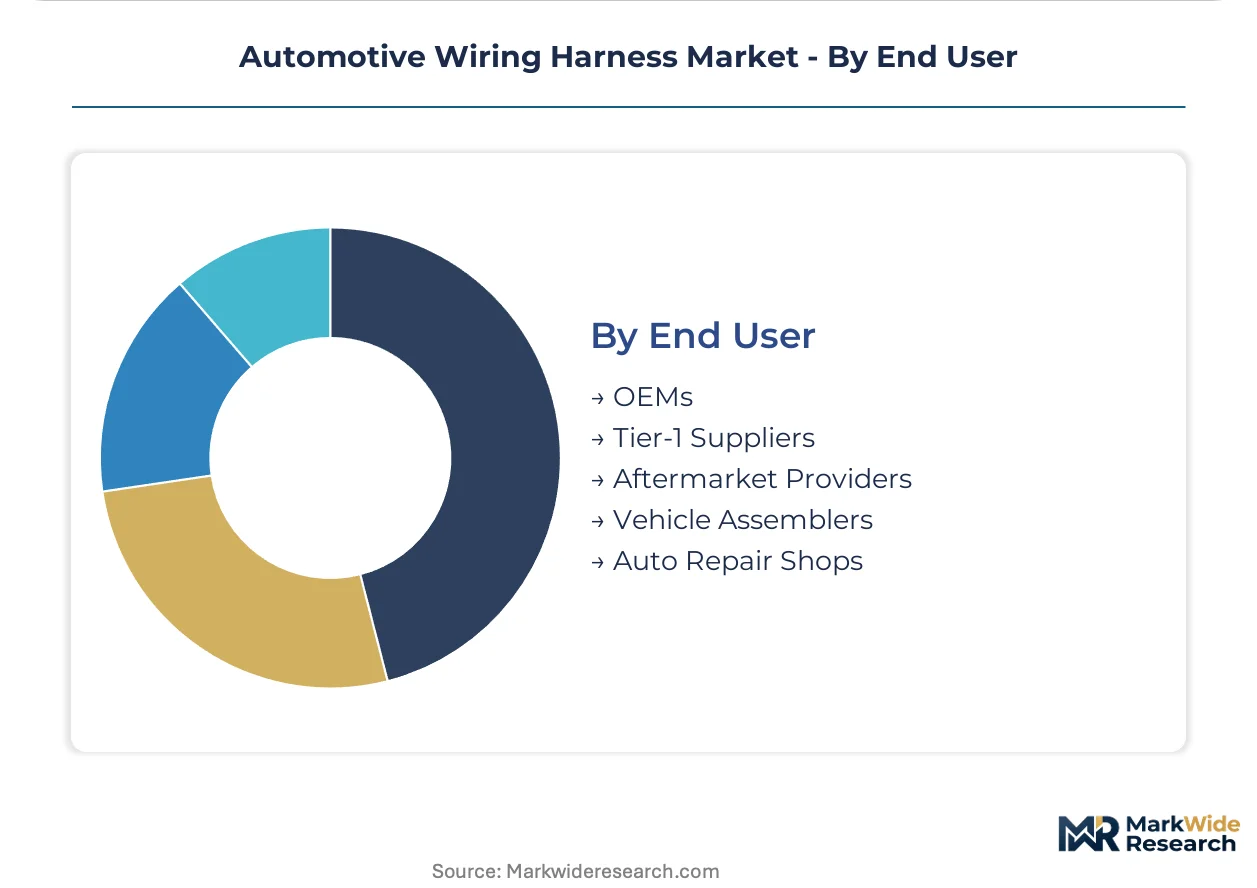
End User:
The distribution channels for wiring harnesses reflect the automotive industry's complex supply chain and aftermarket needs.
- OEMs:Original Equipment Manufacturers procure custom-designed wiring harnesses directly from specialized suppliers for integration into new vehicle production. The direct procurement channel from harness specialists to automotive OEMs is narrowing the space for non-specialized intermediaries.
- Tier-1 Suppliers:These large suppliers integrate harnesses into larger modules or sub-assemblies before delivery to OEMs, often adding value through engineering and system integration. Large-scale suppliers with deep engineering capabilities are favored by OEMs for complete electrical distribution systems.
- Aftermarket Providers:This segment includes companies supplying replacement harnesses or components for vehicle repairs and upgrades. Durability and compatibility with a wide range of vehicle models are important for aftermarket harness providers.
- Vehicle Assemblers:These entities integrate pre-assembled wiring harnesses into the final vehicle structure on the production line. The move to zonal electrical architectures aims to simplify vehicle assembly for vehicle assemblers.
- Auto Repair Shops:These service providers purchase individual harness components or complete assemblies for vehicle maintenance and accident repairs. Availability and cost-effectiveness are key factors for auto repair shops sourcing wiring harness parts.
OEMs dictate the majority of new harness demand. Tier-1 Suppliers are consolidating their position in systems integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive automotive production networks underpin the global automotive wiring harness market, driving demand for specialized electrical systems. These networks facilitate the complex supply chains required for vehicle manufacturing, from component sourcing to final assembly. The electrification push and ADAS integration are reshaping regional demand for advanced harness technologies.
United States
The United States automotive market generates strong demand for high-voltage harnesses in electric vehicles and sophisticated shielded wiring for ADAS. US EPA regulations pushing for greater vehicle electrification directly stimulate this segment. Michigan's automotive corridor, particularly around Detroit, remains a significant hub for vehicle production and R&D, requiring constant innovation in wiring solutions.
Germany
Germany's automotive sector demands advanced high-voltage systems for premium electric vehicles and robust data connectivity solutions for autonomous driving. EU Green Deal regulations strongly influence the adoption of sustainable and efficient harness technologies. Bavaria's automotive cluster focuses on cutting-edge engineering and manufacturing, contributing to the development of next-generation electrical architectures.
China
China's rapid expansion in electric vehicle production drives substantial demand for high-voltage wiring harnesses and digital connectivity solutions. The country's dual carbon goals accelerate EV adoption, mandating advanced electrical systems. Shanghai's numerous EV manufacturing plants and associated supply chains create a concentrated market for specialized harness suppliers.
Japan
In Japan, demand concentrates on sophisticated wiring for hybrid electric vehicles and high-speed data harnesses for advanced driver-assistance features. METI policies support innovation in automotive electronics and lightweight materials. Toyota City's extensive automotive supply chain integrates complex wiring solutions for efficient and reliable vehicle platforms.
Mexico
Mexico benefits from significant nearshoring of automotive production, fueling demand for wiring harnesses for export-oriented vehicle manufacturing. NAFTA/USMCA trade agreements support local production and cross-border supply chains. Querétaro's growing aerospace and automotive cluster attracts harness suppliers, serving regional OEMs with integrated electrical systems.
Automotive Wiring Harness Market Key Industry Players
On the supply side, the industry is characterized by a blend of large, integrated specialists and smaller, niche players. The market structure favors suppliers with extensive engineering capabilities and global manufacturing footprints. Strategic archetypes include global system integrators focused on complete electrical distribution systems and regional component specialists serving specific vehicle platforms. Dominant competitive moves involve strategic partnerships for technology development and continuous investment in capacity expansion to meet OEM nearshoring demands.
Within the global system integrator archetype, Yazaki Corporation and Aptiv PLC exemplify firms leveraging extensive manufacturing footprints and advanced technology portfolios. Yazaki Corporation represents a supplier with broad market reach and long-term OEM contracts. Aptiv PLC, meanwhile, anchors its position through high-voltage and data connectivity solutions for next-generation vehicles. Lear Corporation also sits within this tier, sustaining its market standing through integrated seating and e-systems offerings for diverse vehicle types.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Aptiv PLC |
| Lear Corporation |
| Leoni AG |
| Furukawa Electric |
| Fujikura Ltd. |
| THB Group |
| Kromberg & Schubert |
Cost & Logistics Intelligence
Commodity volatility in copper and aluminum directly impacts harness production costs, influencing pricing tiers and driving supply chain regionalization for stability. This fluctuation shapes supplier investment decisions and OEM procurement strategies.
Pricing Analysis
Volume-discount models characterize automotive wiring harness pricing, rewarding large-scale OEM procurement. Price differentiation stems from customization levels for specific vehicle platforms and the integration of advanced technologies like high-voltage or shielded wiring. Pricing softness impacts standard body and chassis harnesses due to intense competition among suppliers. Electric vehicle applications show less price sensitivity due to their critical safety and performance requirements.
Supply Chain Analysis
Upstream feedstock, primarily copper and aluminum, forms the material foundation for wiring harnesses, sourced globally from major mining regions. Geographic supply concentration for harness manufacturing centers in Mexico, Central Europe, and China due to automotive production hubs. A structural risk is the reliance on a few large-scale raw material suppliers, creating potential for price shocks. Distribution runs through direct procurement channels from harness specialists to OEMs, with Tier-1 suppliers integrating components into larger modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive wiring harness market presents a defensive moat story, largely due to regulatory entrenchment requiring strict compliance with standards like ISO 26262 for functional safety. This creates high barriers to entry for new players.
For Market Incumbents:Insulate core business by investing in advanced manufacturing automation, particularly for high-voltage and shielded harnesses, to counter emerging component supplier threats. Deepen vertical integration into specialized connector and terminal production, addressing potential supply chain bottlenecks. Expand engineering capabilities for zonal architectures to secure long-term contracts with OEMs shifting vehicle platforms. Focus on continuous material innovation, like aluminum alloys, to meet lightweighting mandates and maintain market share against cost-focused competitors.
For New Entrants and Emerging Players:Build out niche expertise in specific, high-growth segments like commercial vehicle electrification, which currently presents an underpenetrated opportunity. Target regional automotive clusters in Mexico and Central Europe with localized production facilities, leveraging nearshoring trends. A go-to-market angle involves offering modular harness solutions for zonal architectures, simplifying OEM assembly processes. Focus on rapid iteration in advanced materials science to meet evolving performance and weight targets.
For Investors and Strategic Acquirers:The market sits at a transformative growth phase that favors established system integrators with deep engineering capabilities. Long-term viability remains strong, driven by the electrification and software-defined vehicle transitions over the next decade. Acquisition targets should focus on mid-sized specialists possessing unique intellectual property in high-voltage components or advanced data connectivity. The signal to watch is the adoption rate of zonal electrical architectures across new vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces design complexity and manufacturing costs across diverse vehicle models. |
| High-Voltage System R&D | Secures competitive advantage in the rapidly expanding electric vehicle segment. |
| Global Manufacturing Footprint Expansion | Supports OEM nearshoring initiatives and optimizes logistics for regional supply chains. |
| Advanced Material Development | Addresses OEM demands for lightweighting and enhanced performance in critical applications. |
| Functional Safety Certification Investment | Ensures compliance with strict international regulations, maintaining market access. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research validation. Primary data involved conversations with OEM procurement managers, Tier-1 engineering leads, material science researchers, and regulatory compliance officers. Secondary sources included automotive production databases, regulatory body publications (e.g., US EPA, EU Green Deal), company annual reports, and technical journals. This approach enabled bottom-up and top-down triangulation for robust market sizing.
Forecast inputs considered market segmentation across product type, technology, application, and end-user, alongside regional production clusters. The analytical framework modeled volume and value outputs over the projection horizon, integrating vehicle electrification rates and ADAS penetration. Compound annual growth rates were derived from historical data analysis and projected technological adoption curves. Content per vehicle for wiring harnesses and material cost trends served as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology disruptors or major raw material suppliers would shift outcomes. Projections reflect current regulatory environments and anticipated technological advancements. Cross-checking against vehicle production forecasts from independent automotive research firms is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market