
 Europe Light Commercial Vehicle Rental Market | 2026-2036
Europe Light Commercial Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Light Commercial Vehicle Rental Market Insights
The EU Green Deal is broadening the addressable market for rental operators that can offer zero-emission light commercial vehicles without long-term ownership risk. Sixt SE leverages its premium fleet positioning to capture corporate sustainability mandates, while Fraikin SAS anchors its growth on full-service leasing with maintenance bundled for mid-size French and Spanish contractors. Northgate plc competes through dense depot networks across the United Kingdom and Ireland, enabling same-day van replacement that minimizes downtime for trade fleets.
Light commercial vehicle rental covers the short-to-medium term provision of vans, trucks, and minibuses—typically gross vehicle weights between 3.5 and 7.5 tonnes—through contractual arrangements that transfer operating risk from user to provider while preserving balance-sheet flexibility for businesses. Vans dominate transaction volumes due to their versatility in urban parcel distribution, though refrigerated trucks command premium daily rates driven by cold-chain compliance costs and specialized insulation maintenance. Short-term rentals absorb peak-season demand spikes in logistics and construction, while long-term structures appeal to businesses navigating uncertain contract durations or testing electrification before purchase commitment.
EMA fleet CO2 monitoring requirements, national low-emission zones enforced by city authorities in London, Paris, and Berlin, and the EU AI Act's forthcoming liability frameworks for automated vehicle dispatch are reshaping operator investment priorities and customer qualification protocols. The F-Gas Regulation additionally constrains refrigerant choices for temperature-controlled rental units, elevating compliance costs for refrigerated truck segments. Stakeholders must weigh electrification capex against residual value risk while monitoring how fragmented municipal access rules redefine competitive moats in dense European urban corridors.
Market Dynamics
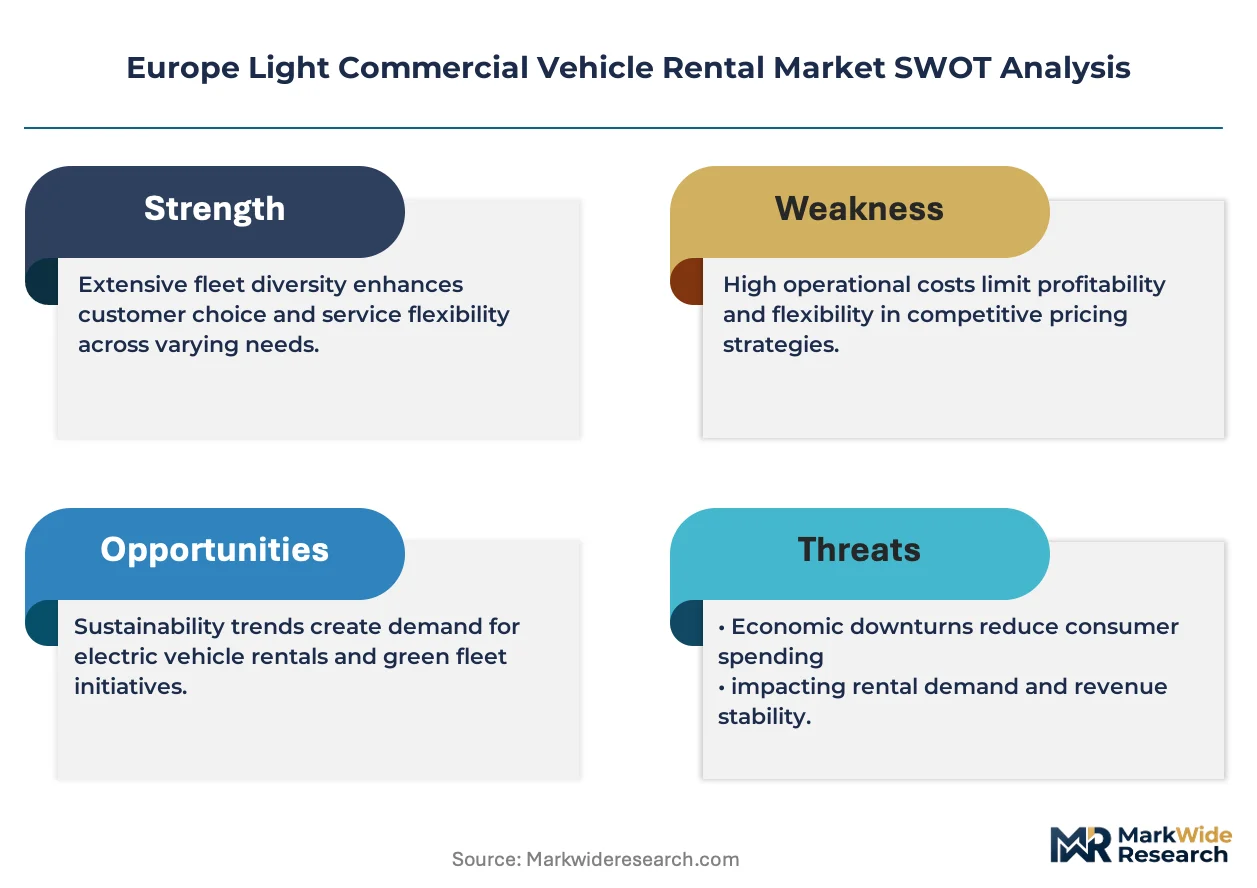
The EU Green Deal's phased CO2 standards for commercial vehicles are forcing rental operators to restructure fleet procurement faster than their capital-constrained owner-operator competitors can match, compressing electrification timelines across urban logistics corridors.
Growth Catalysts
- EMA Fleet CO2 Monitoring:Mandatory emissions reporting for commercial vehicle fleets above specific thresholds creates compliance-driven demand for rental operators with pre-certified zero-emission van portfolios.
- Last-Mile Delivery Expansion:E-commerce fulfillment networks across Germany, France, and the United Kingdom are scaling rental agreements to avoid balance-sheet vehicle ownership during demand volatility.
- Low-Emission Zone Proliferation:Municipal access restrictions in London, Paris, and Berlin make flexible electric van access preferable to diesel ownership with uncertain residual values.
Market Restraints
- Battery Supply Concentration:European cell manufacturing capacity remains concentrated among Asian suppliers, exposing rental fleet electrification timelines to import dependency and price volatility.
- F-Gas Refrigerant Constraints:The F-Gas Regulation limits hydrofluorocarbon availability for temperature-controlled rental trucks, elevating compliance costs and service complexity for cold-chain segments.
- Residual Value Uncertainty:Rapid battery technology evolution and policy shifts create valuation opacity for electric commercial vehicles, constraining rental operator asset financing options.
Strategic Opportunities
- Spanish and Italian Market Underpenetration:Fragmented local rental markets in Southern Europe present acquisition and greenfield expansion opportunities for operators with electrified portfolios.
- EU AI Act Dispatch Liability Frameworks:Automated vehicle routing and predictive maintenance systems will create differentiation for rental operators investing in compliant fleet management platforms.
- Telematics-Enabled Usage Billing:Real-time mileage and payload monitoring allows rental operators to unbundle pricing from fixed daily rates, capturing value from variable logistics demand patterns.
Industry Challenges
- Electric Vehicle Technician Scarcity:High-voltage systems certification requirements outpace vocational training program output across France, Germany, and the United Kingdom, extending maintenance response times.
- Multi-Jurisdictional Access Compliance:Fragmented municipal low-emission zone rules with varying vehicle standards, payment systems, and enforcement mechanisms multiply fleet qualification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Light Commercial Vehicle Rental Market |
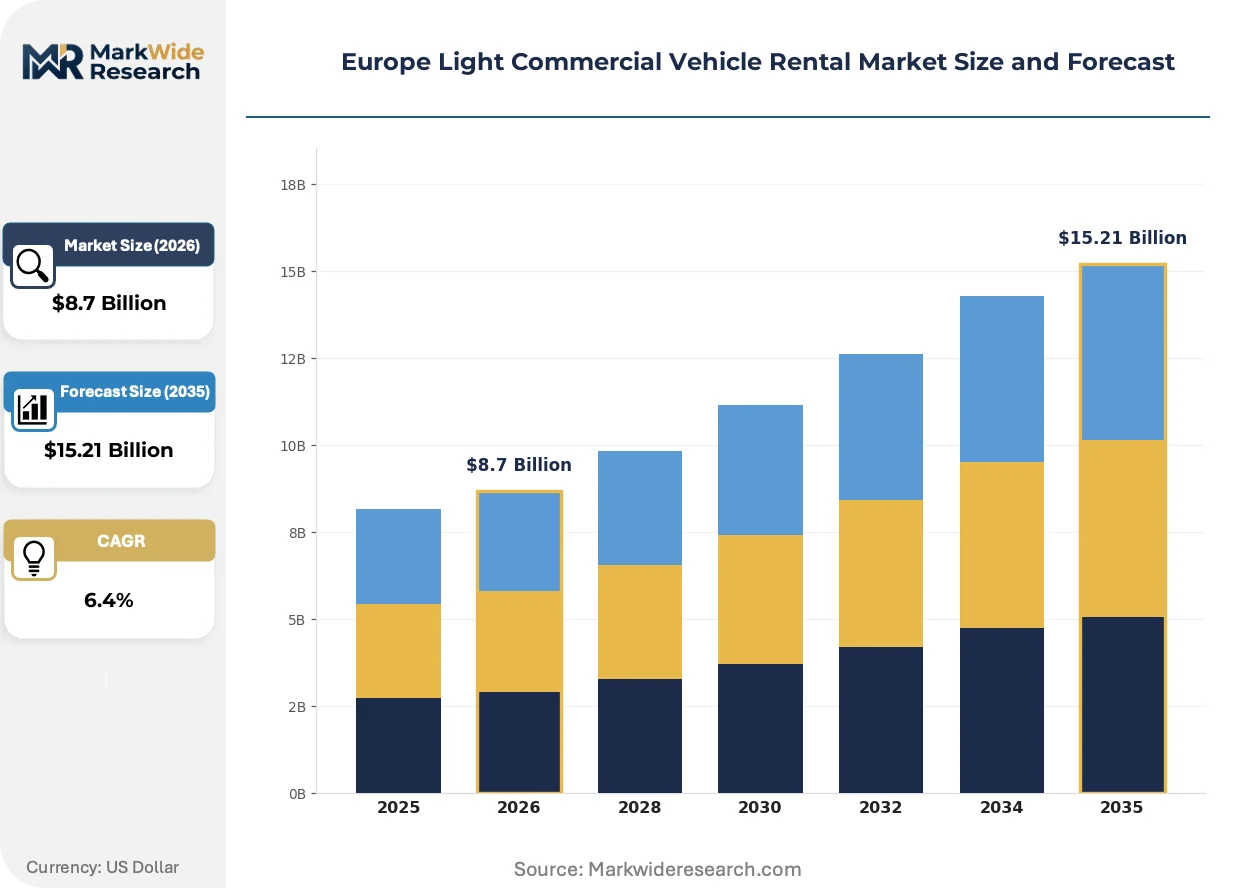
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Vans, Trucks, Minibuses, Refrigerated Trucks Rental Duration: Short-term, Long-term, Weekend, Daily Customer Type: Businesses, Individual Users, Government Agencies, Non-profits Usage Purpose: Logistics, Transport Services, Relocation, Construction |
| Companies Covered | Hertz Global Holdings, Sixt SE, Enterprise Holdings, ALD Automotive, LeasePlan Corp NV, Avis Budget Group, Fraikin SAS, Northgate plc, Europcar Mobility Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Light Commercial Vehicle Rental Market Trends and Innovations
Telematics integration and battery-electric drivetrains are compressing rental contract structures from fixed-term leases toward variable-usage models, while regulatory pressure accelerates fleet turnover cycles.
Modular battery-swapping architectures for light commercial vehicles are consolidating around standardized cell formats and automated exchange stations. Urban parcel distributors in the Netherlands and Denmark are piloting subscription-based energy access that separates vehicle rental from battery ownership. This consolidation of hardware and energy provisioning into unified service layers reduces upfront capital barriers for fleet electrification.
The EU AI Act's forthcoming liability provisions for automated dispatch systems are compelling rental operators to restructure telematics contracts and data governance frameworks. Fleet management platforms must now document algorithmic decision trails for accident attribution. Temperature-controlled rental segments face compounded compliance burden from concurrent F-Gas refrigerant phase-down schedules and AI-enabled route optimization audits.
Corporate sustainability mandates are compressing procurement evaluation cycles from multi-year frameworks toward quarterly rental reviews with emissions performance clauses. Large logistics contractors in Germany and the United Kingdom now require Scope 3 documentation from vehicle providers. This behavioral shift elevates rental operators with certified carbon accounting over traditional ownership models lacking comparable transparency infrastructure.
Europe Light Commercial Vehicle Rental Market Segmentation
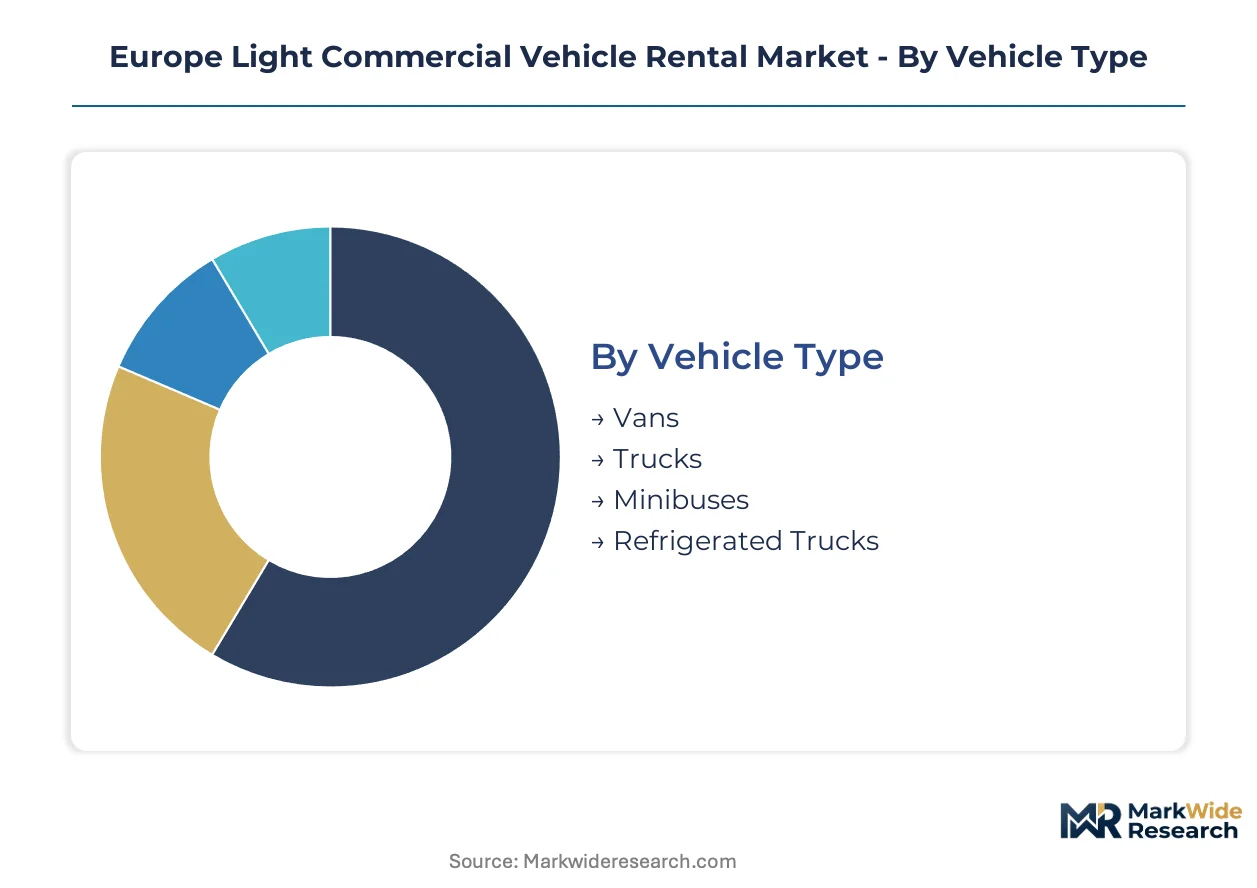
Rental operators structure fleet procurement and pricing around vehicle specifications, contract duration, and customer risk profiles. Segmentation clarity determines residual value management and electrification capex allocation across urban logistics corridors.
Vehicle Type:
Standalone rental assets dominate transaction volumes, while embedded cold-chain systems command specialized maintenance protocols and premium rate structures.
- Vans:Gross vehicle weights between 3.5 and 7.5 tonnes with flatbed or enclosed cargo configurations. Last-mile parcel distributors in Germany and the United Kingdom absorb peak-season spikes through flexible daily agreements, avoiding capital lock-up during demand volatility.
- Refrigerated Trucks:Insulated cargo compartments with integrated cooling units using hydrofluorocarbon or natural refrigerant systems. Cold-chain compliance costs and F-Gas Regulation constraints elevate daily rates above standard trucks, with demand concentrating in pharmaceutical and fresh-food logistics across France and the Netherlands.
- Trucks:Chassis-cab configurations for payload-intensive applications.
- Minibuses:Passenger configurations for crew transport and shuttle services.
Volume placements concentrate in Vans; the faster expansion belongs to Refrigerated Trucks.
Rental Duration:
Contract structures stratify by balance-sheet flexibility requirements, with shorter terms absorbing demand uncertainty and longer terms capturing fleet standardization benefits.
- Short-term:Agreements spanning days to weeks without residual value transfer. Construction contractors in Spain and Italy rent during project-specific peaks, sidestepping ownership risk in fragmented municipal markets.
- Long-term:Multi-month to multi-year contracts with bundled maintenance and replacement guarantees. Corporate sustainability mandates in Germany now embed emissions performance clauses, favoring rental over purchase for electrification testing.
- Weekend:Compressed-rate structures for non-commercial peak periods.
- Daily:Transactional access for immediate replacement or surge capacity.
Transaction frequency peaks in Short-term; Long-term contracts are climbing the fastest as electrification trials extend.
Customer Type:
Risk transfer preferences diverge by entity scale, with larger organizations prioritizing operational flexibility and smaller users seeking asset access without credit burden.
- Businesses:Corporate fleets and trade contractors requiring scalable vehicle access. E-commerce fulfillment networks across the United Kingdom and France expand rental agreements to avoid balance-sheet vehicle ownership during demand volatility.
- Individual Users:Sole traders and micro-enterprises without fleet financing capacity. Self-employed contractors in Italy and Poland rely on daily van rentals for project-based income, constrained by limited credit access for purchase.
- Government Agencies:Municipal and national fleet procurement with sustainability procurement rules.
- Non-profits:Social service and humanitarian organizations with grant-dependent budgets.
Revenue concentration sits with Businesses; Individual Users are gaining share fastest as gig-economy participation expands.
Usage Purpose:
Application-specific requirements drive fleet composition, with urban access restrictions and payload demands shaping vehicle specification.
- Logistics:Parcel distribution and supply-chain fulfillment with time-definite delivery requirements. Low-emission zones in London, Paris, and Berlin compel electric van adoption, with rental operators capturing demand from owner-operators facing residual value uncertainty.
- Construction:Materials transport and site services with payload and terrain demands. German and French trade fleets minimize downtime through same-day replacement services from dense depot networks.
- Transport Services:Passenger and specialized cargo movement.
- Relocation:Residential and commercial moving with volume-variable needs.
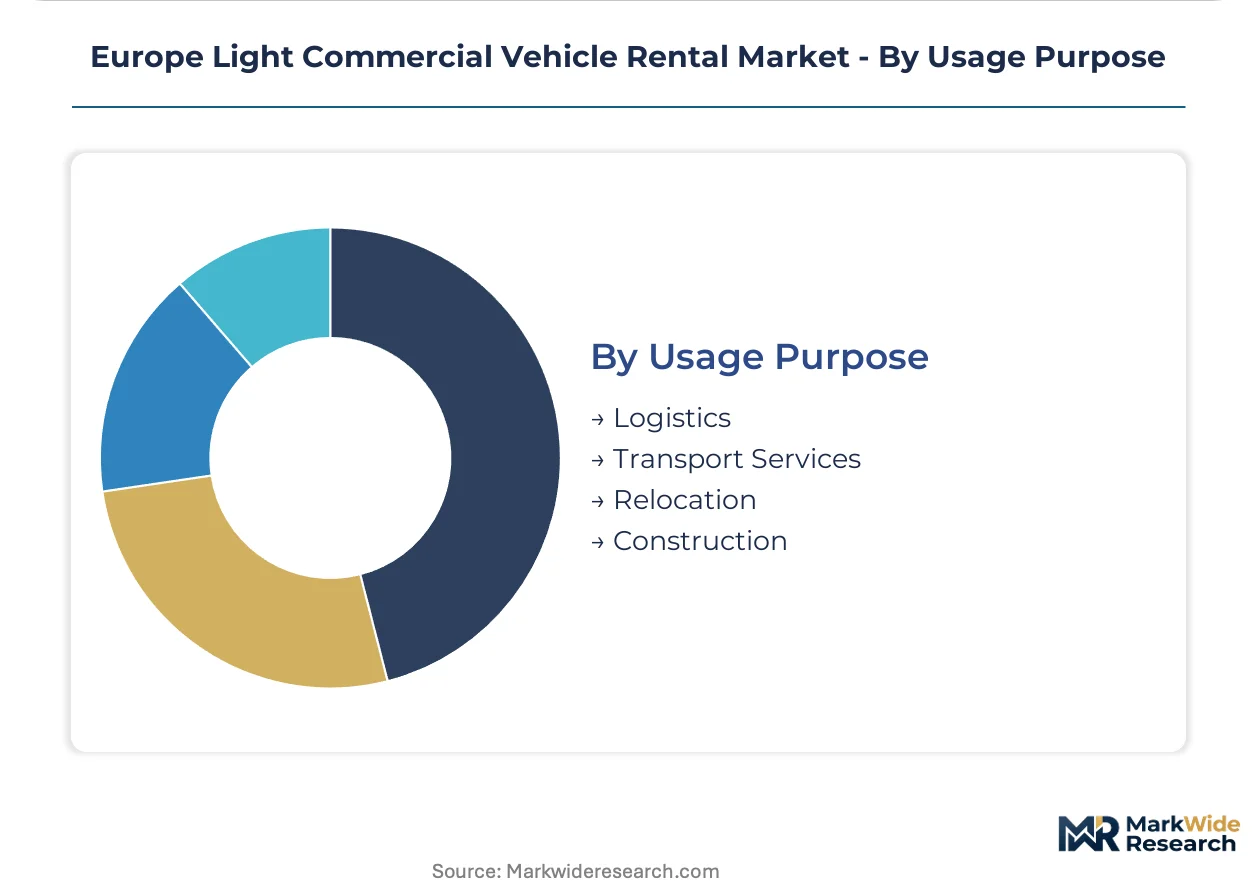
Deployment density is highest in Logistics; Construction shows the steepest expansion trajectory as infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of light commercial vehicles concentrates in Germany and France, while rental demand disperses across urban logistics corridors where low-emission zones and last-mile delivery networks drive fleet turnover.
Germany
E-commerce fulfillment networks in Berlin and Hamburg are scaling flexible rental agreements to manage demand volatility without balance-sheet vehicle ownership. The KBA enforces EMA fleet CO2 monitoring thresholds that push logistics contractors toward rental operators with pre-certified electric van portfolios. Bavaria's manufacturing belt around Munich supplies chassis-cab configurations that rental fleets deploy across Rhine-Ruhr logistics clusters.
United Kingdom
London's Ultra Low Emission Zone and expanding clean air regulations in Birmingham and Manchester compel trade fleets to abandon diesel ownership for flexible electric van access. The Department for Transport coordinates national zero-emission vehicle mandates with municipal enforcement mechanisms that fragment compliance requirements. Dense depot networks across the Midlands and Southeast enable same-day replacement services that minimize downtime for construction and parcel distribution fleets.
France
Corporate sustainability mandates from Paris-based headquarters operations are compressing procurement cycles toward quarterly rental reviews with embedded emissions performance clauses. ANSM and CNIL oversight intersects with EU AI Act liability frameworks for automated dispatch systems that rental operators must document. The Île-de-France logistics corridor anchors cold-chain rental demand for pharmaceutical distribution, while Auvergne-Rhône-Alpes supports full-service leasing growth for mid-size contractors.
Netherlands
Urban parcel distributors in Rotterdam and Amsterdam are piloting subscription-based battery-swapping architectures that separate vehicle rental from energy ownership. National climate agreements accelerate municipal low-emission zone coordination that reduces multi-jurisdictional compliance burden for cross-border fleet operators. Randstad logistics density supports telematics-enabled usage billing models that capture value from variable delivery demand patterns.
Spain
Fragmented local rental markets in Madrid and Barcelona present acquisition opportunities for operators with electrified portfolios seeking Southern European expansion. Construction contractors in Valencia and Seville rely on short-term rentals during project-specific peaks, sidestepping ownership risk in volatile municipal markets. The national recovery plan channels infrastructure investment that steepens construction fleet expansion trajectories.
Europe Light Commercial Vehicle Rental Market Competitive Landscape
The competitive structure tilts toward full-service leasing specialists with bundled maintenance capabilities. Tiered positioning separates premium fleet operators from volume-driven daily rental networks and regional depot-density players. Strategic archetypes include electrification-first portfolio managers, multi-modal mobility platforms, and contractor-focused replacement guarantee providers. Consolidation moves center on Southern European market entry and telematics platform integration.
Within the premium fleet tier, Sixt SE occupies a position exemplifying corporate sustainability mandate capture, while Fraikin SAS represents the full-service leasing archetype for mid-size French and Spanish contractors. Northgate plc anchors the dense depot-network model across the United Kingdom and Ireland. These three patterns illustrate how rental operators align electrification capex with distinct customer risk-transfer preferences.
| Leading Market Players |
|---|
| Hertz Global Holdings |
| Sixt SE |
| Enterprise Holdings |
| ALD Automotive |
| LeasePlan Corp NV |
| Avis Budget Group |
| Fraikin SAS |
| Northgate plc |
| Europcar Mobility Group |
| Others |
Pricing and Supply Chain Analysis
Battery-electric drivetrain adoption across European rental fleets simultaneously elevates upfront capital requirements and concentrates procurement leverage among chassis manufacturers in Germany and France. This technological transition compresses margin structures for mid-tier operators while amplifying pricing power for integrated full-service providers with captive maintenance capabilities.
Pricing Analysis
Margin tightening in standard van tiers reflects battery cost pass-through limitations and aggressive electrification subsidies from national governments. Three-tier pricing structure across premium full-service, standard operational lease, and economy daily rental levels stratifies by maintenance bundling and replacement guarantee scope. Cost-down pressure on economy tiers accelerates because gig-economy contractors prioritize transaction accessibility over service depth. Individual users exhibit highest price sensitivity, while corporate sustainability officers accept premium positioning for certified zero-emission portfolios.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's battery passport requirements are reshaping sourcing patterns toward European cell assembly and regional chassis fabrication. Vehicle supply concentrates in Germany, France, and Spain, with battery cell production drawing from Hungary and Poland greenfield investments. Key inputs include lithium-ion cell packs, high-strength steel chassis components, and telematics hardware. Single-source vulnerability around Asian semiconductor supply for fleet management systems elevates delivery risk. Distribution runs through manufacturer-direct fleet sales, specialized leasing subsidiaries, and independent rental depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle technician scarcity across France, Germany, and the United Kingdom constrains fleet expansion velocity, propping residual value premiums for operators with certified maintenance infrastructure.
For Market Incumbents: Deploy telematics-enabled usage billing platforms to capture variable demand patterns from logistics networks. Consolidate Southern European depot networks through targeted acquisitions in Spain and Italy to preempt emerging entrants. Backward integration into high-voltage technician training programs defends against maintenance response time erosion from vocational pipeline gaps.
For New Entrants and Emerging Players: The premium-economy price-point gap in refrigerated truck segments creates entry space for specialized cold-chain operators with F-Gas-compliant natural refrigerant systems. Spanish municipal construction markets offer the most penetrable geography, with fragmented local incumbents lacking electrified portfolios. A subscription-based energy-access go-to-market angle separates vehicle rental from battery ownership, reducing customer capital barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with full-service leasing specialists given corporate sustainability mandate acceleration and embedded maintenance revenue visibility. Long-term viability favors operators with dense depot networks and certified carbon accounting infrastructure over asset-light platform plays. Watch battery residual value transparency indices as the inflection signal for financing option expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake contracts with European gigafactories secure fleet electrification timelines against import dependency. |
| Telematics Platform Integration | EU AI Act-compliant dispatch systems differentiate operators through documented algorithmic decision trails for liability attribution. |
| Geographic Expansion | Greenfield depot deployment in Madrid and Barcelona captures Southern European infrastructure investment acceleration. |
| Charging Infrastructure Partnership | Collaboration with municipal networks in London, Paris, and Berlin ensures customer access within low-emission zone boundaries. |
| Full-Service Leasing Acquisition | Consolidation of mid-size French and Spanish contractors builds maintenance density and replacement guarantee capabilities. |
Research Methodology
Independent corroboration across fleet procurement directors, high-voltage technician training program administrators, and municipal low-emission zone policy officers underwrites the qualitative findings. Primary interviews with rental operator fleet managers, OEM commercial vehicle sales executives, and logistics contractor procurement leads combined with secondary validation from KBA registration data, ANSM pharmaceutical distribution fleet disclosures, and EU EMA fleet CO2 monitoring reports. Bottom-up transaction volume estimates and top-down macroeconomic absorption models triangulate market sizing.
Rate-of-change decomposition across vehicle type, rental duration, customer scale, and urban corridor regulatory intensity structures the analytical framework. Segmentation dimensions modeled include propulsion architecture, contract structure, end-use application, and geographic compliance cluster. CAGRs derive from logistic curve adoption modeling for electric van penetration and elasticity-adjusted demand response to congestion charging expansion. Forecast inputs incorporate battery cost decline trajectories and municipal low-emission zone proliferation schedules.
Inputs from fleet operator financial disclosures and national automotive registration databases were available through the study window; gaps in real-time telematics utilization data introduce uncertainty bands around usage-billing revenue projections. Forecasts reflect documented assumptions regarding policy enforcement consistency and cell manufacturing capacity commissioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Europe Van Rental Market
Transportation Services
Car Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Ship Management Software Market
Transportation Services
India Taxi Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Scooter Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
Cross Docking Services Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Water Truck Rental Market