
 Train Exterior Lighting Market | 2026-2036
Train Exterior Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Train Exterior Lighting Market Analytics
Consolidation among state-backed rail operators is realigning procurement patterns toward long-term framework agreements. OSRAM GmbH leverages its automotive LED heritage to compete in rail-specific optical engineering. Wabtec Corporation anchors its position through integrated signaling and lighting platforms for North American freight corridors. Siemens Mobility extends its reach via digital lighting control systems bundled with rolling stock modernization contracts.
Train exterior lighting comprises sealed, vibration-resistant luminaires engineered to withstand aerodynamic loads, thermal cycling, and electromagnetic interference across operational speeds exceeding 300 km/h. These systems serve critical functions including forward illumination, marker visibility, and emergency egress signaling for passenger and freight rolling stock. LED light type segments now dominate new installations due to lumen-per-watt efficiency gains and maintenance interval extension. High-speed rail train type applications command premium specification tiers, while commuter segments drive volume through fleet standardization programs. Direct current power source configurations retain structural importance in electrified rail networks where catenary infrastructure eliminates auxiliary generation needs.
European Union rail interoperability standards under the European Union Agency for Railways shape product certification requirements for cross-border rolling stock. The US Federal Railroad Administration mandates minimum brightness and beam pattern specifications for locomotive headlamps through 49 CFR Part 229. China's national rail administration enforces GB standards for exterior lighting on high-speed trainsets deployed across its expanding network. Stakeholders must monitor evolving photometric requirements tied to autonomous train operation readiness and nighttime visibility enhancement protocols.
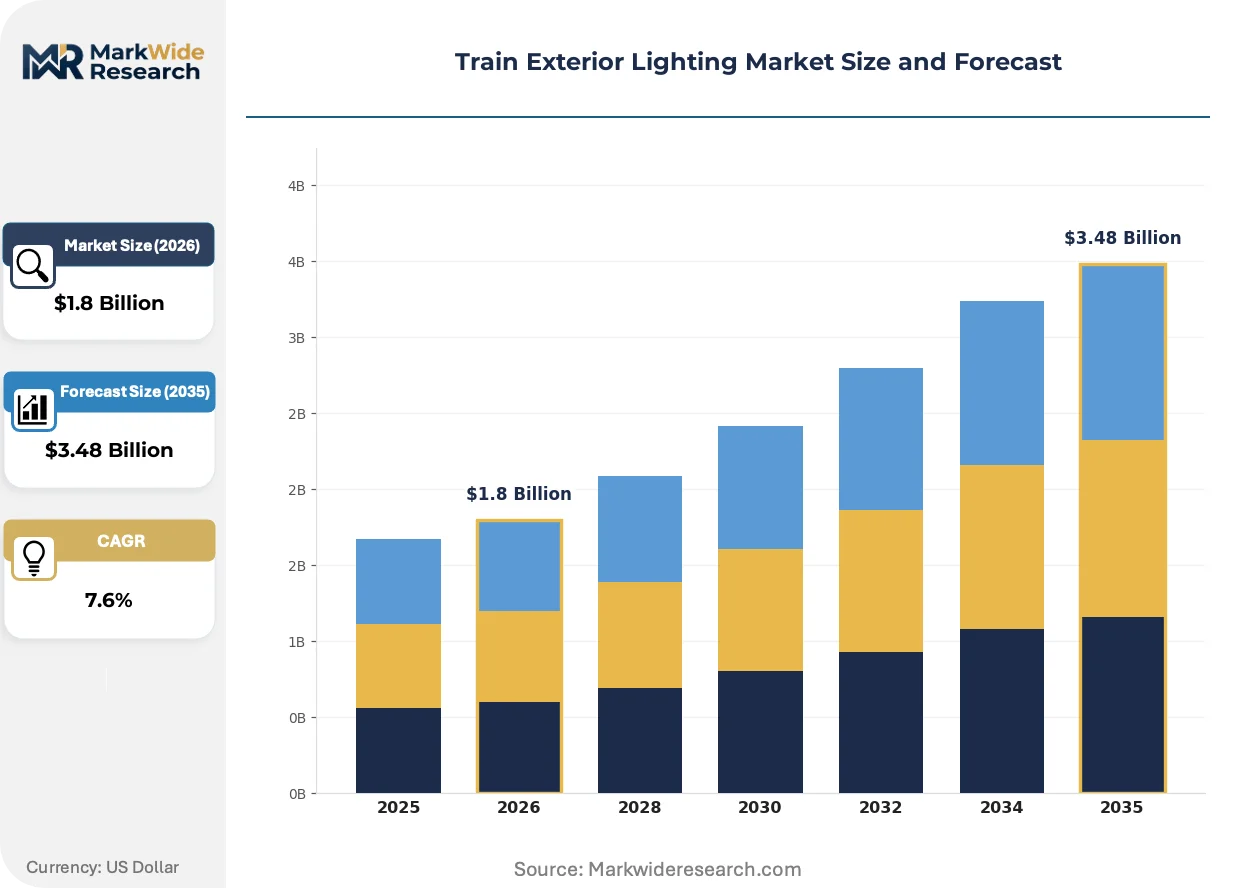
Market Dynamics
LED retrofits are compressing replacement cycles across electrified rail networks as operators prioritize lumen efficiency and maintenance reduction over incumbent halogen systems.
Growth Catalysts
- EU Agency for Railways interoperability mandates:Cross-border rolling stock certification requirements under TSIs are forcing lighting upgrades on international corridors.
- High-speed rail expansion in China:GB standards enforcement on new trainset deployments creates sustained procurement volume for sealed LED headlamp assemblies.
- Photometric efficiency gains:Solid-state lumen-per-watt improvements are extending service intervals from 2,000 to 50,000 hours.
Market Restraints
- Aluminum housing cost volatility:Cast enclosure prices fluctuate with energy-intensive smelting inputs, pressuring margin structures for luminaire assemblers.
- Optical-grade silicone supply concentration:Lens material production clusters in East Asian chemical corridors, exposing buyers to single-source risk.
- Electromagnetic compatibility testing burden:EN 50121-3-2 compliance for rolling stock adds 14-18 weeks to product qualification timelines.
Strategic Opportunities
- Indian Railways electrification push:The CEA's 100% electric traction target by 2024 opens demand for DC-native LED marker systems on legacy diesel routes.
- Autonomous train readiness:Machine-vision-compatible infrared marker bands represent uncontracted specification space ahead of GoA4 deployments.
- Digital lighting control bundling:DALI-2 protocol integration with train management systems enables predictive failure monitoring as a service layer.
Industry Challenges
- Optomechanical engineering talent scarcity:Rail-specific thermal and vibration modeling expertise concentrates in German and Japanese supplier ecosystems.
- Legacy 74V DC infrastructure incompatibility:Retrofit LED drivers must interface with aging power distribution architectures without signal interference.
- Multi-standard certification overlap:Simultaneous FRA Part 229, GB, and EN compliance creates documentation redundancy for multinational rolling stock lessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Exterior Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Light Type: LED, Halogen, Xenon, Fluorescent Power Source: Battery, Solar, Diesel Generator, Direct Current Installation Type: Integrated, Aftermarket, Modular, Fixed Train Type: High-Speed Rail, Freight, Commuter, Luxury |
| Companies Covered | Signify N.V., OSRAM GmbH, General Electric Company, Toshiba Corporation, Hitachi Ltd., Koito Manufacturing Co., Ltd., Wabtec Corporation, Alstom SA, Siemens Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Exterior Lighting Market Evolving Landscape
Photonic integration and predictive maintenance architectures are redefining how exterior lighting systems generate value beyond illumination functions.
Adaptive beam-shaping LED arrays with pixel-level intensity control are electrifying forward illumination specifications for high-speed corridors. Deutsche Bahn and SNCF are specifying these systems on next-generation trainsets to eliminate glare for oncoming traffic while maintaining regulatory lux levels. The technology is compressing the specification gap between automotive and rail optical engineering.
REACH substance restrictions on halogenated flame retardants are forcing housing material transitions toward ceramic-filled thermoplastics. Compound suppliers in Germany and Japan are qualifying new polymer grades for EN 45545-2 HL3 fire safety ratings. European rolling stock OEMs are absorbing 8-12% material cost premiums to maintain cross-border certification validity.
Framework contracting with 10-15 year lifecycle coverage is displacing transactional component purchasing among state-backed operators. Deutsche Bahn's Licht 2025 program and JR East's consolidated supplier panels exemplify this concentration. The shift is most visible in Western Europe where public procurement rules favor total-cost-of-ownership evaluation over unit price.
Train Exterior Lighting Market Segmentation
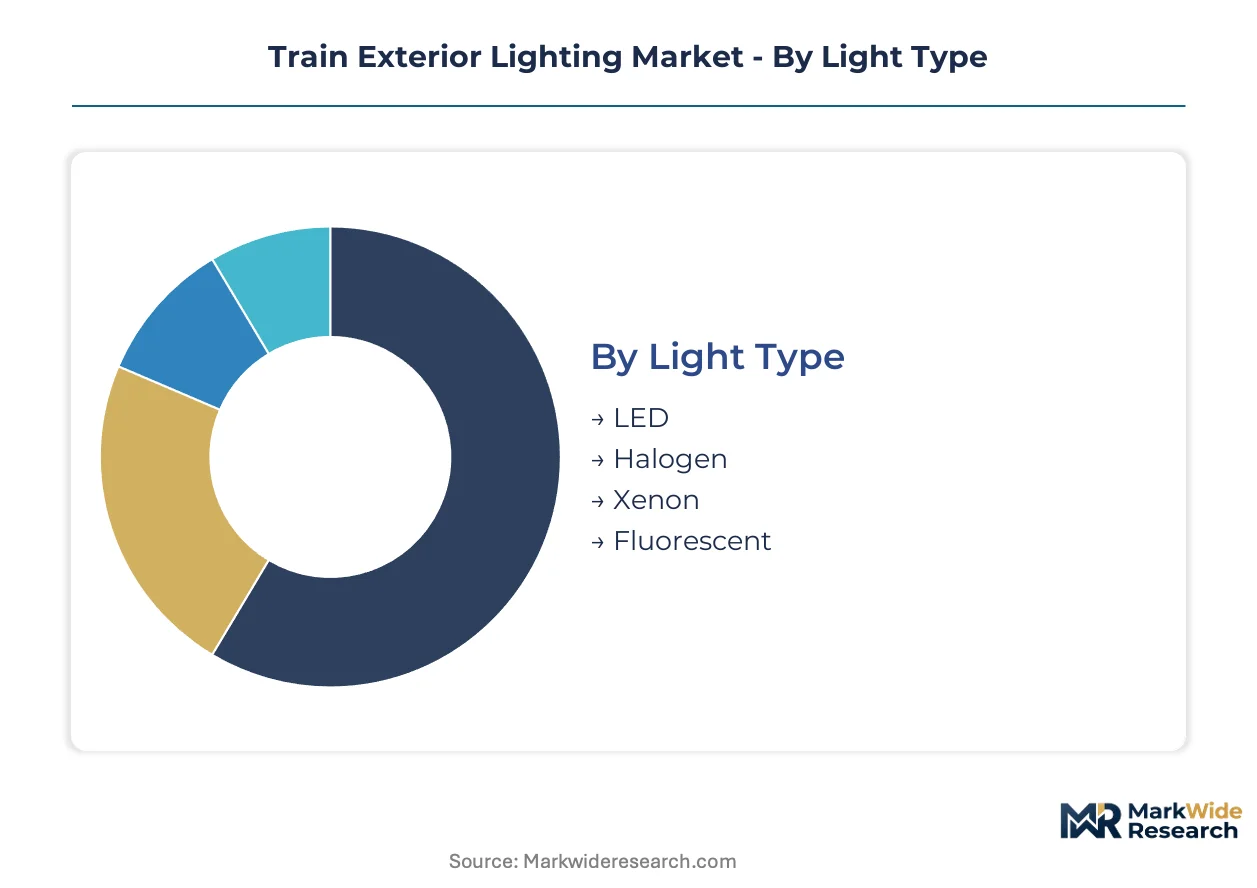
Segmentation in train exterior lighting reveals how procurement patterns diverge between retrofit markets and new rolling stock programs. Each dimension—light source, power architecture, installation method, and train category—carries distinct specification tiers and supplier qualification requirements.
Light Type:
LED systems now dominate as standalone replacements, while legacy technologies persist in embedded configurations where full trainset redesigns remain uneconomical.
- LED:Solid-state arrays deliver lumen-per-watt efficiency above 150 lm/W with sealed housings rated for IP67 ingress protection. Deutsche Bahn and SNCF are specifying adaptive beam-shaping variants on next-generation trainsets to eliminate glare for oncoming traffic. Demand concentrates in Western European high-speed corridors where EN 50155 compliance mandates extended service intervals.
- Halogen:Tungsten-halogen filaments remain entrenched in freight locomotive headlamp positions where 74V DC infrastructure limits driver retrofit compatibility. North American Class I railroads continue procurement for maintenance-of-way equipment where capital budgets prioritize reliability over efficiency gains.
- Xenon:High-intensity discharge arc lamps produce 3,000+ lumen outputs for tunnel penetration on alpine routes. Swiss Federal Railways maintains specification on legacy intercity fleets.
- Fluorescent:Linear tube configurations survive in marker and interior-egress crossover applications. Japanese commuter operators retain limited procurement for standardized fleet maintenance.
Volume placements concentrate in LED; the faster expansion belongs to adaptive beam-shaping LED variants.
Power Source:
Electrified network architecture dictates whether lighting draws from catenary-fed DC busses or requires onboard generation, creating divergent supplier ecosystems.
- Battery:Nickel-metal hydride and lithium-ion packs enable emergency egress illumination independent of traction power. Urban metro operators in China specify battery-backed LED markers for tunnel evacuation compliance under GB standards.
- Solar:Photovoltaic panels with supercapacitor storage serve wayside signal lighting and isolated maintenance-of-way vehicles. Australian mining rail corridors deploy solar marker systems where grid extension proves uneconomical.
- Diesel Generator:Auxiliary gensets power lighting on locomotive-hauled passenger coaches and non-electrified freight routes. Indian Railways' diesel legacy fleet sustains procurement.
- Direct Current:Catenary-derived DC distribution dominates high-speed and commuter installations. 74V and 110V bus architectures prevail in European and Asian electrified networks.
Direct Current claims the largest installed base; battery-backed configurations are climbing the fastest as urban metro safety regulations tighten.
Installation Type:
Procurement channels split between OEM-embedded programs and operator-directed retrofit campaigns, with distinct margin structures and qualification timelines.
- Integrated:Luminaires ship as original equipment within rolling stock manufacturer supply chains. Siemens Mobility and Alstom bundle LED headlamp assemblies with trainset delivery contracts.
- Aftermarket:Replacement units address end-of-life failures and efficiency upgrades outside OEM channels. Wabtec Corporation anchors position through North American freight operator direct procurement.
- Modular:Field-replaceable LED engines and driver modules reduce full luminaire replacement costs. Deutsche Bahn's Licht 2025 program specifies modular architectures for lifecycle cost optimization.
- Fixed:Permanently sealed units with potted electronics minimize maintenance on high-speed trainsets exceeding 300 km/h operational speeds.
Integrated installations generate the highest absolute revenue; aftermarket channels are expanding most quickly as LED retrofit cycles compress.
Train Type:
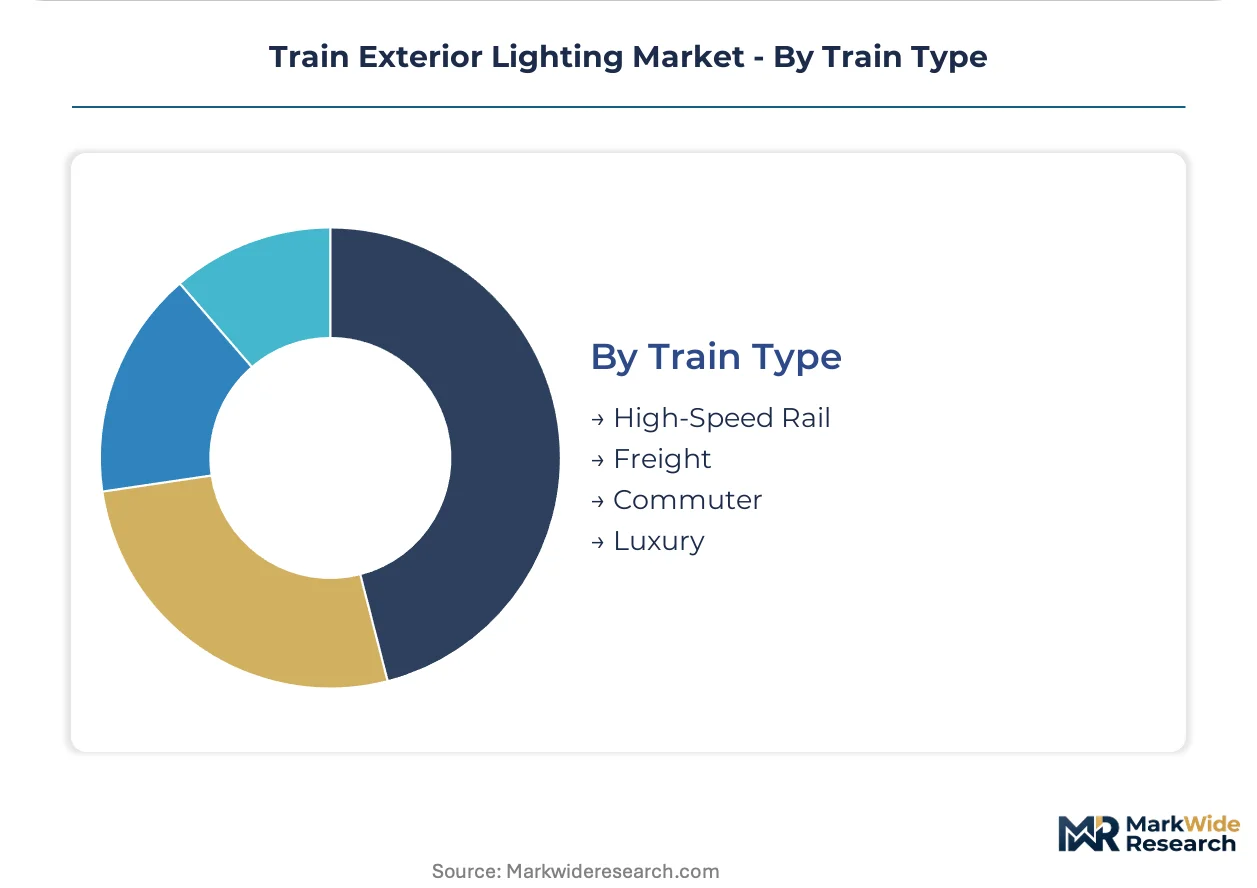
Speed regime and service pattern determine specification intensity, from premium optical engineering on high-speed trainsets to durability prioritization on heavy-haul freight.
- High-Speed Rail:Aerodynamic nose-integrated headlamps must withstand 350+ km/h airflow loads and thermal cycling. China's CR400 series and European Velaro platforms specify sealed LED arrays with active thermal management.
- Freight:Locomotive forward lighting emphasizes impact resistance and electromagnetic compatibility in harsh environments. US Federal Railroad Administration Part 229 mandates govern minimum brightness and beam pattern specifications.
- Commuter:High-volume fleet standardization programs drive LED adoption across urban and regional networks. JR East and SNCF operate consolidated supplier panels for marker and headlamp procurement.
- Luxury:Premium tourist and cruise train services specify aesthetic customization and enhanced nighttime visibility. The Venice Simplon-Orient-Express and Japan's Seven Stars incorporate bespoke lighting designs.
Commuter fleets account for the greatest unit volume; high-speed rail commands the steepest expansion trajectory as network construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume for high-speed rail exterior lighting as network expansion accelerates. Germany and Japan anchor optical engineering expertise for premium specification tiers. The United States sustains freight corridor demand through Federal Railroad Administration mandates.
China
CR400 series trainset deployments drive sealed LED headlamp assembly procurement at scale. GB standards enforcement by the national rail administration mandates exterior lighting compliance on all new high-speed deployments. Manufacturing clusters in Changchun and Qingdao produce integrated nose-cone luminaire systems for domestic and export markets.
Germany
Deutsche Bahn's Licht 2025 program consolidates supplier panels for lifecycle cost optimization across commuter and intercity fleets. EU Agency for Railways interoperability mandates under TSIs force cross-border rolling stock lighting upgrades. Industrial concentration in Bavaria and Baden-Württemberg houses specialized optomechanical engineering talent for thermal and vibration modeling.
Japan
JR East operates consolidated supplier frameworks for marker and headlamp standardization across high-volume commuter networks. METI oversight aligns JIS standards with international rail safety protocols for export compatibility. Manufacturing ecosystems in Aichi and Kanagawa prefectures specialize in vibration-resistant sealed housing production.
United States
North American Class I railroads sustain procurement for freight locomotive headlamp systems under 49 CFR Part 229 brightness mandates. FRA regulations govern minimum beam pattern specifications for nighttime visibility on non-electrified corridors. Wabtec Corporation anchors aftermarket channels through direct operator procurement relationships.
India
Indian Railways' electrification push under CEA targets creates demand for DC-native LED marker systems on legacy diesel route conversions. The 100% electric traction objective drives retrofit procurement across regional networks. Industrial corridors in Maharashtra and Gujarat host luminaire assembly operations for domestic fleet modernization.
Train Exterior Lighting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital lighting control integration and predictive maintenance architectures. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with rail divisions, specialized lighting engineering houses with automotive heritage, and rolling stock OEMs with captive lighting supply chains. Consolidation pressures favor long-term framework contracting over transactional component purchasing. Competitive moves concentrate on backward integration into optical-grade silicone and aluminum housing supply, plus technology licensing for adaptive beam-shaping IP.
Within the diversified industrial tier, General Electric Company and Toshiba Corporation exemplify conglomerate structures spanning multiple infrastructure verticals. OSRAM GmbH and Koito Manufacturing Co., Ltd. represent specialized lighting heritage players with automotive-to-rail optical engineering transfer. Siemens Mobility and Alstom SA occupy rolling stock OEM positions with bundled lighting control system offerings. Wabtec Corporation anchors North American aftermarket channels. Hitachi Ltd. and Signify N.V. sit within broader technology and lighting solution portfolios respectively.
| Leading Market Players |
|---|
| Signify N.V. |
| OSRAM GmbH |
| General Electric Company |
| Toshiba Corporation |
| Hitachi Ltd. |
| Koito Manufacturing Co., Ltd. |
| Wabtec Corporation |
| Alstom SA |
| Siemens Mobility |
| Others |
Value Network & Pricing Analysis
EU Green Deal decarbonization mandates gate qualified supply access for rail exterior lighting manufacturers, forcing EN 45545-2 HL3 fire safety certification investments that stratify pricing tiers between compliant premium suppliers and excluded commodity players. Aluminum housing and optical-grade silicone procurement costs concentrate pricing power among German and Japanese suppliers with validated polymer compound supply chains.
Pricing Analysis
Volume placements in commuter fleet standardization programs compress margins through scale-driven procurement, while high-speed rail specifications sustain premium tiers via adaptive beam-shaping LED engineering and active thermal management integration. Price differentiation hinges on EN 50155 compliance certification and 10-15 year framework contract bundling with digital control systems. Cost compression in standard LED retrofits intensifies as Chinese manufacturers expand DC-native driver production for electrified networks. Freight operators in North America exhibit highest price sensitivity due to maintenance-of-way capital budget constraints; European state-backed rail operators show lowest sensitivity under total-cost-of-ownership evaluation rules.
Supply Chain Analysis
Single-source vulnerability sits with East Asian chemical corridors for optical-grade silicone lens production, exposing luminaire assemblers to concentrated supply risk. Manufacturing gravity centers on China, Germany, and Japan for sealed housing fabrication and optomechanical engineering. Raw material dependencies encompass aluminum cast enclosures, ceramic-filled thermoplastics, and semiconductor-grade LED chips. Tariff exposure on energy-intensive smelting inputs threatens margin structures for housing suppliers. Distribution runs through rolling stock OEM bundled channels and direct operator procurement relationships anchored by Wabtec Corporation in North American aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EN 50121-3-2 electromagnetic compatibility testing creates a 14-18 week qualification barrier that protects incumbent positions against unvalidated entrants.
For Market Incumbents: Deploy framework contracting leverage to lock out emerging digital lighting control competitors before DALI-2 protocol integration becomes standard specification. Consolidate backward integration into optical-grade silicone supply through qualified polymer compound partnerships in Germany and Japan. Defensive positioning requires absorbing 8-12% REACH-driven material cost premiums faster than challengers can qualify alternative ceramic-filled thermoplastics. For New Entrants and Emerging Players: Digital-channel route through predictive maintenance-as-a-service offerings bypasses entrenched OEM supply relationships in commoditized LED replacement markets. Target Indian Railways electrification retrofit campaigns where CEA-mandated DC-native systems create specification white space outside established European supplier panels. Machine-vision-compatible infrared marker bands for autonomous train readiness represent uncontracted premium tier access ahead of GoA4 deployment timelines. For Investors and Strategic Acquirers: Deutsche Bahn Licht 2025 supplier panel consolidation announcements are the leading indicator that European framework contracting concentration will replicate across Asian state-backed operators. Five-to-ten year viability favors specialized optomechanical engineering houses with automotive-to-rail optical IP transfer capabilities over diversified conglomerate rail divisions. Acquisition focus should center on German and Japanese mid-caps with EN 45545-2 HL3 validated polymer grades and captive thermal modeling expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical-Grade Silicone | Captive lens material supply insulates margin structures from East Asian chemical corridor concentration risk. |
| DALI-2 Protocol Integration | Predictive failure monitoring bundling with Deutsche Bahn and JR East framework contracts creates recurring service revenue. |
| Adaptive Beam-Shaping IP Licensing | Automotive optical engineering transfer to rail specifications compresses development cycles for high-speed corridor deployments. |
| REACH-Compliant Polymer Qualification | Ceramic-filled thermoplastic validation maintains cross-border certification validity under EU Green Deal substance restrictions. |
| Modular LED Engine Architecture | Field-replaceable driver modules reduce full luminaire replacement costs for lifecycle-optimized operator procurement. |
Research Methodology
Multi-period observation of high-speed rail deployment timelines, LED retrofit cycle compression, and framework contract migration patterns anchored the trend analysis, supplemented by interviews with rolling stock OEM procurement directors, rail operator maintenance chiefs, optomechanical engineering specialists, and polymer compound suppliers. Secondary validation drew from EU Agency for Railways TSI documentation, FRA Part 229 regulatory filings, GB standards enforcement records, and customs data on aluminum enclosure trade flows. Bottom-up segment sizing triangulated against top-down market aggregation across light type, power source, installation method, and train category dimensions.
Input-output matrix modeling connected catenary electrification expansion rates, LED lumen-per-watt efficiency curves, and regulatory compliance cost burdens to procurement volume forecasts across the projection horizon. Segmentation dimensions encompassed light source technology tier, DC power architecture specification, OEM-embedded versus aftermarket channel mix, and speed regime application category. CAGRs were derived from fitted growth curves calibrated to named country infrastructure investment announcements. Industry-specific forecast inputs included Indian Railways CEA electrification targets and Chinese CR400 series deployment schedules.
Inputs from rolling stock manufacturer delivery contracts and state rail operator procurement databases were available through the study window; gaps in autonomous train specification finalization introduce uncertainty bands around machine-vision lighting demand projections. Forecasts reflect documented assumptions regarding EN 50121-3-2 testing timeline stability and REACH substance restriction phase-in schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
South Africa Rail Freight Transport Market
Railway
Global Train Control and Management Systems Market
Railway
Railroads Market
Railway
Rail Damper Market
Railway
Rail Glazing Market
Railway
Railway Engine Market
Railway
Railcar Vehicle Toilet Market
Railway
Railway Buffer Stops Market
Railway
40-Foot Platform Wagons Market
Railway
Bullet Train Market
Railway
Rail Bellows Market
Railway
Solar Train Market
Railway
Rail Seat Market
Railway
France Connected Rail Market
Railway
Railway Draft Gears Market
Railway
Train Locomotive Suspension Market