
 Radar and Lidar Technology for Railways Application Market | 2026-2036
Radar and Lidar Technology for Railways Application Market Size, Share, and Industry Trends Forecast 2026-2036
Radar and Lidar Technology for Railways Application Market Analytics
Freight rail corridors is restructuring demand for collision-avoidance sensing across North American Class I networks. Siemens Mobility leverages its European signaling heritage to anchor 3D lidar integration with ETCS Level 3 architectures. Navtech Radar competes in all-weather radar deployments for Canadian and Australian heavy-haul routes where precipitation degrades optical systems. Thales Group dominates digital interlocking projects that embed radar-based obstacle detection as standard specification.
Radar and Lidar Technology for Railways Application encompasses electromagnetic and optical sensing systems operating at 76-81 GHz radar bands and 905-1550 nm lidar wavelengths, engineered to detect track obstructions, monitor rolling stock separation, and generate real-time point-cloud data for train control algorithms. These systems serve the primary industrial purpose of replacing visual track inspection with continuous automated surveillance under degraded visibility conditions. Active radar systems sustain the largest installed base across legacy networks where retrofit economics favor single-sensor upgrades, while 3D lidar captures the fastest expansion in greenfield metro projects demanding centimeter-grade spatial resolution for platform screen door synchronization. Safety solutions concentrate margin pools where EN 50126/8/9 functional-safety certification creates pricing power for qualified vendors.
The EU Agency for Railways enforces ERTMS deployment mandates that directly specify radar-compatible train-to-track interfaces, while the US FRA's Positive Train Control regulations compel freight operators to source certified obstacle-detection layers. China's NMPA and MIIT jointly administer GB standard conformity for railway lidar used in driverless operational modes, tightening product-access thresholds for imported sensors. Stakeholders must monitor divergence between European SIL-rated safety architectures and North American FRA-mandated braking curves, as incompatible certification paths threaten supplier scale economics.
Market Dynamics
The collision-avoidance sensing market for rail infrastructure is bifurcating around a single structural force: the regulatory mandate for autonomous train protection systems is compressing procurement cycles while fragmenting vendor qualification pathways across incompatible safety architectures.
Growth Catalysts
- ERTMS Level 3 deployment:The EU Agency for Railways mandates radar-compatible train-to-track interfaces that compel infrastructure managers to replace legacy signaling with continuous position monitoring.
- China's unmanned metro expansion:MIIT-certified 3D lidar modules receive mandatory procurement preference for driverless operational modes across new intercity corridors.
- All-weather operational requirements:Heavy-haul freight operators in precipitation-prone geographies specify millimeter-wave radar systems that sustain detection performance where optical sensors degrade.
Market Restraints
- Silicon photonics supply concentration:1550 nm lidar transmitter components depend on a narrow supplier base concentrated in East Asian foundries, exposing lead-time volatility.
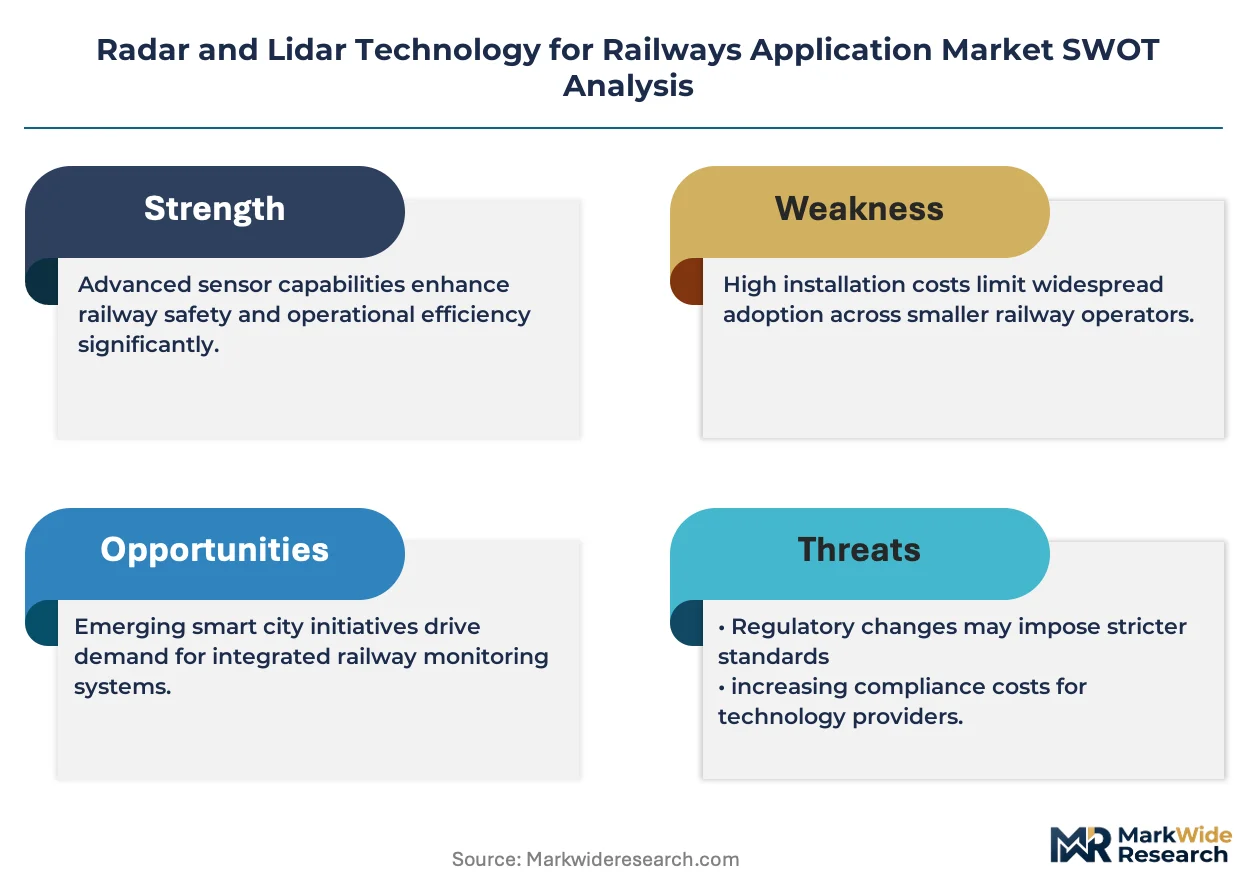
- Functional-safety certification costs:EN 50126/8/9 SIL-rated qualification cycles consume 18-24 months and six-figure testing budgets, freezing out unqualified vendors.
- Radar-lidar substitution tension:Active radar retrofits on legacy networks cannibalize greenfield lidar opportunities where infrastructure managers prioritize single-sensor economics over performance.
Strategic Opportunities
- Indian Dedicated Freight Corridors:The country's national railway regulator is specifying obstacle-detection layers for 3,360 km of new track where no incumbent sensing infrastructure exists.
- F-Gas Regulation tailwinds:EU restrictions on fluorinated greenhouse gases are accelerating lidar-based track monitoring as a replacement for gas-insulated switchgear inspection protocols.
- Sensor fusion architectures:Converged radar-lidar processing units that merge 76-81 GHz returns with 905 nm point clouds are creating new specification categories for platform screen door synchronization.
Industry Challenges
- Embedded systems talent scarcity:Functional safety engineers with rail-specific EN 50128 software competency command premium compensation and extend development timelines.
- Legacy analog interlocking integration:Digital obstacle-detection layers must interface with electromechanical relay logic from the 1980s, requiring custom signal-conditioning hardware.
- Cross-certification fragmentation:European SIL-rated safety architectures and North American FRA-mandated braking curves lack mutual recognition, forcing redundant engineering for multi-continental suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar and Lidar Technology for Railways Application Market |
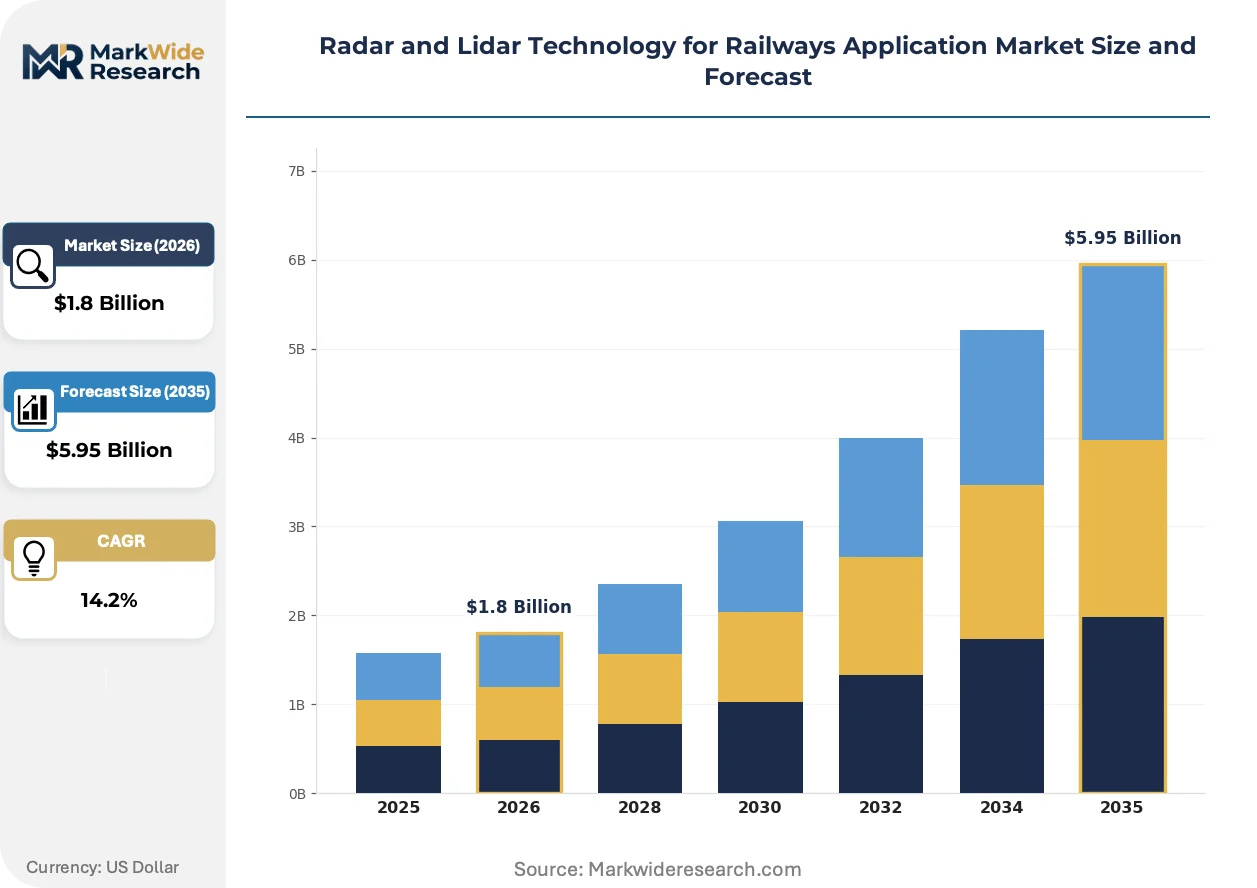
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Lidar Sensors, Tracking Systems, Safety Solutions Technology: Active Radar, Passive Radar, 2D Lidar, 3D Lidar Application: Obstacle Detection, Traffic Monitoring, Autonomous Operations, Maintenance Planning End User: Rail Operators, Infrastructure Managers, Technology Providers, Government Agencies |
| Companies Covered | Bosch Mobility Solutions, Navtech Radar, Leica Geosystems AG, Radarxense BV, DEUTA-WERKE GmbH, BlackBerry Limited, Siemens Mobility, Thales Group, Trimble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar and Lidar Technology for Railways Application Market Evolving Landscape
Sensor hardware and processing architectures are converging around solid-state designs that eliminate mechanical scanning components. This shift is compressing unit economics while expanding the addressable base of retrofit installations.
Solid-state lidar is unifying detection and localization functions in a single photonic package. Metro operators in China and Japan are specifying chip-scale 905 nm arrays for platform edge detection, collapsing the traditional separation between obstacle sensing and train positioning subsystems. This convergence is unifying procurement categories that previously required distinct vendor relationships and maintenance protocols.
The EU F-Gas Regulation is compelling infrastructure managers to eliminate sulfur hexafluoride-dependent inspection methods. Lidar-based track geometry monitoring systems are displacing gas-insulated switchgear for continuous catenary and rail wear assessment. German and French network operators are accelerating pilot deployments ahead of 2030 phase-down deadlines, redirecting capital from traditional maintenance vehicles toward fixed sensing infrastructure.
Maintenance contracting is fragmenting from bundled service agreements toward unbundled sensor-as-a-service models. European infrastructure managers now procure detection hardware separately from algorithm updates and cloud analytics, reversing decade-long preferences for integrated OEM service contracts. This unbundling is most visible in Scandinavian markets where state rail authorities have mandated open API standards for obstacle-detection data feeds.
Radar and Lidar Technology for Railways Application Market Segmentation
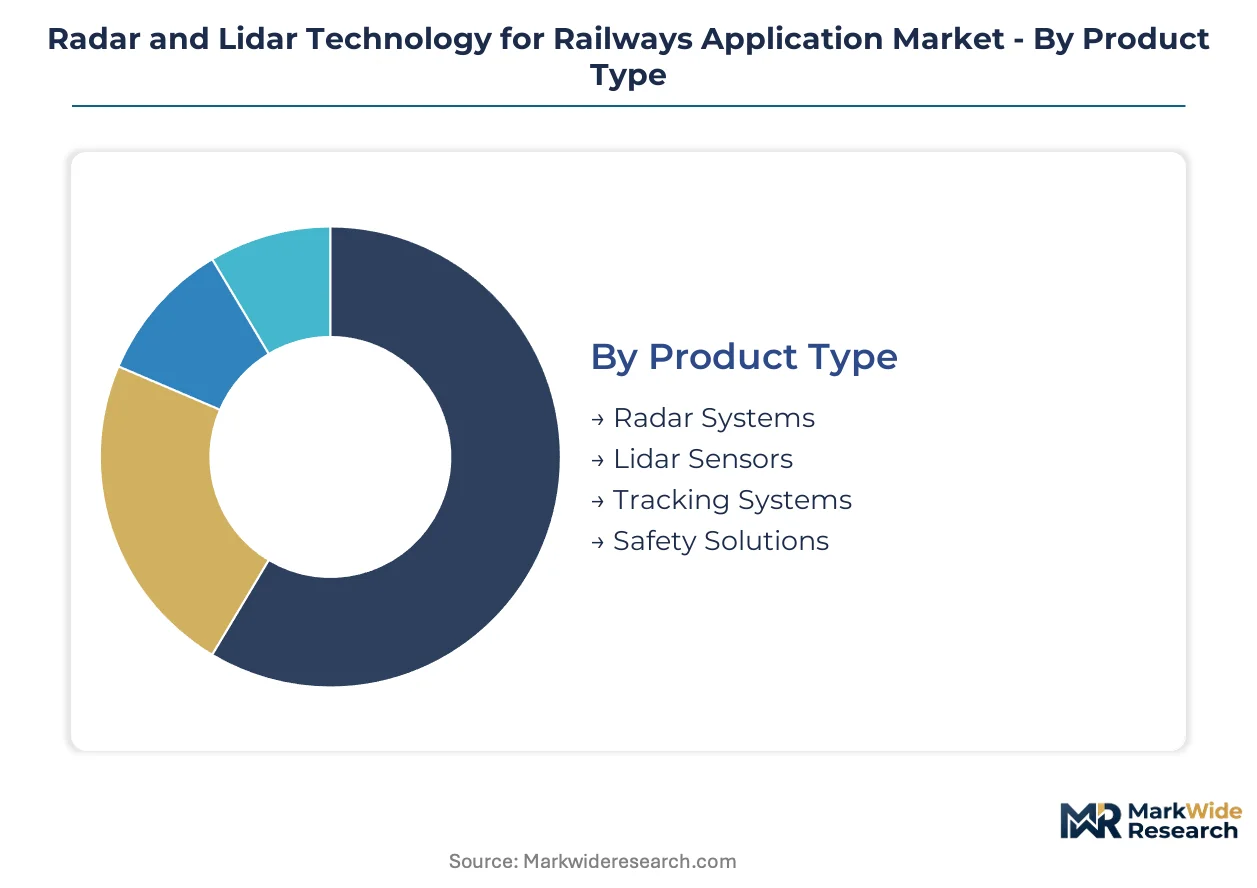
Railway sensing procurement fragments across distinct technical specifications and operational mandates. Infrastructure managers prioritize sensor architectures that align with legacy signaling investments and emerging autonomous operational requirements.
Product Type:
Supply concentration clusters around vendors holding EN 50126/8/9 certification, creating tiered access to safety-critical procurement channels.
- Radar Systems:Millimeter-wave units operating at 76-81 GHz sustain detection through precipitation and particulate interference. North American Class I freight networks specify these for heavy-haul corridors where optical degradation is unacceptable.
- Lidar Sensors:Time-of-flight and frequency-modulated continuous-wave architectures generate centimeter-grade point clouds for platform screen door synchronization. China's unmanned metro lines mandate MIIT-certified 3D modules, compressing procurement timelines for qualified suppliers.
- Tracking Systems:Continuous position monitoring hardware integrates with ETCS Level 3 train-to-track interfaces.
- Safety Solutions:Bundled obstacle-detection layers with SIL-rated software stacks command premium pricing in European tenders.
Radar Systems absorb the bulk of installed capacity; Lidar Sensors are expanding most quickly.
Technology:
Application requirements determine wavelength and processing architecture selection, with weather resilience and spatial precision trading off across deployment contexts.
- Active Radar:Transmitter-receiver pairs emit electromagnetic pulses and analyze return signals for obstruction ranging. Canadian and Australian heavy-haul operators favor these for all-weather reliability on precipitation-prone routes.
- Passive Radar:Exploits existing broadcast signals for detection without dedicated transmission hardware, reducing electromagnetic spectrum licensing burdens.
- 2D Lidar:Single-plane scanning supports basic obstacle alerting at reduced cost points for legacy network retrofits.
- 3D Lidar:Solid-state photonic arrays at 905-1550 nm unify localization and detection functions. Japanese metro operators specify chip-scale designs that collapse procurement categories previously requiring separate vendor relationships.
Active Radar dominates retrofit economics; 3D Lidar is climbing the fastest on greenfield project specifications.
Application:
Functional-safety certification requirements vary sharply across use cases, fragmenting vendor qualification pathways.
- Obstacle Detection:Continuous track surveillance replaces visual inspection with automated alerting under degraded visibility. The EU Agency for Railways mandates radar-compatible interfaces for ERTMS deployment, directing infrastructure manager procurement.
- Traffic Monitoring:Real-time rolling stock separation measurement feeds train control algorithms for headway optimization.
- Autonomous Operations:Sensor fusion architectures merging radar returns with lidar point clouds enable driverless operational modes. China's intercity network expansion specifies these layers as mandatory for unmanned lines.
- Maintenance Planning:Predictive track geometry assessment displaces scheduled manual inspection, redirecting capital toward fixed sensing infrastructure.
Obstacle Detection commands the largest safety-budget allocation; Autonomous Operations is gaining share fastest on regulatory mandate timelines.
End User:
Procurement authority and technical specification control diverge across public and private rail governance structures.
- Rail Operators:Freight and passenger carriers specify onboard and wayside sensing for collision avoidance and operational efficiency. North American Class I networks restructure demand around Positive Train Control compliance deadlines.
- Infrastructure Managers:Track-owning authorities in Germany, France, and Italy control fixed-asset sensing deployment for ETCS integration.
- Technology Providers:System integrators bundle hardware with algorithm development and cloud analytics, though European unbundling trends fragment contracting models.
- Government Agencies:National regulators in China, India, and Japan set mandatory technical standards that determine product market access thresholds.
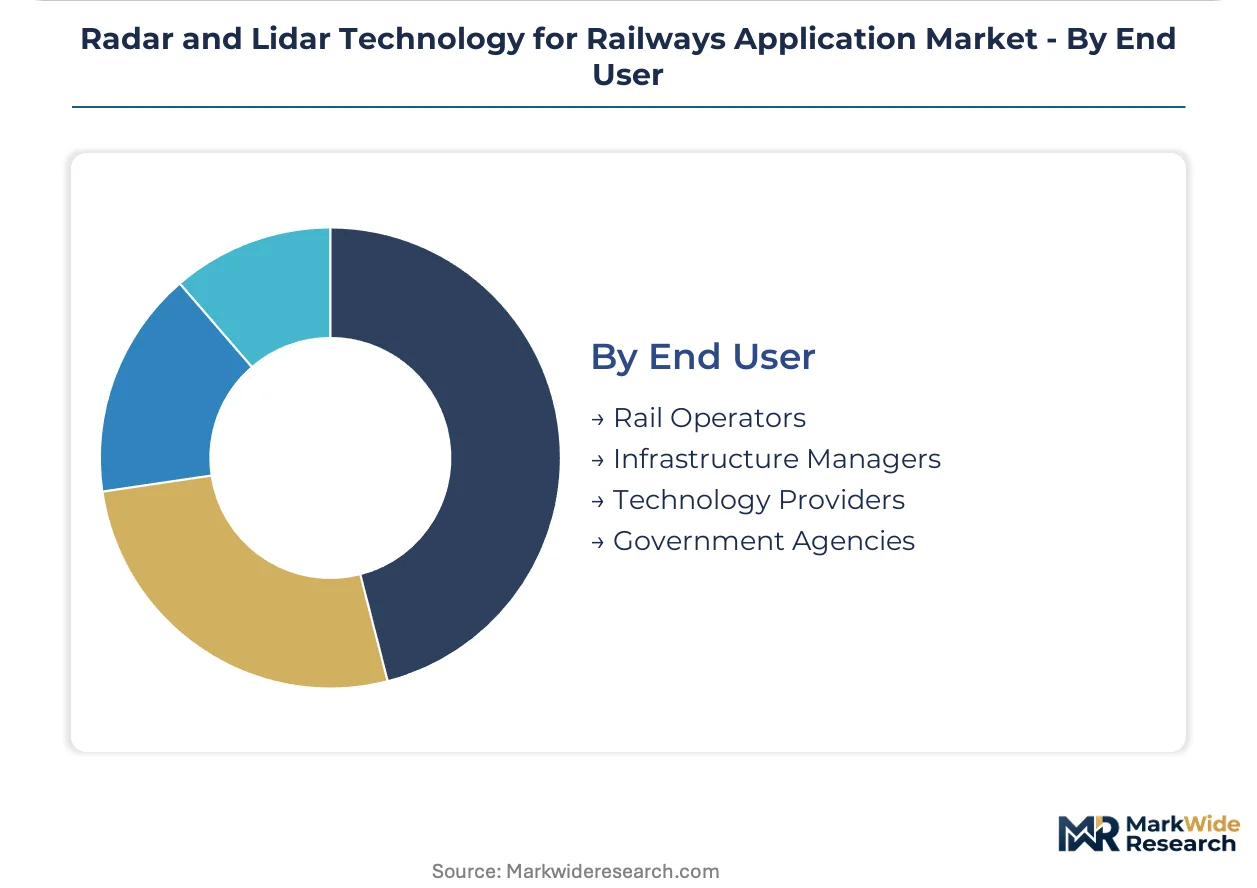
Infrastructure Managers direct the majority of fixed-asset procurement; Technology Providers are expanding most quickly on sensor-as-a-service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate MIIT-certified lidar module production for unmanned metro deployments. Germany's Ruhr industrial corridor anchors radar manufacturing for ERTMS Level 3 integration. Japan's Kansai region hosts solid-state photonic array development for platform screen door synchronization.
China
Intercity rail expansion across the Pearl River Delta drives procurement of 3D lidar modules for driverless operational modes. MIIT and NMPA jointly administer GB standard conformity assessment, tightening market access for imported sensors. Shenzhen and Guangzhou metro authorities mandate domestic-certified photonic arrays for all new unmanned line construction.
Germany
Deutsche Bahn's ETCS migration program compels infrastructure managers to deploy radar-compatible train-to-track interfaces across the Cologne-Frankfurt high-speed corridor. The EU Agency for Railways enforces ERTMS deployment mandates that specify electromagnetic sensing protocols. Bavaria's rail technology cluster around Munich hosts development centers for SIL-rated safety software stacks.
Japan
Tokyo Metro and JR East specify chip-scale 905 nm lidar arrays that unify obstacle detection with train positioning subsystems. METI promotes domestic photonics manufacturing through JIS standard alignment for railway safety equipment. Osaka-Kobe industrial corridor houses solid-state sensor foundries serving platform screen door synchronization projects.
United States
North American Class I freight networks restructure procurement around Positive Train Control compliance deadlines across the Chicago rail hub. The FRA mandates certified obstacle-detection layers for heavy-haul corridors where precipitation degrades optical performance. Illinois and Texas host integration facilities for millimeter-wave radar deployments on precipitation-prone routes.
India
The Dedicated Freight Corridor Corporation specifies obstacle-detection layers for 3,360 km of new track where no incumbent sensing infrastructure exists. Indian Railways and the CEA coordinate technical standards for automated track surveillance systems. Gujarat and Maharashtra industrial zones attract sensor assembly operations serving Delhi-Mumbai freight routes.
Radar and Lidar Technology for Railways Application Market Competitive Landscape
Top-tier vendors anchor ERTMS-certified safety architectures, while mid-tier specialists compete on retrofit economics for legacy analog interlocking integration. The vendor base stratifies across EN 50126/8/9 qualification holders and unqualified challengers frozen out by eighteen-month certification cycles. European signaling heritage groups compete against Asian photonics fabricators, with all-weather radar specialists occupying distinct procurement channels from solid-state lidar developers. Dominant competitive moves include strategic partnerships for sensor fusion architectures and geographic expansion into Indian greenfield corridor projects.
Within the European signaling heritage tier, Siemens Mobility and Thales Group exemplify vendors leveraging ETCS integration mandates to anchor premium positioning in digital interlocking projects. Navtech Radar occupies a distinct archetype among all-weather radar specialists serving precipitation-prone heavy-haul geographies. These three entities represent the dominant competitive configurations: integrated signaling-lidar platforms, radar-only precipitation specialists, and multi-modal safety system bundlers.
| Leading Market Players |
|---|
| Bosch Mobility Solutions |
| Navtech Radar |
| Leica Geosystems AG |
| Radarxense BV |
| DEUTA-WERKE GmbH |
| BlackBerry Limited |
| Siemens Mobility |
| Thales Group |
| Trimble Inc. |
| Others |
Value Network & Pricing Analysis
European signaling heritage groups, rolled up through private equity consolidation over the past decade, anchor premium pricing tiers through captive EN 50126/8/9 certification assets while Asian photonics fabricators compete on spot inventory economics. This ownership pattern concentrates pricing power with qualified vendors who can absorb eighteen-month SIL-rated qualification cycles, forcing unqualified challengers toward discount positioning or component supply roles.
Pricing Analysis
Premium pricing for compressed lead times separates qualified EN 50126/8/9 vendors from spot-market component suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Asian photonics fabricators are flooding 905 nm transmitter modules into non-safety-critical retrofit channels. Infrastructure managers in European ETCS programs show least price sensitivity, while North American Class I freight operators restructure procurement around PTC compliance deadlines with acute volume-scale bargaining power.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries producing 1550 nm lidar transmitter components. Manufacturing concentrates in China, Japan, and South Korea for solid-state photonic arrays and millimeter-wave radar modules. Raw material dependencies include indium phosphide substrates, gallium arsenide wafers, and specialized optical coatings. Tariff exposure on Chinese-manufactured components threatens lead-time volatility for European and North American integrators. Distribution runs through system integrators who bundle hardware with algorithm development and cloud analytics, though European unbundling trends fragment this structure toward direct procurement by infrastructure managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radar and lidar technology for railways application market is becoming a vertical-integration race as vendors seek upstream control over 1550 nm transmitter fabrication and downstream capture of sensor-as-a-service recurring revenue streams.
For Market Incumbents: To counter Asian photonics fabricators flooding 905 nm spot markets, Siemens Mobility and Thales Group should deepen backward integration into solid-state lidar chip fabrication through captive foundry investments or exclusive offtake agreements with East Asian suppliers. Certification investment in dual SIL-rated and FRA-compliant product architectures preserves multi-continental bidding eligibility against margin erosion from single-market specialists. For New Entrants and Emerging Players: System integrators with open API competency represent the most accessible channel partner type for unqualified vendors frozen out of direct safety-critical procurement. White-space targets include Indian Dedicated Freight Corridor projects where no incumbent sensing infrastructure exists and Scandinavian markets mandating unbundled sensor-as-a-service contracting. A go-to-market angle through predictive maintenance algorithm licensing bypasses hardware certification barriers while capturing recurring revenue. For Investors and Strategic Acquirers: MIIT certification timeline acceleration for domestic Chinese lidar modules is the leading indicator that regulatory preference is hardening around sovereign-controlled supply chains, compressing market access for imported sensors. Long-term viability favors vertically integrated photonics fabricators with captive 1550 nm transmitter capacity and dual-architecture certification assets spanning European SIL and North American FRA pathways. The signal to monitor is Deutsche Bahn's ETCS migration procurement awards, which will anoint preferred vendor tiers for the next decade of European high-speed deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photonics Fabrication | Captive 1550 nm transmitter capacity insulates against East Asian foundry concentration and tariff exposure. |
| Dual-Certification Architecture Development | Parallel EN 50126/8/9 SIL and FRA-compliant product lines preserve bidding eligibility across incompatible safety regimes. |
| Sensor-as-a-Service Model Launch | Unbundled hardware procurement with recurring algorithm updates captures Scandinavian infrastructure manager mandates. |
| Open API Standard Adoption | Standardized obstacle-detection data feeds align with European state rail authority procurement specifications. |
| Indian Greenfield Corridor Partnership | Dedicated Freight Corridor Corporation specifications for 3,360 km of new track create anchor customer relationships. |
Research Methodology
Document review covered EU Agency for Railways ERTMS deployment mandates, FRA Positive Train Control regulatory filings, and MIIT GB standard conformity assessments, complemented by interviews with infrastructure managers at Deutsche Bahn and JR East, functional safety engineers with EN 50128 software competency, and procurement leads at North American Class I freight networks. Secondary validation drew from customs trade data on photonics component flows, SEC filings of listed signaling vendors, and ERTMS deployment progress reports. Bottom-up sensor shipment estimates triangulated against top-down infrastructure capital expenditure allocations across the analysis window.
Cross-referencing historical ERTMS deployment curves against expert panel input on unmanned metro expansion timelines shaped the analytical framework. Segmentation dimensions modeled include product type, technology wavelength, application safety-criticality, and end-user procurement authority. CAGRs were derived from curve-fitting observed procurement volumes against regulatory mandate deadlines. Industry-specific forecast inputs encompassed ETCS Level 3 migration schedules and Chinese intercity rail construction permits.
Caveats apply where ERTMS deployment timeline slippage or Chinese regulatory preference shifts toward domestic suppliers could materially shift the outlook. Forecasts reflect assumptions about certification cycle durations and foundry capacity expansion that remain sensitive to geopolitical friction. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Train Transformer Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Digital Railway Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
Railway After-Cooler Market