
 Global Autonomous Trains Market | 2026-2036
Global Autonomous Trains Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autonomous Trains Market Analysis
The EU Green Deal's modal shift targets for freight and passenger transport is restructuring procurement priorities across European rail networks. Siemens AG leverages its digital signaling portfolio to anchor automated corridor projects in Germany and Austria. Alstom SA competes through integrated platform-screen door systems paired with its Urbalis communication-based train control technology. Hitachi Rail navigates the Japanese regulatory environment while extending its European presence through converged AI-based control platforms.
Autonomous trains integrate sensor fusion arrays, vehicle-to-ground communication links, and algorithmic decision engines to execute acceleration, braking, and routing without continuous human intervention. The systems achieve positioning precision through doppler radar, lidar, and balise transponder networks operating at sub-meter accuracy. Passenger trains dominate current deployment value, though freight trains represent the fastest-expanding segment as mining and port logistics operators pursue continuous-operation models. Communication-based train control captures the largest installed base, while AI-based control platforms concentrate emerging margin pools through software licensing and predictive maintenance overlays.
The European Union Agency for Railways enforces ERTMS/ETCS compatibility mandates that shape supplier certification pathways and lock in technical architectures for cross-border services. China's NMPA and Ministry of Transport coordinate GB standard updates that govern signal system interoperability across provincial high-speed networks. Japan's METI subsidizes automated transit demonstrations through its Society 5.0 framework, conditioning market access on JIS-compliant safety validation. Stakeholders must track divergence between European interoperability mandates and China's domestically standardized ecosystem to calibrate platform development roadmaps.
Market Dynamics
The European Union Agency for Railways' ERTMS/ETCS compatibility mandates are compressing supplier certification timelines and locking technical architectures for cross-border autonomous corridors, while China's GB standard updates create a parallel standardization gravity well that fragments global platform development roadmaps.
Growth Catalysts
- EU Green Deal modal shift targets:The framework restructures procurement priorities across European freight and passenger networks, mandating rail capacity expansion that favors automated systems for frequency optimization.
- Urban metro labor cost pressures:Asia-Pacific operators deploy Grade of Automation 4 systems to eliminate driver positions and enable 90-second headways on saturated corridors.
- Sensor fusion positioning arrays:Doppler radar, lidar, and balise transponder networks achieving sub-meter accuracy enable safe operation without continuous human intervention.
Market Restraints
- Copper and rare-earth magnet cost volatility:Traction motor and permanent magnet supply chains concentrate in Chinese processing facilities, exposing European and Japanese integrators to input price swings.
- Cross-border regulatory friction:Divergence between EU interoperability mandates and China's domestically standardized ecosystem forces redundant certification investments for global suppliers.
- Legacy signaling infrastructure lock-in:Existing trackside equipment depreciation cycles extend 25-40 years, delaying full CBTC replacement in mature networks.
Strategic Opportunities
- Indian suburban rail automation:The Ministry of Railways' Mumbai-Ahmedabad high-speed corridor and Delhi-Meerut RRTS create first-mover openings for Grade of Automation 3-4 deployments.
- AI-based predictive maintenance overlays:Software licensing models for algorithmic decision engines capture recurring revenue streams beyond hardware installation.
- Port and mining freight corridors:Continuous-operation models in Australian iron ore networks and Middle East container terminals bypass passenger safety certification complexity.
Industry Challenges
- Functional safety engineer scarcity:EN 50126/50128/50129 certification expertise concentrates in German and French engineering pools, constraining project ramp rates.
- Legacy system integration complexity:Mixed-traffic corridors requiring interoperability between automated and manually operated trains demand bespoke signaling overlays.
- Extended safety validation timelines:JIS-compliant demonstration requirements under Japan's METI subsidy framework condition market access on multi-year field trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autonomous Trains Market |
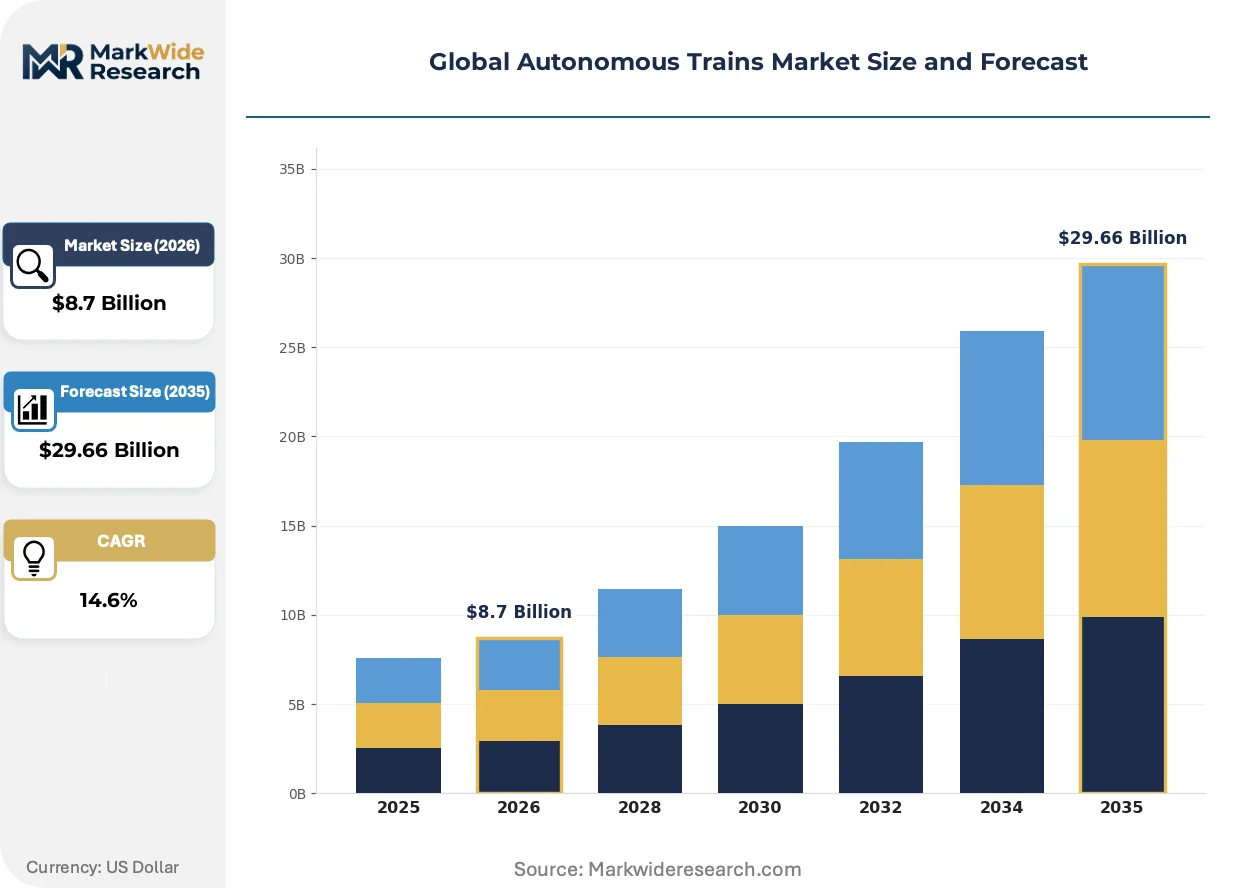
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Trains, Freight Trains, Light Rail, Monorail Technology: AI-Based Control, Communication-Based Train Control, Sensor Technology, Autonomous Navigation End User: Public Transit Authorities, Freight Operators, Private Operators, Logistics Companies Installation: Onboard Systems, Ground Infrastructure, Hybrid Systems, Combined Solutions |
| Companies Covered | CRRC Corporation Limited, Thales Group, Siemens AG, Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Alstom SA, Wabtec Corporation, CAF, Hitachi Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autonomous Trains Market Emerging Trajectories
Algorithmic control architectures are displacing hardware-centric signaling, compressing margins on traditional equipment while expanding software and data service addressable markets across passenger and freight applications.
Communication-based train control is consolidating positioning and movement authority functions into unified vehicle-to-ground data links. Urban metro operators in Germany and Austria adopt these systems to eliminate trackside signal infrastructure. The technology is consolidating supplier value capture into software licensing and predictive maintenance subscriptions.
The EU AI Act's risk classification framework subjects autonomous train decision engines to conformity assessment procedures, extending certification timelines for algorithmic braking and routing systems. European manufacturers now embed explainability requirements into control platform development. Freight corridors crossing German-Austrian borders face the steepest compliance cost increases.
Buyer concentration among state-owned rail operators is compressing vendor negotiation cycles and unbundling after-sales service contracts. Chinese and European procurement offices now separate hardware purchase from long-term software maintenance agreements. This pattern is most visible in CRRC's high-speed network expansions and Deutsche Bahn's digital signaling upgrades.
Global Autonomous Trains Market Segmentation
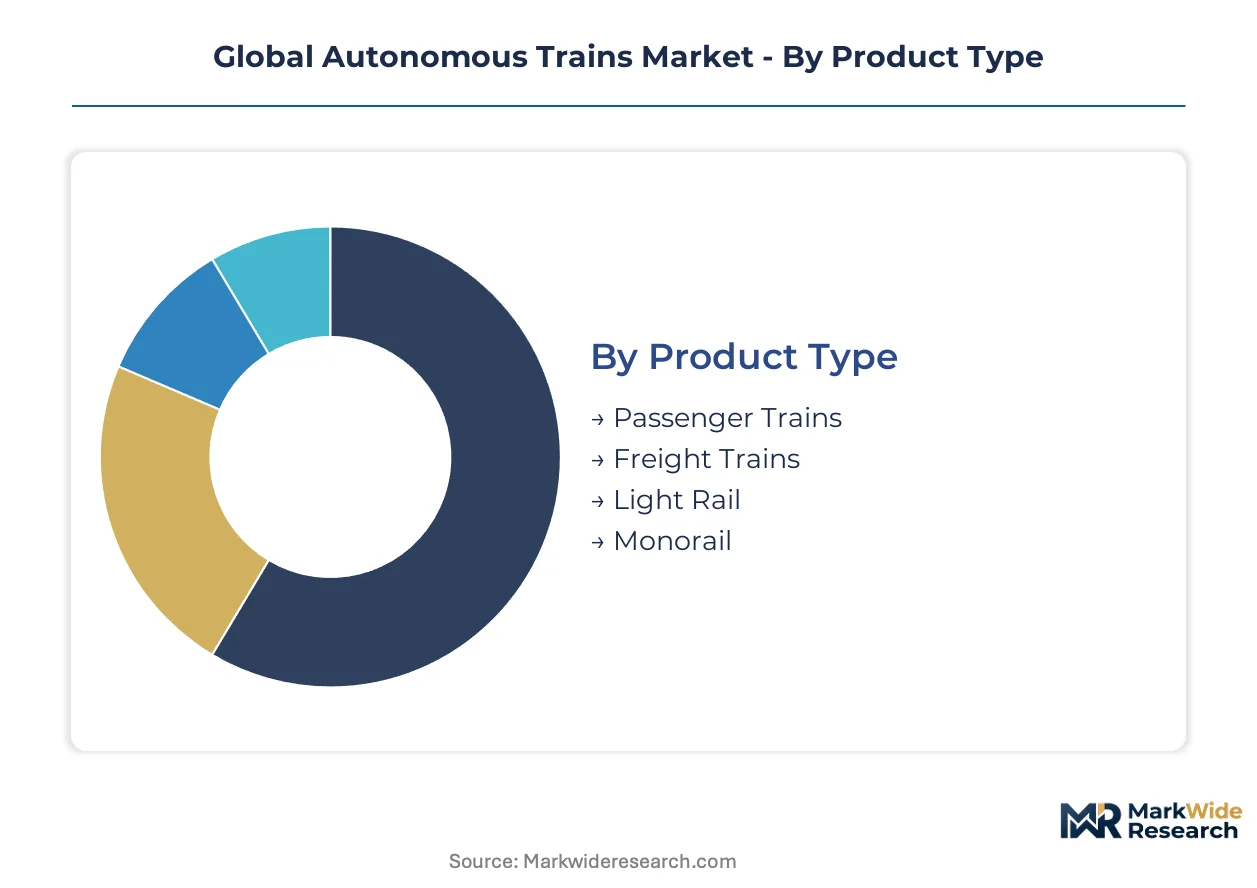
Autonomous train deployments diverge sharply across operational contexts, with passenger safety mandates, freight economics, and infrastructure legacy each dictating distinct technology configurations and procurement timelines. Segment boundaries reflect these divergent buyer priorities rather than uniform technology diffusion.
Product Type:
Freight operators prioritize continuous operation and labor elimination, while passenger authorities balance frequency gains against public safety certification burdens.
- Passenger Trains:Urban metro and intercity services deploy Grade of Automation 4 systems to compress headways below 90 seconds on saturated corridors. China's high-speed network anchors current procurement volume, with state operators mandating platform-screen door integration and balise-based positioning at sub-meter accuracy.
- Freight Trains:Mining and port logistics operators pursue driverless continuous-operation models that bypass passenger safety complexity. Australian iron ore networks and Middle East container terminals represent concentrated demand for heavy-haul autonomous corridors.
- Light Rail:Street-running tram networks integrate collision avoidance arrays and pedestrian detection sensors for mixed-traffic environments.
- Monorail:Elevated guideway systems in dense Asian megacities exploit structural isolation to accelerate GoA4 certification timelines.
Volume sits with Passenger Trains; growth tilts toward Freight Trains.
Technology:
Control architecture choices determine supplier margin structures, with hardware-centric signaling giving way to software licensing and predictive maintenance overlays.
- Communication-Based Train Control:Unified vehicle-to-ground data links consolidate positioning and movement authority functions, eliminating trackside signal infrastructure. German and Austrian urban metros anchor installed base expansion.
- AI-Based Control:Algorithmic decision engines for braking and routing face extended EU AI Act conformity assessments, embedding explainability requirements into platform development. European manufacturers absorb steepest compliance cost increases on cross-border corridors.
- Sensor Technology:Doppler radar, lidar, and transponder arrays achieve positioning precision for safe intervention-free operation.
- Autonomous Navigation:Self-contained positioning systems reduce ground infrastructure dependency for remote freight corridors.
Revenue concentrates in Communication-Based Train Control; margin expansion favors AI-Based Control.
End User:
Public procurement cycles and private capital availability create divergent deployment velocities across buyer categories.
- Public Transit Authorities:State-owned operators in China and Europe unbundle hardware purchase from long-term software maintenance agreements. Mumbai-Ahmedabad and Delhi-Meerut corridors in India create first-mover openings for Grade of Automation 3-4 deployments.
- Freight Operators:Mining and bulk commodity networks prioritize continuous-operation economics over certification speed. Australian and Brazilian iron ore railways drive heavy-haul automation adoption.
- Private Operators:Airport and campus shuttle systems exploit captive infrastructure to accelerate field trials.
- Logistics Companies:Port terminal operators integrate autonomous yard movements with automated vessel loading systems.
Procurement scale favors Public Transit Authorities; deployment velocity favors Freight Operators.
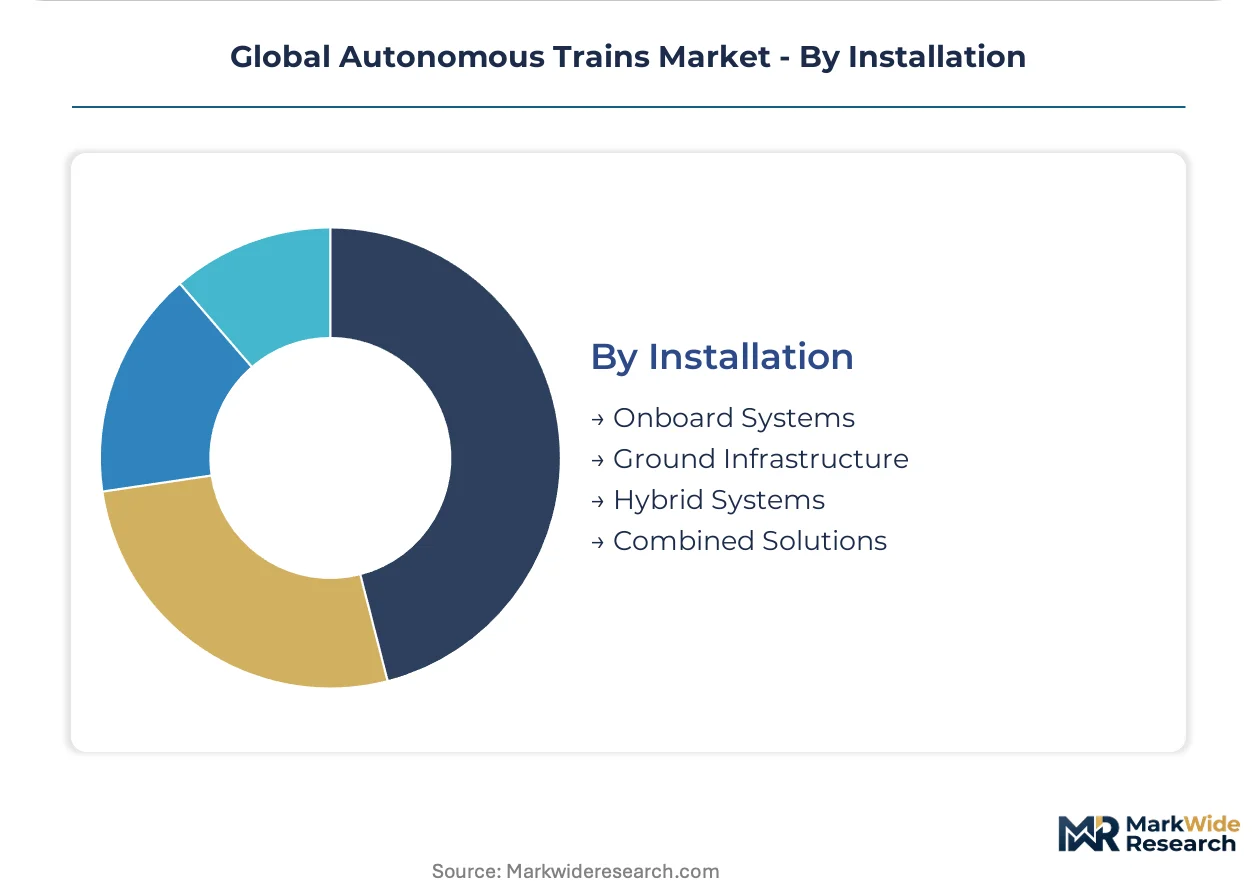
Installation:
System architecture choices reflect legacy infrastructure density and corridor isolation levels.
- Onboard Systems:Vehicle-integrated control platforms reduce trackside capital expenditure for greenfield deployments. CRRC's high-speed expansions and Deutsche Bahn's digital signaling upgrades demonstrate concentrated demand for integrated onboard packages.
- Ground Infrastructure:Trackside balise networks and centralized traffic management systems dominate mature network retrofits. Existing equipment depreciation cycles extending 25-40 years delay full replacement in European and Japanese networks.
- Hybrid Systems:Mixed configurations balance legacy compatibility with automation gains on transitional corridors.
- Combined Solutions:Turnkey integration of onboard and ground elements addresses fragmented supplier accountability.
Investment flows favor Onboard Systems; retrofit necessity sustains Ground Infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing anchors the world's most extensive autonomous rail deployment, with CRRC and state operators commissioning Grade of Automation 4 systems across provincial high-speed networks. This concentration shapes supplier certification requirements and technical roadmaps for the broader industry.
China
Beijing-Shanghai and Chengdu-Chongqing corridors drive the bulk of GoA4 procurement volume. The Ministry of Transport coordinates GB standard updates that govern signal system interoperability across provincial networks. CRRC's manufacturing clusters in Changchun and Qingdao integrate platform-screen door systems with balise-based positioning at sub-meter accuracy.
Germany
Deutsche Bahn's Stuttgart-Ulm digital signaling upgrade and Hamburg S-Bahn automation anchor European demand. The EU Agency for Railways enforces ERTMS/ETCS compatibility mandates that compress supplier certification timelines. Siemens AG leverages its Munich-based engineering pools to anchor automated corridor projects with Austrian Federal Railways.
Japan
Tokyo Metro and Osaka Municipal Subway accelerate GoA4 conversions on saturated urban corridors. METI subsidizes automated transit demonstrations through its Society 5.0 framework, conditioning market access on JIS-compliant safety validation. Hitachi Rail and Kawasaki Heavy Industries concentrate development in Kobe and Yokohama manufacturing zones.
India
Mumbai-Ahmedabad high-speed corridor and Delhi-Meerut RRTS create first-mover openings for Grade of Automation 3-4 deployments. The Ministry of Railways mandates domestic content requirements through its Make in India procurement guidelines. Bharat Heavy Electricals and Titagarh Rail Systems cluster manufacturing around Kolkata and Chennai industrial corridors.
Australia
Fortescue Metals and Rio Tinto operate driverless iron ore railways across Pilbara mining districts. The National Transport Commission coordinates heavy-haul safety standards that bypass passenger certification complexity. Autonomous haulage corridors between Newman and Port Hedland represent concentrated freight automation demand.
Global Autonomous Trains Market Vendor Landscape
The competitive structure tilts toward integrated signaling specialists with captive trackside installation capabilities. European and Chinese markets exhibit divergent consolidation patterns: EU procurement fragments across national rail operators while China's state-owned ecosystem concentrates buyer power. Two strategic archetypes dominate—vertically integrated rolling stock manufacturers and pure-play signaling technology licensors. Competitive moves center on unbundling hardware purchase from software maintenance agreements and backward integration into sensor fusion component supply.
Among Chinese state-affiliated manufacturers, CRRC Corporation Limited anchors the rolling stock-integrated archetype. Siemens AG and Alstom SA occupy positions within the European signaling-specialist tier, each representing distinct approaches to ERTMS/ETCS platform development. Thales Group exemplifies the defense-technology crossover model, leveraging dual-use sensor expertise for rail applications.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Thales Group |
| Siemens AG |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Alstom SA |
| Wabtec Corporation |
| CAF |
| Hitachi Rail |
| Others |
Supply Flow & Price Mechanics
Deutsche Bahn's unbundling of hardware purchase from software maintenance agreements is forcing suppliers to restructure revenue models and absorb upfront margin compression. This procurement pattern, now visible across European and Chinese state operators, concentrates pricing power with buyers while fragmenting supplier cash flow predictability.
Pricing Analysis
Outcome-based pricing tied to system uptime and throughput guarantees anchors premium tiers in autonomous train contracts. Three-tier pricing structure across premium, standard, and economy levels separates Grade of Automation 4 integrated platforms from modular CBTC upgrades and legacy retrofit kits. Price differentiation hinges on EN 50126/50128/50129 certification tier and geographic delivery scope. Cost compression in standard-tier hardware is intensifying because CRRC's domestic manufacturing clusters undercut European integrators on traction motor assemblies. Freight operators in Australian mining corridors exhibit lowest price sensitivity due to continuous-operation economics, while Indian suburban authorities face acute budget constraints under Make in India procurement guidelines.
Supply Chain Analysis
India's domestic content requirements and China's GB standard mandates are reshaping sourcing patterns for foreign integrators seeking market access. Permanent magnet and rare-earth processing concentrates in Chinese facilities, while traction motor manufacturing clusters sit in Germany and Japan. Control system assembly draws from South Korean semiconductor foundries and Taiwanese sensor component suppliers. Single-source vulnerability in Chinese rare-earth refining exposes European and Japanese manufacturers to input price volatility. Distribution runs through state-owned rail procurement offices in China and Europe, with turnkey integrators managing downstream installation and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity assessment procedures for algorithmic braking systems erect a compliance moat that favors incumbent signaling specialists with established certification expertise. This regulatory barrier fragments competitive entry and consolidates margin pools among pre-qualified vendors.
For Market Incumbents: Extend software licensing footprints through predictive maintenance subscriptions that capture recurring revenue beyond hardware installation cycles. Deepen backward integration into sensor fusion component supply to offset copper and rare-earth magnet cost volatility. Alstom SA and Siemens AG must defend against Chinese state-affiliated manufacturers by anchoring cross-border corridor projects with ERTMS/ETCS platform standardization. For New Entrants and Emerging Players: The gap between premium GoA4 integrated platforms and economy-tier legacy retrofits creates entry space for modular AI-based control overlays. Target Indian suburban rail automation through Delhi-Meerut RRTS and Mumbai-Ahmedabad corridor deployments where domestic content requirements favor local partnerships. Lead with algorithmic decision engine licensing that bypasses capital-intensive rolling stock manufacturing. For Investors and Strategic Acquirers: The window for entry favors pure-play signaling technology licensors with captive EN 50126/50128/50129 certification expertise. Long-term viability rests on software margin expansion and regulatory compliance lock-in rather than hardware volume scaling. Watch for EU Agency for Railways acceleration of ERTMS/ETCS mandates across Eastern European corridors as the inflection signal for consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Software Licensing Expansion | Predictive maintenance subscriptions capture recurring revenue beyond hardware installation at Deutsche Bahn. |
| Backward Integration | In-house production of sensor fusion arrays reduces exposure to Chinese rare-earth processing volatility. |
| Certification Pre-Qualification | Early EU AI Act conformity assessment completion locks out later entrants from German-Austrian corridor bidding. |
| Domestic Partnership Formation | Joint ventures with Bharat Heavy Electricals satisfy Make in India requirements for Delhi-Meerut RRTS deployment. |
| Freight Corridor Specialization | Continuous-operation models in Pilbara mining districts bypass passenger safety certification complexity and accelerate deployment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with signaling system engineers, rail procurement officers at state-owned operators, functional safety certification specialists, and ERTMS/ETCS project managers combined with secondary validation from EU Agency for Railways safety directives, Chinese Ministry of Transport GB standard updates, and Japan METI Society 5.0 framework documentation. Bottom-up deployment tracking across Grade of Automation tiers reconciled with top-down market sizing from rolling stock manufacturer order backlogs.
Data-stream reconciliation across vehicle-to-ground communication system shipments, balise transponder network installations, and AI-based control platform licensing disclosures shaped the analytical framework. Segmentation dimensions modeled include automation grade tier, control architecture type, end-user category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement pipeline data and technology substitution rates. Industry-specific forecast inputs incorporated copper and rare-earth price trajectory assumptions alongside ERTMS/ETCS mandate acceleration scenarios.
Inputs from EU Agency for Railways certification databases and China NMPA signal system registries were available through the study window; gaps in Indian Make in India procurement transparency and Japanese JIS-compliant safety validation timelines introduce uncertainty bands around deployment velocity assumptions. Forecasts reflect documented procurement patterns and regulatory mandate schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Rail Pads Market
Railway Transportation
Global Railway Wiring Harness Market