
 Digital Railway Market | 2026-2036
Digital Railway Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Railway Market Intelligence
The shift from proprietary, closed-loop hardware systems to open-architecture, software-defined platforms is fragmenting the traditional supply base. Siemens leverages its deep domain expertise in signaling and rolling stock to offer integrated digital portfolios. Alstom competes on the strength of its advanced traffic management and predictive maintenance solutions. Thales Group differentiates with its cybersecurity and data analytics capabilities for rail operations.
A digital railway integrates information and communication technologies to optimize rail network performance, safety, and capacity. This involves deploying IoT sensors on tracks and trains to feed real-time data into centralized control systems. Its primary purpose is to enable predictive maintenance, automate train control, and improve passenger experience. Within solutions, predictive maintenance and traffic management systems command significant investment from rail operators.
The European Union's ERTMS standards mandate interoperability, creating a unified market for signaling suppliers. In the United States, the Federal Railroad Administration enforces Positive Train Control regulations, driving technology adoption for safety. China’s national railway standards, managed under authorities like the National Railway Administration, dictate technical specifications for its vast network. Vendor selection will increasingly hinge on the ability to demonstrate compliance with these diverse regional standards and ensure robust cybersecurity.
Market Dynamics
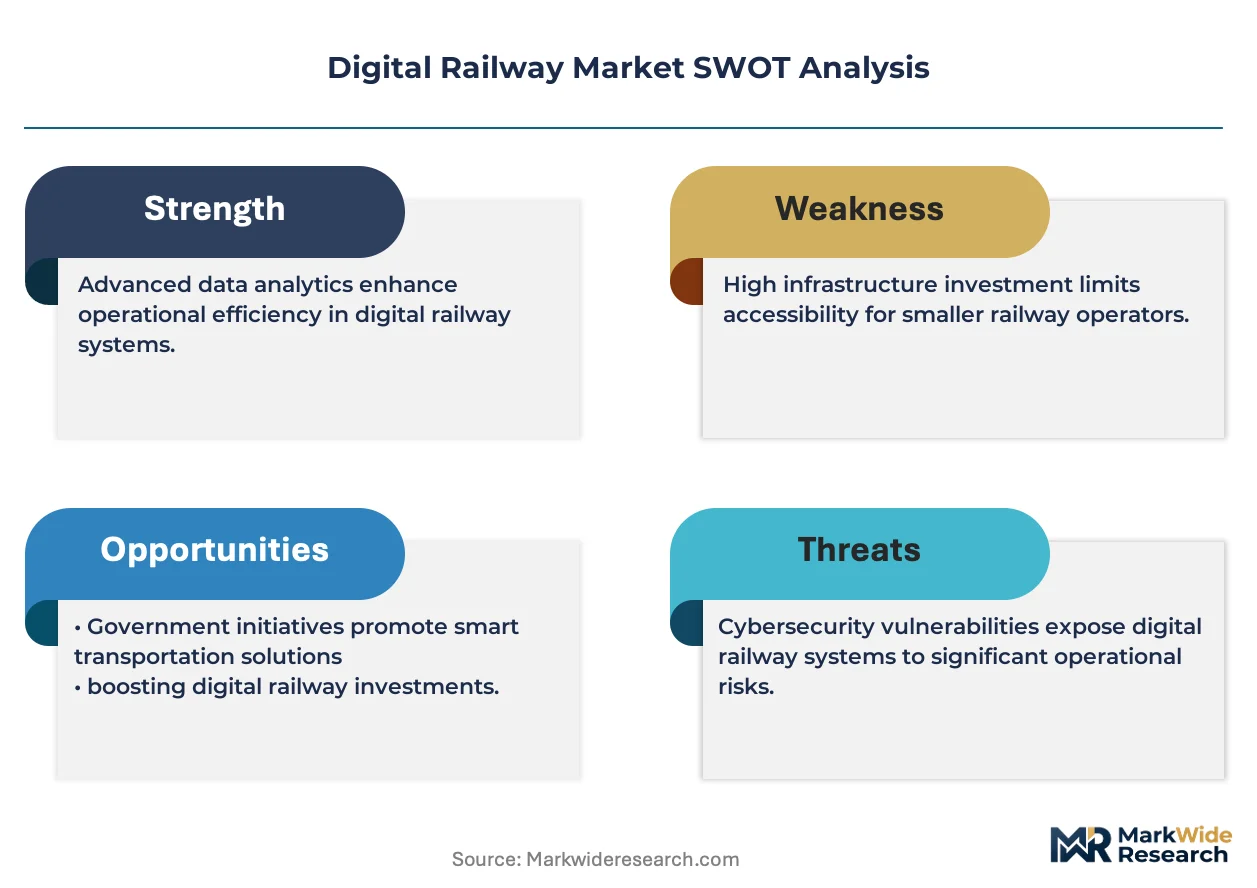
The central force shaping the digital railway market is the industry-wide push for standardization and interoperability. This creates a structural tension between incumbent vendors' proprietary, closed-loop systems and the operator-led demand for open-architecture, multivendor platforms mandated by regulations.
Growth Catalysts
- Regulatory Mandates:The European Union's binding requirement for European Rail Traffic Management System (ERTMS) deployment on core network corridors compels operators to invest in compliant, interoperable digital signaling and train control systems.
- Network Modernization:China's extensive high-speed rail construction and network upgrades necessitate the large-scale adoption of advanced digital solutions for traffic management, control, and safety to manage one of the world's most complex systems.
- Operational Efficiency:The drive to reduce operational expenditures and enhance asset availability pushes rail operators to invest in IoT-enabled predictive maintenance solutions, which use sensor data to forecast equipment failures and optimize maintenance schedules.
Market Restraints
- High Capital Outlay:The substantial upfront investment required to install new digital infrastructure and retrofit vast fleets of legacy rolling stock and signaling systems presents a significant financial barrier for many rail operators.
- Legacy System Integration:Extreme technical complexity and risk are involved in integrating new open-platform digital systems with decades-old, proprietary analog or closed-loop hardware, often leading to prolonged and costly projects.
- Cybersecurity Vulnerabilities:Increasing connectivity of critical operational technology (OT) systems to IT networks exposes railways to a growing threat of cyberattacks, creating safety risks and necessitating significant investment in specialized security measures.
Strategic Opportunities
- Greenfield Deployments:Rail projects in developing regions, such as parts of Southeast Asia and Africa, offer opportunities to build fully digital networks from the ground up, bypassing the integration challenges of legacy infrastructure.
- Cybersecurity as a Service:The heightened threat landscape creates a market for specialized cybersecurity services tailored for rail operations, including continuous monitoring, threat intelligence, and incident response as a managed service.
- 5G for Rail Communications:The convergence of 5G and Future Railway Mobile Communication System (FRMCS) standards provides an opportunity to develop next-generation applications for autonomous train operation and real-time video analytics that require high-bandwidth, low-latency connectivity.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of professionals with combined expertise in railway engineering, data science, and software development hinders the ability of operators and vendors to implement and manage complex digital systems effectively.
- Interoperability Between Vendors:Ensuring seamless data exchange and functional compatibility between different digital subsystems (e.g., signaling, power, ticketing) procured from multiple vendors remains a major operational and technical challenge.
- Data Governance and Ownership:Ambiguity over the ownership and usage rights of the vast amounts of data generated by digital railway systems creates friction between operators, infrastructure managers, and technology suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Railway Market |
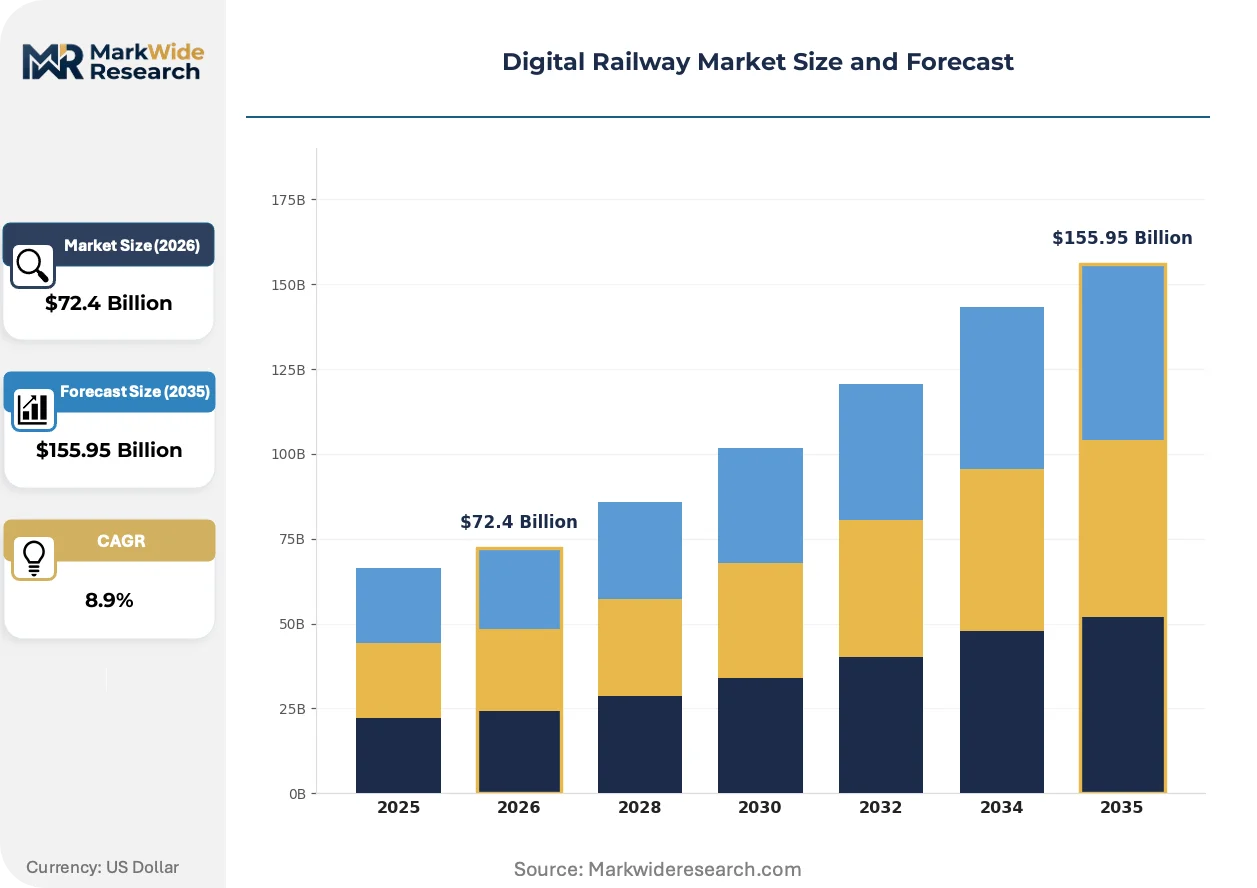
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $155.95 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Traffic Management Systems, Passenger Information Systems, Predictive Maintenance, Asset Monitoring, Signaling Control, Energy Management Technology: IoT Sensors, Big Data Analytics, Cloud Computing, AI & Machine Learning, Edge Computing, Cybersecurity Application: Freight Operations, Commuter Transit, High-Speed Rail, Urban Light Rail, Cargo Tracking, Train Scheduling End User: Rail Operators, Infrastructure Managers, Transport Authorities, Logistic Companies, Maintenance Providers, Fleet Managers |
| Companies Covered | Huawei, ABB Group, Siemens, Wabtec Corporation, CRRC Corporation Limited, Alstom, Cisco, Thales Group, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Railway Market Strategic Shifts & Innovations
The evolution from hardware-centric equipment to software-defined rail operations is the defining market transformation. This shift prioritizes data analytics, connectivity, and automation, fundamentally changing how rail networks are managed, maintained, and monetized.
Digital Twin technology creates a dynamic, virtual replica of physical railway assets, including tracks, signals, and rolling stock. Rail infrastructure managers and train operators are adopting this for advanced simulation and scenario planning. This technology is virtualizing asset lifecycle management, enabling operators to test maintenance strategies and operational changes in a risk-free digital environment before physical deployment.
Legislation like the European Union's AI Act is introducing new compliance layers for intelligent systems in critical infrastructure. The regulation's risk-based framework will classify AI-driven train control and predictive maintenance tools as high-risk, demanding rigorous testing, transparency, and human oversight. This affects technology vendors, who must now engineer for audibility and formal verification to gain market access in regulated geographies.
Rail operators are increasingly moving away from large, one-time capital expenditures for equipment toward more flexible, long-term service agreements for digital capabilities. This change disrupts the traditional transactional sales model, favoring suppliers who can offer comprehensive solutions that bundle hardware, software, and analytics into a single subscription. This trend is most prominent in Europe, where operators seek to align technology costs directly with performance improvements and operational efficiency gains.
Digital Railway Market Segmentation
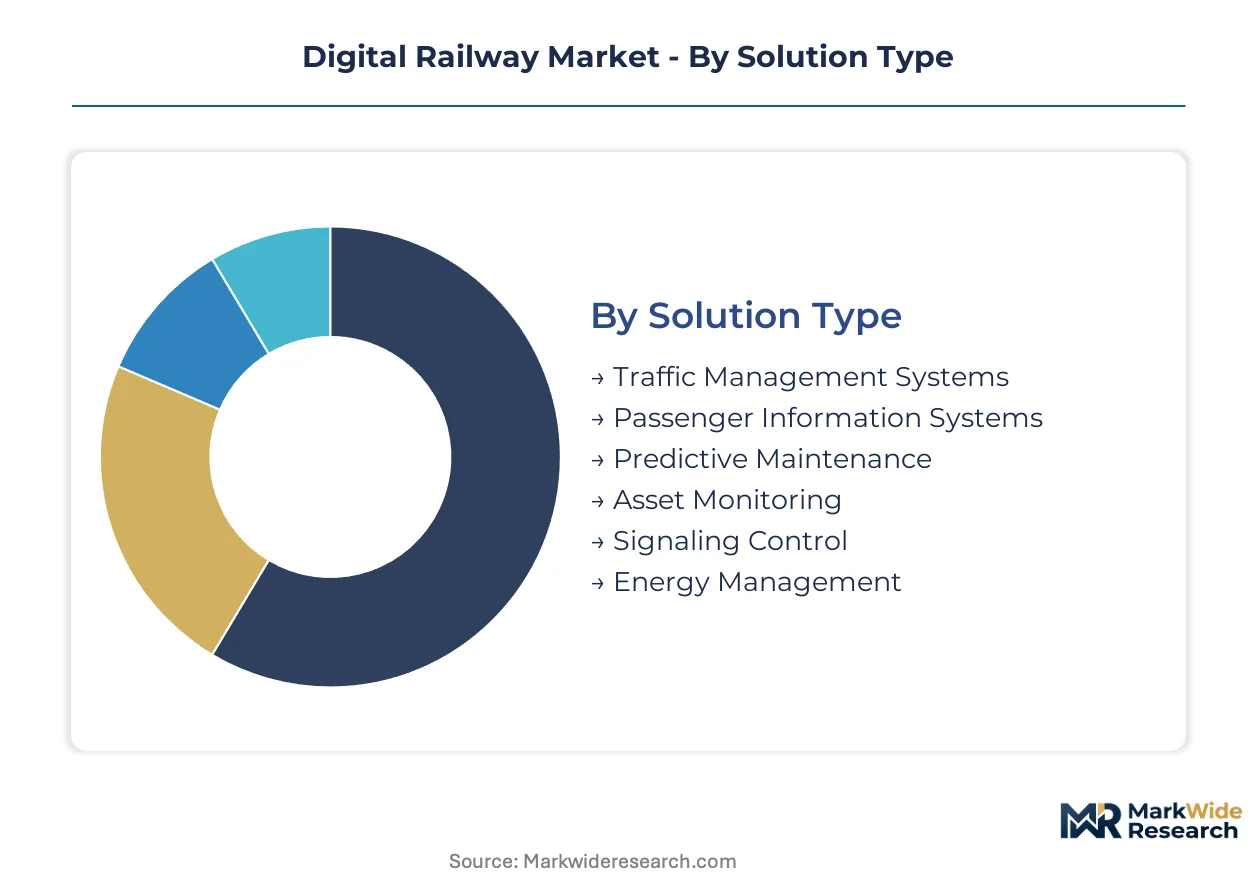
The digital railway market's intricate structure reflects diverse solution requirements and technological advancements across global rail networks. Understanding these segments is crucial for technology providers to align their offerings with specific operational needs and regulatory landscapes.
Solution Type:
The range of digital capabilities provided to rail operators defines the Solution Type segmentation.
- Predictive Maintenance:These systems leverage IoT sensor data and analytics to forecast equipment failures on tracks and rolling stock, optimizing maintenance schedules and reducing downtime. Demand concentrates in European and Chinese networks, driven by operational efficiency goals.
- Signaling Control:This segment encompasses advanced systems for managing train movements and ensuring safe separation, often mandated by standards like ERTMS in the European Union. China's extensive high-speed rail network also relies heavily on sophisticated signaling for capacity management.
- Traffic Management Systems:These solutions integrate real-time data to optimize train scheduling, routing, and network flow, improving overall operational performance.
- Passenger Information Systems:Digital displays and mobile applications provide real-time updates on train status, platforms, and connections to enhance the passenger experience.
- Asset Monitoring:Continuous surveillance of railway infrastructure components like bridges and tunnels identifies degradation and potential issues before they escalate.
- Energy Management:Solutions in this category monitor and optimize power consumption for trains and infrastructure, reducing operational costs and environmental impact.
Signaling Control commands the established base. The steepest expansion runs through Predictive Maintenance.
Technology:
The underlying technical infrastructure powering digital railway systems forms the Technology segmentation.
- IoT Sensors:These devices collect real-time data from tracks, trains, and infrastructure, feeding information into centralized control and analysis platforms. Countries like Germany and France are deploying extensive sensor networks for track monitoring.
- AI & Machine Learning:Algorithms analyze vast datasets to enable predictive maintenance, automate train control, and optimize traffic management, enhancing system intelligence. China's high-speed rail actively integrates AI for operational efficiency.
- Big Data Analytics:Tools and platforms process and interpret large volumes of operational data to derive actionable insights for performance improvement and strategic planning.
- Cloud Computing:This technology provides scalable and flexible infrastructure for hosting digital railway applications and storing extensive datasets, facilitating remote access and collaboration.
- Edge Computing:Processing data closer to the source, such as on trains or at trackside, reduces latency and enables faster decision-making for critical real-time operations.
- Cybersecurity:Robust security measures protect critical operational technology (OT) systems from cyber threats, ensuring the integrity and safety of railway operations.
IoT Sensors provide foundational data capture. AI and Machine Learning technologies are gaining momentum for advanced applications.
Application:
The specific operational contexts where digital railway solutions are deployed drive the Application segmentation.
- High-Speed Rail:These networks require advanced digital solutions for traffic management, signaling, and control to support high speeds and passenger volumes, particularly in China and Europe. ERTMS mandates significantly impact this segment in Europe.
- Commuter Transit:Urban and suburban rail systems leverage digital tools to enhance operational efficiency, manage passenger flow, and improve service reliability in dense metropolitan areas. Cities like London and Tokyo prioritize these solutions.
- Freight Operations:Digital systems optimize logistics, track cargo, and manage train movements for freight networks, improving efficiency and delivery times across continents.
- Urban Light Rail:Tram and light rail networks adopt digital solutions for signaling, passenger information, and fleet management within city environments.
- Cargo Tracking:Real-time monitoring of goods in transit provides visibility and security for logistics companies utilizing rail transport.
- Train Scheduling:Software solutions automate and optimize the complex process of planning train movements across a network, minimizing delays and maximizing capacity.
High-Speed Rail demands complex digital integration. Commuter Transit networks are rapidly adopting solutions for efficiency.
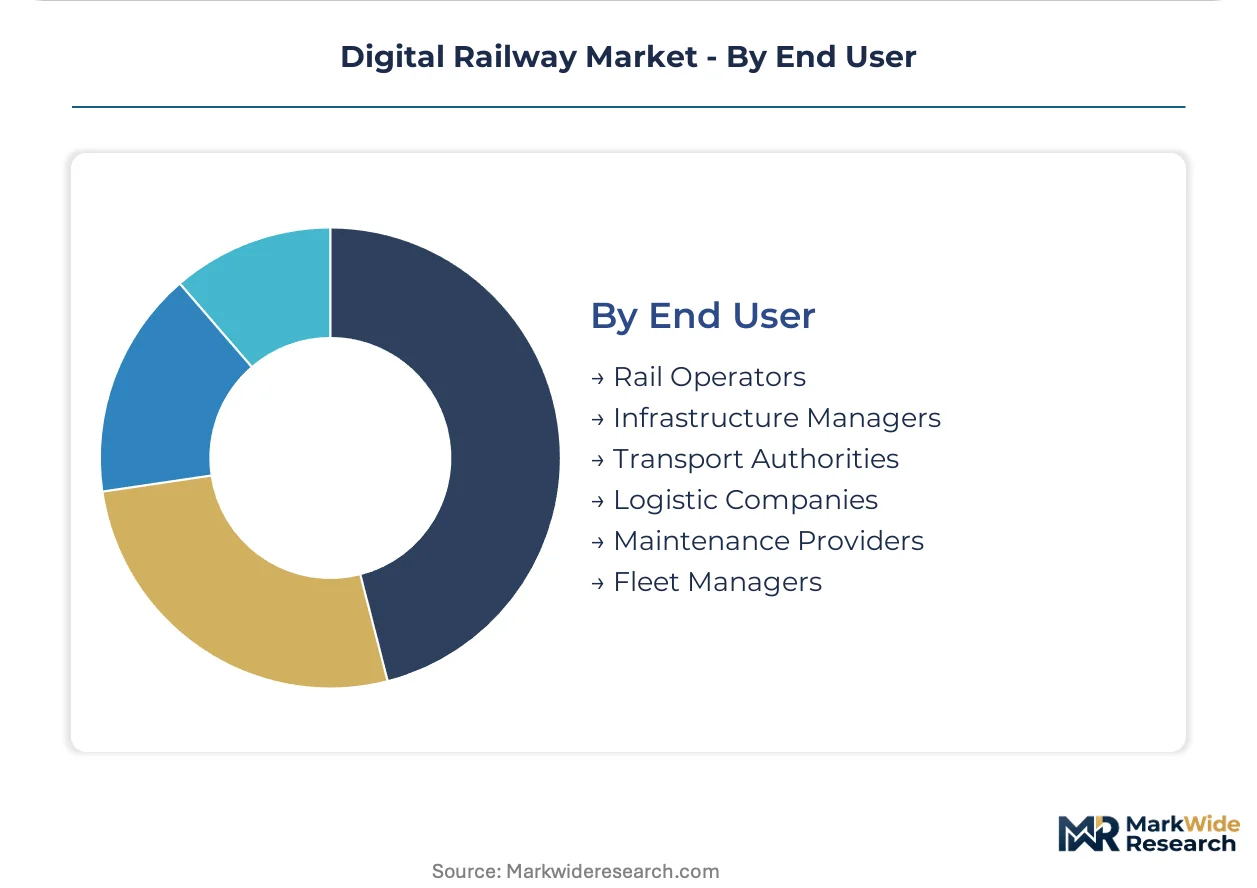
End User:
The primary beneficiaries and purchasers of digital railway systems constitute the End User segmentation.
- Rail Operators:These entities are the primary buyers, investing in digital solutions to manage train fleets, improve service delivery, and enhance passenger experience. Deutsche Bahn in Germany and SNCF in France are significant operators.
- Infrastructure Managers:Organizations responsible for maintaining tracks, signals, and other fixed assets utilize digital tools for asset monitoring, predictive maintenance, and network optimization. Network Rail in the UK exemplifies this user type.
- Transport Authorities:Government bodies and agencies overseeing public transportation systems procure digital solutions for regulatory compliance, safety oversight, and urban planning.
- Logistic Companies:Firms specializing in freight movement leverage digital railway systems for cargo tracking, supply chain optimization, and efficient rail utilization.
- Maintenance Providers:Companies offering maintenance services for railway assets use digital tools to streamline operations, manage resources, and conduct predictive repairs.
- Fleet Managers:Entities responsible for managing rolling stock procure digital solutions for vehicle health monitoring, performance optimization, and asset lifecycle management.
Rail Operators are the central end-users for digital railway solutions. Infrastructure Managers increasingly leverage these systems for network optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail operators, the primary buyers of digital railway systems, drive demand across diverse geographies. This concentration reflects significant investment in network modernization and safety enhancements. Regulatory mandates underpin much of this regional development.
China
China's extensive high-speed rail construction fuels demand for advanced digital solutions, particularly in traffic management and control. The National Railway Administration dictates technical specifications for its vast network, ensuring compliance. The Yangtze River Delta region, with its dense rail infrastructure, sees significant deployment of these systems.
Germany
German rail operators like Deutsche Bahn prioritize digital solutions for operational efficiency and predictive maintenance. The European Rail Traffic Management System (ERTMS) mandates deployment on core network corridors, influencing technology choices. Bavaria's industrial clusters contribute to the development and integration of these advanced railway technologies.
United States
The United States market sees demand driven by safety regulations and freight operations optimization. The Federal Railroad Administration (FRA) enforces Positive Train Control (PTC) regulations, compelling technology adoption. The Northeast Corridor, a high-traffic passenger route, continually upgrades its signaling and control systems.
India
India's ambitious railway modernization projects generate substantial demand for digital signaling and asset monitoring. The Ministry of Railways' initiatives, including dedicated freight corridors, promote the integration of advanced digital systems. The Delhi-NCR region, a major rail hub, serves as a testbed for new traffic management solutions.
Digital Railway Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market structure. The landscape exhibits characteristics of both consolidation among established integrators and fragmentation among niche software providers. Strategic archetypes include large-scale infrastructure providers, specialized software developers, and cybersecurity solution firms. Companies pursue strategic partnerships and portfolio diversification to enhance their market presence.
Integrated infrastructure providers like Siemens and Alstom exemplify the archetype of comprehensive solution delivery, leveraging their extensive rail domain expertise. Thales Group represents a specialized segment, focusing on cybersecurity and data analytics capabilities for rail operations. These companies anchor the market's strategic direction through their broad offerings and technological advancements.
| Leading Market Players |
|---|
| Huawei |
| ABB Group |
| Siemens |
| Wabtec Corporation |
| CRRC Corporation Limited |
| Alstom |
| Cisco |
| Thales Group |
| Hitachi |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly ERTMS and Positive Train Control mandates, dictate both pricing tier spreads and the shape of the digital railway supply chain. Compliance drives premium pricing for integrated solutions and limits market access for non-compliant vendors.
Pricing Analysis
Cost-plus contracts, often indexed to labor and critical component costs, define pricing for many large-scale digital railway deployments. Project-based implementations for signaling control and traffic management systems command significant investment. Price differentiation stems from the level of customization required for legacy integration and the breadth of after-sales service agreements. Rail operators focused on greenfield deployments exhibit lower price sensitivity for comprehensive, integrated solutions.
Supply Chain Analysis
Export-control regimes, particularly those impacting specialized sensor components and secure communication modules, constrain the digital railway supply chain. Supply concentrations are evident in China for core hardware manufacturing and in European nations like Germany and France for advanced signaling software. The industry draws from specialized semiconductors and high-bandwidth communication technologies. Single-source vulnerability for critical operational technology (OT) systems presents a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital railway market is fundamentally a service-attach opportunity, where recurring revenue from predictive maintenance subscriptions and cybersecurity-as-a-service is expanding faster than initial hardware deployments. This shift prioritizes long-term engagement over one-time transactional sales.
For Market Incumbents:
Insulate core signaling and rolling stock revenue streams by aggressively integrating open-architecture software platforms. This counters the threat of specialized software developers fragmenting traditional system sales. Deepen vertical integration into data analytics and AI capabilities to offer comprehensive, high-value digital portfolios. Pursue strategic partnerships with cybersecurity firms to address growing OT vulnerabilities.
For New Entrants and Emerging Players:
Specialized cybersecurity services for rail operational technology in Europe represent a highly penetrable entry point. Focus on offering managed threat intelligence and incident response as a service to address critical vulnerabilities. Target greenfield digital network deployments in Southeast Asia with flexible, cloud-native traffic management solutions. A direct-to-infrastructure-manager sales approach emphasizing compliance and data integrity will gain traction.
For Investors and Strategic Acquirers:
The market sits at a sustained growth phase that favors specialized software and data analytics firms with strong recurring revenue models. Long-term viability over the next decade hinges on interoperability and regulatory compliance. Acquisition targets include niche providers of AI-driven predictive maintenance or 5G-enabled communication solutions. The signal to watch is the acceleration of ERTMS Level 3 deployments across Europe, indicating readiness for advanced automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration for ERTMS Compliance | Ensures market access across European networks, critical for signaling suppliers. |
| Cybersecurity-as-a-Service Offering | Addresses rising OT system vulnerabilities, protecting rail operator assets. |
| AI-driven Predictive Maintenance Development | Optimizes asset availability, directly reducing operational expenditures for Deutsche Bahn. |
| 5G/FRMCS Communication System Investment | Enables next-generation autonomous train operation and real-time video analytics. |
| Digital Twin Deployment for Infrastructure | Virtualizes asset lifecycle management, enhancing scenario planning for Network Rail. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to validate market dynamics. This included discussions with rail operator executives, infrastructure managers, signaling engineers, and software architects. Secondary validation drew from regulatory filings, industry association reports, technical standards documents, and government railway statistics. A bottom-up approach to market sizing was triangulated with top-down validation from total addressable market estimates.
Market size calibration utilized a multi-factor analytical framework across the projection horizon. Segmentation dimensions modeled included solution type, technology, application, end-user, and regional regulatory mandates. Compound Annual Growth Rates were derived from historical data analysis and projected technological adoption curves. Key forecast inputs included infrastructure investment plans and ERTMS deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in global infrastructure spending or supply chain stability would shift the trajectory of digital railway deployments. Forecasts reflect assumptions regarding regulatory enforcement and technological maturity. Material shifts in national railway modernization programs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Rail Pads Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Railway Radiator Market