
 Digital Axle Counter Market | 2026-2036
Digital Axle Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Axle Counter Market Insights
ERTMS/ETCS compatibility mandates across European rail networks are consolidating the cost-of-entry calculus for digital axle counter suppliers. Siemens Mobility leverages its established signaling portfolio to anchor European retrofit contracts. Thales Group competes through integrated train control offerings that bundle axle counting with interlocking systems. Frauscher Sensor Technology specializes in magnetic sensor architectures that differentiate its trackside installations across alpine corridors.
A digital axle counter is an electronic railway safety device that detects wheel passage via magnetic, infrared, or ultrasonic sensors mounted at trackside, transmitting axle count data to control centers for block section occupancy verification. The system operates with detection accuracy typically rated to minus 40 degrees Celsius for cold-climate reliability. Wired counters still dominate installed base volumes across legacy networks, though wireless counters are capturing the fastest growth in greenfield high-speed projects where trenching costs prove prohibitive. Rail operators represent the most concentrated end-user segment, with procurement decisions increasingly favoring technology-agnostic platforms that accommodate multiple sensor types.
EU ERTMS deployment directives, national safety authority certifications under the EU Rail Safety Directive, and country-specific infrastructure standards enforced by Germany's EBA and France's EPSF collectively shape product roadmaps and market access conditions. The US Federal Railroad Administration's PTC implementation rules and India's RDSO axle counter specifications add further compliance layers for suppliers seeking cross-border scale. Stakeholders must monitor which regulatory bodies accelerate mandatory retirement timelines for legacy track circuits, as these determinations will dictate replacement demand timing and vendor qualification requirements.
Market Dynamics
ERTMS/ETCS migration timelines are compressing hardware replacement cycles across European rail networks, forcing operators to retire electromechanical track circuits ahead of depreciation schedules. This regulatory-driven obsolescence is restructuring supplier qualification requirements and concentrating procurement authority within national infrastructure managers.
Growth Catalysts
- EU Rail Safety Directive mandates:Mandatory ERTMS deployment corridors in Germany, France, and Italy are accelerating digital axle counter installations to replace legacy block systems.
- High-speed rail expansion:Greenfield projects across Spain and Turkey favor wireless axle counting architectures to avoid trenching costs through difficult terrain.
- Cold-climate reliability standards:Detection accuracy requirements at minus 40 degrees Celsius are driving sensor technology upgrades across Nordic networks.
Market Restraints
- Copper and rare earth magnet cost volatility:Magnetic sensor cores depend on neodymium supply concentrated in Chinese processing facilities.
- Certification timeline friction:Germany's EBA type-approval processes extend 18-24 months, freezing product roadmaps for non-domestic suppliers.
- Track circuit residual value:Operators in Eastern European networks delay replacement to maximize sunk investment in electromechanical infrastructure.
Strategic Opportunities
- Indian Railways RDSO specifications:The world's largest passenger rail network is tendering axle counter systems for 40,000 km of new track.
- Sensor fusion architectures:Combined magnetic-infrared detection arrays address wheel flat detection, expanding addressable safety applications.
- Performance-based maintenance contracts:Availability-guarantee models replace capital purchase, opening recurring revenue streams for integrated service providers.
Industry Challenges
- Embedded systems cybersecurity certification:IEC 62443 compliance for connected axle counters adds engineering overhead and extends development cycles.
- Legacy interlocking integration:Retrofit projects require protocol adaptation to 30-year-old relay-based signaling systems without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Axle Counter Market |
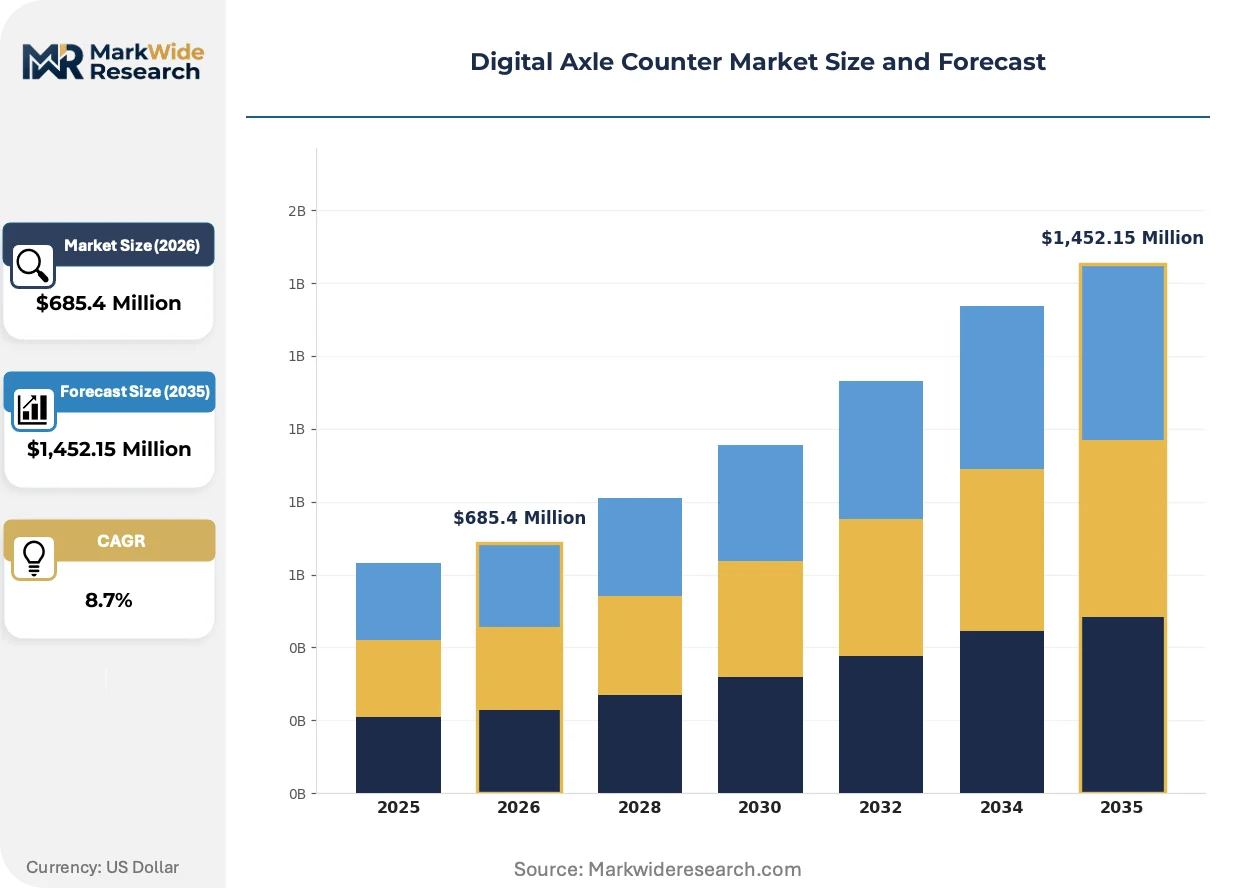
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Counters, Wired Counters, Portable Counters, Fixed Counters End User: Transportation Authorities, Freight Companies, Rail Operators, Mining Companies Installation: Trackside, Onboard Vehicles, Control Centers, Temporary Installations Technology: Infrared Sensors, Magnetic Sensors, Ultrasonic Sensors, Optical Sensors |
| Companies Covered | Siemens Mobility, Thales Group, Alstom SA, Frauscher Sensor Technology Group, CRRC Corporation Limited, Bombardier Transportation, Hitachi Rail STS, Mitsubishi Electric, CAF Signalling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Axle Counter Market Trends and Innovations
Digital axle counter architecture is converging with train control networks, eroding the boundary between detection hardware and signaling software. This integration is compressing supplier margins while expanding system-level contract values.
Wireless axle counting with solar-powered trackside units is rewriting deployment economics for remote corridor segments. Australian and Canadian freight operators are piloting these architectures across 500-kilometer unstaffed stretches. The technology is compressing civil engineering costs to 15 percent of wired equivalent installations.
France's EPSF and Germany's EBA are harmonizing electromagnetic compatibility testing protocols under EU Rail Safety Directive implementing acts. This convergence reduces duplicate certification costs for cross-border suppliers. Alpine corridor operators are consolidating procurement specifications to match these unified standards.
Indian Railways and Turkish State Railways are unbundling hardware supply from 15-year maintenance obligations, reversing bundled procurement norms. Infrastructure managers now separate detection equipment purchase from availability contracts. This bifurcation is visible across greenfield high-speed tenders in Ankara-Izmir and Mumbai-Ahmedabad corridors.
Digital Axle Counter Market Segmentation
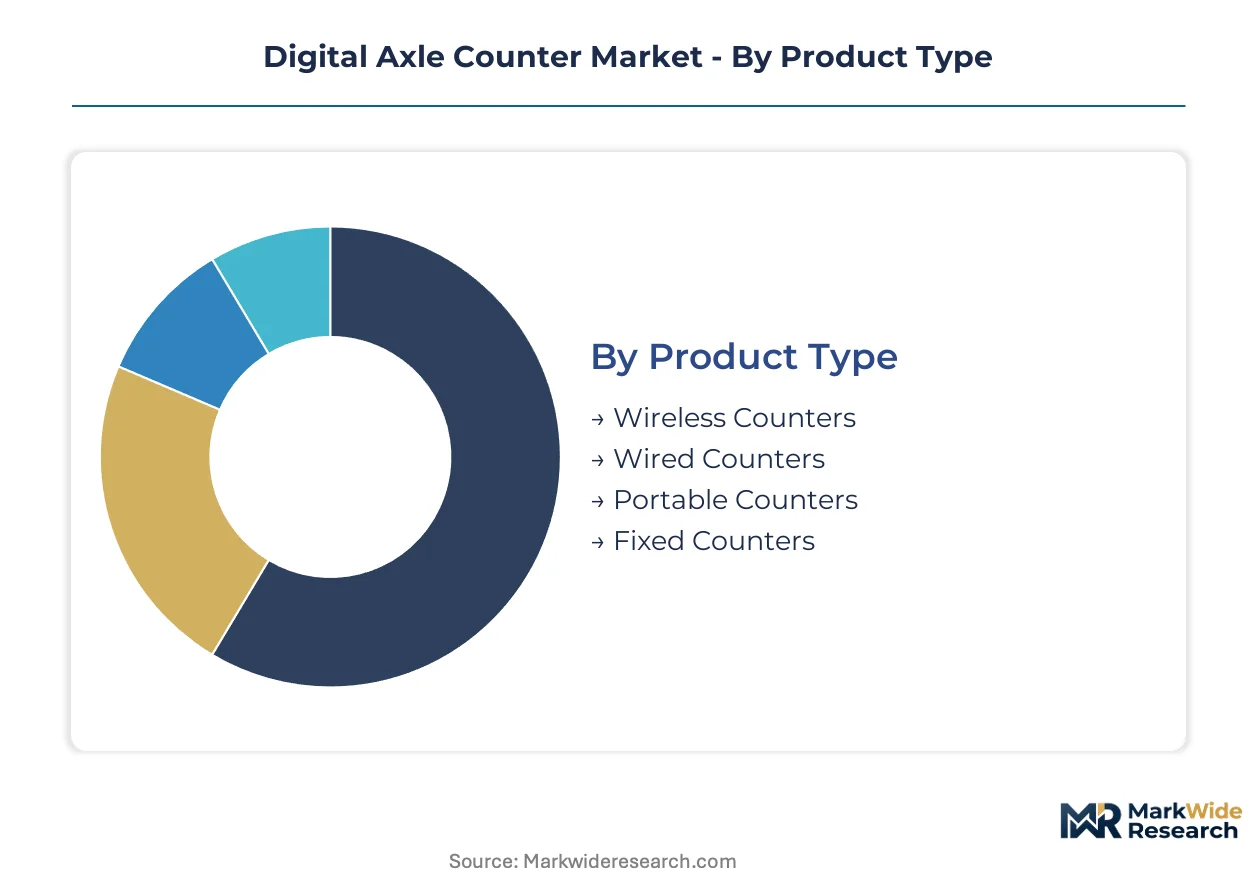
Digital axle counter procurement varies sharply across installation environments and operational mandates, with certification requirements from Germany's EBA, France's EPSF, and India's RDSO shaping supplier qualification pathways. Technology selection directly determines compliance burden and deployment economics across high-speed corridors versus legacy retrofits.
Product Type:
Germany's EBA type-approval processes impose 18-24 month certification timelines that favor established wired counter architectures, while wireless variants face additional electromagnetic compatibility scrutiny under EU Rail Safety Directive implementing acts.
- Wireless Counters:Solar-powered trackside units eliminate trenching costs across remote corridor segments. Australian freight operators pilot these architectures across 500-kilometer unstaffed stretches where civil engineering savings reach 85 percent versus wired equivalents.
- Wired Counters:Legacy copper-cable installations dominate European retrofit volumes, with detection accuracy certified to minus 40 degrees Celsius for Nordic network reliability. Deutsche Bahn's infrastructure modernization program sustains concentrated procurement despite higher installation labor intensity.
- Portable Counters:Temporary deployment configurations serve maintenance windows and construction zones without permanent track modification.
- Fixed Counters:Permanent installations anchor block section occupancy verification across high-density commuter networks.
Wired counters sit at the top of the volume ranking, with wireless counters climbing the fastest.
End User:
Procurement authority concentrates within national infrastructure managers, with freight operators favoring availability-guarantee contracts over capital purchase and mining companies prioritizing dust-resistant sensor specifications.
- Rail Operators:Technology-agnostic platform requirements now accommodate multiple sensor types within unified interlocking systems. India's 40,000 km new track tender unbundles hardware supply from 15-year maintenance obligations.
- Transportation Authorities:Public procurement frameworks across EU member states mandate ERTMS/ETCS compatibility, compressing hardware replacement cycles ahead of depreciation schedules.
- Freight Companies:Canadian and Australian operators drive wireless adoption across low-density corridors where staffing costs dominate operational economics.
- Mining Companies:Heavy-haul extraction routes in Western Australia and northern Canada demand reinforced sensor housings against particulate contamination.
Rail operators command the largest installed base, with freight companies gaining share fastest through performance-based maintenance contracts.
Installation:
Margin structures diverge between trackside civil works—where trenching and signaling integration dominate costs—and control center software layers capturing recurring service revenue.
- Trackside:Detection hardware mounted at rail level requires IP67 environmental sealing and vibration resistance certification. Alpine corridor operators consolidate procurement specifications around harmonized electromagnetic compatibility protocols.
- Control Centers:Centralized axle count processing and block section occupancy logic generate software maintenance streams. Ankara-Izmir and Mumbai-Ahmedabad high-speed tenders separate detection equipment purchase from availability contracts.
- Onboard Vehicles:Train-mounted counting systems serve specialized applications where trackside infrastructure proves impractical.
- Temporary Installations:Rapid-deployment configurations support emergency rerouting and festival service expansion.
Trackside deployments generate the highest absolute revenue, with control centers expanding most quickly through unbundled service contracts.
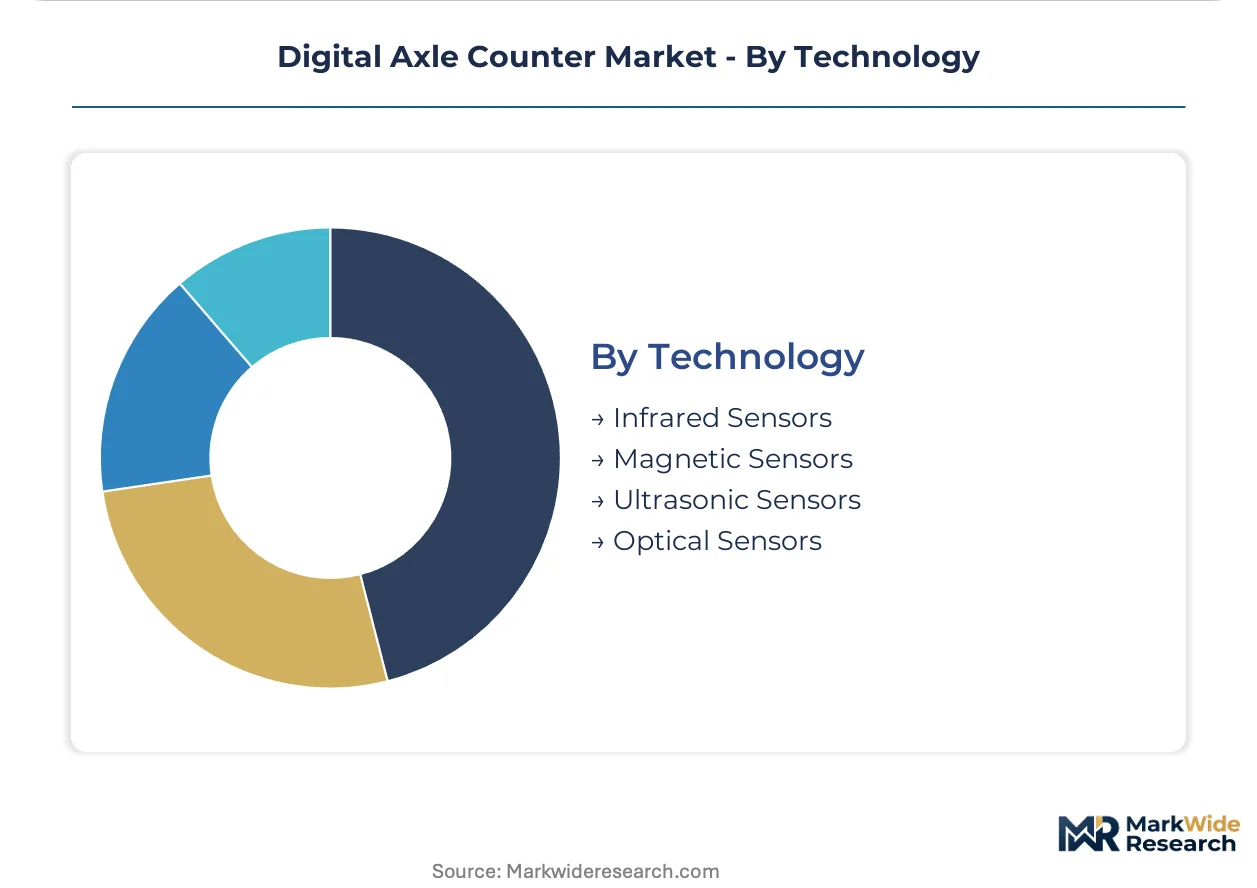
Technology:
Raw material cost volatility in neodymium supply chains concentrates supplier attention on magnetic sensor architectures, while infrared arrays address emerging wheel flat detection applications.
- Magnetic Sensors:Neodymium-core detection elements from Chinese processing facilities face price volatility that reshapes procurement timing. Frauscher Sensor Technology specializes in these architectures across alpine corridor installations.
- Infrared Sensors:Thermal detection arrays enable wheel flat identification alongside axle counting, expanding addressable safety applications. Combined magnetic-infrared fusion architectures penetrate premium specifications.
- Ultrasonic Sensors:Acoustic detection methods serve niche applications with specific interference rejection requirements.
- Optical Sensors:Vision-based counting systems compete in greenfield projects with clean sightline conditions.
Magnetic sensors retain the dominant technology position, with infrared sensors advancing fastest through sensor fusion demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent concentrated in German rail technology clusters anchors European digital axle counter deployment, while procurement authority increasingly centralizes within national infrastructure managers across high-speed corridors.
Germany
Deutsche Bahn's infrastructure modernization program drives sustained axle counter procurement across the Rhine-Ruhr and Rhine-Main corridors. Germany's EBA type-approval processes impose 18-24 month certification timelines that favor established wired architectures. Siemens Mobility leverages its Munich-based signaling portfolio to anchor retrofit contracts throughout Bavaria and Baden-Württemberg.
France
SNCF Réseau accelerates ERTMS/ETCS migration across the LGV Sud-Est and Atlantic high-speed lines, compressing hardware replacement cycles. France's EPSF harmonizes electromagnetic compatibility testing protocols with German EBA standards under EU Rail Safety Directive implementing acts. Thales Group competes through integrated train control offerings bundling axle counting with interlocking systems in the Île-de-France region.
India
Indian Railways tenders axle counter systems for 40,000 km of new track across the Dedicated Freight Corridor and Mumbai-Ahmedabad high-speed project. The RDSO axle counter specifications add compliance layers for suppliers seeking scale in the world's largest passenger rail network. Unbundled procurement now separates detection equipment purchase from 15-year maintenance obligations in corridor segments spanning Maharashtra and Gujarat.
Turkey
Turkish State Railways favors wireless axle counting architectures across the Ankara-Izmir high-speed corridor to avoid trenching costs through Anatolian plateau terrain. Greenfield projects specify solar-powered trackside units that compress civil engineering costs to 15 percent of wired equivalents. Control center software layers in Ankara generate recurring service revenue through availability-guarantee contracts.
Australia
Freight operators pilot wireless axle counting across 500-kilometer unstaffed stretches in Western Australia's Pilbara mining region and Queensland's coal corridors. Solar-powered trackside units address staffing cost economics in low-density networks. Heavy-haul extraction routes demand reinforced sensor housings against particulate contamination in the Hunter Valley and Bowen Basin clusters.
Digital Axle Counter Market Competitive Landscape
The competitive structure tilts toward diversified signaling conglomerates with established ERTMS/ETCS certification pathways. National infrastructure managers concentrate procurement authority within pre-qualified vendor pools, compressing margin structures for hardware-only suppliers. Three archetypes dominate: integrated train control providers, specialized sensor technology firms, and state-backed rail equipment conglomerates. Competitive moves center on strategic partnerships for maintenance contract bundling and technology licensing for wireless architectures.
Within the integrated signaling tier, Siemens Mobility and Thales Group exemplify diversified conglomerates leveraging established ERTMS portfolios. Frauscher Sensor Technology occupies a specialist position anchored in magnetic sensor architectures. CRRC Corporation Limited represents state-backed scale advantages in emerging market tenders. These three archetypes illustrate how certification depth, sensor specialization, and manufacturing scale respectively anchor competitive positioning across European retrofit and Asian greenfield corridors.
| Leading Market Players |
|---|
| Siemens Mobility |
| Thales Group |
| Alstom SA |
| Frauscher Sensor Technology Group |
| CRRC Corporation Limited |
| Bombardier Transportation |
| Hitachi Rail STS |
| Mitsubishi Electric |
| CAF Signalling |
| Others |
Pricing and Supply Chain Analysis
National infrastructure managers in Germany, France, and India concentrate procurement authority within pre-qualified vendor pools, anchoring contract structures around 15-year availability guarantees that bundle detection hardware with maintenance obligations. This buyer consolidation compresses upfront equipment margins while shifting value capture toward recurring service streams.
Pricing Analysis
The unbundling of hardware supply from long-term maintenance contracts across Indian Railways and Turkish State Railways tenders is fragmenting traditional pricing models. Three-tier pricing structure across premium, standard, and economy levels aligns with certification tiers from Germany's EBA, France's EPSF, and India's RDSO. Price differentiation hinges on electromagnetic compatibility testing depth and cold-climate reliability ratings. Cost compression in wireless architectures is intensifying because solar-powered trackside units eliminate trenching expenses. Freight operators in Australia and Canada exhibit highest price sensitivity due to low-density corridor economics, while high-speed rail projects in Europe show lowest sensitivity given ERTMS mandate compliance imperatives.
Supply Chain Analysis
Domestic-content mandates in India's Make in India framework and Turkey's localization requirements for the Ankara-Izmir corridor are reshaping sourcing patterns toward regional manufacturing footprints. Neodymium processing concentrates in Chinese facilities, with magnetic sensor cores drawing from this concentrated supply base. Copper cabling for wired installations sources from Chilean and Peruvian mining operations, while semiconductor components for wireless units rest on Taiwanese and South Korean fabrication capacity. Single-source vulnerability in rare earth magnet supply creates exposure to export restriction shocks. Distribution runs through national infrastructure manager tender processes and authorized system integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Axle Counter Market functions as a stable compounder, with regulatory-mandated ERTMS/ETCS deployment across European corridors ensuring replacement demand visibility regardless of cyclical rail freight volumes.
For Market Incumbents: Acquire wireless axle counting IP portfolios to close capability gaps against greenfield high-speed specifications. Siemens Mobility and Thales Group should deepen backward integration into magnetic sensor manufacturing to offset neodymium price volatility from Chinese processing concentration. Certification investment in India's RDSO specifications offers defensive positioning against CRRC's state-backed emerging market tenders. For New Entrants and Emerging Players: The premium-economy price-point gap in portable and temporary axle counter configurations offers white-space entry. Mining company procurement in Western Australia's Pilbara region remains underpenetrated by established signaling conglomerates, with dust-resistant sensor specifications creating specialist differentiation opportunities. A sensor-fusion go-to-market angle combining magnetic and infrared detection addresses wheel flat detection applications that incumbent bundled offerings underserve. For Investors and Strategic Acquirers: Integrated train control providers are the most active acquirer in this space, with Siemens Mobility and Thales Group consolidating specialist sensor technology firms to fill architecture gaps. The 5-10 year viability window favors targets with established ERTMS/ETCS certification pathways and recurring maintenance contract backlogs. Monitor EU Rail Safety Directive implementing acts for accelerated legacy track circuit retirement timelines as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Architecture Development | Solar-powered trackside units reduce civil engineering costs to 15 percent of wired equivalents across Australian and Canadian freight corridors. |
| Sensor Fusion Integration | Combined magnetic-infrared arrays address wheel flat detection, expanding addressable safety applications beyond basic axle counting. |
| Certification Depth Investment | EBA type-approval processes extending 18-24 months create qualification moats that freeze out non-domestic suppliers without established European track records. |
| Performance-Based Maintenance Contracts | Availability-guarantee models replace capital purchase, opening recurring revenue streams for integrated service providers across Indian and Turkish greenfield projects. |
| Regional Manufacturing Localization | Domestic-content requirements in India's 40,000 km tender and Turkey's Ankara-Izmir corridor necessitate local assembly partnerships to maintain bid eligibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rail infrastructure procurement officers, signaling system integrators, EBA and EPSF certification engineers, and maintenance contract managers at Deutsche Bahn and SNCF Réseau with secondary validation against EU Rail Safety Directive implementing acts, RDSO axle counter specifications, and customs data on neodymium and copper trade flows. Bottom-up installation volume estimates triangulated against top-down infrastructure modernization program budgets from Germany, France, India, and Turkey.
Segment-weighting approaches applied differential growth assumptions across wired versus wireless product architectures, trackside versus control center installation environments, and rail operator versus freight company end-user categories. The analytical framework modeled technology adoption patterns across magnetic, infrared, and sensor fusion detection methods, with CAGRs derived from infrastructure investment trajectories and regulatory compliance timelines. ERTMS/ETCS deployment schedules and cold-climate reliability certification requirements served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for wireless solar-powered architectures would alter the outlook if battery storage costs collapse or electromagnetic interference standards tighten unexpectedly. Forecasts reflect assumptions regarding EU member state adherence to ERTMS migration timelines and Indian Railways' unbundled procurement persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Rail Pads Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railcar Spill Containment Materials Market