
 Urban Rail Transit Market | 2026-2036
Urban Rail Transit Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Rail Transit Market Analysis
Specialized rail systems engineering talent is reorganizing procurement timelines across the Urban Rail Transit Market as project pipelines outpace workforce supply. CRRC Corporation Limited leverages captive manufacturing scale across Asia to dominate heavy rail deliveries. Siemens Mobility anchors European electrification standards through integrated signaling and traction packages. Alstom competes on automated metro technology leadership in Middle Eastern and Latin American tenders.
Urban rail transit encompasses electrically or diesel-powered guided transport systems operating on dedicated rights-of-way within metropolitan areas, typically featuring axle loads between 10 and 16 tonnes and track gauges of 1,435 mm or 1,067 mm, designed to move passenger volumes exceeding 20,000 persons per hour per direction. Heavy rail systems absorb the majority of capital expenditure due to tunneling and station infrastructure requirements, while automated technology segments capture expanding share as operators prioritize reduced staffing costs and headway compression. Light rail maintains mature installed bases across European municipalities, though hybrid propulsion variants are gaining traction where full electrification remains economically constrained.
China's NMPA equipment certification and the EU's CE marking under MDR and F-Gas Regulation shape rolling stock safety and climate-relevant component standards, directly conditioning market access for foreign suppliers. India's BIS mandates and CEA electrical clearance protocols govern domestic procurement eligibility, favoring localized assembly partnerships. Stakeholders must weigh regulatory compliance costs against long-term fleet standardization benefits when selecting technology platforms for multi-decade asset lifecycles.
Market Dynamics
Specialized rail systems engineering talent is reorganizing procurement timelines across the Urban Rail Transit Market as project pipelines outpace workforce supply. Municipal transit authorities in megacities are accelerating fleet procurement while electrification mandates compress delivery windows.
Growth Catalysts
- MIIT dual carbon goals:China's carbon neutrality targets are accelerating electric traction system deployment across new metro lines, forcing fleet electrification timelines forward.
- India PLI scheme:Production-linked incentives for domestic rolling stock manufacturing are concentrating demand in Tier-1 cities and building localized supply chains.
- Population density clustering:Megacity agglomeration in São Paulo, Jakarta, and Cairo is expanding dedicated right-of-way procurement for high-capacity corridors.
Market Restraints
- Steel and copper volatility:Input cost swings for traction motors and overhead catenary systems are compressing rolling stock margins unpredictably.
- European supply concentration:Signaling and control system manufacturing clusters in Germany and France create single-source vulnerability for automated metro tenders.
- CE marking friction:EU MDR and F-Gas Regulation compliance timelines are extending equipment certification cycles for non-European suppliers.
Strategic Opportunities
- Underpenetrated African corridors:Lagos, Addis Ababa, and Dar es Salaam are greenfield markets for light rail with minimal legacy infrastructure displacement costs.
- Battery-diesel hybrid convergence:Dual-mode propulsion systems are opening non-electrified suburban extensions where full catenary installation remains uneconomical.
- CEA electrical clearance protocols:India's domestic certification requirements are creating partnership entry points for foreign suppliers through localized assembly joint ventures.
Industry Challenges
- Systems integration engineering scarcity:Projected metro openings in Riyadh, Doha, and Sydney are competing for finite signaling and platform screen door specialists.
- Legacy fleet interoperability:Mixed-voltage corridors in London and Paris are forcing complex multi-standard propulsion retrofits that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Rail Transit Market |
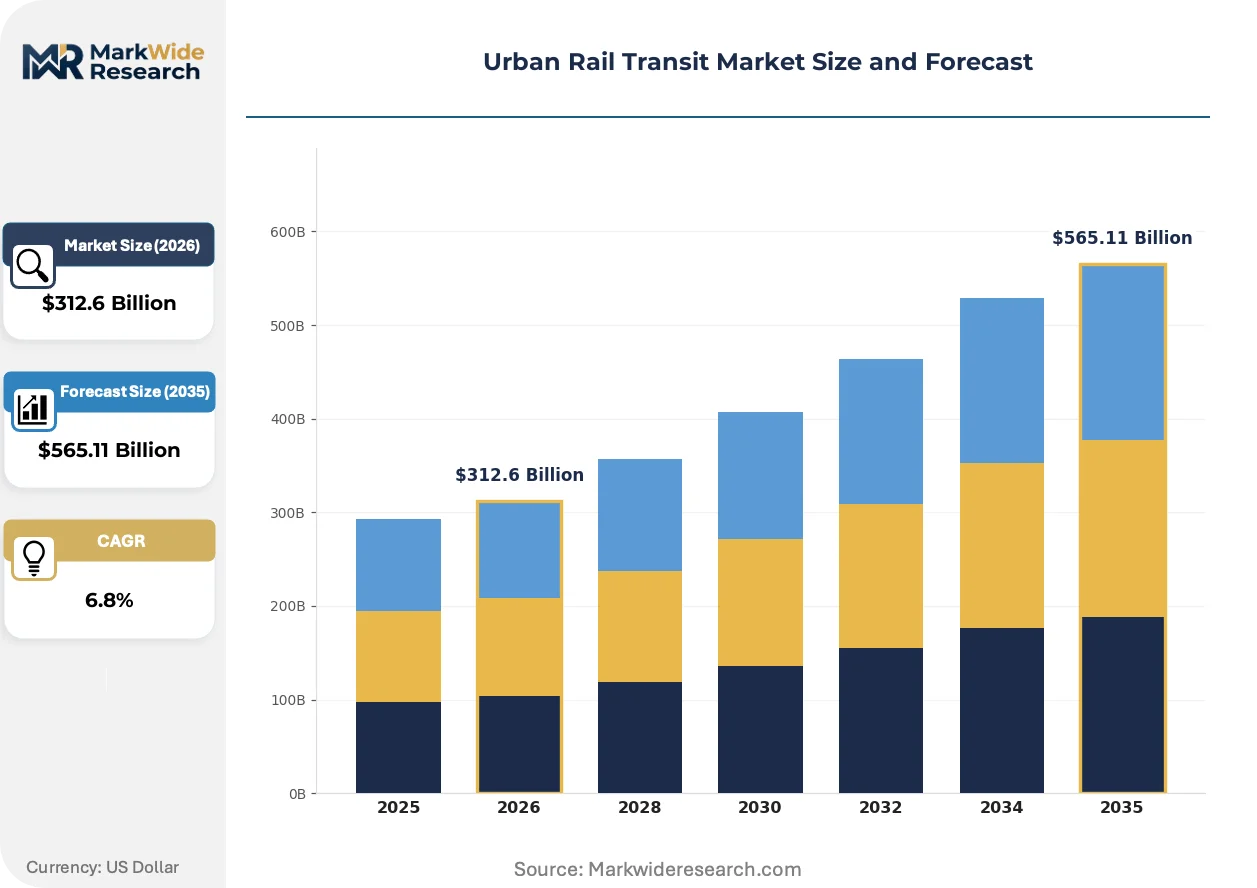
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Light Rail, Heavy Rail, Monorail, Tramway Technology: Electric, Diesel, Hybrid, Automated Application: Passenger Transport, Freight Transport, Intermodal, Urban Logistics End User: Municipalities, Commuters, Tourists, Freight Operators |
| Companies Covered | CRRC Corporation Limited, Alstom, Siemens Mobility, Hitachi Rail, Kawasaki Heavy Industries, Construcciones y Auxiliar de Ferrocarriles, Mitsubishi Heavy Industries, Larsen & Toubro, Škoda Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Rail Transit Market Emerging Trajectories
Automated train operation is compressing headways and reshaping staffing models across metropolitan networks. Three distinct shifts are restructuring how technology platforms, regulatory frameworks, and procurement patterns evolve in parallel.
Communications-based train control (CBTC) is replacing fixed-block signaling with moving-block algorithms that enable 90-second headways. Metro operators in Singapore, Dubai, and Santiago are mandating GoA4 unattended operation for new lines. The technology is bifurcating fleet procurement into fully automated versus driver-retained configurations, splitting supplier R&D investment and fragmenting platform standardization.
EU F-Gas Regulation phase-down schedules are prohibiting high-GWP refrigerants in HVAC systems for rolling stock. European rolling stock manufacturers are retrofitting production lines for CO2 heat pumps and HFO blends. Heavy rail segments serving cross-border corridors face the steepest compliance cost escalation, prompting fleet standardization around single-vendor climate platforms.
Public-private availability-based contracts are displacing traditional design-bid-build procurement for metro extensions. Transport authorities in Brazil, Colombia, and Vietnam are transferring ridership risk to concession operators. This restructuring concentrates fleet specification power with international infrastructure funds and their preferred equipment integrators, marginalizing municipal engineering departments from technical decisions.
Urban Rail Transit Market Segmentation
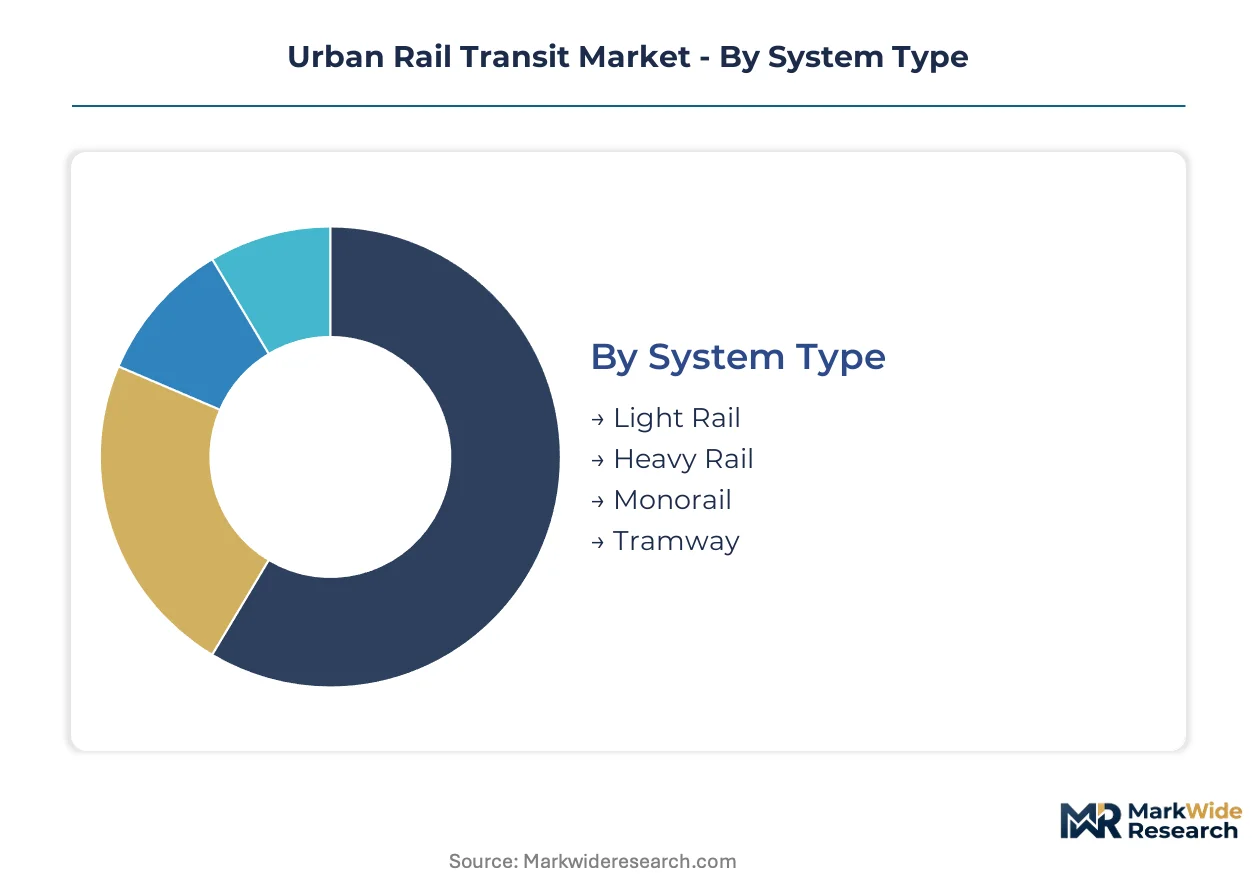
Urban rail transit procurement divides across operational intensity, propulsion standards, and ridership profiles. Regulatory frameworks governing electrification mandates and automated operation certifications reshape how segments cluster in tender specifications.
System Type:
China's MIIT dual carbon goals and the EU's F-Gas Regulation create divergent compliance burdens across infrastructure scales.
- Light Rail:Operates on surface rights-of-way with axle loads below 12 tonnes and partial grade separation. Demand concentrates in European municipalities upgrading legacy tram networks where CE marking under MDR governs platform screen door retrofits. The segment absorbs hybrid propulsion trials where full catenary installation faces budget constraints.
- Heavy Rail:Features dedicated tunnels, third-rail or overhead electrification, and axle loads exceeding 14 tonnes. Procurement accelerates in India's Tier-1 cities where BIS certification and CEA electrical clearance protocols favor localized assembly partnerships for metro expansions. Tunneling costs dominate capital structures.
- Monorail:Straddle-beam or suspended configurations suited for dense urban corridors with severe right-of-way constraints. Bangkok and São Paulo deploy variants for elevated corridor penetration.
- Tramway:Street-running systems with mixed-traffic segments and lower dedicated infrastructure requirements. Czech and Polish manufacturers anchor European supply for heritage network extensions.
Established volume favors Heavy Rail; emerging adoption favors Light Rail.
Technology:
Cost tier differentiation separates capital-intensive electrification from operational flexibility in non-wired extensions.
- Electric:Third-rail or overhead catenary systems delivering continuous power for high-frequency operations. China's MIIT dual carbon goals are accelerating deployment across new metro lines in Shenzhen and Chengdu, with NMPA equipment certification conditioning foreign supplier access.
- Automated:GoA4 unattended operation with CBTC signaling enabling 90-second headways. Singapore's Land Transport Authority and Dubai's RTA mandate specifications for new line procurements, concentrating R&D investment with European signaling specialists.
- Hybrid:Battery-diesel dual-mode propulsion for suburban extensions beyond electrified cores. Indian Railways trials and French regional networks test variants where catenary gaps exceed 15 kilometers.
- Diesel:Mechanical or hydraulic traction for isolated heritage lines and interim shuttle services. Declining procurement share except in African greenfield corridors lacking grid infrastructure.
Capital deployment favors Electric; technology differentiation favors Automated.
Application:
Customer type segmentation separates ridership risk allocation between municipal authorities and concession operators.
- Passenger Transport:High-capacity corridor services moving exceeding 20,000 persons per hour per direction. Megacity agglomeration in Jakarta, Cairo, and São Paulo expands dedicated right-of-way procurement.
- Urban Logistics:Parcel and light freight integration into off-peak metro capacity. Paris and Tokyo pilot cargo compartment retrofits for last-mile distribution.
- Intermodal:Station infrastructure designed for bus, bicycle, and micro-mobility transfers. Brazilian availability-based contracts bundle fleet and feeder network specifications.
- Freight Transport:Dedicated cargo metro lines or night-time freight slots on passenger infrastructure. Limited deployment outside Swiss and German alpine corridors.
ridership concentration favors Passenger Transport; infrastructure utilization favors Urban Logistics.
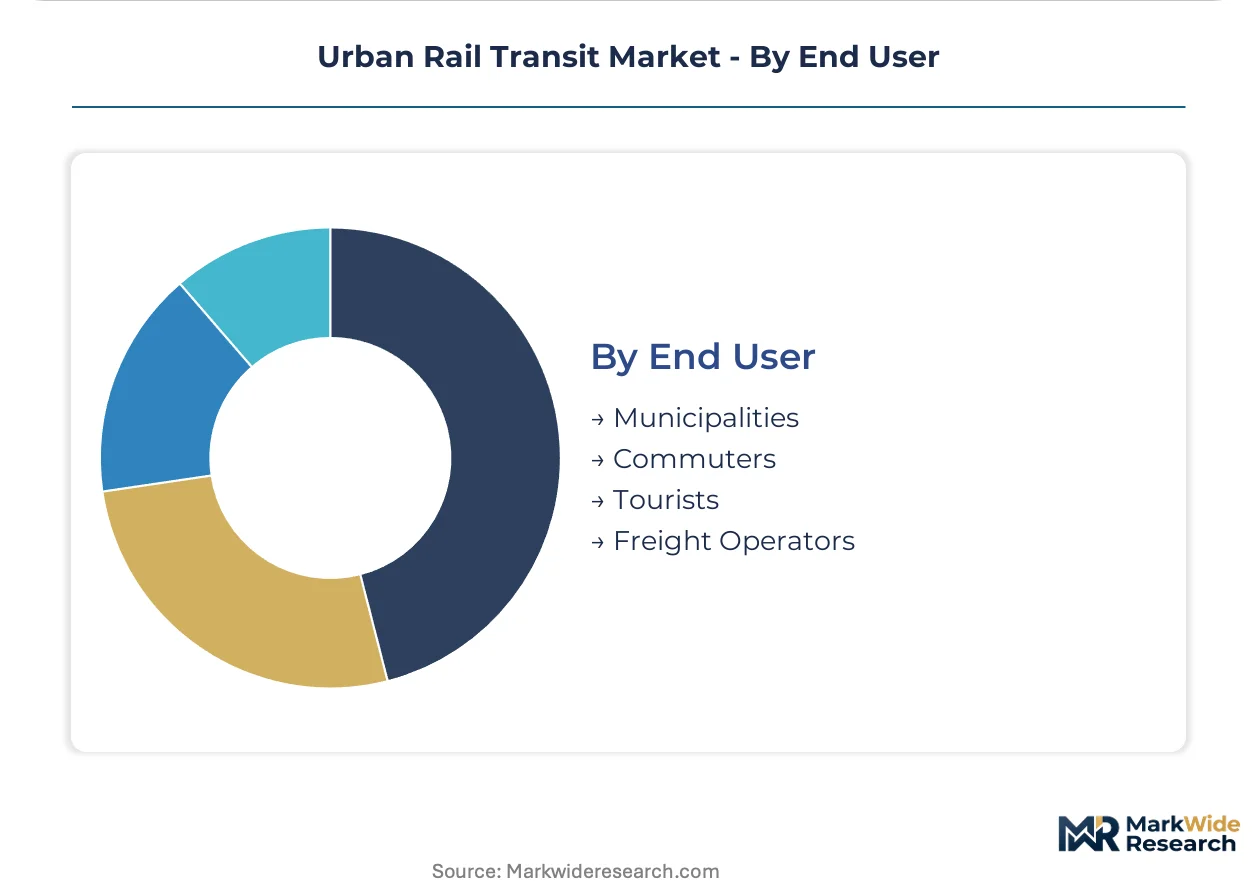
End User:
Procurement authority determines specification control and financing structure.
- Municipalities:Transport authorities in Riyadh, Doha, and Sydney competing for finite systems integration engineering talent. Public-private availability-based contracts transfer technical specification power to infrastructure funds.
- Commuters:Daily ridership patterns dictating peak capacity requirements and fare structure design. Subscription models and contactless payment integration reshape revenue collection.
- Freight Operators:Logistics companies contracting for dedicated cargo slots or last-mile terminal access. Limited market presence outside specialized alpine and port corridor networks.
- Tourists:Seasonal demand spikes and premium service tiers for airport links and heritage route experiences. Airport express specifications diverge from commuter metro standards.
Specification control favors Municipalities; revenue diversification favors Tourists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through captive manufacturing scale, while European suppliers absorb compliance premiums from CE marking and F-Gas Regulation mandates. This asymmetry reshapes tender outcomes across procurement corridors.
China
MIIT dual carbon goals accelerate electric traction deployment across Shenzhen and Chengdu metro expansions. NMPA equipment certification conditions foreign supplier market access, favoring domestic assembly partnerships. CRRC Corporation leverages captive scale across the Yangtze River Delta to dominate heavy rail deliveries for Belt and Road transit corridors.
India
Tier-1 city agglomeration in Mumbai, Delhi-NCR, and Bengaluru expands fleet procurement under PLI scheme incentives. BIS mandates and CEA electrical clearance protocols govern domestic eligibility, requiring localized assembly joint ventures. Larsen & Toubro anchors rolling stock manufacturing partnerships in Maharashtra and Gujarat for metro line extensions.
Germany
EU F-Gas Regulation phase-down schedules force HVAC system retrofits for CO2 heat pumps and HFO blends. Siemens Mobility anchors European electrification standards through integrated signaling and traction packages manufactured in Bavaria and North Rhine-Westphalia. KBA rail vehicle approval protocols extend certification timelines for non-European automated metro suppliers.
United States
Federal Transit Administration capital investment grants compress procurement windows for aging infrastructure replacement in New York, Chicago, and Los Angeles. Buy America domestic content requirements reshape supplier selection for railcar manufacturing. Alstom occupies a position among North American system integrators bidding for Northeast Corridor electrification upgrades.
Brazil
Public-private availability-based contracts transfer ridership risk to concession operators in São Paulo and Rio de Janeiro metro extensions. ANVISA equipment safety protocols govern rolling stock certification for Latin American tenders. CAF and Mitsubishi Heavy Industries exemplify suppliers positioning for automated technology leadership in underpenetrated corridors.
Urban Rail Transit Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Urban Rail Transit Market. The vendor base clusters around three strategic tiers: integrated system integrators bundling signaling and traction, specialized component suppliers for propulsion and HVAC subsystems, and regional fabricators serving protected domestic markets. Consolidation pressure intensifies as automated train operation mandates concentrate R&D investment with European signaling specialists. Strategic moves center on captive manufacturing scale expansion and cross-border joint ventures to satisfy local content requirements.
Within the integrated system integrator tier, CRRC Corporation Limited exemplifies scale-driven cost leadership through captive supply chain control across Asian manufacturing corridors. Alstom and Siemens Mobility occupy positions defining European technology standards for electrification and automated metro platforms. These three anchors represent divergent competitive vectors: Chinese manufacturing scale, French automation specialization, and German signaling-traction integration.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom |
| Siemens Mobility |
| Hitachi Rail |
| Kawasaki Heavy Industries |
| Construcciones y Auxiliar de Ferrocarriles |
| Mitsubishi Heavy Industries |
| Larsen & Toubro |
| Škoda Transportation |
| Others |
Supply Flow & Price Mechanics
CO2 heat pump retrofits replacing conventional HVAC refrigerants are redrawing supplier geography toward European climate-tech clusters while inflating equipment certification premiums for non-compliant manufacturers. This substitution cascade concentrates pricing power with integrated electrification specialists and fragments procurement options for cost-constrained municipal authorities.
Pricing Analysis
Price spreads between Chinese and European rolling stock deliveries exceed forty percent for equivalent heavy rail configurations, reflecting divergent labor cost structures and domestic content requirements. Three-tier pricing structure across premium automated metro platforms, standard electrified systems, and economy diesel-hybrid configurations separates procurement tiers by signaling sophistication and after-sales service bundling. Cost compression in standard electrification segments is intensifying because CRRC Corporation leverages captive manufacturing scale across the Yangtze River Delta. Municipal transport authorities in India's Tier-1 cities exhibit highest price sensitivity due to PLI scheme localization mandates, while Gulf sovereign wealth funds deploying availability-based contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and Red Sea routing disruptions are extending traction motor and signaling component lead times unpredictably. Manufacturing gravity centers on China for complete rolling stock, Germany for CBTC signaling systems, and Japan for propulsion inverters. Raw material dependencies draw from copper cathode for overhead catenary, rare earth elements for permanent magnet motors, and specialty steel for axle assemblies. Single-source vulnerability concentrates in European signaling software clusters, where Siemens Mobility and Alstom control automated train operation protocols. Distribution runs through turnkey EPC contractors bundling fleet delivery with civil infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as automated train operation mandates bifurcate procurement between driver-retained and unattended configurations, creating specialist niches for signaling integrators and platform screen door subsystem suppliers.
For Market Incumbents: Consolidate through backward integration into traction motor manufacturing and captive supply of copper winding assemblies to defend margins against steel and aluminum volatility. European incumbents face margin pressure from F-Gas Regulation compliance cost escalation, requiring certification investment in CO2 heat pump production lines. Capacity addition in India's Maharashtra and Gujarat industrial corridors anchors localized assembly partnerships satisfying BIS mandates. For New Entrants and Emerging Players: Anchor in African greenfield corridors—Lagos, Addis Ababa, Dar es Salaam—where legacy infrastructure displacement costs remain minimal and electrification gaps favor battery-diesel hybrid propulsion trials. Underpenetrated light rail segments in Southeast Asian secondary cities offer white-space entry with lower automated technology compliance burdens. Go-to-market execution through joint ventures with domestic civil contractors transfers project risk and accelerates regulatory approval timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional rolling stock fabricators in Central Europe and Latin America holding established maintenance contracts but lacking automated platform capabilities. Long-term viability hinges on five-to-ten-year fleet modernization windows as GoA4 mandates propagate from Gulf and Asian metros toward European legacy networks. Acquisition targets include specialized signaling subsystem suppliers with CBTC migration expertise. Watch for inflection where Indian CEA electrical clearance protocols force foreign suppliers into mandatory localized assembly joint ventures, triggering consolidation among mid-cap fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Train Operation Certification | GoA4 platform approval with Singapore LTA and Dubai RTA unlocks premium corridor tenders. |
| Localized Assembly Joint Venture | Partnership with Larsen & Toubro in Gujarat satisfies India's CEA clearance and PLI localization. |
| Battery-Diesel Hybrid Development | Dual-mode propulsion trials with Indian Railways open suburban extensions beyond electrified cores. |
| CO2 Heat Pump Retrofit | EU F-Gas Regulation compliance for HVAC systems preserves European market access against phase-down. |
| Availability-Based Contracting | Concession structures with Brazilian operators transfer ridership risk and concentrate fleet specification power. |
Methodological Framework
A spread of perspectives from metro procurement directors, systems integration engineers, rolling stock manufacturing executives, and regulatory compliance officers converged on the working assumptions shaping demand elasticity and technology adoption timelines. Primary fieldwork combined structured interviews with transit authority planning departments and rolling stock OEM commercial teams, validated against secondary sources including NMPA equipment certification databases, EU MDR and F-Gas Regulation implementation guidance, and Indian BIS technical committee proceedings. Bottom-up fleet procurement pipelines were triangulated with top-down infrastructure investment forecasts across the analysis window.
Segmentation dimensions modeled encompass system type classification, propulsion technology tier, automation grade, and application intensity across passenger transport corridors. Value projections rest on unit economics for heavy rail versus light rail configurations, adjusted for tunneling cost differentials and signaling sophistication premiums. CAGRs derive from ridership growth elasticity to urban density, electrification mandate acceleration under MIIT dual carbon goals, and localized manufacturing incentives under India's PLI scheme. Industry-specific inputs include steel and copper price volatility indices, systems engineering labor availability, and cross-border certification friction metrics.
Material uncertainties—commodity price swings, regulatory timeline extensions for CE marking, and workforce scarcity in signaling specialization—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure fund deployment pacing and municipal debt capacity for availability-based contracts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Train Transformer Market
Railway Transportation
Rail Fasteners Market