
 Railcar Spill Containment Materials Market | 2026-2036
Railcar Spill Containment Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Railcar Spill Containment Materials Market Analytics
EPA hazardous materials transport rules is recalibrating the cost-of-entry calculus for railcar spill containment procurement. UltraTech International leverages proprietary polymer formulations to sustain premium positioning in absorbent pad supply. SafeRack anchors its market presence through specialized loading rack containment integration. ENPAC LLC differentiates via modular spill kit architectures that compete across multiple rail operator maintenance categories.
Railcar spill containment materials encompass engineered absorbents, barriers, and collection systems designed to capture hydrocarbons, chemicals, and industrial fluids during loading, transit, and unloading operations. Polypropylene melt-blown media achieve sorption capacities exceeding ten times their dry weight for petroleum derivatives, while clay-based granules provide cost-effective containment for non-aggressive liquid spills. Spill kits lead product type demand due to standardized compliance bundling for rail yard operations, though containment booms represent the fastest-growing segment as railroads retrofit trackside drainage infrastructure. Synthetic fiber materials command margin premiums over natural fiber alternatives in applications involving corrosive chemical transport.
Federal Railroad Administration safety directives and EPA Spill Prevention, Control, and Countermeasure requirements shape product certification standards and procurement specifications for rail operators. OSHA workplace exposure limits further constrain material selection for maintenance personnel handling saturated containment media. Stakeholders must monitor evolving DOT tank car integrity rules and state-level environmental liability frameworks to anticipate replacement demand cycles and specification shifts.
Market Dynamics
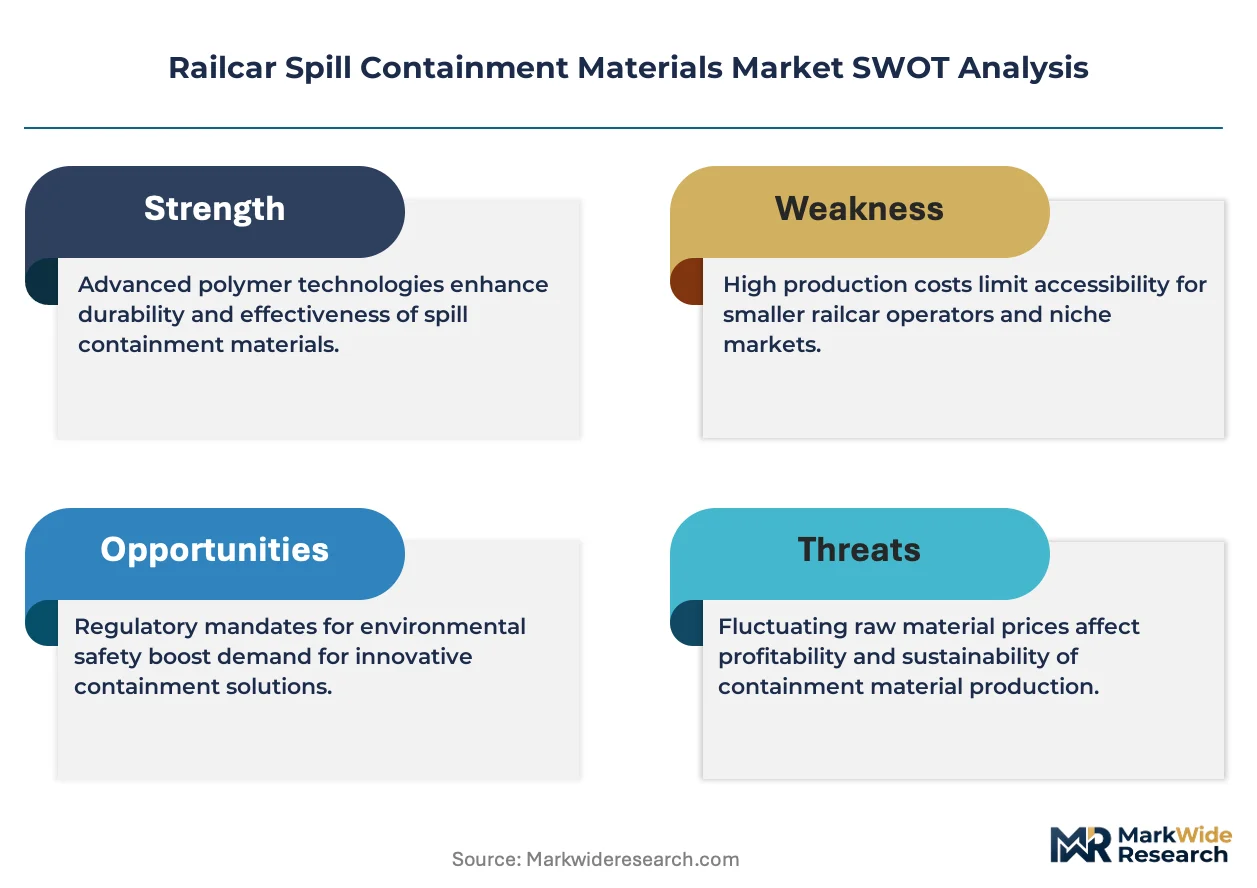
DOT tank car integrity rules and EPA Spill Prevention, Control, and Countermeasure mandates are compressing replacement cycles for legacy containment infrastructure across North American rail networks. Chemical shippers face escalating liability exposure that forces specification upgrades for absorbent media and collection systems.
Growth Catalysts
- EPA hazardous materials transport rules:Compliance thresholds for containment performance are tightening procurement specifications for Class I railroads operating bulk liquid corridors.
- Polypropylene melt-blown media:Sorption capacities exceeding ten times dry weight for petroleum derivatives are displacing clay-based alternatives in premium chemical transport applications.
- United States:Elevated remediation liability and replacement cycles for legacy containment infrastructure are concentrating demand in rail yard retrofit programs.
Market Restraints
- Petroleum feedstock volatility:Synthetic fiber materials depend on propylene supply chains subject to energy price fluctuations that compress margin predictability for polypropylene absorbent manufacturers.
- Clay-based granule substitution:Cost-effective containment for non-aggressive liquid spills limits pricing power for advanced synthetic formulations in commodity chemical transport segments.
- OSHA workplace exposure limits:Material selection constraints for maintenance personnel handling saturated containment media add compliance costs to training and personal protective equipment procurement.
Strategic Opportunities
- Trackside drainage infrastructure retrofit:Containment booms represent underpenetrated deployment as railroads upgrade stormwater management systems to capture railcar discharge events.
- Federal Railroad Administration safety directives:Product certification standard evolution creates first-mover advantage for suppliers achieving early compliance with performance testing protocols.
- Modular spill kit architectures:Standardized compliance bundling for rail yard operations enables cross-selling across multiple operator maintenance categories and fleet types.
Industry Challenges
- State-level environmental liability framework fragmentation:Anticipating replacement demand cycles requires monitoring fifty distinct regulatory regimes with varying enforcement intensity and damage calculation methodologies.
- Legacy containment infrastructure integration:Retrofitting absorbent pad systems and collection hardware onto existing tank car fleets demands custom engineering that extends deployment timelines and strains field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railcar Spill Containment Materials Market |
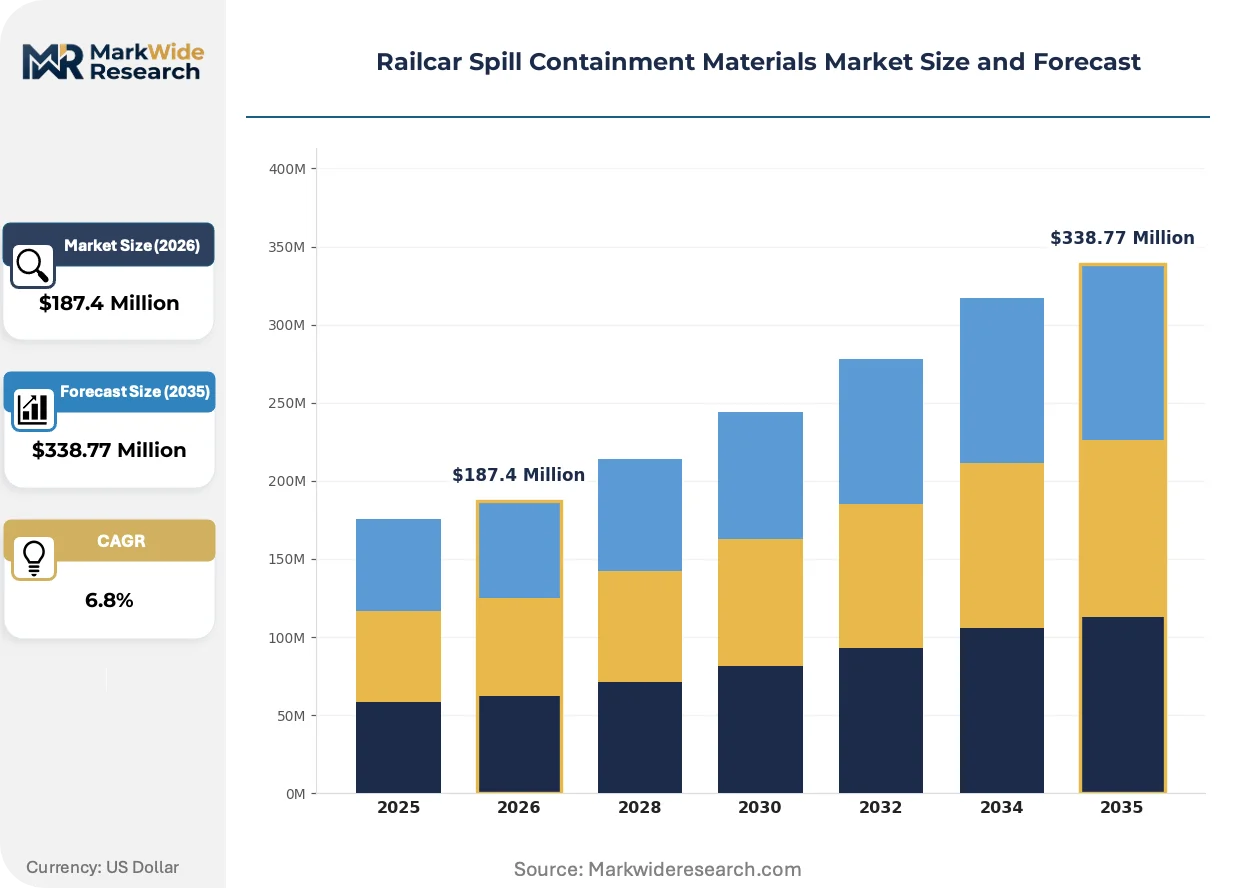
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, Containment Booms, Spill Kits, Drain Covers Material: Polypropylene, Clay, Natural Fiber, Synthetic Fiber Application: Rail Transportation, Industrial Storage, Waste Management, Emergency Response End User: Rail Operators, Chemical Manufacturers, Environmental Agencies, Logistics Companies |
| Companies Covered | Eagle Manufacturing Company, ENPAC LLC, UltraTech International, New Pig Corporation, SafeRack, Justrite Manufacturing Company, SpillTech Environmental, Complete Environmental Products, Chemtex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railcar Spill Containment Materials Market Evolving Landscape
Material science advances and regulatory precision are converging to reshape competitive positioning in railcar spill containment. Suppliers must now engineer for simultaneous compliance with federal transport safety mandates and state environmental liability frameworks.
Smart absorbent technologies incorporating color-change indicators and RFID tracking are decentralizing inventory management across distributed rail yard networks. Major chemical shippers are piloting these systems at Midwest hub facilities to automate saturation monitoring and replacement scheduling. The technology is decentralizing procurement authority from central supply chains to field maintenance supervisors who now trigger reorder events based on real-time capacity data rather than calendar-based replacement cycles.
EPA Spill Prevention, Control, and Countermeasure requirements are mandating secondary containment capacity calculations that exceed historical rail industry norms. Rail operators must now document volumetric capture capability for worst-case discharge scenarios involving entire tank car volumes. Bulk liquid terminals in Texas and Louisiana are most affected, deploying modular berm systems and rapid-deployment boom inventories to satisfy inspection protocols.
Buyer consolidation among Class I railroads is compressing supplier negotiation cycles and unbundling after-sales service from equipment procurement. Maintenance departments now source saturated media disposal and containment hardware refurbishment through separate contracts rather than bundled service agreements. This pattern is most visible in the United States, where Union Pacific and BNSF Railway have centralized procurement functions that disintermediate traditional distributor relationships.
Railcar Spill Containment Materials Market Segmentation
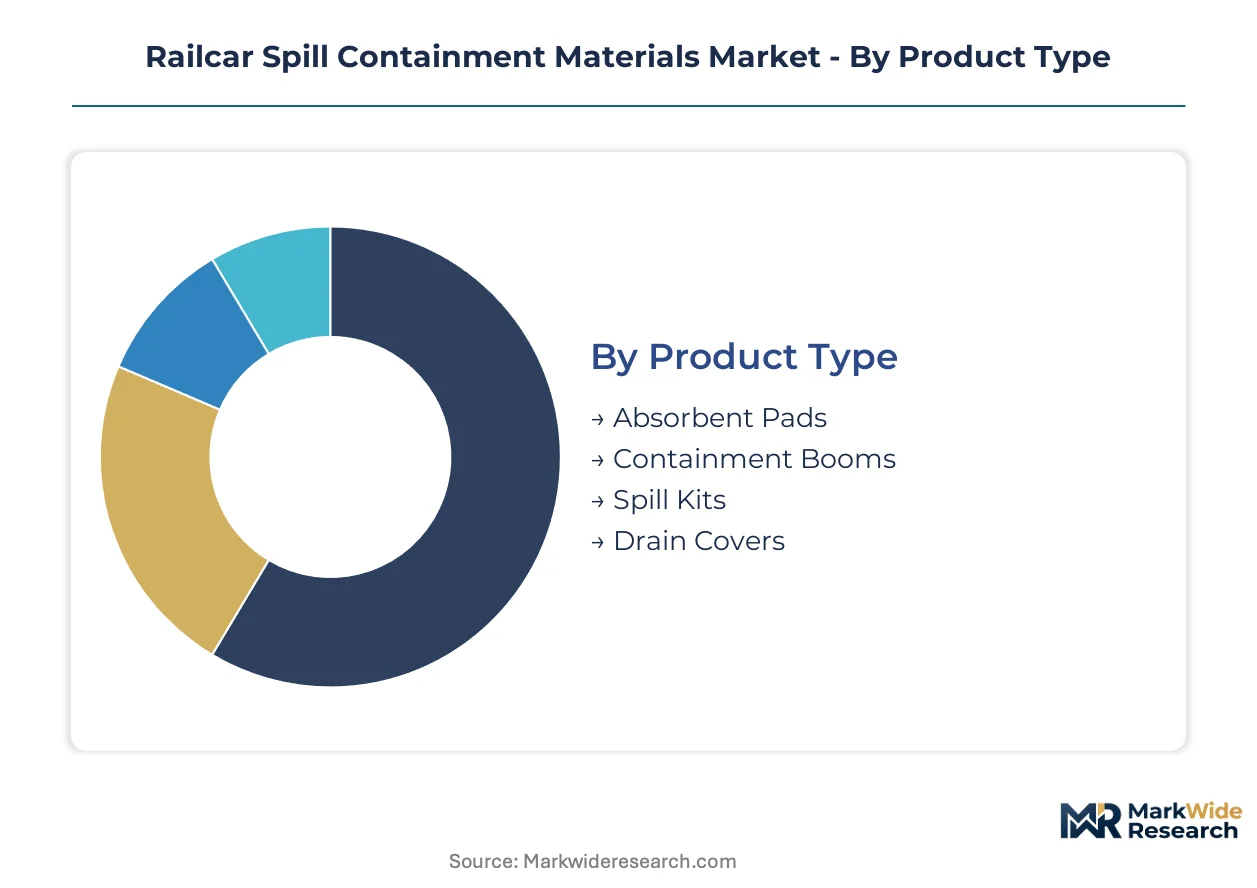
Railcar spill containment procurement varies sharply across product configurations, material specifications, and operational contexts. Segment boundaries determine compliance pathways, replacement economics, and supplier margin structures for railroad operators and chemical shippers.
Product Type:
Upgrade cycles for legacy containment infrastructure differ markedly by product format, with modular systems commanding premium replacement economics versus disposable consumables.
- Spill Kits:Pre-configured bundles of absorbent pads, socks, and disposal bags standardized for EPA compliance documentation. Rail yard operations in Texas and Louisiana concentrate procurement here due to SPCC inspection protocols at bulk liquid terminals.
- Containment Booms:Flexible barrier systems deployed for trackside drainage capture and stormwater management retrofit. These are climbing fastest as Class I railroads retrofit infrastructure to satisfy volumetric capture mandates for worst-case discharge scenarios.
- Absorbent Pads:Flat-sheet media for localized spill response on tank car surfaces and loading platforms.
- Drain Covers:Temporary sealing devices for rail yard storm drain protection during loading operations.
Spill kits sit at the top of the volume ranking, with containment booms climbing the fastest.
Material:
Cost tier separation between synthetic and natural formulations drives specification divergence across chemical transport corridors with varying corrosion exposure.
- Polypropylene:Melt-blown synthetic media achieving sorption capacities exceeding ten times dry weight for petroleum derivatives. Premium chemical transport applications in corrosive liquid corridors favor this material despite propylene supply chain volatility.
- Clay:Cost-effective granule formulations for non-aggressive liquid containment. Commodity chemical shippers specify this tier where liability exposure permits lower-performance economics.
- Synthetic Fiber:Engineered blends for specialized chemical resistance beyond standard polypropylene capabilities.
- Natural Fiber:Cellulose and cotton-based alternatives constrained by OSHA exposure limits for maintenance personnel handling saturated media.
Polypropylene dominates revenue concentration, though clay retains volume share in price-sensitive segments.
Application:
Customer type maturity determines specification complexity, with established rail operators demanding certified performance versus emergent users prioritizing procurement simplicity.
- Rail Transportation:Primary demand channel encompassing tank car loading, transit, and unloading containment. Federal Railroad Administration safety directives and DOT tank car integrity rules compress replacement cycles here.
- Industrial Storage:Secondary containment for rail-served bulk liquid terminals and tank farms. Texas and Louisiana facilities face elevated EPA SPCC compliance thresholds.
- Emergency Response:Rapid-deployment inventory for derailment and discharge events.
- Waste Management:Saturated media collection and disposal logistics.
Rail transportation anchors volume demand, with industrial storage expanding most quickly on terminal infrastructure investment.
End User:
Procurement authority concentration shapes supplier access, with centralized railroad purchasing functions disintermediating traditional distributor relationships.
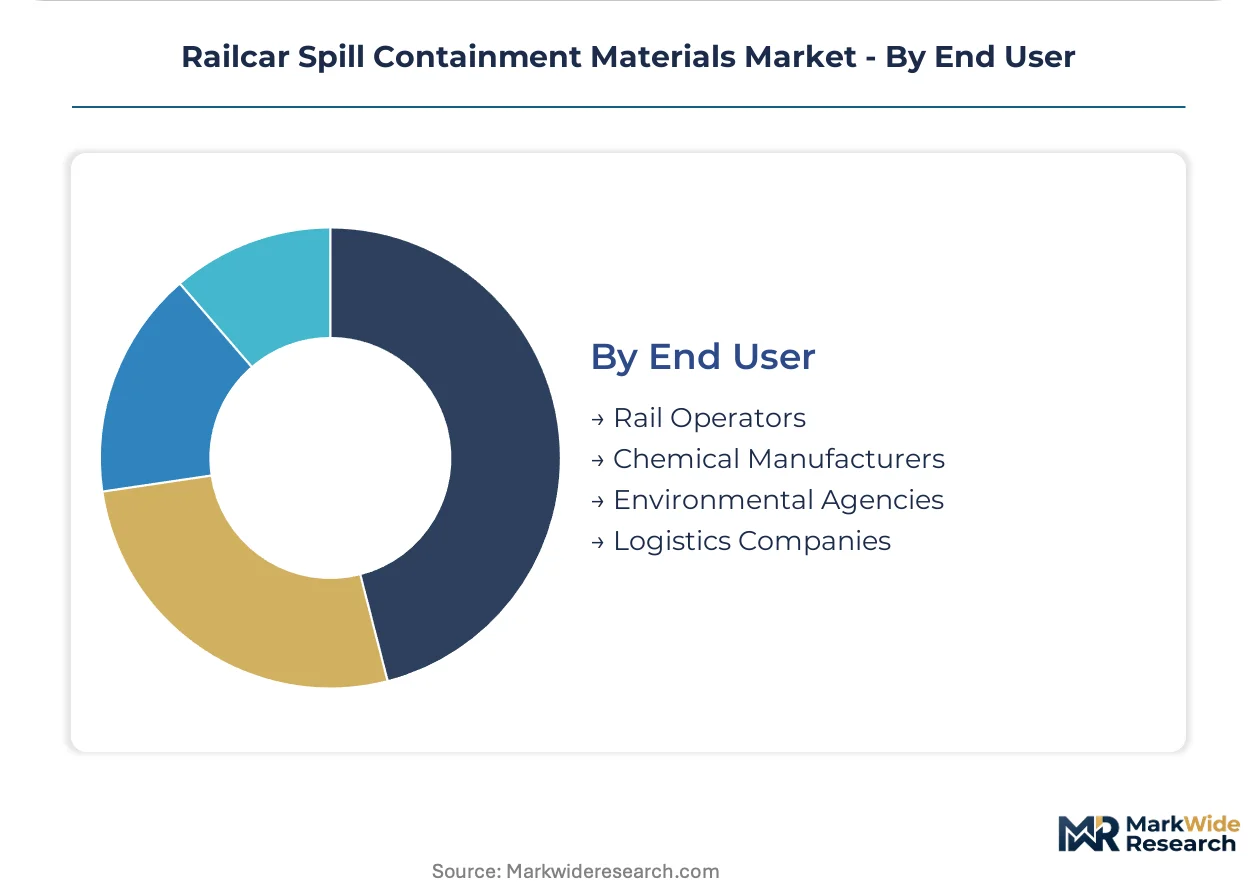
- Rail Operators:Class I railroads including Union Pacific and BNSF Railway drive specification standards through centralized procurement. Buyer consolidation compresses negotiation cycles and unbundles service from hardware.
- Chemical Manufacturers:Bulk liquid shippers face escalating liability exposure that forces absorbent media upgrades. Midwest hub facilities pilot smart absorbent technologies with RFID tracking.
- Environmental Agencies:Regulatory enforcement drives compliance bundling requirements.
- Logistics Companies:Third-party railcar lessors and transload operators with fragmented procurement authority.
Rail operators command the largest procurement volume, with chemical manufacturers gaining share fastest on liability-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Houston and Baton Rouge anchor North American spill containment procurement authority. Chemical transport corridors concentrate specification-setting power in these Gulf Coast metros. Regulatory enforcement intensity varies sharply across state environmental liability frameworks.
United States
Class I railroads including Union Pacific and BNSF Railway compress replacement cycles through centralized procurement functions. EPA Spill Prevention, Control, and Countermeasure requirements exceed historical rail industry norms for secondary containment capacity. Bulk liquid terminals in Texas and Louisiana deploy modular berm systems to satisfy volumetric capture mandates for worst-case discharge scenarios.
Canada
Transcontinental rail operators face parallel Transport Canada dangerous goods regulations with inspection protocols for tank car integrity. The country's national transport regulator mandates containment performance documentation for crude oil and chemical corridors. Alberta's oil sands shipping infrastructure drives absorbent media procurement for bitumen transport applications.
Germany
Rail freight operators navigate EU REACH chemical safety standards alongside national rail safety directives. The Federal Railway Authority enforces containment specifications for cross-border chemical transport through the Rhine-Ruhr industrial corridor. BASF and Bayer shipping operations at Ludwigshafen and Leverkusen anchor demand for high-performance absorbent formulations.
China
State railway operators expand chemical transport capacity along coastal manufacturing belts under MEE environmental compliance frameworks. The Ministry of Ecology and Environment tightens spill response preparedness for hazardous materials corridors. Yangtze River Delta petrochemical clusters at Ningbo and Shanghai drive procurement of trackside drainage retrofit systems.
India
Indian Railways and private freight operators face escalating liability exposure on bulk liquid corridors serving refinery and chemical zones. The Central Pollution Control Board mandates spill prevention infrastructure at major loading terminals. Gujarat's Jamnagar refinery complex and Maharashtra's Mumbai-Pune industrial belt concentrate demand for standardized spill kit deployments.
Railcar Spill Containment Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base organizes around three strategic archetypes: polymer technology developers, modular system integrators, and compliance-focused distributors. Consolidation pressure intensifies as railroads centralize purchasing authority and unbundle service from hardware procurement. Dominant competitive moves include backward integration into absorbent media manufacturing and geographic expansion through distributor acquisition.
Within the polymer formulation tier, UltraTech International and ENPAC LLC exemplify technology-driven positioning. SafeRack occupies a specialist position in loading rack containment integration. Eagle Manufacturing Company and New Pig Corporation represent diversified industrial safety players with cross-sector spill containment portfolios. Justrite Manufacturing Company anchors the fire safety and containment convergence segment. These named entities illustrate how supplier archetypes map to distinct procurement channels: technology premiums for chemical shippers, integration value for terminal operators, and compliance bundling for maintenance departments.
| Leading Market Players |
|---|
| Eagle Manufacturing Company |
| ENPAC LLC |
| UltraTech International |
| New Pig Corporation |
| SafeRack |
| Justrite Manufacturing Company |
| SpillTech Environmental |
| Complete Environmental Products |
| Chemtex |
| Others |
Value Network & Pricing Analysis
Propylene price benchmarks cascade through polypropylene melt-blown media supply chains, compressing margin structures for premium absorbent manufacturers while amplifying cost advantages for clay-based granule suppliers serving commodity chemical transport segments across North American rail networks.
Pricing Analysis
Service unbundling from hardware procurement compresses supplier pricing power as Class I railroads separate saturated media disposal contracts from containment equipment purchases. Three-tier pricing structure across premium, standard, and economy levels reflects sorption capacity certification grades and EPA SPCC documentation completeness. Pricing pressure stems from buyer consolidation among Union Pacific and BNSF Railway procurement functions. Chemical manufacturers exhibit lowest price sensitivity due to liability-driven specification mandates, while third-party logistics operators prioritize economy-tier clay formulations.
Supply Chain Analysis
Regional distribution centers in Houston and Baton Rouge anchor hub-and-spoke patterns for Gulf Coast chemical corridor deployment. Manufacturing concentrates in the United States, China, and Germany. Polypropylene resin, melt-blown fabrication equipment, and RFID sensor components constitute critical input dependencies. Tariff exposure on Chinese synthetic fiber imports threatens margin stability for modular spill kit assemblers. Distribution runs through railroad-approved vendor lists and direct terminal contracts rather than traditional industrial safety distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Railcar Spill Containment Materials Market functions as a stable compounder anchored by EPA and DOT regulatory mandates that perpetuate replacement cycle visibility regardless of freight volume cyclicality.
For Market Incumbents: Acquire specialized polymer formulation capabilities to secure captive supply of melt-blown media and defend against propylene price volatility. Deepen backward integration into RFID-enabled smart absorbent manufacturing to capture technology premiums from Midwest chemical hub pilots. Consolidate field service capacity for legacy infrastructure retrofit deployments before regional specialists scale. For New Entrants and Emerging Players: Smart absorbent technologies with color-change saturation indicators offer defensible entry points against established pad suppliers. Target trackside drainage infrastructure retrofit opportunities where containment boom specification standards remain fluid. Pursue direct contracting relationships with Texas and Louisiana bulk liquid terminal operators bypassing centralized railroad procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with modular spill kit architects possessing cross-fleet standardization capabilities and EPA documentation automation tools. The five-to-ten-year viability window favors suppliers with demonstrated Federal Railroad Administration safety directive compliance. Monitor DOT tank car integrity rule revision timing as inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Media Manufacturing | Captive resin processing insulates margins from propylene benchmark volatility in Gulf Coast chemical corridors. |
| Smart Absorbent Technology Launch | RFID tracking and color-change indicators decentralize inventory authority to field maintenance supervisors. |
| EPA SPCC Compliance Certification Investment | Documented volumetric capture capability satisfies inspection protocols at Texas and Louisiana bulk terminals. |
| Long-term Service Agreement with Class I Railroads | Bundled saturated media disposal contracts restore pricing power disintermediated by centralized procurement. |
| Joint Venture with Regional Distributor Network | Hub-and-spoke distribution access accelerates deployment timelines for legacy containment infrastructure retrofit. |
Research Methodology
Coverage spans the United States, Canada, Germany, China, and India, with primary inputs from each market cluster combining executive interviews with rail operator procurement directors, chemical shipper EHS managers, containment system distributors, and EPA compliance consultants. Secondary validation draws from Federal Railroad Administration safety directives, EPA Spill Prevention Control and Countermeasure filings, DOT tank car integrity rule dockets, and customs trade data for polypropylene absorbent imports. Bottom-up unit economics for spill kit configurations triangulate against top-down rail yard retrofit expenditure estimates.
Granularity-level modeling disaggregates volume and value across product type, material formulation, application context, and end-user procurement authority. Sorption capacity tiers, certification documentation requirements, and fleet replacement cycle phasing constitute industry-specific forecast inputs. CAGRs derive from regulatory mandate compliance deadlines and historical replacement pattern analysis across the projection horizon.
The model holds under sustained EPA and DOT enforcement intensity; deviation in state-level environmental liability framework harmonization or propylene supply disruption would shift replacement timing and specification mix. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Digital Railway Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railcar Movers Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Point Machine Market
Railway Transportation
Rail Pads Market