
 Rail Testing Vehicle Market | 2026-2036
Rail Testing Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Testing Vehicle Market Insights
Carbon fiber-reinforced polymer is consolidating its position as the preferred chassis material for next-generation rail testing vehicles, replacing conventional steel frames to reduce axle loads and improve sensor stability at operating speeds above 200 km/h. Siemens Mobility leverages its in-house composite manufacturing to control component costs across European deployments. Wabtec Corporation anchors its North American fleet with steel-aluminum hybrid designs that sustain interoperability with legacy maintenance infrastructure. Alstom differentiates through integrated sensor housing architectures that dominate high-speed corridors in France and Spain.
A rail testing vehicle is a self-propelled or towable railway car equipped with non-destructive testing apparatus, including ultrasonic wheel probes, laser alignment scanners, and accelerometer arrays, designed to detect rail defects, track geometry deviations, and catenary wear during revenue-service or dedicated inspection runs. Track inspection vehicles represent the most mature segment with stable replacement demand across European infrastructure managers, while ultrasonic testing platforms capture the fastest expansion as operators shift from periodic manual rail flaw detection to continuous automated monitoring. Railway diagnostics applications concentrate margin pools where real-time data transmission to traffic control centers commands premium pricing from integrated system vendors.
The Federal Railroad Administration enforces Track Safety Standards that mandate minimum inspection frequencies, directly shaping procurement volumes for Class I railroads operating across the United States. The European Union Agency for Railways coordinates interoperability standards through the CCS TSI specification, while Germany's KBA certifies vehicle authorization for cross-border deployment. Japan's MLIT rail safety directives require earthquake-resilient testing protocols that influence sensor redundancy specifications. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting between outsourced inspection services and captive fleet investments.
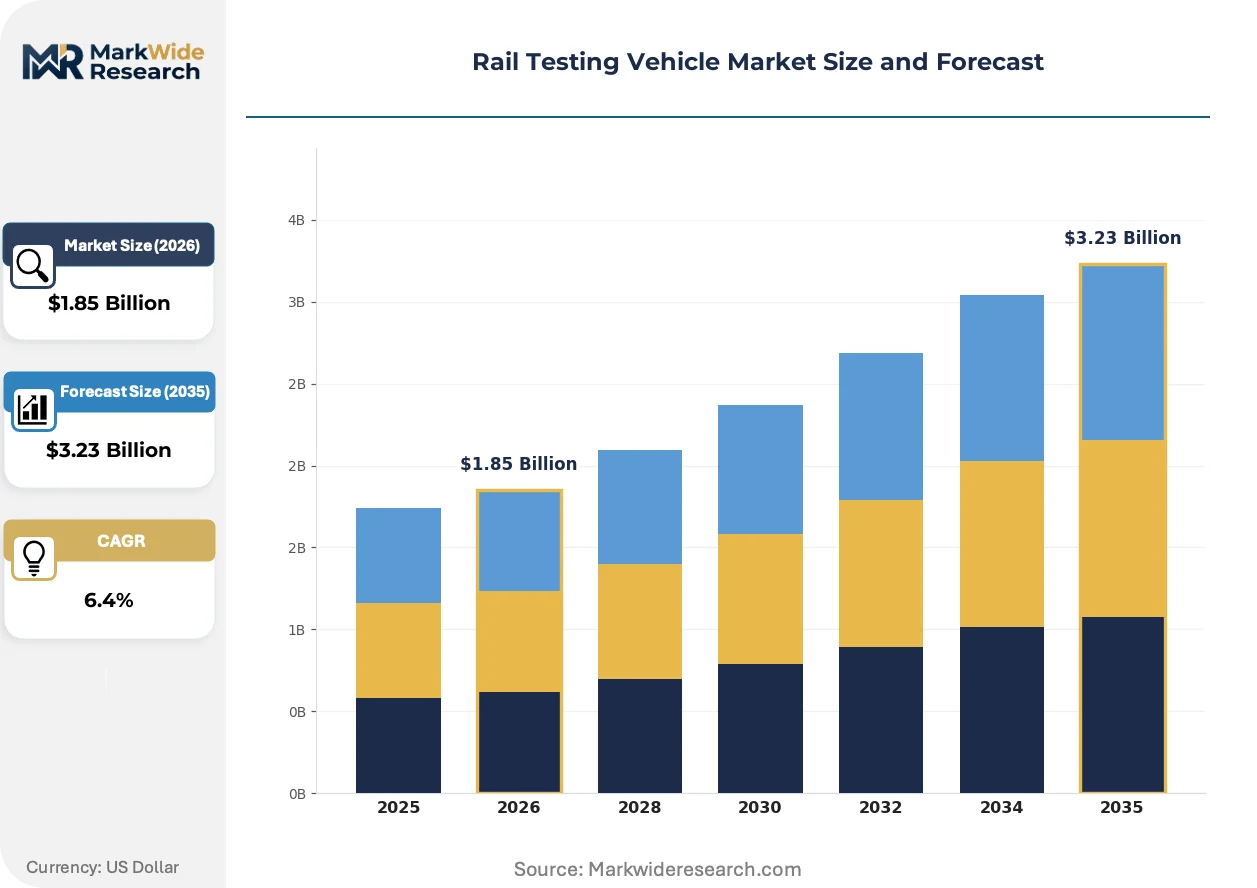
Market Dynamics
The Federal Railroad Administration's Track Safety Standards are compressing inspection cycles for Class I railroads, forcing a structural shift from manual flaw detection crews toward continuous automated monitoring platforms that operate at revenue-service speeds.
Growth Catalysts
- Ultrasonic wheel probe arrays:German high-speed corridors now mandate continuous rail flaw detection at 200 km/h, eliminating scheduled track possession windows and accelerating vehicle procurement.
- Carbon fiber chassis adoption:Infrastructure managers in France and Spain prioritize axle load reduction to minimize track damage during inspection runs, favoring composite platforms over steel frames.
- FRA Track Safety Standards:Minimum inspection frequency mandates for US Class I railroads create captive demand cycles independent of freight volume fluctuations.
Market Restraints
- Specialized sensor supply concentration:Laser alignment scanner production clusters in Germany and Japan, exposing procurement timelines to single-source bottlenecks.
- Steel-aluminum hybrid platform obsolescence risk:Legacy maintenance infrastructure across North American rail yards locks operators into heavier chassis designs that forfeit speed advantages.
- Catenary wear detection technical limits:Existing accelerometer arrays struggle to isolate pantograph contact force variations from track-induced vibration noise.
Strategic Opportunities
- India's Dedicated Freight Corridors:Greenfield track construction creates first-mover positioning for integrated diagnostic vehicle suppliers before maintenance ecosystems crystallize.
- EU CCS TSI interoperability certification:Cross-border vehicle authorization requirements favor system vendors with established European railway agency relationships.
- Real-time data transmission to traffic control:5G rail corridor deployments in Japan enable premium-priced predictive maintenance subscriptions.
Industry Challenges
- Ultrasonic technician certification pipelines:European infrastructure managers face 18-month training timelines for flaw interpretation specialists.
- Legacy track geometry database integration:Decades of manual inspection records resist standardization into machine-readable formats for algorithmic trend analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Testing Vehicle Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Track Inspection, Ultrasonic Testing, Railway Diagnostics, Measuring Vehicle Technology: Digital Signal Processing, Optical Sensors, Acoustic Emission, RFID Application: Track Maintenance, Safety Inspection, Performance Testing, Quality Assurance End User: Railway Operators, Infrastructure Managers, Government Agencies, Engineering Consultants |
| Companies Covered | Bombardier Transportation, MoniRail, Wabtec Corporation, Sensonic, PhySens, Alstom, Next Generation Robotics, MxV Rail, Siemens Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Testing Vehicle Market Trends and Innovations
Sensor fusion architectures are compressing the distinction between track geometry measurement and rail flaw detection, enabling single-pass inspection runs that previously required dedicated vehicle fleets.
Machine vision systems paired with eddy current arrays are unifying surface defect detection and subsurface crack identification into unified sensor heads. Deutsche Bahn and SNCF Réseau have operationalized these platforms across their high-speed networks since 2023. This convergence is unifying procurement specifications that previously separated geometry cars from ultrasonic testing vehicles.
Japan's MLIT earthquake-resilient testing protocols now require redundant inertial measurement units and backup power systems for vehicles operating on Shinkansen corridors. Vehicle manufacturers must demonstrate sensor continuity through simulated seismic events before receiving type approval. The directive compresses design cycles for suppliers lacking prior seismic certification experience.
Maintenance outsourcing contracts are fragmenting fleet ownership models across European infrastructure managers. Deutsche Bahn and Trenitalia now lease inspection capacity from specialized service providers rather than maintaining captive vehicle pools. This rotation is most visible in Germany, where DB Netz has transferred over half its testing fleet to long-term operating leases since 2022.
Rail Testing Vehicle Market Segmentation
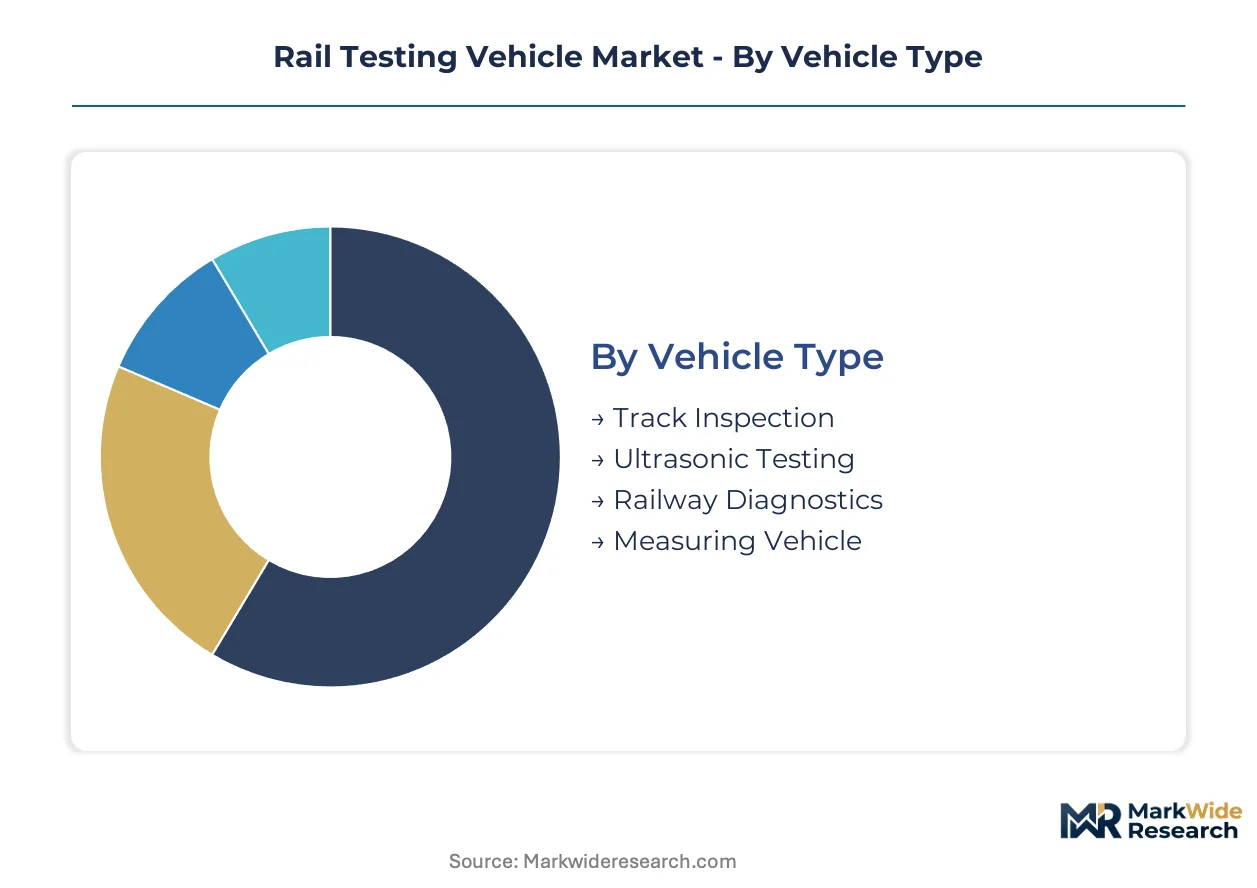
Rail testing vehicle procurement splits sharply between standardized fleet replacements and custom-engineered platforms for high-speed corridors. Infrastructure managers weigh interoperability certification costs against performance specifications when selecting across these dimensions.
Vehicle Type:
Standardized chassis designs dominate volume procurement, while specialized sensor integration commands premium positioning in high-speed networks.
- Track Inspection:Conventional wheel-rail interface monitoring systems with laser alignment and accelerometer arrays. Deutsche Bahn and SNCF Réseau deploy these across legacy networks in Germany and France where replacement cycles follow fixed maintenance windows.
- Ultrasonic Testing:Continuous rail flaw detection platforms operating at revenue-service speeds above 200 km/h. Japan's Shinkansen corridors and Spain's AVE network mandate these for automated subsurface crack identification, eliminating manual track possession requirements.
- Railway Diagnostics:Integrated multi-sensor architectures combining geometry measurement with catenary wear assessment.
- Measuring Vehicle:Precision track geometry recording systems for new line commissioning and post-maintenance verification.
Leading the category by volume: Track Inspection. Growing fastest: Ultrasonic Testing.
Technology:
Processing architectures cluster around real-time data throughput requirements, with edge computing adoption separating premium from standard tiers.
- Digital Signal Processing:FPGA-based ultrasonic signal interpretation enabling immediate flaw classification without cloud dependency. US Class I railroads prioritize these systems for FRA compliance reporting across remote territory lacking continuous cellular coverage.
- Optical Sensors:Machine vision and laser triangulation for surface defect mapping at speeds exceeding 300 km/h. France and Spain specify these for high-speed corridor contracts where pantograph-catenary interaction monitoring adds incremental value.
- Acoustic Emission:Vibration signature analysis for wheel flat detection and bearing condition monitoring.
- RFID:Automated asset tracking and location tagging for inspection data georeferencing.
Widest deployment: Digital Signal Processing. Steepest expansion trajectory: Optical Sensors.
Application:
Regulatory mandate intensity varies sharply across these use cases, with safety-critical applications commanding captive procurement regardless of freight volume cycles.
- Track Maintenance:Scheduled geometry verification and tamping quality control following renewal work. Infrastructure managers in Italy and Germany outsource these functions to specialized service providers under long-term operating leases.
- Safety Inspection:FRA Track Safety Standards and EU CCS TSI compliance verification. US Class I railroads face mandatory minimum frequencies that structure fleet sizing independent of commercial performance.
- Performance Testing:Ride quality assessment and dynamic load measurement for new rolling stock acceptance.
- Quality Assurance:Post-construction verification for greenfield track installations.
Most procurement volume concentrates in: Track Maintenance. Fastest regulatory-driven expansion: Safety Inspection.
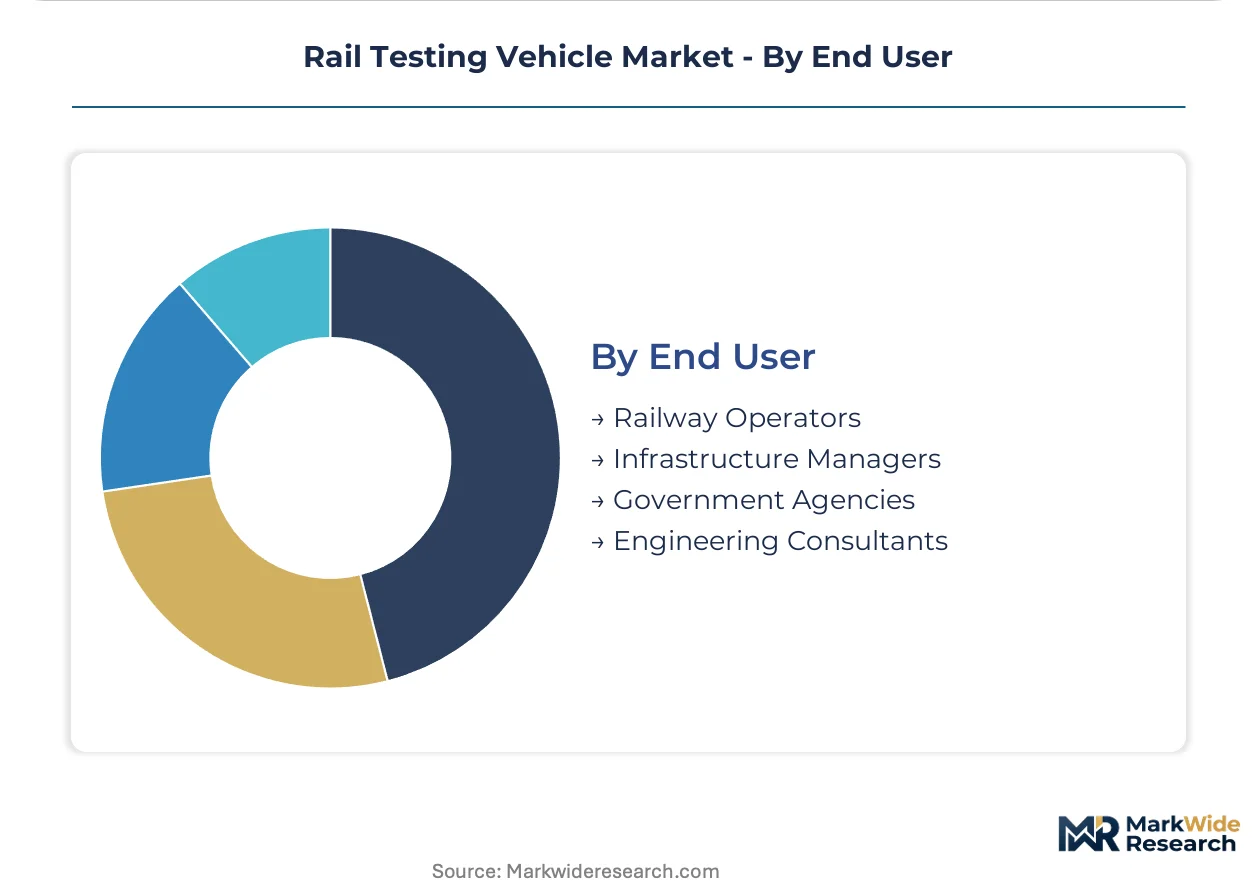
End User:
Ownership models fragment between captive fleet operators and outsourced service providers, reshaping vendor customer relationships across European markets.
- Railway Operators:Integrated freight and passenger carriers maintaining internal inspection capacity. BNSF Railway and Union Pacific in the United States anchor North American demand with dedicated ultrasonic testing fleets.
- Infrastructure Managers:Dedicated track authorities like DB Netz and Trenitalia that increasingly lease rather than own testing vehicles. This shift concentrates procurement authority with fewer specialized service providers.
- Government Agencies:National safety regulators and transport ministries funding research and standardization programs.
- Engineering Consultants:Third-party verification services for new line commissioning and dispute resolution.
Dominant procurement authority: Infrastructure Managers. Emerging contract structure growth: Engineering Consultants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German infrastructure managers and US Class I railroads concentrate procurement authority for rail testing vehicles, while Japanese Shinkansen operators and Spanish AVE networks drive high-speed corridor specifications. Regulatory mandates from the Federal Railroad Administration and EU Agency for Railways structure fleet replacement cycles across these markets.
United States
Class I railroads including BNSF Railway and Union Pacific maintain dedicated ultrasonic testing fleets exceeding 200 vehicles combined. The Federal Railroad Administration enforces Track Safety Standards mandating minimum inspection frequencies that structure captive demand independent of freight volume fluctuations. Omaha and Fort Worth serve as fleet maintenance hubs where Wabtec Corporation anchors North American deployments with steel-aluminum hybrid chassis designs.
Germany
Deutsche Bahn and DB Netz transferred over half their testing fleet to long-term operating leases since 2022, fragmenting ownership toward specialized service providers. Germany's KBA certifies vehicle authorization for cross-border deployment under EU CCS TSI interoperability standards. Berlin and Munich host composite manufacturing clusters where Siemens Mobility controls carbon fiber-reinforced polymer component costs for next-generation chassis platforms.
Japan
MLIT rail safety directives require earthquake-resilient testing protocols with redundant inertial measurement units for Shinkansen corridor operations. The directive compresses design cycles for suppliers lacking prior seismic certification experience. Nagoya and Osaka anchor manufacturing clusters where sensor redundancy specifications influence procurement decisions for continuous monitoring platforms operating above 300 km/h.
France
SNCF Réseau operationalized machine vision systems paired with eddy current arrays across high-speed networks since 2023, unifying surface and subsurface defect detection. Infrastructure managers prioritize axle load reduction through carbon fiber chassis adoption to minimize track damage during inspection runs. Paris and Lyon concentrate procurement authority where Alstom dominates through integrated sensor housing architectures.
Spain
AVE network operators mandate ultrasonic testing platforms for automated subsurface crack identification, eliminating manual track possession requirements. Adif infrastructure managers specify optical sensors for pantograph-catenary interaction monitoring on high-speed corridors. Madrid and Barcelona serve as deployment centers where EU CCS TSI certification requirements favor established European railway agency relationships.
Rail Testing Vehicle Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding premium positioning in high-speed corridors and component suppliers anchoring volume procurement for legacy network modernization. The vendor base clusters around three strategic archetypes: composite chassis specialists leveraging in-house manufacturing, sensor fusion integrators unifying multi-modal detection platforms, and outsourced service providers capturing fleet ownership through long-term operating leases. Dominant competitive moves include M&A activity targeting ultrasonic probe array capabilities and strategic partnerships with infrastructure managers for predictive maintenance subscriptions.
Within the integrated system tier, Siemens Mobility and Alstom exemplify European-based specialists with established railway agency certification pathways, while Wabtec Corporation occupies a position among North American fabricators with legacy maintenance infrastructure interoperability. These three entities represent contrasting archetypes: composite manufacturing control, sensor housing integration, and steel-aluminum hybrid platform continuity.
| Leading Market Players |
|---|
| Bombardier Transportation |
| MoniRail |
| Wabtec Corporation |
| Sensonic |
| PhySens |
| Alstom |
| Next Generation Robotics |
| MxV Rail |
| Siemens Mobility |
| Others |
Pricing and Supply Chain Analysis
Ultrasonic technician certification pipelines concentrated in Germany and Japan feed labor-cost differentials that widen pricing spreads between premium sensor-integrated platforms and standardized chassis replacements. Infrastructure managers in France and Spain absorb premium positioning for carbon fiber-reinforced polymer architectures, while North American operators locked into steel-aluminum hybrid designs capture mid-tier economics through legacy maintenance infrastructure interoperability.
Pricing Analysis
Volume procurement concentrates in standardized track inspection chassis where economies of scale compress unit economics, while margin pools accrue to ultrasonic testing platforms with integrated FPGA-based signal processing and real-time flaw classification. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber composite architectures with full sensor fusion from steel-aluminum hybrids with discrete measurement arrays and basic geometry-only configurations. Cost compression in the standard tier intensifies because infrastructure managers in Germany and Italy increasingly outsource fleet ownership to specialized service providers under long-term operating leases. Government agencies and research institutions exhibit least price sensitivity given mandate-driven procurement timelines, while regional railway operators in emerging corridors demonstrate highest elasticity to upfront capital requirements.
Supply Chain Analysis
Laser alignment scanner production rests on German and Japanese specialty sensor manufacturers, creating single-source vulnerability for infrastructure managers procuring high-speed corridor platforms. Carbon fiber-reinforced polymer chassis draw from composite manufacturing clusters in Germany and France, while steel-aluminum hybrid frames source from North American fabrication networks anchored in Omaha and Fort Worth. FPGA-based digital signal processing modules hinge on semiconductor supply chains concentrated in Taiwan and South Korea. Tariff exposure on carbon fiber precursor materials threatens cost structures for European composite chassis specialists. Distribution runs through direct vendor relationships with infrastructure managers and railway operators, with increasing penetration of leased fleet arrangements that shift procurement authority toward specialized service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
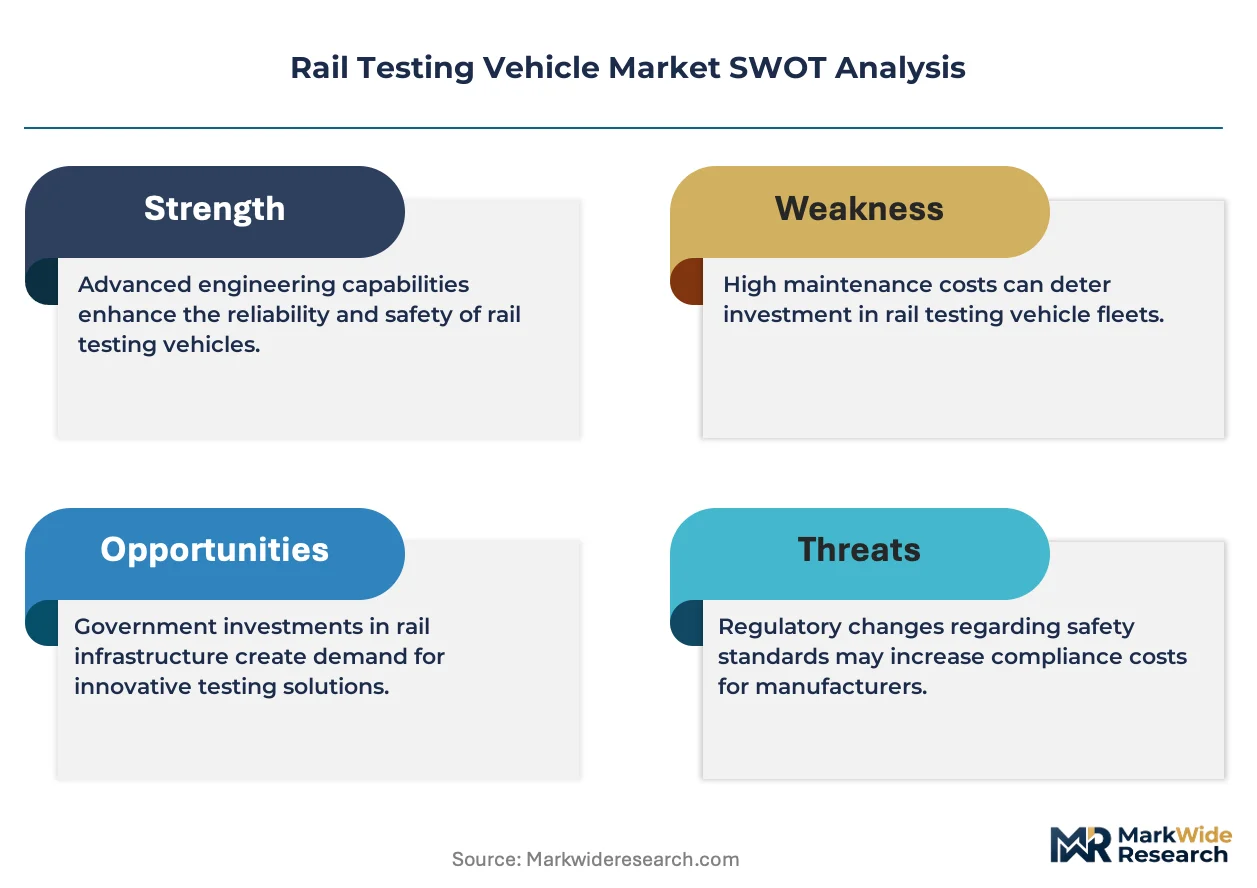
This market operates as a vertical-integration race where control over carbon fiber-reinforced polymer manufacturing or ultrasonic probe array capabilities determines margin capture across high-speed corridor deployments.
For Market Incumbents: Lock in sensor fusion architectures through captive development of machine vision and eddy current array integration, defending against modular component suppliers that unbundle detection capabilities. Secure long-term operating lease agreements with infrastructure managers in Germany and Italy before maintenance outsourcing ecosystems crystallize around specialized service providers. Prioritize KBA and EU CCS TSI certification pathways to maintain cross-border vehicle authorization advantages over North American competitors lacking established European railway agency relationships. For New Entrants and Emerging Players: Enter via India's Dedicated Freight Corridors where greenfield track construction creates first-mover positioning before maintenance ecosystems and incumbent fleet relationships solidify. Target outsourced inspection service contracts with infrastructure managers transitioning from captive fleet ownership, particularly in European markets where Deutsche Bahn and Trenitalia have transferred majority testing capacity to operating leases. Lead with 5G-enabled real-time data transmission capabilities that command premium pricing from Japanese Shinkansen operators under MLIT earthquake-resilient testing protocols. For Investors and Strategic Acquirers: Re-rating potential sits with composite chassis specialists possessing in-house carbon fiber-reinforced polymer manufacturing given infrastructure manager prioritization of axle load reduction across France and Spain. Long-term viability over the projection horizon favors vendors with integrated sensor housing architectures rather than discrete component suppliers facing unbundling pressure from modular procurement specifications. Monitor FRA Track Safety Standards enforcement intensity as the inflection indicator for North American ultrasonic testing vehicle procurement cycles independent of freight volume fluctuations.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Chassis Manufacturing Scale-Up | Siemens Mobility controls component costs through in-house composite production for European high-speed deployments. |
| Ultrasonic Probe Array Acquisition | Integrated sensor fusion capabilities unify surface and subsurface defect detection previously requiring separate vehicle fleets. |
| EU CCS TSI Certification Investment | Cross-border vehicle authorization requirements favor established relationships with Germany's KBA and European railway agencies. |
| 5G Real-Time Data Platform Launch | Japanese MLIT protocols enable premium-priced predictive maintenance subscriptions through traffic control center integration. |
| Operating Lease Fleet Restructuring | Deutsche Bahn and DB Netz have transferred majority testing capacity to specialized service providers since 2022. |
Research Methodology
Document review covered FRA Track Safety Standards filings, EU CCS TSI interoperability specifications, KBA vehicle authorization records, and Japan MLIT rail safety directives, complemented by interviews with infrastructure managers at Deutsche Bahn and SNCF Réseau, procurement leads at BNSF Railway and Union Pacific, ultrasonic technician training program directors, and composite manufacturing engineers at Siemens Mobility facilities. Secondary validation drew from customs and trade data for rail testing vehicle imports, SEC 10-K disclosures from Wabtec Corporation, railway infrastructure investment databases, and high-speed network operator procurement records. Bottom-up unit economics triangulated against top-down infrastructure modernization budget allocations across Germany, the United States, Japan, France, and Spain.
Historical deployment patterns for track inspection and ultrasonic testing vehicles cross-referenced against panel input from infrastructure managers regarding fleet replacement timelines and regulatory compliance windows. Segmentation modeling incorporated vehicle type, processing architecture, application mandate intensity, and end-user ownership structure across the projection horizon. CAGRs derived from elasticity-adjusted demand curves reflecting FRA minimum inspection frequency mandates and German high-speed corridor continuous monitoring requirements. Industry-specific forecast inputs included carbon fiber precursor material cost trajectories and ultrasonic wheel probe array production capacity at German and Japanese specialty sensor manufacturers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended FRA enforcement delays or accelerated EU CCS TSI interoperability deadlines. Modeling assumptions reflect regulatory mandate intensity, infrastructure manager outsourcing propensity, and composite chassis adoption curves across high-speed networks. Shifts in Federal Railroad Administration Track Safety Standards interpretation, KBA certification timeline compression, or MLIT seismic protocol amendments warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Rail Pads Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Rail Fasteners Market