
 Electric Motors for IC Engine Vehicle Market | 2026-2036
Electric Motors for IC Engine Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motors for IC Engine Vehicle Market Foresight
Buyer concentration among tier-one automotive suppliers is recalibrating procurement strategies for electric motors serving internal combustion engine vehicles. Robert Bosch GmbH leverages its integrated powertrain division to supply 48-volt belt-driven starter-generator units across multiple OEM platforms. Denso Corporation anchors Japanese automaker supply chains with compact, high-efficiency motor designs for hybrid assist applications. Continental AG competes through scalable manufacturing architectures that span low-voltage mild hybrids and high-voltage plug-in systems.
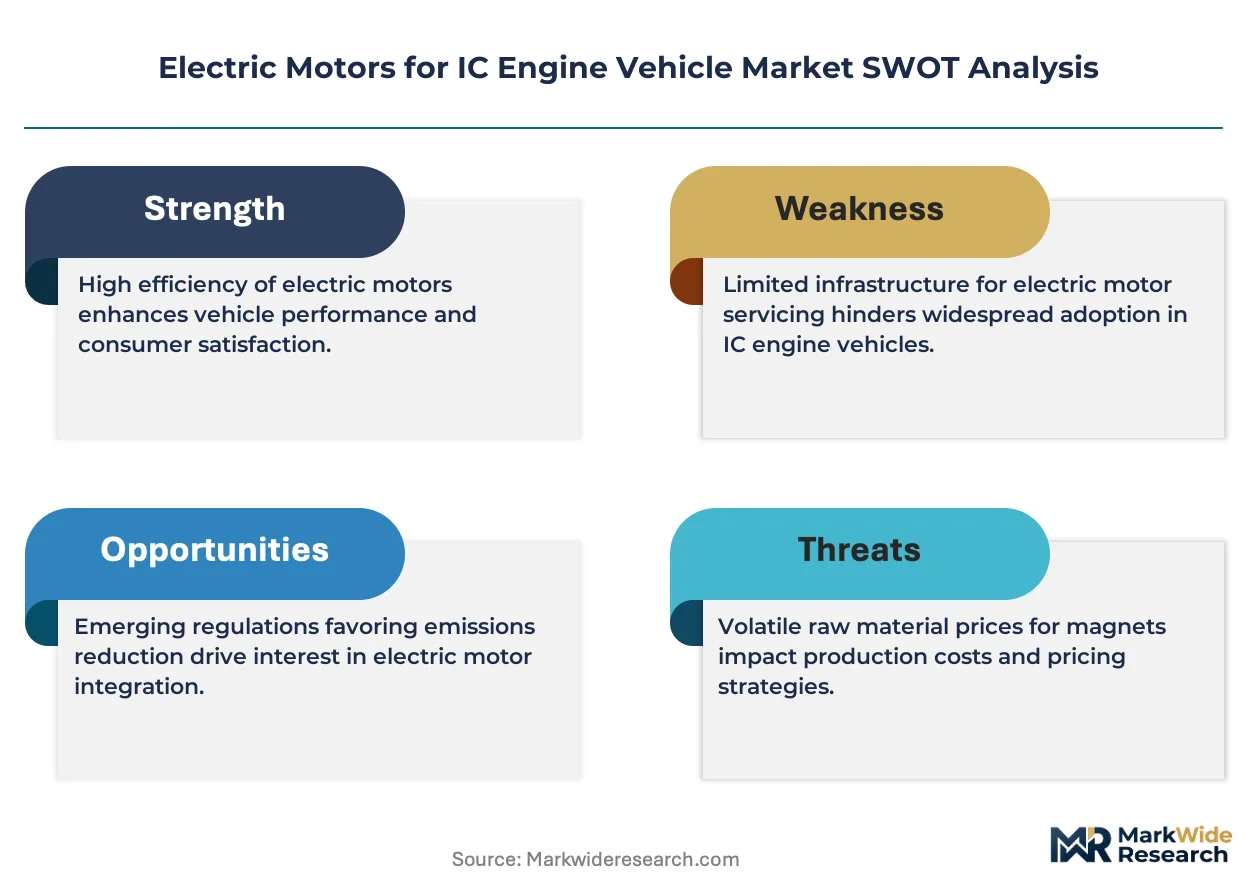
Electric motors for IC engine vehicles are electromechanical devices converting electrical energy into mechanical torque, typically operating at 12V to 800V depending on hybrid architecture, with permanent magnet rotor designs achieving peak efficiencies above 95 percent in starter-generator and electric boost roles. Their primary purpose is to enable fuel-saving functions including regenerative braking, torque fill, and engine stop-start across vehicles retaining gasoline or diesel combustion cores. Permanent magnet motor types currently lead value capture due to rare-earth magnet performance density, while switched reluctance designs are gaining engineering attention for reduced material cost exposure. Application demand clusters around mild hybrid and full hybrid electric vehicles where motor integration with existing transmission and thermal systems minimizes platform redesign burden.
The EPA enforces tailpipe CO2 standards that directly expand motor electrification requirements across light-duty and medium-duty vehicle classes, while NHTSA administers fuel economy rules creating compliance credit value for hybrid motor deployment. OEMs must monitor how these regulatory frameworks evolve alongside state-level zero-emission vehicle mandates in California and aligned jurisdictions. Stakeholders should track whether rare-earth supply security policies or alternative magnet material breakthroughs reshape motor cost structures and sourcing geography.
Market Dynamics
The transition from 12-volt architectures to 48-volt mild-hybrid systems is compressing motor supplier margins while expanding unit volumes across passenger car and light truck platforms. This voltage migration demands redesigned winding configurations, thermal management systems, and power electronics integration that incumbent suppliers must absorb without full cost pass-through.
Growth Catalysts
- NHTSA CAFE standards:Fleet averaging rules in the United States create compliance credit value for every gram of CO2 reduction achieved through motor electrification, pushing OEMs to specify belt-driven starter-generator units on base powertrains.
- 48-volt lithium-ion battery cost curves:Cell chemistry improvements and scaled manufacturing in South Korea and China are bringing mild-hybrid battery packs below the threshold where motor-battery system payback periods match typical vehicle ownership cycles.
- German automotive engineering:Stuttgart and Munich engineering centers are anchoring European development of integrated starter-generator architectures that reduce engine displacement without sacrificing drivability.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility and geopolitical friction.
- Copper winding cost exposure:LME copper price swings directly compress gross margins on high-torque motor variants where conductor mass dominates bill-of-materials weight.
- Internal combustion platform sunset risk:OEMs in California and aligned states face CARB zero-emission vehicle mandates that accelerate powertrain electrification timelines, shortening the addressable window for IC-specific motor investments.
Strategic Opportunities
- India's BS-VI Phase II implementation:Tightened particulate and NOx limits are forcing domestic automakers to adopt stop-start systems and mild-hybrid assist, creating first-mover advantage for suppliers establishing local winding and assembly operations.
- Switched reluctance motor convergence:Elimination of permanent magnets through advanced rotor geometry and silicon carbide inverter pairing opens cost-competitive positioning for price-sensitive compact car segments.
- Aftermarket remanufacturing channels:Independent service networks in Germany and the United States are developing diagnostic and rebuild capabilities for starter-generator units, extending revenue capture beyond initial equipment sales.
Industry Challenges
- Electromagnetic compatibility certification:48-volt system architectures must demonstrate immunity to conducted and radiated interference under ISO 11452 and CISPR 25 protocols, extending validation timelines by four to six months.
- Thermal management skill scarcity:Motor suppliers compete for engineers with combined expertise in fluid dynamics, power electronics cooling, and automotive grade reliability, particularly in Michigan and Baden-Württemberg labor markets.
- Legacy transmission integration:Torque fill and launch assist functions require real-time calibration with existing clutch and torque converter control modules, multiplying software validation effort across OEM platform variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motors for IC Engine Vehicle Market |
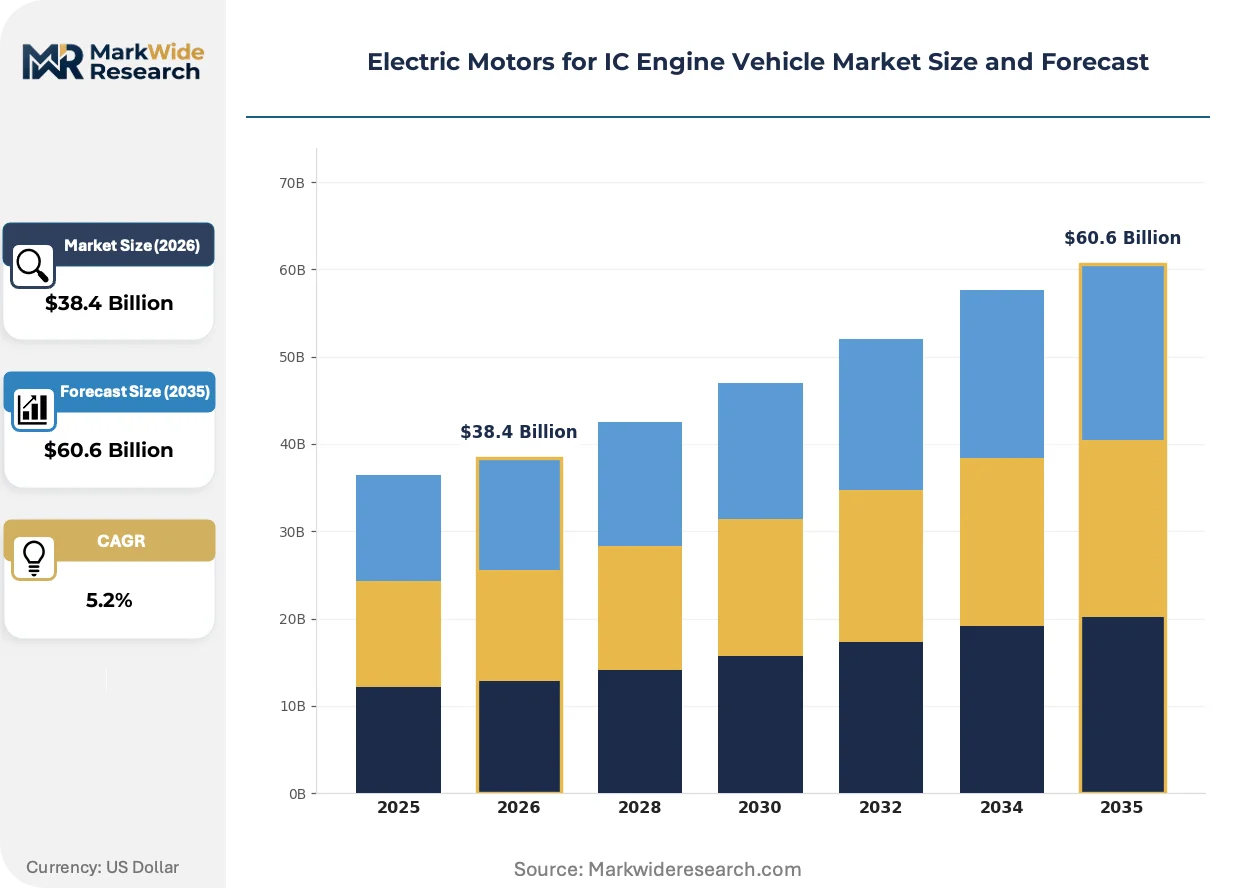
| Market Size in 2026 | $38.4 Billion |
| Market Size in 2035 | $60.6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Induction, Permanent Magnet, Brushless, Switched Reluctance Power Rating: Low Power, Medium Power, High Power, Ultra High Power Application: Hybrid Electric Vehicles, Mild Hybrids, Plug-in Hybrids, Range-Extended Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Commercial Fleets |
| Companies Covered | Nidec Corporation, Denso Corporation, Robert Bosch GmbH, Johnson Electric Holdings Limited, Mitsubishi Electric Corporation, Continental AG, Valeo SA, BorgWarner Inc., Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motors for IC Engine Vehicle Market Shifts & Advancements
Power semiconductor advances and winding automation are converging to reshape motor cost structures and performance envelopes. Suppliers are reconfiguring manufacturing footprints and engineering organizations to capture these shifts.
Hairpin winding technology is expanding into mass-market mild-hybrid motors. This conductor geometry replaces traditional round wire with rectangular cross-sections packed at higher density in the stator slot. Bosch and Denso are deploying automated insertion equipment across their European and Asian plants. The technology is expanding into cost-sensitive segments previously reserved for simpler concentrated windings.
EPA tailpipe CO2 standards are tightening enforcement timelines for light-duty vehicle classes. The regulatory consequence is accelerated platform electrification even within vehicles retaining combustion cores. Full-size pickup and SUV segments in the United States are responding with integrated starter-generator systems that enable cylinder deactivation and aggressive engine-off coasting.
Fleet procurement practices are consolidating motor specifications across multiple OEM customers. Tier-one suppliers now face consolidated annual negotiations where platform-scale commitments determine allocation of engineering resources. This concentration is most visible in Germany, where Bosch, Continental, and Valeo compete for shared mild-hybrid architectures across Volkswagen Group, BMW, and Mercedes-Benz vehicle lines.
Electric Motors for IC Engine Vehicle Market Segmentation
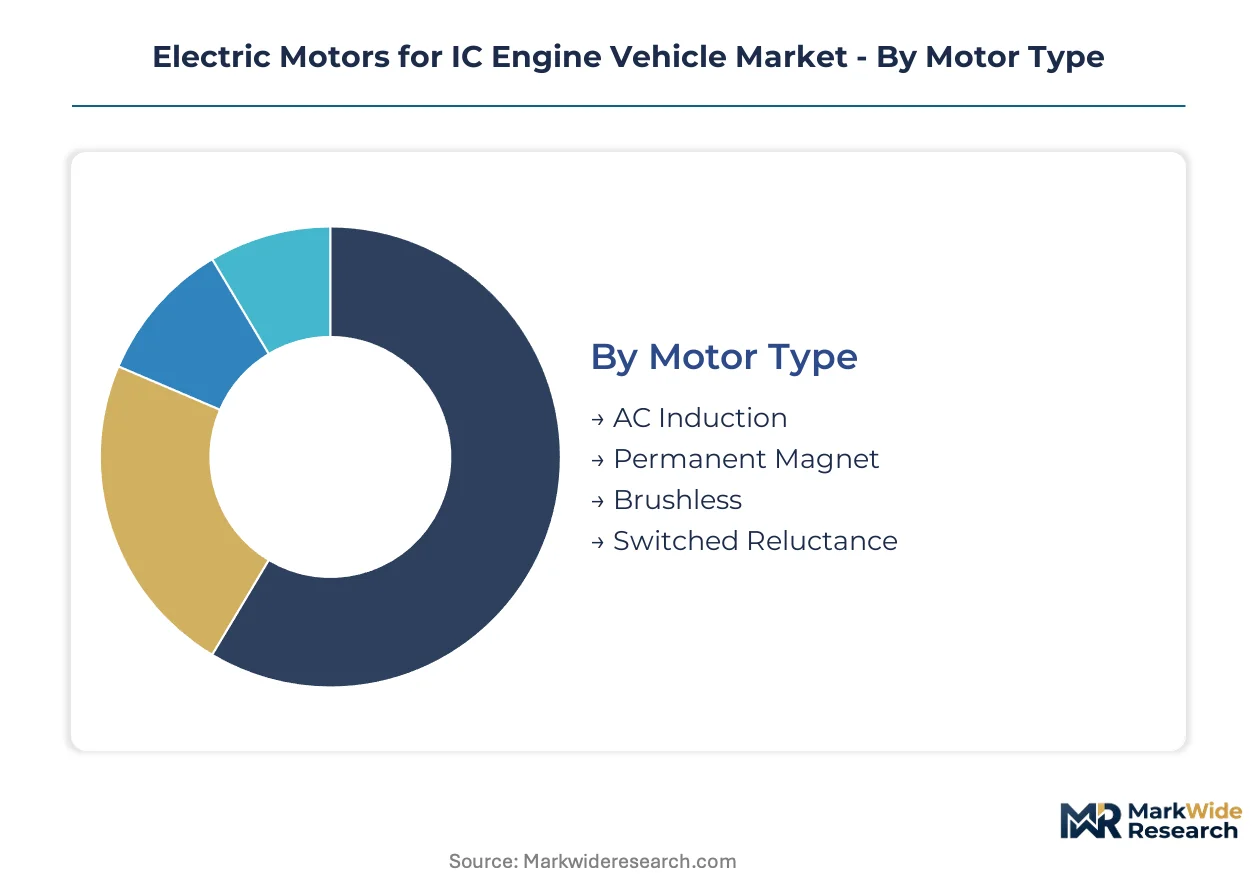
Motor specification diversity reflects the tension between platform electrification depth and combustion retention. Procurement patterns diverge sharply across voltage architectures and thermal integration requirements.
Motor Type:
Supply concentration in rare-earth processing shapes competitive positioning across rotor technologies.
- Permanent Magnet:Neodymium-iron-boron rotors deliver torque density above 95% peak efficiency in 48-volt belt-driven starter-generator applications. Demand clusters in German passenger car platforms where Bosch and Continental anchor supply chains for mild-hybrid architectures.
- Switched Reluctance:Elimination of rare-earth materials through salient-pole rotor geometry reduces bill-of-materials exposure to Chinese export quotas. Engineering attention is accelerating in India's compact car segment as domestic automakers seek cost-competitive electrification under BS-VI Phase II mandates.
- AC Induction:Copper rotor designs dominate cost-sensitive fleet applications with lower efficiency tolerance.
- Brushless:Electronic commutation enables precise torque control in integrated transmission-mounted configurations.
Permanent magnet configurations absorb the bulk of installed capacity; switched reluctance is expanding most quickly.
Power Rating:
Cost tier differentiation separates premium thermal management from commodity winding specifications.
- Medium Power:10-30 kW continuous output enables cylinder deactivation and electric boost in full-size US pickup platforms. EPA tailpipe enforcement is accelerating OEM procurement for integrated starter-generator systems that preserve towing capacity while capturing compliance credits.
- Low Power:Sub-10 kW belt-driven units serve stop-start and mild regenerative braking functions. Volume concentration in Japanese kei-car and European A-segment platforms where Denso and Valeo compete on packaging efficiency.
- High Power:30-80 kW outputs support torque fill in plug-in hybrid architectures.
- Ultra High Power:Above 80 kW ratings enable electric-only launch in performance-oriented range-extended vehicles.
Medium power ratings dominate current procurement volumes; low power configurations are climbing the fastest as 48-volt architectures penetrate mass-market segments.
Application:
Customer type fragmentation distinguishes platform integration depth from retrofit feasibility.
- Mild Hybrids:48-volt belt-driven or crankshaft-mounted systems enable engine-off coasting and regenerative braking without transmission redesign. German engineering centers in Stuttgart and Munich anchor European development for Volkswagen Group and BMW shared architectures.
- Hybrid Electric Vehicles:Full hybrid power-split systems demand motor integration with planetary gearsets and dedicated cooling circuits. Toyota and Honda supply chains in Japan concentrate procurement of compact, high-efficiency designs from Denso.
- Plug-in Hybrids:Dual-motor configurations support extended electric-only range.
- Range-Extended Vehicles:Traction motor sizing prioritizes electric drivability over combustion efficiency.
Mild hybrids capture the majority of current platform engineering resources; hybrid electric vehicles are gaining share fastest as US and Japanese OEMs balance electrification timelines against combustion sunset risk.
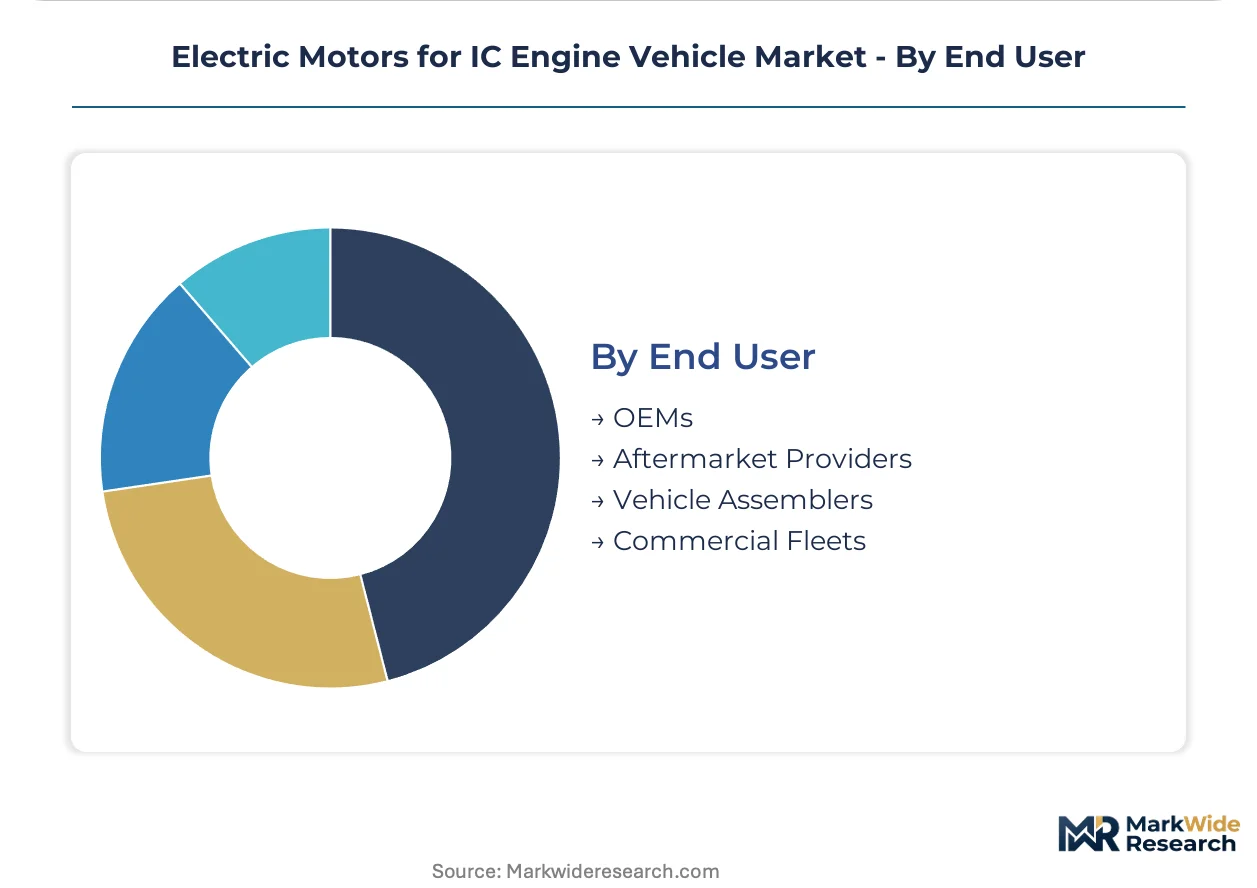
End User:
Geography of demand separates consolidated OEM negotiations from fragmented service channel economics.
- OEMs:Tier-one suppliers face annual platform-scale commitments that determine engineering resource allocation. Fleet procurement consolidation is most visible in Germany where Bosch, Continental, and Valeo compete for shared mild-hybrid specifications across Mercedes-Benz, BMW, and Volkswagen Group vehicle lines.
- Aftermarket Providers:Independent service networks in Germany and the United States are developing diagnostic and rebuild capabilities for starter-generator units. Revenue capture extends beyond initial equipment sales through remanufactured component channels.
- Vehicle Assemblers:Contract manufacturing arrangements concentrate motor sourcing decisions at parent OEM level.
- Commercial Fleets:High-utilization operators prioritize total cost of ownership over acquisition price.
OEMs command the dominant share of engineering-intensive procurement; aftermarket providers are expanding most quickly as first-generation mild-hybrid vehicles exit warranty coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electric motors in IC engine vehicles concentrates in automotive manufacturing clusters where emissions regulations and hybrid platform investments intersect most intensively.
United States
NHTSA CAFE standards and EPA tailpipe regulations are accelerating OEM procurement of integrated starter-generator systems for full-size pickup and SUV platforms. The regulatory enforcement timeline creates compliance credit value for every gram of CO2 reduction achieved through motor electrification. Detroit-area engineering centers anchor development of belt-driven starter-generator architectures that preserve towing capacity while enabling aggressive engine-off coasting.
Germany
Stuttgart and Munich engineering centers anchor European development of 48-volt mild-hybrid architectures for Mercedes-Benz, BMW, and Volkswagen Group vehicle lines. The country's national automotive regulator KBA enforces EU emissions frameworks that expand motor electrification requirements across passenger car fleets. Bosch, Continental, and Valeo compete for shared platform specifications in Baden-Württemberg and Bavaria industrial corridors.
Japan
Denso Corporation anchors supply chains for Toyota and Honda hybrid power-split systems requiring compact, high-efficiency motor designs. METI industrial policy supports domestic manufacturing of electrified powertrain components amid shifting global trade dynamics. Nagoya and Tokyo metropolitan areas concentrate engineering talent for transmission-integrated motor configurations.
China
Domestic automakers are expanding 48-volt mild-hybrid adoption to meet MIIT fuel consumption standards without full platform electrification. The country's dual carbon goals create policy pressure for incremental efficiency gains in vehicles retaining combustion cores. Shanghai and Guangzhou manufacturing clusters are scaling winding and assembly operations for regional OEM supply.
India
BS-VI Phase II implementation is forcing domestic automakers to adopt stop-start systems and mild-hybrid assist for particulate and NOx compliance. The Central Pollution Control Board enforcement timeline compresses supplier qualification windows for motor manufacturers. Chennai and Pune industrial belts are attracting first-mover suppliers establishing local winding and assembly operations.
Electric Motors for IC Engine Vehicle Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue switched reluctance and rare-earth-free alternatives to reduce material cost exposure. The supplier base organizes around three archetypes: integrated powertrain divisions of diversified conglomerates, specialized motor manufacturers with winding automation expertise, and diversified electronics suppliers leveraging power electronics capabilities. Consolidation pressure intensifies as OEM procurement teams negotiate platform-scale commitments across multiple vehicle lines. Dominant competitive moves include capacity expansion in low-cost manufacturing regions and strategic partnerships for silicon carbide inverter integration.
Among Japanese diversified suppliers, Denso Corporation and Mitsubishi Electric Corporation exemplify the integrated electronics-to-powertrain archetype. Robert Bosch GmbH anchors the European tier through its Stuttgart-based powertrain division. Nidec Corporation represents the specialized motor manufacturer model with concentrated winding automation investments. These three entities occupy positions spanning the voltage architecture spectrum from 12-volt stop-start to 800-volt plug-in hybrid systems.
| Leading Market Players |
|---|
| Nidec Corporation |
| Denso Corporation |
| Robert Bosch GmbH |
| Johnson Electric Holdings Limited |
| Mitsubishi Electric Corporation |
| Continental AG |
| Valeo SA |
| BorgWarner Inc. |
| Hitachi Astemo |
| Others |
Supply & Pricing Matrix
Tier-one automotive OEM procurement teams concentrate annual platform-scale negotiations with Bosch, Continental, and Denso, locking in contract-based long-term offtake pricing that compresses supplier margins while securing volume commitments across multiple vehicle lines.
Pricing Analysis
Volume-margins split sharply between high-volume belt-driven starter-generator units and low-volume integrated transmission motors. Pricing stratifies across premium, standard, and economy tiers based on thermal management sophistication and ISO 26262 functional safety certification levels. Cost compression in standard-tier 48-volt motors is intensifying because OEMs demand full cost pass-through on winding automation investments. Fleet procurement managers at commercial operators exhibit highest price sensitivity, while performance-oriented OEMs tolerate premium positioning for torque-fill capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth processing capacity in Inner Mongolia and Jiangxi provinces, where neodymium and dysprosium extraction feeds permanent magnet rotor production. The motor supply chain draws from German power electronics engineering, Chinese magnet processing, and Japanese precision winding equipment manufacturing. Commodity price volatility in copper and rare-earth oxides creates margin squeeze risk for high-torque motor variants. Distribution runs through consolidated Tier 1 supplier hubs in Stuttgart, Nagoya, and Detroit before final assembly at OEM powertrain plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric motor for IC engine vehicle market sits in a technology-transition phase where 48-volt mild-hybrid architectures displace pure 12-volt systems before full battery-electric platforms sunset the addressable market entirely.
For Market Incumbents: Extend manufacturing automation investments into hairpin winding equipment to defend cost position against emerging switched reluctance entrants. Secure backward integration into silicon carbide inverter partnerships as power electronics integration becomes the primary differentiation lever. Lock in multi-year platform commitments with Volkswagen Group and Toyota before Chinese suppliers qualify for shared mild-hybrid architectures. For New Entrants and Emerging Players: Aftermarket service networks in Germany and the United States represent the most penetrable buyer archetype as first-generation mild-hybrid vehicles exit warranty coverage. Target independent rebuild shops with diagnostic equipment and remanufactured rotor-stator assemblies. Pursue qualification partnerships with domestic Indian automakers seeking BS-VI Phase II compliance through cost-competitive switched reluctance designs. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized winding automation specialists in Baden-Württemberg and Michigan as OEM procurement consolidation pressures mid-tier suppliers. The five-to-ten-year viability window hinges on internal combustion platform sunset timelines in California-aligned jurisdictions. Monitor CARB zero-emission vehicle mandate enforcement acceleration as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Hairpin Winding Automation Deployment | Bosch and Denso capture cost parity with round-wire legacy designs across European and Asian plants. |
| Silicon Carbide Inverter Integration | Continental and Valeo reduce switching losses in 48-volt belt-driven starter-generator thermal management. |
| Rare-Earth-Free Motor Development | Switched reluctance rotor designs eliminate Chinese magnet quota exposure for India's BS-VI Phase II segment. |
| Aftermarket Diagnostic Platform Launch | German independent service networks rebuild starter-generator units beyond initial equipment revenue capture. |
| Local Winding Operations in India | First-mover suppliers establish Chennai and Pune assembly capacity ahead of domestic automaker qualification windows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and power electronics specialists. EPA enforcement timelines, NHTSA CAFE compliance databases, and KBA type-approval registries provided regulatory validation. Vehicle production databases and IHS Markit registration data enabled bottom-up volume triangulation against top-down market sizing.
Data-stream reconciliation across motor type, power rating, application depth, and regional production cluster dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro fleet electrification assumptions. Forecast inputs incorporated OEM platform electrification timelines, rare-earth supply quota trajectories, and 48-volt lithium-ion battery cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CARB zero-emission vehicle mandate acceleration and Chinese rare-earth export policy shifts. Forecasts reflect documented assumptions about internal combustion platform sunset timelines and hybrid architecture penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Air Motor Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
UAE Electric Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Car Charger Market
Electric Motor
Smart E-Drive Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Europe Automotive Torque Actuator Motor Market