
 Brake Override System Market | 2026-2036
Brake Override System Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Override System Market Analysis
The EU Green Deal's embedded vehicle safety requirements is expanding brake override mandates across European OEM supply chains. Robert Bosch GmbH leverages its mechatronics integration depth to dominate electronic module supply. Continental AG anchors German manufacturing scale for sensor-fused override architectures. Toyota Motor Corporation sustains Japanese market leadership through captive production of hybrid brake override systems.
A brake override system is an active safety mechanism that electronically prioritizes brake command over accelerator input when both pedals are depressed simultaneously, typically integrating throttle position sensors, brake pedal switches, and powertrain control modules with sub-50 millisecond response latency. Its primary commercial purpose is eliminating unintended acceleration incidents in mass-produced automobiles. Electronic product types command the widest OEM fitment scope due to software-definable calibration thresholds, while passenger vehicle applications generate the deepest volume pool despite slower per-unit margin expansion relative to commercial vehicle safety-enhancement tiers. Adaptive technology segments attract Tier-1 engineering investment as automakers seek predictive pedal conflict detection rather than reactive intervention.
NHTSA Federal Motor Vehicle Safety Standards and UN ECE Regulation 13-H shape North American and European product certification pathways, while Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces domestic type approval for brake override integration. China's MIIT and GB standards increasingly mandate comparable functionality for new energy vehicle platforms. Stakeholders must monitor divergence between adaptive AI-driven override protocols and legacy deterministic architectures as regulatory bodies weigh algorithmic transparency requirements against real-time safety performance.
Market Dynamics
UN ECE Regulation 13-H and NHTSA pedal entrapment directives are compressing brake override system certification timelines while forcing Tier-1 suppliers to rearchitect sensor-fused electronic modules for sub-50 millisecond response latency.
Growth Catalysts
- UN ECE vehicle safety protocols:Mandated electronic brake override integration across European passenger vehicle platforms is accelerating module procurement cycles for German and Japanese OEMs.
- New energy vehicle platforms:China's MIIT and GB standards are embedding comparable brake override functionality into battery-electric and hybrid powertrain architectures.
- Precision electronics cluster:Japan's concentration of mechatronics engineering talent is enabling rapid calibration of adaptive AI-driven override protocols.
Market Restraints
- Semiconductor input volatility:Powertrain control module chip supply concentration in East Asian foundries creates procurement risk for electronic brake override manufacturers.
- Regulatory fragmentation:Divergence between deterministic legacy architectures and adaptive AI-driven protocols across NHTSA, UN ECE, and Japan's MLIT approval pathways extends certification timelines.
- Mechanical override substitution:Low-cost commercial vehicle segments in emerging markets continue specifying cable-actuated throttle systems that bypass electronic intervention.
Strategic Opportunities
- Predictive pedal conflict detection:Convergence of throttle position sensors with machine learning inference engines is expanding into premium passenger vehicle safety packages.
- EU Green Deal embedded requirements:Vehicle safety mandates tied to carbon-neutral fleet targets are creating regulatory tailwinds for brake override module standardization.
- US Southeast manufacturing belt:Toyota Motor Corporation's regional production network offers captive supply integration opportunities for electronic module suppliers.
Industry Challenges
- Algorithmic transparency compliance:Regulators weighing AI-driven override protocols against deterministic systems are demanding explainable decision logic documentation that extends engineering cycles.
- Legacy powertrain integration:Retrofitting electronic brake override into existing internal combustion architectures without full platform redesign creates calibration complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Override System Market |
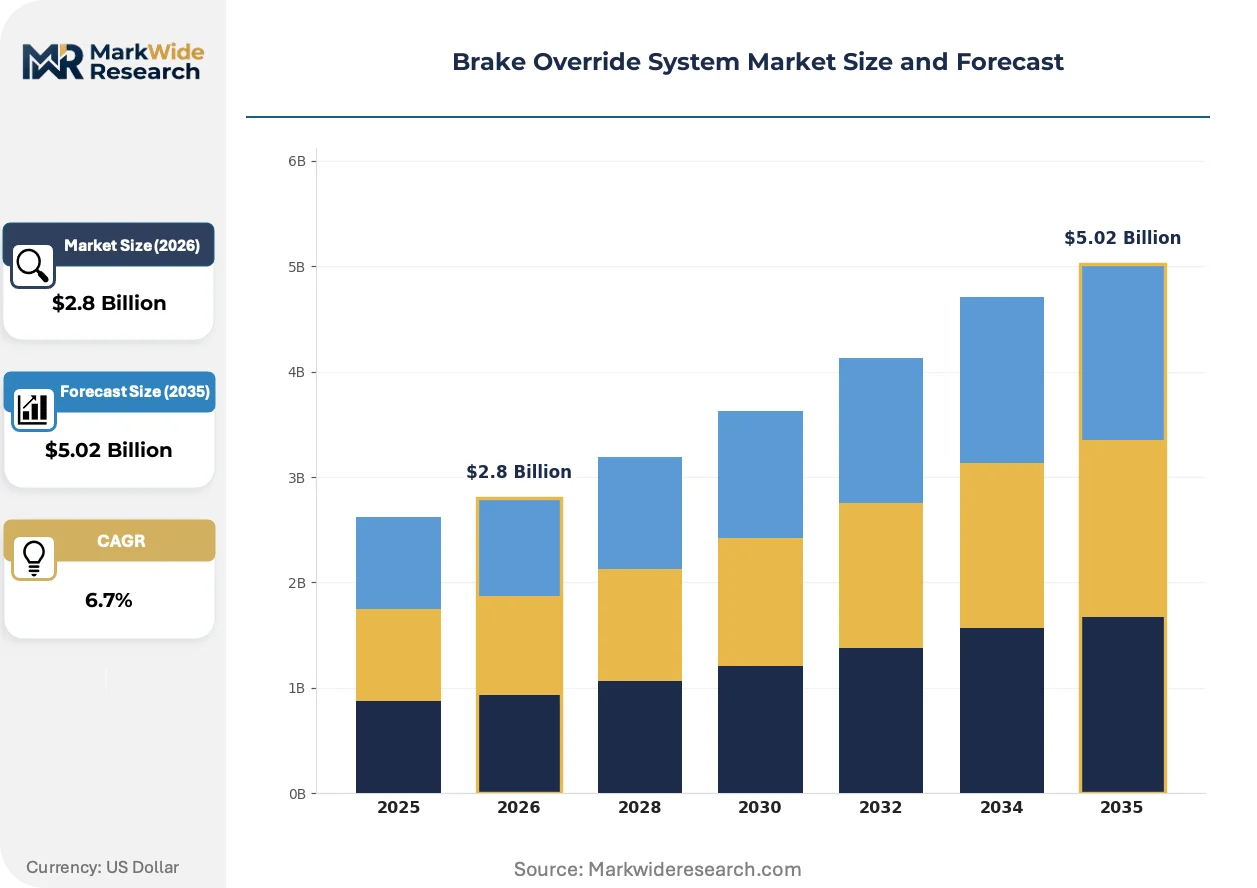
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Hybrid, Software Application: Passenger Vehicles, Commercial Vehicles, Buses, Motorcycles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Automatic, Manual, Adaptive, Safety-Enhancement |
| Companies Covered | Toyota Motor Corporation, Nissan Motor Co. Ltd., Honda Motor Co. Ltd., Robert Bosch GmbH, BMW AG, Hyundai Motor Co., Continental AG, Suzuki Motor Corporation, Renault, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Override System Market Emerging Trajectories
Sensor fusion architectures and adaptive inference engines are displacing deterministic brake override logic, while procurement patterns consolidate around vertically integrated mechatronics suppliers capable of end-to-end module certification.
Adaptive brake override technology integrating predictive pedal conflict detection with real-time powertrain arbitration is expanding into premium and mass-market passenger vehicle segments. European and Japanese OEMs are adopting these sensor-fused architectures fastest, driven by tightened UN ECE and MLIT response latency requirements. This capability expansion is compressing margins for standalone electronic module suppliers lacking upstream sensor integration.
EU Green Deal embedded vehicle safety requirements are mandating brake override functionality as a condition of fleet carbon compliance, effectively bundling active safety with environmental certification. This regulatory convergence forces OEMs to source integrated modules rather than discrete components. German automotive suppliers are responding by consolidating mechatronics engineering with powertrain control calibration under single supplier accountability.
Buyer concentration among passenger vehicle OEMs is consolidating procurement decisions around Tier-1 suppliers with captive sensor production and in-house firmware development. Discrete component vendors without vertical integration are losing position in RFQ processes. This supplier consolidation is most visible in Germany's automotive corridor and Japan's precision electronics cluster, where Bosch and Toyota anchor respective regional production networks.
Brake Override System Market Segmentation
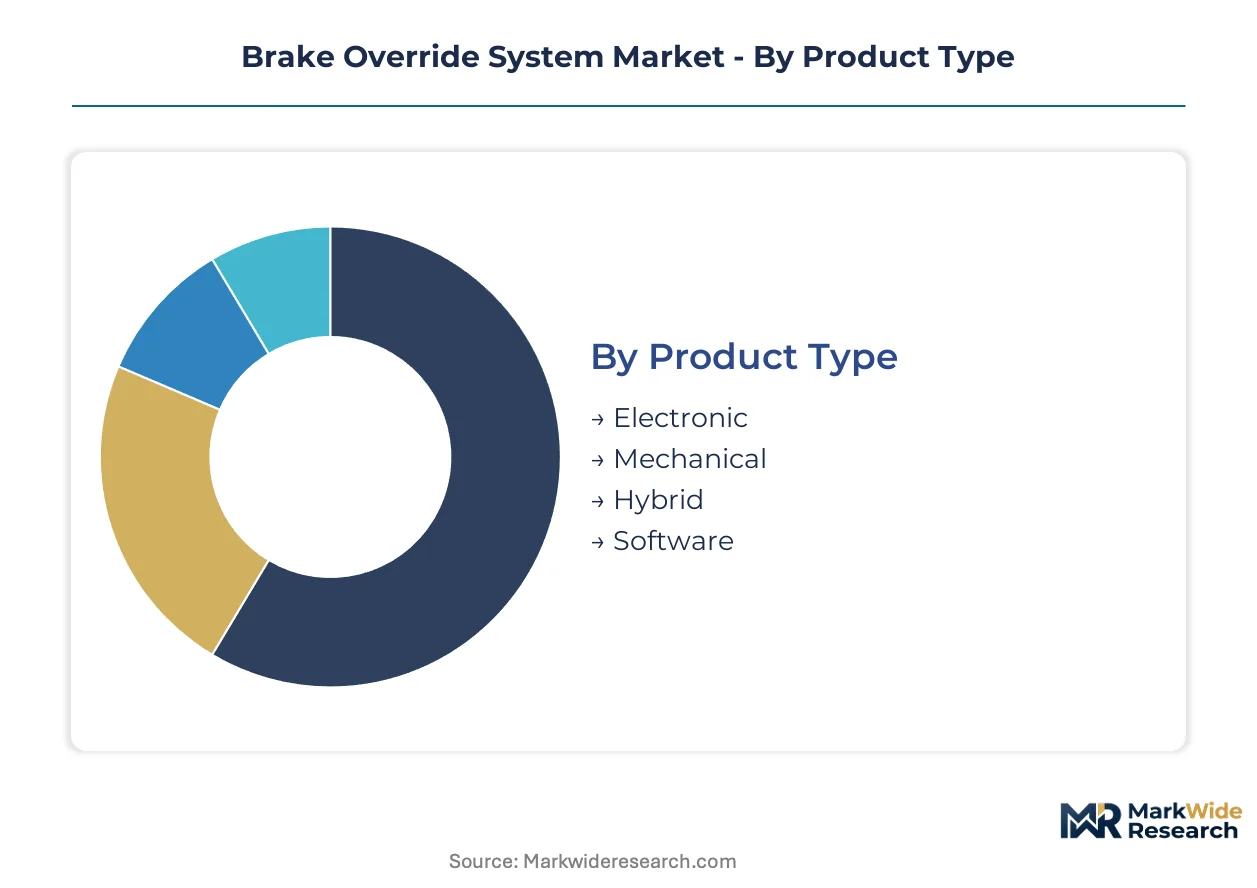
Brake override system procurement varies sharply across calibration complexity, integration depth, and regulatory certification tiers. Segmentation reveals where electronic module suppliers capture margin versus where mechanical alternatives retain cost-driven volume.
Product Type:
Standardization dominates at the low end with mechanical systems, while electronic and hybrid architectures demand extensive calibration customization per OEM platform.
- Electronic:Sensor-fused architectures integrate throttle position sensors, brake pedal switches, and powertrain control modules with sub-50 millisecond response latency. Procurement concentrates among German and Japanese passenger vehicle OEMs tightening compliance with UN ECE Regulation 13-H and NHTSA pedal entrapment directives.
- Mechanical:Cable-actuated throttle bypass systems operate without electronic intervention, preserving lowest-cost fitment for emerging market commercial segments. Demand persists where semiconductor supply volatility deters electronic module adoption.
- Hybrid:Dual-mode systems combine electronic priority logic with mechanical fallback redundancy.
- Software:Firmware-definable calibration stacks enabling over-the-air threshold updates.
Leading the category by volume: Electronic. Expanding most quickly: Software.
Application:
Passenger vehicle platforms generate deepest procurement volume, though commercial safety tiers sustain premium pricing through enhanced certification requirements.
- Passenger Vehicles:Mass-market fitment across compact through luxury segments drives electronic module standardization. German OEMs in Stuttgart and Munich anchor European demand, while Toyota Motor Corporation's production network across Aichi and Kentucky shapes global procurement patterns.
- Commercial Vehicles:Heavy-duty safety-enhancement tiers command per-unit premiums through predictive pedal conflict detection integration. Fleet operators in North American long-haul segments specify adaptive override architectures for insurance liability reduction.
- Buses:Municipal and intercity coach mandates under Japan's MLIT type approval accelerate sensor-fused adoption.
- Motorcycles:Two-wheeler brake override remains nascent, constrained by packaging limits and cost sensitivity in Asian volume markets.
Deepest volume concentration: Passenger Vehicles. Steepest expansion trajectory: Commercial Vehicles.
End User:
Procurement authority concentrates upstream as OEMs consolidate Tier-1 accountability for end-to-end module certification.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and Hyundai Motor Group direct brake override specification through captive supplier development programs. Direct OEM procurement of electronic modules is displacing discrete component sourcing as EU Green Deal embedded requirements bundle active safety with carbon compliance.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG anchor German manufacturing scale, integrating mechatronics engineering with firmware calibration under single-source accountability.
- Aftermarket Providers:Retrofit electronic modules face warranty exposure and calibration complexity in legacy internal combustion architectures.
- Fleet Operators:Commercial vehicle fleet procurement specifies adaptive override systems for duty-cycle-specific pedal conflict detection.
Controlling procurement decisions: OEMs. Gaining procurement authority fastest: Tier-1 Suppliers.
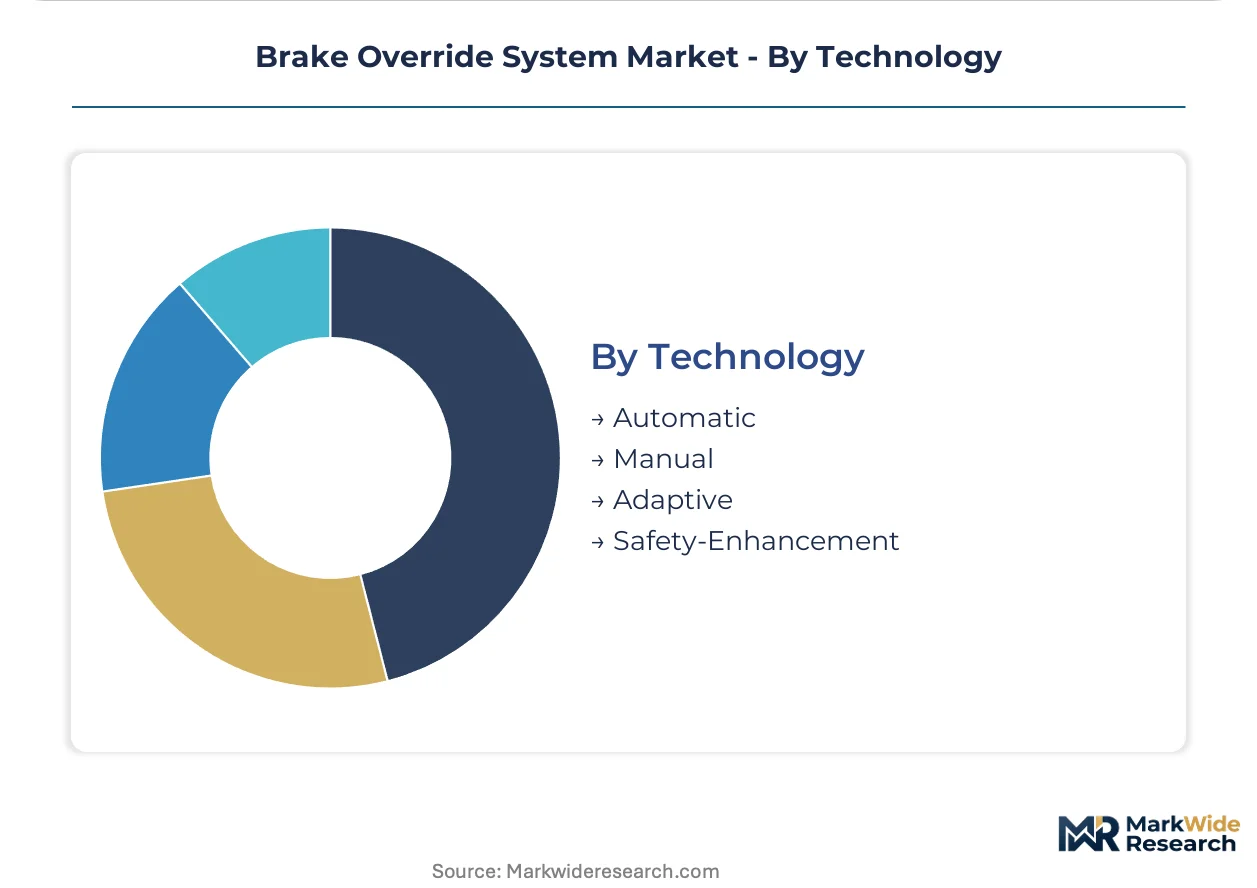
Technology:
Deterministic legacy architectures face displacement as adaptive inference engines attract engineering investment for predictive intervention.
- Adaptive:Machine learning inference engines converging throttle position sensors with real-time powertrain arbitration enable predictive pedal conflict detection. Japanese precision electronics clusters in Nagoya and Tokyo Bay lead calibration engineering for UN ECE and MLIT response latency compliance.
- Automatic:Reactive electronic priority logic triggers brake command override upon simultaneous pedal depression without predictive capability.
- Manual:Driver-selectable override modes retain limited fitment in specialty commercial applications.
- Safety-Enhancement:Supplementary override layers integrated with advanced driver-assistance system stacks.
Fastest technology transition: Adaptive. Broadest installed base: Automatic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the most concentrated brake override system demand corridor, with German automotive OEMs driving electronic module procurement through tightened UN ECE Regulation 13-H compliance mandates.
Germany
Volkswagen Group and BMW AG specification of sensor-fused architectures accelerates procurement cycles for Tier-1 suppliers. KBA type approval processes compress certification timelines for adaptive override protocols. The Baden-Württemberg automotive corridor concentrates Robert Bosch GmbH and Continental AG manufacturing scale for powertrain control module integration.
Japan
Toyota Motor Corporation's captive production of hybrid brake override systems sustains domestic market leadership through Aichi Prefecture manufacturing networks. MLIT domestic type approval enforces sub-50 millisecond response latency standards for new vehicle platforms. Nagoya's precision electronics cluster enables rapid calibration engineering for throttle position sensor fusion architectures.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate electronic brake override fitment across passenger vehicle platforms, with pedal entrapment directives accelerating module adoption. The Southeast manufacturing belt concentrates Toyota Motor Corporation's Kentucky production network for regional supply integration. Michigan-based OEM engineering centers specify adaptive override architectures for insurance liability reduction in commercial fleet segments.
China
MIIT and GB standards embed brake override functionality into battery-electric and hybrid powertrain architectures for new energy vehicle platforms. BYD and SAIC Motor procurement concentrates demand in the Yangtze River Delta manufacturing corridor. Shanghai and Shenzhen electronics clusters supply powertrain control module chips despite semiconductor input volatility from East Asian foundry concentration.
South Korea
Hyundai Motor Group directs brake override specification through captive supplier development programs for domestic and export platforms. MFDS automotive safety guidelines align with UN ECE protocols for electronic module certification. The Seoul Capital Area concentrates R&D investment in predictive pedal conflict detection integration with advanced driver-assistance system stacks.
Brake Override System Market Vendor Landscape
The competitive structure tilts toward vertically integrated mechatronics specialists with captive sensor production and in-house firmware calibration capability. Tier-1 supplier consolidation compresses margins for discrete component vendors lacking upstream integration. Three archetypes dominate: German automotive suppliers with end-to-end module certification, Japanese OEMs with captive hybrid system production, and diversified electronics conglomerates with semiconductor supply chain control. Competitive moves center on backward integration into sensor manufacturing and strategic partnerships for AI-driven override protocol development.
Among German-based suppliers, Robert Bosch GmbH and Continental AG occupy positions representing integrated mechatronics accountability, combining powertrain control engineering with firmware calibration under single-source supplier relationships. Toyota Motor Corporation exemplifies the OEM-captive archetype through in-house production of hybrid brake override systems across its Aichi and Kentucky manufacturing networks. These three entities anchor regional procurement patterns in their respective production corridors.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Nissan Motor Co. Ltd. |
| Honda Motor Co. Ltd. |
| Robert Bosch GmbH |
| BMW AG |
| Hyundai Motor Co. |
| Continental AG |
| Suzuki Motor Corporation |
| Renault |
| Others |
Supply Flow & Price Mechanics
UN ECE Regulation 13-H response latency mandates are compressing procurement cycles for German and Japanese OEMs, forcing Tier-1 suppliers to absorb sensor fusion engineering costs while electronic module pricing stratifies across certification tiers. This specification tightening concentrates purchasing power among vertically integrated suppliers capable of end-to-end firmware calibration, squeezing margins for discrete component vendors lacking captive sensor production.
Pricing Analysis
Value-based pricing anchored to insurance liability reduction outcomes dominates commercial vehicle fleet procurement, where predictive pedal conflict detection commands premiums over reactive automatic systems. Three-tier pricing structure across adaptive AI-driven, sensor-fused automatic, and legacy mechanical bypass levels reflects certification complexity and firmware customization depth. Cost compression in economy-tier mechanical systems is intensifying because emerging market commercial segments bypass electronic modules amid semiconductor supply volatility. Fleet operators exhibit lowest price sensitivity due to duty-cycle-specific safety mandates, while aftermarket retrofit channels face acute margin pressure from warranty exposure and calibration complexity.
Supply Chain Analysis
Japan's MLIT domestic content requirements for type approval are reshaping sourcing patterns, compelling Toyota Motor Corporation and Nissan Motor Co. Ltd. to prioritize Aichi and Kanagawa Prefecture manufacturing networks over offshore alternatives. Powertrain control module chip supply draws from Taiwan, South Korea, and China's Yangtze River Delta electronics clusters, creating single-source vulnerability when East Asian foundry capacity tightens. Semiconductor input volatility feeds from automotive-grade MCU concentration at TSMC and Samsung Foundry. Distribution runs through captive OEM supplier development programs rather than open component markets, with Tier-1 accountability consolidating under Robert Bosch GmbH and Continental AG in Germany's automotive corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
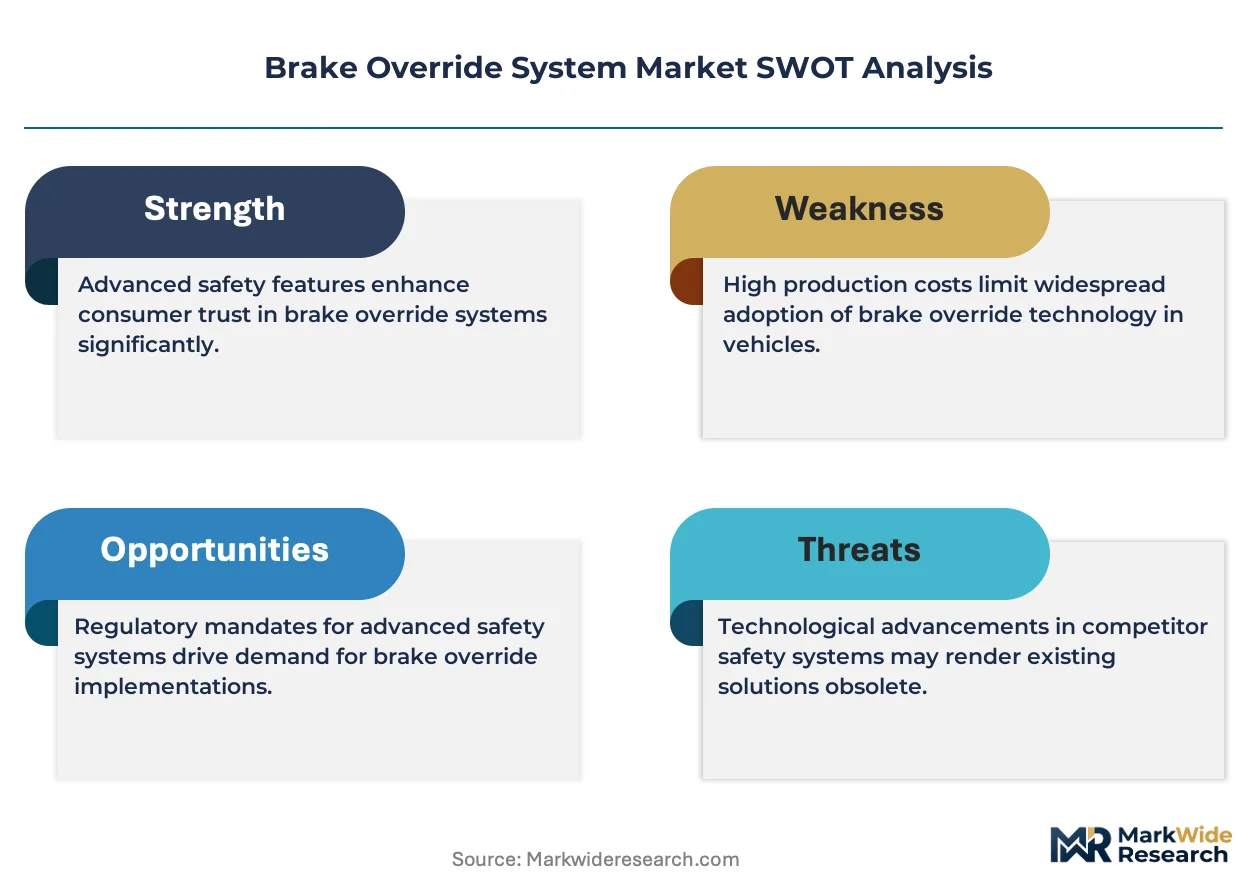
Semiconductor foundry capacity constraints for automotive-grade MCUs are propping electronic module pricing, creating a supply-constrained market where captive sensor production determines competitive viability.
For Market Incumbents: Deploy backward integration into throttle position sensor manufacturing to defend against margin erosion from adaptive AI-driven protocol competition. Consolidate firmware calibration capability under single-source accountability to meet KBA and MLIT compressed certification timelines. Capacity addition in Germany's Baden-Württemberg corridor anchors regional procurement relationships with Volkswagen Group and BMW AG. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched OEM supplier development barriers for commercial vehicle adaptive override systems. White-space concentrates in North American long-haul fleet procurement, where insurance liability reduction specifications outpace incumbent response cycles. Municipal bus mandates under Japan's MLIT type approval offer secondary penetration vectors with lower certification friction than passenger vehicle platforms. For Investors and Strategic Acquirers: The window for entry favors mechatronics specialists with captive sensor production and in-house powertrain control firmware capability. Long-term viability hinges on regulatory convergence between deterministic legacy architectures and adaptive AI-driven protocols across NHTSA, UN ECE, and MLIT approval pathways. Algorithmic transparency documentation requirements serve as the inflection indicator for engineering cycle compression and supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Investment | Enables sub-50 millisecond response latency compliance with UN ECE Regulation 13-H mandates. |
| Captive Throttle Position Sensor Production | Secures upstream component supply against East Asian foundry volatility for German Tier-1 suppliers. |
| Firmware-Defined Calibration Stack Development | Supports over-the-air threshold updates for adaptive AI-driven override protocols in premium segments. |
| Regional Manufacturing Footprint Expansion | Aligns with Toyota Motor Corporation's Kentucky production network for US Southeast supply integration. |
| Regulatory Certification Partnership | Accelerates MLIT type approval timelines for Japanese precision electronics cluster suppliers. |
Methodological Framework
Independent corroboration across Tier-1 supplier procurement leads, OEM platform engineering directors, and aftermarket distribution specialists underwrites the qualitative findings on brake override system specification trends. Secondary validation draws from NHTSA Federal Motor Vehicle Safety Standards filings, UN ECE Regulation 13-H certification databases, vehicle production registries, and semiconductor trade flow data. Bottom-up module shipment estimates triangulate against top-down OEM platform penetration assumptions across passenger and commercial vehicle segments.
Rate-of-change decomposition separates volume growth from value-per-unit expansion across electronic, mechanical, hybrid, and software product categories throughout the forecast period. Segmentation modeling incorporates vehicle class, propulsion architecture, response latency tier, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves calibrated to historical adoption patterns and mandated fitment phase-in schedules. Industry-specific inputs include powertrain control module chip supply lead times and KBA type approval cycle durations.
The model holds under stable UN ECE and NHTSA regulatory enforcement; deviation in algorithmic transparency mandate timing or East Asian foundry capacity allocation would shift module availability and pricing trajectories. Forecasts reflect documented assumptions regarding OEM captive production preferences and Tier-1 supplier consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market