
 Global Plasma Protease C1 Inhibitor Treatment Market | 2026-2036
Global Plasma Protease C1 Inhibitor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Protease C1 Inhibitor Treatment Market Intelligence
The U.S. FDA's Orphan Drug Act is decoupling the high costs of research and development from market exclusivity periods for rare disease therapies. This regulatory incentive encourages investment in niche indications like Hereditary Angioedema. CSL Behring leverages its extensive plasma collection infrastructure to sustain a leading position in plasma-derived products. Takeda Pharmaceutical Company competes with a portfolio that includes both prophylactic and acute treatments. Meanwhile, Pharming Group N.V. specializes in recombinant C1 inhibitor production, offering an alternative to human plasma-sourced therapies.
Plasma protease C1 inhibitor treatment involves administering a concentrated form of the C1-esterase inhibitor protein, a key regulator of the complement and contact systems. This therapy functions by inhibiting proteases like plasma kallikrein and factor XIIa, thereby preventing the uncontrolled swelling attacks characteristic of angioedema. While plasma-derived products remain a foundational treatment segment, recombinant C1 inhibitors represent a significant area of development, addressing concerns about supply consistency and viral transmission risk. Subcutaneous delivery modes are expanding the market beyond intravenous infusions, enabling prophylactic use in home care settings and improving patient autonomy.
Market access is governed by stringent approvals from regulators such as the U.S. FDA, the European Medicines Agency (EMA), and Japan's Pharmaceuticals and Medical Devices Agency (PMDA). These bodies enforce rigorous standards for clinical efficacy, safety, and manufacturing consistency under Good Manufacturing Practices (GMP). The complex approval pathways and high development costs create substantial barriers for new entrants. Future competitive advantage will hinge on the development of longer-acting formulations and successful navigation of reimbursement policies for novel delivery systems.
Market Dynamics
The structural shift toward patient autonomy, enabled by subcutaneous self-administration technologies, is fundamentally altering the treatment paradigm for angioedema. This move away from clinic-based infusions empowers patients, creating new demand patterns and requiring novel support and distribution infrastructures.
Growth Catalysts
- Favorable Regulatory Frameworks:The U.S. FDA's Orphan Drug Act and similar programs from the EMA provide market exclusivity and financial incentives, spurring investment into therapies for rare conditions like Hereditary Angioedema.
- Subcutaneous Delivery Systems:The development of self-administered subcutaneous formulations enhances patient quality of life and compliance, expanding the market for prophylactic treatment outside of hospital settings.
- Improved Diagnostic Rates:Increased physician and patient education is leading to earlier and more accurate diagnosis of HAE, particularly in developed economies, thereby expanding the addressable patient population.
Market Restraints
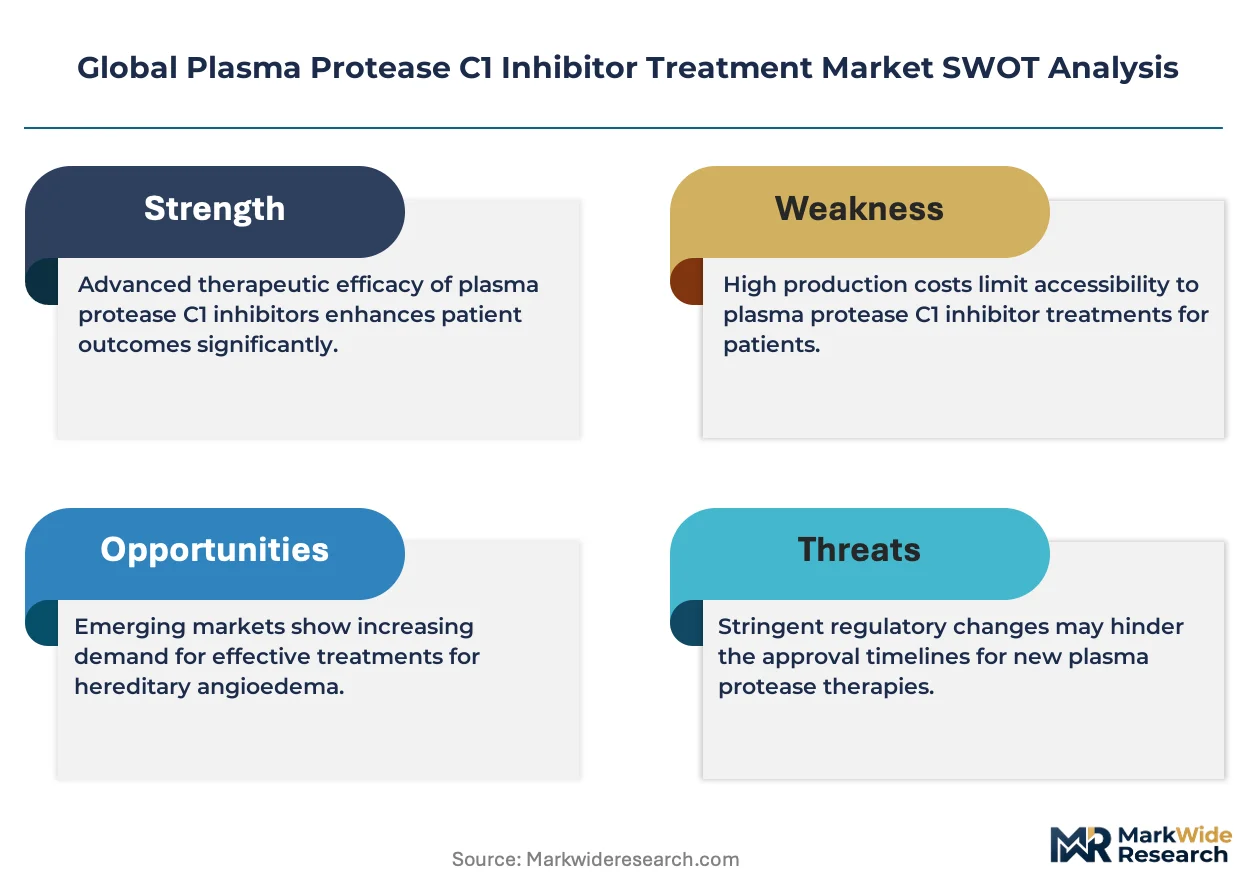
- High Production Costs:The intricate processes of plasma fractionation for plasma-derived products and bioreactor cultivation for recombinant versions result in a high cost of goods, limiting affordability and access.
- Plasma Supply Dependency:The market for plasma-derived inhibitors is vulnerable to fluctuations in the supply and cost of source plasma, a dependency concentrated in a few large-scale collection organizations.
- Stringent Regulatory Hurdles:New entrants face substantial barriers due to the lengthy and expensive clinical trials required for approval by bodies like the FDA, EMA, and PMDA, which demand rigorous proof of safety and efficacy.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in markets outside the United States with developing healthcare reimbursement systems and increasing diagnostic capabilities, such as Brazil and South Korea.
- Longer-Acting Formulations:Developing C1 inhibitors with extended half-lives would reduce dosing frequency for prophylactic users, representing a major competitive advantage and improvement in patient convenience.
- Indication Expansion:Research into the efficacy of C1 inhibitors for other complement-mediated conditions, such as sepsis or antibody-mediated rejection, could open substantial new therapeutic areas beyond angioedema.
Industry Challenges
- Reimbursement Navigation:Securing favorable reimbursement status for novel, higher-cost subcutaneous and long-acting formulations from public and private payers is a complex operational challenge.
- Cold Chain Logistics:The transition to home-based care requires the establishment of robust and reliable cold chain distribution networks managed by specialty pharmacies to ensure product integrity to the patient's door.
- Manufacturing Compliance:Adhering to evolving Good Manufacturing Practices (GMP) across international jurisdictions requires continuous investment in quality control systems and process validation, posing an ongoing operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Protease C1 Inhibitor Treatment Market |
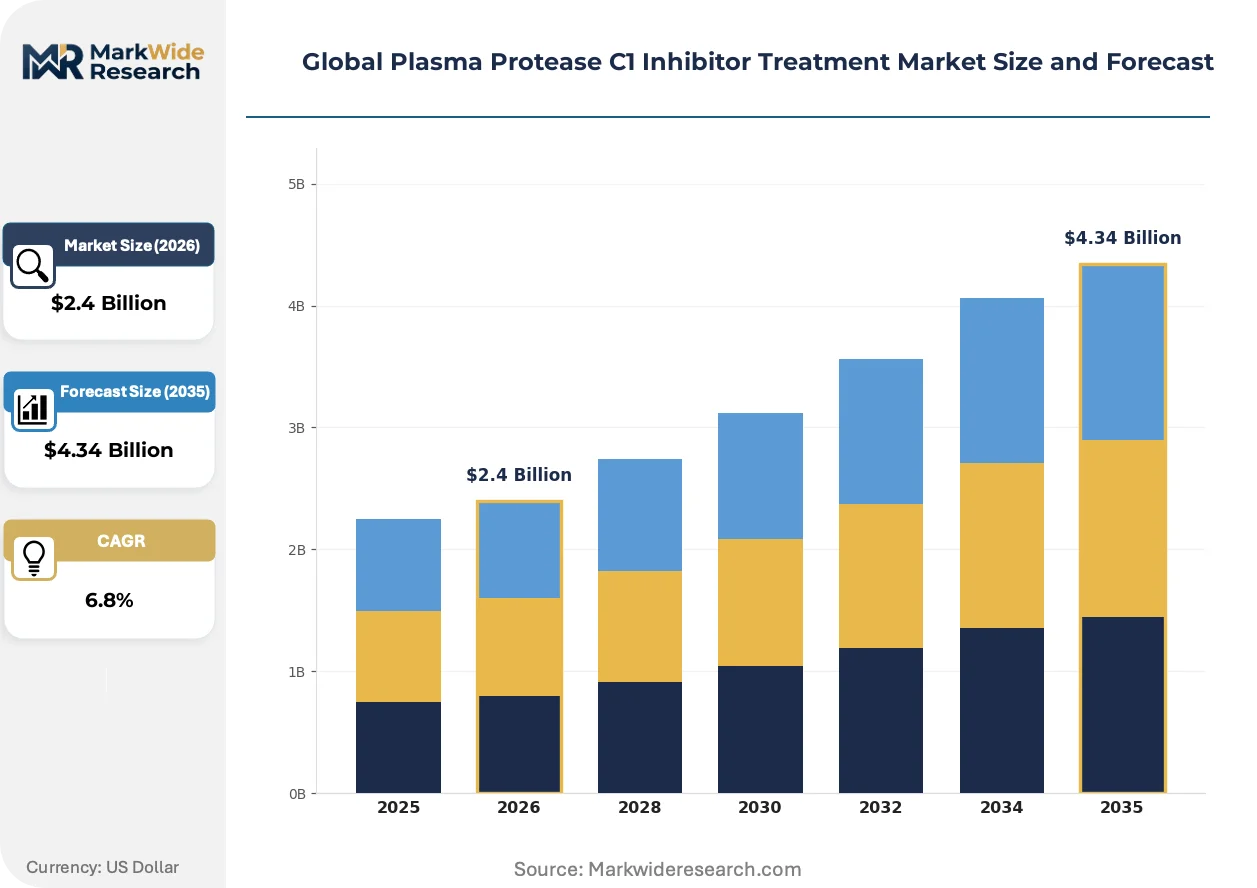
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C1 Inhibitor Concentrate, Recombinant C1 Inhibitor, Plasma-derived Product, Others Application: Hereditary Angioedema, Acquired Angioedema, Surgical Prophylaxis, Trauma Management Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Specialty Clinics, Home Care, Research Institutions |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company, Pharming Group N.V., BioCryst Pharmaceuticals, KalVista Pharmaceuticals, Sanquin, AbbVie, Alexion, Argenx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Protease C1 Inhibitor Treatment Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot from reactive, acute care toward proactive, patient-managed prophylactic therapy. This transition is driven by technological advances in drug formulation and delivery that prioritize patient autonomy and long-term disease management over episodic intervention.
Recombinant production technology provides a method for creating C1 inhibitors without reliance on human plasma. Physicians and patients concerned with the theoretical risk of pathogen transmission and plasma supply volatility are increasingly receptive to these alternatives. Consequently, the development of recombinant proteins is overtaking plasma sourcing as the primary focus for therapeutic innovation, aiming to standardize dose consistency and secure the supply chain.
Regulatory incentives like the European Medicines Agency's (EMA) orphan medicinal product designation are critical. This framework grants benefits such as protocol assistance and a decade of market exclusivity, de-risking investment in therapies for rare diseases. The HAE treatment segment in the European Union is most affected, as these incentives encourage biopharmaceutical firms to pursue clinical development within the region.
A fundamental behavioral shift is occurring as treatment moves from on-demand infusions in a clinic to scheduled, prophylactic self-injection at home. This change diminishes the role of the traditional hospital infusion center in chronic HAE management, elevating specialty pharmacies that provide distribution, training, and support services. This patient-centric model is most pronounced in the United States, where reimbursement structures and patient advocacy support greater autonomy.
Global Plasma Protease C1 Inhibitor Treatment Market Segmentation
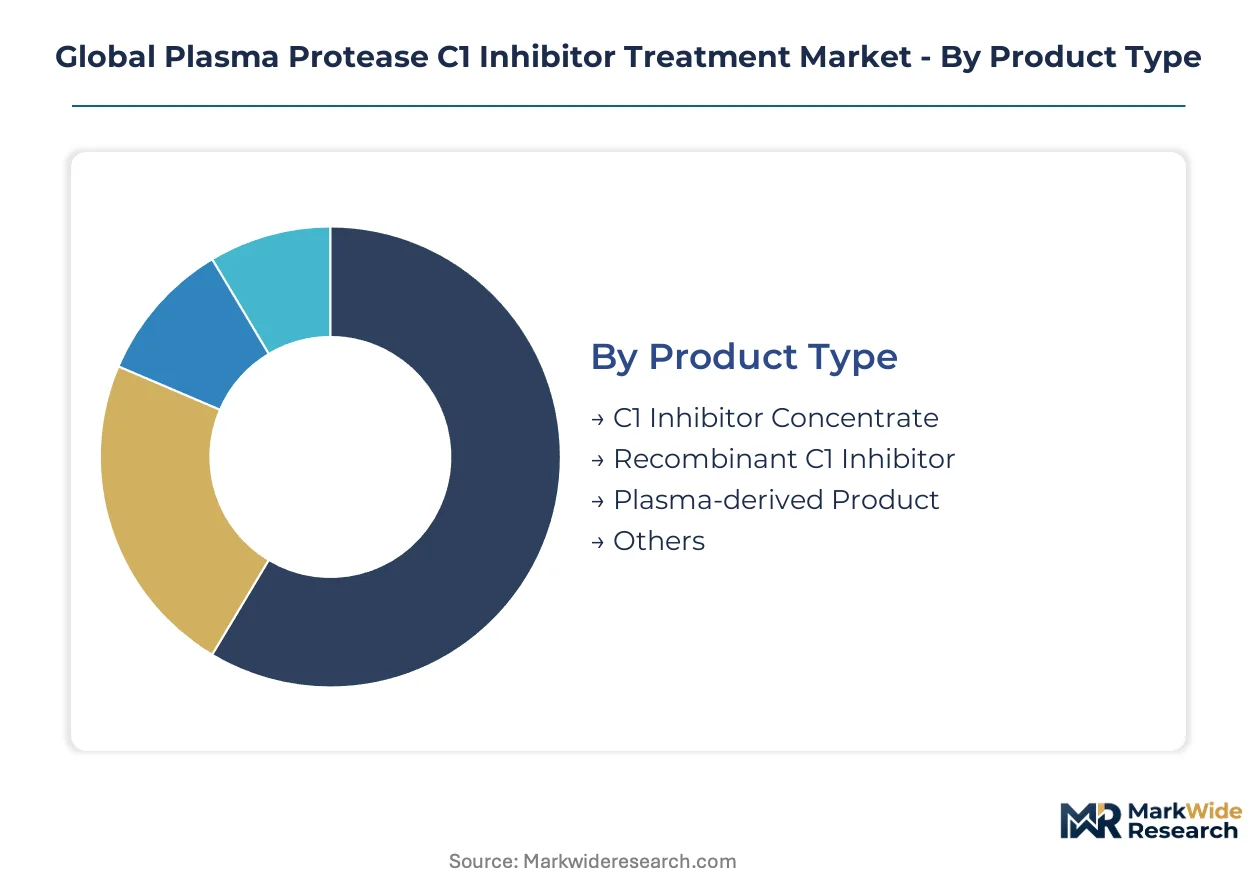
The Plasma Protease C1 Inhibitor Treatment market exhibits distinct segments across product types, applications, delivery modes, and end users. Understanding these divisions is crucial for analyzing market dynamics, identifying growth opportunities, and tailoring strategic approaches for different therapeutic needs.
Product Type:
Product type segmentation highlights the fundamental differences in manufacturing origin and therapeutic composition, influencing market adoption and supply chain resilience.
- C1 Inhibitor Concentrate:A concentrated form of the C1-esterase inhibitor protein derived from human plasma, used to replenish deficient levels in patients. Demand for this foundational product remains consistent in established markets for acute angioedema management.
- Recombinant C1 Inhibitor:Produced through advanced biotechnology without reliance on human plasma, offering a consistent and potentially safer alternative to plasma-derived products. Demand is gaining traction in developed markets like the United States due to concerns over viral transmission risk and supply consistency.
- Plasma-derived Product:Therapeutic agents extracted and purified from human blood plasma, containing the active C1-esterase inhibitor protein. This product type maintains a foundational role in angioedema treatment globally, particularly where established infrastructure for plasma collection exists.
- Others:This category encompasses investigational products, synthetic analogs, and alternative C1 inhibitor therapies under development for various indications.
Volume placements concentrate in Plasma-derived Product; the faster expansion belongs to Recombinant C1 Inhibitor.
Application:
Application analysis reveals the distinct therapeutic areas where C1 inhibitor treatments provide critical intervention, guiding research and development investments.
- Hereditary Angioedema:A rare genetic disorder characterized by recurrent episodes of severe swelling, where C1 inhibitors prevent or treat acute attacks. Demand is heavily concentrated in the United States and European Union, driven by increased diagnostic rates and favorable orphan drug designations.
- Acquired Angioedema:A rare condition similar to HAE but typically affecting older individuals, often associated with lymphoproliferative disorders.
- Surgical Prophylaxis:Administration of C1 inhibitors before surgical procedures or dental work to prevent angioedema attacks in susceptible patients. Demand is crucial in hospital settings across developed economies to minimize perioperative complications for high-risk individuals.
- Trauma Management:Investigational use of C1 inhibitors to mitigate inflammation and vascular leakage in severe traumatic injuries.
Hereditary Angioedema represents the largest therapeutic segment; Surgical Prophylaxis is gaining share fastest.
Delivery Mode:
Delivery mode differentiation highlights the evolving landscape of patient administration, impacting convenience, compliance, and treatment settings.
- Intravenous:The traditional administration method requiring infusion by a healthcare professional, primarily for acute attacks or initial prophylactic loading doses. Demand remains standard in hospital and clinic settings, especially for rapid symptom control in critical situations.
- Subcutaneous:Self-administered injection under the skin, enabling home-based prophylactic treatment and improving patient quality of life. Demand is experiencing significant expansion in regions like the United States due to patient preference and pharmaceutical innovation.
- Intramuscular:A delivery method involving injection into muscle tissue, less common for C1 inhibitors but explored for specific formulations.
- Oral:Represents an aspirational delivery route for C1 inhibitors, offering maximum patient convenience but facing significant formulation challenges.
Intravenous administration currently dominates volume; subcutaneous delivery modes show the steepest expansion trajectory.
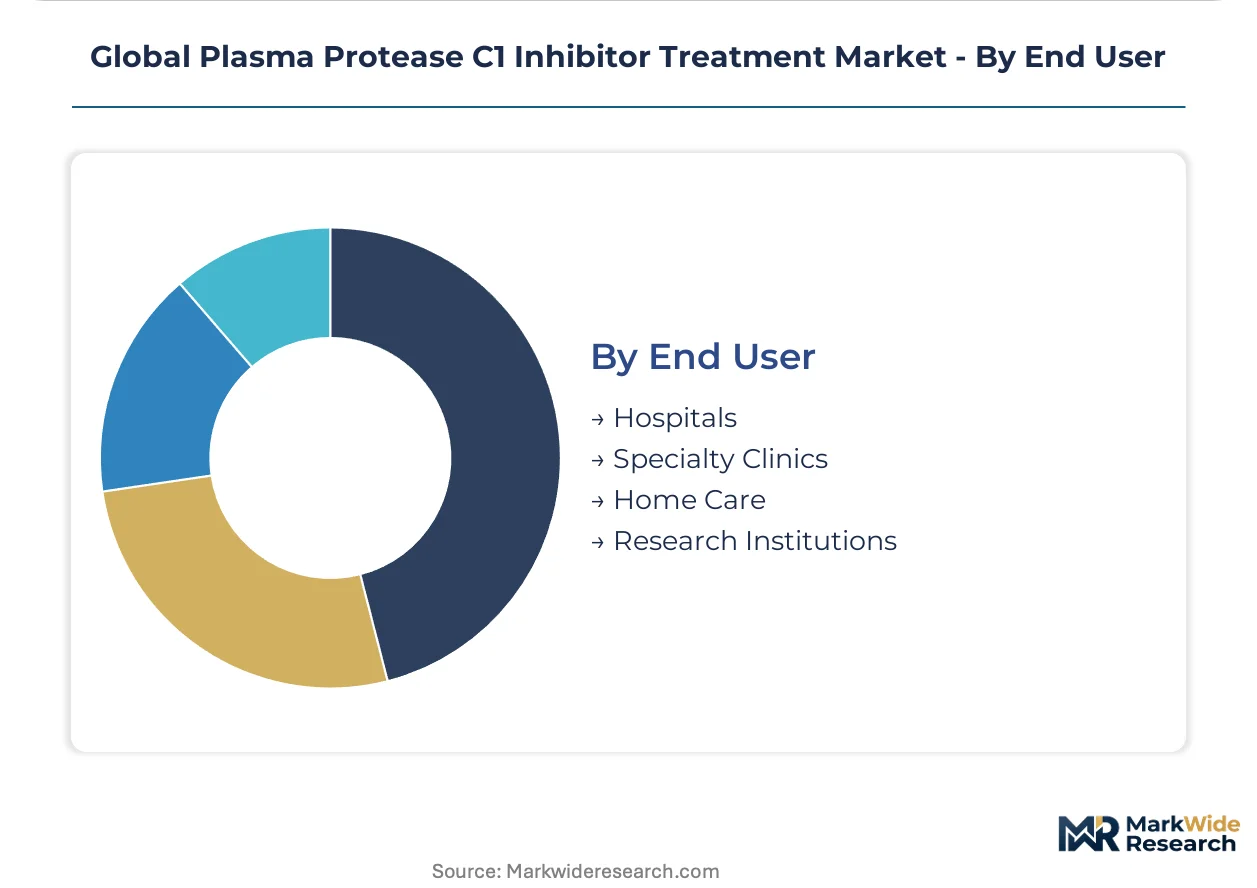
End User:
End-user segments illustrate where C1 inhibitor treatments are primarily dispensed and administered, reflecting the diverse healthcare infrastructure.
- Hospitals:Major sites for acute angioedema treatment, surgical prophylaxis, and initial diagnosis, equipped with necessary medical infrastructure. Demand is consistently high across all developed and developing healthcare systems for emergency and inpatient care.
- Specialty Clinics:Outpatient facilities focusing on specific conditions like angioedema, providing diagnosis, long-term management, and infusions.
- Home Care:A growing segment driven by subcutaneous self-administration, allowing patients to manage prophylactic treatment independently outside clinical settings. Demand is expanding rapidly in the United States and parts of Europe, supported by specialty pharmacies and patient advocacy.
- Research Institutions:Organizations conducting clinical trials and basic science research into C1 inhibitors, exploring new indications and formulations.
Hospitals retain the largest share of C1 inhibitor utilization; Home Care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for plasma protease C1 inhibitor treatment concentrates heavily in the United States, which exhibits the largest patient population and highest treatment expenditures. This global market sees significant regional variations in diagnostic rates, regulatory frameworks, and healthcare infrastructure. Developed economies with established reimbursement systems drive the majority of current market value.
United States
The United States drives demand through its large hereditary angioedema patient population and high per-patient treatment expenditures. The U.S. FDA's Orphan Drug Act provides significant incentives, encouraging biopharmaceutical investment in rare disease therapies. Major biotech hubs like Boston and San Francisco continue to lead in C1 inhibitor research and development.
Germany
Germany represents a substantial European market for C1 inhibitor treatments, supported by a robust healthcare system and increasing HAE diagnostic rates. The European Medicines Agency (EMA) orphan medicinal product designation offers market exclusivity and development assistance. Pharmaceutical clusters in regions like Frankfurt and Munich contribute to both manufacturing and clinical research.
Japan
Japan's demand for C1 inhibitor treatment stems from its advanced medical infrastructure and a growing focus on rare disease management. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces stringent approval standards for new therapies, ensuring product safety and efficacy. Tokyo's biomedical research parks are central to innovation in this therapeutic area.
South Korea
South Korea offers a significant growth opportunity, characterized by its developing healthcare reimbursement systems and increasing diagnostic capabilities. The Ministry of Food and Drug Safety (MFDS) oversees regulatory approvals, supporting the introduction of novel treatments. Seoul's vibrant biotech industry fosters local development and adoption of advanced C1 inhibitor therapies.
Brazil
Brazil presents an expanding market, driven by improving healthcare access and rising awareness of hereditary angioedema among medical professionals. ANVISA, the national health surveillance agency, manages drug approvals and market entry for C1 inhibitor products. São Paulo acts as a key distribution hub for pharmaceutical products throughout Latin America.
Global Plasma Protease C1 Inhibitor Treatment Market Key Industry Players
United States producers anchor one tier of the market, focusing on innovation and patient-centric delivery, while European specialists hold strong positions in established plasma-derived product segments. The market structure exhibits a mix of large pharmaceutical companies and specialized biotech firms. Strategic archetypes include plasma-derived product leaders, recombinant C1 inhibitor innovators, and broader rare disease portfolio holders. Companies primarily engage in research and development for longer-acting formulations and strategic partnerships to expand geographic reach.
Within the plasma-derived product segment, CSL Behring exemplifies a vertically integrated player leveraging extensive plasma collection infrastructure. Takeda Pharmaceutical Company, a global pharmaceutical entity, occupies a position with a diversified portfolio spanning both prophylactic and acute treatments. Pharming Group N.V. represents a specialist in recombinant C1 inhibitor production, offering alternatives to human plasma-sourced therapies.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company |
| Pharming Group N.V. |
| BioCryst Pharmaceuticals |
| KalVista Pharmaceuticals |
| Sanquin |
| AbbVie |
| Alexion |
| Argenx |
| Others |
Cost & Logistics Intelligence
Hospital systems represent a concentrated buyer archetype, influencing the contract-based pricing models prevalent for C1 inhibitor treatments. This concentration shapes purchasing power and drives negotiations for volume-based discounts.
Pricing Analysis
Lead-time-driven pricing offers premium rates for immediate supply of C1 inhibitor concentrates, reflecting urgent clinical need. The dominant pricing structure involves contract-based long-term agreements between manufacturers and healthcare providers or national health systems. Price differentiation stems from product origin, distinguishing plasma-derived C1 inhibitors from recombinant versions, and the level of patient support services offered. Pricing pressure originates from public and private payers seeking cost containment for high-value therapies. Public reimbursement bodies demonstrate the highest price sensitivity, while patients typically face lower direct costs due to comprehensive insurance coverage.
Supply Chain Analysis
Certification and qualification gating by regulators like the U.S. FDA and the EMA are critical entry barriers for C1 inhibitor supply. Geographic supply concentration for human plasma collection and processing centers in the United States, Germany, and Japan underpins the market. Raw material dependencies include source plasma for traditional products and specialized bioreactor components for recombinant versions. Single-source vulnerability for plasma supply poses a structural risk. Downstream distribution runs through highly specialized cold chain logistics networks managed by specialty pharmacies and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasma protease C1 inhibitor market is undergoing a technology-transition phase, with subcutaneous self-administration options replacing traditional intravenous infusions as the preferred delivery method.
For Market Incumbents: Lock in long-term supply agreements for source plasma to mitigate raw material volatility, leveraging existing collection infrastructure. Invest significantly in research and development for longer-acting, next-generation recombinant C1 inhibitors to counter emerging competitive threats from novel drug platforms. Expand partnerships with specialty pharmacies to enhance channel control for home-based care. Reinforce market presence through patient education programs, ensuring continued brand loyalty amidst evolving treatment landscapes.
For New Entrants and Emerging Players: Recombinant C1 inhibitor technology provides a technology-first wedge into the market, bypassing plasma supply constraints. Target underpenetrated segments like pediatric hereditary angioedema or new indications such as sepsis, where C1 inhibitors show promise. South Korea and Brazil offer penetrable geographies with developing reimbursement systems and rising diagnostic rates. A direct-to-patient support model, emphasizing convenience and adherence for subcutaneous formulations, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized biotech firms in the United States with strong intellectual property in recombinant or gene therapy platforms. The long-term viability of rare disease therapies remains robust, supported by orphan drug incentives and consistent patient demand. Acquisition targets should prioritize companies with late-stage clinical assets or novel delivery technologies. Successful Phase 3 trial readouts for oral C1 inhibitor formulations represent a critical signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Recombinant C1 Inhibitor R&D | Secures future supply independence and addresses concerns about plasma-derived product risks. |
| Expand Subcutaneous Delivery Formulations | Enhances patient quality of life and expands prophylactic treatment access in home settings. |
| Strengthen Cold Chain Logistics Partnerships | Ensures product integrity and reliable home delivery for temperature-sensitive C1 inhibitor therapies. |
| Pursue Indication Expansion for C1 Inhibitors | Diversifies revenue streams beyond angioedema and addresses unmet needs in other complement-mediated conditions. |
| Engage in Value-Based Reimbursement Negotiations | Aligns treatment costs with patient outcomes, facilitating broader market access for high-cost therapies. |
Research Approach
Document review covered U.S. FDA filings, EMA submissions, and clinical trial registries, complemented by interviews with regulatory affairs leads, HAE specialists, patient advocates, and hospital pharmacists. This approach combined primary insights with extensive secondary validation, utilizing both bottom-up and top-down triangulation to ensure data accuracy.
Historical market data was cross-referenced with expert panel input to construct the forecast framework across the projection horizon. The analytical model segmented the market by product types, applications, delivery modes, end-users, and regional regulatory frameworks. Compound annual growth rates were derived from a blend of historical trends and consensus from industry experts, incorporating specific forecast inputs such as HAE diagnostic rates and orphan drug designations.
Several conditions sit outside the modeled scope, including unforeseen macroeconomic shocks or rapid advancements in gene therapy that could fundamentally alter the treatment landscape. Forecasts reflect assumptions documented through this rigorous process. A model refresh is warranted upon material change in global reimbursement policies or unexpected clinical trial outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market