
 Rhabdomyosarcoma Treatment Market | 2026-2036
Rhabdomyosarcoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rhabdomyosarcoma Treatment Market Analysis
Pediatric oncologist workforce shortages in rural and semi-urban areas is reorganizing where treatment delivery concentrates, pushing families toward major metropolitan cancer centers. Pfizer Inc. leverages its established pediatric oncology infrastructure to sustain clinical trial access across North American referral networks. Novartis AG anchors its position through targeted therapy development programs focused on sarcoma molecular subtypes. Bristol Myers Squibb Company differentiates via immuno-oncology platforms that compete for investigator-initiated study partnerships.
Rhabdomyosarcoma treatment encompasses multimodal therapeutic intervention against malignant skeletal muscle-origin tumors, combining cytotoxic agents with surgical resection margins and precision radiation dosing calibrated to tumor histology and staging. Chemotherapy remains the backbone modality, with vincristine-dactinomycin-cyclophosphamide protocols serving as first-line standards, while targeted therapy segments gain traction where receptor tyrosine kinase pathways show actionable alterations. Pediatric hospitals capture the dominant share of procedure volume given case concentration requirements and multidisciplinary care complexity, though home care settings expand for post-chemotherapy monitoring. Immunotherapy within medication type segments attracts development investment as biologic agents demonstrate checkpoint inhibitor potential in relapsed populations.
FDA orphan drug designations and EMA pediatric investigation plans shape development timelines and exclusivity incentives for sponsors addressing this indication. The EU's Clinical Trials Regulation standardizes pediatric study requirements across member states, while WHO essential medicines list inclusion pressures pricing accessibility in lower-income health systems. Stakeholders must monitor biomarker-driven trial eligibility criteria that segment addressable populations and reshape competitive dynamics between cytotoxic and precision medicine approaches.
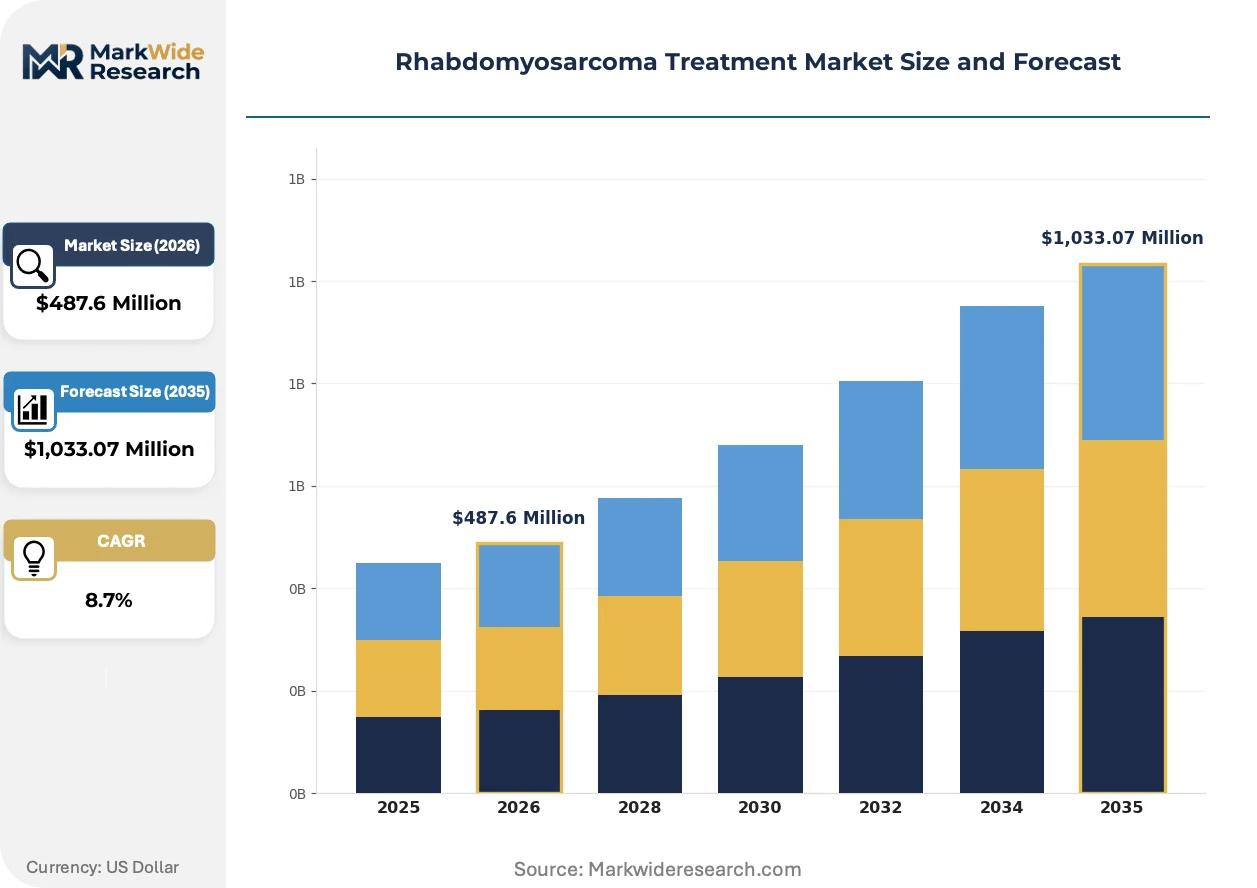
Market Dynamics
Pediatric oncologist workforce shortages in rural corridors are forcing treatment delivery to reorganize around metropolitan academic medical centers, consolidating procedure volume and reshaping referral network economics.
Growth Catalysts
- FDA Rare Pediatric Disease Priority Review Voucher program:This incentive mechanism accelerates sponsor timelines and attracts development investment into rhabdomyosarcoma indications where commercial returns alone would be insufficient.
- Targeted therapy pipelines:Receptor tyrosine kinase inhibitors are expanding addressable populations in fusion-positive molecular subtypes, creating new enrollment channels for precision oncology trials.
- Metropolitan cluster concentration:Families in the United States are migrating toward major cancer centers in Boston, Houston, and Memphis, concentrating procedure volume and enabling multidisciplinary care scale.
Market Restraints
- Platinum-based chemotherapy input costs:Vincristine and dactinomycin supply volatility creates protocol interruption risk and margin pressure for hospital pharmacy operations.
- Single-source radiation equipment dependency:Proton therapy capacity concentrates at fewer than fifty North American facilities, creating geographic access barriers for precision dosing requirements.
- EMA pediatric investigation plan complexity:Multi-year development timelines and stringent juvenile toxicology requirements extend sponsor burn rates before commercial eligibility.
Strategic Opportunities
- Home care monitoring infrastructure:Post-chemotherapy surveillance is shifting toward ambulatory settings, creating channel expansion potential for wearable toxicity assessment devices.
- Biomarker-driven trial segmentation:PAX-FOXO1 fusion status is enabling enrichment strategies that compress enrollment timelines and improve signal detection in relapsed cohorts.
- Checkpoint inhibitor convergence:Combination protocols pairing PD-1 blockade with conventional cytotoxics are opening investigator-initiated study partnerships at underutilized sarcoma programs.
Industry Challenges
- Pediatric oncology nursing specialization gaps:Chemotherapy administration certification requirements outpace training program throughput, constraining bed expansion at high-volume centers.
- Multidisciplinary care coordination complexity:Surgical resection margin planning, radiation dosing, and systemic therapy sequencing demand integrated scheduling systems that legacy hospital IT infrastructure cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhabdomyosarcoma Treatment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Radiation Therapy, Targeted Therapy End User: Pediatric Hospitals, Oncology Clinics, Research Institutions, Home Care Settings Treatment Stage: First-Line Treatment, Second-Line Treatment, Adjuvant Treatment, Palliative Care Medication Type: Chemotherapeutic Agents, Hormone Therapy, Immunotherapy, Biologic Agents |
| Companies Covered | Boehringer Ingelheim International GmbH, Celgene Corporation, Pfizer Inc., MacroGenics, Inc., Eisai Co., Ltd., Bristol Myers Squibb Company, Eli Lilly & Company, Exelixis, Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhabdomyosarcoma Treatment Market Emerging Trajectories
Next-generation sequencing platforms are compressing molecular diagnostic timelines from weeks to days, enabling real-time treatment protocol adjustments that reshape competitive positioning between cytotoxic and precision medicine approaches.
Chimeric antigen receptor T-cell constructs targeting GD2 and B7-H3 surface antigens are supplanting salvage chemotherapy as the preferred investigational pathway for relapsed rhabdomyosarcoma. Children's Oncology Group sites are prioritizing CAR-T enrollment over cytotoxic rechallenge protocols. This shift is compressing addressable populations for late-stage chemotherapy assets while expanding biologics manufacturing requirements at academic cell therapy facilities.
The EU's Clinical Trials Regulation standardized pediatric study requirements across member states, eliminating country-specific submission duplications that previously fragmented European enrollment. Sponsors now file single protocols covering Germany, France, and Italy through centralized EMA procedures. This harmonization is accelerating patient access timelines in molecularly defined subpopulations where European sites previously lagged North American activation.
Caregiver mobility patterns are restructuring treatment access economics. Families in the United States are relocating temporarily to metropolitan corridors with embedded sarcoma programs, abandoning community oncology relationships for centralized pediatric hospital networks. This geographic arbitrage concentrates procedure revenue at flagship institutions while depleting case volume at regional children's hospitals lacking dedicated sarcoma infrastructure.
Rhabdomyosarcoma Treatment Market Segmentation
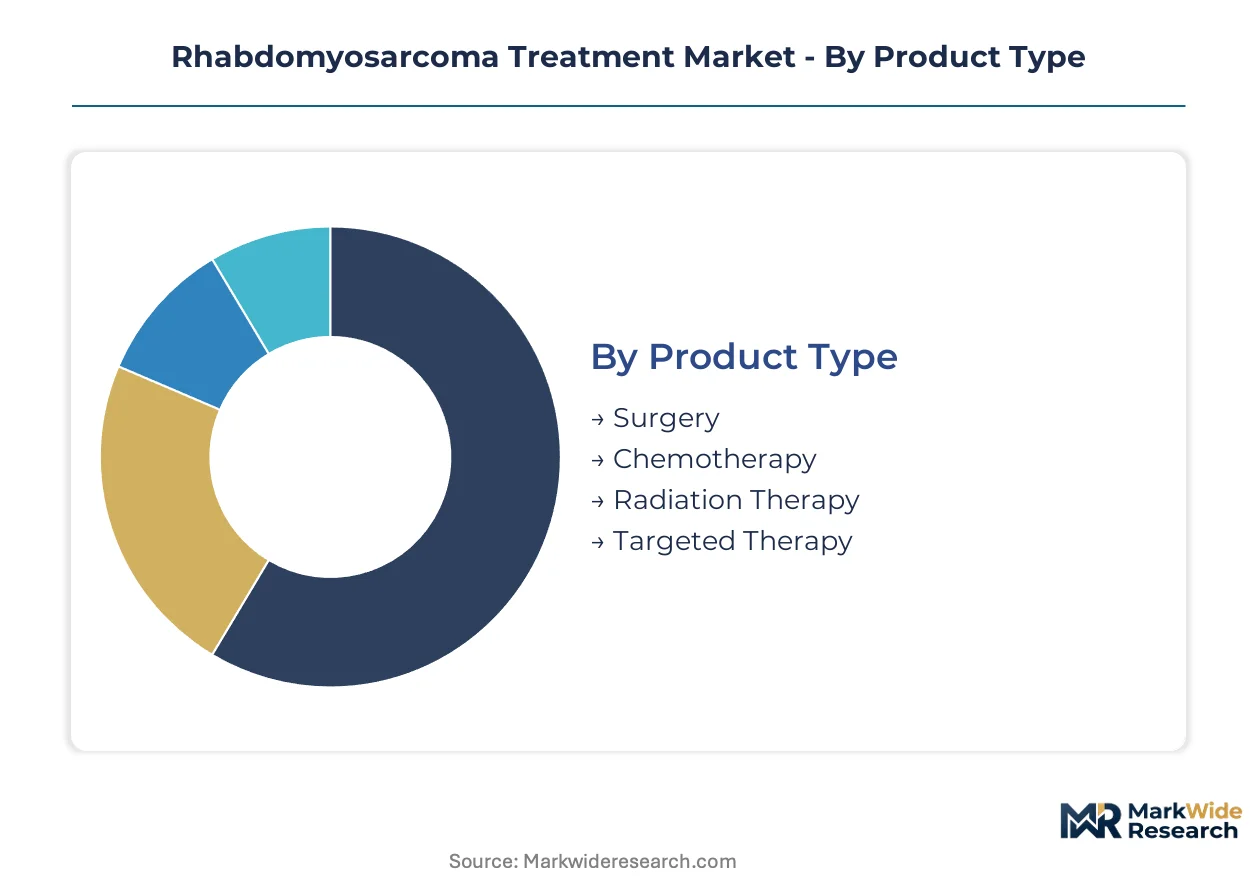
Treatment modality selection in rhabdomyosarcoma hinges on molecular subtype classification and staging protocols, with reimbursement pathways diverging sharply between curative-intent and salvage interventions. Segmentation reveals how capital-intensive radiation infrastructure and biologics manufacturing capacity reshape competitive boundaries across delivery settings.
Product Type:
Margin concentration pools in multimodal combination protocols where surgical resection margins, precision radiation dosing, and systemic therapy sequencing generate bundled reimbursement premiums.
- Chemotherapy:Vincristine-dactinomycin-cyclophosphamide protocols remain the backbone modality, with supply chain volatility for platinum-based inputs creating intermittent protocol interruptions. Demand concentrates at pediatric hospitals in Boston, Houston, and Memphis where multidisciplinary care teams manage toxicity monitoring at scale.
- Radiation Therapy:Proton therapy capacity delivers the highest per-procedure margins, though fewer than fifty North American facilities possess the equipment required for precision pediatric dosing. Families relocate temporarily to metropolitan corridors with embedded proton centers, concentrating revenue at flagship academic institutions.
- Surgery:Resection margin planning demands integrated scheduling with systemic therapy sequencing, limiting viable settings to high-volume sarcoma programs with dedicated pediatric surgical oncology teams.
- Targeted Therapy:Receptor tyrosine kinase inhibitors address fusion-positive molecular subtypes, with PAX-FOXO1 status determining trial eligibility and payer coverage pathways.
The dominant share belongs to Chemotherapy, while Targeted Therapy is closing the gap fastest as biomarker-driven enrollment channels expand.
End User:
Volume distribution tracks caregiver mobility patterns, with temporary family relocation to metropolitan corridors reshaping where procedure revenue concentrates.
- Pediatric Hospitals:Academic medical centers with dedicated sarcoma programs capture the dominant procedure volume, driven by case concentration requirements and multidisciplinary care complexity. St. Jude Children's Research Hospital, Dana-Farber/Boston Children's, and MD Anderson anchor referral networks that draw families from rural catchment areas.
- Home Care Settings:Post-chemotherapy surveillance is shifting toward ambulatory monitoring, with wearable toxicity assessment devices creating channel expansion potential. This segment is expanding most quickly as families seek to reduce temporary relocation burdens.
- Oncology Clinics:Community-based delivery remains limited by chemotherapy administration certification gaps and the absence of integrated surgical and radiation planning capabilities.
- Research Institutions:Children's Oncology Group sites prioritize CAR-T enrollment over cytotoxic rechallenge, compressing addressable populations for late-stage chemotherapy assets while expanding biologics manufacturing requirements.
Pediatric Hospitals command the majority of curative-intent procedures, though Home Care Settings are gaining share fastest in the surveillance and supportive care phases.
Treatment Stage:
Reimbursement intensity peaks in first-line protocols where curative intent justifies aggressive multimodal intervention, while salvage therapy segments face compressed margins and experimental coverage hurdles.
- First-Line Treatment:Standard-risk and high-risk stratification protocols drive the majority of commercial pharmaceutical utilization, with FDA orphan drug designations accelerating sponsor timelines for agents entering this segment.
- Second-Line Treatment:Relapsed populations shift toward investigational pathways, with checkpoint inhibitor combinations and CAR-T constructs supplanting cytotoxic rechallenge at major academic centers.
- Adjuvant Treatment:Consolidation therapy following surgical resection maintains chemotherapy backbone utilization, though duration protocols vary by histologic subtype and response assessment.
- Palliative Care:Symptom-focused interventions concentrate in hospice-eligible populations, with limited pharmaceutical innovation targeting this segment due to commercial return constraints.
First-Line Treatment retains the largest share of pharmaceutical revenue, while Second-Line Treatment is expanding fastest as relapsed cohorts access precision oncology trials.
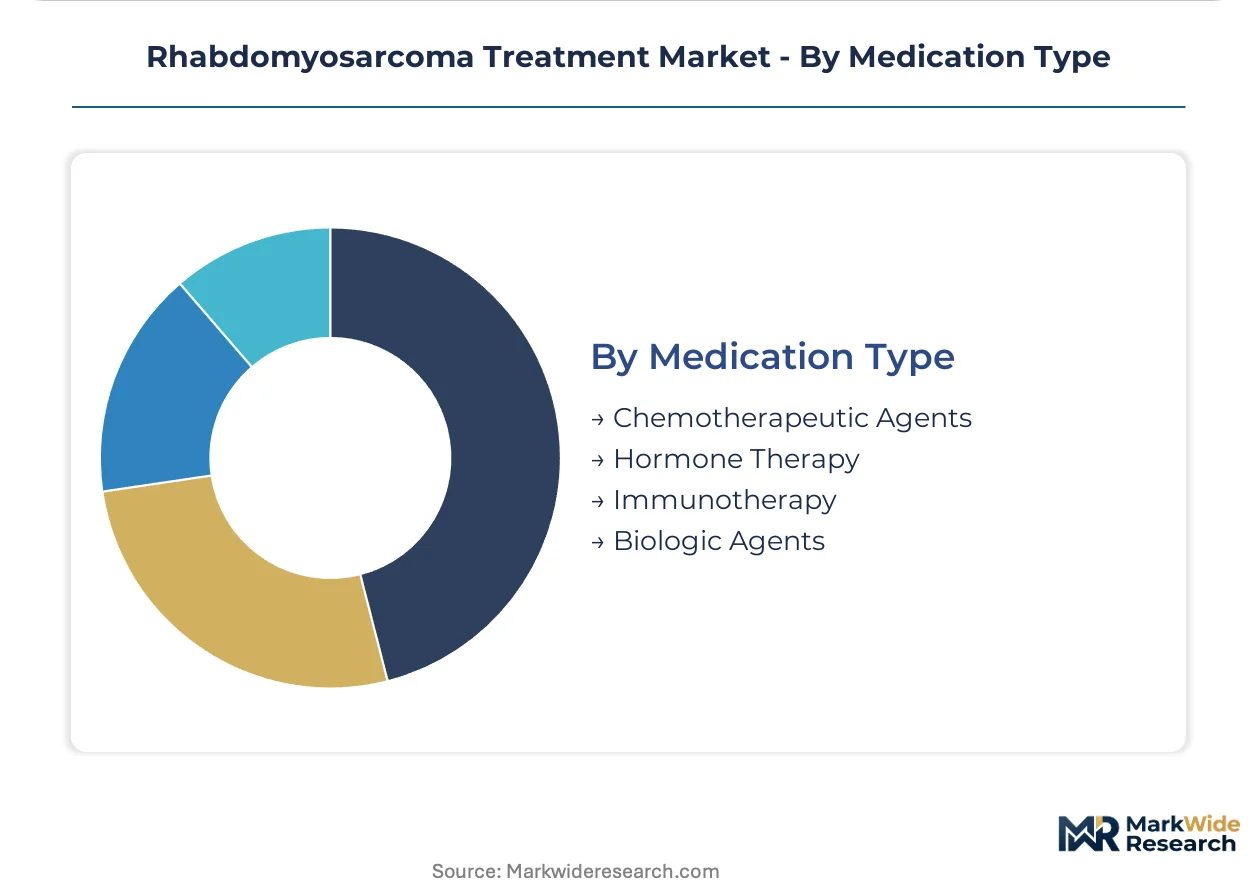
Medication Type:
Development investment migrates toward biologics as checkpoint inhibitors and cell therapy constructs demonstrate signal in relapsed populations, displacing cytotoxic dominance in sponsor pipelines.
- Chemotherapeutic Agents:Vincristine, dactinomycin, cyclophosphamide, and ifosfamide-etoposide combinations constitute the established standard of care, with supply volatility creating intermittent shortage risks.
- Immunotherapy:PD-1 blockade paired with conventional cytotoxics is opening investigator-initiated study partnerships at underutilized sarcoma programs, attracting development investment from Bristol Myers Squibb and competitors.
- Biologic Agents:GD2 and B7-H3 targeting CAR-T constructs represent the preferred investigational pathway for relapsed disease, with manufacturing requirements expanding at academic cell therapy facilities.
- Hormone Therapy:Limited applicability in this indication restricts segment scale, with minimal pipeline activity relative to other pediatric solid tumors.
Chemotherapeutic Agents maintain the dominant position by volume, though Immunotherapy is climbing the fastest as biologics manufacturing capacity scales at major treatment centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designations anchor development timelines in the United States, where referral networks concentrate pediatric sarcoma expertise. EMA pediatric investigation plans shape European enrollment strategies. WHO essential medicines list inclusion pressures pricing accessibility in lower-income health systems.
United States
Families migrate temporarily toward metropolitan corridors with embedded sarcoma programs, abandoning community oncology relationships for centralized networks. The Rare Pediatric Disease Priority Review Voucher program accelerates sponsor timelines for rhabdomyosarcoma indications. St. Jude Children's Research Hospital, Dana-Farber/Boston Children's, and MD Anderson anchor referral networks drawing cases from rural catchment areas.
Germany
Academic medical centers in Berlin and Heidelberg coordinate multicenter pediatric sarcoma trials through centralized EMA procedures. The EU Clinical Trials Regulation standardized pediatric study requirements, eliminating country-specific submission duplications. Bavarian and North Rhine-Westphalian university hospitals concentrate proton therapy capacity and biologics manufacturing infrastructure.
United Kingdom
NHS England's specialized commissioning framework concentrates rhabdomyosarcoma treatment at designated Principal Treatment Centers in London, Manchester, and Birmingham. The MHRA operates under retained EU law for pediatric medicines, maintaining alignment with EMA pediatric investigation plans. Great Ormond Street Hospital anchors molecular diagnostics and CAR-T trial access for relapsed cohorts.
Japan
PMDA pediatric review divisions accelerate orphan drug applications for rare childhood cancers through Sakigake designation pathways. Tokyo and Osaka academic medical centers concentrate multidisciplinary sarcoma programs with integrated surgical and radiation planning capabilities. Keio University Hospital and National Cancer Center Hospital anchor referral networks spanning the Kanto and Kansai regions.
India
CDSCO streamlined pediatric oncology trial approvals through 2019 New Drugs and Clinical Trials Rules, reducing activation timelines for molecularly defined subpopulations. Tata Memorial Hospital in Mumbai and All India Institute of Medical Sciences in Delhi concentrate case volume and referral networks. Post-chemotherapy surveillance shifts toward ambulatory settings as families seek to reduce temporary relocation burdens.
Rhabdomyosarcoma Treatment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical corporations leveraging established pediatric oncology infrastructure against emerging biologics developers. The upper tier commands clinical trial access across North American referral networks and EMA-coordinated European sites. Three archetypes dominate: cytotoxic chemotherapy incumbents defending backbone protocol positions, targeted therapy developers pursuing fusion-positive molecular subtypes, and immuno-oncology platforms competing for investigator-initiated study partnerships. Consolidation pressure operates through strategic licensing of receptor tyrosine kinase inhibitors and cell therapy manufacturing partnerships.
Within the integrated pharmaceutical tier, Pfizer Inc. and Novartis AG occupy positions sustained by pediatric oncology infrastructure and targeted therapy development programs respectively. Bristol Myers Squibb Company exemplifies the immuno-oncology archetype through checkpoint inhibitor platform competition. These three anchors represent distinct strategic vectors: cytotoxic backbone defense, precision medicine expansion, and biologics convergence with conventional protocols.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Celgene Corporation |
| Pfizer Inc. |
| MacroGenics, Inc. |
| Eisai Co., Ltd. |
| Bristol Myers Squibb Company |
| Eli Lilly & Company |
| Exelixis, Inc. |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Checkpoint inhibitor substitution for salvage chemotherapy is simultaneously redrawing supply geography toward academic cell therapy facilities and compressing pricing power for platinum-based cytotoxic manufacturers. This substitution dynamic concentrates procurement decisions at pediatric hospitals with embedded biologics manufacturing infrastructure while eroding margin buffers for vincristine and dactinomycin suppliers facing intermittent shortage cycles.
Pricing Analysis
Long-term offtake agreements dominate chemotherapy procurement for pediatric hospitals, though spot-market volatility for vincristine and dactinomycin creates intermittent protocol interruption costs. Price differentiation rests on FDA orphan drug designation tiering and biologics manufacturing certification at academic medical centers. Pricing pressure intensifies as CAR-T manufacturing scales compress addressable populations for late-stage cytotoxic assets. Community oncology clinics exhibit highest price sensitivity due to reimbursement rate compression, while flagship academic centers absorb premium pricing for proton therapy access.
Supply Chain Analysis
Strategic stockpiling of platinum-based chemotherapy inputs prevails among high-volume pediatric hospitals facing vincristine supply interruptions, contrasting with just-in-time preferences for biologics with limited shelf stability. Active pharmaceutical ingredient production concentrates in India and China, with finished dose formulation anchored in the United States and Germany. Supply chain risk centers on single-source radiation equipment dependency, with proton therapy capacity restricted to fewer than fifty North American facilities. Distribution runs through specialized oncology distributors with cold-chain capabilities for biologics and cytotoxics alike.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating at flagship pediatric hospitals with embedded sarcoma programs, as family relocation patterns consolidate procedure volume and procurement decision-making at St. Jude, Dana-Farber/Boston Children's, and MD Anderson.
For Market Incumbents: Consolidate manufacturing partnerships for receptor tyrosine kinase inhibitors to defend against CAR-T substitution threats in relapsed populations. Deepen backward integration into biologics manufacturing capacity at academic medical center sites to secure investigator-initiated study access. Lock in long-term offtake agreements for vincristine and dactinomycin supply to buffer against API volatility from Indian and Chinese sources. For New Entrants and Emerging Players: Differentiate on home care monitoring infrastructure for post-chemotherapy surveillance, where wearable toxicity assessment devices remain underpenetrated. Target ambulatory settings in metropolitan corridors where families seek to reduce temporary relocation burdens. Pursue reimbursement strategy partnerships with pediatric hospital networks lacking dedicated sarcoma infrastructure to capture diverted case volume. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations possessing pediatric biologics capacity and FDA orphan drug designation expertise. Five-to-ten-year viability hinges on checkpoint inhibitor convergence timelines and CAR-T manufacturing scale economics. Watch PAX-FOXO1 fusion status trial enrollment rates as the signal indicating precision medicine substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | CAR-T constructs targeting GD2 and B7-H3 antigens are supplanting salvage chemotherapy at Children's Oncology Group sites. |
| Regulatory Approval Pathway | FDA Rare Pediatric Disease Priority Review Vouchers accelerate sponsor timelines where commercial returns alone would be insufficient. |
| Manufacturing Scale-Up | Academic cell therapy facilities in Boston, Houston, and Memphis are expanding biologics production capacity for relapsed cohorts. |
| Licensing Agreement | Receptor tyrosine kinase inhibitors for fusion-positive subtypes are reshaping competitive boundaries through strategic partnerships. |
| Pipeline Diversification | Checkpoint inhibitor combinations with conventional cytotoxics are opening investigator-initiated study partnerships at underutilized sarcoma programs. |
Methodological Framework
Operator-level perspectives from pediatric oncologists, hospital pharmacy directors, sarcoma program administrators, and biologics manufacturing specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA orphan drug designation filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocol records, and hospital procurement database extracts. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs across treatment modality, molecular subtype, and regional regulatory cluster dimensions.
Sensitivity analysis tested forecast robustness against platinum-based chemotherapy supply volatility scenarios and CAR-T manufacturing capacity expansion rates across the projection horizon. Segmentation dimensions modeled include treatment stage, medication type, end-user setting, and molecular subtype classification. CAGRs were derived from patient incidence trajectories, protocol duration assumptions, and pricing evolution for precision medicine substitution. Forecast inputs incorporated referral network concentration patterns and family relocation elasticity to metropolitan sarcoma programs.
Material uncertainties — pediatric oncologist workforce shortages, proton therapy capacity constraints, and biomarker-driven trial eligibility fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about FDA voucher program continuity and EMA pediatric investigation plan harmonization stability. Revision becomes warranted when CAR-T manufacturing scale crosses thresholds that materially compress chemotherapy addressable populations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Hemangioma Treatment Market