
 Psoriatic Arthritis (Psa) Treatment Market | 2026-2036
Psoriatic Arthritis (Psa) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Psoriatic Arthritis (Psa) Treatment Market Analytics
Specialty pharmacy distribution is reshaping how biologic therapies reach psoriatic arthritis patients, with hub services and patient support programs now controlling access. AbbVie Inc. leverages its immunology infrastructure to sustain Humira's formulary position against biosimilar erosion. Novartis AG competes through Cosentyx with differentiated IL-17A mechanism positioning in dermatology-rheumatology crossover prescribing. Amgen Inc. anchors the TNF-inhibitor legacy segment while navigating Otezla's oral therapy channel expansion.
Psoriatic arthritis treatment encompasses pharmacological interventions targeting joint inflammation, skin manifestations, and systemic immune dysregulation in patients with concurrent psoriasis, with biologics requiring cold-chain logistics and subcutaneous or intravenous administration protocols. The therapeutic category spans monoclonal antibodies, fusion proteins, small-molecule inhibitors, and conventional immunosuppressants designed to halt radiographic progression and preserve functional status. Biologics command the dominant value share within product type segmentation, while injectable delivery modes capture the majority volume flow due to mAb formulation requirements. Outpatient care settings represent the fastest-growing application segment as site-of-service economics shift infusion away from hospitals. Adult patients constitute the core demographic, though newly diagnosed patient identification through psoriasis screening protocols is expanding addressable pools.
FDA biosimilar interchangeability standards and EMA extrapolation guidelines are reshaping competitive dynamics and pricing trajectories for TNF-alpha and IL-inhibitor classes. The EU MDR framework imposes strengthened post-market surveillance obligations on device components used in autoinjector delivery systems. Stakeholders must monitor FDA label expansion decisions for IL-23 and JAK inhibitor classes, as these determinations will redirect rheumatology prescribing patterns and payer prior authorization criteria across commercial and government segments.
Market Dynamics
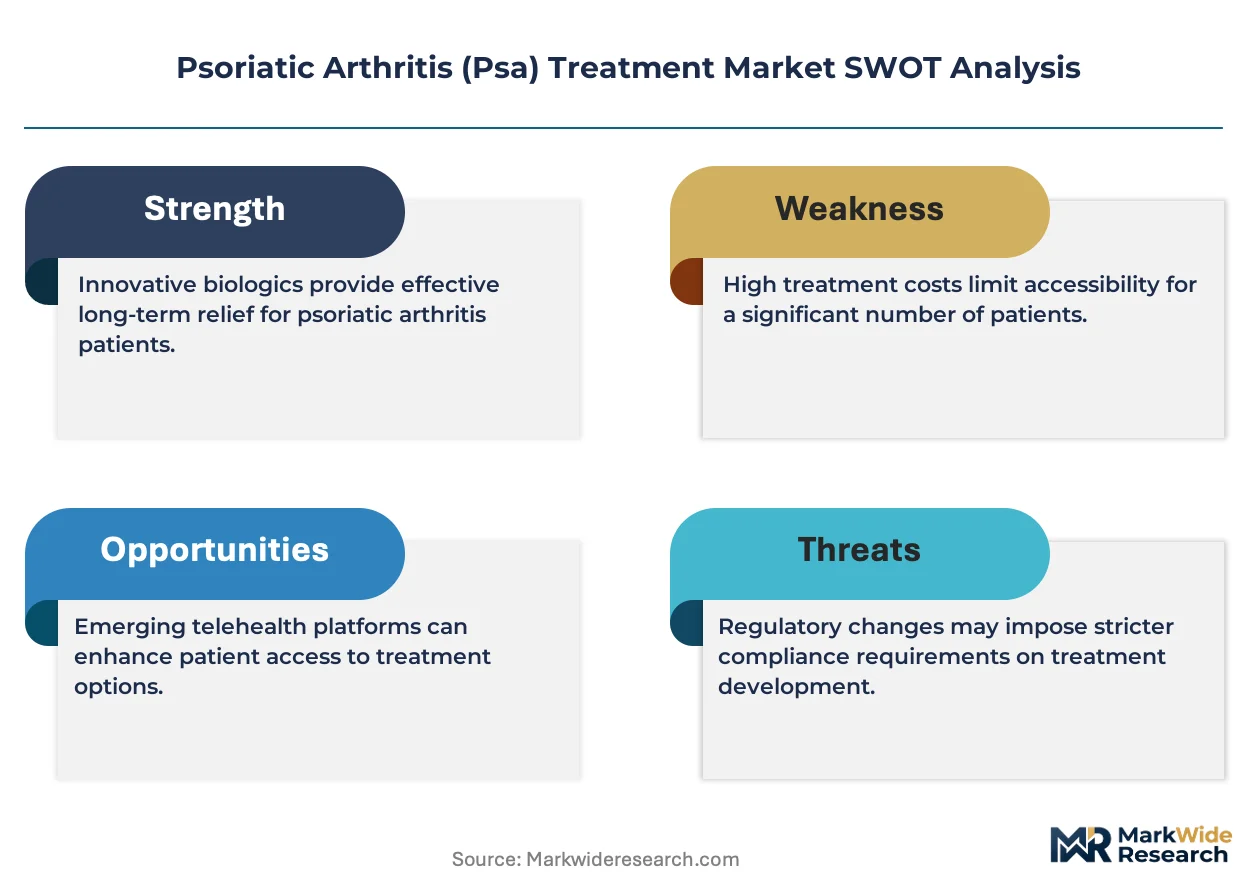
FDA biosimilar interchangeability standards are compressing pricing power across TNF-alpha inhibitor classes while rheumatology clinics accelerate biologic adoption through streamlined prior authorization protocols.
Growth Catalysts
- Interchangeability Pathways:FDA guidance on biosimilar switching protocols expands payer willingness to substitute reference biologics, broadening patient access to lower-cost alternatives without therapeutic compromise.
- IL-17 and IL-23 Mechanisms:Novel biologic classes targeting distinct cytokine pathways offer differentiated efficacy profiles for patients with inadequate response to TNF inhibitors, expanding the addressable treatment population.
- Hub Service Infrastructure:Specialty pharmacy patient support programs reduce abandonment rates through co-pay assistance, injection training, and adherence monitoring integrated with electronic health records.
Market Restraints
- Cold-Chain Distribution Costs:Biologics requiring refrigerated transport and storage impose logistics burdens that limit penetration in rural and underserved areas with fragmented pharmacy infrastructure.
- Prior Authorization Friction:Commercial payers mandate step-therapy protocols and formulary exclusions that delay biologic initiation by months, driving treatment discontinuation before optimal dosing.
- JAK Inhibitor Safety Scrutiny:FDA boxed warnings on cardiovascular and malignancy risks for oral JAK inhibitors constrain rheumatologist prescribing preferences and payer coverage decisions.
Strategic Opportunities
- Oral Small-Molecule Expansion:Development of next-generation TYK2 and PDE4 inhibitors offers non-injectable alternatives that bypass cold-chain requirements and appeal to injection-averse patient segments.
- Integrated Dermatology-Rheumatology Models:Co-located specialty clinics enable earlier psoriatic arthritis detection through systematic psoriasis screening, capturing patients before joint damage progression.
- Site-of-Service Economics:Outpatient infusion centers and home administration programs reduce hospital-based care costs while improving patient convenience and clinic throughput capacity.
Industry Challenges
- Biosimilar Manufacturing Complexity:Cell-line development and analytical characterization requirements for monoclonal antibody biosimilars demand specialized bioprocessing expertise that constrains supplier base expansion.
- Reimbursement Code Fragmentation:Medicare Part B coding distinctions between originator biologics and biosimilars create administrative burden for billing staff and revenue cycle management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psoriatic Arthritis (Psa) Treatment Market |
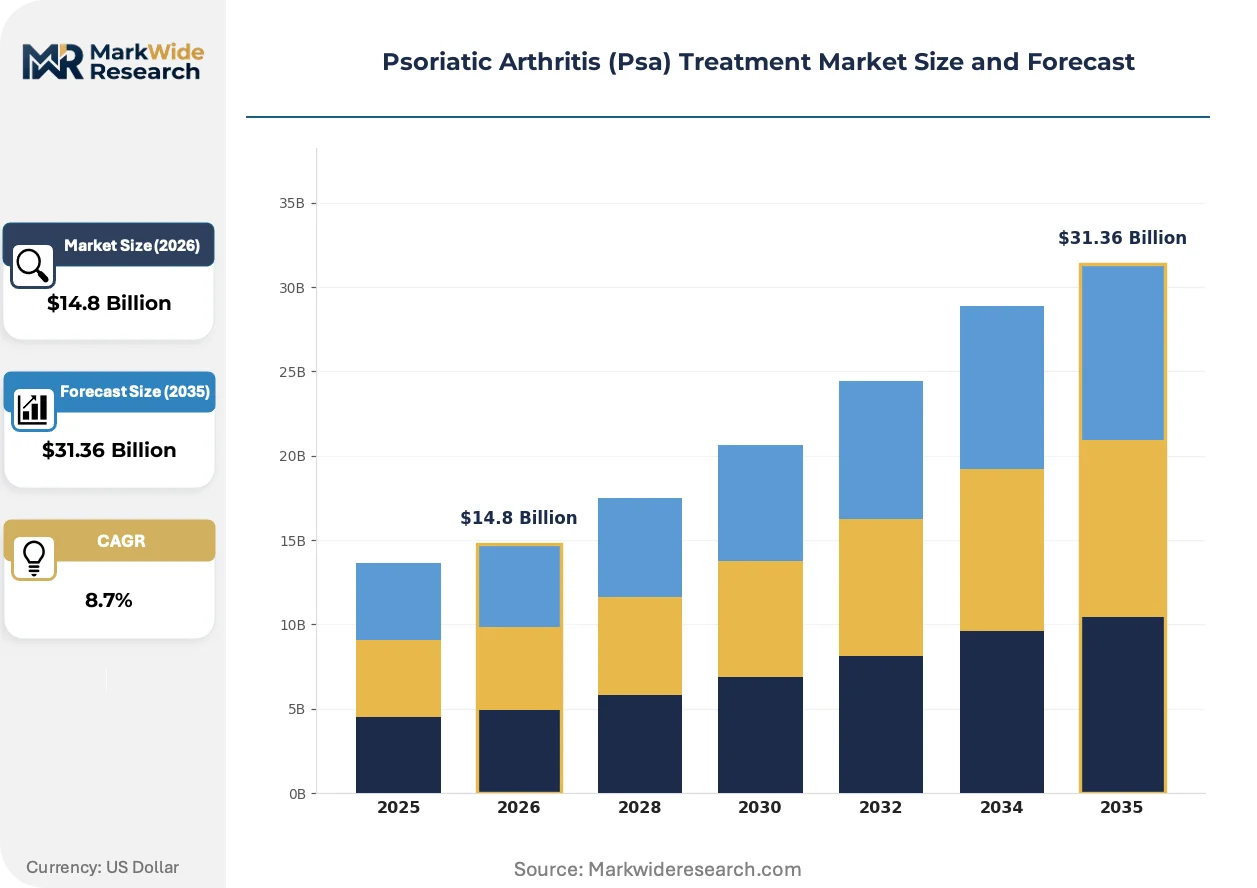
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Nonsteroidal Anti-Inflammatory Drugs, Disease-Modifying Antirheumatic Drugs, Corticosteroids Application: Hospital Treatment, Outpatient Care, Home Care, Specialty Clinics Delivery Mode: Oral, Injectable, Topical, Intravenous Patient Type: Adult Patients, Pediatric Patients, Geriatric Patients, Newly Diagnosed Patients |
| Companies Covered | AbbVie Inc., Johnson & Johnson Services, Inc., Novartis AG, Amgen Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, Pfizer Inc., UCB S.A., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psoriatic Arthritis (Psa) Treatment Market Evolving Landscape
Digital health integration and mechanism-based patient stratification are restructuring how biologic therapies are selected, monitored, and reimbursed across rheumatology practice settings.
Real-world evidence platforms is digitizing treatment response tracking by aggregating electronic health record data, pharmacy claims, and patient-reported outcomes into integrated dashboards. Rheumatology practices are deploying these systems to benchmark biologic switching decisions against population-level effectiveness data. The technology is digitizing prior authorization workflows, compressing approval timelines from weeks to days through automated clinical documentation exchange.
EMA extrapolation guidelines for biosimilar indication expansion are reducing redundant clinical trial requirements for follow-on biologics seeking psoriatic arthritis labels after psoriasis approval. Manufacturers are leveraging pharmacokinetic bridging studies and mechanism-of-action justifications to accelerate regulatory submissions. The EU MDR framework imposes strengthened post-market surveillance on autoinjector device components, forcing device suppliers to upgrade quality management systems.
Patient cost-sharing models are evolving toward value-based designs that tie out-of-pocket exposure to medication adherence and clinical outcome achievement. Commercial payers are piloting programs that reduce co-pays for patients meeting disease activity score targets. This shift is most visible in United States employer-sponsored plans, where pharmacy benefit managers are negotiating outcomes guarantees with biologic manufacturers.
Psoriatic Arthritis (Psa) Treatment Market Segmentation
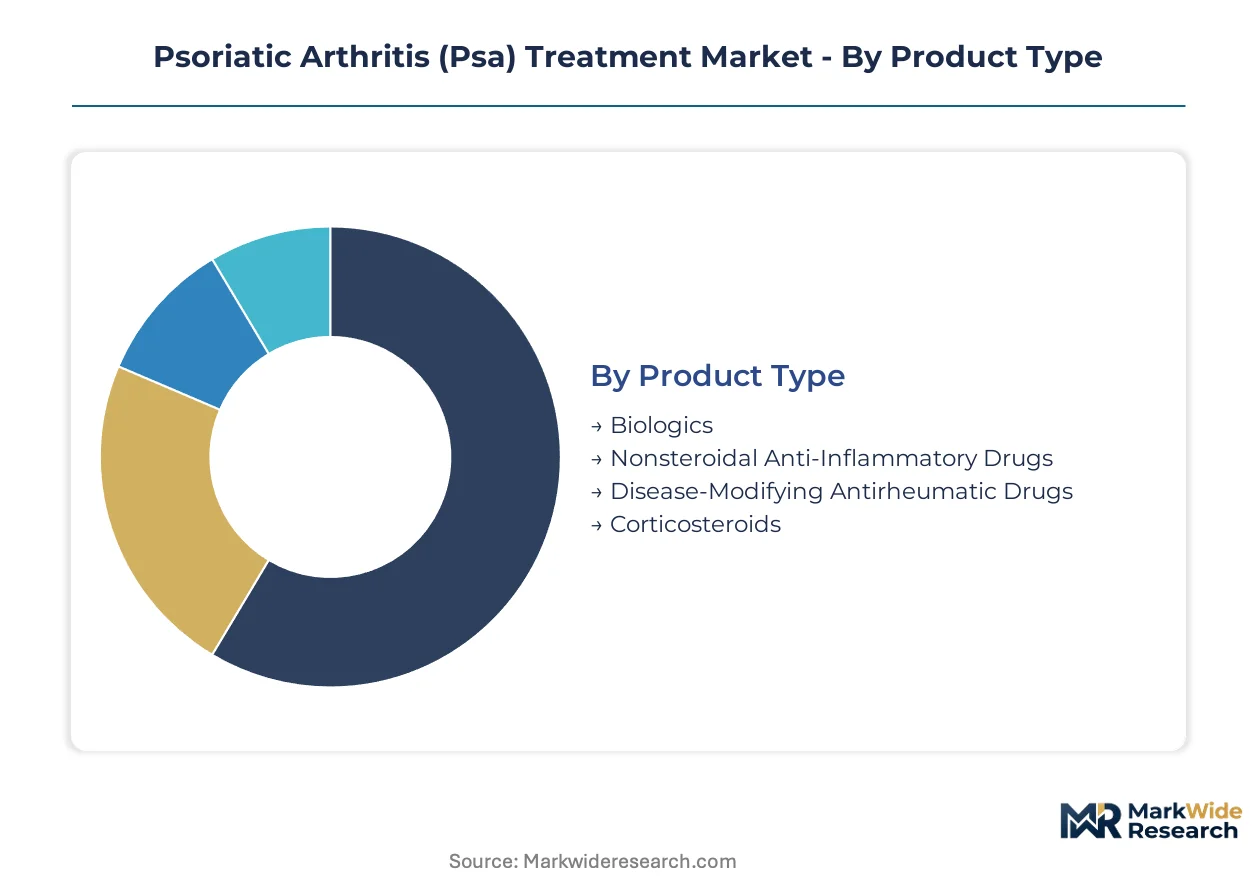
Psoriatic arthritis treatment segmentation reflects divergent clinical pathways, reimbursement structures, and patient access models across the therapeutic continuum. Each dimension captures distinct value pools shaped by mechanism of action, site of service economics, and demographic risk stratification.
Product Type:
Use-case spectrum spans acute symptom control through chronic disease modification, with biologics anchoring premium positioning while conventional agents serve step-therapy protocols.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-17, and IL-23 cytokine pathways require cold-chain distribution and specialty pharmacy dispensing. Demand concentrates in United States rheumatology practices where Medicare Part B reimbursement sustains infusion center economics and commercial prior authorization pathways have matured.
- Disease-Modifying Antirheumatic Drugs:Conventional synthetic DMARDs including methotrexate and sulfasalazine function as first-line therapy under payer step-therapy mandates. Adoption clusters in Medicaid populations and Medicare Advantage plans where cost containment protocols delay biologic escalation.
- Nonsteroidal Anti-Inflammatory Drugs:Oral analgesics address peripheral joint pain and enthesitis in mild disease activity states.
- Corticosteroids:Intra-articular and systemic formulations provide bridging therapy during biologic initiation or disease flares.
Established volume favors Disease-Modifying Antirheumatic Drugs; emerging adoption favors Biologics.
Application:
Cost tier stratification separates hospital-based infusion revenue from lower-acuity outpatient and home administration models.
- Outpatient Care:Rheumatology clinic infusion suites and specialty pharmacy injection programs capture site-of-service margin migration away from hospitals. United States independent clinic networks and hospital outpatient departments compete for Medicare Part B drug administration revenue through throughput optimization.
- Specialty Clinics:Co-located dermatology-rheumatology centers enable systematic psoriasis screening and early PsA detection before radiographic progression. Demand concentrates in United States metropolitan markets where integrated electronic health records support closed-loop referral protocols.
- Hospital Treatment:Acute care settings manage severe disease flares, comorbid infections, and surgical interventions.
- Home Care:Self-administered subcutaneous biologics and oral therapies reduce facility dependency for stable patients.
Hospital Treatment retains the highest per-episode revenue; Outpatient Care is climbing the fastest as site-neutral payment policies expand.
Delivery Mode:
Patient type and convenience requirements segment administration routes, with injection-averse populations driving oral development priorities.
- Injectable:Subcutaneous autoinjector and prefilled syringe formulations dominate biologic delivery, requiring patient training programs and cold-chain logistics. Adoption concentrates in commercially insured United States populations where specialty pharmacy hub services support adherence monitoring.
- Oral:Small-molecule JAK inhibitors, PDE4 inhibitors, and conventional DMARDs bypass injection barriers and refrigeration requirements. Demand is expanding most quickly among pediatric transition populations and geriatric patients with limited caregiver support.
- Intravenous:Hospital and clinic-based infusion of monoclonal antibodies requires nursing supervision and adverse event monitoring.
- Topical:Localized therapies address concurrent psoriasis skin manifestations in mild joint disease.
Injectable captures the dominant value share; Oral is gaining share fastest through next-generation TYK2 mechanisms.
Patient Type:
Maturity gradient separates established adult treatment paradigms from emerging pediatric and newly diagnosed screening protocols.
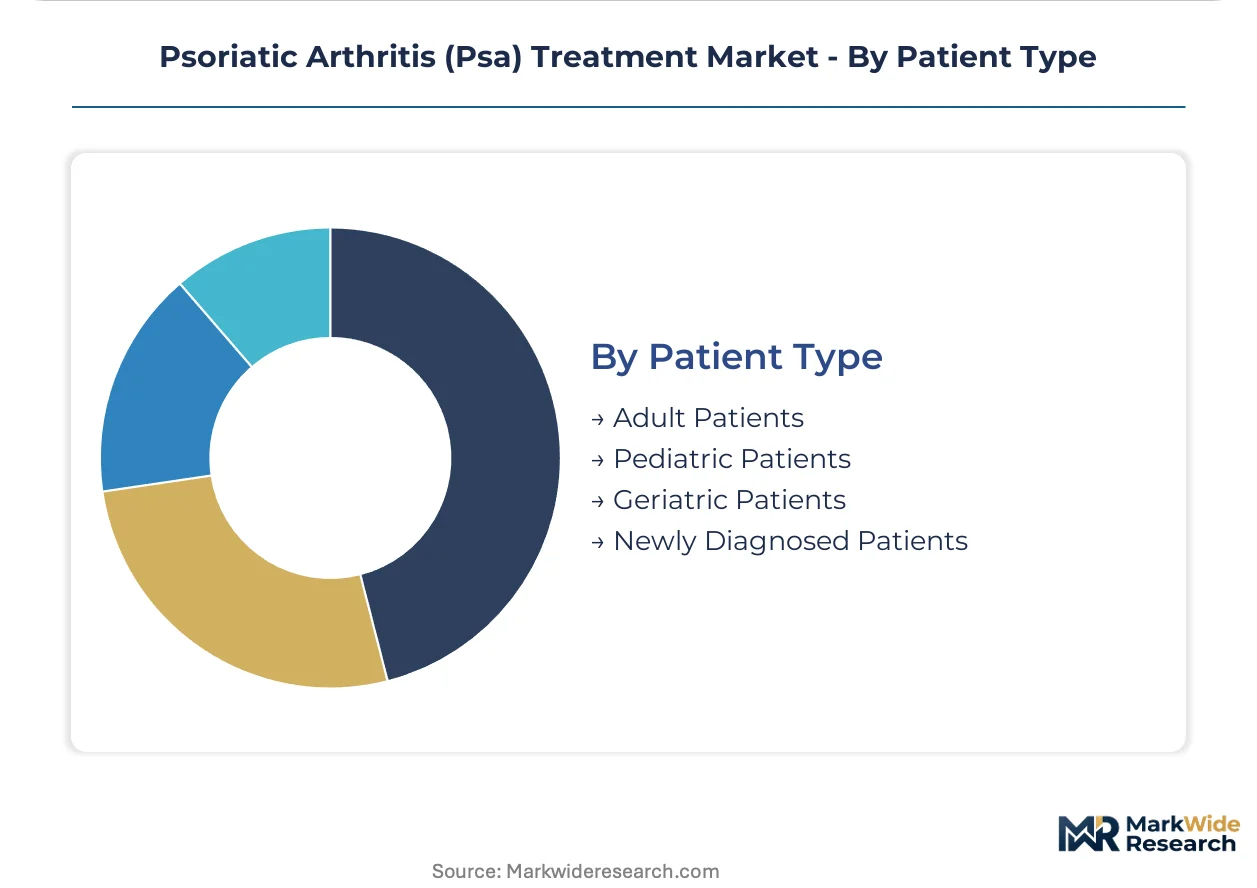
- Adult Patients:Core demographic aged 30-55 with established psoriasis history and progressive joint involvement. Treatment concentration in United States commercial insurance pools where prior authorization pathways for biologics are most streamlined.
- Newly Diagnosed Patients:Screening capture through dermatology referral networks and primary care psoriasis protocols expands addressable pools before structural joint damage. United States integrated delivery systems and accountable care organizations invest in predictive analytics to identify high-risk psoriasis patients.
- Pediatric Patients:Juvenile PsA represents orphan indication status with limited approved biologic labels.
- Geriatric Patients:Comorbidity burden and polypharmacy constrain biologic selection in Medicare populations.
Adult Patients anchor current revenue; Newly Diagnosed Patients represent the steepest expansion trajectory through screening protocol penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors Europe's biologics distribution network, while direct rail links to the Rhein-Ruhr industrial corridor enable temperature-controlled transit to German manufacturing clusters.
United States
Commercial insurance pools and Medicare Part B reimbursement sustain the highest biologic therapy penetration rates globally. FDA accelerated approval pathways for biosimilars compress development timelines for follow-on biologics. The Boston-Cambridge biotechnology corridor concentrates monoclonal antibody development, with Massachusetts-based research institutes driving IL-23 and JAK inhibitor clinical programs.
Germany
EMA extrapolation guidelines enable biosimilar manufacturers to expand psoriatic arthritis indications without redundant clinical trials. The EU MDR framework imposes strengthened post-market surveillance obligations on autoinjector device components. The Rhein-Main region around Frankfurt hosts centralized distribution hubs serving rheumatology specialty clinics across Central Europe.
Switzerland
Swissmedic's streamlined biologics licensing procedures attract European headquarters for immunology-focused pharmaceutical operations. The country's bilateral agreements with the EU facilitate seamless cross-border pharmaceutical trade. Basel's pharmaceutical cluster anchors monoclonal antibody research, with the Rhine river transport corridor connecting to EU distribution networks.
Japan
PMDA's Sakigake designation system accelerates regulatory review for innovative biologics addressing unmet needs in psoriatic arthritis. METI's healthcare export initiatives promote Japanese-developed immunotherapies across Asia-Pacific markets. The Kanto region surrounding Tokyo concentrates rheumatology clinical trial sites and biologics manufacturing capacity.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for biologic therapies, creating transparent but stringent cost-effectiveness thresholds. The MHRA's post-Brexit regulatory autonomy enables tailored approval pathways for biosimilars. The Golden Triangle between London, Oxford, and Cambridge anchors immunology research, with the M1 motorway corridor facilitating distribution to NHS trusts.
Psoriatic Arthritis (Psa) Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around immunology-focused pharmaceutical conglomerates with established biologics manufacturing infrastructure and specialty pharmacy distribution partnerships. Three strategic archetypes dominate: legacy TNF-alpha inhibitor specialists defending against biosimilar erosion, IL-pathway innovators capturing dermatology-rheumatology crossover prescribing, and oral small-molecule developers pursuing non-injectable alternatives. Competitive moves center on portfolio diversification through mechanism expansion and vertical integration into patient hub services.
Within the established biologics tier, AbbVie Inc. and Novartis AG exemplify divergent defensive and offensive positioning strategies, while Amgen Inc. occupies a transitional position bridging TNF-inhibitor legacy portfolios with emerging oral therapy channels. Johnson & Johnson Services, Inc. represents the diversified healthcare conglomerate archetype, leveraging cross-divisional immunology expertise.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Pfizer Inc. |
| UCB S.A. |
| Merck & Co. Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in European biologics manufacturing is tightening supplier leverage and compressing negotiation margins for reference product originators facing biosimilar entry. FDA interchangeability designations accelerate volume migration toward lower-cost alternatives, forcing originators to absorb cold-chain cost premiums to defend formulary position.
Pricing Analysis
Volume-discount tiering structures separate originator biologics from interchangeable biosimilars and non-interchangeable follow-ons across Medicare Part B and commercial formularies. Price differentiation hinges on FDA interchangeability status and cold-chain reliability guarantees, with branded TNF-alpha inhibitors commanding premium positioning against unbranded biosimilar alternatives. Cost compression in the biosimilar tier is intensifying as pharmacy benefit managers consolidate purchasing through specialty distributor networks. Medicaid populations and Medicare Advantage plans exhibit highest price sensitivity, while commercial employer-sponsored plans prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Supplier-financing arrangements including extended payment terms and supply-chain finance facilities are proliferating as biosimilar manufacturers compete for limited contract manufacturing organization capacity. Manufacturing concentrates in the United States, Ireland, and Singapore, with fill-finish operations drawing from German and Swiss precision equipment suppliers. Raw material dependencies span cell culture media, single-use bioreactor components, and pharmaceutical-grade cold-chain packaging. Single-source vulnerability in monoclonal antibody production cell lines poses structural risk. Distribution runs through specialty pharmacy hubs with temperature-controlled last-mile logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as dermatology-rheumatology integrated screening protocols capture treatment-naive patients before radiographic progression. Biosimilar penetration remains below theoretical ceilings, leaving headroom for mechanism-differentiated entrants.
For Market Incumbents: Harden formulary position through outcomes-based contracting with commercial payers and captive manufacturing of autoinjector devices. AbbVie and Amgen face erosion from IL-17 and IL-23 class entrants; vertical integration into patient hub services preserves adherence data control. Certification investment in FDA interchangeability studies for legacy TNF-alpha inhibitors delays biosimilar substitution.
For New Entrants and Emerging Players: Pursue oral small-molecule development targeting injection-averse segments and pediatric transition populations underserved by current biologic labels. The newly diagnosed patient segment through dermatology screening protocols offers lowest competitive density. Co-development partnerships with integrated delivery systems secure real-world evidence generation and prior authorization pathway access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across autoinjector device manufacturing and cold-chain logistics infrastructure. Long-term viability favors platform immunology players with diversified cytokine-targeting portfolios over single-mechanism dependencies. Acquisition targets include mid-cap biologics developers with Phase III IL-23 assets and specialty pharmacy hub operators. Watch FDA label expansion decisions for TYK2 inhibitors as inflection signal for oral therapy displacement of injectable biologics.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III programs for IL-23 and TYK2 mechanisms redirect rheumatology prescribing away from TNF-alpha inhibitors. |
| Regulatory Approval Pathway | FDA interchangeability studies compress biosimilar substitution barriers and accelerate payer formulary adoption. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Ireland and Singapore addresses cold-chain distribution bottlenecks. |
| Pipeline Diversification | Mechanism expansion beyond TNF-alpha into IL-17 and IL-23 classes reduces portfolio concentration risk. |
| Strategic Partnership | Integrated dermatology-rheumatology clinic networks enable systematic psoriasis screening and early PsA detection. |
Research Methodology
Cross-validation between formulary database analysis and clinical trial registry screening anchors the qualitative findings in this study. Primary interviews with rheumatology practice administrators, specialty pharmacy hub directors, payer formulary decision-makers, and biologics manufacturing executives combined with secondary validation from FDA Orange Book listings, EMA EPAR documents, Medicare Part B claims data, and commercial insurance prior authorization protocols. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation ensure segmentation coherence.
Calibration against historical biosimilar adoption curves in rheumatoid arthritis and psoriasis informs the projection framework across the analysis window. Segmentation dimensions include product type, application setting, delivery mode, and patient diagnostic status, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway differences. CAGRs derive from patent expiry schedules, biosimilar pipeline maturity, and payer policy evolution. Forecast inputs incorporate specialty pharmacy dispensing volume trends and step-therapy protocol penetration rates.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, commercial insurance medical loss ratio regulations, or biologics manufacturing input costs would shift the trajectory. Forecasts reflect documented assumptions about biosimilar interchangeability adoption speed and IL-pathway clinical differentiation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Intussusception Market