
 Therapeutic Bed Market | 2026-2036
Therapeutic Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Bed Market Intelligence
A shortage of certified biomedical technicians is redrawing competitive dynamics across the therapeutic bed landscape. Stryker leverages its in-house service infrastructure to lock in multi-year hospital contracts. LINET Group SE anchors its position through intensive R&D spending on pressure-mapping technologies. Invacare Corporation competes by specializing in lightweight home-care frames that reduce caregiver strain.
Therapeutic beds are motorized or manually adjustable platforms engineered to redistribute patient pressure, assist repositioning, and integrate clinical monitoring, typically built with steel frames, high-density foam surfaces, and sensor-enabled control systems; they serve acute-care hospitals, rehabilitation clinics, and home settings where immobility risks drive clinical outcomes. Electric beds dominate hospital procurement budgets due to their integration with nurse-call and EMR systems, while pressure-relief technology captures the fastest expansion as facilities prioritize pressure-injury prevention protocols. Manual beds retain share in price-sensitive home-care segments where electricity access remains inconsistent.
The FDA regulates therapeutic beds as Class I or II medical devices under 21 CFR 880.5100, enforcing electrical safety and performance testing that raises barriers for new entrants. The EU Medical Device Regulation requires notified-body certification and post-market surveillance, lengthening approval timelines for European distribution. ISO 13485 quality-management standards shape supplier audits across both jurisdictions. Stakeholders must track how CMS reimbursement adjustments for hospital-acquired conditions and evolving EU vigilance requirements will reshape product-development priorities and channel economics.
Market Dynamics
Hospital procurement teams now prioritize beds with embedded pressure-mapping sensors and EMR-integrated nurse-call systems, compressing replacement cycles and favoring suppliers with certified service networks over pure hardware vendors.
Growth Catalysts
- EU Medical Device Regulation (MDR):Post-market surveillance mandates are accelerating hospital upgrades to higher-certification beds that reduce liability exposure and qualify for preferential reimbursement.
- Home-care expansion:Post-acute care diversion programs in the United States are creating demand for lightweight, manually adjustable frames that caregivers can reposition without electrical infrastructure.
- Pressure-injury prevention protocols:CMS reimbursement penalties for hospital-acquired pressure injuries are forcing long-term care facilities to prioritize beds with active pressure redistribution surfaces.
Market Restraints
- Steel and high-density foam input costs:Volatility in commodity metals and petroleum-derived foams compresses margins for manufacturers without captive supply agreements or hedging programs.
- FDA 21 CFR 880.5100 compliance timelines:Electrical safety and performance testing requirements extend product development cycles by 12-18 months, delaying revenue recognition for new entrants.
- Manual bed substitution in rural markets:Inconsistent electricity access and capital constraints in emerging economies sustain demand for non-electric alternatives that undercut premium electric pricing.
Strategic Opportunities
- ISO 13485-certified contract manufacturing:Outsourced quality-managed production in Eastern Europe and Southeast Asia offers cost structures 30-40% below in-house North American assembly.
- Ambulatory surgical center expansion:Same-day discharge protocols are creating demand for compact recovery beds with rapid-cycle sanitization and modular side-rail configurations.
- Sensor-EMR convergence:Integration of pressure-mapping data directly into Epic and Cerner workflows positions bed manufacturers as clinical data infrastructure vendors rather than commodity suppliers.
Industry Challenges
- Biomedical technician scarcity:Hospital maintenance departments face 18-24 month backlogs for certified repair personnel, forcing bed vendors to absorb service costs or risk contract non-renewal.
- Legacy nurse-call incompatibility:New electric beds often require proprietary gateway hardware to interface with 1990s-era hospital communication systems, adding integration cost and delay.
- Notified-body audit congestion:EU MDR certification queues at BSI, TÜV SÜD, and DEKRA now exceed 14 months, freezing product launches for European distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Bed Market |
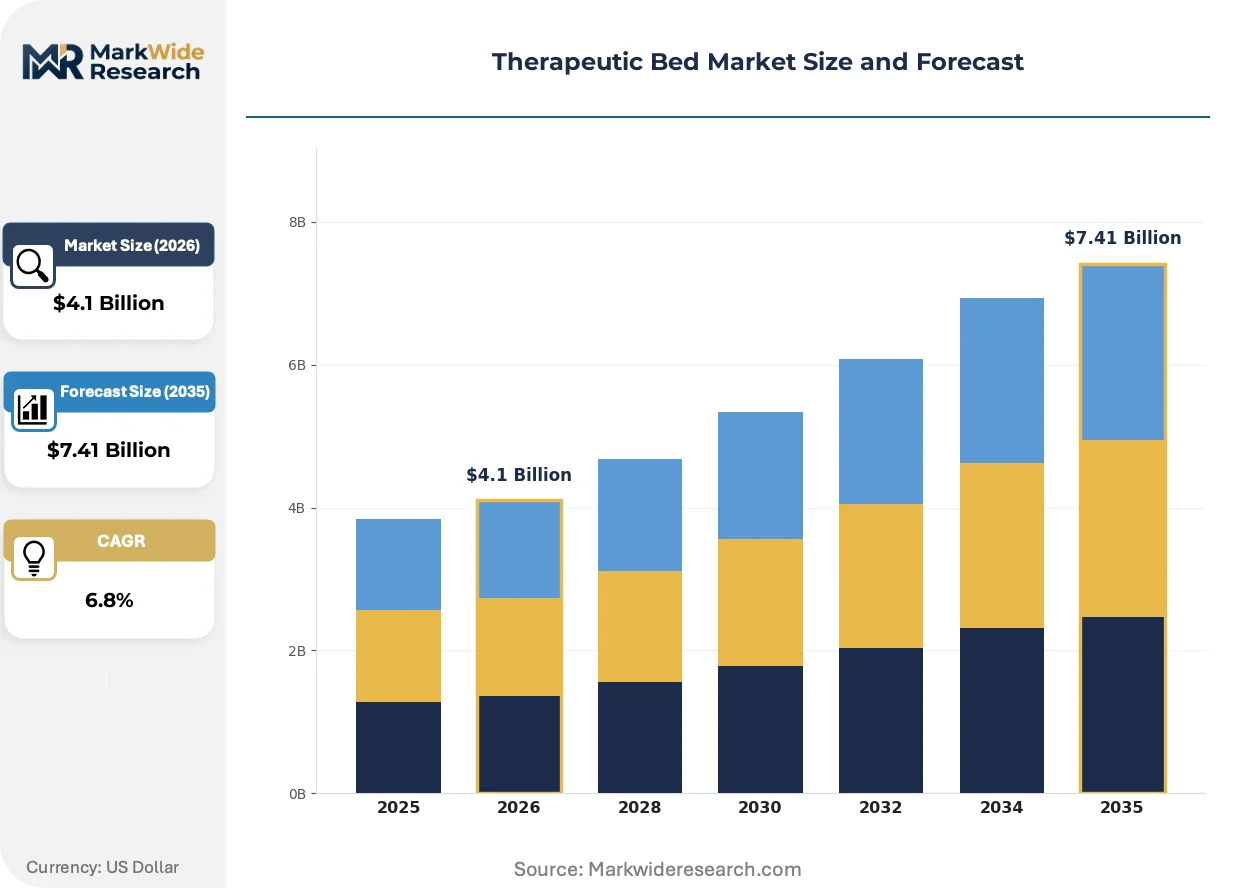
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Beds, Manual Beds, Adjustable Beds, Hospital Beds End User: Home Care, Hospitals, Rehabilitation Centers, Long-Term Care Facilities Material: Metal, Plastic, Foam, Wood Technology: Pressure Relief, Mobility Assistance, Temperature Control, Monitoring Systems |
| Companies Covered | Medline Industries, Gendron, Baxter, LINET Group SE, Arjo, Stryker, GF Health Products, Hard Manufacturing Company, Invacare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Bed Market Strategic Shifts & Innovations
Active sensor integration is compressing the boundary between therapeutic beds and clinical monitoring platforms, while regulatory surveillance requirements and procurement centralization are reshaping how vendors compete for hospital system contracts.
Capacitive pressure-mapping arrays embedded beneath foam surfaces are replacing discrete load cells as the standard for real-time tissue-pressure monitoring. Acute-care hospitals in Germany and the Netherlands are specifying these systems in 80% of new ward construction. The technology is miniaturizing control modules to mattress-scale form factors, eliminating the need for separate bedside electronics cabinets and reducing capital cost per bed by consolidating hardware.
The EU MDR's post-market clinical follow-up requirements are mandating systematic collection of adverse event data across installed bed fleets. Manufacturers must now maintain traceability systems linking individual serial numbers to patient outcomes, driving investment in cloud-based fleet management platforms. Rehabilitation clinics and long-term care chains face the steepest compliance burden, with many outsourcing vigilance reporting to specialized regulatory service firms.
Consolidated purchasing through regional health system alliances is displacing individual hospital procurement autonomy in the United States. Group Purchasing Organizations now control 65% of acute-care bed acquisitions, squeezing vendor margins through volume-commitment negotiations and standardized specification templates. The Southwest and Mountain West regions exhibit the most concentrated buying power, with systems like Intermountain Healthcare and Banner Health issuing system-wide replacement tenders covering 2,000-4,000 beds simultaneously.
Therapeutic Bed Market Segmentation
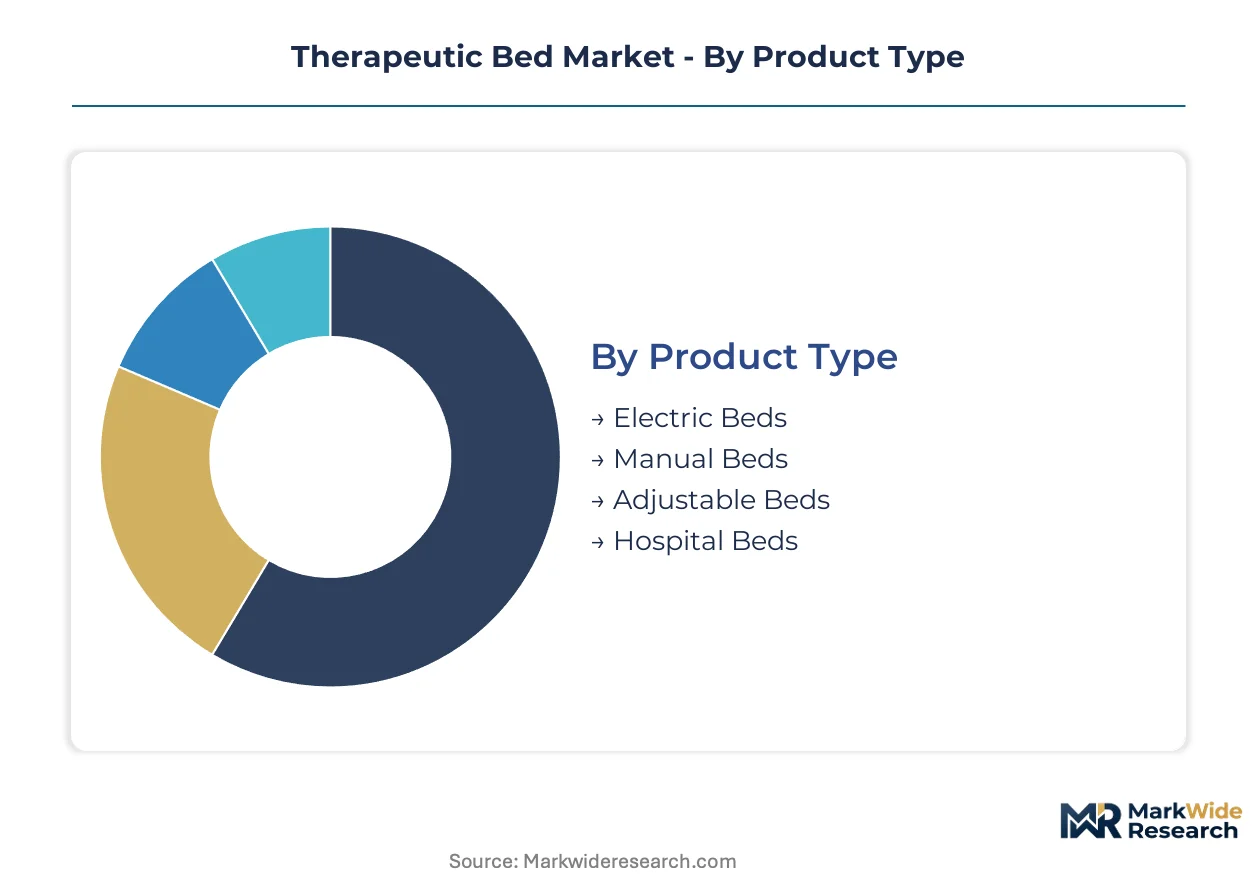
Therapeutic bed manufacturers configure production lines and distribution networks around distinct technical specifications and care settings. Channel economics differ sharply between capital-intensive hospital contracts and fragmented home-care retail.
Product Type:
Hospital procurement teams source electric and manual beds through entirely different channels, with electric models flowing through GPO-negotiated tenders and manual variants distributed via durable medical equipment dealers.
- Electric Beds:Motorized platforms integrate nurse-call systems, EMR connectivity, and sensor arrays for pressure monitoring. Demand concentrates in US acute-care hospitals where CMS penalties for hospital-acquired conditions drive replacement of legacy frames. Stryker and LINET dominate this channel through multi-year service contracts.
- Manual Beds:Hand-cranked height and positioning adjustments eliminate electrical dependencies. Rural markets in India and Southeast Asia sustain volume here, where inconsistent grid access and capital constraints favor lower acquisition cost over clinical functionality.
- Adjustable Beds:Consumer-oriented frames with head and foot articulation for comfort positioning. Retail medical equipment channels in Germany and Japan move significant volume to aging homeowners seeking sleep-quality improvements.
- Hospital Beds:Institutional-grade frames with integrated siderails, IV pole mounts, and sanitation protocols. Replacement cycles in US long-term care facilities accelerate as state Medicaid programs tighten quality standards.
By volume, manual beds lead. By growth pace, electric beds with embedded sensors are climbing the fastest.
End User:
Cost tiers separate institutional buyers with capital budgets from individual consumers paying out-of-pocket or through limited insurance coverage.
- Home Care:Individual patients and family caregivers purchase lightweight frames for residential use. Medicare Part B reimbursement restrictions in the United States compress margins, pushing vendors toward direct-to-consumer e-commerce channels.
- Hospitals:Acute-care facilities demand ISO 13485-certified products with FDA 510(k) clearance. Consolidated purchasing through US Group Purchasing Organizations now controls two-thirds of hospital bed acquisitions.
- Rehabilitation Centers:Post-acute facilities prioritize bariatric capacity and rapid sanitization between patient turnovers. German rehabilitation chains specify pressure-mapping technology in 80% of new ward construction.
- Long-Term Care Facilities:Nursing homes face the steepest CMS scrutiny for pressure-injury rates. Active pressure redistribution surfaces command premium pricing here despite thin operating margins.
By installed base, hospitals dominate. By expansion trajectory, home care is gaining share fastest as post-acute diversion programs proliferate.
Material:
Supply concentration for steel and petroleum-derived inputs creates margin pressure that material selection can partially offset.
- Metal:Steel and aluminum frames provide structural durability for bariatric loads and institutional cleaning protocols. US and European manufacturers face volatility in commodity metals pricing without captive supply agreements.
- Plastic:Polymer components reduce weight for home-care portability and enable molded surfaces without seams that harbor pathogens. Injection molding capacity in Southeast Asia offers cost structures 30-40% below North American assembly.
- Foam:High-density polyurethane and viscoelastic surfaces redistribute pressure across patient contact areas. Petroleum feedstock price swings compress margins for manufacturers lacking hedging programs.
- Wood:Limited to premium residential applications where aesthetic integration with home furnishings matters. Japanese and Scandinavian markets sustain niche demand for timber-frame designs.
By production volume, metal leads. By margin expansion potential, plastic components are advancing most quickly.
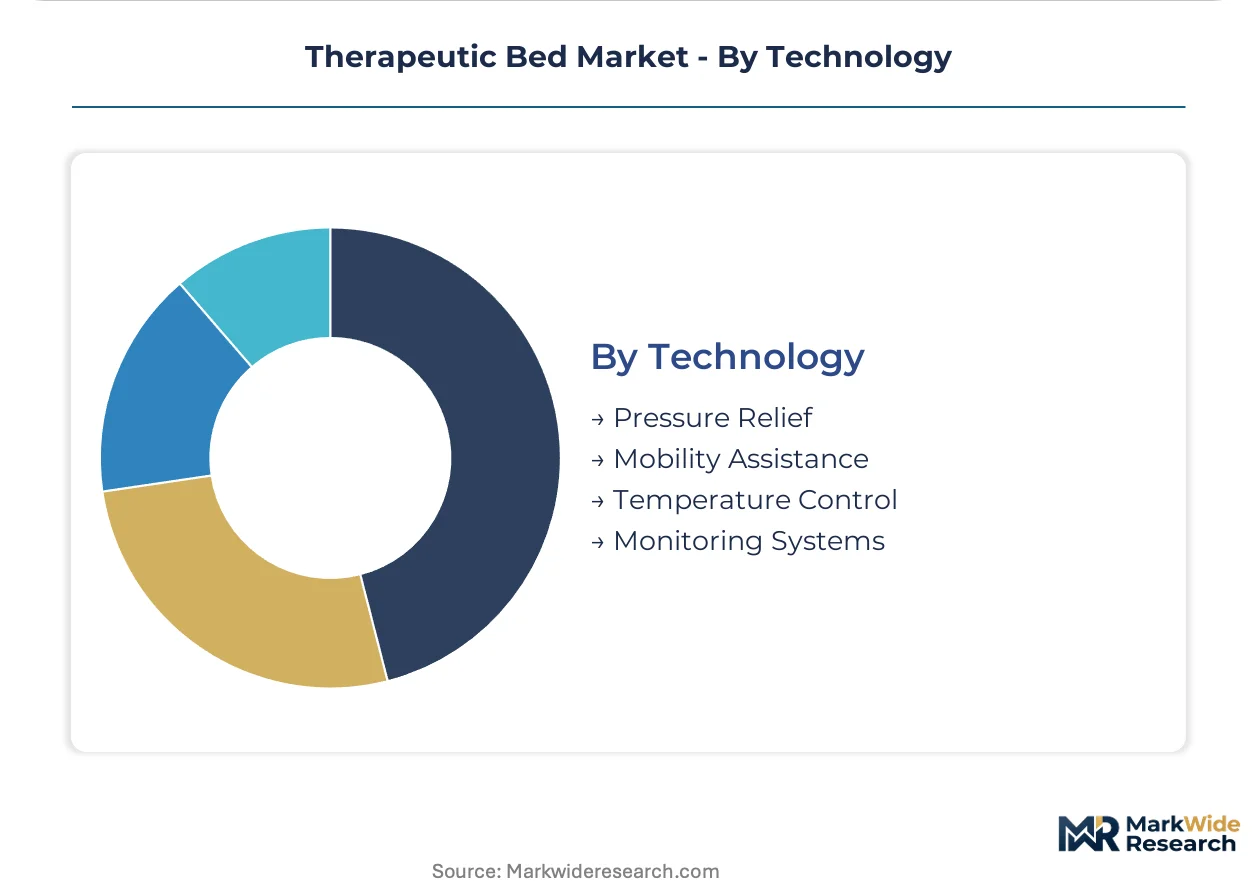
Technology:
Maturity curves separate established pressure-relief mechanisms from emerging monitoring platforms that redefine competitive positioning.
- Pressure Relief:Alternating air cells, low-air-loss surfaces, and foam formulations prevent tissue ischemia. Dutch and German hospital construction specifications now mandate real-time pressure mapping in standard ward configurations.
- Mobility Assistance:Integrated patient lifts, trapeze bars, and Trendelenburg positioning reduce caregiver injury risk. US long-term care facilities face workers compensation pressure that accelerates adoption.
- Temperature Control:Forced-air warming and cooling surfaces manage patient thermoregulation during extended immobility. Burn centers and post-surgical units in Japan and South Korea specify these systems.
- Monitoring Systems:Capacitive sensors detect patient position, respiration patterns, and bed-exit events. Epic and Cerner EMR integration positions bed vendors as clinical data infrastructure suppliers rather than commodity hardware providers.
By current revenue, pressure relief leads. By development investment, monitoring systems are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of 21 CFR 880.5100 anchors the United States as the dominant geography, while EU MDR compliance timelines and aging demographics across Germany, Japan, and the United Kingdom shape procurement patterns in secondary markets.
United States
Post-acute care diversion programs and CMS penalties for hospital-acquired pressure injuries drive replacement cycles in long-term care facilities. The FDA's electrical safety testing requirements under 21 CFR 880.5100 extend product development timelines. Hospital procurement in the Southwest and Mountain West regions concentrates through Intermountain Healthcare and Banner Health system-wide tenders.
Germany
Rehabilitation chains specify pressure-mapping technology in 80% of new ward construction. EU MDR post-market surveillance mandates accelerate hospital upgrades to higher-certification beds. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg host notified-body audit queues at BSI and TÜV SÜD exceeding 14 months.
Japan
Aging homeowners seeking sleep-quality improvements sustain demand for adjustable residential frames. METI and PMDA oversight aligns with ISO 13485 quality-management standards for imported devices. The Kanto region around Tokyo concentrates distribution infrastructure for home-care retail channels.
United Kingdom
NHS procurement centralization favors suppliers with certified service networks over pure hardware vendors. MHRA recognition of EU MDR certificates maintains market access post-Brexit. Manufacturing and R&D activity clusters in the Midlands and Southeast England near regulatory consultancy firms.
India
Inconsistent electricity access and capital constraints in rural markets sustain demand for manually adjustable frames. CDSCO medical device rules and BIS standards govern import and domestic production. Industrial corridors in Maharashtra and Gujarat host contract manufacturing operations serving price-sensitive segments.
Therapeutic Bed Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated hospital service networks competing against lightweight home-care specialists. The market structures around three tiers: premium electric bed manufacturers with embedded sensor platforms, mid-tier suppliers serving regional health systems, and value-oriented fabricators targeting emerging economies. Dominant competitive moves include ISO 13485-certified contract manufacturing partnerships in Eastern Europe and Southeast Asia, plus sensor-EMR integration development to escape commodity positioning.
Within the premium integrated-service tier, Stryker and LINET Group SE exemplify archetypes that anchor multi-year hospital contracts through captive maintenance infrastructure. Invacare Corporation occupies a position among home-care specialists, representing the lightweight frame segment that reduces caregiver strain in residential settings. These three entities illustrate how regulatory compliance depth and channel specialization separate sustainable positioning from transactional hardware supply.
| Leading Market Players |
|---|
| Medline Industries |
| Gendron |
| Baxter |
| LINET Group SE |
| Arjo |
| Stryker |
| GF Health Products |
| Hard Manufacturing Company |
| Invacare Corporation |
| Others |
Cost & Logistics Intelligence
Eighteen-month notified-body audit queues at BSI and TÜV SÜD compress inventory buffers for European-bound production while amplifying pricing power for manufacturers with pre-certified component stockpiles. This lead-time environment rewards suppliers holding strategic foam and steel reserves, penalizing just-in-time operators facing EU MDR compliance deadlines.
Pricing Analysis
Geographic price spreads of 30-40% separate North American hospital contracts from Southeast Asian manual-bed tenders. Three-tier pricing structure across premium sensor-integrated, standard electric, and economy manual levels dominates, with ISO 13485 certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in economy tiers is intensifying because petroleum-derived foam volatility feeds raw material uncertainty. Home-care retail channels exhibit highest price sensitivity, while integrated hospital service contracts show lowest.
Supply Chain Analysis
Strategic stockpiling of high-density foam and steel frames prevails over just-in-time approaches given 12-18 month FDA 510(k) development cycles. Manufacturing concentrates in China, Germany, and the United States, with input dependencies on petroleum-based polyurethane, cold-rolled steel, and capacitive sensor arrays. Single-source vulnerability for pressure-mapping chipsets creates exposure. Distribution runs through Group Purchasing Organizations for hospital channels and durable medical equipment dealers for home-care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from embedded sensor calibration and cloud-based fleet management expands faster than hardware replacement cycles, repositioning therapeutic bed vendors as clinical data infrastructure providers.
For Market Incumbents: Secure multi-year service contracts with certified biomedical technician networks to lock out pure-hardware competitors facing 18-24 month technician scarcity backlogs. Deepen backward integration into pressure-mapping sensor production to reduce chipset single-source exposure. Prioritize ISO 13485-certified contract manufacturing partnerships in Eastern Europe to compress cost structures against margin pressure from commodity metals volatility. For New Entrants and Emerging Players: Differentiate on lightweight manual-bed portability for rural Indian and Southeast Asian markets where electricity access remains inconsistent. Target home-care retail channels in Germany and Japan where aging homeowners seek sleep-quality improvements outside hospital procurement systems. Pursue direct-to-consumer e-commerce angles to bypass Medicare Part B reimbursement compression. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized medical device divisions lacking dedicated regulatory affairs infrastructure. Five-to-ten year viability hinges on sensor-EMR integration capabilities positioning acquirers above commodity hardware tiers. Watch for FDA 510(k) clearance acceleration as signal that regulatory backlog easing may compress first-mover advantages.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485-Certified Contract Manufacturing | Eastern European and Southeast Asian production cuts assembly costs 30-40% below North American captive facilities. |
| Sensor-EMR Platform Integration | Epic and Cerner workflow embedding transforms bed vendors into clinical data infrastructure suppliers. |
| Biomedical Technician Training Programs | In-house certification pipelines address 18-24 month hospital maintenance backlogs threatening contract renewals. |
| Cloud-Based Fleet Management | EU MDR post-market surveillance mandates drive subscription revenue from vigilance reporting automation. |
| Pressure-Mapping Chipset Backward Integration | Captive sensor production reduces single-source dependency and accelerates product development timelines. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR notified-body audit records, hospital procurement databases, and CMS Medicare cost report data preceded structured interviews with biomedical engineering directors, Group Purchasing Organization contracts managers, rehabilitation clinic procurement leads, and home-care durable medical equipment dealers. Bottom-up demand modeling from installed base replacement cycles and top-down validation from macro healthcare expenditure trends were triangulated.
Variance decomposition across product type, end-user setting, material composition, and technology maturity level shaped analytical framework development over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU MDR compliance timeline delays, CMS hospital-acquired condition penalty adjustments, and post-acute care diversion program proliferation rates.
Material uncertainties — regulatory audit queue extensions, commodity metals price spikes, and biomedical technician training pipeline disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding reimbursement stability and certification pathway efficiency. Revision becomes warranted when FDA 510(k) average review duration or EU notified-body backlog months cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market