
 Hashimoto's Thyroiditis Therapeutics Market | 2026-2036
Hashimoto's Thyroiditis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hashimoto's Thyroiditis Therapeutics Market Foresight
Specialty endocrinology clinics is reorganizing demand patterns within the Hashimoto's Thyroiditis Therapeutics landscape, pulling volume away from general practice settings as protocol-driven care intensifies. AbbVie Inc. leverages its immunology infrastructure to navigate autoimmune adjacencies, while Merck & Co. sustains manufacturing scale across hormone synthesis platforms. Pfizer Inc. competes through distribution breadth in chronic therapy categories.
Hashimoto's Thyroiditis Therapeutics comprise pharmaceutical interventions targeting autoimmune-mediated thyroid destruction, primarily through synthetic thyroxine (T4) replacement at precise microgram dosing calibrated to patient-specific TSH suppression targets. These therapies restore euthyroid metabolic status and prevent progression to myxedema complications in affected populations. Levothyroxine formulations anchor the product type landscape as the established standard-of-care with deep generic penetration, while combination therapy segments containing both T4 and T3 analogs represent the fastest-growing structural pocket as clinicians debate optimal hormone ratios. Oral delivery mode dominates volume due to patient convenience and decades of clinical familiarity, though sublingual formats are gaining traction among populations with malabsorption syndromes.
FDA bioequivalence standards for narrow therapeutic index levothyroxine products directly constrain formulation switching and generic substitution protocols, shaping prescriber loyalty and pharmacy benefit design. EMA stability requirements for thyroid hormone products under varying temperature conditions influence packaging specifications and cold-chain investments across European distribution networks. Stakeholders must monitor evolving regulatory posturing on natural desiccated thyroid extracts, as FDA enforcement discretion and compounding pharmacy oversight create asymmetric market access risks that demand proactive portfolio positioning.
Market Dynamics
FDA narrow therapeutic index bioequivalence standards for levothyroxine are forcing prescriber loyalty patterns and constraining generic substitution protocols, fundamentally restructuring how pharmacy benefit managers design formularies and how manufacturers defend formulation market position.
Growth Catalysts
- Autoimmune Diagnosis Protocols:Endocrinology clinics in the United States are expanding protocol-driven care pathways that standardize TSH monitoring frequency and hormone titration schedules, pulling patient volume from general practice settings into specialized channels with higher therapy adherence rates.
- EMA Stability Requirements:Cold-chain packaging investments across European distribution networks are enabling extended shelf-life claims for thyroid hormone products, reducing wastage rates and supporting inventory consolidation at wholesale level.
- Combination Therapy Debate:Clinical discussions around optimal T4:T3 ratios are stimulating prescriber experimentation with liothyronine-containing regimens, creating new demand pockets beyond established levothyroxine monotherapy.
Market Restraints
- API Concentration Risk:Synthetic thyroxine active pharmaceutical ingredient production concentrates among a limited set of specialized chemical manufacturers, exposing formulation supply to single-source disruption vulnerabilities.
- Malabsorption Variability:Gastrointestinal conditions including celiac disease and atrophic gastritis create unpredictable bioavailability in oral levothyroxine, forcing dose escalation and therapeutic monitoring complexity that strains clinic capacity.
- Natural Desiccated Extract Uncertainty:FDA enforcement discretion on compounded thyroid extracts creates asymmetric market access risks, with retail pharmacy chains declining stocking decisions due to liability exposure.
Strategic Opportunities
- Sublingual Delivery Formats:Populations with documented malabsorption syndromes represent an addressable segment for bypass-gastrointestinal absorption technologies, with endocrinology clinics in Germany and France already piloting patient-specific switching protocols.
- Continuous Glucose-Thyroid Monitoring Integration:Convergence of wearable metabolic sensors with automated TSH reporting is enabling closed-loop dose adjustment algorithms that reduce clinic visit burden for stable patients.
- IRA Chronic Therapy Provisions:Out-of-pocket cap mechanisms for Medicare beneficiaries are reducing price sensitivity for branded formulation persistence, supporting premium positioning for differentiated delivery technologies.
Industry Challenges
- Endocrinology Workforce Constraints:Fellowship training pipeline limitations in the United States are extending appointment wait times, compressing the window for initial diagnosis and therapy initiation.
- Formulation Switching Surveillance:Pharmacovigilance systems must capture adverse events during generic substitution events, requiring investment in real-world evidence infrastructure that smaller manufacturers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hashimoto's Thyroiditis Therapeutics Market |
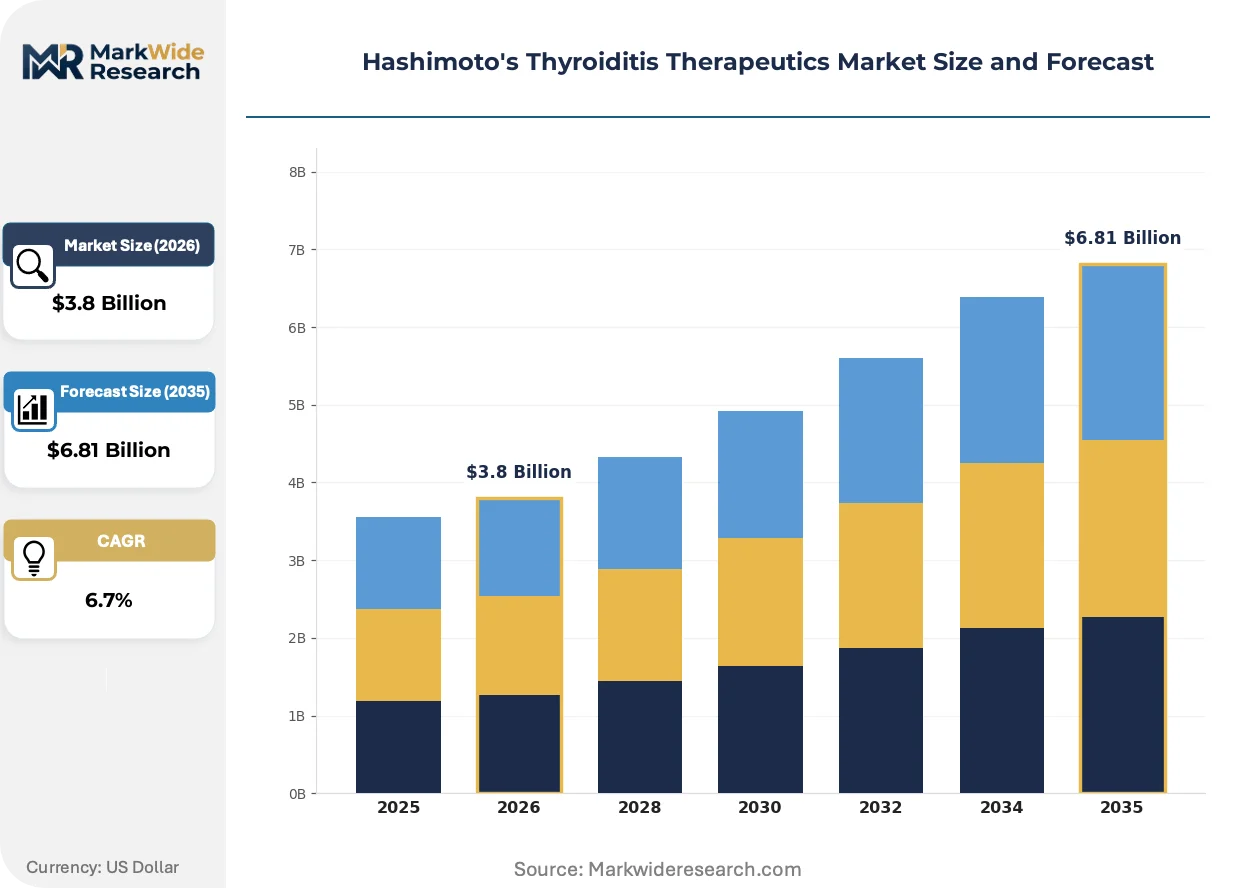
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Levothyroxine, Liothyronine, Natural Desiccated Thyroid, Combination Therapy Therapy Area: Autoimmune Disorders, Endocrinology, Hormonal Imbalance, Metabolism Regulation Delivery Mode: Oral, Injectable, Transdermal, Sublingual End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | AbbVie Inc., Merck & Co., Pfizer Inc., Amneal Pharmaceuticals, Lannett Company, Acella Pharmaceuticals, AstraZeneca plc, Sanofi S.A., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hashimoto's Thyroiditis Therapeutics Market Shifts & Advancements
Precision dosing technologies and alternative delivery modalities are compressing the dominance of conventional oral levothyroxine, while regulatory posturing on natural extracts and reimbursement design for chronic therapy are reshaping competitive positioning.
Liquid levothyroxine formulations with documented absorption advantages in populations with gastric pH alterations are displacing tablet-based standard-of-care in pediatric and geriatric segments. Pediatric endocrinology departments in academic medical centers are adopting these formats for children with concurrent proton pump inhibitor therapy. The structural consequence is fragmenting the tablet market into age-stratified and comorbidity-stratified demand pools that require separate manufacturing lines and stability testing protocols.
EMA revised stability guidelines for thyroid hormone products under temperature excursion conditions are forcing packaging redesign investments across European distribution networks. Manufacturers must now demonstrate potency retention through 40-degree Celsius exposure periods that exceed previous standards. The sublingual and liquid format categories are most affected, as their aqueous bases present greater degradation risk than established tablet matrices, driving consolidation toward suppliers with advanced barrier film capabilities.
Patients with stable euthyroid status are extending refill intervals through 90-day mail-order channels, disintermediating the retail pharmacy touchpoint that historically enabled generic substitution conversations. Pharmacy benefit managers in the United States are responding with tiered copay structures that penalize monthly dispensing frequency. The geographic concentration of this shift is highest in Medicare Part D populations and employer-sponsored plans with integrated mail-order mandates.
Hashimoto's Thyroiditis Therapeutics Market Segmentation
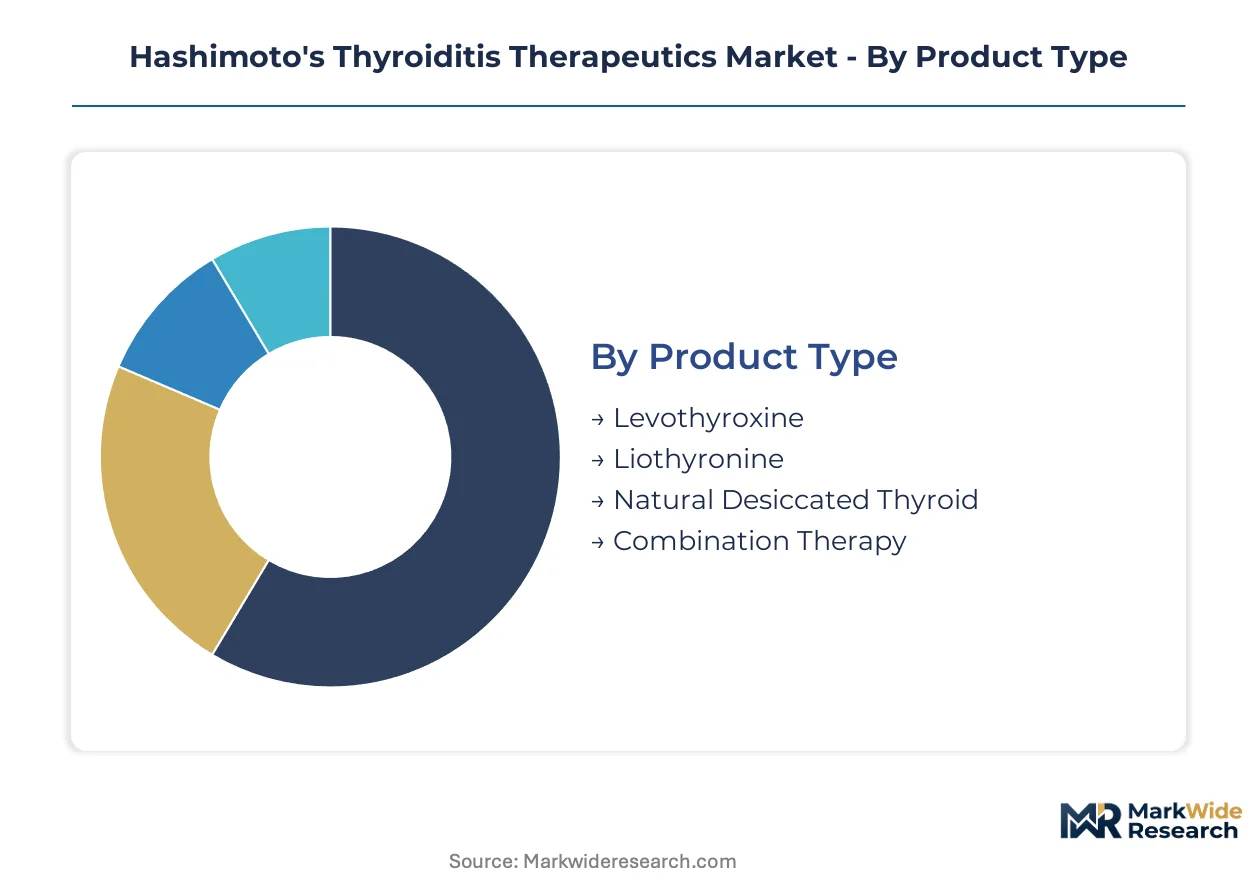
Hashimoto's therapeutics segmentation reveals how formulation chemistry, delivery technology, and care setting economics interact to determine prescribing patterns. Each dimension carries distinct substitution pressures that reshape competitive boundaries between synthetic and natural hormone sources.
Product Type:
Substitution pressure from generic levothyroxine commoditization is forcing differentiation investments across all hormone categories, with narrow therapeutic index standards protecting some segments while exposing others to price collapse.
- Levothyroxine:Synthetic T4 hormone formulated as sodium salt in precise microgram strengths from 25mcg to 300mcg. Demand concentrates in United States Medicare Part D populations where FDA bioequivalence standards constrain pharmacy-level generic switching and sustain prescriber loyalty to specific manufacturers. Volume leadership reflects decades of clinical familiarity and established TSH monitoring protocols.
- Combination Therapy:Fixed-ratio or customizable blends of synthetic T4 and T3 analogs addressing persistent hypothyroid symptoms in euthyroid patients. Germany's endocrinology clinics and France's hospital outpatient departments are piloting patient-specific T4:T3 titration protocols, pulling demand from standardized monotherapy regimens.
- Liothyronine:Synthetic T3 hormone for rapid onset requirements and thyroid storm management, manufactured as sodium salt with shorter half-life demanding divided dosing schedules.
- Natural Desiccated Thyroid:Porcine-derived dried thyroid gland extract containing variable T4:T3 ratios, facing FDA enforcement discretion and retail pharmacy chain stocking refusals due to potency variability liability.
Levothyroxine retains volume leadership across all geographies; combination therapy holds the steepest expansion curve as clinical debate over optimal hormone ratios intensifies.
Therapy Area:
Cost tier stratification separates acute intervention budgets from chronic maintenance reimbursement pools, with endocrinology specialization commanding premium pricing against primary care commoditization.
- Endocrinology:Specialized autoimmune thyroid disorder protocols in dedicated clinics with standardized TSH monitoring frequencies and hormone titration algorithms. United States academic medical centers and Germany's Kassenärztliche Vereinigung network are consolidating volume into protocol-driven channels with higher adherence rates.
- Autoimmune Disorders:Cross-disciplinary management addressing Hashimoto's as comorbidity with type 1 diabetes, celiac disease, and rheumatoid arthritis in integrated care settings.
- Hormonal Imbalance:Broader therapeutic framing encompassing menopausal transition, androgen disorders, and metabolic syndrome overlap syndromes.
- Metabolism Regulation:Adjunctive thyroid therapy in weight management and lipid disorder protocols outside formal hypothyroidism diagnosis.
Endocrinology captures the premium pricing tier; autoimmune disorders show the most rapid patient volume migration toward specialized channels.
Delivery Mode:
Volume concentration in oral formats is fragmenting as malabsorption syndromes and pediatric requirements create addressable niches for alternative absorption pathways.
- Oral:Tablet and capsule formulations dominating chronic therapy with decades of stability data and pharmacy distribution infrastructure. United States mail-order channels are consolidating 90-day dispensing volumes, disintermediating retail touchpoints.
- Sublingual:Bypass-gastrointestinal absorption for populations with celiac disease, atrophic gastritis, or concurrent proton pump inhibitor therapy. Liquid and rapidly-dissolving tablet formats are gaining formulary placement in France's hospital outpatient pharmacies.
- Injectable:Intravenous levothyroxine for myxedema coma and perioperative thyroid replacement in intensive care settings.
- Transdermal:Experimental patches and gels addressing compliance failures in elderly populations with polypharmacy burden.
Oral delivery maintains absolute volume dominance; sublingual formats are climbing the fastest as malabsorption documentation improves.
End User:
Customer type segmentation reflects reimbursement pathway fragmentation, with institutional purchasing power concentrating volume against fragmented homecare economics.
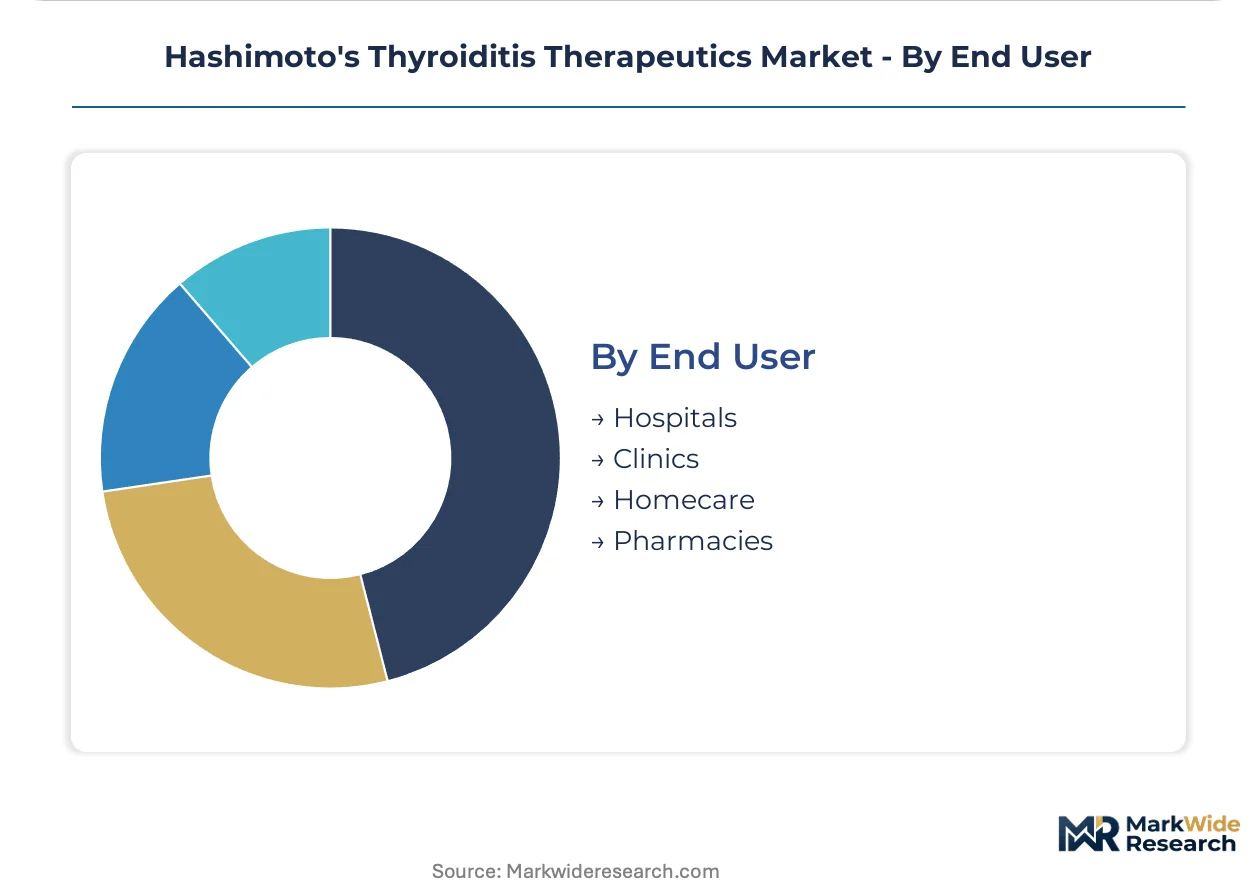
- Clinics:Endocrinology specialty practices with protocol-driven care pathways and direct pharmacy relationships. United States clinic networks are consolidating through private equity acquisition, creating formulary standardization opportunities.
- Homecare:Direct-to-patient delivery for stable euthyroid populations with extended refill intervals and remote TSH monitoring.
- Hospitals:Inpatient initiation of therapy and management of myxedema complications in emergency and critical care departments.
- Pharmacies:Retail and mail-order dispensing with generic substitution protocols shaped by narrow therapeutic index restrictions.
Clinics retain volume leadership as care migration accelerates; homecare shows the steepest expansion curve with remote monitoring technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty endocrinology clinics concentrate procurement power in the United States, Germany, Japan, France, and the United Kingdom, where protocol-driven autoimmune thyroid disorder management pulls volume from general practice into reimbursed specialty channels.
United States
Medicare Part D out-of-pocket caps and narrow therapeutic index bioequivalence standards constrain generic substitution for levothyroxine products. FDA enforcement discretion on natural desiccated thyroid extracts creates asymmetric access risks. Academic medical centers in Boston and the Mayo Clinic network pilot liquid formulation protocols for pediatric populations with concurrent proton pump inhibitor therapy.
Germany
Kassenärztliche Vereinigung networks consolidate Hashimoto's patient volume into protocol-driven endocrinology clinics with standardized TSH monitoring frequencies. EMA stability requirements for temperature excursion conditions force packaging redesign investments. Bavaria's hospital outpatient pharmacies lead sublingual format pilot programs for documented malabsorption syndromes.
Japan
PMDA post-market surveillance requirements for narrow therapeutic index hormone products sustain prescriber loyalty to specific manufacturers. METI industrial policy supports domestic active pharmaceutical ingredient synthesis capabilities. Tokyo and Osaka metropolitan endocrinology departments integrate wearable metabolic sensors with automated TSH reporting for stable patient cohorts.
France
ANSM pharmacovigilance systems capture adverse events during generic substitution events, requiring real-world evidence infrastructure investment. Hospital outpatient pharmacies in Île-de-France and Auvergne-Rhône-Alpes gain formulary placement for liquid and sublingual levothyroxine formats addressing gastric pH alteration populations.
United Kingdom
NHS England specialty commissioning frameworks route Hashimoto's diagnoses through endocrinology referral pathways with extended appointment wait times. NICE technology appraisal processes evaluate combination therapy cost-effectiveness against levothyroxine monotherapy. London and Manchester academic centers debate optimal T4:T3 ratio protocols in clinical guidelines committees.
Hashimoto's Thyroiditis Therapeutics Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with immunology or endocrinology infrastructure, supplemented by generic specialists and regional hormone manufacturers. Market structure consolidates around scale-driven synthesis capabilities and narrow therapeutic index formulation expertise. Three archetypes dominate: Big Pharma incumbents with chronic therapy distribution breadth, generic levothyroxine specialists with FDA bioequivalence defense capabilities, and regional compounders serving natural desiccated extract demand pockets. Competitive moves center on M&A for hormone synthesis capacity and strategic partnerships for sublingual delivery technology licensing.
Among the diversified pharmaceutical conglomerates, AbbVie Inc., Merck & Co., and Pfizer Inc. occupy positions anchored to distinct capability vectors. AbbVie exemplifies the immunology infrastructure archetype with autoimmune adjacency navigation. Merck & Co. represents manufacturing scale concentration across hormone synthesis platforms. Pfizer sits within the chronic therapy distribution breadth tier with pharmacy benefit manager relationship depth. Amneal Pharmaceuticals and Lannett Company exemplify generic specialists competing on bioequivalence documentation and narrow therapeutic index formulation stability.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Merck & Co. |
| Pfizer Inc. |
| Amneal Pharmaceuticals |
| Lannett Company |
| Acella Pharmaceuticals |
| AstraZeneca plc |
| Sanofi S.A. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between specialty endocrinology clinic networks and levothyroxine manufacturers lock in supply access while stabilizing price visibility across narrow therapeutic index product tiers. These arrangements concentrate procurement power among United States Medicare Part D plans and Germany's Kassenärztliche Vereinigung networks, insulating contracted volumes from spot-market volatility in synthetic thyroxine API.
Pricing Analysis
Cost-plus contracts with API indexation anchor levothyroxine pricing, tying formulation costs to synthetic thyroxine sodium salt feedstock movements. Three-tier pricing structure across premium, standard, and economy levels separates branded narrow therapeutic index formulations from authorized generics and commodity tablets. Cost compression in the economy tier is intensifying because of deep generic penetration and 90-day mail-order consolidation. Medicare Part D beneficiaries show lowest price sensitivity due to out-of-pocket caps, while uninsured cash-pay patients in retail pharmacy channels exhibit highest sensitivity.
Supply Chain Analysis
Inventory buffers at wholesale level extend to 60-90 days for oral tablet formats, while sublingual and liquid formats face tighter lead times due to cold-chain requirements. Synthetic thyroxine API production concentrates in China, India, and the United States, with formulation finishing distributed across European and North American sites. Supply chains rest on iodine sourcing from Chilean caliche deposits and Japanese seaweed processing, plus specialized chemical synthesis equipment from German and Swiss suppliers. Single-source vulnerability in high-purity T3 analog synthesis creates concentration risk. Distribution runs through specialty pharmacy channels and integrated mail-order platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hashimoto's therapeutics are recovering from a cyclical trough driven by endocrinology workforce expansion and protocol-driven care migration, with specialty clinic consolidation creating durable demand pull.
For Market Incumbents: Shield formulation market position by deepening FDA bioequivalence documentation for narrow therapeutic index levothyroxine products and securing capacity reservation agreements with synthetic thyroxine API manufacturers. The threat of sublingual delivery technology displacement demands proactive pilot partnerships with malabsorption-focused clinic networks in Germany and France. For New Entrants and Emerging Players: Lead with sublingual and liquid format development targeting documented malabsorption populations in Bavaria's hospital outpatient pharmacies and France's Île-de-France region. The most penetrable segment lies in pediatric and geriatric patients with concurrent proton pump inhibitor therapy. A go-to-market angle through academic medical center formulary committees bypasses retail pharmacy stocking barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale hormone synthesis specialists with captive API capabilities and narrow therapeutic index formulation expertise. Long-term viability over a 5-10 year window hinges on regulatory defense capabilities and clinic network integration depth. The signal to watch is FDA enforcement posture on natural desiccated thyroid extracts, which would reshape competitive boundaries between synthetic and porcine-derived hormone sources.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Combination therapy T4:T3 ratio trials in Germany's Kassenärztliche Vereinigung networks validate new protocol standards. |
| Regulatory Approval Pathway | FDA narrow therapeutic index bioequivalence submissions for sublingual formats unlock Medicare Part D access. |
| Manufacturing Scale-Up | Liquid levothyroxine production expansion serves pediatric endocrinology departments with gastric pH alteration patients. |
| Long-term Supply Agreement | API offtake contracts with Chinese and Indian synthesis specialists secure thyroxine sodium salt feedstock. |
| Strategic Partnership | Wearable metabolic sensor integration with automated TSH reporting reduces clinic visit burden for stable cohorts. |
Research Methodology
The analysis maps levothyroxine monotherapy, combination T4:T3 therapy, liothyronine acute intervention, and natural desiccated extract segments, each validated through endocrinology clinic directors, pharmacy benefit manager formulary leads, FDA regulatory affairs specialists, and wholesale distribution procurement managers. Primary interview intelligence triangulates against FDA Orange Book listings, EMA stability guideline documents, ClinicalTrials.gov protocol registrations, and CMS Medicare Part D claims patterns. Bottom-up patient volume estimates reconcile with top-down pharmaceutical expenditure benchmarks.
Consistency checks against external prescription audit databases and hospital procurement system extracts validate volume and value outputs across the projection horizon. The analytical framework models product type, delivery mode, therapy area, and end-user channel dimensions. CAGRs derive from patient cohort growth trajectories, protocol-driven care migration rates, and reimbursement pathway evolution. Forecast inputs include endocrinology fellowship training pipeline data and narrow therapeutic index generic substitution frequency trends.
Forecasts assume regulatory continuity in FDA bioequivalence standards and EMA stability requirements; material policy shifts would require re-modeling. Supply disruption scenarios, natural desiccated extract enforcement actions, and malabsorption syndrome prevalence revisions constitute specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market