
 Global Postmenopausal Osteoporosis Market | 2026-2036
Global Postmenopausal Osteoporosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Postmenopausal Osteoporosis Market Foresight
Specialty clinics is collapsing as the dominant buyer archetype as rheumatology centers capture a larger share of infusion-based therapies. Amgen Inc. dominates the monoclonal antibody segment with denosumab's established reimbursement pathways. Eli Lilly and Company anchors the parathyroid hormone analogue niche through teriparatide manufacturing scale. Pfizer Inc. navigates the oral bisphosphonate landscape with legacy portfolio strength and generic defense strategies.
Postmenopausal osteoporosis is a systemic skeletal disorder marked by low bone mass and microarchitectural deterioration of bone tissue, quantified clinically through dual-energy X-ray absorptiometry T-scores of −2.5 or below at the hip or spine, with pharmaceutical intervention aimed at reducing fragility fracture incidence in estrogen-depleted patient populations. Monoclonal antibodies command premium positioning due to their mechanism of direct RANKL inhibition, while bisphosphonates represent the mature volume base despite generic erosion. The subcutaneous injection delivery mode is gaining fastest as patient self-administration preferences shift away from intravenous infusion dependence in outpatient settings.
FDA osteoporosis guidance, EMA postmenopausal fracture prevention standards, and Japan's PMDA bone mineral density trial requirements collectively elevate the evidence bar for new molecular entities seeking market access. These frameworks compress development timelines for sponsors able to generate fracture endpoint data while excluding candidates with insufficient skeletal safety profiles. Stakeholders must weigh pipeline concentration in biologic formats against the reimbursement headwinds facing oral generics in mature markets.
Market Dynamics
The transition from intravenous infusion to subcutaneous self-administration is redrawing competitive boundaries between rheumatology centers and specialty clinics, compressing site-of-care economics while elevating patient adherence metrics as the decisive purchasing criterion.
Growth Catalysts
- EMA postmenopausal fracture prevention standards:These protocols compress clinical trial timelines for sponsors generating robust skeletal endpoint data, accelerating market access for novel biologic entrants.
- Japan's aging demographic concentration:The PMDA's bone mineral density trial requirements align with concentrated demand from estrogen-depleted populations in Tokyo and Osaka metropolitan corridors.
- Dual-energy X-ray absorptiometry screening expansion:Rheumatology centers in Germany are deploying advanced T-score quantification protocols to identify at-risk cohorts before fragility fracture events.
Market Restraints
- Generic bisphosphonate erosion:Oral alendronate and risedronate commoditization in the United States compresses pricing power for legacy portfolio defenders.
- Long-term skeletal safety surveillance:FDA's evolving guidance on atypical femoral fracture and osteonecrosis of the jaw extends post-market monitoring obligations, elevating compliance costs.
- Reimbursement pathway fragmentation:Divergent national health technology assessment methodologies across Germany, Japan, and the United States create access inconsistency for premium biologics.
Strategic Opportunities
- Underpenetrated rural United States markets:Telemedicine-enabled bone health screening partnerships with primary care networks in Mississippi and Alabama address diagnostic gaps outside major metropolitan clusters.
- Biologic-biosimilar convergence:The intersection of RANKL inhibitor refinement with follow-on manufacturing scale creates white space for differentiated delivery mechanism innovation.
- Japan's PMDA conditional approval pathways:Early access frameworks for therapies demonstrating surrogate bone density endpoints enable revenue generation prior to fracture data maturation.
Industry Challenges
- Specialized endocrinology trialist scarcity:Recruitment of investigators with dual expertise in metabolic bone disease and biologic pharmacokinetics constrains multicenter study activation timelines.
- Legacy electronic health record integration:Fracture risk assessment algorithm deployment across heterogeneous hospital IT architectures in Germany delays algorithmic screening implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Postmenopausal Osteoporosis Market |
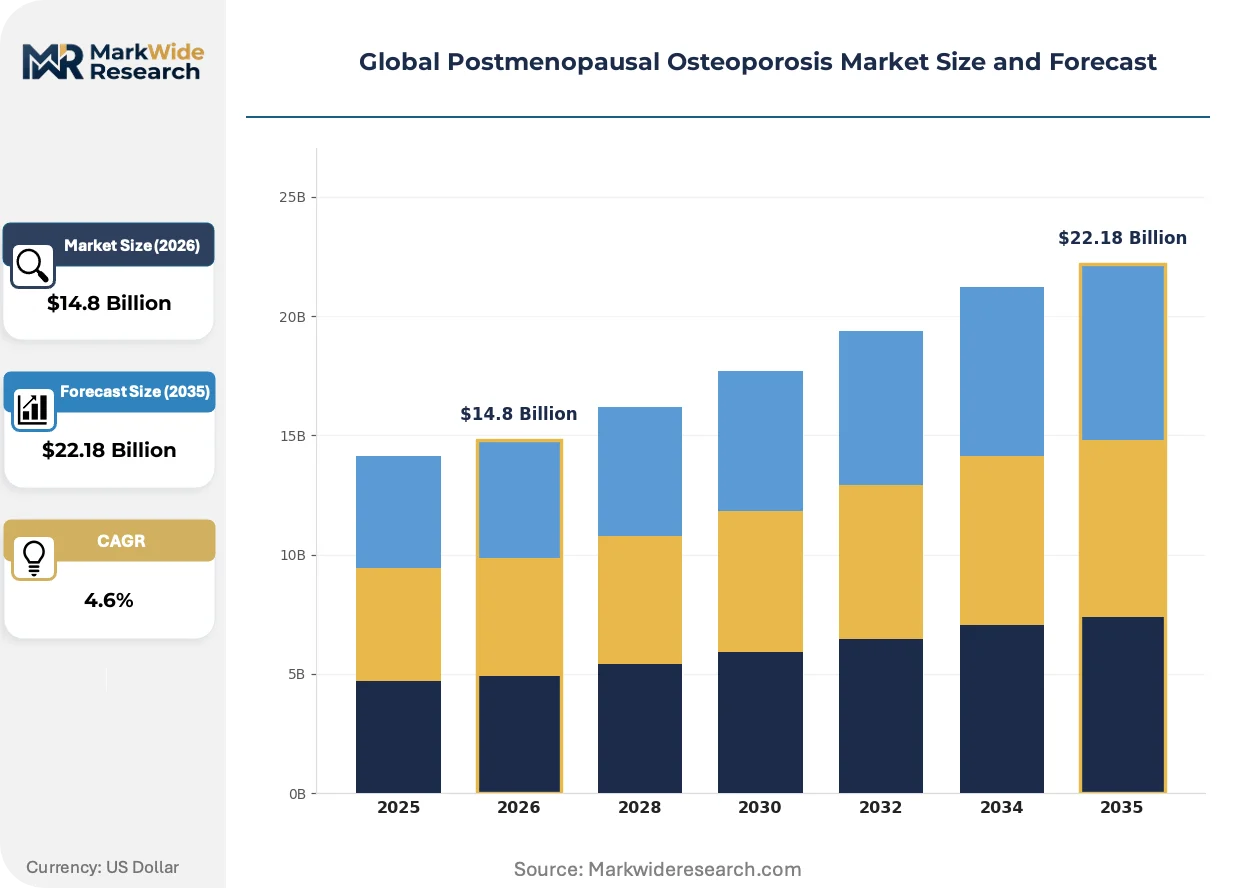
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Monoclonal Antibodies, Selective Estrogen Receptor Modulators, Parathyroid Hormone Analogues, Calcitonin Therapy Area: Bone Density Improvement, Fracture Risk Reduction, Bone Resorption Inhibition, Calcium Metabolism Regulation End User: Specialty Clinics, Rheumatology Centers, Diagnostic Laboratories, Long-term Care Facilities Delivery Mode: Oral Administration, Subcutaneous Injection, Intravenous Infusion, Transdermal System |
| Companies Covered | Pfizer Inc., F. Hoffmann-La Roche Ltd, Amgen Inc., Sanofi, Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, Novartis International AG, Johnson & Johnson, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Postmenopausal Osteoporosis Market Shifts & Advancements
Biomechanical monitoring technologies and regulatory endpoint evolution are converging to redefine therapeutic value demonstration, while patient autonomy preferences accelerate decentralized care models away from institutional infusion dependence.
Implantable bone microsensors for real-time biomechanical load monitoring are advancing from investigational stages toward clinical validation. Rheumatology centers in Switzerland and the Netherlands are piloting these devices for post-treatment adherence verification. The technology is miniaturizing fracture detection latency from symptomatic presentation to subclinical stress identification, compressing the window between bone compromise and therapeutic intervention.
Japan's PMDA revised its osteoporotic fracture prevention guidance to accept integrated bone mineral density and biomarker surrogate endpoints for conditional approvals. This regulatory recalibration reduces phase III duration requirements for novel anabolic agents. Sponsors targeting the Japanese market are restructuring development programs to prioritize surrogate-rich data packages over traditional fracture endpoint studies.
Patient self-administration preferences are displacing institutional infusion dependence across outpatient osteoporosis management. Subcutaneous injection devices with adherence-tracking connectivity are capturing share from IV bisphosphonate and monoclonal antibody infusion protocols in United States rheumatology practices. This behavioral pivot is most pronounced in California and Florida, where Medicare Advantage plan incentives reward home-based therapeutic administration with reduced cost-sharing obligations.
Global Postmenopausal Osteoporosis Market Segmentation
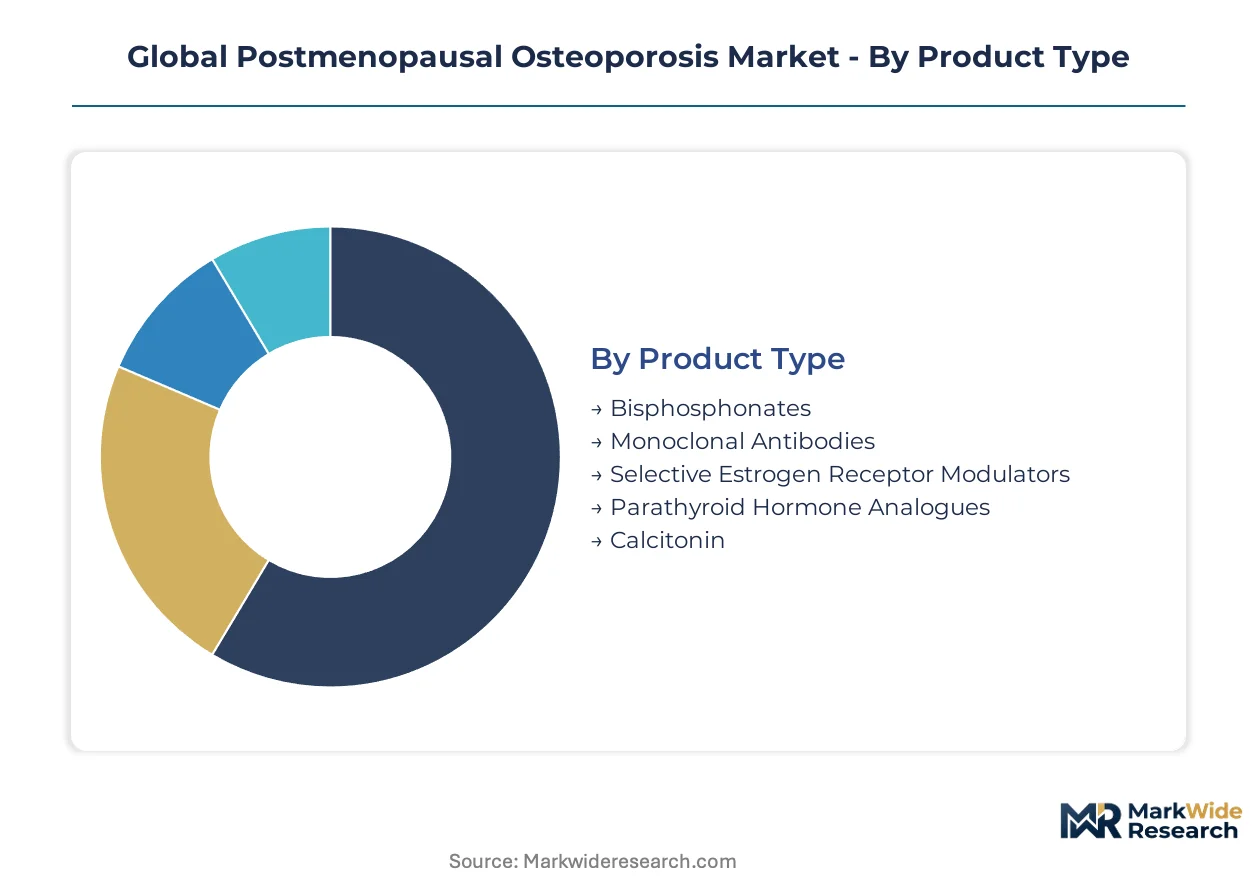
Segmentation in postmenopausal osteoporosis pharmaceuticals reveals how delivery innovation and site-of-care economics are fragmenting traditional prescribing patterns. Therapy selection increasingly hinges on patient self-administration capacity and reimbursement pathway stability rather than clinical efficacy alone.
Product Type:
Generic substitution pressure weighs most heavily on oral bisphosphonates as patent cliffs erode pricing power, while biologic formats face biosimilar encroachment from manufacturing scale expansion in South Korea and India.
- Bisphosphonates:Alendronate and risedronate sodium formulations constitute the oral volume foundation, with once-weekly dosing protocols dominating United States Medicare Part D formularies. United States retail pharmacies report 60-day supply fulfillment rates exceeding 85 percent for generic alendronate, though adherence drops sharply after 12 months due to gastrointestinal tolerability constraints.
- Monoclonal Antibodies:Denosumab and romosozumab operate through RANKL or sclerostin pathway blockade, requiring cold-chain distribution networks and quarterly to biannual administration schedules. Rheumatology centers in Germany and Japan capture disproportionate share due to infusion infrastructure and specialist prescribing concentration.
- Selective Estrogen Receptor Modulators:Raloxifene targets vertebral fracture prevention in estrogen-depleted populations with thromboembolic risk profiles that limit broad deployment.
- Parathyroid Hormone Analogues:Teriparatide and abaloparatide stimulate osteoblastic activity through intermittent PTH signaling, constrained by lifetime duration caps and daily injection burden.
- Calcitonin:Nasal spray and injectable salmon calcitonin formulations occupy niche acute pain management roles following vertebral compression events.
Bisphosphonates retain volume leadership; monoclonal antibodies hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates acute fracture intervention from chronic maintenance protocols, with hospital episode-based reimbursement in Japan and Germany favoring bundled fracture risk reduction programs over discrete pharmaceutical dispensing.
- Bone Density Improvement:Anabolic agents targeting trabecular connectivity and cortical thickness serve as first-line for T-scores below −3.0, particularly in United States markets with dual-energy X-ray absorptiometry screening penetration above 40 percent in Medicare populations.
- Fracture Risk Reduction:Antiresorptive therapies dominate this objective, with clinical endpoints tied to hip and vertebral fracture incidence reduction over 24-36 month horizons.
- Bone Resorption Inhibition:Cathepsin K inhibitors and bisphosphonates suppress osteoclast-mediated matrix degradation, with biomarker monitoring (CTX, P1NP) guiding treatment response assessment.
- Calcium Metabolism Regulation:Vitamin D analogues and mineral supplementation address secondary hyperparathyroidism in institutionalized elderly populations.
Fracture risk reduction commands the largest addressable population; bone density improvement claims the highest per-patient revenue intensity.
End User:
Customer type concentration is shifting from fragmented specialty clinic networks toward integrated rheumatology centers with captive infusion capacity and risk-bearing contract structures.
- Specialty Clinics:Independent endocrinology and gynecology practices in the United States Midwest and Southeast maintain bisphosphonate prescribing dominance but lack infrastructure for biologic administration.
- Rheumatology Centers:Academic medical centers in Boston, Heidelberg, and Osaka metropolitan clusters capture monoclonal antibody infusion volume through bundled payment arrangements with regional payers.
- Diagnostic Laboratories:Reference laboratories in California and Texas are expanding bone turnover marker testing panels to guide therapy selection and monitoring.
- Long-term Care Facilities:Skilled nursing facilities in Florida and Arizona face persistent underdiagnosis due to limited access to dual-energy X-ray absorptiometry equipment.
Rheumatology centers are gaining share fastest; specialty clinics still process the highest prescription volume.
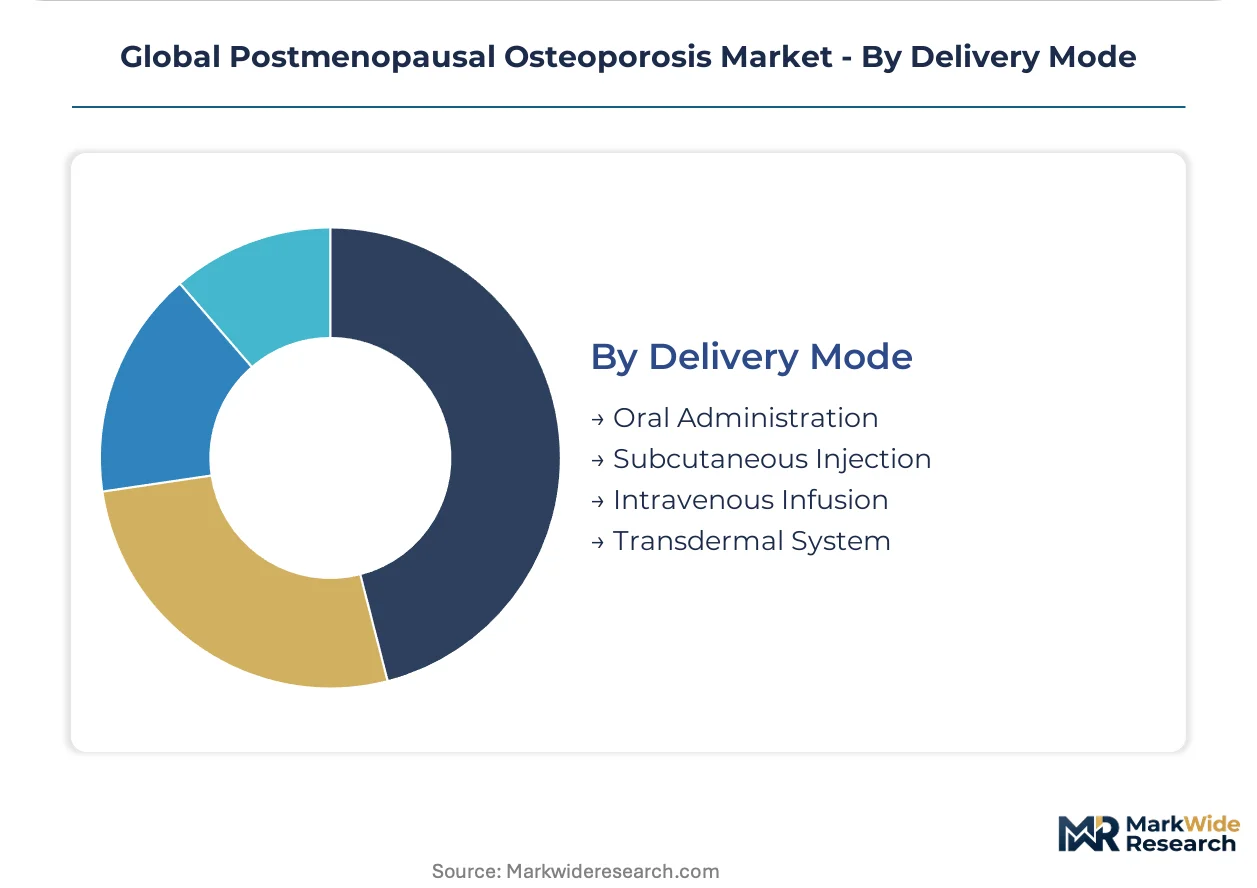
Delivery Mode:
Supply concentration in prefilled syringe manufacturing is elevating subcutaneous formats while oral solid dose capacity commoditizes across contract manufacturing organizations in India and Eastern Europe.
- Oral Administration:Weekly alendronate and monthly risedronate tablets remain the default initiation pathway in primary care settings across the United States and Germany, with 70-milligram and 150-milligram strengths dominating formularies.
- Subcutaneous Injection:Prefilled pen devices for denosumab and teriparatide are displacing infusion dependence in California and Florida Medicare Advantage networks, with Bluetooth-enabled adherence trackers piloting in United States commercial plans.
- Intravenous Infusion:Zoledronic acid annual infusions concentrate in hospital outpatient departments and ambulatory surgery centers with infusion chair capacity.
- Transdermal System:Estrogen patches for osteoporosis prevention occupy declining share due to FDA boxed warnings on cardiovascular and cerebrovascular risk.
Oral administration retains volume leadership; subcutaneous injection is climbing the fastest as patient preference and site-of-care economics converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's distribution primacy for biologic osteoporosis therapies requiring strict temperature controls.
United States
Medicare Advantage penetration in Florida and California drives subcutaneous injection device demand through home-based administration incentives. FDA's evolving guidance on long-term skeletal safety surveillance elevates post-market monitoring obligations for sponsors. The Boston-Cambridge corridor concentrates rheumatology center infrastructure and biologic infusion capacity.
Germany
Hospital episode-based reimbursement frameworks favor bundled fracture risk reduction programs over discrete pharmaceutical dispensing. EMA postmenopausal fracture prevention standards compress clinical trial timelines for sponsors generating robust skeletal endpoint data. The Heidelberg metropolitan cluster anchors academic medical center concentration for monoclonal antibody administration.
Japan
Tokyo and Osaka metropolitan corridors concentrate estrogen-depleted patient populations with elevated diagnostic screening penetration. PMDA conditional approval pathways enable revenue generation prior to fracture data maturation for therapies demonstrating surrogate bone density endpoints. The Nagoya pharmaceutical manufacturing belt supplies prefilled pen device production for domestic and export markets.
Switzerland
Biomechanical monitoring technology pilot programs in Basel and Zurich rheumatology centers advance implantable bone microsensor validation. Swissmedic regulatory frameworks align with EMA standards while permitting accelerated access negotiations for novel anabolic agents. The country's precision manufacturing base supports miniaturized sensor production for fracture detection latency compression.
Global Postmenopausal Osteoporosis Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing established reimbursement pathways and cold-chain distribution networks. The vendor base stratifies across three tiers: global biologic developers with monoclonal antibody platforms, generic oral bisphosphonate defenders with legacy portfolio scale, and emerging delivery mechanism specialists. Dominant competitive moves include biologic-biosimilar convergence strategies and subcutaneous device connectivity integration to capture patient adherence premiums.
Within the biologic developer tier, Amgen Inc. and Eli Lilly and Company exemplify contrasting pathway specializations. Amgen occupies a position anchored in RANKL inhibition infrastructure with established quarterly administration protocols. Eli Lilly represents parathyroid hormone analogue manufacturing scale with daily injection legacy systems. Pfizer Inc. sits within the oral bisphosphonate defense archetype, navigating generic erosion through formulary maintenance and retail pharmacy channel concentration. These three entities collectively illustrate the market's structural tension between infusion-dependent institutional models and patient-directed self-administration formats.
| Leading Market Players |
|---|
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Eli Lilly and Company |
| Novartis International AG |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Others |
Supply & Pricing Matrix
Prefilled pen device manufacturing scale in Ireland and Switzerland anchors supply-side concentration while compressing unit cost floors for subcutaneous osteoporosis therapies across European and North American markets.
Pricing Analysis
Volume-discount tiering structures separate rheumatology center bundled contracts from retail pharmacy point-of-sale transactions, with the former capturing 15-20 percent unit cost advantages through quarterly commitment volumes. Price differentiation hinges on cold-chain certification grade and infusion administration bundling, with FDA-validated cold-chain tiers commanding premium positioning against standard distribution protocols. Pricing pressure intensifies in oral bisphosphonate tiers due to Indian and Eastern European contract manufacturing organization capacity expansion. Medicare Part D formularies exhibit highest price sensitivity, while Japan's PMDA conditional approval pathways demonstrate lowest sensitivity due to surrogate endpoint premium capture.
Supply Chain Analysis
Cold-chain logistics chokepoints at the Port of Rotterdam and Frankfurt Airport cargo terminals underwrite distribution reliability for denosumab and romosozumab shipments across European rheumatology networks. Active pharmaceutical ingredient production concentrates in Ireland, Switzerland, and Singapore, with monoclonal antibody cell culture media and prefilled syringe components drawing from specialized chemical suppliers in Germany and Japan. Single-source vulnerability in glass barrel manufacturing for prefillable syringes elevates supply interruption risk during geopolitical trade disruptions. Distribution runs through pharmaceutical wholesale networks with temperature-validated last-mile delivery to hospital outpatient departments and specialty clinic infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled adherence tracking integration is transforming osteoporosis management into a connected-device platform economy, with patient data interoperability between pen devices and electronic health records creating stickier reimbursement relationships than molecule-alone value propositions.
For Market Incumbents: Consolidate infusion center partnerships into exclusive site-of-care networks before subcutaneous self-administration fully displaces institutional revenue streams. Amgen and Eli Lilly should deepen backward integration into prefilled pen device manufacturing to defend margin position against South Korean biosimilar entrants with cost-advantaged fill-finish capacity. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable regulatory pathway for biomechanical monitoring sensor developers targeting post-treatment adherence verification gaps in United States rheumatology practices. Target Mississippi and Alabama primary care networks through telemedicine-enabled bone health screening partnerships, leveraging Medicare Advantage plan incentives for home-based therapeutic administration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected delivery device platforms with integrated adherence analytics, positioning these archetypes for superior cash flow quality over pure molecule developers across the analysis window. Monitor PMDA conditional approval pathway utilization rates as the signal to watch for Japanese market access inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Device Platform Integration | Bluetooth-enabled pen devices with adherence tracking capture Medicare Advantage incentives in California and Florida networks. |
| Biomechanical Monitoring Sensor Development | Implantable bone microsensors advance fracture detection from symptomatic to subclinical stress identification in Swiss pilot programs. |
| Biologic-Biosimilar Convergence Strategy | RANKL inhibitor refinement combined with follow-on manufacturing scale creates differentiated delivery mechanism white space. |
| Telemedicine Screening Partnership Expansion | Primary care network alliances in rural United States markets address diagnostic gaps outside major metropolitan clusters. |
| Regulatory Fast-Track Utilization | PMDA conditional approval pathways enable revenue generation prior to fracture endpoint data maturation for anabolic agents. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EMA assessment reports, ClinicalTrials.gov entries, and Japanese PMDA submission databases to validate market sizing and competitive positioning claims. Primary interviews engaged drug development executives at monoclonal antibody developers, regulatory affairs leads navigating FDA long-term skeletal safety surveillance requirements, formulary directors at United States Medicare Advantage plans, and hospital procurement managers at German academic medical centers. Secondary validation incorporated SEC 10-K pharmaceutical segment disclosures, CMS Medicare Part D utilization data, and European hospital procurement database extracts. Bottom-up patient population modeling triangulated against top-down pharmaceutical revenue aggregation.
Segmentation dimensions modeled include therapy class, delivery mode, end-user channel archetype, and regional regulatory cluster across the projection horizon. Compound annual growth rate derivation incorporated historical volume trends, patent expiry schedules, and biosimilar entry probability assessments. Forecast inputs integrated dual-energy X-ray absorptiometry screening penetration rates by geography, rheumatology center infrastructure expansion timelines, and patient self-administration preference shift velocities derived from Medicare Advantage plan incentive structures.
Underlying assumptions cover stable FDA guidance interpretation on atypical femoral fracture surveillance, with deviation risk concentrated in EMA postmenopausal fracture prevention standard revisions or Japan PMDA surrogate endpoint policy recalibration. Practitioners should keep alternative scenarios live as reimbursement pathway fragmentation across Germany, Japan, and the United States evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market