
 Global Attention Deficit Hyperactivity Disorder Market | 2026-2036
Global Attention Deficit Hyperactivity Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Attention Deficit Hyperactivity Disorder Market Foresight
EU MDR is rebalancing the cost-of-entry calculus for device-drug combination therapies targeting ADHD. Eli Lilly and Company leverages its manufacturing scale to sustain dominance in long-acting stimulant formulations. Novartis AG anchors its position through deep specialization in transdermal delivery systems, while Takeda Pharmaceutical Company differentiates via extended-release technology leadership.
Attention Deficit Hyperactivity Disorder constitutes a neurodevelopmental condition characterized by persistent patterns of inattention, hyperactivity, and impulsivity, diagnosed through structured clinical interviews and validated rating scales such as the ADHD Rating Scale-IV. The condition demands pharmacological intervention alongside behavioral modification protocols to restore functional capacity across educational, occupational, and social domains. Stimulants command the largest revenue pool due to established efficacy profiles and decades of clinical validation, while non-stimulants represent the fastest-expanding category as prescribers seek alternatives for patients with substance abuse histories or cardiovascular contraindications. Adult ADHD therapy area exhibits concentrated growth as diagnostic criteria broaden and workplace accommodations normalize identification in professional settings.
FDA, EMA, and Health Canada collectively enforce pharmacovigilance protocols that shape post-market surveillance requirements and label expansions for ADHD therapeutics. The FDA's Risk Evaluation and Mitigation Strategy for stimulant medications directly constrains prescribing patterns and distribution channel controls across retail and hospital pharmacies. Stakeholders must monitor how digital biomarker integration and remote therapeutic monitoring reshape regulatory submission pathways and payer reimbursement decisions.
Market Dynamics
Digital therapeutics platforms are forcing a structural reclassification of ADHD interventions, blurring reimbursement boundaries between pharmacological and software-based treatments while compelling regulators to expand approval frameworks.
Growth Catalysts
- FDA Digital Therapeutics Framework:The evolving regulatory pathway accelerates market authorization for prescription digital interventions, creating new reimbursement categories for cognitive behavioral therapy apps.
- Workplace Accommodation Mandates:Corporate diversity and inclusion policies across professional services sectors normalize adult ADHD identification, expanding diagnostic demand beyond pediatric populations.
- Telehealth Infrastructure:Remote psychiatric consultation platforms reduce geographic barriers to specialist diagnosis, particularly in rural United States counties with provider shortages.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of methylphenidate and amphetamine salts depends on limited qualified suppliers in India and China, exposing formulation continuity to export restriction risks.
- DEA Quota Limitations:United States Drug Enforcement Administration production quotas for Schedule II controlled substances cap annual stimulant manufacturing volumes regardless of prescription demand.
- Cardiovascular Contraindication Pool:Substantial patient segments with hypertension or arrhythmia histories remain excluded from stimulant therapy, compressing addressable population for first-line treatments.
Strategic Opportunities
- Brazil ANVISA Expedited Review:Latin America's largest pharmaceutical market offers accelerated approval pathways for novel non-stimulant formulations with demonstrated pediatric efficacy.
- Transdermal Delivery Convergence:Patch-based methylphenidate systems bypass first-pass metabolism concerns while improving compliance among patients with swallowing difficulties or gastric sensitivity.
- Employer-Sponsored Digital Prescriptions:Self-insured corporations in the United States increasingly contract directly with digital therapeutic developers for workforce mental health benefits.
Industry Challenges
- Behavioral Health Credentialing Backlogs:Insurance panel enrollment delays for nurse practitioners and clinical psychologists extend patient wait times for initial ADHD assessments.
- Biomarker Validation Complexity:EEG and eye-tracking diagnostic adjuncts lack standardized normative databases across age cohorts, slowing regulatory acceptance as confirmatory tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Attention Deficit Hyperactivity Disorder Market |
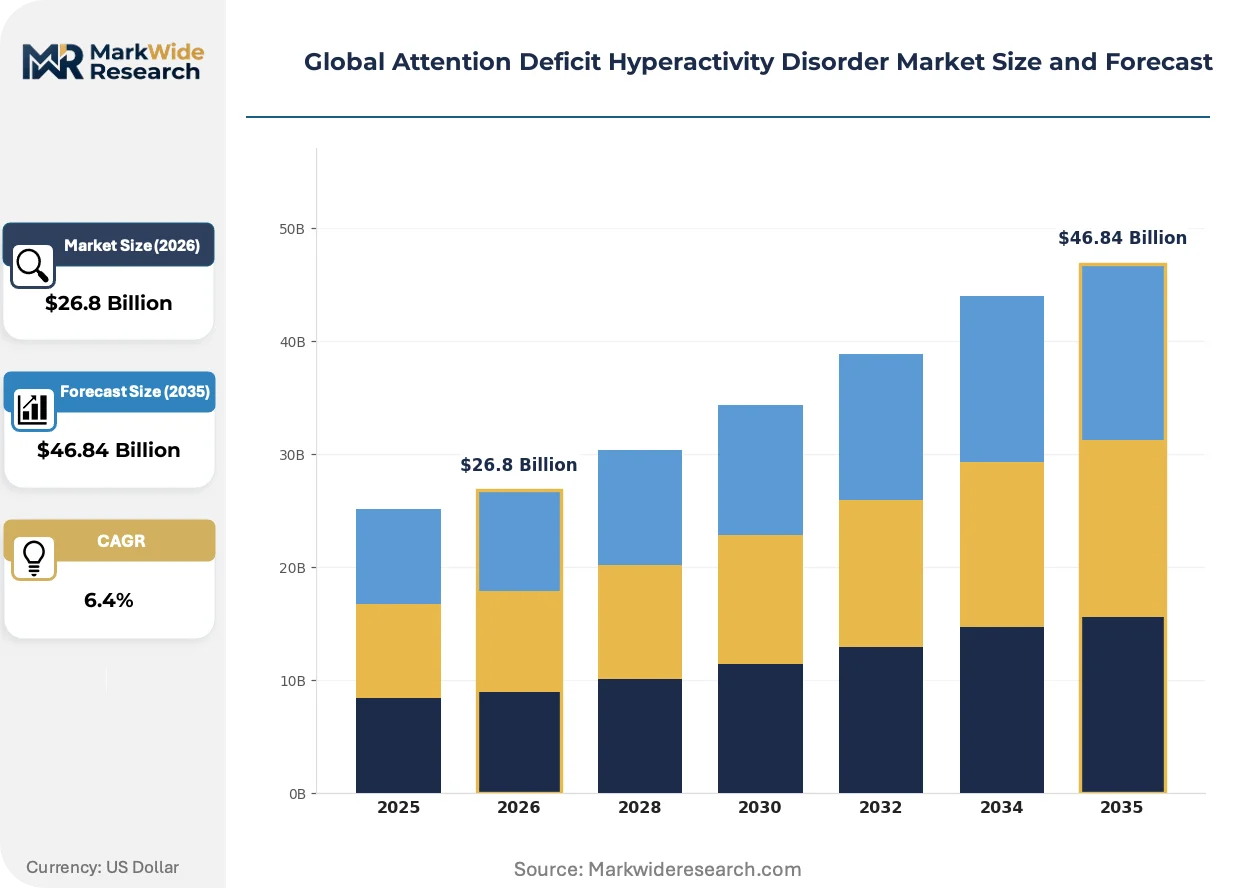
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Non-Stimulants, Antidepressants, Herbal Supplements Therapy Area: Inattentive Type, Hyperactive-Impulsive Type, Combined Type, Adult ADHD End User: Specialty Clinics, Mental Health Hospitals, Pediatric Centers, Community Health Services Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Eli Lilly and Company, Novartis AG, Johnson & Johnson, Takeda Pharmaceutical Company, Pfizer, Supernus Pharmaceuticals, Mallinckrodt plc, Lupin, Aytu BioPharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Attention Deficit Hyperactivity Disorder Market Shifts & Advancements
Artificial intelligence and continuous physiological monitoring are converging to transform ADHD assessment from episodic clinical interviews toward longitudinal, objective measurement paradigms.
Digital phenotyping through smartphone sensor data and wearable accelerometers is converging with machine learning classification algorithms to enable passive symptom quantification. Pediatric behavioral health centers in the United States pilot these systems for treatment response monitoring. This convergence is compressing the interval between dosage adjustments and clinical feedback, potentially displacing traditional monthly follow-up intervals.
EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on software-as-medical-device products claiming therapeutic benefit for neurodevelopmental conditions. Manufacturers must now demonstrate equivalence to established interventions through randomized controlled trials. Developers targeting European markets respond by structuring pivotal studies with active pharmacological comparators rather than placebo controls.
Self-directed diagnostic screening via validated adult ADHD rating scales proliferates through employee assistance programs and university health services. Traditional referral-dependent pathways lose volume to direct-access telepsychiatry platforms that integrate assessment with prescription fulfillment. This pattern concentrates in the United States where direct-to-consumer advertising and broad behavioral health parity laws reduce gatekeeper friction.
Global Attention Deficit Hyperactivity Disorder Market Segmentation
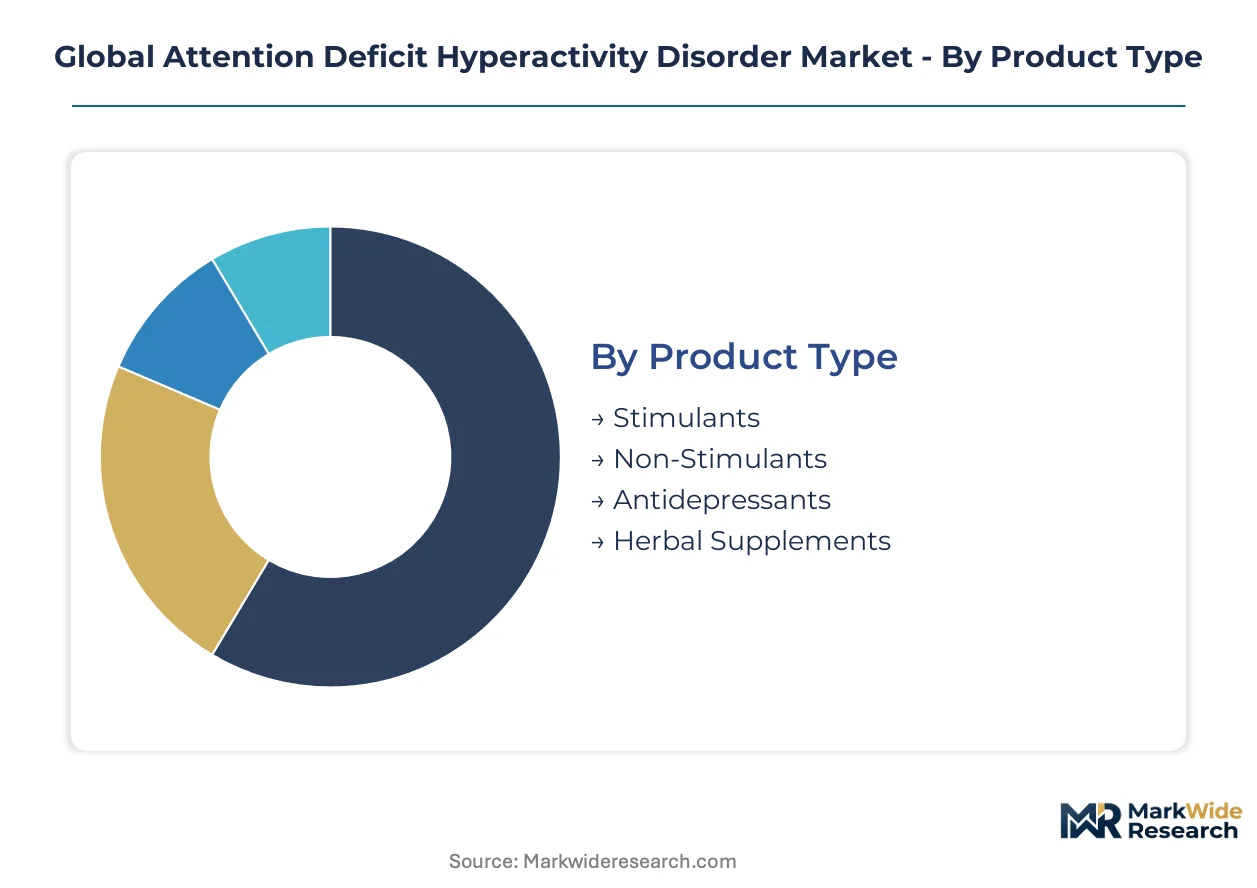
ADHD market segmentation reflects divergent regulatory pathways and reimbursement architectures across pharmacological and non-pharmacological interventions. Each category carries distinct certification burdens that shape commercial viability and geographic prioritization for manufacturers.
Product Type:
FDA's Risk Evaluation and Mitigation Strategy applies differentially across this category, with Schedule II controlled substances facing DEA quota constraints and specialized distribution controls that non-stimulant alternatives bypass entirely.
- Stimulants:Methylphenidate and amphetamine salt formulations dominate prescription volumes through established efficacy in dopamine and norepinephrine reuptake inhibition. Demand concentrates in the United States where DEA manufacturing quotas and pharmacy lock-in agreements create supply-side rigidities. The FDA's REMS program mandates prescriber certification and patient counseling documentation.
- Non-Stimulants:Atomoxetine and guanfacine extended-release mechanisms target norepinephrine modulation without Schedule II classification. Prescription growth is accelerating fastest among adult patients with substance use histories or cardiovascular contraindications in Germany and France, where EMA labeling emphasizes cardiac monitoring protocols.
- Antidepressants:Off-label bupropion and tricyclic applications address comorbid mood disorders in treatment-resistant pediatric populations.
- Herbal Supplements:Omega-3 formulations and proprietary botanical blends operate outside prescription frameworks, facing variable Health Canada NHP regulations and FDA DSHEA enforcement discretion.
Leading the category by volume: Stimulants. Growing fastest: Non-Stimulants.
Therapy Area:
Diagnostic coding specificity varies substantially across this category, with DSM-5 criteria application and reimbursement eligibility creating divergent addressable populations for targeted therapeutic development.
- Combined Type:Simultaneous inattention and hyperactivity-impulsivity symptom clusters generate the highest medication adherence rates due to pronounced functional impairment across academic and occupational settings. Pediatric centers in the United Kingdom and Australia prioritize this segment for intensive behavioral modification protocols alongside pharmacotherapy.
- Adult ADHD:Expanding diagnostic recognition among professional services workers drives prescription growth as workplace accommodation policies normalize disclosure. Telehealth platforms in California, Texas, and New York concentrate diagnostic volume through direct-to-patient subscription models.
- Inattentive Type:Predominantly distractible presentations without hyperactivity often delay diagnosis until academic underperformance triggers referral.
- Hyperactive-Impulsive Type:Physical restlessness and interruptive behavior patterns dominate early childhood identification and intervention pathways.
Combined Type generates largest prescription volumes. Adult ADHD climbs the fastest as diagnostic criteria broaden and workplace screening proliferates.
End User:
Credentialing requirements and reimbursement rates create tiered access economics across this category, with board-certified psychiatrist concentration determining geographic service availability.
- Specialty Clinics:Concentrated expertise in neurodevelopmental assessment supports complex diagnostic differentiation from anxiety and learning disorders. United States metropolitan clusters in Boston, Chicago, and San Francisco maintain waiting lists exceeding six months due to behavioral health panel enrollment backlogs.
- Pediatric Centers:Integrated developmental-behavioral pediatrics programs combine medication management with parent training interventions. Expansion is concentrating across North American children's hospital networks as Medicaid reimbursement for developmental screening improves.
- Mental Health Hospitals:Inpatient stabilization and intensive outpatient programming address severe comorbidities.
- Community Health Services:Federally qualified health centers extend access to uninsured and underinsured populations through sliding-scale fee structures.
Specialty Clinics command highest reimbursement rates. Pediatric Centers are gaining share fastest through health system vertical integration.
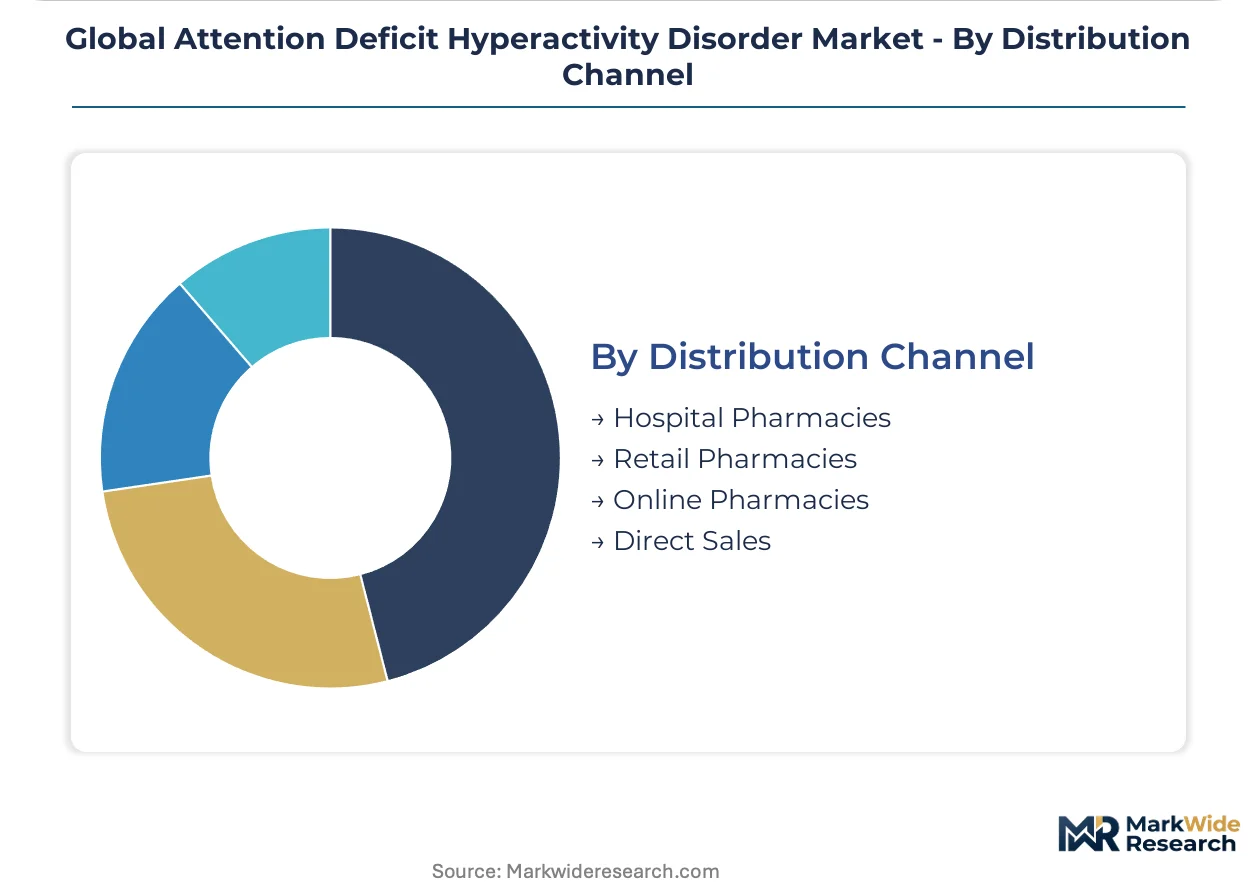
Distribution Channel:
Controlled substance scheduling dictates channel segmentation, with DEA registration requirements and electronic prescribing mandates creating structural barriers to direct-to-patient models for stimulant medications.
- Retail Pharmacies:National chains and independent operators handle the majority of stimulant prescription fulfillment through centralized inventory management and prescriber verification systems. CVS, Walgreens, and Rite Aid locations across the United States implement real-time prescription drug monitoring program integration.
- Hospital Pharmacies:Captive dispensing within academic medical centers supports clinical trial participation and specialty formulation access. Concentrated in major teaching hospitals in Toronto, London, and Melbourne where investigational drug services manage protocol compliance.
- Online Pharmacies:Legitimate telehealth-integrated platforms face competition from unverified international operators.
- Direct Sales:Limited to institutional contracting for school-based medication administration programs.
Retail Pharmacies dominate volume. Online Pharmacies show steepest expansion trajectory through telehealth platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for pharmaceutical manufacturing in Ireland and Puerto Rico concentrate ADHD active pharmaceutical ingredient production, creating tax-advantaged supply nodes that serve formulation facilities across multiple continents.
United States
Workplace accommodation mandates and expanded behavioral health parity coverage drive adult diagnostic volume. FDA's Risk Evaluation and Mitigation Strategy for Schedule II stimulants constrains prescribing through prescriber certification requirements. Pediatric specialty clusters in Boston, Chicago, and San Francisco maintain six-month waiting lists due to credentialing backlogs.
Germany
Atomoxetine and guanfacine prescription growth accelerates among adults with cardiovascular contraindications to stimulants. EMA labeling emphasizes cardiac monitoring protocols for non-stimulant therapies. Frankfurt and Munich host concentrated neurodevelopmental assessment centers integrated with university hospital networks.
Japan
PMDA accelerated review pathways for pediatric ADHD formulations reduce time-to-market for novel non-stimulant entrants. Workplace mental health screening programs normalize adult identification in professional services sectors. Tokyo and Osaka metropolitan areas concentrate board-certified psychiatrist capacity.
Brazil
ANVISA expedited review pathways attract developers of novel non-stimulant formulations with demonstrated pediatric efficacy. Private health insurance expansion broadens reimbursement for behavioral health services. São Paulo anchors diagnostic and treatment capacity for the Southern Cone.
United Kingdom
NHS England commissioning frameworks prioritize combined-type ADHD for intensive behavioral modification protocols alongside pharmacotherapy. NICE guidelines restrict stimulant first-line use in certain age cohorts. London and Manchester academic medical centers pilot digital phenotyping for treatment response monitoring.
Global Attention Deficit Hyperactivity Disorder Market Competitive Landscape
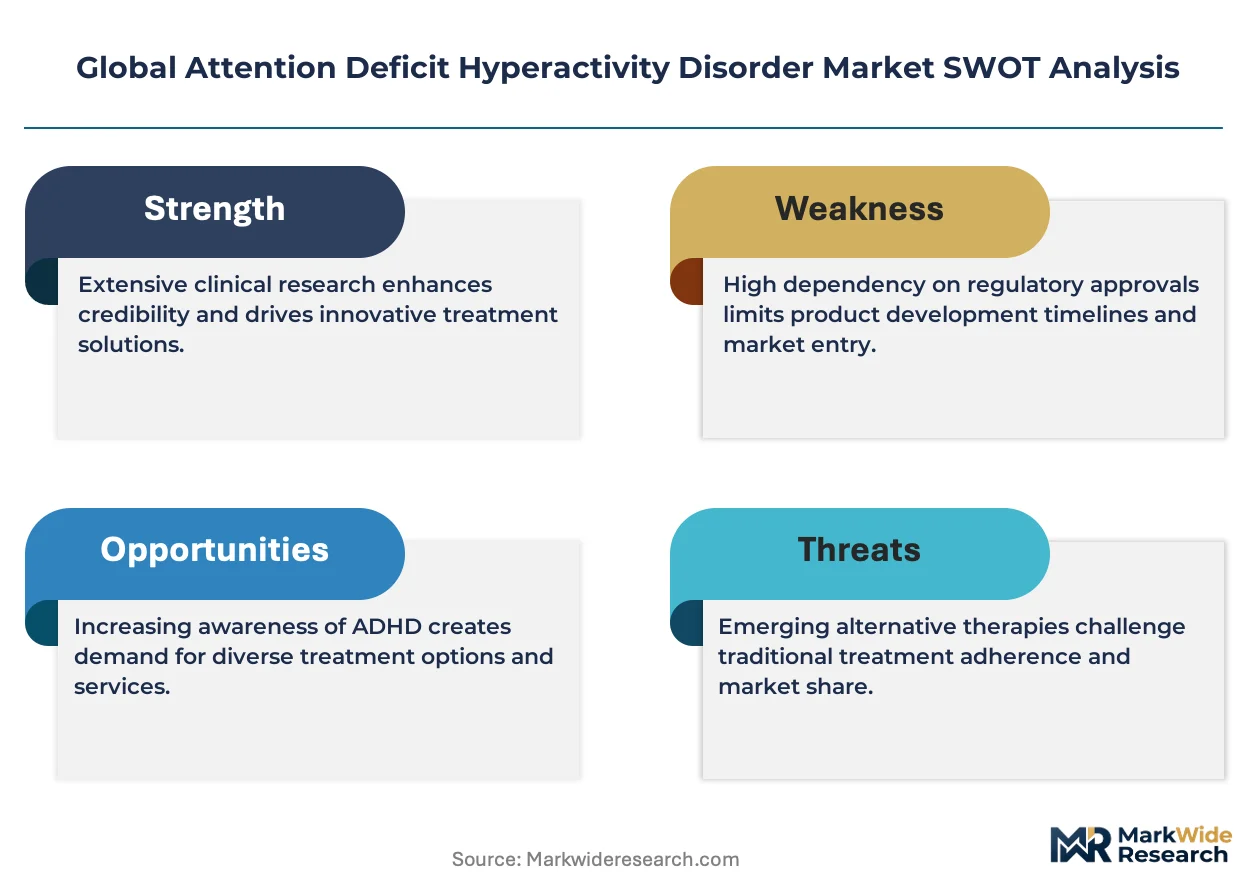
Diversified conglomerates compete with focused pure-play specialists across formulation, delivery technology, and digital therapeutic vectors. Market structure tilts toward consolidation among long-acting stimulant developers while fragmenting across emerging non-stimulant and software-based intervention categories. Three archetypes dominate: integrated pharmaceutical conglomerates with manufacturing scale, specialized neuropsychiatric pure-plays, and digital therapeutic developers. Competitive moves concentrate on transdermal delivery convergence and employer-sponsored digital prescription contracting.
Among integrated pharmaceutical conglomerates, Eli Lilly and Company and Novartis AG exemplify scale-driven positions anchored in manufacturing infrastructure and delivery system specialization. Takeda Pharmaceutical Company occupies a differentiated position through extended-release technology leadership. These three entities represent the dominant competitive anchors shaping formulation standards and regulatory engagement patterns across the United States, European, and Japanese markets.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novartis AG |
| Johnson & Johnson |
| Takeda Pharmaceutical Company |
| Pfizer |
| Supernus Pharmaceuticals |
| Mallinckrodt plc |
| Lupin |
| Aytu BioPharma |
| Others |
Supply & Pricing Matrix
Captive integration into active pharmaceutical ingredient synthesis anchors both supply security and pricing power for long-acting stimulant developers. Eli Lilly and Novartis sustain margin structures through backward control over methylphenidate precursor supply chains, insulating formulation operations from Indian and Chinese export volatility while commanding premium positioning against spot-market dependent competitors.
Pricing Analysis
Short lead-time premiums separate DEA quota-secured manufacturers from spot-market purchasers facing allocation uncertainty. Three-tier pricing structure across premium extended-release, standard immediate-release, and economy generic tiers stratifies according to REMS certification burden and manufacturing complexity. Cost compression in immediate-release generics intensifies because of Indian API oversupply and Medicaid reimbursement ceiling compression. Pediatric centers exhibit highest price sensitivity due to formulary committee oversight, while self-insured employers demonstrate lowest sensitivity through direct digital therapeutic contracting.
Supply Chain Analysis
Single-source vulnerability sits with methylphenidate and amphetamine salt precursor manufacturers concentrated in Gujarat, India and Shandong, China. Synthesis of lisdexamfetamine and mixed amphetamine salts draws from ephedrine and pseudoephedrine feedstocks subject to international precursor control conventions. Regulatory restriction risk through DEA quota limitations and export licensing delays threatens formulation continuity regardless of prescription demand. Distribution runs through DEA-registered wholesale distributors to retail pharmacy chains with electronic prescribing mandate compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream API control and downstream digital therapeutic platforms represent the decisive levers. Players securing both manufacturing capacity and employer contracting relationships will dictate pricing architecture.
For Market Incumbents: Acquire transdermal delivery technology specialists to defend against non-stimulant formulation entrants eroding stimulant market share. Secure DEA manufacturing quota expansion through lobbying investment before alternative norepinephrine reuptake inhibitors achieve first-line guideline status. Consolidate pediatric center partnerships through integrated medication-behavioral therapy bundled contracts.
For New Entrants and Emerging Players: The price-point gap between premium extended-release stimulants and unregulated herbal supplements offers white-space entry for validated digital therapeutics with prescription status. Target employer-sponsored mental health benefits as the most penetrable channel through direct contracting with self-insured corporations. Pursue ANVISA expedited review for novel non-stimulant pediatric formulations in Brazil.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical conglomerates seeking neuropsychiatric specialization. Long-term viability hinges on regulatory moat sustainability and reimbursement pathway durability. Watch FDA digital therapeutics framework expansion as the inflection signal for software-based intervention valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Convergence | Patch-based methylphenidate systems bypass first-pass metabolism while improving pediatric compliance rates. |
| Digital Therapeutic FDA Submission | Prescription software status unlocks employer-sponsored reimbursement separate from pharmacy benefit managers. |
| DEA Quota Expansion Lobbying | Manufacturing volume ceilings constrain revenue regardless of diagnostic demand acceleration. |
| Employer Direct Contracting | Self-insured corporations bypass traditional payer gatekeepers for workforce mental health benefits. |
| Pediatric Center Vertical Integration | Health system ownership of developmental-behavioral programs secures captive prescription volume. |
Research Methodology
Independent corroboration across regulatory filings, pharmaceutical procurement databases, and clinical trial registries underwrites the qualitative findings. Primary interviews with drug development executives, formulary directors at major payers, regulatory affairs specialists, and pediatric behavioral health center administrators combined with secondary validation against FDA REMS documentation, DEA quota publications, EMA assessment reports, and ClinicalTrials.gov entries. Bottom-up prescription volume modeling and top-down revenue triangulation anchored segmentation outputs.
Comparable-period anchoring to historical stimulant prescription trends and non-stimulant launch trajectories structured the forecast window. Segmentation dimensions across the modeling period included pharmacological class, dosage form mechanism, patient age cohort, diagnostic subtype, and regional regulatory cluster. CAGRs derived from multivariate regression against DEA manufacturing quota trends, diagnostic prevalence studies, and reimbursement policy shifts. Digital therapeutic adoption curves and workplace accommodation mandate diffusion served as category-specific forecast inputs.
Inputs from payer formulary committees and health system procurement officers were available through the study window; gaps in longitudinal digital therapeutic outcome data introduce uncertainty bands around software-based intervention projections. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement parity maintenance. Pipeline failure rates for novel non-stimulant mechanisms and DEA quota policy revisions represent specific risk factors that could revise trajectory projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market