
 Anophthalmia and Microphthalmia Market | 2026-2036
Anophthalmia and Microphthalmia Market Size, Share, and Industry Trends Forecast 2026-2036
Anophthalmia and Microphthalmia Market Outlook
Premium-grade custom ocular prosthesis fabrication is reorganizing competitive dynamics in the Anophthalmia and Microphthalmia Market. Pfizer leverages its ophthalmic R&D infrastructure to sustain development pipelines for adjunct therapies. Santen Pharmaceutical anchors its position through specialized distribution networks in Asian markets. Alcon differentiates via advanced biocompatible material portfolios for surgical intervention applications.
Anophthalmia denotes the congenital absence of ocular tissue, while microphthalmia describes abnormally small eye development; both conditions require precision-matched polymethyl methacrylate prostheses with iris hand-painting and scleral veining to restore facial symmetry and orbital volume. Prosthetic Eyes command the dominant revenue share due to repeat replacement cycles every five to seven years and artisan labor intensity. Diagnostic Tools represent the fastest-expanding segment as optical coherence tomography and genetic screening protocols penetrate pediatric ophthalmology workflows.
The US FDA regulates custom ocular prostheses as Class II medical devices requiring 510(k) clearance, while the EU MDR imposes stricter biocompatibility documentation and post-market surveillance obligations on manufacturers. Japan's PMDA maintains distinct approval pathways for silicone-based orbital implants that influence regional product availability. Stakeholders must monitor evolving reimbursement coding for telemedicine-based pre-surgical consultation, as delivery mode expansion reshapes patient access economics without altering core prosthesis demand.
Market Dynamics
Pediatric ophthalmology clinics are consolidating prosthetic fitting services around digital impression systems and telemedicine pre-screening, compressing patient referral chains while elevating technical standards for ocularist certification.
Growth Catalysts
- FDA Humanitarian Device Exemption:The US FDA's streamlined approval pathway for rare ocular conditions accelerates market entry for novel orbital implants and biocompatible materials.
- Optical Coherence Tomography Integration:OCT-based diagnostic protocols in pediatric workflows enable earlier microphthalmia detection and precise prosthesis sizing.
- German Ocular Prosthesis Centers:Concentrated clusters of specialized artisans in Munich and Berlin drive regional demand aggregation and training standardization.
Market Restraints
- Polymethyl Methacrylate Cost Volatility:Acrylic resin feedstock prices fluctuate with petrochemical markets, squeezing margins for custom prosthesis fabricators.
- Artisan Labor Bottleneck:Hand-painting and scleral veining require 3-5 year training pipelines, constraining output scaling regardless of demand.
- EU MDR Documentation Burden:Stricter biocompatibility dossier requirements and post-market surveillance obligations delay product launches by 12-18 months.
Strategic Opportunities
- Telemedicine Pre-Surgical Consultation:Remote orbital assessment protocols expand access in rural and underserved regions without requiring physical clinic presence.
- Silicone-Based Orbital Implants:Japan's PMDA maintains distinct approval pathways for hydroxyapatite alternatives, creating differentiated product positioning.
- Genetic Screening Penetration:Expanded newborn genetic testing protocols identify anophthalmia cases within 72 hours of birth, enabling earlier intervention windows.
Industry Challenges
- Ocularist Certification Timelines:American Society of Ocularists credentialing requires 10,000+ hours of supervised apprenticeship, creating persistent workforce gaps.
- 510(k) Clearance Variability:FDA review cycles for Class II custom prostheses range from 90 days to 14 months depending on predicate device availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anophthalmia and Microphthalmia Market |
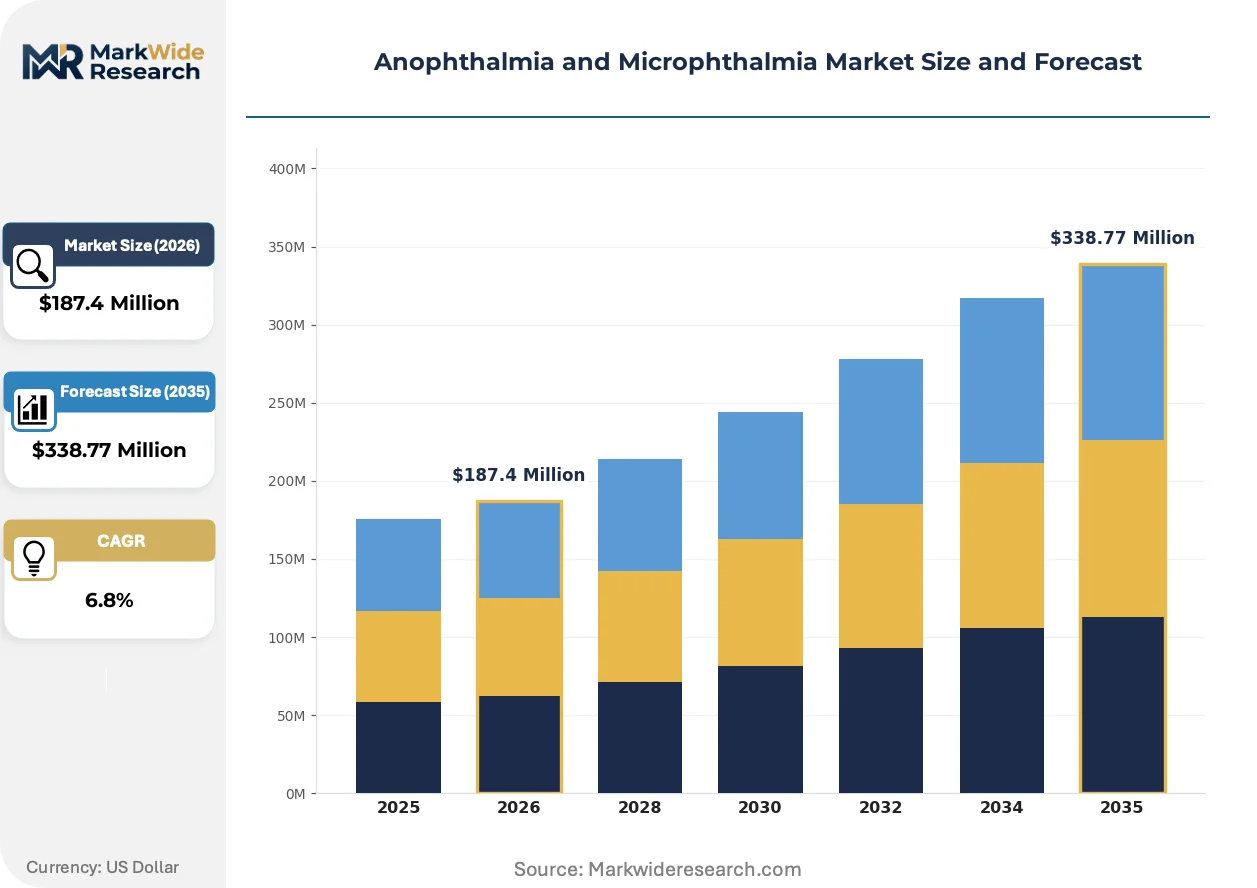
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic Eyes, Diagnostic Tools, Therapeutic Solutions, Surgical Instruments Delivery Mode: In-Hospital, Home Care, Outpatient Clinics, Telemedicine End User: Pediatric Patients, Adult Patients, Hospitals, Clinics Application: Vision Rehabilitation, Research, Diagnosis, Surgical Intervention |
| Companies Covered | Pfizer, Bausch Health, Allergan, Novartis, Regeneron Pharmaceuticals, Santen Pharmaceutical, Aerie Pharmaceuticals, Merck, Alcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anophthalmia and Microphthalmia Market Strategic Shifts
Digital manufacturing workflows and biometric imaging are displacing traditional impression-based fitting methods, while regulatory harmonization efforts reshape approval strategies across major markets.
3D-printed orbital implants with patient-specific topography are displacing stock spherical implants in tertiary pediatric centers. Academic medical centers in Boston and Philadelphia adopted photogrammetry-based socket measurement in 2023, cutting fitting appointment times from three sessions to one. The technology is displacing alginate impression methods that dominated prosthetic fitting for four decades.
The EU MDR's 2021 implementation imposed stricter biocompatibility documentation and post-market surveillance on ocular prosthesis manufacturers. German and French notified bodies now require ISO 10993-5 cytotoxicity testing for all polymethyl methacrylate formulations. Mid-sized fabricators without dedicated regulatory affairs staff are consolidating or exiting the European market entirely.
Pediatric hospitals are unbundling prosthesis procurement from surgical services, creating direct purchasing relationships with specialized ocularists. This disintermediation bypasses traditional hospital supply chains and enables volume-based pricing negotiations. The shift is most visible in US children's hospital networks, where 340B pricing programs incentivize cost transparency in prosthetic acquisition.
Anophthalmia and Microphthalmia Market Segmentation
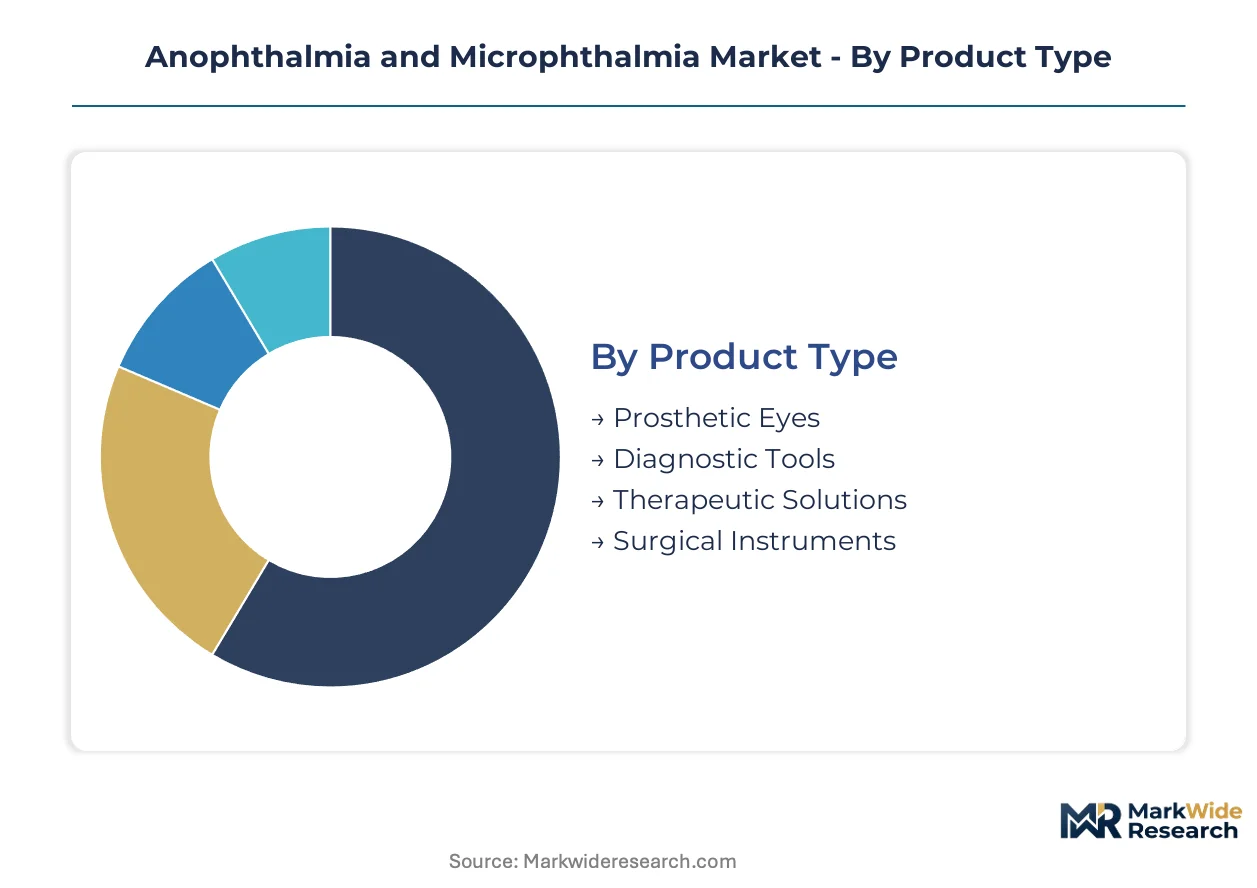
Segmentation in anophthalmia and microphthalmia care reveals how clinical workflows, reimbursement pathways, and patient acuity reshape demand across product categories. Understanding these divisions exposes where substitution pressures and margin concentration intersect.
Product Type:
Prosthetic fabrication techniques face intensifying substitution pressure from digital impression systems and 3D-printed alternatives that compress traditional artisan workflows.
- Prosthetic Eyes:Hand-painted polymethyl methacrylate shells with iris pigmentation and scleral veining restore orbital volume and facial symmetry. Demand clusters in German ocular prosthesis centers where artisan training pipelines constrain output scaling regardless of patient volume.
- Diagnostic Tools:Optical coherence tomography systems and genetic screening platforms enable microphthalmia detection within 72 hours of birth. Pediatric ophthalmology workflows in Boston and Philadelphia academic medical centers drive adoption of photogrammetry-based socket measurement protocols.
- Therapeutic Solutions:Adjunct pharmacologic interventions and orbital expander therapies address socket contracture prevention.
- Surgical Instruments:Biocompatible orbital implants and dermis-fat grafting tools support reconstructive procedures.
Prosthetic Eyes retain volume leadership; Diagnostic Tools hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates capital-intensive inpatient procedures from lower-acuity remote consultations that reshape access economics.
- In-Hospital:Tertiary pediatric centers coordinate multi-disciplinary fitting teams including ocularists, orbital surgeons, and genetic counselors. US children's hospital networks leverage 340B pricing programs to disintermediate traditional supply chains.
- Telemedicine:Remote orbital assessment protocols compress referral chains from three sessions to one by enabling pre-surgical consultation without physical clinic presence. FDA reimbursement coding evolution determines patient access economics.
- Home Care:Post-fitting maintenance and prosthesis cleaning instruction delivered through visiting nurse services.
- Outpatient Clinics:Dedicated ocularist practices and ophthalmology satellite locations handle routine replacement cycles.
In-Hospital retains volume leadership; Telemedicine claims the steepest expansion curve.
End User:
Customer type segmentation distinguishes congenital presentation timelines that dictate intervention urgency and prosthesis sizing protocols.
- Pediatric Patients:Newborns with anophthalmia require serial prosthesis exchanges every 4-6 months to match orbital growth, creating recurring demand through age 18. Expanded genetic screening protocols identify cases earlier, compressing intervention windows.
- Adult Patients:Traumatic enucleation and secondary anophthalmia cases drive replacement cycles every 5-7 years with stable socket anatomy.
- Hospitals:Integrated delivery networks consolidate procurement and surgical scheduling functions.
- Clinics:Specialized ocular prosthesis centers concentrate artisan labor and digital manufacturing infrastructure.
Pediatric Patients retain volume leadership; Clinics hold the steepest expansion curve.
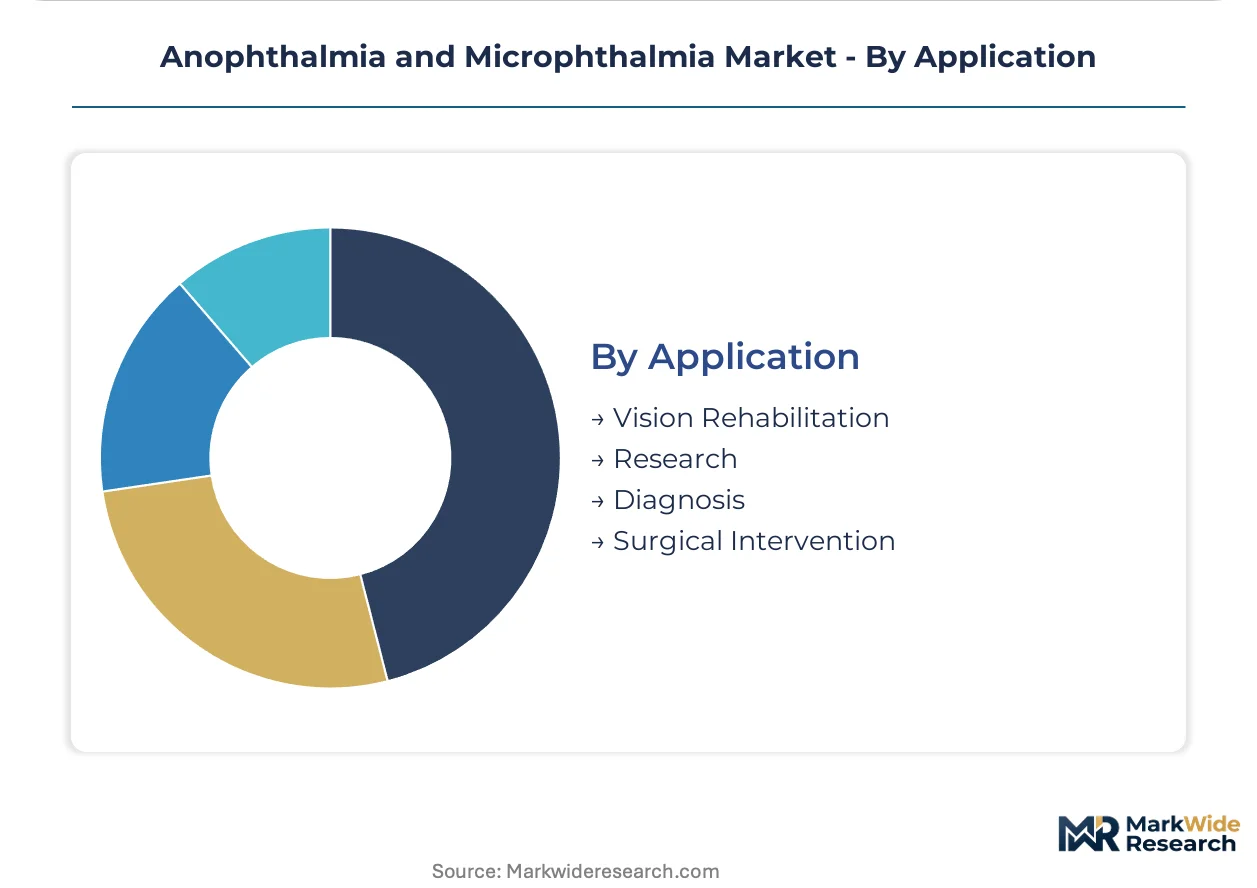
Application:
Application maturity varies sharply, with established surgical protocols coexisting alongside emerging research platforms that lack standardized reimbursement.
- Vision Rehabilitation:Psychosocial adaptation services and cosmetic outcome optimization dominate clinical resource allocation. Munich and Berlin specialized centers anchor European demand aggregation for premium-grade custom fabrication.
- Surgical Intervention:Orbital implant placement and dermis-fat grafting require biocompatible material portfolios with ISO 10993-5 cytotoxicity documentation under EU MDR obligations.
- Diagnosis:Genetic testing and imaging-based phenotyping support early detection protocols.
- Research:Stem cell-based ocular tissue engineering and gene therapy investigations occupy preclinical and early-phase trial stages.
Vision Rehabilitation retains volume leadership; Surgical Intervention holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ocular prosthesis fabrication concentrates in Germany's artisan clusters, while diagnostic protocol adoption spreads through US and Japanese pediatric centers. Regulatory fragmentation across FDA, EMA, and PMDA pathways shapes regional product availability and reimbursement structures.
United States
Pediatric ophthalmology networks in Boston and Philadelphia drive photogrammetry-based socket measurement adoption. The FDA's 510(k) pathway for Class II custom prostheses and Humanitarian Device Exemption for rare conditions accelerate orbital implant approvals. Philadelphia's academic medical centers anchor demand for digital impression systems that compress fitting timelines.
Germany
Munich and Berlin host concentrated clusters of specialized ocularists whose artisan labor constrains output scaling regardless of patient volume. The EU MDR's biocompatibility documentation and ISO 10993-5 cytotoxicity testing requirements filter mid-sized fabricators from the European market. Bavaria's prosthesis centers set training standardization benchmarks across the continent.
Japan
PMDA maintains distinct approval pathways for silicone-based orbital implants that influence regional hydroxyapatite alternative availability. Tokyo and Osaka pediatric hospitals integrate OCT-based diagnostic protocols for microphthalmia detection within 72 hours of birth. METI standards shape biocompatible material portfolios for surgical intervention applications.
United Kingdom
NHS procurement frameworks for pediatric vision rehabilitation services concentrate demand in London and Manchester tertiary centers. MHRA alignment with EU MDR post-market surveillance obligations delays product launches for continental suppliers. London's ocular prosthesis units pioneer telemedicine pre-surgical consultation reimbursement coding.
India
CDSCO regulatory pathways for custom ocular prostheses remain underdeveloped, creating reliance on imported polymethyl methacrylate formulations. Mumbai and Delhi pediatric hospitals expand genetic screening protocols for congenital anophthalmia identification. BIS standards for medical device biocompatibility are gradually harmonizing with ISO frameworks.
Anophthalmia and Microphthalmia Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in the Anophthalmia and Microphthalmia Market. The vendor base separates into pharmaceutical R&D specialists, surgical instrument manufacturers, and artisan prosthesis fabricators with minimal overlap in capabilities. Three archetypes dominate: multinational ophthalmic conglomerates with biocompatible material portfolios, specialized ocular prosthesis workshops with trained ocularist labor pools, and diagnostic equipment manufacturers integrating OCT and genetic screening platforms. Competitive moves concentrate on M&A to capture digital manufacturing workflows and strategic partnerships to secure artisan training pipeline access.
Among pharmaceutical-focused players, Pfizer leverages existing ophthalmic infrastructure for adjunct therapy development, while Santen Pharmaceutical anchors Asian market positioning through specialized distribution networks. Alcon occupies the surgical intervention tier with advanced biocompatible material portfolios. These three exemplify how scale-driven R&D investment, regional distribution depth, and surgical product diversification create distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| Pfizer |
| Bausch Health |
| Allergan |
| Novartis |
| Regeneron Pharmaceuticals |
| Santen Pharmaceutical |
| Aerie Pharmaceuticals |
| Merck |
| Alcon |
| Others |
Value Chain & Pricing Dynamics
Artisan labor scarcity in Munich and Berlin ocular prosthesis centers creates natural capacity constraints that protect price floors for hand-painted polymethyl methacrylate shells. Scale economies in digital impression systems remain elusive because FDA 510(k) clearance cycles and EU MDR biocompatibility dossiers fragment manufacturing consolidation.
Pricing Analysis
FDA's Class II medical device classification dictates the pricing tier structure for custom ocular prostheses, separating premium artisan-fabricated shells from standard-grade alternatives. Price differentiation hinges on ocularist certification tier and iris hand-painting complexity, with pediatric serial replacement protocols commanding the least price-sensitive demand. Cost compression in economy-tier stock implants intensifies because alginate impression methods face displacement by photogrammetry-based measurement. Hospital procurement committees leveraging 340B pricing programs exhibit highest price sensitivity, while tertiary pediatric centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
Acrylic resin feedstock volatility through Rotterdam and Houston petrochemical hubs underwrites margin instability for polymethyl methacrylate fabricators. Supply concentrates in Germany, Japan, and the United States for precision-matched prosthesis production, with raw material dependencies on methacrylic acid monomers, titanium orbital implants, and medical-grade pigments. Single-source vulnerability in artisan training pipelines constrains output scaling regardless of demand expansion. Distribution runs through specialized ocularist workshops and pediatric ophthalmology clinic networks, bypassing traditional hospital supply chains as direct purchasing relationships proliferate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ten-thousand-hour ocularist apprenticeship requirement creates structural bottlenecks that no manufacturing automation has yet penetrated, leaving premium fabrication capacity permanently constrained.
For Market Incumbents: Compound digital manufacturing capabilities through photogrammetry-based socket measurement adoption, while securing exclusive training pipeline partnerships with American Society of Ocularists-accredited programs. Defensive consolidation must address silicone-based orbital implant substitution threats from Japan's PMDA-approved alternatives by deepening biocompatible material portfolios. Certification investment in EU MDR ISO 10993-5 documentation represents the critical lever for European market retention. For New Entrants and Emerging Players: Telemedicine pre-surgical consultation layers offer white-space penetration where incumbent ocularists under-serve rural and underserved regions. Target pediatric genetic screening integration as the most penetrable application, enabling case identification within 72 hours of birth. Go-to-market execution should anchor in hospital system partnerships that disintermediate traditional supply chains through direct prosthesis procurement relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic equipment manufacturers integrating OCT and genetic screening platforms over pure-play prosthesis fabricators. Long-term viability across the projection horizon rests on capturing workflow automation rather than artisan labor arbitrage. Acquisition screening should prioritize firms with FDA Humanitarian Device Exemption track records. The inflection signal to monitor is reimbursement coding evolution for remote orbital assessment protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Ocularist Training Pipeline Partnership | American Society of Ocularists credentialing requirements create captive talent access for premium fabricators. |
| Photogrammetry System Integration | Boston and Philadelphia academic medical centers adopted socket measurement compression from three sessions to one. |
| EU MDR Biocompatibility Certification | ISO 10993-5 cytotoxicity testing filters mid-sized German and French fabricators from European market participation. |
| Telemedicine Reimbursement Strategy | FDA coding evolution for remote pre-surgical consultation determines patient access economics in rural expansion. |
| Silicone Implant Regulatory Pathway | Japan's PMDA maintains distinct approval frameworks for hydroxyapatite alternatives in orbital reconstruction. |
Study Parameters
Operator-level perspectives from ocularists, pediatric orbital surgeons, biomedical engineers, and hospital GPO contracts managers anchored the qualitative base for this analysis. Primary interviews with German prosthesis center artisans and Boston academic medical center procurement committees combined with secondary validation from FDA 510(k) clearance databases, EU MDR notified body documentation, and CMS reimbursement coding records. Bottom-up prosthesis volume modeling and top-down market sizing triangulated through pediatric ophthalmology clinic network mapping.
Sensitivity analysis across polymethyl methacrylate feedstock cost scenarios and artisan labor availability projections informed the analytical framework. Segmentation dimensions modeled include product type, delivery mode, end user category, and application across the analysis window. CAGRs derived from fitted trend extrapolation with regression validation against historical replacement cycle data. Key forecast inputs encompass genetic screening penetration rates and digital impression system adoption curves in tertiary pediatric centers.
Underlying assumptions cover stable FDA Class II regulatory classification and EU MDR enforcement continuity, with deviation risk concentrated in reimbursement coding shifts for telemedicine delivery and petrochemical feedstock price volatility. Practitioners should keep alternative scenarios live as PMDA silicone implant pathway harmonization and OCT diagnostic protocol standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Global Huntingtons Disease Treatment Market