
 Plasma-Derived Protein Therapies Market | 2026-2036
Plasma-Derived Protein Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma-Derived Protein Therapies Market Analytics
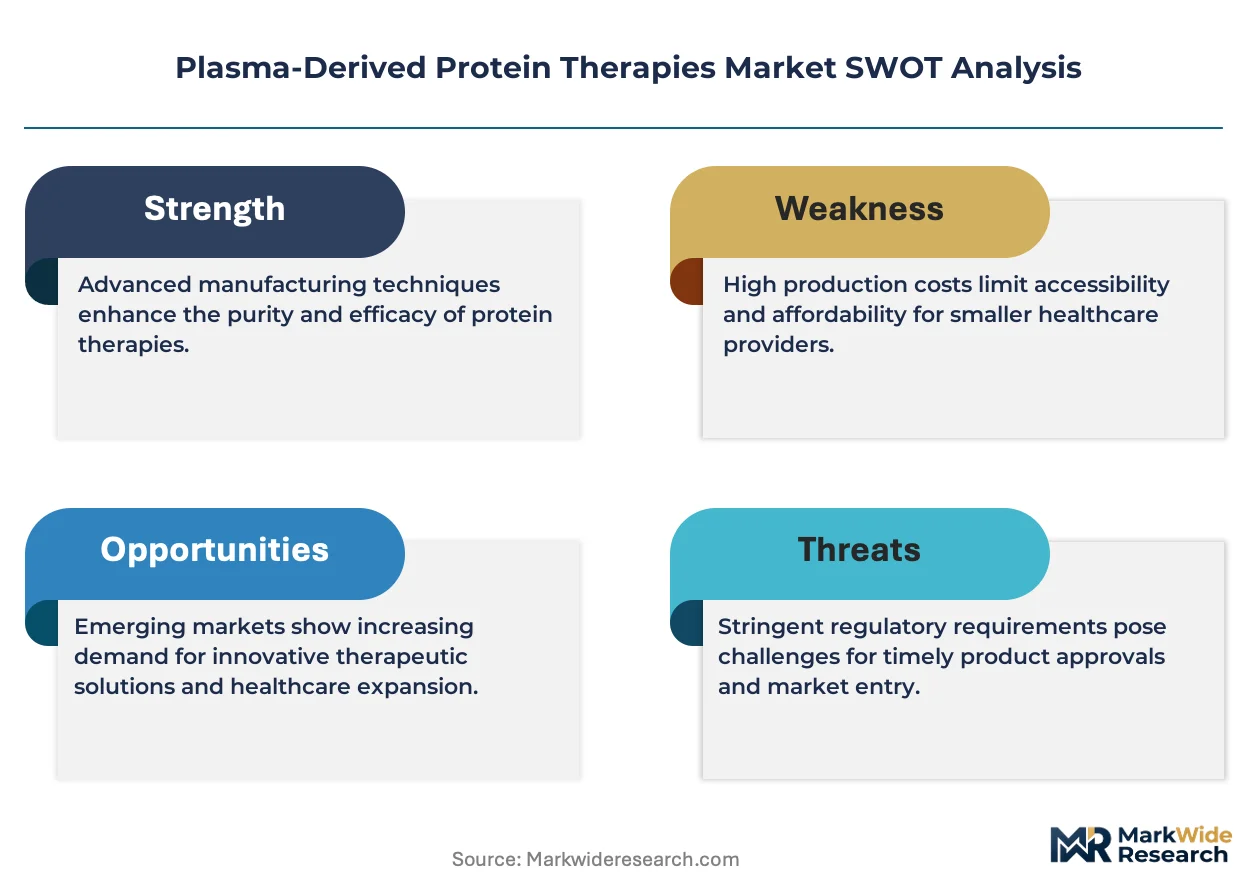
Multi-source plasma collection is realigning supply security across the industry. CSL Behring leverages vertical integration from fractionation to finished sterile product, sustaining margin capture across the value chain. Takeda Pharmaceutical Company Limited anchors its position through geographic dominance in Asia-Pacific collection centers, while Grifols specializes in high-volume albumin and immunoglobulin output from European and US plasma networks.
Plasma-derived protein therapies comprise biologically active proteins—primarily immunoglobulins, coagulation factors, albumin, and hyperimmune globulins—isolated through cold ethanol fractionation or chromatographic purification of human source plasma, then formulated for intravenous, subcutaneous, or intramuscular delivery to treat inherited deficiencies, autoimmune conditions, and trauma-related volume loss. The immunoglobulin segment commands the largest revenue pool due to chronic replacement needs in primary immune deficiency, whereas coagulation factors generate premium pricing from recombinant competition and hemophilia treatment complexity. Subcutaneous delivery is expanding fastest among home care end users seeking reduced infusion center dependency, though intravenous administration still dominates hospital-based trauma and critical care applications.
FDA plasma sourcing regulations, EU Good Manufacturing Practice standards enforced by EMA, and WHO plasma quality guidelines collectively determine collection eligibility, pathogen safety testing, and fractionation facility licensing. These frameworks elevate compliance costs for new market entrants while reinforcing incumbent advantages through established inspection histories and validated viral reduction protocols. Stakeholders must monitor evolving fractionation capacity constraints against collection volume growth to assess supply adequacy for expanding autoimmune and neurological indications.
Market Dynamics
Fractionation capacity constraints are tightening against plasma collection volume expansion, forcing manufacturers to prioritize high-margin immunoglobulin output over albumin while viral inactivation compliance costs reshape facility economics.
Growth Catalysts
- EMA viral safety mandates:Stricter EU Good Manufacturing Practice standards for pathogen reduction are consolidating demand toward validated fractionators with established inspection histories, accelerating replacement of legacy facilities.
- Home care migration:Subcutaneous immunoglobulin delivery is displacing hospital-based infusion for primary immune deficiency patients, expanding addressable patient populations beyond institutional capacity limits.
- German collection network density:Centralized plasma procurement infrastructure and reimbursement depth in Germany are sustaining per-capita therapy access rates that outpace Southern European markets.
Market Restraints
- Plasma supply concentration:United States-derived plasma dominates global source material, exposing fractionators to FDA donor eligibility policy shifts and geographic supply shocks.
- Recombinant substitution:Engineered coagulation factors are capturing hemophilia treatment share from plasma-derived equivalents, compressing pricing power in the highest-premium therapy segment.
- Fractionation capex intensity:New viral inactivation and chromatographic purification equipment requires nine-figure facility investments that bar mid-scale entrants from regulatory compliance.
Strategic Opportunities
- Neurological indication expansion:CIDP and multifocal motor neuropathy are emerging as immunoglobulin growth vectors beyond traditional immune deficiency, with dosing protocols under clinical refinement.
- Asia-Pacific collection infrastructure:Takeda-operated centers in Japan and licensed Chinese collection networks offer untapped source plasma access for fractionators with regional regulatory expertise.
- ISO 13485 quality certification:Medical device-grade manufacturing standards are becoming a procurement discriminator for hospital systems consolidating supplier panels under value-based purchasing frameworks.
Industry Challenges
- Plasma protein assay standardization:Lot-to-lot potency variability in immunoglobulin products complicates dosing consistency and adverse event tracking across chronic therapy populations.
- Cold chain integrity maintenance:Temperature excursion risks during subcutaneous product distribution to home care settings demand specialized logistics partnerships that fragment fulfillment economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma-Derived Protein Therapies Market |
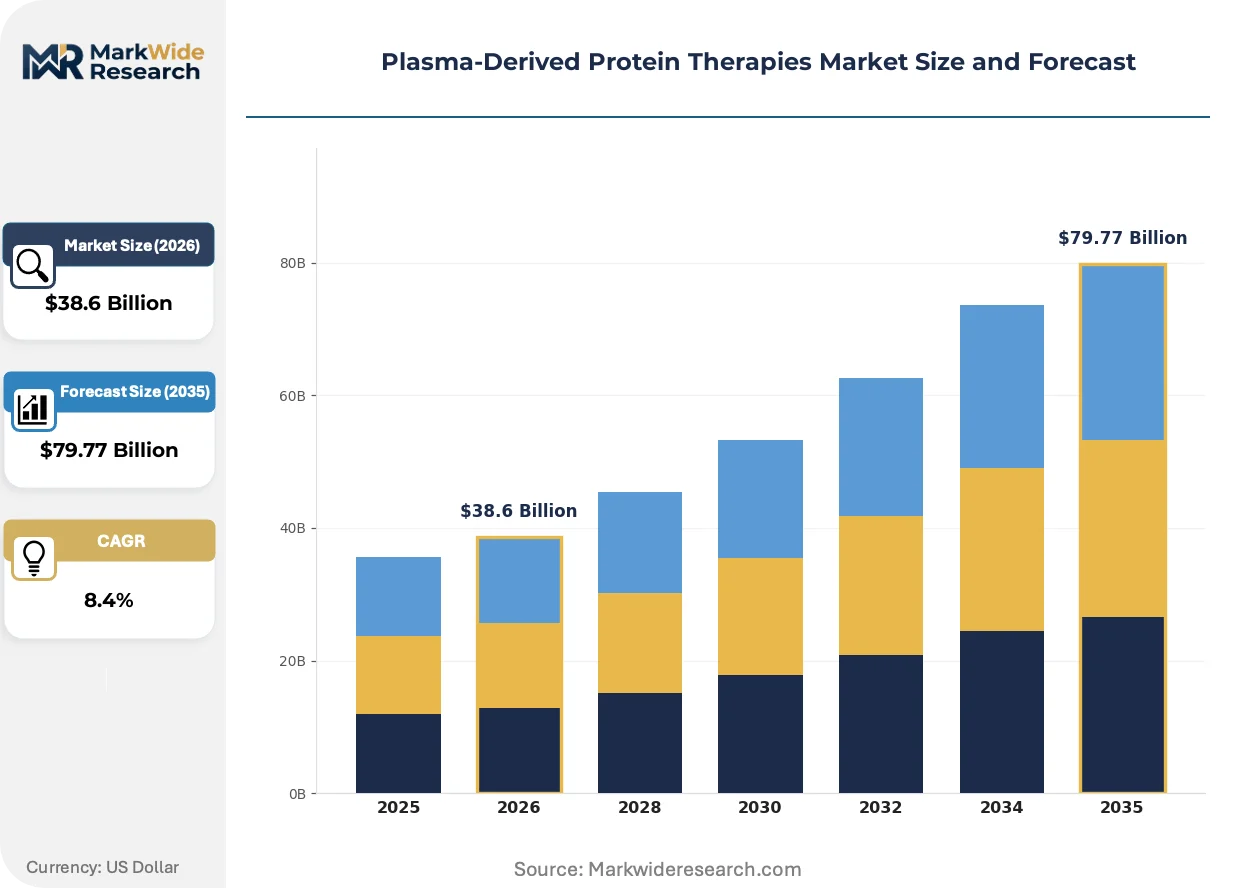
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulin, Coagulation Factors, Albumin, Hyperimmune Globulins End User: Hospitals, Clinics, Blood Banks, Home Care Application: Hemophilia, Immune Disorders, Trauma, Autoimmune Diseases Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Others |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Grifols, Octapharma, Kedrion, ADMA Biologics, BPL, Biotest AG, SK Plasma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma-Derived Protein Therapies Market Evolving Landscape
Chromatographic purification advances are displacing cold ethanol fractionation as the dominant isolation methodology, while regulatory frameworks on both sides of the Atlantic tighten manufacturing accountability.
Capto MMC multimodal chromatography is converging with nanofiltration viral clearance to enable higher-purity immunoglobulin yields from lower-volume plasma inputs. Specialty fractionators in Switzerland and Austria are retrofitting legacy facilities with these combined systems to extend batch economics without greenfield construction. The technology pairing is compressing cost per gram for intravenous formulations while meeting EMA pathogen safety thresholds.
FDA's updated Guidance for Industry on Plasma-Derived Products now mandates enhanced donor deferral screening and nucleic acid testing protocols for emerging pathogens. US-based fractionators are absorbing compliance costs through facility automation investments that reduce manual handling contamination risks. The immunoglobulin segment bears the heaviest documentation burden due to chronic dosing regimens and pediatric patient exposure.
Hospital procurement committees are consolidating plasma protein contracts under single-source agreements that bundle immunoglobulin, albumin, and coagulation factor supply. Integrated delivery networks in the Northeastern United States are replacing fragmented multi-vendor purchasing with formulary standardization that prioritizes supply security over unit price negotiation. The concentration trend is visible most acutely in academic medical centers managing complex hemophilia treatment centers.
Plasma-Derived Protein Therapies Market Segmentation
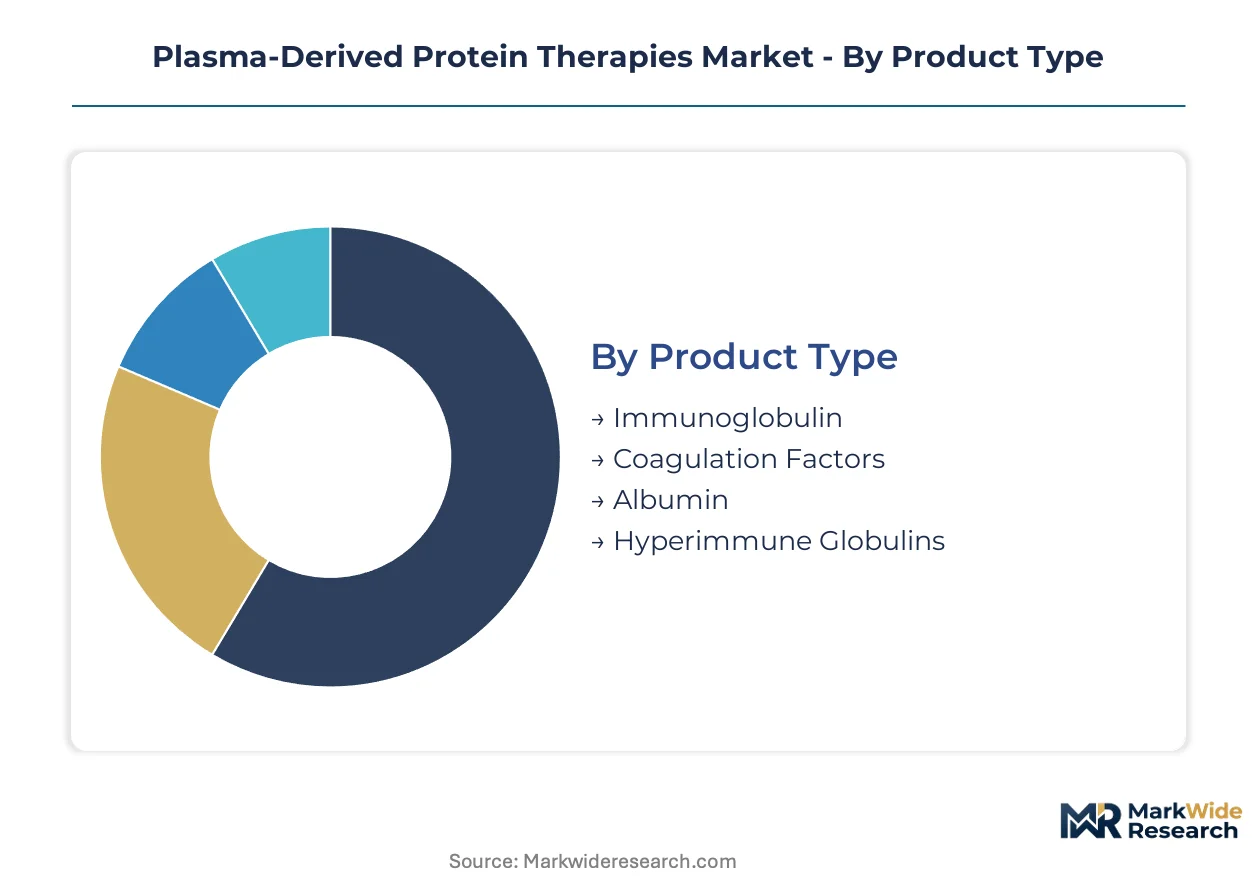
Plasma-derived protein therapies segment across product chemistry, clinical setting, disease target, and administration route. Each dimension carries distinct margin profiles, regulatory pathways, and competitive dynamics that reshape procurement priorities for fractionators and healthcare systems.
Product Type:
Upgrade cycles favor high-purity immunoglobulin output as fractionators retrofit ethanol-based plants with multimodal chromatography systems.
- Immunoglobulin:Polyclonal antibody concentrates isolated through Cohn fractionation or chromatographic capture, then stabilized for intravenous or subcutaneous infusion. German and US hospital systems are concentrating chronic replacement volume for primary immune deficiency patients, while EMA pathogen safety mandates are consolidating supply toward validated fractionators with established inspection histories.
- Coagulation Factors:Clotting protein concentrates—primarily Factors VIII, IX, and prothrombin complex—derived from large-pool plasma fractionation. Hemophilia treatment centers in academic medical settings are absorbing premium-priced inventory despite recombinant substitution pressure, as plasma-derived products retain advantages in inhibitor patients and developing markets.
- Albumin:Human serum albumin for volume expansion and protein replacement, manufactured through cold ethanol precipitation. Trauma and critical care applications in institutional settings sustain baseline demand.
- Hyperimmune Globulins:Pathogen-specific antibody concentrates from vaccinated or convalescent donor plasma. Niche demand concentrates in rabies, hepatitis B, and tetanus post-exposure prophylaxis.
Immunoglobulin sits at the top of the volume ranking, with hyperimmune globulins climbing the fastest through emerging infectious disease applications.
End User:
Cost tier differentiation separates capital-intensive hospital infusion centers from decentralized home care delivery models.
- Hospitals:Academic medical centers and trauma facilities managing complex hemophilia treatment centers and critical care volume replacement. Northeastern US integrated delivery networks are consolidating plasma protein contracts under single-source agreements that bundle immunoglobulin, albumin, and coagulation factor supply.
- Home Care:Subcutaneous immunoglobulin administration by primary immune deficiency patients outside institutional settings. Patient preference for reduced infusion center dependency is expanding addressable populations beyond hospital capacity constraints.
- Clinics:Outpatient infusion centers handling routine immunoglobulin replacement and coagulation factor prophylaxis.
- Blood Banks:Institutional repositories managing albumin inventory for surgical and trauma applications.
Hospitals command the highest absolute spend, though home care is gaining share fastest through subcutaneous delivery adoption.
Application:
Margin concentration tracks disease chronicity, with lifelong replacement therapies outperforming acute episodic indications.
- Immune Disorders:Primary and secondary immunodeficiency requiring chronic immunoglobulin replacement. Pediatric patient exposure intensifies documentation burdens and lot-to-lot potency tracking requirements.
- Autoimmune Diseases:CIDP and multifocal motor neuropathy are emerging as immunoglobulin growth vectors beyond traditional immune deficiency, with dosing protocols under clinical refinement.
- Hemophilia:Inherited coagulation factor deficiency managed through prophylactic or on-demand replacement. Recombinant competition is compressing pricing power in this historically premium segment.
- Trauma:Acute volume resuscitation and protein replacement in emergency settings. Albumin dominates this application with standardized dosing protocols.
Immune disorders anchor revenue stability, while autoimmune diseases are expanding most quickly through neurological indication approvals.
Delivery Mode:
Patient convenience preferences are accelerating route migration from institutional infusion to self-administered delivery.
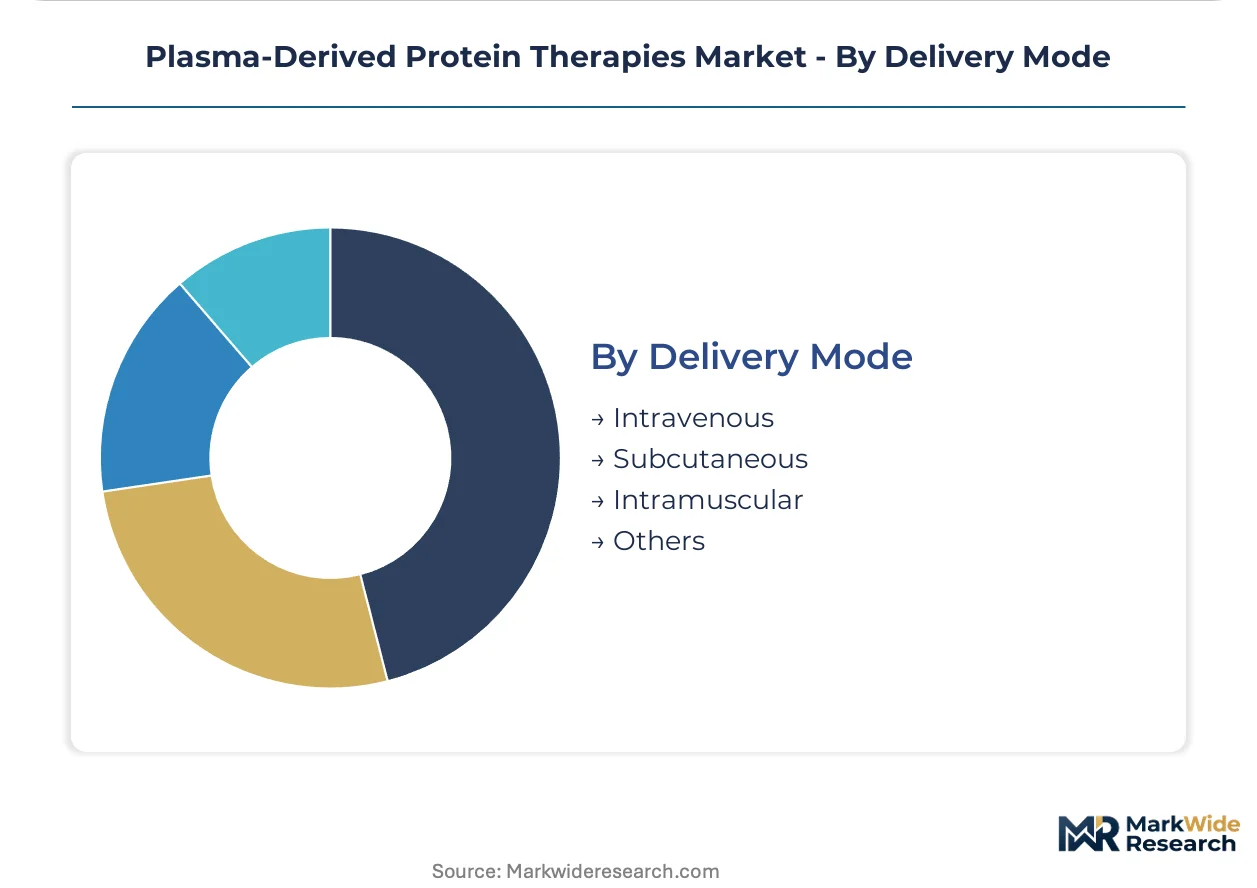
- Subcutaneous:Immunoglobulin delivery via portable infusion pumps for home-based chronic replacement. Cold chain integrity maintenance demands specialized logistics partnerships that fragment fulfillment economics.
- Intravenous:Hospital-based infusion for trauma, critical care, and high-dose immunoglobulin protocols. Still dominates acute applications requiring rapid volume administration.
- Intramuscular:Hyperimmune globulin administration for post-exposure prophylaxis in rabies and hepatitis B.
- Others:Emerging depot formulations and sustained-release technologies under clinical development.
Intravenous retains the largest procedure volume, with subcutaneous delivery climbing fastest among primary immune deficiency populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fractionation capacity deployment as manufacturers migrate investment toward jurisdictions with established viral safety inspection histories and centralized procurement infrastructure.
United States
FDA donor eligibility policies and nucleic acid testing mandates dominate plasma sourcing protocols for fractionators serving domestic and export markets. The agency's updated Guidance for Industry on Plasma-Derived Products imposes enhanced deferral screening that elevates compliance costs for collection center operators. North Carolina and Georgia host concentrated fractionation infrastructure where facility automation investments reduce manual handling contamination risks.
Germany
Centralized plasma procurement networks and reimbursement depth sustain per-capita therapy access rates exceeding Southern European benchmarks. EMA Good Manufacturing Practice standards enforced through national competent authorities consolidate demand toward validated fractionators with established inspection histories. Bavaria anchors European fractionation output through high-volume immunoglobulin and albumin production facilities serving hospital system contracts.
Japan
PMDA oversight of plasma collection center licensing and fractionation facility certification creates barriers to foreign source material importation. METI industrial policy supports domestic self-sufficiency in blood products through targeted infrastructure investment. The Kanto region around Tokyo concentrates plasma-derived protein manufacturing capacity serving national health insurance reimbursement frameworks.
Switzerland
Swissmedic regulatory stringency and ISO 13485 quality certification requirements position the country as a premium-tier manufacturing jurisdiction. Specialty fractionators retrofit legacy facilities with multimodal chromatography and nanofiltration viral clearance systems to extend batch economics. The Basel-Zurich corridor hosts precision purification operations supplying hospital systems under value-based purchasing frameworks.
Australia
TGA plasma quality guidelines and fractionation facility licensing determine collection eligibility and pathogen safety testing protocols for domestic manufacturers. National blood supply arrangements through the National Blood Authority concentrate procurement decision-making at the federal level. Victoria and New South Wales maintain plasma collection infrastructure supporting regional self-sufficiency in immunoglobulin and coagulation factor supply.
Plasma-Derived Protein Therapies Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue niche indication specialization and regional collection infrastructure partnerships. The vendor base concentrates among fractionators with validated viral reduction protocols and multi-decade inspection histories with FDA and EMA. Three archetypes dominate: vertically integrated plasma collectors with captive fractionation capacity, specialized immunoglobulin manufacturers with chromatographic purification expertise, and regional champions leveraging geographic collection network density. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers address fractionation constraints against rising collection volumes.
Within the vertically integrated tier, CSL Behring and Takeda Pharmaceutical Company Limited exemplify archetypes spanning collection through finished sterile product. Grifols occupies a position emphasizing high-volume output from European and US plasma network concentration. These three anchors demonstrate how geographic collection infrastructure and regulatory compliance depth determine competitive positioning in a market where viral safety validation histories serve as durable barriers to new entrant expansion.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Grifols |
| Octapharma |
| Kedrion |
| ADMA Biologics |
| BPL |
| Biotest AG |
| SK Plasma |
| Others |
Value Network & Pricing Analysis
Academic medical center procurement committees command pricing leverage through single-source bundling agreements that consolidate immunoglobulin, albumin, and coagulation factor contracts. This buyer concentration forces fractionators toward contract-based long-term offtake structures with volume-tiered discounts.
Pricing Analysis
Distributor margins compress as hospital systems consolidate supplier panels under value-based purchasing frameworks. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified Swissmedic-validated product from standard EMA-compliant output and economy-grade albumin. Pricing pressure stems from recombinant coagulation factor substitution in hemophilia treatment. Pediatric immune deficiency programs show least price sensitivity due to chronic dosing requirements and lot-to-lot potency tracking burdens.
Supply Chain Analysis
Regional distribution centers in North Carolina, Georgia, and Bavaria anchor hub-and-spoke patterns radiating to hospital systems and home care logistics partners. Source plasma draws from United States, Germany, and Austrian collection networks. Cold chain integrity maintenance depends on specialized logistics partnerships for subcutaneous immunoglobulin home delivery. Single-source vulnerability concentrates in FDA donor eligibility policy shifts affecting US plasma access. Distribution runs through fractionator-controlled cold storage facilities to institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-derived protein therapies function as a geographic-arbitrage play where EMA viral safety compliance costs in Europe run substantially higher than FDA-aligned facility automation investments in the United States.
For Market Incumbents: Anchor fractionation capacity in jurisdictions with established inspection histories to defend against emerging chromatographic purification specialists. Prioritize multimodal Capto MMC retrofit investments in legacy Bavarian and Swiss facilities. Extend validated viral reduction protocol documentation to meet EMA Good Manufacturing Practice consolidation mandates. Lock hospital procurement committees through single-source bundling that co-opts albumin and coagulation factor volume. For New Entrants and Emerging Players: The premium-to-economy tier price gap in subcutaneous immunoglobulin delivery creates entry space for ISO 13485-certified regional fractionators. Target Asia-Pacific collection infrastructure partnerships in Japan and licensed Chinese networks where PMDA and NMPA barriers limit incumbent expansion. Pursue neurological indication specialization in CIDP and multifocal motor neuropathy dosing protocols. Deploy direct-to-home-care logistics partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Specialty pharmaceutical companies with existing immunology portfolios are the most active acquirer in this space. Five-to-ten year viability hinges on fractionation capacity scarcity against expanding autoimmune and neurological indications. Target mid-scale fractionators with chromatographic purification expertise and established EMA inspection histories. Monitor plasma protein assay standardization progress as the inflection indicator for dosing consistency premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Purification Retrofit | Capto MMC systems in Swiss and Austrian facilities extend batch economics without greenfield construction. |
| EMA Viral Safety Compliance Investment | Facility automation reduces manual handling contamination risks under updated FDA Guidance for Industry. |
| Home Care Logistics Partnership | Specialized cold chain fulfillment fragments economics but captures subcutaneous immunoglobulin volume expansion. |
| Asia-Pacific Collection Infrastructure | Takeda-operated Japanese centers and licensed Chinese networks offer untapped source plasma access. |
| Neurological Indication Clinical Development | CIDP and multifocal motor neuropathy dosing refinement expands immunoglobulin addressable populations beyond immune deficiency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged fractionation facility directors, EMA regulatory affairs leads, hospital procurement managers at academic medical centers, and home care infusion coordinators. Secondary validation drew from FDA Guidance for Industry filings, EMA Good Manufacturing Practice inspection records, ClinicalTrials.gov immunoglobulin protocol registrations, and hospital GPO contract databases. Bottom-up plasma collection volume modeling triangulated against top-down therapy demand projections.
Comparable historical periods anchored the forecast window to pre-pandemic baseline utilization and post-viral-safety-mandate capacity adjustments. Segmentation modeling spanned product chemistry tiers, administration route migration patterns, disease target chronicity, and regional regulatory cluster alignment. CAGRs derived from plasma collection growth trajectories mapped against fractionation capacity expansion schedules. Forecast inputs included viral inactivation compliance cost absorption rates and subcutaneous delivery adoption curves.
Caveats apply where EMA pathogen safety mandate enforcement intensity or FDA donor eligibility policy shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding plasma collection network expansion and chromatographic purification yield improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Simvastatin Market