
 Facial Paralysis Market | 2026-2036
Facial Paralysis Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Paralysis Market Analysis
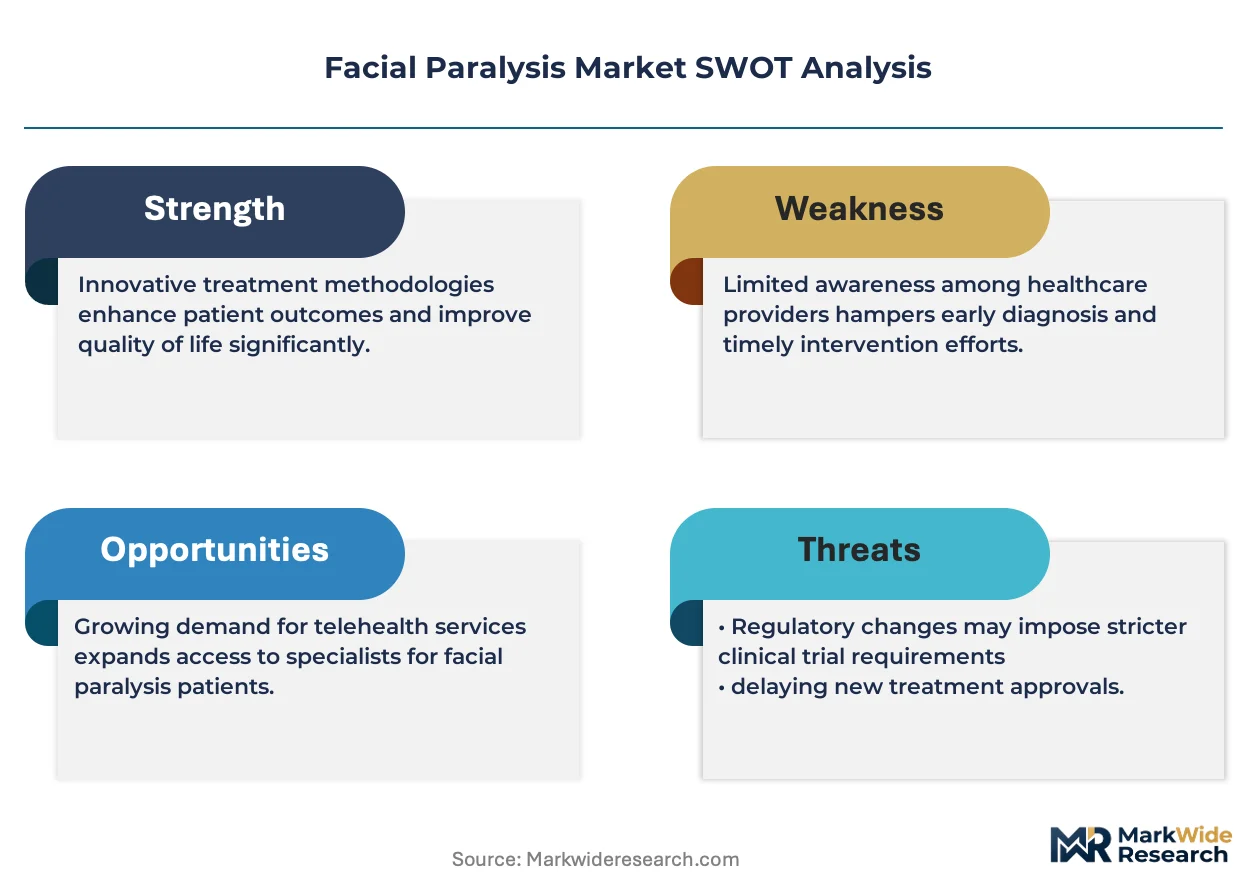
Botulinum toxin formulations are expanding their role beyond cosmetic applications into functional rehabilitation for synkinesis and facial asymmetry. Pfizer Inc. leverages its neurology portfolio to sustain clinical trial pipelines across multiple facial paralysis indications. Boston Scientific Corporation anchors its position through electrostimulation platforms designed for facial nerve retraining protocols. AbbVie Inc. differentiates via Allergan-derived neuromodulator expertise that occupies a leading share of therapeutic botulinum toxin applications.
Facial paralysis constitutes the partial or complete loss of voluntary muscle movement in the face, typically resulting from seventh cranial nerve damage due to Bell's palsy, trauma, tumor resection, or viral infection; functional parameters include House-Brackmann grading scales and Sunnybrook facial grading systems that quantify symmetry at rest and during motion. Surgical treatments command premium positioning due to microvascular nerve transfer complexity and specialized surgeon scarcity. Neuromodulators represent the fastest-expanding segment as outpatient injection protocols reduce hospital dependency. Physical therapy devices occupy a mature, cost-sensitive tier where reimbursement variability constrains margin expansion.
FDA clearance pathways for Class II and Class III electrostimulation devices impose multi-year validation requirements that filter market entrants. EMA's Medical Device Regulation and Japan's PMDA standards for neurostimulation systems create parallel compliance burdens for multinational manufacturers. WHO disability assessment frameworks increasingly recognize facial function as a quality-of-life determinant, expanding advocacy for treatment access in public health systems. Stakeholders must monitor evolving FDA guidance on adaptive trial designs for rare facial nerve disorders and anticipate how real-world evidence requirements will reshape post-market study obligations.
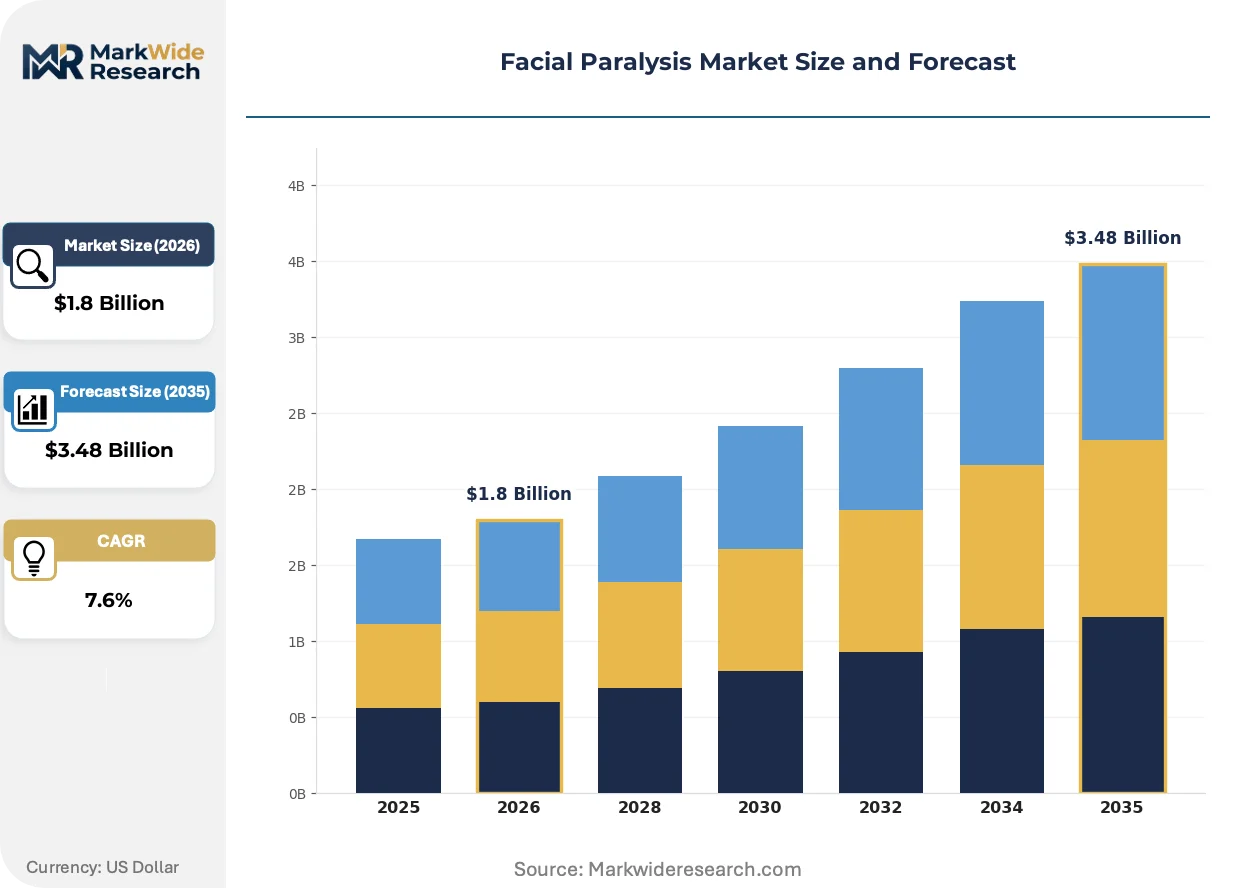
Market Dynamics
Neuromodulator injection protocols are compressing treatment timelines and shifting patient flow from inpatient surgical suites to ambulatory settings, restructuring how providers configure facial nerve service lines.
Growth Catalysts
- Adaptive trial design guidance:FDA pathways for rare facial nerve disorders accelerate biologics validation timelines. Device manufacturers leverage streamlined pre-submission meetings to compress development cycles.
- Rehabilitation robotics:Electrostimulation platforms enable home-based facial retraining protocols. Patients in Germany and Japan access reimbursed remote monitoring through specialized nerve centers.
- WHO disability frameworks:Recognition of facial function as a quality-of-life determinant expands public health system advocacy. National reimbursement bodies in multiple geographies now cover functional restoration procedures previously classified as cosmetic.
Market Restraints
- Microvascular surgeon scarcity:Nerve transfer complexity limits procedure volume growth. Training pipelines produce fewer than fifty specialized surgeons annually across major markets.
- Biologics cold chain requirements:Botulinum toxin storage and transport impose distribution costs. Temperature excursions degrade product efficacy and trigger safety reporting obligations.
- EMA MDR compliance burdens:Neurostimulation device recertification consumes eighteen to twenty-four months. Smaller manufacturers exit rather than absorb notified body audit costs.
Strategic Opportunities
- Pediatric congenital indications:Moebius syndrome and birth trauma applications remain underpenetrated. Dedicated pediatric facial nerve centers in the United States and Germany establish protocol templates.
- Telehealth-integrated physical therapy:Remote assessment tools using smartphone-based symmetry measurement expand access. Rural patients bypass travel requirements to urban tertiary centers.
- Real-world evidence mandates:FDA post-market study requirements create data infrastructure partnerships. Registry platforms aggregate outcomes across dispersed treatment sites.
Industry Challenges
- Electrophysiology technician training:Facial nerve monitoring during parotid and acoustic neuroma surgery requires specialized certification. Hospital staffing shortages delay surgical schedule expansion.
- Cross-border licensing complexity:Telemedicine platforms delivering remote neuromodulator guidance face practitioner credentialing fragmentation. State-level medical board variations impede scalable service models.
- Legacy EMR integration:Sunnybrook and House-Brackmann grading data lack standardized interoperability. Quantitative outcome tracking requires manual abstraction or custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Paralysis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Treatments, Neuromodulators, Physical Therapy Devices, Assistive Technologies End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Treatment Method: Medications, Surgery, Electrostimulation, Massage Therapy Severity Level: Mild, Moderate, Severe, Complete |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., Boston Scientific Corporation, Bayer AG, AbbVie Inc., Novartis AG, Johnson & Johnson, Siemens Healthcare GmbH, Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Paralysis Market Emerging Trajectories
Digital biomarker capture and algorithmic treatment planning are restructuring how clinicians assess facial nerve recovery and calibrate intervention intensity.
Smartphone-based facial symmetry analysis applications are decentralizing initial assessment and progress monitoring. Primary care networks in the United States and community hospitals in Germany deploy these tools to triage patients toward appropriate specialist referral. The technology is decentralizing geographic access constraints that previously concentrated diagnosis in major urban nerve centers.
EMA's Medical Device Regulation imposes clinical evidence requirements for electrostimulation devices that previously qualified under self-certification. Manufacturers must generate prospective safety and performance data for Class IIa and above neurostimulation systems. Facial retraining device categories face the steepest compliance cost increases, favoring larger portfolio holders with established clinical affairs infrastructure.
Patients increasingly demand unbundled procedure pricing with transparent out-of-pocket exposure before committing to surgical intervention. Academic medical centers in Japan and private specialty clinics in Germany respond with packaged episode-of-care rates. This behavioral shift pressures traditional fee-for-service reimbursement models and accelerates value-based contracting experiments in United States health systems.
Facial Paralysis Market Segmentation
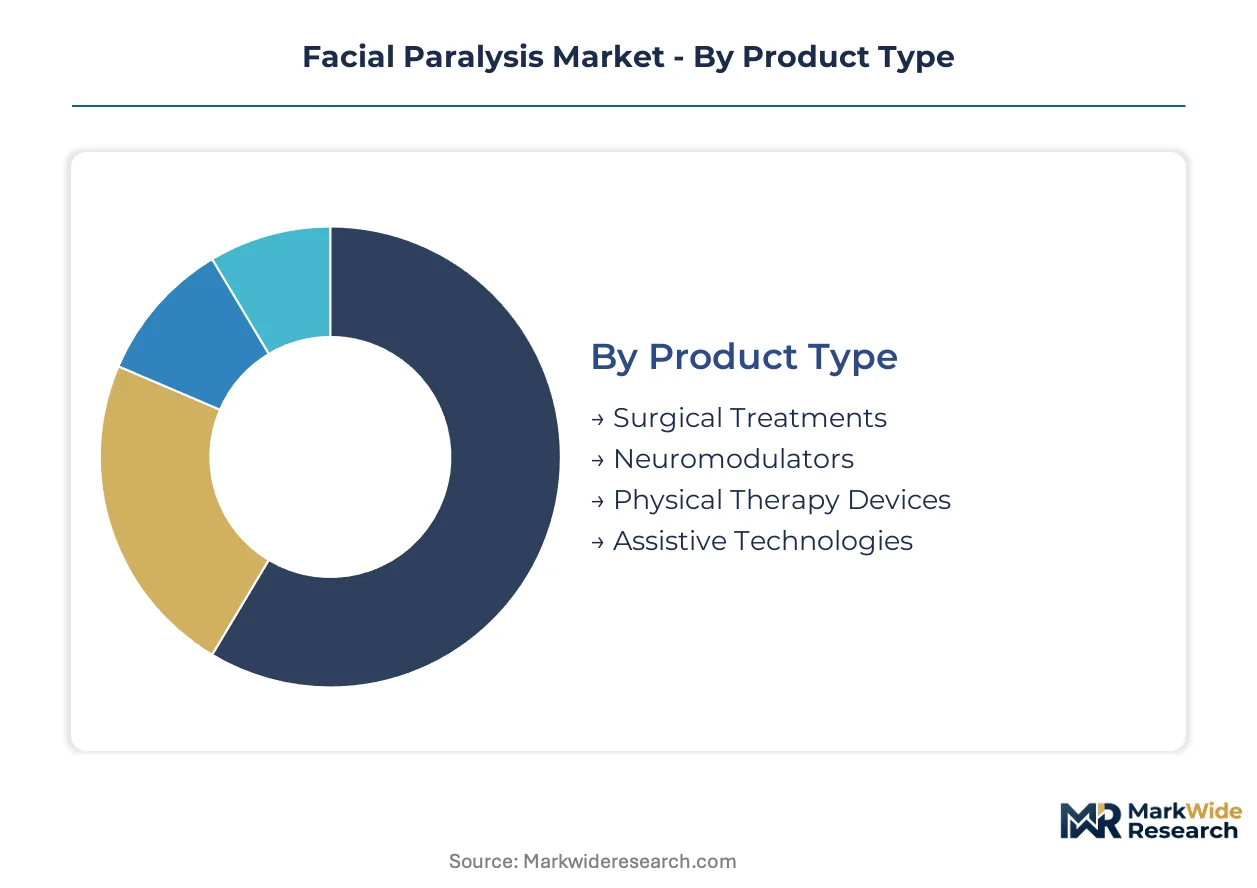
Facial paralysis treatment selection hinges on House-Brackmann grading, surgical candidacy, and reimbursement tier. Segmentation reveals how neuromodulators compress hospital revenue while surgical complexity sustains premium pricing. Understanding these splits enables targeted service line configuration across ambulatory and inpatient settings.
Product Type:
Surgical treatments anchor value concentration despite lower procedure volumes, while neuromodulators dominate patient throughput with compressed margins per encounter.
- Surgical Treatments:Microvascular nerve transfers and static slings require specialized microsurgical suites. Demand concentrates in academic medical centers across the United States, Germany, and Japan where fellowship-trained surgeons command six-figure procedure fees and limited annual capacity.
- Neuromodulators:Botulinum toxin protocols for synkinesis management deliver outpatient efficiency with quarterly injection cycles. Rehabilitation centers in Germany access broad reimbursement for functional asymmetry correction, expanding beyond cosmetic indications.
- Physical Therapy Devices:Surface electrostimulation units for home-based facial retraining occupy cost-sensitive procurement tiers.
- Assistive Technologies:Eyelid weight implants and oral commissure splints address functional deficits in severe cases.
Today's leader: Surgical Treatments. Tomorrow's challenger: Neuromodulators.
End User:
Site-of-care migration reshapes capital allocation as reimbursement favors ambulatory settings over traditional hospital anchoring.
- Hospitals:Tertiary nerve centers integrate multidisciplinary facial paralysis teams spanning otolaryngology, plastic surgery, and neurology. United States academic medical centers maintain dominant positions through bundled episode payments that capture surgical, inpatient, and rehabilitation phases.
- Rehabilitation Centers:Specialized facial nerve clinics in Japan deploy electrostimulation protocols with remote monitoring integration. PMDA reimbursement pathways for neurostimulation device rental sustain margin structures unavailable in purely device-sale markets.
- Home Care:Patient-administered mirror therapy and smartphone-guided exercise programs reduce specialist dependency.
- Clinics:Dermatology and neurology practices capture neuromodulator injection volume with lower overhead than hospital-based administration.
Hospitals retain complex surgical volume; clinics capture expanding neuromodulator share.
Treatment Method:
Intervention intensity correlates with severity grading, creating distinct reimbursement and outcome tracking requirements across the care continuum.
- Medications:Corticosteroid protocols for acute Bell's palsy and antiviral adjuncts constitute first-line community management. Primary care networks in the United States initiate treatment within seventy-two hours of symptom onset per AAO-HNS guidelines.
- Surgery:Nerve decompression, grafting, and muscle transfer procedures target House-Brackmann IV-VI presentations. Microvascular surgeon scarcity across all major markets limits annual procedure growth regardless of underlying disease incidence.
- Electrostimulation:Transcutaneous and percutaneous facial nerve stimulation enables home-based neuromuscular retraining.
- Massage Therapy:Manual lymphatic drainage and facial exercise protocols support synkinesis management.
Medications dominate incident volume; surgery commands value concentration.
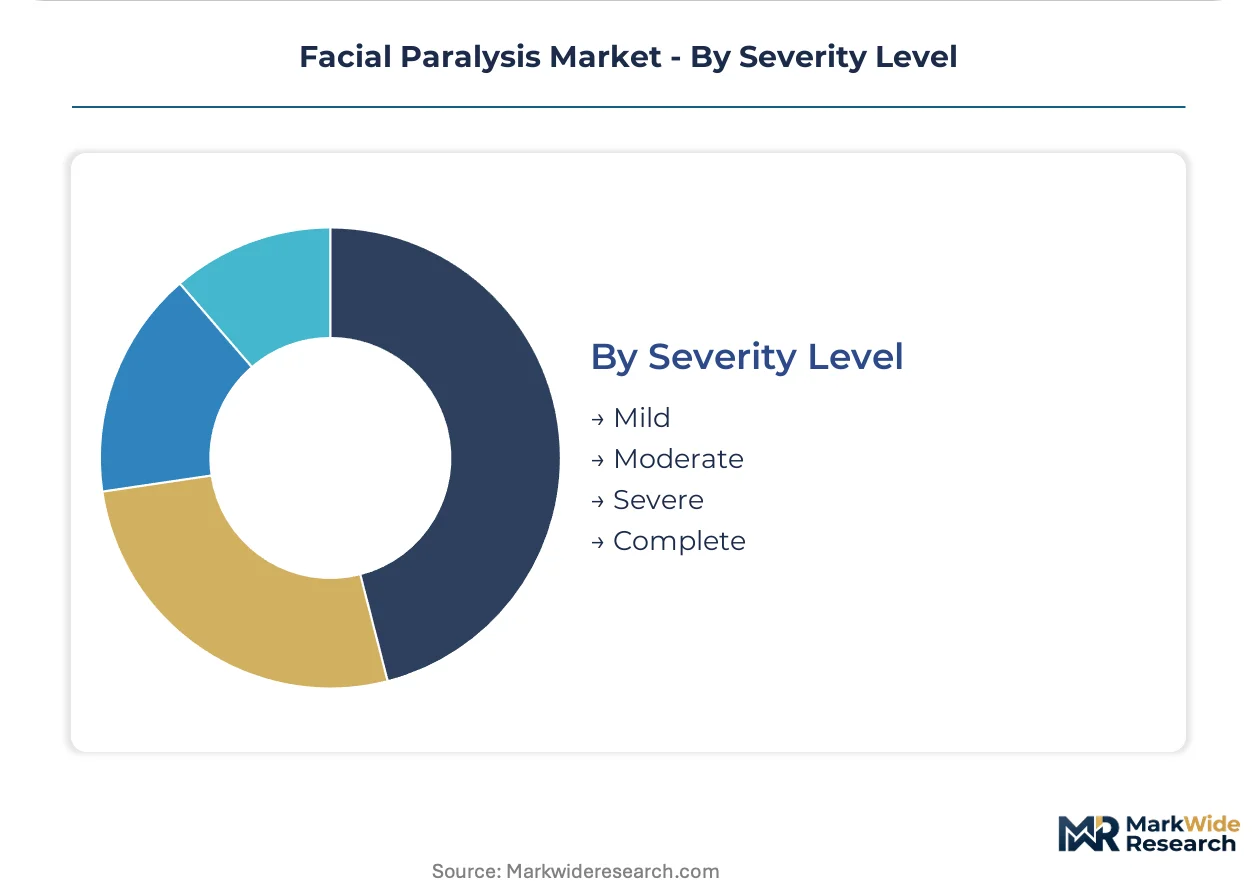
Severity Level:
Grading system alignment determines treatment eligibility and payer authorization thresholds across public and private coverage schemes.
- Mild:House-Brackmann Grade I-II presentations with subtle asymmetry at rest or motion. Patients in Germany access early physiotherapy referral through statutory health insurance without specialist gatekeeping.
- Moderate:Grade III-IV deficits with visible dysfunction and functional impairment including incomplete eye closure. United States commercial payers increasingly require documented failure of conservative management before authorizing surgical consultation.
- Severe:Grade V presentations with minimal voluntary movement and significant functional compromise.
- Complete:Grade VI flaccid paralysis requiring comprehensive surgical reconstruction or permanent assistive device dependence.
Moderate severity generates contested utilization; complete paralysis drives surgical innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized facial nerve centers in the United States anchor clinical trial density and surgical innovation pipelines. Reimbursement frameworks in Germany and Japan accelerate neuromodulator adoption beyond cosmetic classifications. Regulatory pathways across FDA, EMA, and PMDA jurisdictions filter device market entrants through multi-year validation cycles.
United States
Academic medical centers in Massachusetts and California concentrate microvascular surgeon training pipelines and bundled episode payment experiments. FDA adaptive trial design guidance for rare facial nerve disorders compresses biologics validation timelines for sponsors. Tertiary nerve centers in Boston and San Francisco integrate multidisciplinary teams spanning otolaryngology, plastic surgery, and neurology rehabilitation protocols.
Germany
Statutory health insurance covers functional botulinum toxin applications for synkinesis management, expanding patient access beyond cosmetic tiers. EMA Medical Device Regulation imposes eighteen-to-twenty-four-month recertification cycles for electrostimulation systems. Facial nerve clinics in Berlin and Munich deploy reimbursed remote monitoring protocols for home-based neuromuscular retraining.
Japan
PMDA reimbursement pathways for neurostimulation device rental sustain margin structures unavailable in pure device-sale markets. METI standards for home healthcare equipment shape electrostimulation platform design specifications. Specialized rehabilitation centers in Tokyo and Osaka integrate smartphone-based symmetry measurement tools into telehealth-physical therapy hybrids.
United Kingdom
NHS England referral pathways for House-Brackmann Grade III-IV presentations require documented conservative management failure before surgical authorization. MHRA post-market surveillance mandates for Class IIa neurostimulation devices align with EMA MDR transition timelines. London teaching hospitals maintain fellowship programs producing fewer than ten specialized microvascular surgeons annually.
Switzerland
Swissmedic expedited pathways for breakthrough facial nerve devices attract EU-headquartered manufacturers seeking parallel regulatory validation. Cantonal health insurance variations create reimbursement fragmentation for electrostimulation therapy across Zurich, Geneva, and Basel clusters. University Hospital Zurich anchors European surgical innovation through nerve transfer protocol development and outcomes registry leadership.
Facial Paralysis Market Vendor Landscape
Portfolio diversification dominates the current landscape as pharmaceutical incumbents extend neurology franchises into facial nerve indications. The vendor base concentrates around three strategic tiers: diversified pharmaceutical conglomerates with neuromodulator portfolios, electrostimulation device manufacturers with neurostimulation expertise, and specialized surgical supply providers. Market structure reflects high barriers to entry from FDA Class III device validation and microvascular surgeon training scarcity. Competitive moves center on biologics pipeline expansion and electrostimulation platform integration with remote monitoring capabilities.
Within the pharmaceutical tier, Pfizer Inc. and AbbVie Inc. occupy positions anchored by neuromodulator development infrastructure and Allergan-derived therapeutic botulinum toxin expertise. Boston Scientific Corporation exemplifies the electrostimulation archetype through neurostimulation platform specialization. These three entities represent distinct competitive vectors: pharmaceutical biologics, therapeutic neuromodulators, and device-based neuromuscular retraining systems.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| Boston Scientific Corporation |
| Bayer AG |
| AbbVie Inc. |
| Novartis AG |
| Johnson & Johnson |
| Siemens Healthcare GmbH |
| Astellas Pharma Inc. |
| Others |
Supply Flow & Price Mechanics
EMA MDR clinical evidence requirements for Class IIa neurostimulation devices gate qualified supply access and premium-tier pricing power, compressing margins for manufacturers lacking established clinical affairs infrastructure while rewarding portfolio holders with pre-certified platforms.
Pricing Analysis
Input-cost pass-through from biologics cold chain logistics and specialized microsurgical instrument fabrication drives three-tier pricing structure across premium, standard, and economy levels. Premium tiers command six-figure procedure fees at academic nerve centers where fellowship-trained surgeon scarcity limits capacity. Price differentiation hinges on certification grade and vertical integration depth. Pricing pressure stems from ambulatory migration as neuromodulator protocols displace inpatient surgical encounters. Rehabilitation centers exhibit highest price sensitivity; tertiary academic centers demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from hospital GPOs and specialized nerve centers mandate multi-supplier qualification for botulinum toxin formulations and electrostimulation platforms. Manufacturing concentrates in the United States, Germany, and Switzerland for device final assembly; active pharmaceutical ingredients draw from established biologics production hubs. Critical dependencies include medical-grade silicone for implants, precision microelectronics for stimulation systems, and temperature-controlled logistics infrastructure. Single-source vulnerability runs through specialized microvascular instrument suppliers. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-clinic neuromodulator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory validation timelines into durable competitive moats, with FDA adaptive trial design guidance for rare facial nerve disorders accelerating biologics pipelines and reshaping investor return profiles.
For Market Incumbents: To counter electrostimulation platform commoditization from EMA MDR compliance burdens, deepen backward integration into surgical instrument manufacturing and secure exclusive GPO contracts with top-decile nerve centers. Prioritize certification investment for pediatric congenital indications where protocol templates establish switching costs. For New Entrants and Emerging Players: Telehealth-integrated physical therapy platforms represent the most penetrable white space, enabling rural patient access without tertiary center dependency. Target home-based facial retraining segments where reimbursement variability has deterred incumbent investment. Deploy smartphone-based symmetry measurement as the go-to-market wedge to bypass capital-intensive device hardware. For Investors and Strategic Acquirers: Valuations sit cheapest among electrostimulation device manufacturers facing eighteen-to-twenty-four-month EMA recertification cycles. Long-term viability over a five-to-ten year window favors targets with established FDA 510(k) clearances and remote monitoring software companions. Watch FDA real-world evidence mandate implementation as the inflection signal for registry-platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Recertification Pathway | Eighteen-to-twenty-four-month validation cycles filter smaller electrostimulation manufacturers from competitive participation. |
| Hospital System Partnership | Bundled episode payments at academic medical centers capture surgical, inpatient, and rehabilitation phases under single contract. |
| Software Companion Development | Smartphone-based symmetry measurement tools enable telehealth-physical therapy hybrids reimbursable in Germany and Japan. |
| Pediatric Protocol Template | Moebius syndrome and birth trauma applications at dedicated centers establish switching costs for congenital indications. |
| Reimbursement Strategy | WHO disability framework recognition expands statutory coverage for functional restoration beyond cosmetic classifications. |
Methodological Framework
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with microvascular surgeons, facial nerve clinic directors, GPO contracts managers, and neuromodulator reimbursement specialists against secondary validation from FDA 510(k) filings, EMA MDR submission databases, ClinicalTrials.gov facial nerve disorder entries, and hospital procurement database extracts.
Input-output matrices map treatment method intensity against severity grading distributions across United States, German, and Japanese nerve centers. Segmentation dimensions span product type, end-user site-of-care, treatment method, and severity level. CAGRs derive from procedure volume trajectories and pricing tier migration patterns. Forecast inputs incorporate microvascular surgeon training pipeline outputs and EMA notified body audit capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA real-world evidence mandate enforcement intensity and PMDA neurostimulation device rental reimbursement stability. Deviation in microvascular surgeon fellowship graduation rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market