
 Marfan Syndrome Treatment Market | 2026-2036
Marfan Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Marfan Syndrome Treatment Market Analysis
Modular care bundles combining genetic counseling with cardiovascular surveillance is recalibrating how hospitals purchase Marfan syndrome services. Novartis Pharmaceuticals Corporation leverages its cardiovascular therapy portfolio to anchor presence in beta-blocker and ARB segments for aortic protection. Baxter Healthcare Corporation sustains critical supply positions in surgical products used during prophylactic aortic repair procedures. Sanofi competes through established channels in antihypertensive therapies that manage hemodynamic stress in Marfan patients.
Marfan syndrome treatment encompasses pharmacological, surgical, and monitoring interventions targeting the connective tissue disorder's cardiovascular, skeletal, and ocular manifestations, with beta-adrenergic blockade remaining the foundational pharmacologic approach to reduce aortic wall stress and delay aneurysm progression. The application dimension shows cardiovascular management commanding the largest share due to life-threatening aortic complications, while preventive care represents the fastest-expanding segment as familial screening protocols broaden identification of asymptomatic carriers. Among delivery modes, oral administration dominates chronic therapy maintenance, though implantable devices for aortic root monitoring are gaining traction in high-risk surgical candidates.
The FDA oversees orphan drug approvals and cardiovascular device clearances that shape product development priorities for Marfan-specific therapies, while the EMA's orphan designation framework creates parallel access pathways in European markets. HIPAA compliance requirements influence how monitoring data from homecare settings integrates with hospital electronic records, affecting telehealth expansion for this dispersed patient population. Stakeholders must track evolving payer policies around prophylactic surgery thresholds versus medical management to anticipate shifts in procedure volumes and pharmaceutical utilization patterns.
Market Dynamics
Specialized aortic surgery centers at academic medical institutions are consolidating cardiovascular care pathways, concentrating patient volume and purchasing power among fewer high-capability facilities while fragmenting service delivery across regional catchment areas.
Growth Catalysts
- Orphan drug designation pathway:The FDA's accelerated approval framework compresses development timelines for novel Marfan-specific therapies, incentivizing pharmaceutical investment in rare disease indications.
- Familial screening protocol expansion:Genetic counseling services integrated with cardiology departments broaden identification of asymptomatic carriers, expanding the addressable patient population for preventive interventions.
- Telehealth infrastructure maturation:HIPAA-compliant remote monitoring platforms enable dispersed patient populations to maintain continuous cardiovascular surveillance without geographic proximity to specialized centers.
Market Restraints
- Prophylactic surgery threshold uncertainty:Payer policy variability around aortic diameter intervention criteria creates reimbursement friction, delaying procedure authorization and compressing provider margins.
- Beta-blocker generic saturation:Patent expiration across foundational pharmacologic agents eliminates pricing power, constraining revenue pools for cardiovascular pharmaceutical portfolios.
- Implantable device certification timelines:FDA premarket approval requirements for aortic root monitoring devices extend commercialization cycles, deferring market entry for sensor-integrated surgical platforms.
Strategic Opportunities
- Modular care bundle penetration:Integrated genetic counseling and cardiovascular surveillance packages recalibrate hospital procurement patterns, creating stickier provider relationships.
- Homecare monitoring channel development:Wearable hemodynamic sensors paired with cloud-based analytics platforms displace episodic in-clinic assessment for stable patients.
- EMA parallel pathway utilization:The European orphan designation framework enables synchronized regulatory submissions, accelerating multi-territory commercialization for novel therapies.
Industry Challenges
- Cardiovascular-geneticist workforce scarcity:Limited fellowship-trained specialists capable of managing Marfan-specific aortic pathology constrains patient intake capacity at expanding centers.
- Surgical product supply concentration:Critical dependence on specialized graft and stent graft manufacturers creates vulnerability to single-source disruption during prophylactic repair procedures.
- Electronic health record interoperability:Fragmented data standards between genetic testing laboratories, imaging centers, and surgical suites impede longitudinal patient tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marfan Syndrome Treatment Market |
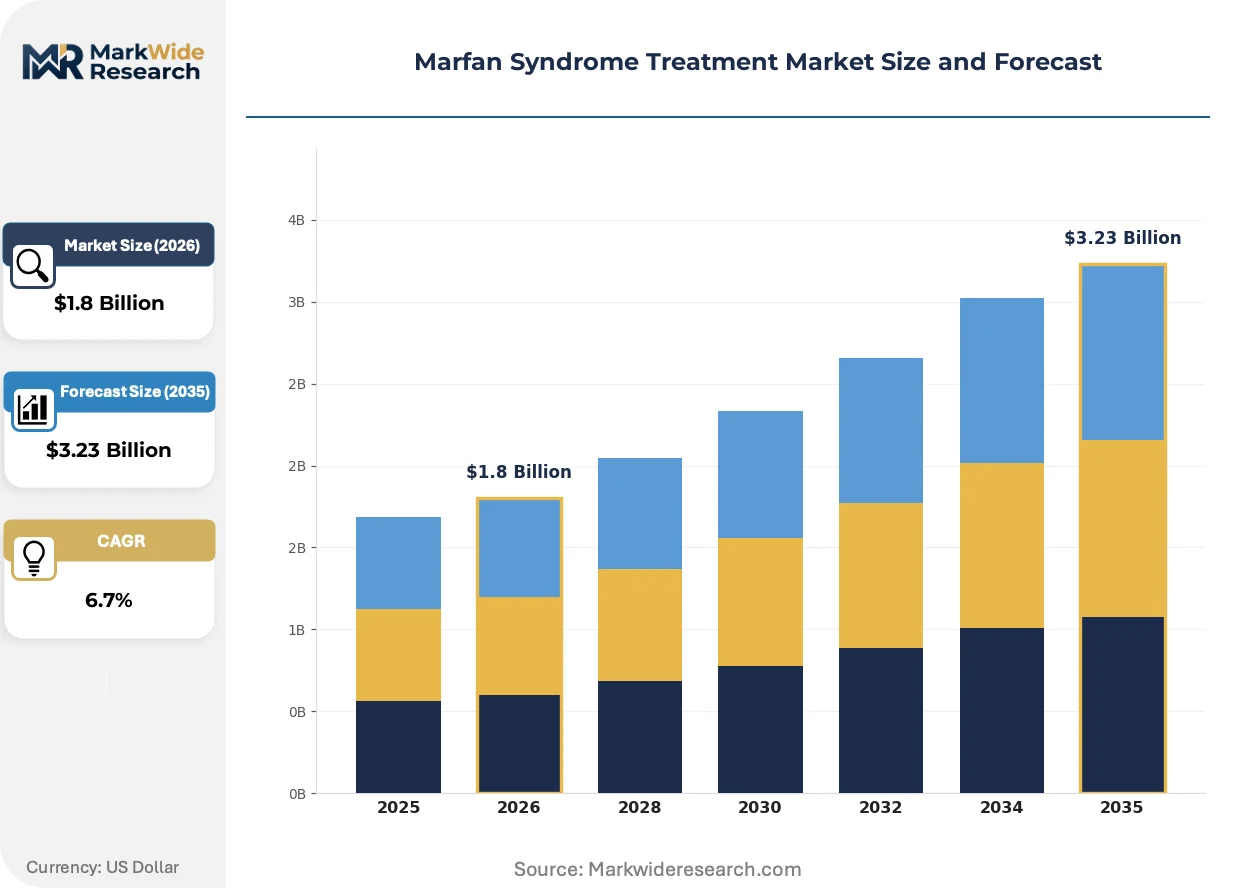
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Surgery, Genetic Counseling, Monitoring Devices Application: Cardiovascular Management, Skeletal Treatment, Ophthalmic Intervention, Preventive Care End User: Hospitals, Specialty Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Oral, Injectable, Implantable, Inhalation |
| Companies Covered | Novartis Pharmaceuticals Corporation, Baxter Healthcare Corporation, Sanofi, Teva Pharmaceutical Industries Ltd, Merck & Co., Inc., ANI Pharmaceuticals Inc., AstraZeneca, Validus Pharmaceuticals Inc., Sanis Health Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marfan Syndrome Treatment Market Emerging Trajectories
Computational modeling of aortic wall stress is displacing empirical diameter thresholds for surgical intervention, while biomarker-guided therapy selection and patient-specific graft design are compressing the gap between standardized and precision care.
Patient-specific computational fluid dynamics is overtaking generic risk stratification tools for aortic dissection prevention. Major aortic surgery centers at Johns Hopkins, Stanford, and the Cleveland Clinic deploy finite element analysis to model wall stress distribution from individual CT angiography datasets. This technology is overtaking diameter-based surgical criteria, enabling earlier intervention in morphologically complex aneurysms that fall below conventional size thresholds.
The FDA's breakthrough device designation pathway is accelerating review timelines for aortic monitoring implants, compressing the gap between prototype validation and commercial availability. This regulatory mechanism prioritizes real-world evidence collection over traditional randomized controlled trials for rare disease indications. High-risk surgical candidates at US academic medical centers are gaining access to implantable pressure sensors ahead of European markets.
Academic medical centers are unbundling after-sales device monitoring from surgical procedure billing, shifting toward subscription-based remote surveillance contracts. This procurement evolution displaces capital-intensive equipment purchasing with recurring revenue relationships. The model concentrates among US hospital systems with captive accountable care organizations seeking to reduce emergency dissection events.
Marfan Syndrome Treatment Market Segmentation
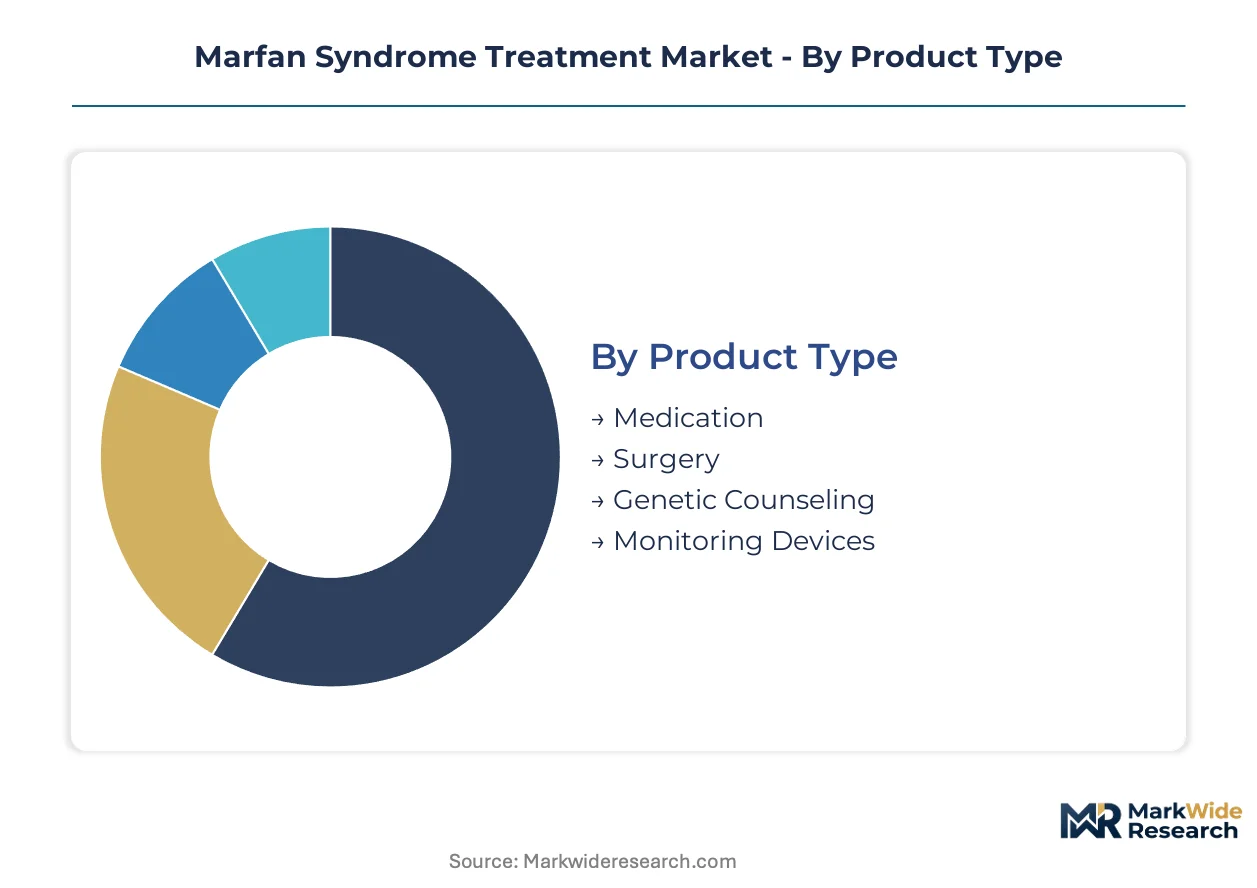
Treatment modalities for Marfan syndrome span acute intervention and lifelong management, requiring distinct procurement pathways across pharmaceutical, surgical, and monitoring domains. Segmentation reveals where integrated care bundles displace fragmented service delivery.
Product Type:
Standalone therapeutic agents dominate chronic management, while embedded surgical systems and genetic diagnostics increasingly bundle into comprehensive care contracts.
- Medication:Beta-adrenergic blockers and angiotensin receptor blockers constitute the pharmacologic foundation for aortic wall stress reduction. Demand concentrates at academic medical centers with established Marfan clinics, driven by payer preference for generic therapeutic pathways that limit specialty pharmacy spend.
- Surgery:Prophylactic aortic root replacement and valve-sparing procedures require specialized graft materials and cardiopulmonary bypass systems. Johns Hopkins, Stanford, and Cleveland Clinic anchor US surgical volume, constrained by cardiovascular-geneticist workforce scarcity that limits patient intake capacity.
- Genetic Counseling:Familial cascade screening services identify asymptomatic carriers across dispersed kindreds.
- Monitoring Devices:Implantable pressure sensors and wearable hemodynamic trackers enable remote surveillance.
Surgery leads volumes today; genetic counseling is gaining share fastest.
Application:
Cost tier stratification separates life-threatening cardiovascular emergencies from elective skeletal and ocular interventions.
- Cardiovascular Management:Aortic dissection prevention commands premium reimbursement through specialized surgery centers. US academic medical institutions cluster expertise, though EMA parallel pathways accelerate European adoption of novel monitoring implants.
- Preventive Care:Asymptomatic carrier identification through familial screening expands the addressable patient population. Genetic counseling integrated with cardiology departments at major hospital systems drives volume, supported by HIPAA-compliant telehealth infrastructure for dispersed populations.
- Skeletal Treatment:Orthopedic interventions address scoliosis and pectus deformities.
- Ophthalmic Intervention:Lens dislocation and retinal detachment repairs target ocular manifestations.
Cardiovascular management captures the highest reimbursement intensity; preventive care shows the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with hospital systems consolidating purchasing power while homecare channels fragment delivery.
- Hospitals:Tertiary centers with specialized aortic surgery programs consolidate patient volume and purchasing leverage. Major US academic medical institutions bundle genetic counseling, imaging, and surgical services into modular care contracts.
- Homecare Settings:Remote monitoring platforms displace episodic clinic visits for stable post-surgical patients. Wearable hemodynamic sensors paired with cloud analytics expand access beyond geographic proximity to specialized centers.
- Specialty Clinics:Cardiovascular-geneticist practices provide longitudinal management.
- Rehabilitation Centers:Post-surgical recovery and physical therapy services support functional outcomes.
Hospitals dominate procurement value; homecare settings are expanding most quickly.
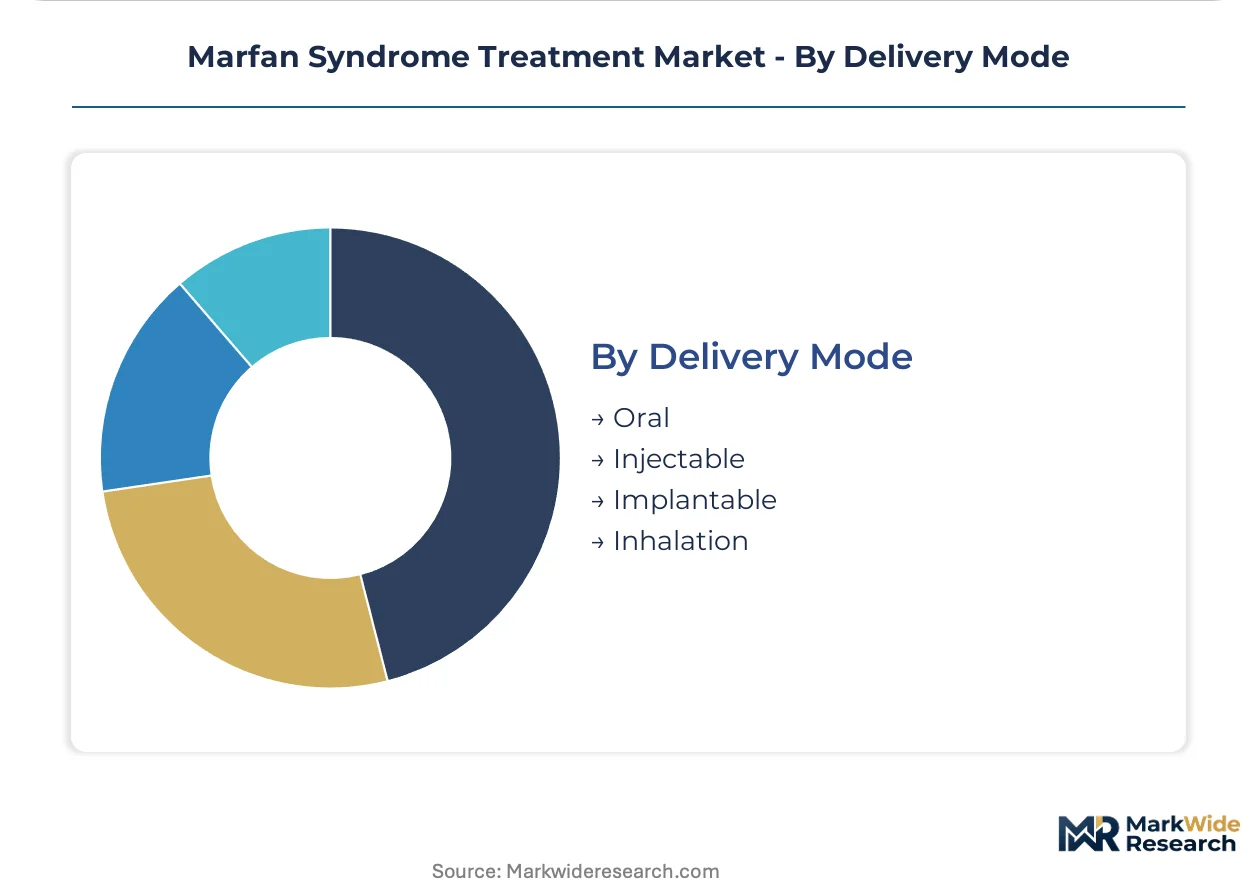
Delivery Mode:
Maturity curves separate decades-established oral pathways from emerging implantable and inhalation technologies.
- Oral:Chronic beta-blocker and ARB administration remains the default maintenance pathway. Generic saturation across foundational agents eliminates pricing power, constraining pharmaceutical portfolio margins.
- Implantable:Aortic root pressure sensors and vascular grafts require FDA premarket approval. Breakthrough device designation accelerates review timelines, enabling US academic centers to access novel sensors ahead of European markets.
- Injectable:Acute hemodynamic management and anesthesia delivery.
- Inhalation:Emerging delivery research for targeted therapies.
Oral delivery anchors chronic therapy volumes; implantable systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Marfan syndrome treatment industry traces its clinical foundations to Johns Hopkins Hospital in Baltimore, where Victor McKusick established the first dedicated connective tissue disorder clinic in the 1950s. This institutional lineage concentrated expertise at US academic medical centers before propagating to European surgical hubs. Today, specialized aortic surgery programs cluster around historic cardiovascular research institutions across three continents.
United States
Academic medical centers at Johns Hopkins, Stanford, and Cleveland Clinic anchor surgical volume and pharmaceutical demand. FDA breakthrough device designation accelerates access to implantable aortic sensors ahead of other markets. The concentration of cardiovascular-geneticist specialists in Boston and Baltimore sustains patient intake capacity for complex prophylactic repairs.
Germany
EMA orphan designation pathways enable parallel regulatory submissions with US counterparts, compressing commercialization timelines for novel therapies. The German Heart Center Berlin and Heidelberg University Hospital maintain high-volume aortic surgery programs. Reimbursement frameworks through statutory health insurance favor preventive cardiovascular interventions over emergency repairs.
Switzerland
Swissmedic's streamlined orphan drug review attracts pharmaceutical development investment for rare connective tissue disorders. University Hospital Zurich and Geneva University Hospitals integrate genetic counseling with cardiovascular surveillance. The country's precision medicine infrastructure supports patient-specific graft design and computational aortic modeling.
Japan
PMDA's Sakigake designation system accelerates priority review for innovative cardiovascular devices targeting Marfan-related aortic pathology. Tokyo Medical and Dental University Hospital and Osaka University Hospital concentrate surgical expertise. Aging demographics expand demand for remote monitoring solutions among dispersed rural patient populations.
United Kingdom
NHS England's specialized commissioning framework consolidates Marfan syndrome care at designated supraregional centers in London, Manchester, and Glasgow. The National Institute for Health and Care Excellence publishes evidence-based intervention thresholds that influence payer policies across Commonwealth markets. Genomic England's screening programs broaden asymptomatic carrier identification.
Marfan Syndrome Treatment Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with cardiovascular therapy portfolios. Consolidation pressures favor organizations capable of bundling pharmacologic, surgical, and monitoring interventions into modular care contracts. Three archetypes dominate: multinational pharmaceutical firms with orphan drug capabilities, surgical product manufacturers with graft and bypass system expertise, and emerging precision diagnostics developers. Competitive moves center on strategic partnerships between pharmaceutical and device manufacturers, plus geographic expansion of specialized aortic surgery center networks.
Among the established pharmaceutical players, Novartis Pharmaceuticals Corporation, Sanofi, and AstraZeneca occupy positions anchored by cardiovascular therapy portfolios. Novartis represents the integrated pharmaceutical archetype with beta-blocker and ARB assets for aortic protection. Sanofi exemplifies the antihypertensive therapy specialist serving hemodynamic management requirements. AstraZeneca sits within the cardiovascular-metabolic portfolio tier addressing comorbidity profiles in connective tissue disorder patients. Baxter Healthcare Corporation anchors the surgical supply segment through its position in products deployed during prophylactic aortic repair procedures.
| Leading Market Players |
|---|
| Novartis Pharmaceuticals Corporation |
| Baxter Healthcare Corporation |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Merck & Co., Inc. |
| ANI Pharmaceuticals Inc. |
| AstraZeneca |
| Validus Pharmaceuticals Inc. |
| Sanis Health Inc |
| Others |
Supply Flow & Price Mechanics
Patient-specific graft design and computational aortic modeling are compressing cost economics while concentrating procurement leverage among US academic medical centers with captive surgical volume. This production-method transition simultaneously elevates material precision requirements and fragments supply access for smaller hospital systems lacking integrated cardiovascular programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by surgical complexity and after-sales monitoring bundling. FDA breakthrough device designation commands certification premiums for implantable sensors, while generic beta-blocker saturation eliminates pricing power in chronic pharmacologic maintenance. Cost compression in foundational pharmaceutical tiers is intensifying because payer preference for generic therapeutic pathways limits specialty pharmacy spend. Academic medical centers with bundled care contracts exhibit lowest price sensitivity; regional hospitals without specialized aortic programs face highest procurement friction.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Switzerland anchor hub-and-spoke patterns for specialized graft materials and cardiopulmonary bypass systems. Critical inputs draw from medical-grade polymer manufacturers, precision sensor fabricators, and genetic testing laboratory networks. Single-source vulnerability concentrates in specialized aortic root graft suppliers serving prophylactic repair procedures. Distribution runs through hospital system procurement consortia and GPO contracts that consolidate purchasing power at tertiary centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
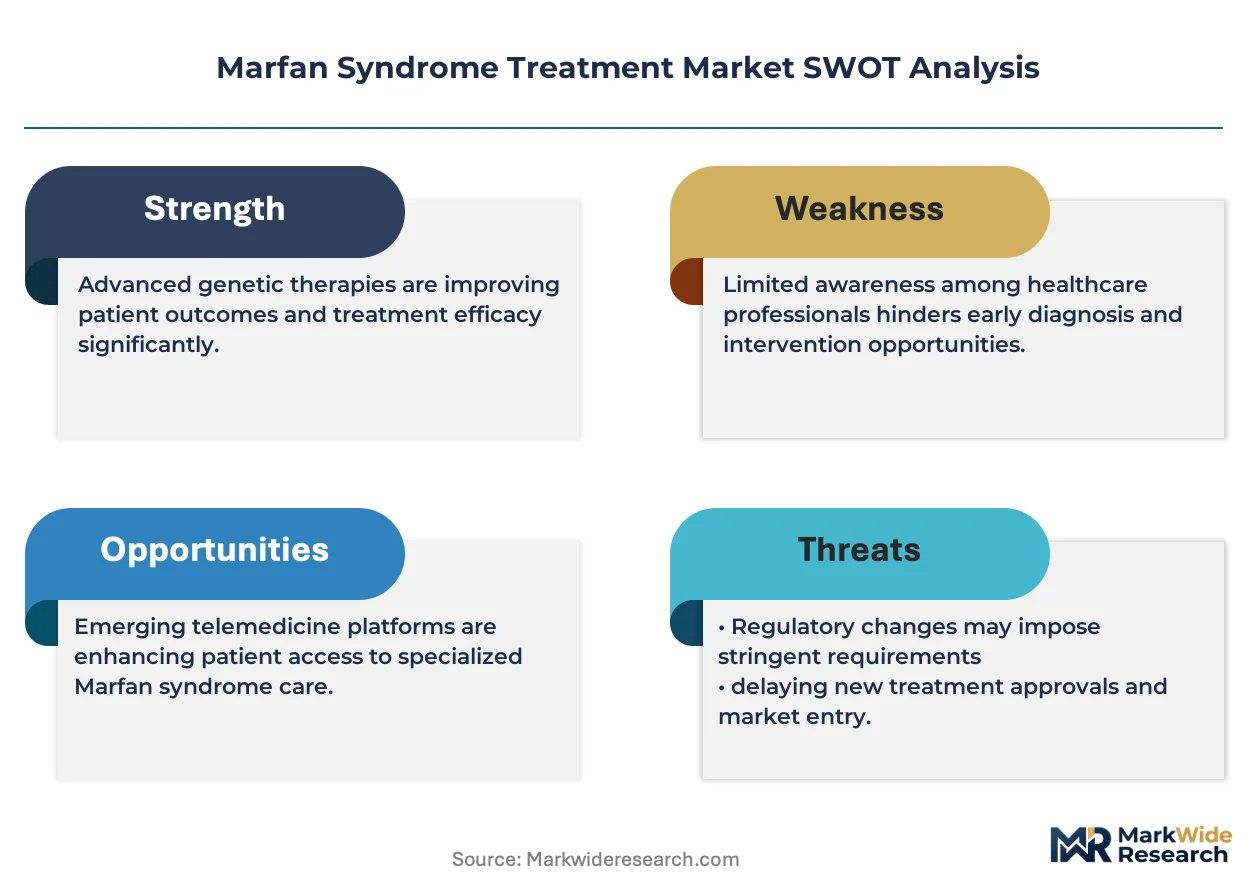
The Marfan syndrome treatment market compounds steadily through orphan drug designation incentives that compress development timelines and sustain pharmaceutical investment. Familial screening protocol expansion provides predictable patient population growth without cyclical demand volatility.
For Market Incumbents: Acquire remote monitoring platform capabilities to anchor subscription-based revenue relationships displacing capital-intensive equipment purchasing. Secure cardiovascular-geneticist workforce pipelines through fellowship program endowments at Johns Hopkins, Stanford, and Cleveland Clinic to defend patient intake capacity against emerging specialized centers. Backward integration into patient-specific graft manufacturing reduces dependence on single-source suppliers.
For New Entrants and Emerging Players: Capture homecare monitoring channel whitespace through wearable hemodynamic sensors paired with cloud-based analytics platforms. Target dispersed rural patient populations in Japan and the United Kingdom where geographic distance from specialized centers creates service delivery gaps. Pursue EMA parallel pathway submissions to synchronize multi-territory commercialization with US FDA breakthrough device review timelines.
For Investors and Strategic Acquirers: Roll-up economics work for precision diagnostics developers because computational modeling and biomarker-guided therapy selection are displacing standardized care protocols. Five-to-ten year viability hinges on regulatory capture in orphan drug and breakthrough device pathways. Monitor FDA premarket approval timeline compression for aortic root monitoring implants as inflection indicator for sensor-integrated surgical platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates review timelines for implantable aortic sensors ahead of European markets. |
| Hospital System Partnership | Bundles genetic counseling with cardiovascular surveillance into modular care contracts. |
| Reimbursement Strategy | Secures payer coverage for prophylactic surgery thresholds versus medical management. |
| Software Companion Development | Enables HIPAA-compliant remote monitoring platforms for dispersed patient populations. |
| CE Marking Pathway | Opens EMA parallel access for synchronized multi-territory commercialization. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiovascular-geneticists, hospital procurement managers, pharmaceutical regulatory affairs leads, and payer access specialists with secondary validation against FDA orphan drug filings, EMA designation databases, ClinicalTrials.gov entries, and hospital procurement contract repositories. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Comparable historical reference periods anchored the projection horizon across treatment modality, application severity tier, end-user facility type, and delivery mode segmentation dimensions. CAGRs derived from fitted growth curves incorporating orphan drug pipeline velocity, familial screening expansion rates, and telehealth infrastructure maturation patterns. Computational modeling adoption curves and implantable device certification timelines provided industry-specific forecast inputs.
Regulatory approval delays, payer policy reversals on prophylactic intervention thresholds, and cardiovascular-geneticist workforce attrition are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding screening protocol penetration and remote monitoring reimbursement parity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Microcephaly Market