
 North America Alopecia Market | 2026-2036
North America Alopecia Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alopecia Market Insights
Competitive Dynamics
The capital-intensity divergence between biopharmaceutical incumbents and device-centric entrants is redrawing competitive boundaries in the North America Alopecia Market. Johnson & Johnson Services, Inc. leverages its consumer health infrastructure to sustain shelf presence across pharmacy and supermarket channels. Merck & Co., Inc. anchors prescription-grade finasteride positioning through long-standing physician relationships. Pfizer Inc. competes via clinical trial investment in next-generation topical formulations, while Eli Lilly and Company extends its metabolic portfolio into hair biology research.
Market Structure
Alopecia encompasses pathological hair loss conditions spanning androgenetic, autoimmune, and cicatricial etiologies, with treatments ranging from topical vasodilators to follicular unit extraction procedures requiring stereomicroscopic graft preparation. The primary commercial purpose centers on halting follicle miniaturization or restoring viable hair density through pharmacological, surgical, or energy-based interventions. Minoxidil and finasteride dominate the treatment type landscape as mature, genericized pillars, while hair transplant procedures capture premium margin pools concentrated in coastal metropolitan clinics. The end user base tilts toward dermatology practices and specialized clinics, where procedure bundling and consultation fees reinforce pricing power against commoditized homecare alternatives.
Regulatory Environment
FDA oversight governs pharmaceutical alopecia therapies through NDA and ANDA pathways, while the FCC regulates marketing claims for laser-based devices promoted for hair regrowth. Health Canada and the FDA jointly shape cross-border product standards, with the former's Medical Devices Directorate imposing additional efficacy documentation requirements on photobiomodulation equipment. Stakeholders must monitor evolving FDA guidance on combination drug-device products, as topical-finasteride-plus-minoxidil formulations and automated transplant systems blur traditional classification boundaries and trigger dual regulatory tracks.
Market Dynamics
FDA's accelerated clearance pathway for combination drug-device products is compressing commercialization timelines for topical-finasteride-plus-minoxidil formulations, forcing incumbents to reconfigure R&D pipelines around dual-track regulatory submissions rather than sequential approvals.
Growth Catalysts
- Photobiomodulation device deregulation:FCC marketing claim relaxations for low-level laser therapy devices are expanding direct-to-consumer distribution channels across dermatology and homecare segments.
- Metropolitan corridor density:Boston-to-Philadelphia patient concentration creates economies of scale for follicular unit extraction clinics, reducing per-procedure fixed cost allocation.
- Health Canada alignment:Medical Devices Directorate reciprocity agreements with FDA are shortening cross-border product launch intervals for Canadian market entry.
Market Restraints
- Generic finasteride commoditization:Patent expiration erosion has collapsed prescription pricing power, compressing margin pools available for novel formulation development.
- Follicular extraction skill concentration:Stereomicroscopic graft preparation expertise clusters in coastal metropolitan clinics, creating supply bottlenecks for interior geographies.
- Minoxidil efficacy ceiling:Topical vasodilator response rates plateau at forty percent of patients, limiting expansion of addressable patient populations without combination therapies.
Strategic Opportunities
- Canadian provincial expansion:Ontario and Quebec dermatology practice consolidation lags US metropolitan density, presenting first-mover clinic network establishment potential.
- Automated transplant robotics:Integration of AI-guided follicular unit extraction with real-time graft viability assessment is opening precision-margin service tiers.
- Telemedicine prescription pathways:HIPAA-compliant remote consultation platforms are unlocking rural patient access to prescription-grade therapies previously limited to urban corridors.
Industry Challenges
- Combination product classification ambiguity:FDA dual-track submissions for drug-device topical formulations are extending pre-market review timelines and multiplying compliance documentation burdens.
- Hair biology research talent scarcity:Dermatology fellowship programs produce insufficient follicular miniaturization specialists to match expanding clinic service menus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alopecia Market |
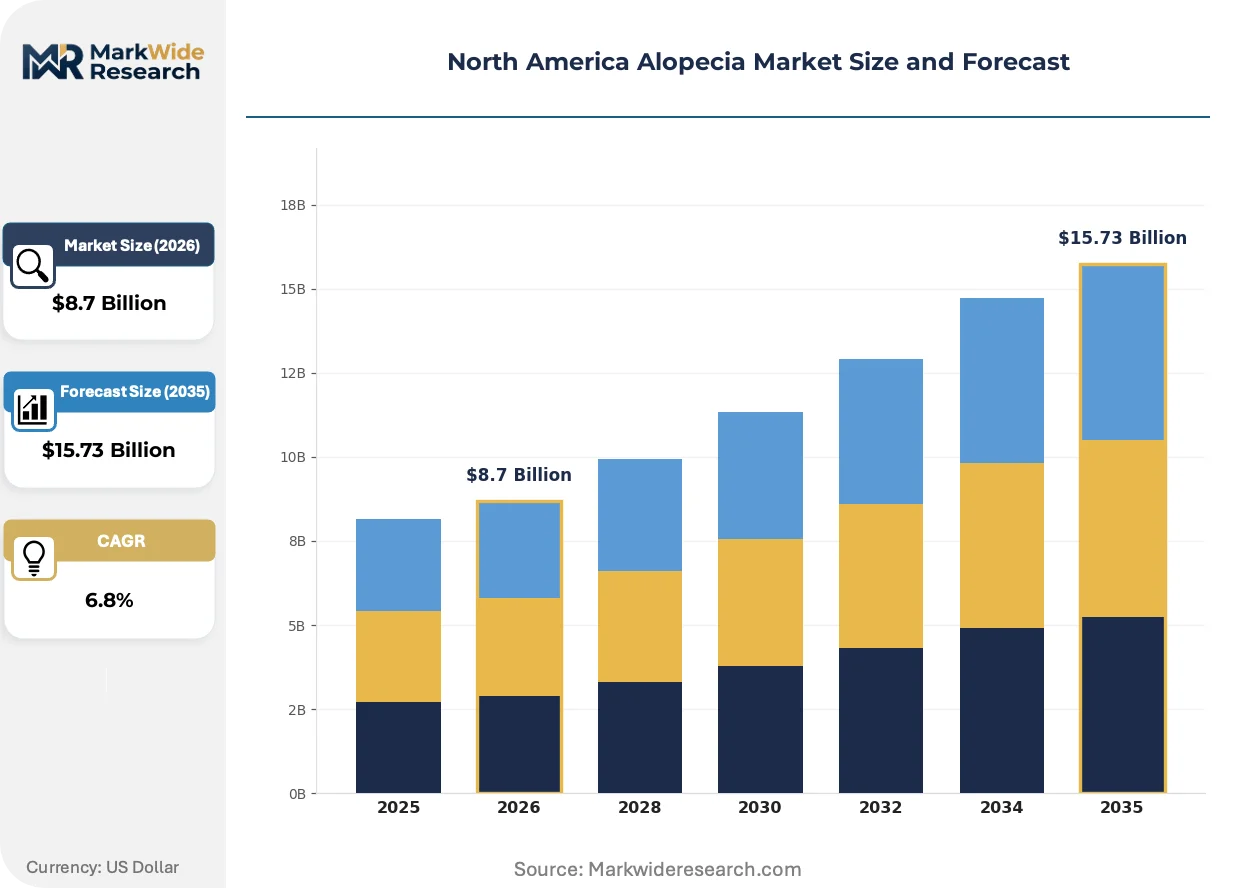
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Minoxidil, Finasteride, Corticosteroids, Hair Transplant End User: Clinics, Dermatology Practices, Beauty Salons, Homecare Gender: Male, Female, Transgender, Others Distribution Channel: Online, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Johnson & Johnson Services, Inc., Merck & Co., Inc., Pfizer Inc., Sun Pharmaceutical Industries Ltd., Cipla Inc., Dr. Reddy's Laboratories Ltd., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alopecia Market Trends and Innovations
Energy-based interventions and automated surgical systems are redrawing the boundary between clinical and homecare treatment modalities, compressing the traditional tiering between prescription pharmaceuticals and procedural interventions.
Fractional laser technology is fragmenting the hair restoration landscape by enabling precise dermal papilla stimulation without follicular extraction trauma. Dermatology practices in Manhattan and Los Angeles are adopting these systems at replacement-cycle pace, displacing older continuous-wave devices. The structural consequence is margin compression for standalone transplant clinics as combination therapy bundling becomes standard.
FDA draft guidance on microneedling-plus-topical drug delivery systems is creating classification uncertainty for devices incorporating active pharmaceutical ingredients. Manufacturers must now navigate simultaneous 510(k) and NDA submission requirements, doubling regulatory capital deployment. The topical formulation segment is responding by pre-submission meetings with CDRH and CDER to align combination product development pathways.
Subscription-based homecare device leasing is displacing outright purchase models in the direct-to-consumer channel. Patients in Texas and Florida metropolitan areas are prioritizing monthly payment structures over upfront capital expenditure, forcing device manufacturers to reconfigure revenue recognition and warranty liability frameworks. This shift is most visible in low-level laser therapy cap distribution, where clinic referral networks now compete with telehealth-integrated e-commerce platforms.
North America Alopecia Market Segmentation
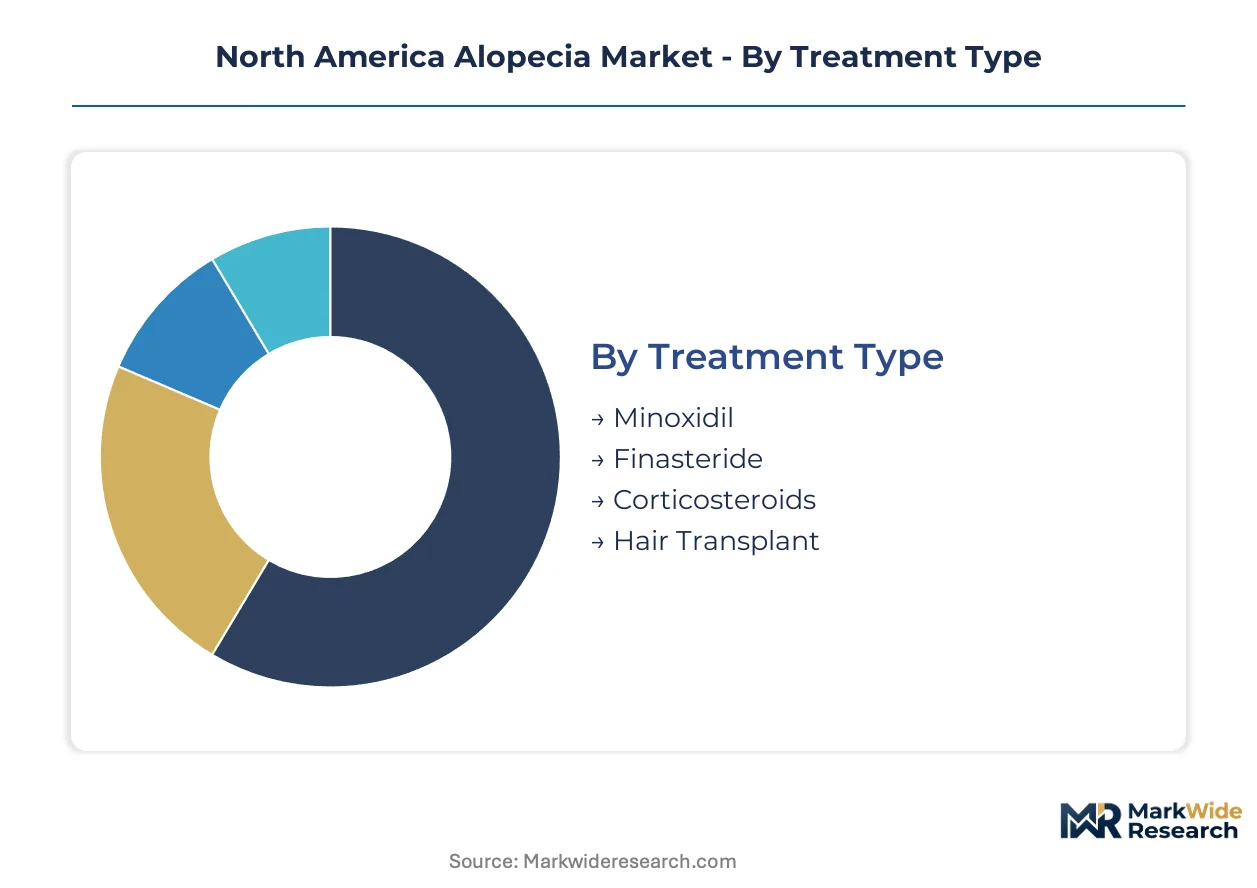
Treatment modality selection in the North America Alopecia Market hinges on follicle viability staging, patient candidacy for surgical intervention, and reimbursement pathways that diverge sharply between prescription pharmaceuticals and procedural services. Segmentation clarity enables stakeholders to align R&D investment with addressable patient pools and margin structures.
Treatment Type:
Substitution pressure intensifies as energy-based devices and robotic surgical systems erode the historical dominance of topical and oral pharmacotherapies.
- Minoxidil:Topical vasodilator formulation available in 2% and 5% concentrations with foam and solution delivery vehicles. Demand concentrates in homecare channels across Texas and Florida metropolitan corridors where direct-to-consumer advertising drives self-directed initiation. Efficacy plateau at partial responder rates limits expansion without combination protocols.
- Hair Transplant:Follicular unit extraction and follicular unit transplantation procedures requiring stereomicroscopic graft preparation and recipient site creation. Coastal metropolitan clinics from Boston through Los Angeles capture premium pricing through surgeon reputation concentration and procedure bundling with platelet-rich plasma adjuncts.
- Finasteride:Oral 5-alpha-reductase inhibitor with established prescription pathways through dermatology practices and telemedicine platforms.
- Corticosteroids:Intralesional and topical immunosuppressant formulations targeting autoimmune alopecia areata etiologies.
Minoxidil anchors the volume base while hair transplant gains share at the steepest rate.
End User:
Service delivery economics vary dramatically across settings, with fixed cost absorption and pricing power determining viable procedure mixes.
- Dermatology Practices:Board-certified specialists offering diagnostic workup, prescription management, and in-office energy-based interventions. Patient concentration in Manhattan, Los Angeles, and Chicago drives referral network density and cross-selling of cosmetic dermatology services.
- Homecare:Self-administered topical applications and leased low-level laser therapy devices distributed through e-commerce and pharmacy channels. HIPAA-compliant telemedicine platforms in rural Texas and interior Canadian provinces unlock prescription access previously limited to urban corridors.
- Clinics:Dedicated hair restoration facilities focusing on surgical and non-surgical procedural interventions.
- Beauty Salons:Cosmetology-licensed establishments offering cosmetic camouflage and referral services.
Dermatology practices capture the margin premium while homecare expands most quickly through subscription-based device leasing models.
Gender:
Patient presentation patterns and treatment response profiles diverge across demographic categories, shaping protocol customization and marketing segmentation.
- Male:Androgenetic alopecia with characteristic vertex and frontal recession patterns. FDA-cleared finasteride and minoxidil indications originally developed around male biochemistry and progression timelines.
- Female:Diffuse thinning patterns and distinct hormonal etiologies requiring modified diagnostic workup and off-label prescribing for systemic anti-androgens.
- Transgender:Hormone therapy-induced hair changes creating specialized consultation demand at academic medical centers and LGBTQ+-focused practices.
- Others:Non-binary patients seeking gender-affirming hair restoration approaches.
Male patients anchor the volume base while female-specific formulations climb the fastest as manufacturers address prior clinical trial underrepresentation.
Distribution Channel:
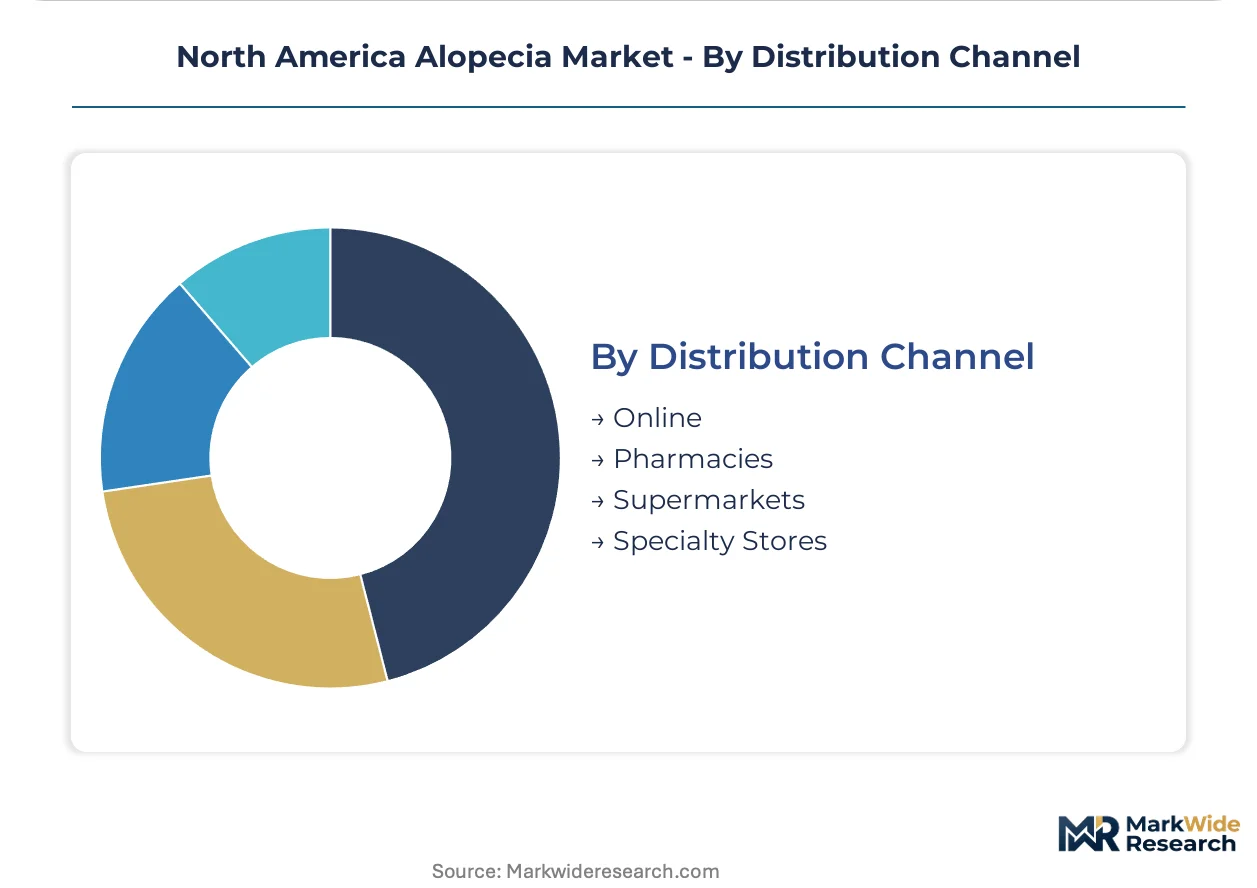
Channel economics reflect regulatory classification, with prescription requirements fragmenting volume across pharmacy, clinical, and direct-to-consumer pathways.
- Pharmacies:Retail and mail-order fulfillment of prescription finasteride and over-the-counter minoxidil with pharmacist consultation services. CVS and Walgreens shelf placement sustains brand recognition for Johnson & Johnson consumer health divisions.
- Online:Telehealth-integrated e-commerce platforms and direct-to-consumer device manufacturers bypassing traditional wholesale markups. Canadian provincial regulatory alignment enables cross-border fulfillment efficiency for Ontario and Quebec patients.
- Supermarkets:Mass-market minoxidil placement in health and beauty aisles with limited pharmacist interaction.
- Specialty Stores:Medical supply and cosmetic retailers offering professional-grade devices and camouflage products.
Pharmacies anchor the volume base while online channels gain share at the steepest rate through telemedicine integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity across North America diverges sharply: Canadian patients exhibit pronounced price sensitivity toward prescription therapies, while metropolitan U.S. corridors sustain premium pricing for procedural interventions with minimal volume erosion.
United States
FDA-cleared combination drug-device pathways are accelerating commercialization timelines for topical-finasteride-plus-minoxidil formulations. The 510(k) and NDA dual-track submission requirements, overseen by CDRH and CDER respectively, are compressing pre-market review intervals for manufacturers with aligned development strategies. Manhattan, Los Angeles, and Chicago dermatology practices concentrate follicular unit extraction expertise, driving procedure bundling with platelet-rich plasma adjuncts at premium price points.
Canada
Health Canada's Medical Devices Directorate reciprocity agreements with FDA are shortening cross-border product launch intervals for photobiomodulation equipment. Provincial formularies in Ontario and Quebec impose stricter reimbursement criteria for prescription finasteride than U.S. commercial payers, channeling demand toward over-the-counter minoxidil and leased low-level laser therapy devices. Toronto and Vancouver metropolitan areas lag U.S. coastal clinic density, presenting first-mover network establishment potential for dedicated hair restoration facilities.
Mexico
COFEPRIS regulatory alignment with FDA standards is enabling faster registration pathways for U.S.-manufactured topical formulations entering through border distribution channels. Out-of-pocket payment dominance in the Mexican market concentrates demand in Tijuana and Mexico City metropolitan corridors, where medical tourism from California and Texas sustains follicular unit extraction clinic viability. Cross-border telemedicine platforms are unlocking prescription access for northern Mexican patients through HIPAA-compliant U.S. physician consultations.
North America Alopecia Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Alopecia Market. Biopharmaceutical incumbents anchor prescription-grade positioning through clinical trial infrastructure and physician relationship networks, while device-centric entrants and generic manufacturers compete on price-accessibility vectors. The competitive structure stratifies across three archetypes: diversified healthcare conglomerates with consumer health divisions, specialty pharmaceutical firms with dermatology focus, and emerging device manufacturers with direct-to-consumer distribution capabilities. Dominant competitive moves include portfolio diversification into combination drug-device products and geographic expansion through telemedicine-integrated platforms.
Within the diversified healthcare conglomerate tier, Johnson & Johnson Services, Inc. and Pfizer Inc. exemplify players with cross-divisional resources spanning consumer health and prescription pharmaceutical segments. Merck & Co., Inc. occupies a position representing long-standing genericized prescription anchoring through established 5-alpha-reductase inhibitor positioning. Eli Lilly and Company sits within the metabolic portfolio extension archetype, applying endocrinology research capabilities toward hair biology applications.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Inc. |
| Dr. Reddy's Laboratories Ltd. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with photobiomodulation device manufacturers lock in supply access for dermatology clinic chains while freezing component costs against semiconductor volatility. These arrangements tether pricing visibility to inbound logistics performance across Pacific trade lanes serving FDA-regulated distribution hubs.
Pricing Analysis
After-sales service contracts for low-level laser therapy caps now drive lifetime value beyond initial hardware margins. Subscription-based leasing models stratify across premium, standard, and economy tiers differentiated by device generation and telehealth integration depth. Cost compression in the generic minoxidil segment is intensifying because retail pharmacy chains consolidate procurement volume. Homecare patients in Texas and Florida exhibit highest price sensitivity, while Manhattan follicular unit extraction clinics maintain lowest sensitivity through surgeon reputation premiums.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Vancouver ports constrain margin recovery for Asian-manufactured photobiomodulation equipment. Component sourcing draws from China for laser diodes, South Korea for microelectronics, and Mexico for injection-molded housings. Single-source vulnerability concentrates in FDA-cleared diode arrays produced by limited qualified suppliers. Distribution runs through dermatology practice networks, direct-to-consumer e-commerce platforms, and pharmacy retail chains with diverging markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's accelerated clearance pathway for combination drug-device products creates a regulatory inflection that compresses commercialization timelines and rewards aligned R&D investment. This disruption favors players with dual-track submission capabilities and cross-functional regulatory affairs infrastructure.
For Market Incumbents: Shield prescription-grade finasteride positioning through formulary defense contracts with major payers against telemedicine-driven generic substitution. Deepen backward integration into topical formulation manufacturing to capture margin pools eroding at the pharmacy shelf. Fortify clinician education networks to sustain physician preference against direct-to-consumer device marketing. For New Entrants and Emerging Players: Anchor in Canadian provincial markets where dermatology practice consolidation lags U.S. metropolitan density, particularly Ontario and Quebec. Exploit Health Canada-FDA reciprocity agreements to accelerate product launch intervals against slower-moving incumbents. Pursue telehealth-integrated subscription models for rural patient access as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward device-centric entrants with direct-to-consumer distribution capabilities and automated transplant robotics intellectual property. Long-term viability over the coming decade hinges on capturing the shift from procedural to homecare modalities. Monitor FDA draft guidance on microneedling-plus-topical systems as the critical inflection signal for combination product classification clarity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Dual-Track Submission Alignment | CDRH and CDER pre-submission meetings compress review timelines for combination drug-device topical formulations. |
| Telemedicine Platform Integration | HIPAA-compliant remote consultation unlocks rural prescription access beyond traditional urban corridor concentration. |
| Canadian Provincial Network Establishment | Ontario and Quebec clinic density gaps present first-mover advantage for dedicated hair restoration facilities. |
| Automated Transplant Robotics Development | AI-guided follicular unit extraction with real-time graft assessment opens precision-margin service tiers. |
| Subscription-Based Device Leasing | Monthly payment structures displace outright purchase in Texas and Florida metropolitan patient segments. |
Research Methodology
A spread of perspectives from dermatology practice administrators, FDA regulatory affairs specialists, health system procurement directors, and photobiomodulation device engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and NDA submission databases, Health Canada Medical Devices Directorate filings, and ClinicalTrials.gov protocol registries. Bottom-up patient flow modeling and top-down pharmaceutical and device revenue triangulation anchored market sizing.
Segmentation dimensions modeled span treatment modality, end-user setting, patient gender, and distribution channel across the projection horizon. CAGRs were derived from procedure volume growth rates, pharmaceutical script trajectories, and device shipment data normalized against demographic incidence curves. Forecast inputs incorporated follicular unit extraction clinic expansion pipelines, telemedicine platform subscriber acquisition costs, and provincial formulary reimbursement decisions.
Decision-makers should treat outputs as directional under assumptions of sustained FDA clearance pathway efficiency and stable Health Canada reciprocity frameworks; material deviation would warrant model refresh. Specific risks include combination product classification ambiguity extending pre-market timelines and hair biology research talent scarcity constraining clinic service menu expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Hemangioma Market