
 Bullous Pemphigoid Treatment Market | 2026-2036
Bullous Pemphigoid Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bullous Pemphigoid Treatment Market Outlook
Modular biologic dosing regimens is pivoting prescriber preference toward flexible administration schedules. Pfizer Inc. leverages its inflammation portfolio to sustain dermatology franchise relevance. Sanofi anchors European market access through established rare disease channels. Regeneron competes on IL-4/IL-13 pathway science with differentiated efficacy positioning.
Bullous Pemphigoid Treatment encompasses pharmacologic interventions targeting autoantibody-mediated subepidermal blistering, with biologics such as dupilumab and rituximab engineered to disrupt B-cell activation and IL-4/IL-13 signaling cascades. The primary purpose is disease control through immunomodulation, reducing steroid burden and preventing mucosal complications. Biologics command the fastest expansion trajectory among product type segments, while corticosteroids retain volume leadership as first-line induction therapy. Subcutaneous delivery mode is gaining structural share through home administration economics, though intravenous biologics occupy the premium reimbursement tier.
FDA orphan drug designations and EMA PRIME eligibility criteria shape development priorities and exclusivity value for biologic developers. The EU AI Act and FDA digital health guidance are beginning to influence remote patient monitoring integration in dermatology practice. Stakeholders must weigh pipeline positioning against evolving payer evidence requirements for biologic access expansion.
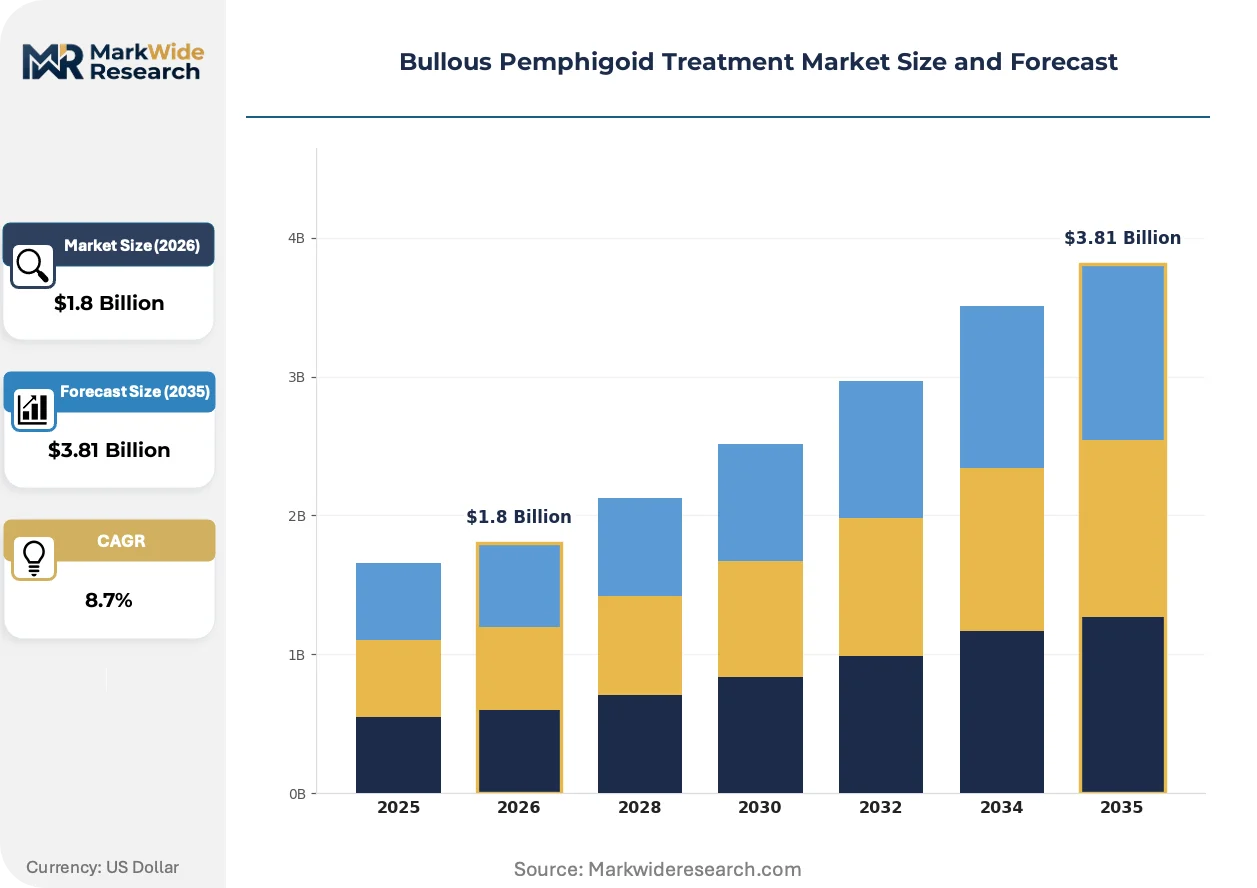
Market Dynamics
FDA orphan drug designations and EMA PRIME eligibility criteria are compressing development timelines for biologic developers targeting autoimmune blistering diseases, while payer evidence requirements simultaneously tighten market access thresholds.
Growth Catalysts
- EMA PRIME Eligibility:Priority medicines status accelerates regulatory review timelines for rare disease biologics, reducing time-to-market for novel immunomodulators.
- Subcutaneous Delivery Economics:Home administration protocols reduce infusion center burden and expand prescriber willingness to initiate biologic therapy.
- Tertiary Hospital Expansion:Dermatology departments in academic medical centers are building dedicated autoimmune blistering disease clinics with biologic prescribing infrastructure.
Market Restraints
- Plasma-Derived Protein Supply Concentration:Limited fractionation capacity in North America and Europe constrains rituximab biosimilar availability.
- Biologic Manufacturing Complexity:Cell culture yield variability for monoclonal antibodies extends batch release timelines and limits supply flexibility.
- Reimbursement Prior Authorization Friction:Medicare and commercial payers impose step-therapy requirements that delay biologic initiation by 4-12 weeks.
Strategic Opportunities
- Japan's Aging Dermatology Population:PMDA's sakigake designation pathway offers expedited review for biologics addressing unmet need in elderly patients with steroid-refractory disease.
- Remote Patient Monitoring Integration:FDA digital health guidance enables smartphone-based blister photography and symptom tracking for decentralized trial endpoints.
- IL-4/IL-13 Pathway Expansion:Convergence of atopic dermatitis and bullous pemphigoid mechanistic science creates indication-stretch opportunities for existing biologic assets.
Industry Challenges
- Specialized Immunodermatology Workforce Scarcity:Fellowship-trained clinicians capable of diagnosing and managing autoimmune blistering diseases remain concentrated in urban academic centers.
- Biologics License Application Complexity:Immunogenicity assay validation and long-term safety database requirements extend regulatory submission preparation by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bullous Pemphigoid Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Antibiotics Delivery Mode: Topical, Oral, Intravenous, Subcutaneous End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Formulation: Creams, Ointments, Tablets, Injections |
| Companies Covered | Pfizer Inc., Sanofi, Regeneron, Almirall, S.A, F. Hoffmann-La Roche Ltd, Novartis AG, AstraZeneca, Argenx, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bullous Pemphigoid Treatment Market Strategic Shifts
Modular dosing platforms and real-world evidence generation are restructuring how biologics demonstrate value to institutional purchasers and specialty pharmacy networks.
Subcutaneous dupilumab formulations are rewriting administration patterns for IL-4/IL-13 pathway inhibition. Community dermatology practices in Germany and the United States are adopting these protocols faster than hospital-based infusion centers. The shift is compressing site-of-care economics and redistributing margin capture toward specialty pharmacy distributors.
EMA's PRIME eligibility criteria and FDA's breakthrough therapy designation are converging to create dual-track regulatory strategies for rare disease biologics. Developers now sequence European and American submissions to optimize label breadth and reimbursement negotiations. Autoimmune blistering disease programs with biomarker-enriched trial designs are securing priority review vouchers that accelerate commercial timelines.
Specialty pharmacy networks are consolidating patient onboarding and adherence monitoring functions that academic medical centers previously performed in-house. Payers in the United States are mandating these channel arrangements for biologics exceeding $30,000 annual therapy cost. Germany's regional sickness funds are piloting comparable models, shifting clinical oversight responsibility from prescribing physicians to pharmacy-based care coordinators.
Bullous Pemphigoid Treatment Market Segmentation
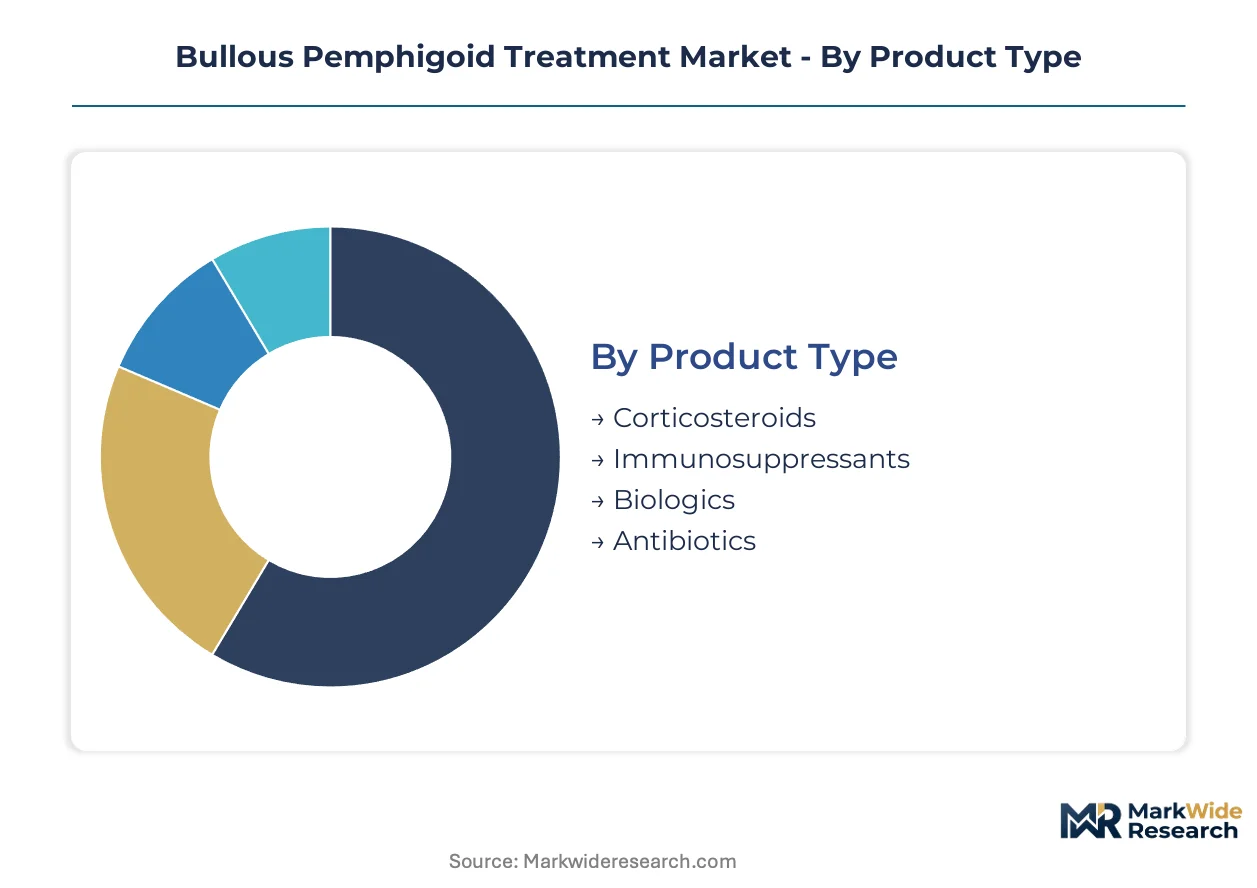
Bullous pemphigoid treatment selection hinges on disease severity, comorbidity burden, and site-of-care economics. Prescribers navigate four intersecting dimensions when matching patients to appropriate therapeutic modalities.
Product Type:
Replacement cycles for first-line therapies are shortening as biologics displace prolonged steroid exposure in refractory cases.
- Corticosteroids:Prednisone and topical clobetasol remain the induction backbone, with tapering protocols designed to minimize osteoporosis and diabetes complications. Demand concentrates in United States Medicare populations where physician familiarity supports rapid initiation despite toxicity concerns.
- Biologics:Engineered monoclonal antibodies targeting IL-4/IL-13 and CD20 pathways disrupt B-cell activation and cytokine signaling. Germany's regional sickness funds and Japan's PMDA are accelerating access for steroid-refractory elderly patients through specialized reimbursement channels.
- Immunosuppressants:Azathioprine and mycophenolate mofetil serve as steroid-sparing bridge therapies with established pregnancy safety databases.
- Antibiotics:Doxycycline and dapsone address mild disease variants and infection prophylaxis during immunosuppression.
Volume placements concentrate in corticosteroids; the faster expansion belongs to biologics.
Delivery Mode:
Cost tier differentiation separates hospital-based administration from economically advantageous home delivery protocols.
- Subcutaneous:Prefilled autoinjector devices enable patient self-administration, reducing infusion center overhead and expanding rural access. United States specialty pharmacy networks capture margin through centralized distribution and adherence monitoring programs.
- Intravenous:Hospital-based rituximab infusions occupy premium reimbursement tiers with intensive monitoring requirements. German university hospitals maintain volume leadership through established autoimmune blistering disease clinics.
- Oral:Tablet formulations dominate maintenance phases with predictable pharmacokinetics and broad prescriber comfort.
- Topical:Limited skin surface area involvement drives localized cream and ointment applications in early-stage disease.
Patient preference is shifting toward subcutaneous modalities; institutional purchasers retain commitment to intravenous biologics for complex cases.
End User:
Customer type fragmentation reflects divergent capabilities in biologic prescribing, adverse event management, and reimbursement navigation.
- Hospitals:Tertiary academic centers in Japan and the United States house dedicated immunodermatology units with fellowship-trained clinicians capable of managing rituximab infusion reactions.
- Specialty Pharmacies:Centralized hubs coordinate prior authorization, cold-chain logistics, and nurse-led patient education for high-cost biologics exceeding $30,000 annual therapy cost.
- Clinics:Community dermatology practices in Germany are adopting subcutaneous dupilumab protocols faster than hospital-based centers.
- Homecare:Visiting nurse services support elderly patients with mobility limitations in rural United States markets.
Biologic volume concentrates in specialty pharmacy channels; hospital-based clinics retain dominance for diagnostic confirmation and acute management.
Formulation:
Supply concentration among sterile injectable manufacturers shapes availability patterns across dosage forms.
- Injections:Lyophilized vials and prefilled syringes require cold-chain integrity with 2-8°C storage specifications throughout distribution.
- Tablets:Oral solid dosage forms offer manufacturing scale economies and extended shelf stability.
- Creams:Semi-solid emulsions deliver corticosteroid penetration for limited cutaneous involvement.
- Ointments:Occlusive petrolatum-based vehicles enhance drug retention on eroded blister surfaces.
Manufacturing complexity elevates injection costs; tablet formulations maintain volume leadership through generic substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic manufacturing concentrates in Switzerland, Massachusetts, and Basel while consumption tilts toward aging populations in Germany, Japan, and the United States. Tertiary hospital infrastructure and specialist dermatology workforce density determine regional access patterns for advanced immunomodulatory therapies.
United States
Medicare Part D reimbursement policies and prior authorization requirements shape biologic initiation timelines for elderly patients with steroid-refractory disease. The FDA's breakthrough therapy designation accelerates review for novel IL-4/IL-13 pathway inhibitors. Boston and New York City house dedicated immunodermatology units at academic medical centers that drive clinical trial enrollment and prescriber education.
Germany
Regional sickness funds pilot outcomes-based reimbursement contracts for subcutaneous biologics exceeding $30,000 annual therapy cost. EMA's PRIME eligibility criteria compress regulatory review timelines for rare disease developers targeting autoimmune blistering diseases. Munich and Heidelberg maintain volume leadership through university hospital autoimmune blistering disease clinics with established rituximab infusion protocols.
Japan
PMDA's sakigake designation pathway offers expedited review for biologics addressing unmet need in elderly populations with limited steroid tolerance. METI coordinates domestic biologic manufacturing capacity expansion to reduce import dependency for monoclonal antibodies. Tokyo and Osaka concentrate specialist dermatology workforce and tertiary hospital infrastructure capable of managing complex immunomodulatory therapy.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while offering national flexibility for early access programs in rare diseases. The country's fractionation and monoclonal antibody manufacturing base supplies European and Asian markets with plasma-derived and recombinant biologics. Basel anchors global immunology R&D operations with integrated clinical development and regulatory submission capabilities.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that filter biologic access through specialized commissioning arrangements. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways diverging from EMA timelines. London and Manchester concentrate NHS England specialist dermatology services with fellowship-trained clinicians capable of diagnosing autoimmune blistering diseases.
Bullous Pemphigoid Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with inflammation portfolio depth rather than pure-play dermatology specialists. Large-cap developers leverage established rare disease commercial infrastructure and payer relationships to compress biologic launch timelines. Two strategic archetypes dominate: inflammation portfolio generalists repurposing existing immunology assets, and rare disease specialists securing orphan drug exclusivity for novel mechanisms. Competitive moves concentrate on indication-stretch strategies for approved biologics and strategic partnerships to access subcutaneous formulation technology.
Within the inflammation portfolio tier, Pfizer Inc. and Sanofi occupy positions anchored by broad immunology franchises with dermatology application potential. Regeneron exemplifies the science-driven archetype with pathway-specific positioning in IL-4/IL-13 inhibition. These three entities represent the dominant competitive anchors, with Roche and Novartis AG sitting within adjacent immunology segments capable of competitive entry.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Regeneron |
| Almirall, S.A |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| AstraZeneca |
| Argenx |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Plasma protein fractionation capacity constraints in North America and Europe cascade through biologic manufacturing into tiered pricing structures that separate hospital-based infusion therapies from subcutaneous home-administration alternatives. Cell culture yield variability for monoclonal antibodies compresses batch release timelines and concentrates pricing power among sterile injectable manufacturers with validated cold-chain infrastructure.
Pricing Analysis
Cost-down pressure on intravenous biologics accelerates because Medicare Part D reimbursement compression and commercial payer step-therapy requirements extend prior authorization timelines. Pricing stratifies across premium intravenous hospital-administered therapies, standard subcutaneous autoinjector formulations, and economy-tier corticosteroid induction protocols. Brand premiums attach to FDA breakthrough-designated IL-4/IL-13 pathway inhibitors with orphan drug exclusivity. Community dermatology practices in Germany exhibit highest price sensitivity due to regional sickness fund budget caps, while Japanese tertiary hospitals retain lowest sensitivity through PMDA sakigake pathway access.
Supply Chain Analysis
Dual-sourcing mandates from United States specialty pharmacy networks and German hospital procurement committees require qualification of at least two sterile injectable manufacturers for monoclonal antibody supply. Manufacturing concentrates in Switzerland, Massachusetts, and Basel for cell culture production, with fill-finish operations distributed across Ireland, Singapore, and North Carolina. Supply chains draw from Chinese hamster ovary cell lines, single-use bioreactor systems, and plasma-derived protein feedstocks. Single-source vulnerability concentrates in plasma fractionation capacity for rituximab biosimilars. Distribution runs through centralized specialty pharmacy hubs with 2-8°C cold-chain integrity and nurse-led patient onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic manufacturing complexity and limited fractionation capacity create supply-constrained conditions that prop pricing for validated sterile injectable producers. Cell culture yield variability functions as the binding capacity bottleneck preserving margin structures.
For Market Incumbents: Lock in plasma-derived protein supply agreements with fractionators in Switzerland and North America to secure rituximab biosimilar availability against emerging CD20 pathway competitors. Expand subcutaneous formulation capacity in Germany and Japan where regional reimbursement pilots favor home-administration economics. Vertical integration into autoinjector device manufacturing reduces dependency on third-party combination product suppliers.
For New Entrants and Emerging Players: Capture Japan's aging dermatology population through PMDA sakigake designation applications for steroid-refractory elderly indications with limited therapeutic alternatives. Target community dermatology practices in Germany adopting subcutaneous dupilumab protocols faster than hospital-based centers. Deploy outcomes-based contracting with regional sickness funds as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: The window for entry favors biologic developers with validated immunogenicity assays and long-term safety databases already assembled. Five-to-ten year viability hinges on indication-stretch potential across autoimmune blistering diseases and atopic dermatitis mechanistic convergence. Watch for FDA priority review voucher awards to autoimmune blistering disease programs as the inflection signal for compressed commercial timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA PRIME Eligibility Application | Accelerates regulatory review timelines for rare disease biologics targeting steroid-refractory populations. |
| Subcutaneous Formulation Development | Enables home administration economics that redistribute margin capture toward specialty pharmacy networks. |
| Specialty Pharmacy Network Partnership | Consolidates prior authorization, cold-chain logistics, and adherence monitoring for high-cost biologics. |
| IL-4/IL-13 Pathway Indication Expansion | Creates label-stretch opportunities leveraging mechanistic convergence with atopic dermatitis science. |
| Remote Patient Monitoring Integration | Aligns with FDA digital health guidance for decentralized trial endpoints and real-world evidence generation. |
Study Parameters
Document review covered FDA orphan drug designations, EMA PRIME eligibility criteria, and PMDA sakigake pathway submissions, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers in Germany and Japan. Secondary validation drew from ClinicalTrials.gov enrollment data, CMS Medicare Part D expenditure reports, and regional sickness fund reimbursement bulletins. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Cross-referencing historical biologic launch trajectories against panel input from immunodermatology specialists informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, treatment line progression rates, and biologic penetration assumptions. Forecast inputs incorporated plasma fractionation capacity expansion timelines and subcutaneous formulation adoption curves.
The model holds under stable plasma protein supply conditions and sustained specialty pharmacy network consolidation; deviation in fractionation capacity constraints or reimbursement policy shifts would shift volume trajectories. A model refresh is warranted upon material change in FDA breakthrough therapy designation awards or EMA PRIME eligibility decisions for autoimmune blistering disease programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Urea Cycle Disorder Market