
 Dental Carpule Market | 2026-2036
Dental Carpule Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Carpule Market Intelligence
Use in specialized dental centers for complex procedures like periodontal treatments and surgical extractions is broadening the market beyond traditional dental clinics. Septodont leverages its extensive product portfolio to serve both general and specialized end-users. Dentsply Sirona differentiates through its integrated digital dentistry solutions, which incorporate anesthetic delivery. Meanwhile, Novocol Pharmaceuticals sustains its position through large-scale manufacturing of lidocaine and articaine carpules.
A dental carpule is a pre-filled, single-use glass or plastic cartridge containing a local anesthetic solution, typically in a 1.7mL or 1.8mL volume. Its primary purpose is to provide a sterile, precisely measured dose for injection during dental procedures. Lidocaine carpules remain the standard for routine treatments, but articaine-based products are gaining share in more invasive surgical extractions. While glass carpules hold the largest market share, plastic variants are gaining traction due to superior durability and safety.
Market access is governed by stringent regulatory frameworks that ensure product safety and efficacy. In the United States, the FDA oversees anesthetic drug approvals, while in Europe, carpules fall under the Medical Device Regulation (MDR) for delivery systems. China's NMPA enforces its own standards for medical products. The selection between material types and anesthetic agents for specific procedural needs remains a critical decision for procurement managers.
Market Dynamics
The market's structural evolution is defined by the material transition from traditional glass to advanced, shatter-resistant plastics. This shift addresses longstanding safety protocols in dental clinics and specialized centers, impacting manufacturing processes and supply chain logistics for all participants.
Growth Catalysts
- Specialized Procedure Adoption:The rising complexity of dental procedures, including periodontal treatments and surgical extractions in specialized centers, requires reliable, single-dose anesthetic delivery systems.
- Shatter-Resistant Plastics:The adoption of advanced polymer carpules enhances workplace safety by minimizing risks of breakage and contamination, a key factor for institutional procurement managers.
- Stringent Efficacy Standards:Regulatory bodies like the FDA and EMA enforce strict guidelines for anesthetic efficacy and sterility, favoring pre-filled, precisely dosed carpules over multi-dose vials.
Market Restraints
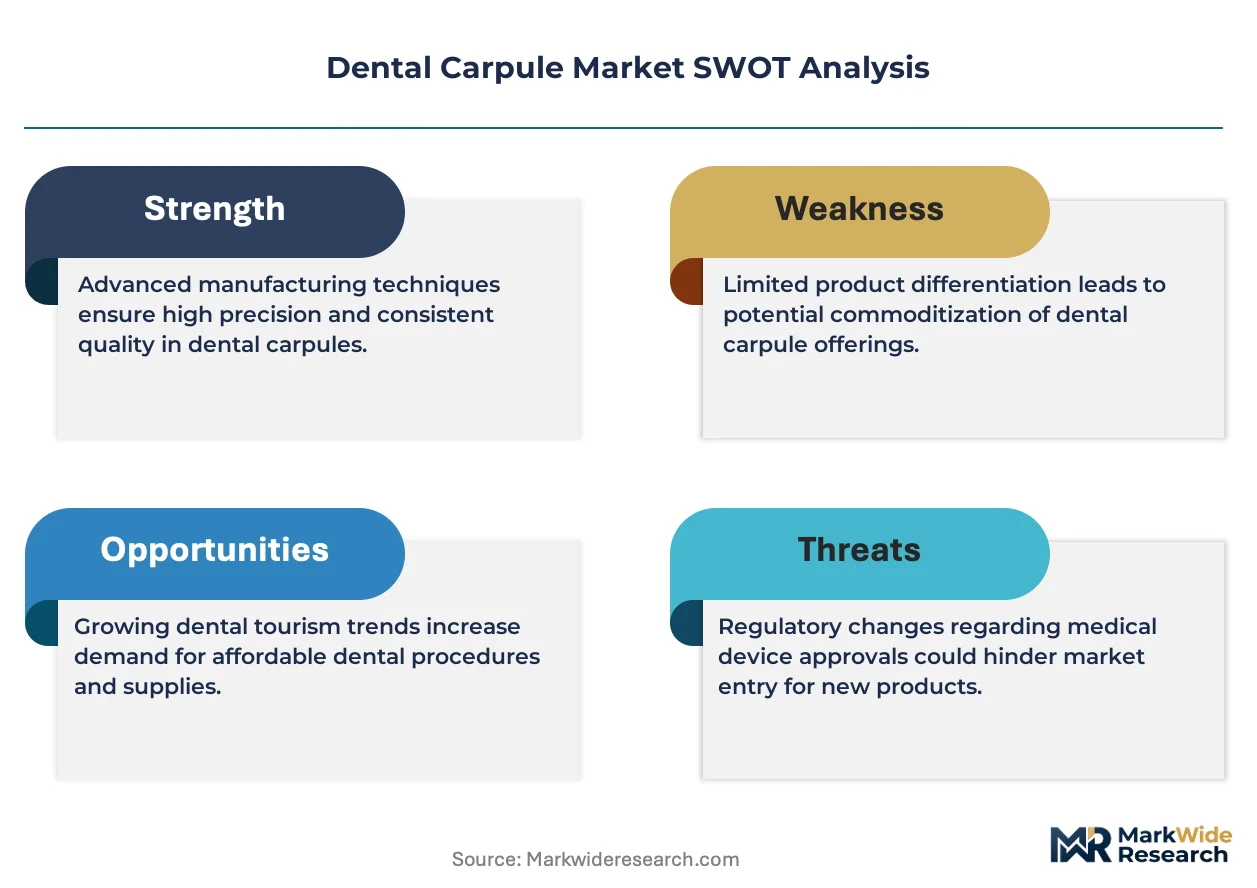
- Anesthetic Agent Costs:The price volatility of active pharmaceutical ingredients for anesthetics like articaine and lidocaine creates margin pressure for manufacturers, impacting final product pricing.
- Lengthy Approval Cycles:Gaining market access requires navigating prolonged and costly approval processes with agencies like the NMPA in China and the FDA in the United States.
- Alternative Anesthetic Delivery:The emergence of computer-controlled local anesthetic delivery (C-CLAD) systems presents a substitution threat in specific, high-end clinical scenarios.
Strategic Opportunities
- Emerging Asian Markets:Dental infrastructure development in Southeast Asian countries presents a significant opportunity for market entry, where carpule use is less saturated compared to North America.
- Non-Opioid Anesthetics:Developing and commercializing carpules with non-opioid pain management agents can address public health concerns and create a new, high-value product category.
- Digital Dentistry Integration:Carpules with RFID tags or barcodes that integrate with digital patient records and automated inventory systems offer a path for product differentiation in large clinics.
Industry Challenges
- Supply Chain Sterility:Maintaining an end-to-end sterile supply chain from API manufacturing to final delivery poses a significant logistical and quality control challenge, especially across international borders.
- MDR Compliance Burden:Transitioning to Europe's Medical Device Regulation (MDR) for the delivery component requires extensive technical documentation and clinical evidence, creating a substantial operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Carpule Market |
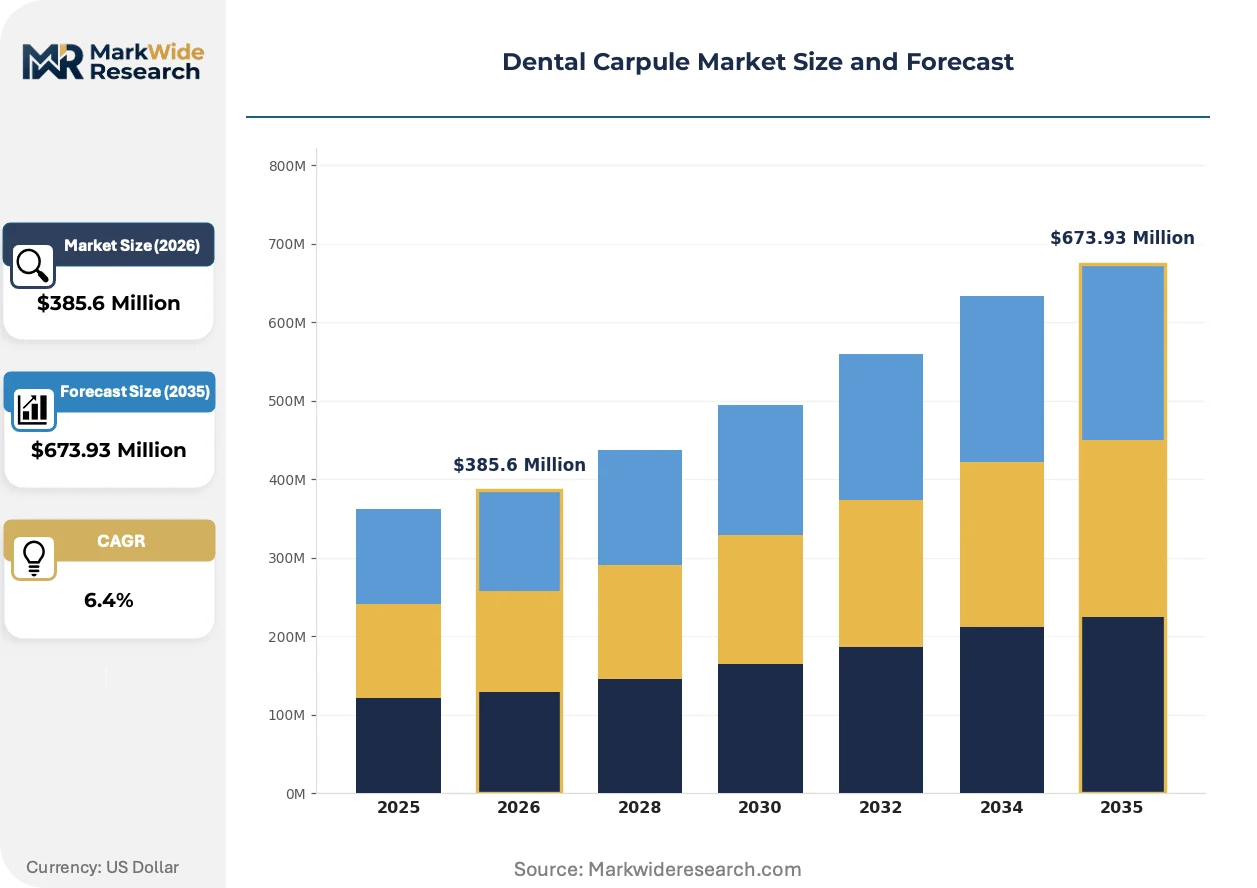
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lidocaine Carpules, Articaine Carpules, Mepivacaine Carpules, Prilocaine Carpules Packaging Type: Glass Carpules, Plastic Carpules, Aluminium Sealed Carpules, Composite Sealed Carpules Application: Local Anesthesia, Pulp Therapy, Periodontal Treatment, Surgical Extractions End User: Dental Clinics, Dental Colleges, Hospitals, Specialized Dental Centers |
| Companies Covered | Novocol Pharmaceuticals, Ultradent Products, Septodont, Medline Industries, Milestone Scientific, Dentsply Sirona, Kerr Dental, Hu-Friedy, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Carpule Market Strategic Shifts & Innovations
Material science advancements and digital integration are converging to enhance patient safety and procedural efficiency. This evolution is driven by a clinical need for greater precision in anesthetic delivery and improved material handling characteristics in demanding dental environments.
Articaine-based formulations, often combined with epinephrine, offer faster onset and deeper anesthesia than traditional lidocaine. Specialized dental centers and oral surgeons are rapidly adopting these formulations for complex procedures like surgical extractions and implantology. The superior efficacy of articaine for invasive treatments is rewriting the standard of care, shifting lidocaine's dominance toward more routine procedures.
The European Union's Medical Device Regulation (MDR) classifies the carpule as a medical device, distinct from the drug inside. This regulation mandates a more rigorous conformity assessment process for CE marking, increasing compliance costs. Consequently, suppliers targeting Europe are investing heavily in technical documentation and post-market surveillance to maintain access.
Large dental service organizations (DSOs) and hospital networks are centralizing procurement of consumables like carpules. This model disrupts traditional sales channels that targeted individual private practices, favoring suppliers with volume pricing and streamlined logistics. The shift is most visible in the United States, where the DSO model is expanding.
Dental Carpule Market Segmentation
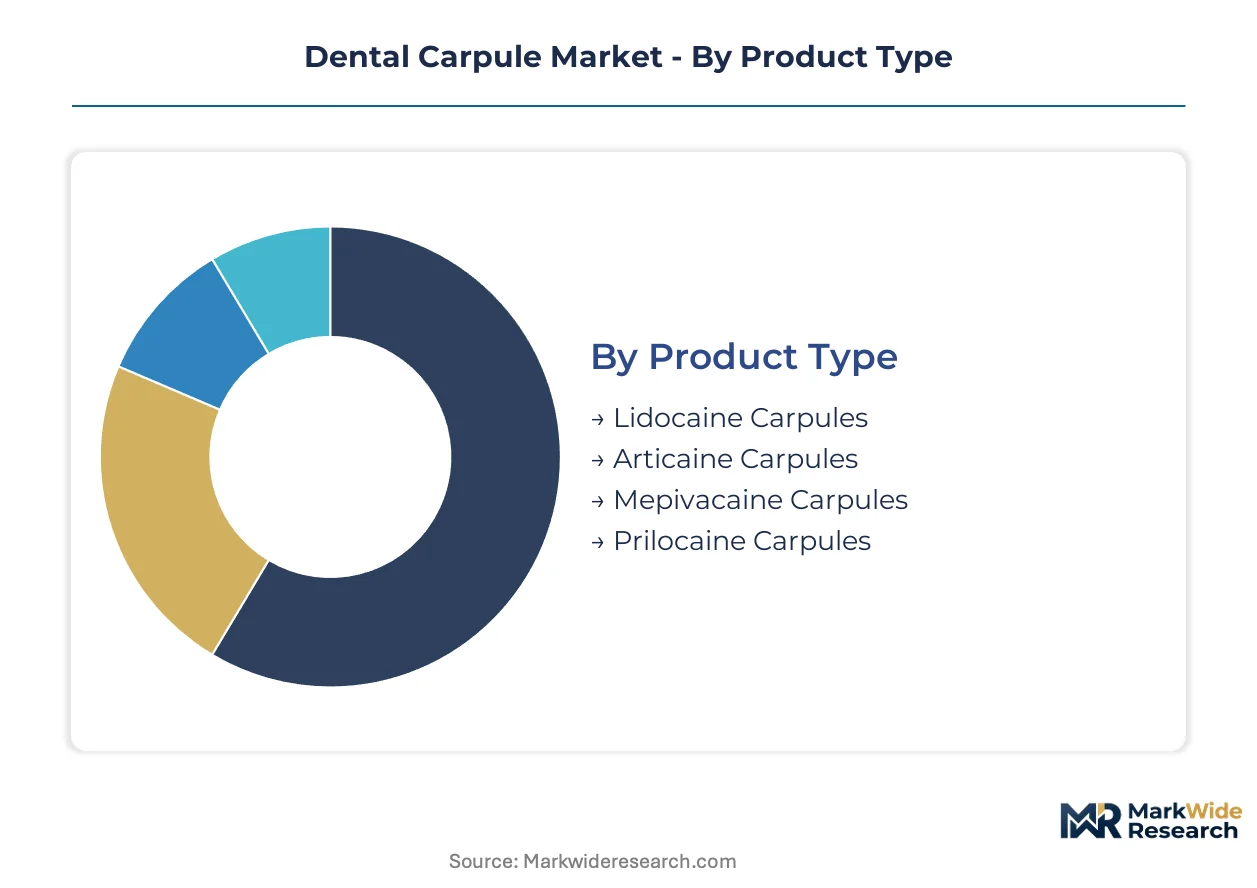
The Dental Carpule Market requires detailed segmentation to understand varying product demands and end-user preferences. This analysis highlights how material science, anesthetic agent efficacy, and clinical application drive market dynamics. Understanding these distinctions is crucial for manufacturers and procurement managers navigating procurement and product development strategies.
Product Type:
The integration of anesthetic solutions into pre-filled carpules defines the primary delivery mechanism, distinguishing between standard formulations and those designed for more complex procedures.
- Lidocaine Carpules:These pre-filled cartridges contain lidocaine, a widely used local anesthetic, often combined with epinephrine to prolong its effect. Demand concentrates in general dental clinics for routine cavity preparations and basic restorative procedures, driven by its established safety profile and cost-effectiveness.
- Articaine Carpules:Articaine-based formulations offer faster onset and deeper anesthesia, making them suitable for more invasive dental interventions. Specialized dental centers and oral surgeons in the United States increasingly adopt these for surgical extractions and implantology due to superior efficacy in complex cases.
- Mepivacaine Carpules:Mepivacaine carpules provide local anesthesia without a vasoconstrictor, suitable for patients with cardiovascular conditions or those sensitive to epinephrine.
- Prilocaine Carpules:Prilocaine formulations offer an alternative for patients sensitive to other anesthetics, providing effective local anesthesia for various dental treatments.
Lidocaine Carpules leads volumes today; Articaine Carpules is gaining share fastest.
Packaging Type:
Material selection for carpule packaging directly influences manufacturing costs and safety protocols, creating distinct tiers based on durability and production complexity.
- Glass Carpules:Traditional glass carpules, typically made from borosilicate glass, offer high chemical inertness and optical clarity for visual inspection of the anesthetic solution. They hold the largest market share in established dental markets due to historical preference and widespread manufacturing infrastructure, despite some safety concerns.
- Plastic Carpules:Shatter-resistant plastic carpules, often made from polypropylene or similar polymers, enhance safety by minimizing breakage risks during handling and injection. Adoption is accelerating in specialized dental centers and hospitals due to improved durability and reduced potential for contamination.
- Aluminium Sealed Carpules:These carpules feature an aluminum seal, ensuring sterility and extending shelf life for sensitive anesthetic agents requiring robust protection.
- Composite Sealed Carpules:Composite sealed carpules combine different materials to optimize barrier properties, offering enhanced protection against moisture and oxygen ingress.
Glass Carpules dominates market share, while Plastic Carpules exhibits strong growth.
Application:
The complexity of dental procedures dictates the specific anesthetic requirements, influencing carpule selection based on depth, duration, and onset of action.
- Surgical Extractions:These procedures, including impacted wisdom teeth removal and complex oral surgeries, require profound and prolonged anesthesia, often favoring articaine-based carpules. Specialized dental centers rely on these formulations for their superior efficacy in managing significant pain and discomfort.
- Local Anesthesia:This broad category encompasses routine dental interventions like fillings, crown preparations, and minor soft tissue procedures. Lidocaine carpules remain the standard for local anesthesia due to their reliability, rapid onset, and established safety profile across general dental clinics.
- Pulp Therapy:Pulp therapy, including root canal treatments, demands effective anesthesia to manage intense pain associated with inflamed or infected pulp tissue.
- Periodontal Treatment:Periodontal treatments, such as scaling and root planing, require localized anesthesia to ensure patient comfort during deep cleaning and gum procedures.
Demand for Local Anesthesia procedures drives consistent uptake, with Surgical Extractions treatments requiring specialized solutions.
End User:
The organizational structure and operational scale of dental care providers significantly impact procurement patterns and the types of carpules demanded.
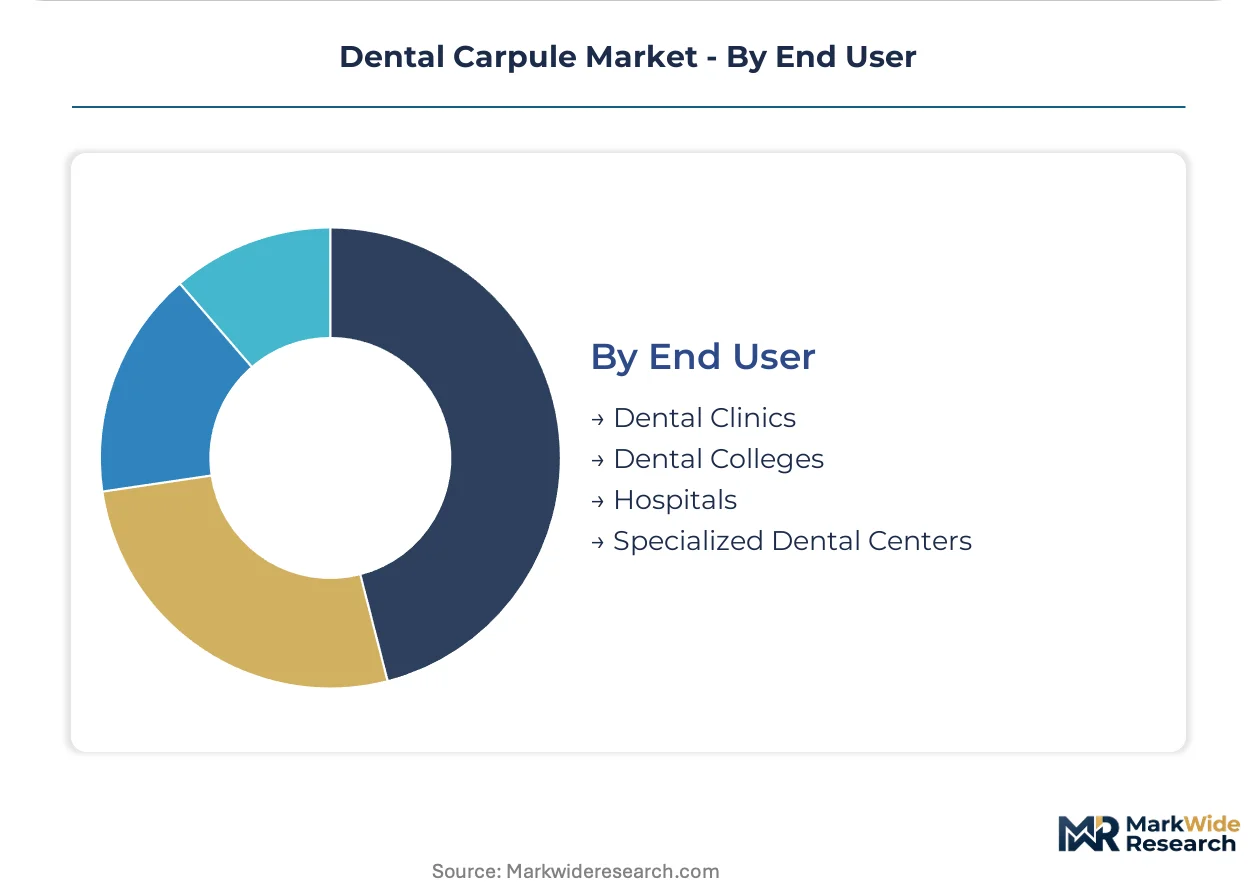
- Dental Clinics:Independent and small group dental clinics form the largest end-user segment, primarily utilizing lidocaine carpules for a wide range of routine restorative and preventive procedures. Their procurement often involves direct supplier relationships or local distributors, focusing on cost-effectiveness and reliable supply.
- Specialized Dental Centers:These centers focus on complex procedures like oral surgery, periodontics, and implantology, driving demand for advanced articaine carpules and shatter-resistant plastic variants. Procurement managers in these facilities prioritize product efficacy, safety, and integration with advanced digital dentistry solutions.
- Dental Colleges:Dental colleges serve as training grounds, consuming carpules for educational purposes and patient treatment within supervised clinical settings.
- Hospitals:Hospitals integrate dental services into broader healthcare offerings, using carpules for oral surgeries and dental treatments within inpatient or outpatient departments.
Traditional Dental Clinics remain primary consumers, but Specialized Dental Centers are expanding their procurement volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' advanced dental infrastructure drives significant demand for dental carpules, particularly for specialized procedures and routine treatments. This demand spans both general dental clinics and specialized centers across various geographies. Regulatory frameworks like those from the FDA ensure product safety and efficacy across the market.
United States
The United States' advanced dental care infrastructure drives substantial demand for dental carpules, particularly for specialized procedures. The FDA rigorously oversees anesthetic drug approvals, ensuring high product safety and efficacy standards. In the New York City metropolitan area, numerous dental clinics and research institutions contribute to continuous product innovation and adoption. Procurement managers prioritize both efficacy and safety in their selection criteria.
Germany
Germany's sophisticated healthcare system and high adoption of advanced dental techniques create consistent demand for specialized dental carpules. The European Medical Device Regulation (MDR) mandates rigorous conformity assessments for delivery systems, influencing market access. Bavaria, a hub for medical technology manufacturing, sees significant development and distribution of high-quality dental consumables. Dental professionals seek products meeting stringent European standards.
China
China's expanding dental infrastructure and increasing dental tourism drive a growing market for anesthetic carpules. The NMPA enforces stringent standards for medical products, shaping local manufacturing and import strategies. Within the Yangtze River Delta, a rapidly developing cluster of dental clinics and hospitals is adopting both domestic and international carpule technologies. Local procurement focuses on cost-effectiveness and regulatory compliance.
Japan
Japan's aging population requires extensive dental care, sustaining a high demand for reliable anesthetic solutions. The PMDA ensures strict regulatory oversight for all medical devices and pharmaceuticals, prioritizing patient safety. The Tokyo metropolitan area, with its dense concentration of dental practices and research facilities, frequently integrates innovative carpule designs and advanced anesthetic agents. Dental professionals emphasize precision and minimal invasiveness.
India
India's rising disposable incomes and expanding middle class contribute to a growing demand for modern dental treatments. The CDSCO regulates drug and device approvals, influencing the availability and quality of dental carpules. Maharashtra, particularly Mumbai, hosts a significant number of dental clinics and educational institutions, driving the adoption of both traditional and advanced anesthetic delivery systems. Local manufacturers are increasing their production capacity.
Dental Carpule Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers seek to broaden their offerings across various anesthetic agents and carpule materials. The market structure includes established global players, specialized anesthetic producers, and integrated digital dentistry solution providers. Strategic partnerships and geographic expansion are common competitive moves, alongside continuous product innovation to meet evolving clinical needs. Manufacturers balance product efficacy with stringent regulatory compliance.
Within the global diversified segment, Septodont exemplifies a strategy of leveraging an extensive product portfolio to serve both general and specialized dental end-users. Dentsply Sirona, a global dental technology company, occupies a position anchored by its integrated digital dentistry solutions, which incorporate anesthetic delivery. Novocol Pharmaceuticals, a specialized anesthetic producer, sustains its market presence through large-scale manufacturing of essential lidocaine and articaine carpules, catering to high-volume demand.
| Leading Market Players |
|---|
| Novocol Pharmaceuticals |
| Ultradent Products |
| Septodont |
| Medline Industries |
| Milestone Scientific |
| Dentsply Sirona |
| Kerr Dental |
| Hu-Friedy |
| Henry Schein |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of anesthetic agents anchors the supply position for major dental carpule producers, directly influencing their pricing power in a market defined by stringent regulatory requirements. This integration allows for better cost control and ensures consistent availability of critical pharmaceutical ingredients.
Pricing Analysis
The cost pass-through of active pharmaceutical ingredients significantly impacts dental carpule pricing. Per-unit transactional pricing dominates this market, with differentiation stemming from material quality, such as borosilicate glass versus advanced polymers, and stringent regulatory compliance like FDA or MDR certifications. Pricing pressure stems from the price volatility of anesthetic agents, creating margin challenges for manufacturers. Dental clinics exhibit higher price sensitivity compared to specialized dental centers, which prioritize efficacy and safety features.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China and India influences the global dental carpule supply chain. Production relies heavily on active pharmaceutical ingredients such as lidocaine and articaine, alongside specialized borosilicate glass or polymer materials. Maintaining end-to-end sterility across the supply chain, from API manufacturing to final delivery, presents a significant logistical and quality control challenge. Distribution runs through both large dental service organizations centralizing procurement and traditional local distributors serving individual practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental carpule market presents a late-cycle quality story, driven by a demand shift towards premium specifications for advanced anesthetic agents like articaine. Clinical needs for superior efficacy in complex procedures underscore this evolution.
For Market Incumbents:Acquire specialized polymer manufacturing capabilities to enhance shatter-resistant plastic carpule production. Incumbents must invest in R&D for non-opioid anesthetic formulations, addressing public health concerns and creating new product categories. This strategy defends against the substitution threat from computer-controlled local anesthetic delivery (C-CLAD) systems. Strengthening partnerships with large dental service organizations secures distribution channels and procurement volumes.
For New Entrants and Emerging Players:Digital integration through RFID tags or barcodes offers a pathway for new entrants to differentiate products within large clinics. Focus on emerging Asian markets, particularly Southeast Asian countries, represents the most penetrable geography due to less saturated carpule use. Developing and commercializing non-opioid anesthetic carpules provides a high-value product category, appealing to procurement managers in large dental service organizations.
For Investors and Strategic Acquirers:Roll-up economics work for specialized anesthetic producers due to their focused manufacturing capabilities and established regulatory compliance. The market exhibits long-term viability, driven by sustained global demand for dental care across diverse procedures. Target acquisition archetypes include manufacturers with advanced polymer carpule production or specialized articaine formulation expertise. Monitor the adoption rates of shatter-resistant plastic carpules as a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Articaine Production Capacity | Addresses rising demand from specialized dental centers for complex surgical extractions. |
| Invest in Plastic Carpule Manufacturing | Enhances safety protocols and meets institutional procurement preferences in dental clinics. |
| Pursue MDR Compliance for Europe | Secures market access and strengthens competitive positioning for delivery systems in Germany. |
| Develop Non-Opioid Anesthetic Formulations | Creates new high-value product categories addressing public health concerns in the United States. |
| Integrate RFID/Barcode Technology | Streamlines inventory management for large dental service organizations and digital patient records. |
Research Approach
Direct dialogue with dental professionals, procurement managers, and regulatory experts provided qualitative grounding for this study. Primary research was validated against a comprehensive review of secondary sources, including FDA filings, NMPA standards, and EMA guidelines. Bottom-up and top-down triangulation ensured data accuracy. Industry association reports further informed market dynamics.
Market size projections and growth rates were produced by the quantitative model across the analysis window. Segmentation dimensions included product type, packaging type, application, end user, and regional regulatory environment. Compound annual growth rates derived from historical trends and projected adoption patterns. Key forecast inputs included anesthetic agent demand and material science advancements.
The model assumes a particular technology adoption path; alternative pathways for C-CLAD systems would alter the outlook. Forecasts reflect assumptions regarding regulatory shifts and material science breakthroughs. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Dental Healing Caps Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Dental Contouring Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Prophy Dental Handpiece Market