
 Specialty Generics Market | 2026-2036
Specialty Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Generics Market Intelligence
Indian API-to-finished-dose manufacturers is consolidating around injectable capacity and oncology filings. Teva Pharmaceutical Industries Ltd leverages its vertically integrated sterile manufacturing network to anchor hospital contract positions in North America and Europe. Sun Pharmaceutical Industries Ltd sustains a differentiated portfolio in dermatology and CNS specialty generics across emerging and developed markets. Dr. Reddy's Laboratories Ltd competes through complex formulation capabilities in injectables and biosimilar-adjacent small molecules.
Specialty generics comprise chemically synthesized off-patent drugs requiring specialized manufacturing processes, stability controls, or administration protocols that create meaningful barriers to generic substitution. These products typically involve parenteral formulations, controlled-release matrices, or drug-device combinations demanding validated aseptic processing and extractables-leachables testing. Injectables command the deepest margin pools due to sterile manufacturing complexity and limited qualified facility capacity. Oncology within therapy areas attracts the fastest portfolio expansion as patent cliffs for cytotoxics and supportive care agents accelerate filing activity. Oral tablets remain the largest volume category but face steeper price erosion as formulation barriers lower.
FDA's ANDA suitability petitions and complex generic guidance shape product-specific development pathways and bioequivalence standards for specialty formulations. EMA's centralized marketing authorization procedures and variation frameworks govern batch-release and manufacturing-site changes across European member states. India's CDSCO and BIS standards for active pharmaceutical ingredients influence upstream supply qualification for export-oriented manufacturers. Stakeholders must monitor regulatory divergence between FDA's product-specific guidance and EMA's scientific advice procedures when prioritizing development sequences and target market filings.
Market Dynamics
Patent cliffs for complex injectables are pulling capacity-constrained manufacturers into sterile oncology filings faster than facility qualification timelines can absorb, creating a supply bottleneck that favors pre-qualified sterile networks.
Growth Catalysts
- Medicare reimbursement policies:The IRA's inflation rebate provisions and Part B payment adjustments for biosimilar-adjacent small molecules accelerate hospital formulary switches to lower-cost alternatives.
- India's CDSCO streamlined approvals:Export-oriented manufacturers leverage faster domestic clearances to front-load ANDA submissions for complex parenterals into the US FDA queue.
- Controlled-release matrix technologies:Advances in lipid nanoparticle and polymeric depot formulations extend product life cycles beyond basic generic substitution.
Market Restraints
- Qualified facility scarcity:Sterile injectable capacity concentrates among a limited pool of FDA-inspected sites, constraining batch release velocity for new entrants.
- API input cost volatility:Cytotoxic active pharmaceutical ingredient supply chains face solvent and starting material price swings tied to energy-intensive chemical synthesis.
- EMA variation framework friction:Manufacturing site changes for approved products trigger prolonged centralized procedure timelines, freezing capacity reallocation decisions.
Strategic Opportunities
- Brazil's ANVISA accelerated pathway:Local partnership structures for oncology injectables open access to Latin America's largest hospital procurement pool.
- Drug-device combination filings:Pre-filled syringe and auto-injector platforms for supportive care agents create differentiation beyond commodity vial presentations.
- Specialty pharmacy channel consolidation:Limited distribution network contracts for high-touch parenteral products concentrate volume with logistics-capable dispensers.
Industry Challenges
- Aseptic processing technician shortage:Validated sterile operators with media fill experience command premium wages, constraining batch throughput at expansion sites.
- Extractables-leachables testing timelines:Container closure system qualification for novel delivery formats extends development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Generics Market |
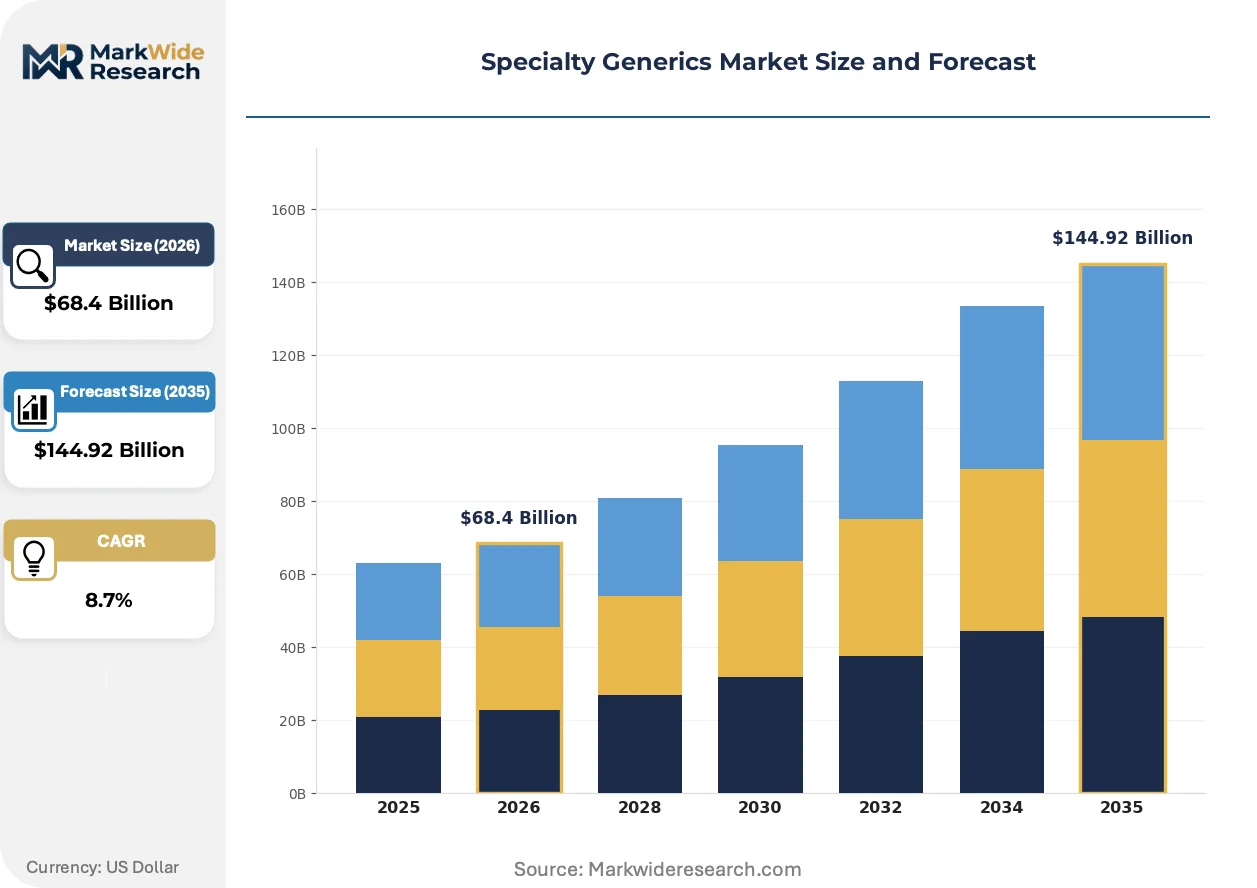
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Oral Tablets, Creams, Transdermal Patches Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology Delivery Mode: IV Administration, Oral, Topical, Intranasal End User: Hospitals, Pharmacies, Clinics, Specialty Clinics |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Viatris Inc., Sun Pharmaceutical Industries Ltd, Hikma Pharmaceuticals PLC, Amneal Pharmaceuticals LLC, Mallinckrodt, Endo Pharmaceuticals Inc., Dr. Reddy’s Laboratories Ltd, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Generics Market Strategic Shifts & Innovations
Continuous manufacturing and real-time release testing are compressing batch cycle times while regulatory acceptance of process analytical technology expands. These shifts favor capital-rich manufacturers with legacy sterile infrastructure.
Isolator-based aseptic filling lines with restricted access barrier systems are automating vial handling and capping sequences previously requiring human intervention. Hospital procurement groups now specify robotic manufacturing audit trails in supplier scorecards. This automation is compressing contamination risk profiles and reducing batch failure rates for high-potency cytotoxics.
EMA's revised Annex 1 sterile manufacturing guidelines mandate stricter environmental monitoring and contamination control strategies for aseptic processing. European manufacturers face capital outlays for upgraded HVAC and isolator infrastructure. Oncology injectable sites in Germany and Switzerland are prioritizing barrier technology retrofits over greenfield expansion.
Group purchasing organizations for hospital oncology products are consolidating formulary decisions under centralized pharmacy and therapeutics committees. Independent community oncology practices lose direct purchasing autonomy as integrated delivery networks absorb infusion capacity. This concentration is most visible in Texas and Florida, where specialty pharmacy carve-outs now manage buy-and-bill reimbursement flows.
Specialty Generics Market Segmentation
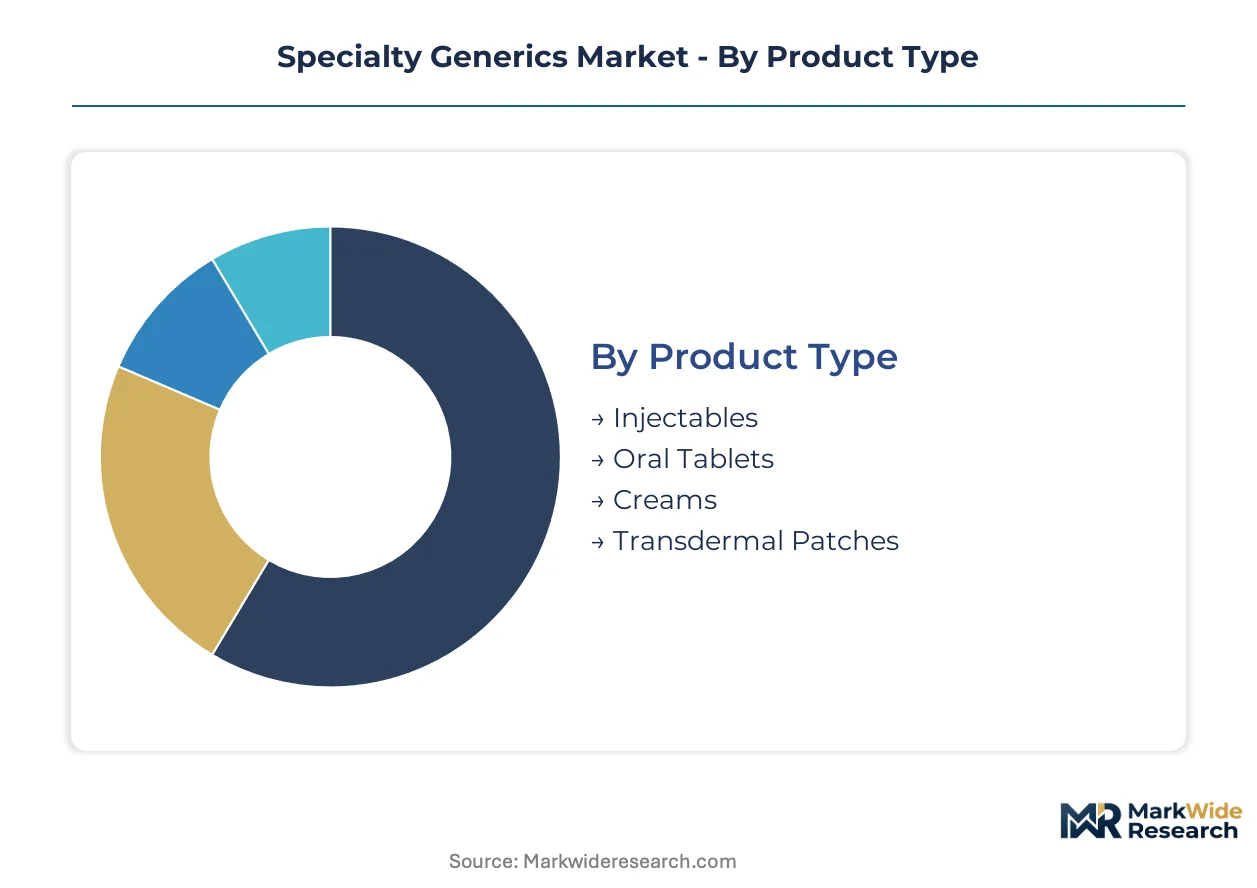
Specialty generics segmentation reveals how manufacturing complexity, clinical setting requirements, and reimbursement pathways fragment commercial opportunity across distinct technical and customer categories. Understanding these divides explains why sterile capacity constraints command premium positioning while oral formulations face commodity pressure.
Product Type:
Upgrade cycles in manufacturing infrastructure are pulling capital toward higher-barrier formats as basic oral capacity saturates.
- Injectables:Parenteral formulations demand validated aseptic processing, isolator-based filling lines, and extractables-leachables qualification for container closure systems. Hospital procurement of oncology injectables concentrates in the United States and Germany, where Medicare reimbursement policies and EMA batch-release frameworks reward pre-qualified sterile networks with formulary preference.
- Oral Tablets:Immediate-release and modified-release matrices utilize standard compression and coating equipment with lower capital barriers. Volume placements cluster in retail pharmacy channels across India and Brazil, though price erosion accelerates as CDSCO streamlined approvals and ANVISA pathways multiply qualified suppliers.
- Creams:Semi-solid emulsions require homogenization and tube-filling infrastructure with validated cleaning protocols for potency switching. Dermatology demand in France and Italy sustains margin pools for topical corticosteroid and immunomodulator generics.
- Transdermal Patches:Matrix and reservoir designs integrate adhesive lamination with rate-controlling membranes for sustained delivery. Pain management applications in Japan and South Korea drive regulatory filings for fentanyl and buprenorphine patch adaptations.
Volume placements concentrate in Oral Tablets; the faster expansion belongs to Injectables.
Therapy Area:
Cost tier differentiation separates chronic maintenance therapies from acute intervention categories with concentrated hospital purchasing power.
- Oncology:Cytotoxic injectables and supportive care agents require containment facilities with operator exposure limits and environmental monitoring. Hospital networks in Texas and Florida consolidate buy-and-bill procurement under specialty pharmacy carve-outs, accelerating formulary switches to lower-cost alternatives.
- Cardiovascular:Antihypertensive and anticoagulant oral generics face intense price competition but sustain volume through Medicare Part D coverage. Retail dispensing in the United States and United Kingdom dominates, with 90-day supply incentives driving generic substitution rates.
- Neurology:Controlled-release formulations for epilepsy and Parkinson's disease demand bioequivalence studies with pharmacokinetic endpoints in patient populations. CNS specialty generics from Indian manufacturers penetrate Latin American markets through partnership structures with local distributors.
- Endocrinology:Insulin and GLP-1 adjacent small molecules confront biosimilar competition but retain niche positioning for oral hypoglycemics. Diabetes clinic procurement in Germany and Switzerland favors validated cold-chain handling for peptide-containing formulations.
Revenue concentrates in Oncology; the steepest volume trajectory belongs to Cardiovascular.
Delivery Mode:
Application context determines whether administration requires clinical supervision or permits self-managed dosing, reshaping distribution infrastructure requirements.
- IV Administration:Infusion protocols demand hospital or infusion center settings with nursing oversight and adverse event monitoring. Oncology and antimicrobial applications in the United States and United Kingdom anchor demand for pre-mixed bag and vial presentations.
- Oral:Self-administered dosing enables retail pharmacy dispensing with adherence packaging and refill automation. Chronic disease management across India and Brazil sustains volume for metformin, statin, and antihypertensive portfolios.
- Topical:Dermatology and localized pain applications permit outpatient dispensing with patient education on application technique. European pharmacy networks in Spain and Poland manage reimbursement verification for high-potency corticosteroid creams.
- Intranasal:Spray and drop formulations for migraine, allergy, and emergency reversal agents require priming instructions and dose-counting devices. Emergency department procurement in the United States and Canada specifies naloxone and sumatriptan spray presentations.
Procurement concentrates in IV Administration; the expanding application base belongs to Intranasal.
End User:
Customer type fragmentation reflects how reimbursement flow and clinical risk tolerance distribute purchasing authority across care settings.
- Hospitals:Inpatient and outpatient infusion centers manage oncology and antimicrobial procurement through pharmacy and therapeutics committees. Group purchasing organization consolidation in the United States centralizes formulary decisions under integrated delivery networks.
- Pharmacies:Retail and mail-order channels handle oral generic dispensing with automated refill programs and 90-day supply incentives. Medicare Part D plans in the United States and NHS reimbursement in the United Kingdom drive volume concentration.
- Clinics:Physician office-based infusion for supportive care and chronic disease management operates under buy-and-bill reimbursement. Community oncology practices in Texas and Florida lose purchasing autonomy as specialty pharmacy carve-outs absorb infusion capacity.
- Specialty Clinics:Limited distribution networks for high-touch parenteral products concentrate volume with logistics-capable dispensers. Dermatology and neurology centers in Germany and Switzerland manage prior authorization for controlled-release formulations.
Procurement concentrates in Hospitals; the channel gaining share fastest belongs to Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis clusters in Gujarat and Telangana anchor upstream supply for sterile oncology formulations. Finished dose manufacturing gravitates toward FDA-inspected facilities in the United States, Germany, and Switzerland.
United States
Hospital procurement of oncology injectables concentrates in Texas and Florida infusion networks. The IRA's inflation rebate provisions accelerate formulary switches to lower-cost alternatives. Integrated delivery networks in Houston and Miami absorb community oncology practice purchasing autonomy under specialty pharmacy carve-outs.
Germany
EMA batch-release frameworks reward pre-qualified sterile manufacturing sites with formulary preference in hospital procurement. The country's national pharmaceutical regulator mandates stricter environmental monitoring under revised Annex 1 sterile manufacturing guidelines. Oncology injectable facilities in Bavaria prioritize barrier technology retrofits over greenfield expansion.
India
Export-oriented manufacturers leverage CDSCO streamlined approvals to front-load ANDA submissions for complex parenterals. The national pharmaceutical regulator's faster domestic clearances compress development timelines. API-to-finished-dose consolidation centers on injectable capacity in Gujarat and Telangana.
Switzerland
Swissmedic oversight of sterile manufacturing maintains exacting standards for cytotoxic containment facilities. The national regulator's variation frameworks govern batch-release across European distribution. Basel-area manufacturing clusters specialize in high-potency oncology formulations with validated cold-chain infrastructure.
Brazil
ANVISA accelerated pathways for oncology injectables open access to Latin America's largest hospital procurement pool. The national health surveillance agency's streamlined procedures attract partnership structures from Indian manufacturers. São Paulo hospital networks consolidate formulary decisions under centralized pharmacy committees.
Specialty Generics Market Key Industry Players
Global majors compete with regional champions across sterile manufacturing capacity and complex formulation capabilities. The vendor base stratifies between vertically integrated API-to-dose networks and specialized sterile contractors. Three archetypes dominate: capital-rich sterile infrastructure owners, Indian export-oriented filers, and regional hospital contract anchors. Competitive moves concentrate on M&A for qualified facility access and strategic partnerships for Latin American market entry.
Among Israeli and Indian pharmaceutical manufacturers, Teva Pharmaceutical Industries Ltd and Sun Pharmaceutical Industries Ltd exemplify vertically integrated sterile network strategies, while Dr. Reddy's Laboratories Ltd occupies a position within the complex formulation specialist tier. These companies represent contrasting approaches to hospital contract positioning across North American and European procurement channels.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Viatris Inc. |
| Sun Pharmaceutical Industries Ltd |
| Hikma Pharmaceuticals PLC |
| Amneal Pharmaceuticals LLC |
| Mallinckrodt |
| Endo Pharmaceuticals Inc. |
| Dr. Reddy's Laboratories Ltd |
| Lupin |
| Others |
Cost & Logistics Intelligence
EMA's revised Annex 1 sterile manufacturing guidelines gate both qualified supply and premium-tier pricing access, as facilities investing in isolator infrastructure and enhanced environmental monitoring capture formulary preference from hospital procurement committees while non-compliant manufacturers face margin compression in commodity oral segments.
Pricing Analysis
Service-bundling separates validated batch-release documentation and regulatory compliance support from base product quotations in hospital contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA inspection history, EMA variation framework compliance, and cold-chain handling certification. Price differentiation hinges on sterile manufacturing complexity and qualified facility scarcity. Cost compression in oral tablet categories is intensifying because CDSCO streamlined approvals multiply qualified Indian suppliers, while injectable premiums widen as capacity constraints persist.
Supply Chain Analysis
Cytotoxic API synthesis rests on specialty chemical producers in Gujarat and Telangana, with finished dose manufacturing anchored in FDA-inspected sites across the United States, Germany, and Switzerland. Key inputs include platinum-based catalysts, high-purity solvents, and borosilicate vials with validated extractables profiles. Single-source vulnerability concentrates in sterile filling capacity, where media fill-qualified technicians command premium wages and constrain batch throughput. Distribution runs through group purchasing organizations for hospital oncology procurement and specialty pharmacy networks for limited distribution products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as qualified facility scarcity and EMA variation framework friction force sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Extend sterile network capacity through barrier technology retrofits at existing FDA-inspected sites rather than greenfield expansion, as EMA batch-release timelines freeze capacity reallocation decisions. Deepen hospital contract positions in Texas and Florida infusion networks before specialty pharmacy carve-outs absorb remaining community oncology purchasing autonomy. Backward integration into cytotoxic API synthesis in Gujarat insulates against solvent price volatility and starting material supply disruption. For New Entrants and Emerging Players: Continuous manufacturing platforms with real-time release testing offer a technology-first wedge into hospital procurement scorecards specifying robotic manufacturing audit trails. Target Brazil's ANVISA accelerated pathway through partnership structures with São Paulo hospital networks, the most penetrable geography for oncology injectable entry. Lead with drug-device combination filings for pre-filled syringe presentations that differentiate beyond commodity vial supply. For Investors and Strategic Acquirers: FDA warning letter resolution at sterile oncology facilities is the leading indicator that distressed manufacturing assets are approaching investable condition. Long-term viability favors vertically integrated API-to-dose networks with captive sterile capacity across multiple regulatory jurisdictions. Watch for CDSCO streamlined approval acceleration as the signal that Indian export-oriented manufacturers are front-loading ANDA submissions and approaching liquidity events.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Aseptic Filling Investment | Robotic manufacturing audit trails satisfy hospital procurement scorecards in Texas and Florida networks. |
| CDSCO Streamlined Approval Leverage | Faster domestic clearances compress ANDA submission timelines for complex parenterals into FDA queues. |
| Drug-Device Combination Filing Expansion | Pre-filled syringe platforms for supportive care agents differentiate beyond commodity vial presentations. |
| API-to-Finished-Dose Consolidation | Captive cytotoxic synthesis in Gujarat insulates against solvent price volatility and supply disruption. |
| Specialty Pharmacy Network Partnership | Limited distribution contracts concentrate high-touch parenteral volume with logistics-capable dispensers. |
Research Approach
Multi-period observation of FDA ANDA filing volumes, EMA centralized procedure approvals, and hospital formulary switch rates anchored the trend analysis, supplemented by interviews with sterile manufacturing executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA Orange Book listings, EMA EPAR documents, CDSCO approval databases, and CMS Medicare reimbursement data. Bottom-up facility capacity modeling and top-down therapy area demand estimation were triangulated against cross-referenced primary intelligence.
Segment-weighting across product type, therapy area, delivery mode, and end user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves against patent cliff timing and regulatory pathway acceleration. Modeled inputs included sterile manufacturing capacity utilization rates, API input cost indices, and Medicare Part B payment adjustment impacts on hospital formulary substitution.
Several conditions sit outside the modeled scope, including unforeseen regulatory guidance revisions, abrupt API supply disruptions from geopolitical events, and rapid biosimilar displacement of small-molecule oncology agents. Forecasts reflect documented assumptions about qualified facility expansion timelines and reimbursement policy continuity. A small set of named triggers warrants ongoing watch: FDA inspection citation trends, EMA Annex 1 implementation delays, and IRA inflation rebate provision administrative rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Alopecia Market