
 ADHD Therapeutics Market | 2026-2036
ADHD Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
ADHD Therapeutics Market Analysis
Adult psychiatric services is realigning demand away from purely pediatric prescribing patterns. Takeda Pharmaceutical Company leverages its transdermal patch portfolio to sustain differentiation in non-stimulant delivery. Eli Lilly and Company anchors its position through R&D intensity in novel mechanism antidepressant-adjacent compounds. Novartis AG dominates European regulatory pathways with established extended-release formulations.
ADHD therapeutics comprise pharmacological interventions targeting dopaminergic and noradrenergic neurotransmission dysregulation, formulated as immediate-release or extended-release matrices with defined dissolution profiles to sustain plasma concentration across school or workday intervals. Stimulants occupy the largest revenue pool due to decades of clinical evidence and payer familiarity, while extended-release formulations capture the fastest expansion as adherence engineering reduces midday dosing burden. Non-stimulants command premium positioning where controlled-substance restrictions or cardiovascular contraindications limit amphetamine or methylphenidate access.
The FDA's scheduling oversight under the Controlled Substances Act combines with DEA production quotas to constrain supply elasticity and shape manufacturer capacity planning. The EMA's pediatric investigation plans and the EU's pharmacovigilance framework impose parallel development obligations for sponsors seeking transatlantic approval. Stakeholders must monitor how digital therapeutics candidates seeking FDA breakthrough designation compete for prescriber mindshare and reimbursement slots against established molecular therapies.
Market Dynamics
The DEA's production quota system for controlled substances is constraining supply elasticity and forcing manufacturers to align capacity planning with multi-year federal allocation schedules rather than market demand signals.
Growth Catalysts
- Extended-release formulation engineering:Matrix dissolution technologies reduce midday dosing burden for school and workplace adherence. Pediatric psychiatry clinics are expanding medication management programs around these platforms.
- FDA labeling modernization:Updated controlled substance prescription protocols are standardizing electronic prescribing mandates and reducing diversion risk. This regulatory clarity accelerates payer formulary inclusion for new molecular entities.
- Adult diagnostic expansion:Psychiatric services in the United States are reclassifying previously undiagnosed cases, creating demand outside traditional pediatric prescribing patterns.
Market Restraints
- DEA quota rigidity:Annual production ceilings for amphetamine and methylphenidate active pharmaceutical ingredients prevent supply response to demand surges. Manufacturers cannot expand output without federal schedule adjustment.
- Cardiovascular contraindication screening:Pre-treatment cardiac risk assessment requirements limit stimulant access for adult patients with hypertension or arrhythmia history.
- Generic immediate-release commoditization:Patent-expired methylphenidate and mixed amphetamine salts compress pricing power for originator brands in the largest volume segment.
Strategic Opportunities
- Transdermal delivery white space:Non-stimulant patches bypass first-pass hepatic metabolism and gastrointestinal tolerability issues. Takeda's portfolio demonstrates pathway feasibility for noradrenergic agents.
- EMA pediatric investigation plan alignment:Sponsors completing European development obligations gain simultaneous transatlantic regulatory positioning. Extended-release formulations with European approval anchor premium pricing in Germany and France.
- Digital therapeutic adjacency:FDA breakthrough-designation candidates for cognitive behavioral intervention apps compete for prescriber mindshare and reimbursement slots alongside molecular therapies.
Industry Challenges
- Controlled substance compliance infrastructure:Manufacturers must maintain DEA-registered facilities with dual-lock storage, perpetual inventory tracking, and chain-of-custody documentation across distribution networks.
- Clinical trial recruitment compression:Pediatric psychiatry study enrollment faces competition from oncology and rare disease pipelines, extending development timelines for novel mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ADHD Therapeutics Market |
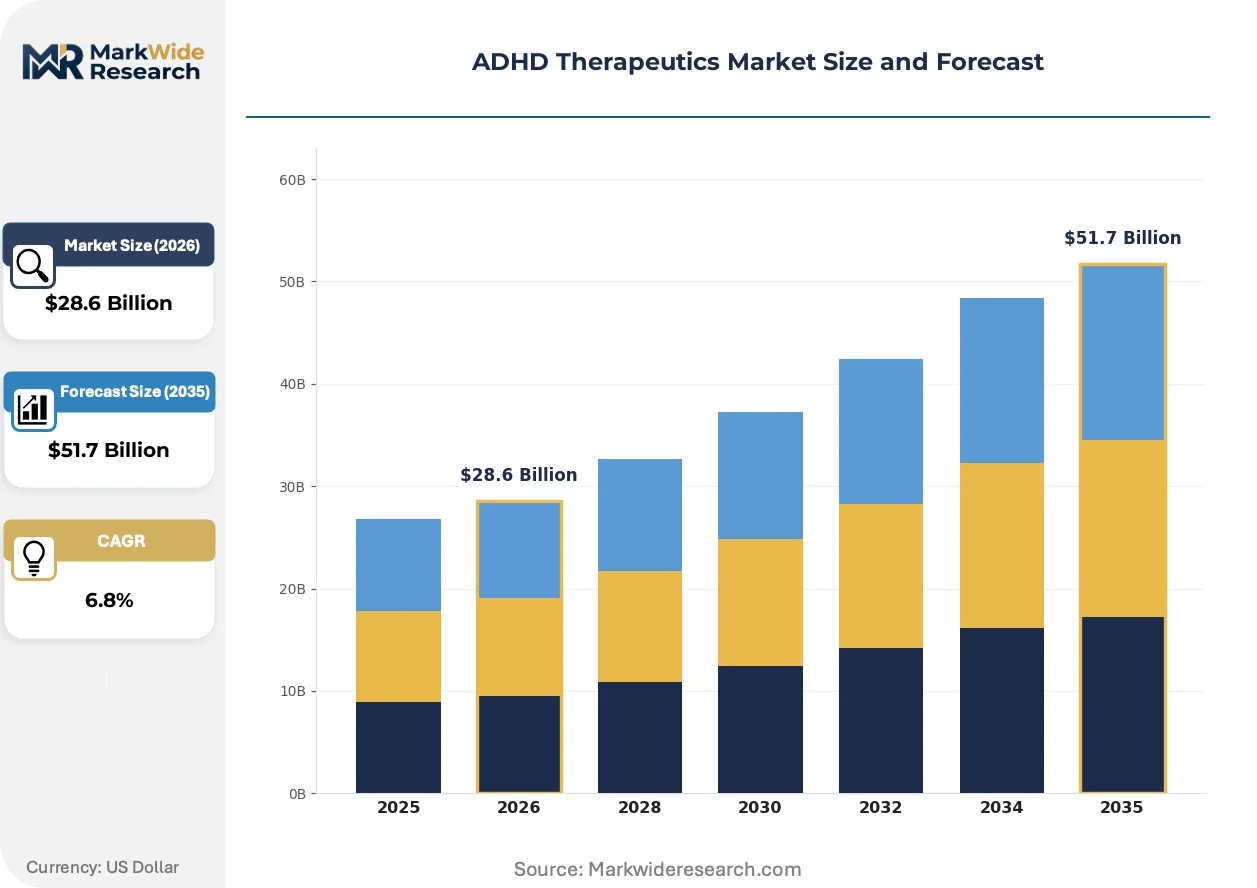
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Non-Stimulants, Combination Therapies, Extended-Release Formulations Delivery Mode: Oral Tablets, Transdermal Patches, Injectable Solutions, Sublingual Sprays Age Group: Pediatrics, Adolescents, Adults, Geriatrics End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Takeda Pharmaceutical Company, Novartis AG, Eli Lilly and Company, Johnson & Johnson, Pfizer, Supernus Pharmaceuticals, Tris Pharma, NEOS Therapeutics, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADHD Therapeutics Market Emerging Trajectories
Formulation science and regulatory technology are converging to reshape how ADHD therapeutics reach patients. Three developments are compressing competitive timelines and altering prescriber-channel relationships.
Prodrug activation systems are consolidating pharmacokinetic control within single daily doses. These platforms release active moieties through enzymatic cleavage in the gastrointestinal tract, smoothing plasma concentration curves. Adult workplace populations with inflexible scheduling are adopting these formulations fastest, compressing demand for traditional immediate-release rescue dosing.
EMA's pharmacovigilance framework is tightening post-market surveillance obligations for extended-release stimulants. Sponsors must submit periodic safety update reports with real-world cardiovascular event data. European national regulators in France and Germany are responding with stricter risk-minimization measures for adult initiation protocols.
Employer-sponsored mental health benefits are restructuring how adult patients access diagnosis and ongoing management. Large self-insured plans in the United States are contracting directly with telepsychiatry platforms, bypassing traditional primary care gatekeeping. This channel shift concentrates volume with formulary-managed digital-first providers rather than dispersed community prescribers.
ADHD Therapeutics Market Segmentation
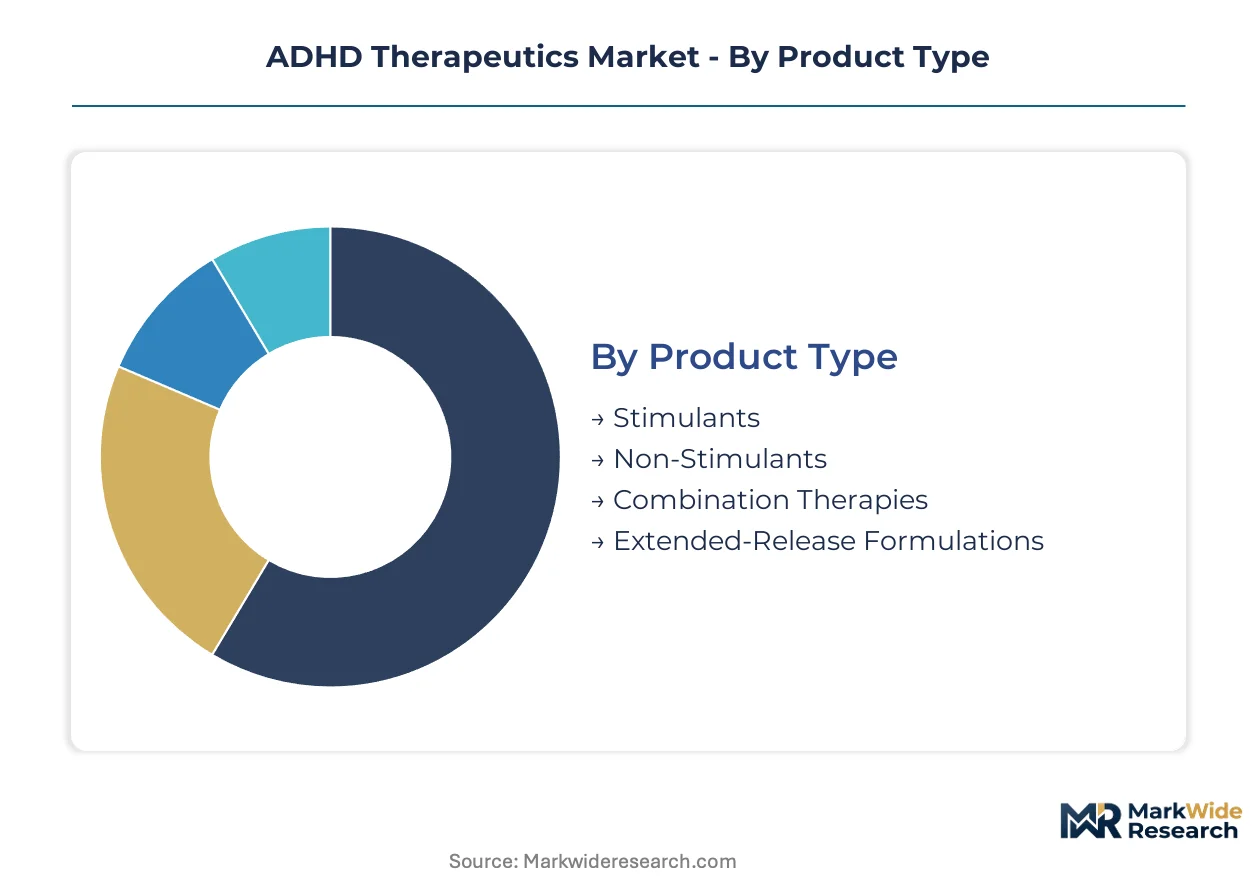
ADHD therapeutics segmentation reflects divergent regulatory pathways and reimbursement logic across molecular classes and delivery platforms. Manufacturers must align formulation investments with DEA scheduling tiers, FDA pediatric study requirements, and EMA pharmacovigilance obligations that vary sharply by segment.
Product Type:
DEA Schedule II classification burdens stimulant segments with production quotas and dual-lock distribution infrastructure, while non-stimulant alternatives navigate lighter FDA labeling but heavier cardiovascular risk documentation.
- Stimulants:Amphetamine and methylphenidate derivatives dominate prescription volume through decades of established efficacy data. Demand concentrates in the United States where adult diagnostic expansion outpaces pediatric growth, though DEA quota rigidity constrains supply response during demand surges.
- Non-Stimulants:Atomoxetine and guanfacine formulations bypass controlled-substance scheduling entirely, enabling electronic prescribing flexibility and reduced diversion monitoring costs. Prescribers in Germany and France increasingly initiate adult patients on these agents given EMA cardiovascular surveillance mandates for stimulant alternatives.
- Combination Therapies:Fixed-dose stimulant-adjunct pairings address partial responders.
- Extended-Release Formulations:Matrix dissolution technologies reduce midday dosing burden for workplace adherence.
Leading the category by volume: Stimulants. Growing fastest: Extended-Release Formulations.
Delivery Mode:
Cost stratification separates premium transdermal platforms from commoditized oral generics, with reimbursement tiers dictating prescriber selection patterns across employer-sponsored and Medicaid formularies.
- Oral Tablets:Immediate-release methylphenidate and mixed amphetamine salts face generic commoditization, compressing originator pricing power. Volume concentrates in Medicaid programs and cash-pay segments where cost minimization overrides adherence engineering.
- Transdermal Patches:Methylphenidate and rivastigmine patches bypass first-pass hepatic metabolism, improving gastrointestinal tolerability profiles. Takeda's portfolio demonstrates commercial viability for noradrenergic patch delivery, with fastest adoption among adult workplace populations seeking dosing discretion.
- Injectable Solutions:Long-acting intramuscular formulations serve non-adherent patients.
- Sublingual Sprays:Rapid-onset delivery addresses acute symptom breakthrough.
Highest reimbursement tier: Transdermal Patches. Deepest volume penetration: Oral Tablets.
Age Group:
Application-specific development obligations fragment clinical trial investment, with pediatric segments requiring EMA investigation plans and adult segments driving near-term revenue concentration.
- Pediatrics:Patients aged 6-12 years anchor historical prescribing patterns and school-based medication management programs. FDA pediatric exclusivity incentives and EMA investigation plan requirements extend development timelines, concentrating sponsor investment with established players possessing regulatory infrastructure.
- Adults:Previously undiagnosed cases aged 18-45 years represent the steepest expansion trajectory as psychiatric services reclassify inattentive presentations. United States telepsychiatry platforms and employer-sponsored mental health benefits are compressing diagnostic latency, redirecting volume from pediatric-focused community prescribers.
- Adolescents:Transition-age patients bridge pediatric and adult protocols.
- Geriatrics:Late-life diagnosis remains underpenetrated given cardiovascular contraindication prevalence.
Dominant revenue pool: Adults. Slowest regulatory pathway: Pediatrics.
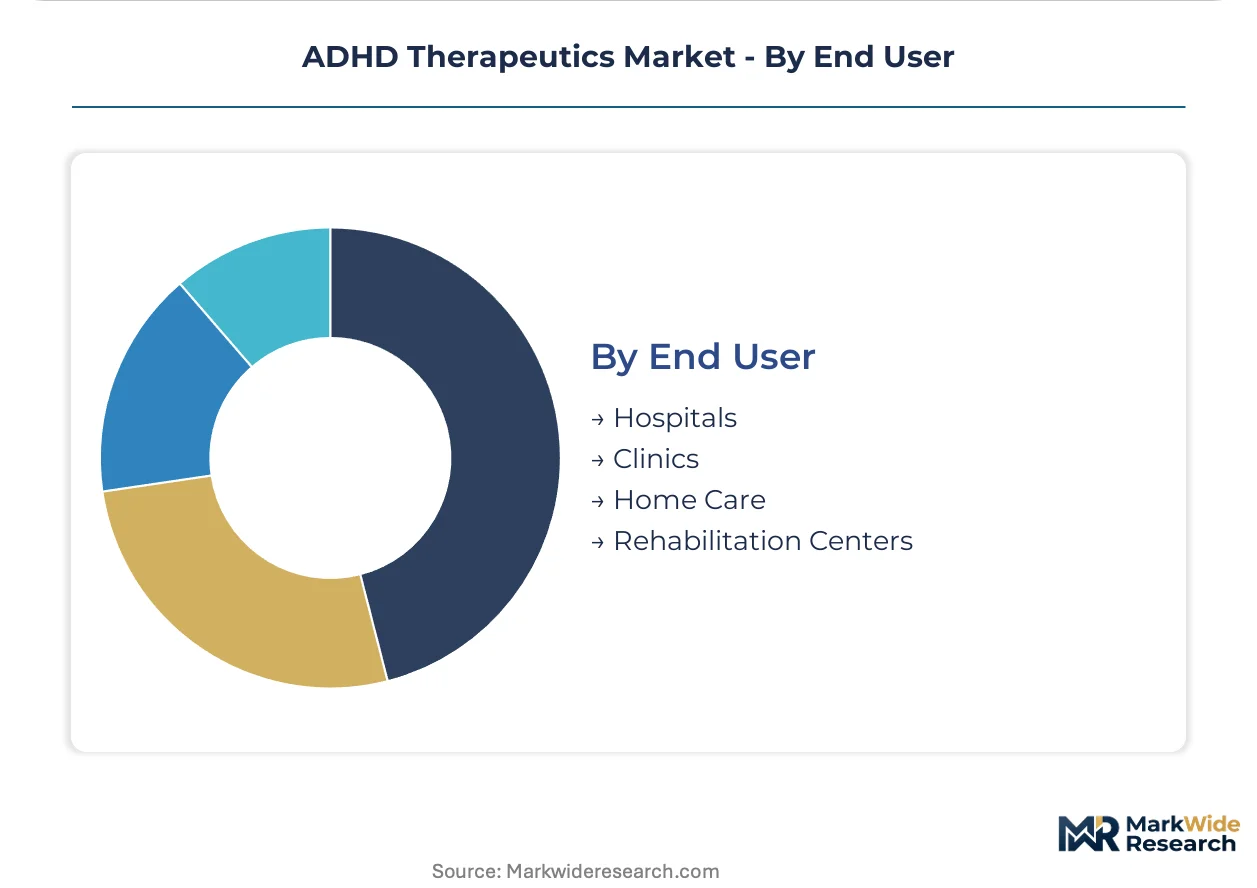
End User:
Customer-type concentration is reshaping distribution economics, with digital-first channels displacing traditional hospital-based initiation for stable maintenance patients.
- Hospitals:Academic medical centers and tertiary psychiatric facilities manage complex comorbid presentations requiring cardiology consultation and multi-agent titration. These settings concentrate prescriber training on novel mechanisms and extended-release formulation selection.
- Clinics:Pediatric psychiatry and adult ADHD specialty practices drive ongoing medication management volume. United States-based telepsychiatry platforms contracted by self-insured employers are capturing stable adult patients, bypassing traditional primary care gatekeeping.
- Home Care:Mail-order pharmacy and remote monitoring support maintenance therapy.
- Rehabilitation Centers:Substance use comorbidity programs utilize non-stimulant alternatives.
Fastest channel shift: Clinics. Highest acuity concentration: Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park zone in North Carolina concentrates clinical trial infrastructure for CNS drug development, attracting sponsor investment through state tax credits and FDA proximity. This incentive geography shapes where Phase III ADHD studies initiate and where regulatory consulting clusters form.
United States
Adult diagnostic expansion through employer-sponsored telepsychiatry platforms is redirecting prescription volume from pediatric-focused community prescribers. The FDA's updated controlled substance labeling requirements under the CSA are standardizing electronic prescribing mandates nationwide. Boston's academic medical corridor anchors complex comorbidity management programs requiring cardiology consultation for stimulant initiation.
Germany
EMA pediatric investigation plan compliance obligations are extending development timelines for sponsors seeking European approval. The Federal Institute for Drugs and Medical Devices enforces stricter risk-minimization measures for adult stimulant initiation protocols. The Rhine-Main cluster around Frankfurt concentrates pharmacovigilance reporting infrastructure for extended-release formulations.
Japan
PMDA's streamlined review pathways for pediatric psychiatric indications are accelerating market entry for novel non-stimulant mechanisms. METI's pharmaceutical innovation subsidies support transdermal delivery platform development. The Kansai region around Osaka hosts specialized CNS formulation manufacturing for Asia-Pacific distribution.
United Kingdom
NHS England's digital-first mental health service specifications are contracting directly with telepsychiatry platforms, bypassing traditional primary care gatekeeping. The MHRA's post-Brexit regulatory autonomy is diverging from EMA pediatric study requirements in timeline flexibility. London's research quarter concentrates health technology assessment submissions for novel ADHD therapeutics.
India
CDSCO's accelerated approval pathways for drugs with established US FDA or EMA clearance are compressing regulatory lag for imported extended-release formulations. The country's central bank maintains foreign investment caps in pharmaceutical retail that shape distribution economics. Hyderabad's active pharmaceutical ingredient corridor supplies methylphenidate intermediates to global formulation networks.
ADHD Therapeutics Market Vendor Landscape
Top-tier vendors anchor the extended-release and transdermal formulation segments, while mid-scale specialists occupy generic immediate-release niches and regional distribution channels. The competitive structure reflects DEA quota allocation patterns that favor established manufacturers with perpetual inventory infrastructure. Three archetypes dominate: originator pharmaceutical companies with transatlantic regulatory capabilities, mid-cap formulation specialists with DEA-registered facilities, and emerging digital therapeutic developers seeking FDA breakthrough designation. Capacity expansion and portfolio diversification toward non-stimulant delivery platforms represent the dominant competitive moves.
Within the originator tier, Takeda Pharmaceutical Company and Eli Lilly and Company exemplify the regulatory infrastructure archetype required for sustained DEA quota access and EMA pediatric investigation plan compliance. Novartis AG occupies a position representing European market anchoring through established extended-release formulation portfolios. These three companies collectively illustrate how transatlantic regulatory positioning separates sustainable competitors from quota-constrained challengers.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company |
| Novartis AG |
| Eli Lilly and Company |
| Johnson & Johnson |
| Pfizer |
| Supernus Pharmaceuticals |
| Tris Pharma |
| NEOS Therapeutics |
| Lupin |
| Others |
Supply Flow & Price Mechanics
Captive integration into DEA-registered manufacturing infrastructure anchors pricing power for established stimulant producers, while outsourcing API procurement to Indian and Chinese suppliers exposes mid-tier formulators to quota volatility and margin compression.
Pricing Analysis
Short lead-time premiums for Schedule II stimulants command substantial markups over contract-scheduled volumes, reflecting DEA quota allocation rigidities. Three-tier pricing structure across extended-release, transdermal, and immediate-release oral tiers separates premium adherence-engineered formulations from commoditized generics. Cost compression in immediate-release methylphenidate intensifies because of patent expiration and multi-source generic entry. Medicaid programs exhibit highest price sensitivity, while self-insured employer plans demonstrate lowest sensitivity for novel non-stimulant delivery platforms.
Supply Chain Analysis
Dual-sourcing requirements for amphetamine and methylphenidate active pharmaceutical ingredients mandate qualification of both domestic and overseas API manufacturers. Supply concentration centers on India for methylphenidate intermediates, China for specialty chemical precursors, and the United States for finished dosage formulation. Raw material dependencies include controlled-substance precursors, extended-release matrix polymers, and transdermal adhesive substrates. Single-source vulnerability from DEA quota allocation decisions represents the dominant structural risk. Distribution runs through DEA-registered wholesale distributors with perpetual inventory tracking to retail pharmacy and mail-order channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ADHD therapeutics market operates as a cost-of-compliance story where DEA controlled-substance scheduling erects formidable barrier-to-entry moats favoring manufacturers with perpetual inventory infrastructure and quota allocation history.
For Market Incumbents: Deploy transdermal delivery platform expansion to defend against digital therapeutic substitutes encroaching on cognitive behavioral intervention slots. Consolidate DEA quota access through backward integration into API manufacturing and dual-lock facility certification upgrades. Capacity addition in Research Triangle Park clinical trial infrastructure reinforces transatlantic regulatory positioning against EMA pediatric investigation plan requirements. For New Entrants and Emerging Players: Enter via non-stimulant transdermal white space in adult workplace populations seeking dosing discretion outside controlled-substance protocols. Target employer-sponsored telepsychiatry channels contracted by self-insured plans for fastest formulary access. White-space concentration in geriatric late-life diagnosis segments offers penetrable entry with cardiovascular risk-tailored positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of mid-cap formulation specialists possessing DEA-registered facilities and established quota relationships. Long-term viability hinges on transatlantic regulatory infrastructure capable of simultaneous FDA and EMA submission navigation. Watch DEA production quota expansion decisions as inflection indicator for supply-constrained stimulant segment revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Platform Expansion | Takeda's patch portfolio demonstrates noradrenergic agent feasibility for adult workplace adherence. |
| DEA Manufacturing Facility Certification | Dual-lock storage and perpetual inventory infrastructure separates quota-eligible producers from challengers. |
| EMA Pediatric Investigation Plan Alignment | European development obligations accelerate transatlantic regulatory positioning for extended-release formulations. |
| Digital Therapeutic Adjacency Investment | FDA breakthrough-designation candidates for cognitive behavioral apps compete for prescriber reimbursement slots. |
| Telepsychiatry Channel Partnership | Self-insured employer contracts bypass traditional primary care gatekeeping for adult diagnostic volume. |
Methodological Framework
Multi-period observation of DEA quota allocation patterns, FDA approval timelines, and EMA pediatric investigation plan completion rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from FDA controlled-substance scheduling filings, EMA submission databases, ClinicalTrials.gov enrollment data, and hospital procurement records. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation cross-checked segment-level estimates.
Input-output matrices mapped stimulant and non-stimulant demand drivers across product type, delivery mode, age group, and end-user segmentation dimensions over the projection horizon. CAGRs were derived from iterative convergence of patient population forecasts, diagnosis rate trends, and pricing elasticity assumptions. Forecast inputs incorporated DEA production quota trajectories, cardiovascular contraindication screening protocol adoption, and employer-sponsored mental health benefit expansion rates.
Revisions become necessary when DEA quota expansion decisions, FDA scheduling reclassification, or EMA pharmacovigilance enforcement shifts materialize. Forecasts reflect documented assumptions regarding diagnostic expansion sustainability and telepsychiatry channel penetration. Deviation in controlled-substance regulatory stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Global Brain Tumor Therapeutics Market