
 Ulcerated Necrobiosis Lipoidica Management Market | 2026-2036
Ulcerated Necrobiosis Lipoidica Management Market Size, Share, and Industry Trends Forecast 2026-2036
Ulcerated Necrobiosis Lipoidica Management Market Analytics
Modular therapy kits that combine topical steroids with antimicrobial coverage are decoupling traditional single-agent prescribing patterns in ulcerated necrobiosis lipoidica care. Johnson & Johnson leverages its dermatology portfolio breadth to anchor hospital formulary positioning across wound management suites. AbbVie sustains R&D intensity in immunomodulator pathways relevant to granulomatous skin disorders. Pfizer competes through manufacturing scale that supports reliable supply of systemic corticosteroid formulations used in refractory cases.
Ulcerated necrobiosis lipoidica management encompasses pharmacologic and procedural interventions targeting painful, ulcerated plaques arising from degenerative collagen disorders in the dermis, typically involving intralesional corticosteroid injection at concentrations of 10-40 mg/mL triamcinolone to achieve granulation tissue formation and wound closure. The primary purpose centers on preventing secondary infection, managing exudative drainage, and halting progressive tissue destruction in lower-extremity lesions. Biologics within the product type dimension command premium positioning as pipeline agents target TNF-alpha and IL-17 pathways in recalcitrant presentations. Combination therapy approaches across the treatment approach dimension are gaining fastest traction as clinicians sequence phototherapy with immunomodulators to reduce corticosteroid burden.
FDA oversight of dermatologic biologics through the Center for Drug Evaluation and Research shapes clinical trial design and labeling requirements for ulcerated necrobiosis lipoidica indications, while EMA's Committee for Medicinal Products for Human Use influences parallel European development strategies through centralized assessment of rare disease therapies. ISO 13485 standards for medical device quality management systems govern wound care adjunct products used alongside pharmacologic management in homecare settings. Stakeholders must monitor how evolving FDA guidance on real-world evidence collection for rare dermatologic conditions reshapes post-market study obligations and payer negotiation leverage.
Market Dynamics
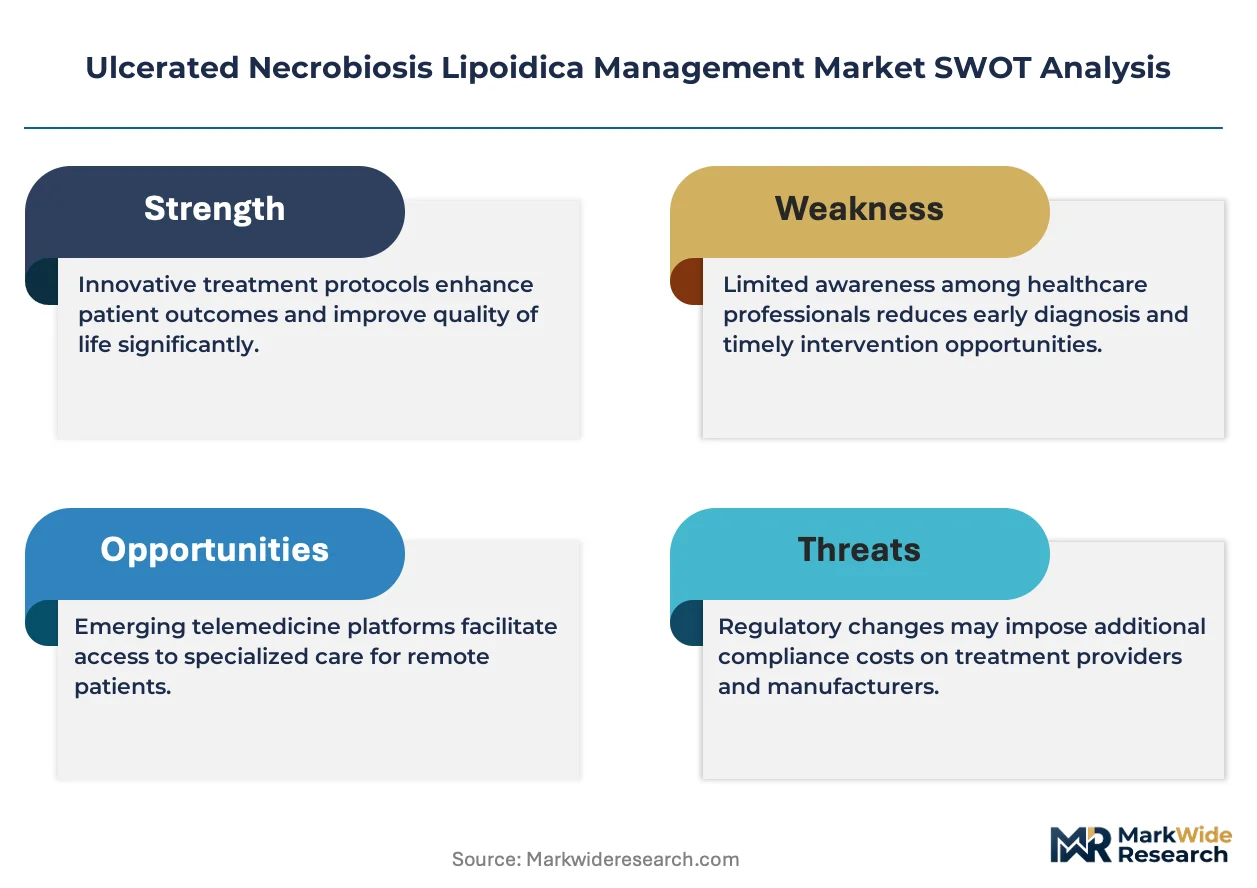
The FDA's orphan drug designation pathway is restructuring biologic development economics for rare dermatologic conditions, compressing trial timelines and amplifying reimbursement leverage for ulcerated necrobiosis lipoidica therapies.
Growth Catalysts
- Specialized wound care infrastructure:The United States maintains advanced reimbursement frameworks that accelerate advanced therapy uptake in dermatology clinics and hospital outpatient departments.
- EMA centralized assessment pathways:European rare disease therapy designations streamline cross-border market access for immunomodulator developers targeting granulomatous skin disorders.
- Phototherapy-immunomodulator sequencing:Combination protocols that reduce corticosteroid burden are gaining protocol adoption across academic medical centers.
Market Restraints
- Trial recruitment limitations:Small patient populations for ulcerated necrobiosis lipoidica extend clinical development timelines and inflate per-patient study costs.
- Reimbursement heterogeneity:Payer coverage for biologics in dermatology varies substantially across national health systems, creating access fragmentation.
- Topical corticosteroid substitution:Generic triamcinolone formulations commoditize first-line therapy and compress margins for novel agents.
Strategic Opportunities
- Homecare wound management:ISO 13485-certified medical device adjuncts for exudative lesion care address the shift toward ambulatory treatment settings.
- Real-world evidence collection:Evolving FDA guidance on post-market study design creates negotiation leverage with payers for biologic therapies.
- TNF-alpha pathway expansion:Pipeline agents targeting IL-17 and TNF-alpha cytokines open addressable space in refractory presentations.
Industry Challenges
- Dermatopathology specialization gaps:Accurate diagnosis of ulcerated necrobiosis lipoidica requires expertise in granulomatous disorders that concentrates in tertiary referral centers.
- Biologic cold chain logistics:Temperature-controlled distribution for injectable immunomodulators complicates inventory management in outpatient dermatology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ulcerated Necrobiosis Lipoidica Management Market |
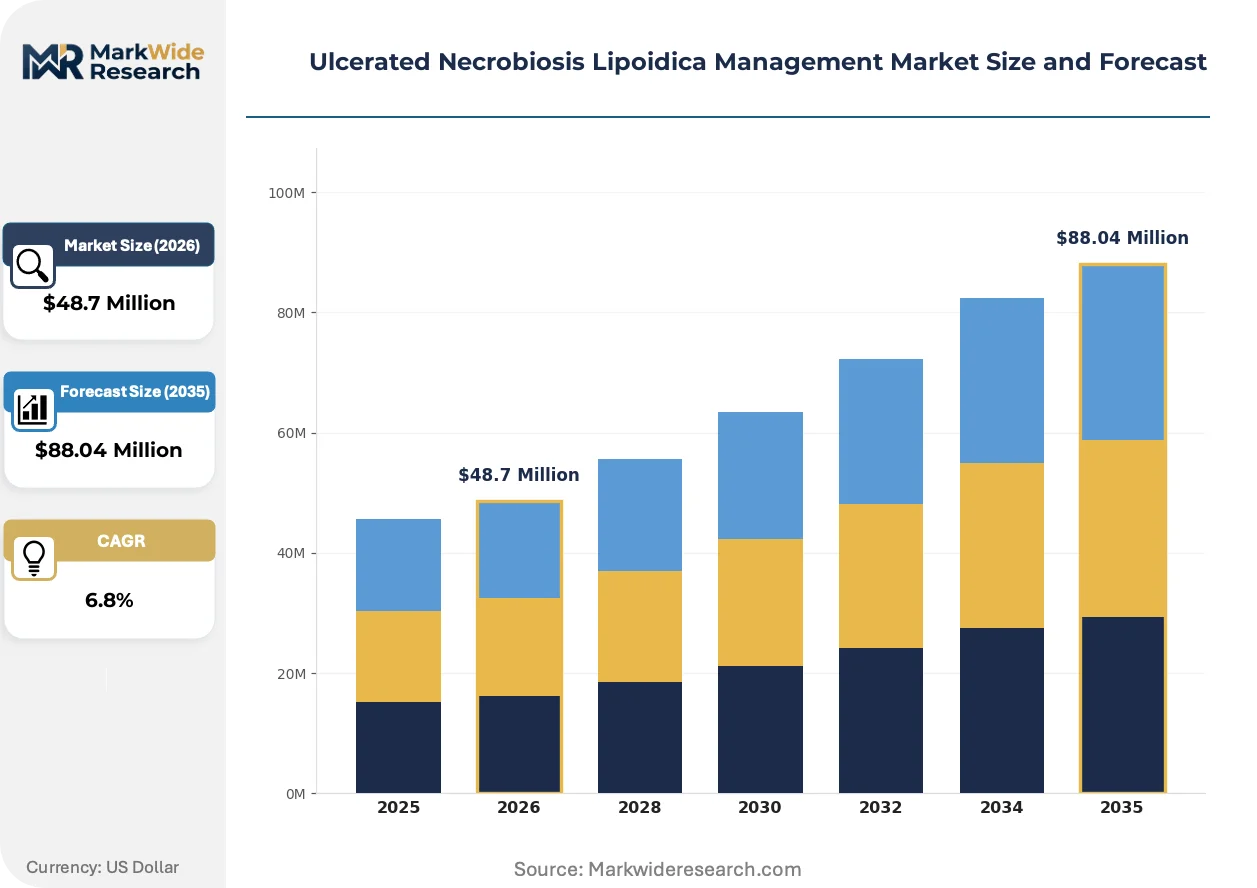
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Steroids, Immunomodulators, Antimicrobials, Biologics Delivery Mode: Intralesional, Systemic, Topical, Oral End User: Hospitals, Dermatology Clinics, Homecare Settings, Research Institutions Treatment Approach: Conservative Care, Surgical Intervention, Phototherapy, Combination Therapy |
| Companies Covered | Processa Pharmaceuticals, Ocuphire Pharma, Johnson & Johnson, AbbVie, Pfizer, Sanofi, Novartis, GlaxoSmithKline, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ulcerated Necrobiosis Lipoidica Management Market Evolving Landscape
Modular therapy platforms are displacing single-agent prescribing conventions across ulcerated necrobiosis lipoidica management, with technology convergence and regulatory adaptation reshaping competitive positioning.
Intralesional corticosteroid delivery systems are converging with antimicrobial coverage modules in integrated wound care kits. Dermatology clinics in academic medical centers are adopting these platforms at accelerated rates compared to community settings. The technology is converging with digital wound monitoring tools to enable remote assessment of granulation tissue progression.
EMA's Committee for Medicinal Products for Human Use has tightened evidentiary standards for rare dermatology indications, requiring adaptive trial designs with biomarker endpoints. This policy shift extends development timelines for biologics targeting TNF-alpha pathways. European sponsors are responding by front-loading health technology assessment submissions to parallel regulatory reviews.
After-sales service unbundling is separating wound care education from product supply in homecare settings. Patients and caregivers now purchase training modules independently from dressing materials and pharmacologic agents. The United States exhibits the most pronounced shift, where specialized wound care nurses deliver protocol education through telehealth platforms rather than device manufacturers.
Ulcerated Necrobiosis Lipoidica Management Market Segmentation
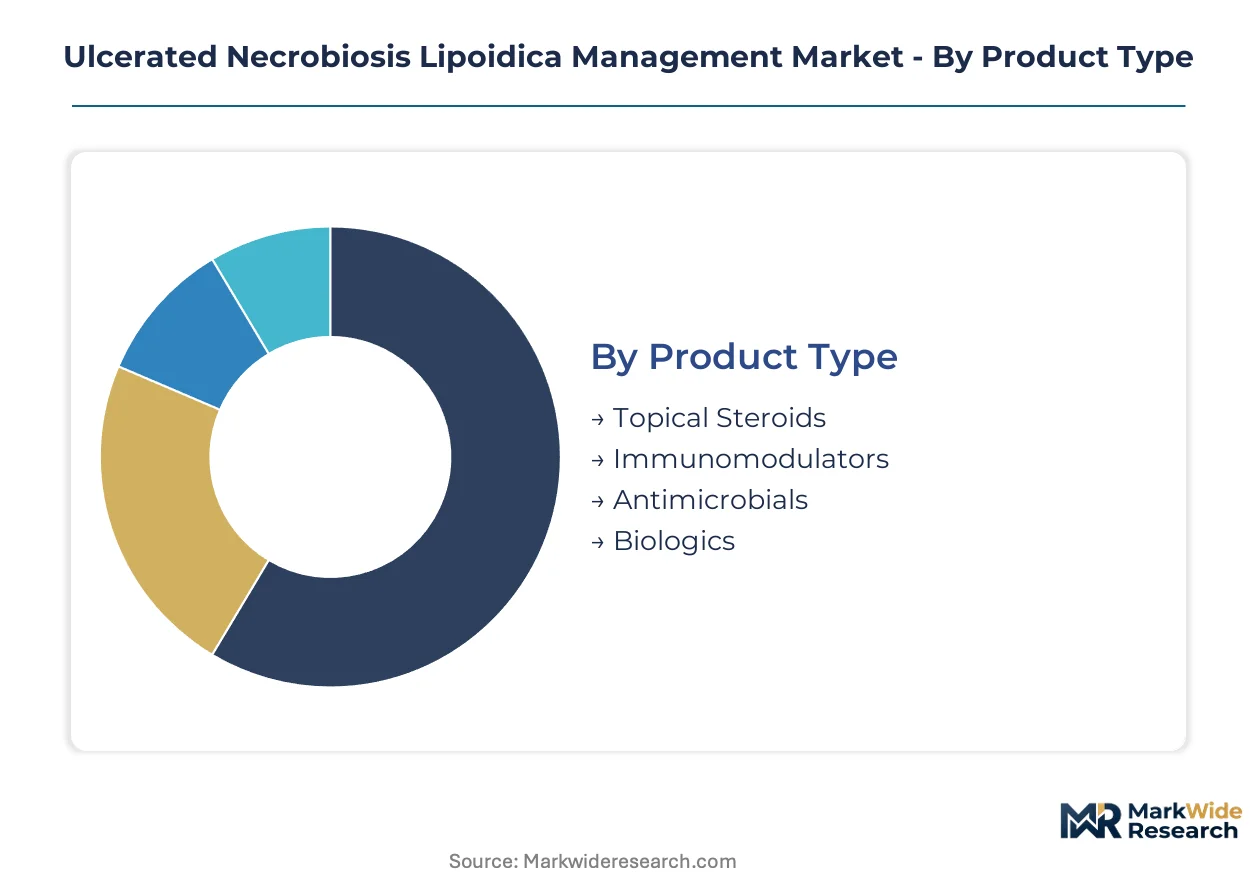
Ulcerated necrobiosis lipoidica management requires precise patient stratification to match lesion severity with appropriate intervention intensity. Treatment protocols differ substantially between ambulatory wound care and acute surgical settings, driving distinct procurement patterns across delivery channels.
Product Type:
Clinicians rotate through therapeutic classes based on ulcer depth, infection status, and prior corticosteroid exposure, creating natural upgrade pathways from topical agents to systemic and biologic alternatives.
- Biologics:Engineered monoclonal antibodies targeting TNF-alpha and IL-17 cytokine pathways demonstrate efficacy in refractory granulomatous presentations. Academic medical centers in the United States concentrate demand for these agents, driven by FDA orphan drug designation incentives that compress development timelines and amplify reimbursement negotiation leverage for rare dermatologic indications.
- Topical Steroids:Corticosteroid formulations at 10-40 mg/mL triamcinolone concentrations remain first-line for superficial ulcerated plaques without secondary infection. Generic substitution pressures commoditize this segment, compressing margins while sustaining high prescription volumes in community dermatology practices.
- Immunomodulators:Calcineurin inhibitors and JAK pathway modulators serve as steroid-sparing alternatives for patients with corticosteroid intolerance.
- Antimicrobials:Topical and systemic antimicrobial coverage addresses secondary bacterial colonization in exudative lesions.
Volume placements concentrate in topical steroids; the faster expansion belongs to biologics.
Delivery Mode:
Route selection depends on lesion distribution, patient compliance capacity, and required tissue penetration depth, with intralesional methods commanding premium positioning for localized recalcitrant plaques.
- Intralesional:Direct corticosteroid injection into ulcerated plaques achieves targeted granulation tissue formation with minimal systemic exposure. Dermatology clinics favor this modality for lower-extremity lesions, supported by reimbursement frameworks that recognize procedural complexity in specialized wound care settings.
- Topical:Cream, ointment, and gel formulations enable patient self-administration for maintenance therapy following procedural intervention. Homecare settings drive sustained demand, particularly where telehealth wound monitoring platforms facilitate remote assessment of treatment response.
- Systemic:Oral or parenteral corticosteroid distribution addresses widespread or rapidly progressive disease.
- Oral:Tablet formulations support chronic immunomodulation in patients with recurrent ulceration patterns.
Procedure volumes favor intralesional delivery; oral administration is climbing the fastest as maintenance protocols extend beyond acute care episodes.
End User:
Site-of-care migration from inpatient to ambulatory settings reshapes purchasing authority, with dermatology clinics gaining formulary influence at the expense of hospital pharmacy committees.
- Dermatology Clinics:Specialized outpatient facilities concentrate expertise in granulomatous skin disorder diagnosis and intralesional technique. The United States exhibits the most pronounced channel shift, where advanced reimbursement frameworks accelerate adoption of combination therapy protocols and biologic agents in academic and community dermatology practices.
- Homecare Settings:Patients and caregivers manage wound dressing changes, topical applications, and digital monitoring through remote platforms. ISO 13485-certified medical device adjuncts for exudative lesion care address this channel's expansion, with after-sales service unbundling separating education from product supply.
- Hospitals:Inpatient and emergency departments handle acute secondary infection and surgical debridement.
- Research Institutions:Academic centers conduct adaptive clinical trials with biomarker endpoints for pipeline biologics.
Patient volumes concentrate in dermatology clinics; homecare settings are gaining share fastest as ambulatory treatment protocols mature.
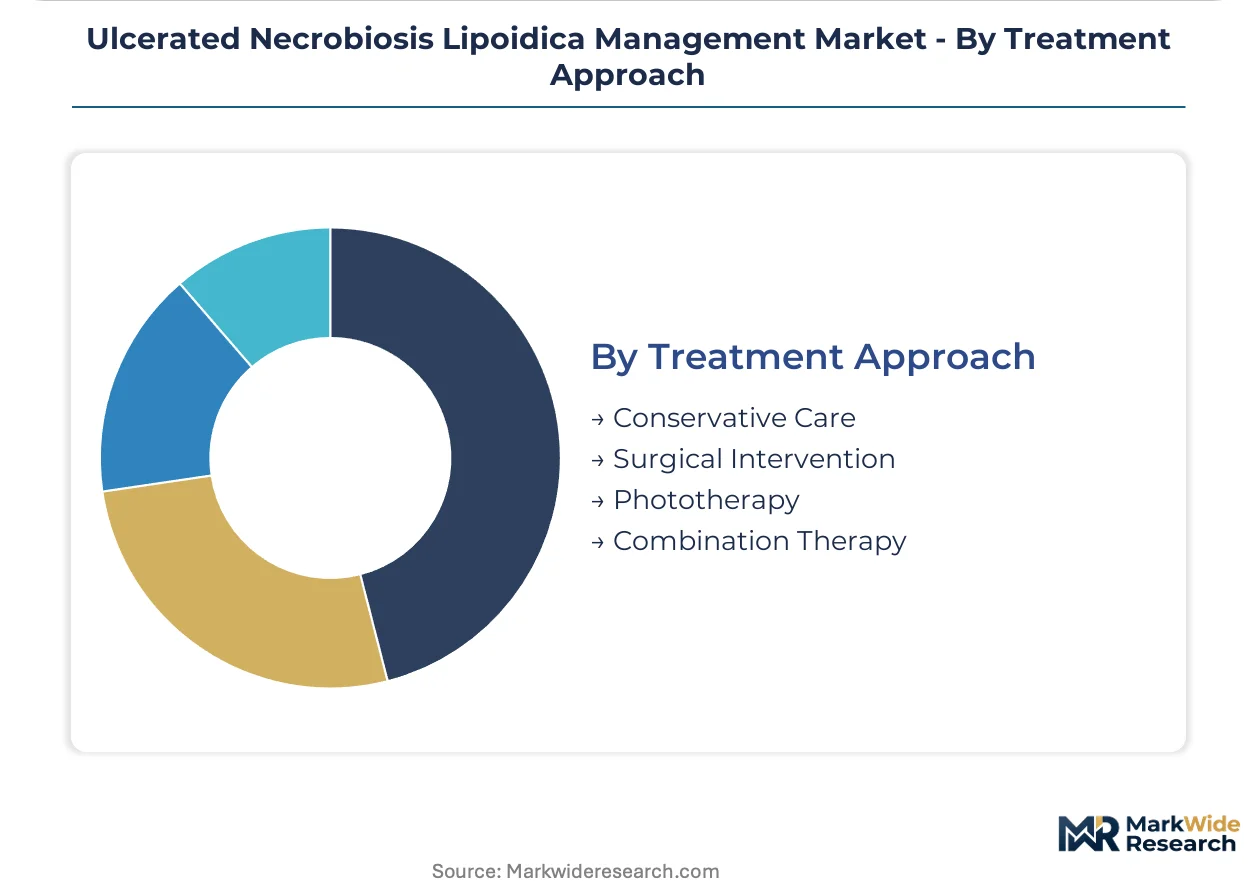
Treatment Approach:
Sequencing strategies that layer modalities to reduce corticosteroid exposure are displacing single-agent prescribing conventions across ulcerated necrobiosis lipoidica management.
- Combination Therapy:Phototherapy-immunomodulator sequencing reduces corticosteroid burden while maintaining disease control. Academic medical centers pioneered these protocols, with EMA centralized assessment pathways for rare disease therapies streamlining cross-border adoption of validated combination regimens in European dermatology networks.
- Phototherapy:Ultraviolet light modalities target inflammatory pathways in superficial ulcerated plaques. Dermatology clinics integrate these systems with digital wound monitoring tools to enable remote assessment of granulation tissue progression.
- Conservative Care:Topical and supportive measures address early-stage or limited disease.
- Surgical Intervention:Debridement and grafting procedures manage extensive tissue destruction.
Procedure counts concentrate in conservative care; combination therapy shows the steepest expansion trajectory as clinicians seek steroid-sparing alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for biomedical research in the United States, Germany, and Switzerland concentrate orphan drug development infrastructure for rare dermatologic conditions. These jurisdictions leverage targeted tax incentives and accelerated regulatory pathways to anchor biologic manufacturing and clinical trial operations.
United States
FDA orphan drug designations compress development timelines for ulcerated necrobiosis lipoidica therapies while Medicare reimbursement frameworks support advanced wound care uptake in dermatology clinics. The 21st Century Cures Act provisions streamline real-world evidence collection for rare disease indications. Boston-Cambridge anchors biologic R&D clusters where academic medical centers pilot phototherapy-immunomodulator combination protocols.
Germany
EMA centralized assessment pathways enable cross-border market access for immunomodulator developers targeting granulomatous skin disorders. The country's statutory health insurance system maintains consistent coverage for biologic therapies in dermatology. Baden-Württemberg concentrates medical device manufacturing for ISO 13485-certified wound care adjuncts serving homecare channels.
Switzerland
Swissmedic's alignment with EMA standards accelerates parallel European development strategies for pipeline TNF-alpha pathway agents. Federal innovation incentives support precision medicine initiatives in rare dermatology. Basel anchors pharmaceutical headquarters where immunomodulator portfolios target refractory inflammatory conditions.
United Kingdom
NICE technology appraisals shape reimbursement negotiations for biologics in specialized wound care settings. The NHS England commissioning framework concentrates ulcerated necrobiosis lipoidica expertise in tertiary referral centers. London-Oxford-Cambridge corridor hosts adaptive clinical trial units with biomarker endpoint capabilities for rare disease therapies.
Japan
PMDA's sakigake designation system provides priority review for orphan dermatologic indications with unmet medical needs. The aging demographic expands demand for ambulatory wound management solutions. Tokyo-Osaka corridor concentrates dermatology clinic networks adopting digital wound monitoring platforms for remote patient assessment.
Ulcerated Necrobiosis Lipoidica Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the ulcerated necrobiosis lipoidica management landscape, creating a tiered structure where portfolio breadth anchors hospital formulary positioning against targeted immunomodulator development. The market exhibits moderate consolidation among large-cap pharmaceutical manufacturers with dermatology divisions, while mid-cap biotech developers concentrate on cytokine pathway innovation. Strategic archetypes include diversified wound care conglomerates, immunology-focused biopharmaceutical firms, and rare disease pure-plays. Dominant competitive moves encompass portfolio diversification into modular therapy platforms and strategic partnerships to secure real-world evidence generation capabilities.
Within the diversified pharmaceutical tier, Johnson & Johnson, AbbVie, and Pfizer exemplify contrasting strategic postures. Johnson & Johnson occupies a position anchored by wound care portfolio breadth spanning medical devices and pharmaceuticals. AbbVie exemplifies the immunology-specialized archetype with sustained R&D intensity in granulomatous disorder pathways. Pfizer represents scale-driven manufacturing capabilities supporting reliable supply of systemic formulations. These three entities collectively illustrate how competitive positioning derives from divergent resource allocation across research intensity, manufacturing scale, and portfolio integration rather than uniform strategic convergence.
| Leading Market Players |
|---|
| Processa Pharmaceuticals |
| Ocuphire Pharma |
| Johnson & Johnson |
| AbbVie |
| Pfizer |
| Sanofi |
| Novartis |
| GlaxoSmithKline |
| Amgen |
| Others |
Value Network & Pricing Analysis
Cold chain logistics costs for biologic immunomodulators cascade through distribution tiers, compressing margins at the dermatology clinic level while amplifying price premiums for TNF-alpha pathway agents in academic medical centers.
Pricing Analysis
Margin tightening in topical steroid tiers reflects generic triamcinolone substitution pressures that commoditize first-line therapy. Three-tier pricing structure across premium biologics, standard immunomodulators, and economy topical formulations separates reimbursement-eligible hospital outpatient departments from cash-pay homecare channels. Cost-down pressure on antimicrobial adjuncts accelerates because ISO 13485-certified device manufacturers unbundle education from product supply. Community dermatology practices exhibit highest price sensitivity; academic medical centers with orphan drug designation access show lowest.
Supply Chain Analysis
Regional distribution centers in Basel, Boston-Cambridge, and Baden-Württemberg anchor hub-and-spoke patterns for temperature-controlled biologic distribution. Active pharmaceutical ingredient synthesis draws from Switzerland, Germany, and the United States for corticosteroid precursors. Single-source vulnerability concentrates in cold chain logistics providers serving outpatient dermatology practices. Distribution runs through specialized pharmaceutical wholesalers with rare disease therapy handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phototherapy-immunomodulator sequencing protocols are displacing corticosteroid monotherapy as the clinical standard in ulcerated necrobiosis lipoidica management.
For Market Incumbents: Hedge against generic erosion in topical steroid portfolios by deepening backward integration into corticosteroid API manufacturing in Germany. Anchor hospital formulary positioning through bundled wound care kits that combine intralesional delivery systems with antimicrobial coverage modules. Certification investment in ISO 13485 quality management systems secures homecare channel access against emerging device competitors. For New Entrants and Emerging Players: Rural dermatology clinics with limited granulomatous disorder expertise represent the most penetrable buyer archetype for telehealth-enabled wound monitoring platforms. White-space targets include homecare settings where after-sales service unbundling separates education from product supply, and European markets where EMA centralized assessment pathways streamline cross-border adoption. A direct-to-clinic digital companion go-to-market angle bypasses entrenched hospital pharmacy committees. For Investors and Strategic Acquirers: FDA orphan drug designation awards for TNF-alpha pathway agents are the leading indicator that reimbursement leverage and development timeline compression will concentrate value in rare dermatology biotechs. Long-term viability over the next decade hinges on real-world evidence generation capabilities that satisfy evolving post-market study obligations. Acquisition target archetypes include mid-cap immunomodulator developers with adaptive trial infrastructure. Monitor EMA biomarker endpoint guidance tightening as the inflection signal for European development cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA pathway compression accelerates biologic development timelines for rare dermatologic indications. |
| Modular Therapy Platform Launch | Integrated wound care kits displace single-agent prescribing in dermatology clinic formularies. |
| Real-World Evidence Infrastructure | Post-market study capabilities amplify payer negotiation leverage for biologic therapies. |
| Cold Chain Distribution Partnership | Temperature-controlled logistics networks extend biologic reach to community dermatology practices. |
| Telehealth Wound Monitoring Integration | Digital granulation tissue assessment platforms enable remote patient management in homecare settings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with dermatology clinic directors, hospital formulary managers, wound care nurses, and biologic supply chain specialists. FDA orphan drug designation databases, EMA centralized assessment records, ClinicalTrials.gov entries, and ISO 13485 certification registries provided structured secondary validation. Bottom-up patient volume estimates across delivery channels triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Granularity-level modeling operated at the treatment approach-by-end-user intersection, with combination therapy protocols, phototherapy systems, and conservative care modalities tracked separately across dermatology clinics, homecare settings, hospitals, and research institutions. CAGRs were derived from segmented growth rate analysis across the projection horizon. Forecast inputs incorporated FDA guidance evolution on real-world evidence collection and EMA evidentiary standard tightening for rare dermatology indications.
Revisions become necessary when regulatory guidance on post-market study design shifts materially, orphan drug designation criteria expand or contract, or reimbursement frameworks for biologic wound care therapies undergo structural reform. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Global Occupational Medicines Market