
 Geographic Atrophy Market | 2026-2036
Geographic Atrophy Market Size, Share, and Industry Trends Forecast 2026-2036
Geographic Atrophy Market Intelligence
Patient access is pivoting toward consolidated retinal specialty networks as hospital systems acquire independent ophthalmology practices across the United States and Western Europe. Roche leverages its diagnostics-to-therapeutics infrastructure to anchor geographic atrophy portfolios in integrated care pathways. Apellis Pharmaceuticals competes through complement C3 inhibition specialization, while Novartis controls anti-VEGF legacy positioning that extends into adjacent retinal disease markets.
Geographic atrophy denotes the progressive, irreversible loss of retinal pigment epithelium and photoreceptors in the macula, characterized by sharply demarcated lesions exceeding 175 microns in diameter with visible choroidal vessels, ultimately destroying central vision in advanced age-related macular degeneration. Its primary commercial purpose centers on halting lesion expansion through targeted pharmacologic intervention rather than restoration of lost tissue. Anti-VEGF and complement inhibitor segments lead current revenue pools where intravitreal injection protocols dominate clinical practice, while gene therapy approaches represent the fastest-growing development category despite manufacturing complexity that constrains near-term margin expansion. Ophthalmology clinics capture disproportionate procedure volume compared to hospital outpatient departments due to specialized imaging infrastructure and streamlined patient throughput.
FDA breakthrough therapy designations and EMA PRIME eligibility frameworks compress development timelines for novel geographic atrophy therapies, directly shaping trial endpoint standards and post-market surveillance obligations that manufacturers must navigate. The EU AI Act and FDA software-as-medical-device guidance increasingly govern automated lesion segmentation tools used in diagnosis and progression monitoring. Stakeholders must monitor complement pathway biomarker stratification as payer organizations integrate predictive response criteria into coverage determinations.
Market Dynamics
Complement pathway inhibition is consolidating clinical protocols across retinal specialty networks, compressing development timelines and reshaping how manufacturers align diagnostic infrastructure with therapeutic delivery.
Growth Catalysts
- EMA PRIME Eligibility:Accelerated assessment frameworks compress regulatory review periods for novel geographic atrophy therapies entering European markets.
- Intravitreal Injection Infrastructure:Retinal specialty clinics in the United States and Germany deploy standardized imaging-to-treatment workflows that streamline patient throughput.
- Gene Therapy Manufacturing:Viral vector production scale-up is expanding capacity for next-generation interventions targeting complement regulatory proteins.
Market Restraints
- Biologics Cold Chain Complexity:Temperature-sensitive complement inhibitors require specialized logistics infrastructure that limits distribution reach.
- Reimbursement Uncertainty:Payer organizations in Japan apply step-therapy protocols that delay first-in-class therapy access.
- Retinal Specialist Scarcity:Fellowship-trained ophthalmologists concentrate in urban academic medical centers, constraining rural treatment capacity.
Strategic Opportunities
- AI-Assisted Lesion Segmentation:Automated progression monitoring tools create new service revenue streams within integrated eye care networks.
- Biosimilar Pathways:EMA and FDA guidance frameworks open development corridors for follow-on complement inhibitors.
- India's Specialty Clinic Expansion:Metro hospital systems in Mumbai and Delhi acquire independent retinal practices, creating concentrated demand pools.
Industry Challenges
- Intravitreal Injection Training Bottlenecks:Certification requirements for safe anti-VEGF and complement inhibitor administration limit provider pool expansion.
- Diagnostic Imaging Integration:OCT-A and fundus autofluorescence systems require capital investment that smaller ophthalmology groups struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geographic Atrophy Market |
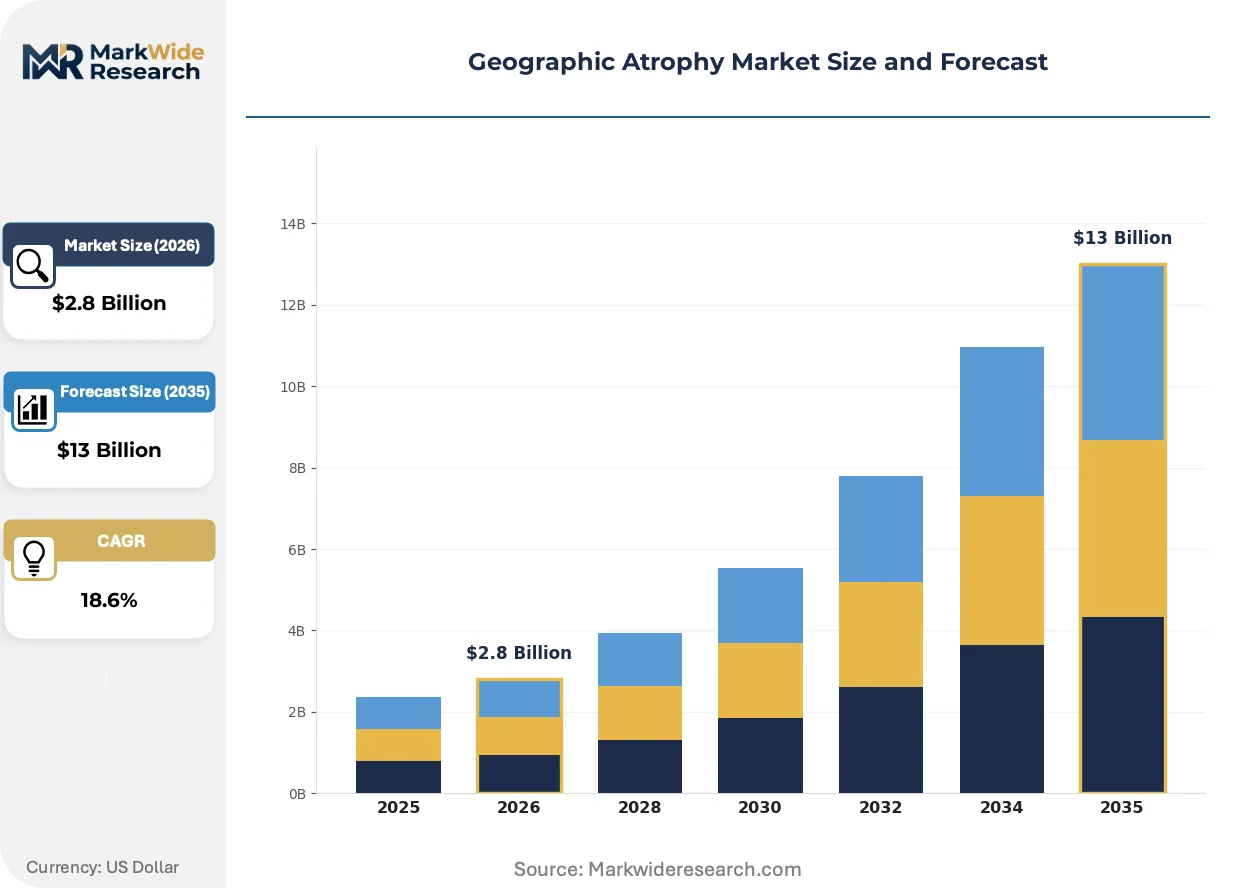
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Anti-VEGF, Corticosteroids, Nutritional Supplements End User: Ophthalmology Clinics, Hospitals, Homecare Settings, Research Laboratories Technology: Laser Therapy, Gene Therapy, Microneedling, Photodynamic Therapy Treatment Stage: Early Intervention, Advanced Stage, Preventive Care, Palliative Care |
| Companies Covered | Roche, Astellas Pharma, Apellis Pharmaceuticals, Allegro Ophthalmics, Stealth BioTherapeutics, Iveric Bio, Novartis, Hemera Biosciences, Alkeus Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geographic Atrophy Market Strategic Shifts & Innovations
Automated diagnostic platforms and sustained-release delivery mechanisms are compressing treatment burdens while regulatory frameworks accelerate novel mechanism approvals.
Extended-release intravitreal implants are consolidating maintenance protocols for geographic atrophy patients. Retinal specialty networks in Germany and the United States adopt these depot formulations to reduce injection frequency. The technology is consolidating patient retention within high-volume clinic systems that can manage complex implant logistics.
FDA breakthrough therapy designation pathways compress Phase III endpoint requirements for complement inhibitors targeting geographic atrophy progression. Manufacturers navigate accelerated approval contingent on post-market confirmatory trials. Retinal biologics with novel C3 or C5 mechanisms face heightened scrutiny in the United States compared to standard anti-VEGF review timelines.
Consolidated procurement by hospital-owned ophthalmology networks is displacing independent practice purchasing patterns. Integrated delivery systems in Japan and the United States negotiate formulary placement directly with manufacturers. This concentration is most visible in metropolitan markets where specialty clinic acquisition activity has accelerated since 2023.
Geographic Atrophy Market Segmentation
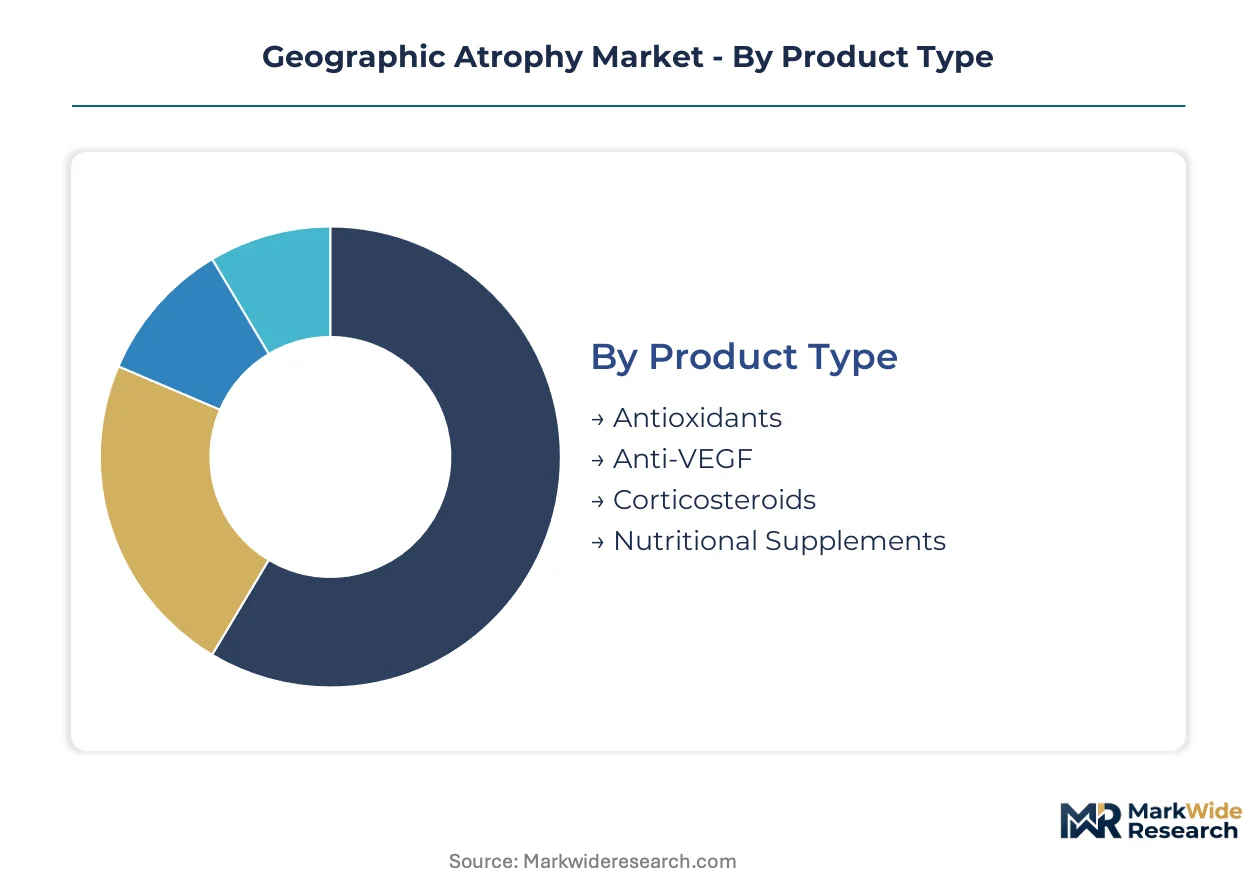
Segmentation in geographic atrophy reveals how therapeutic modalities, delivery settings, and intervention timing create distinct commercial ecosystems. Manufacturers must align pipeline investments with where patient volume concentrates versus where premium pricing persists.
Product Type:
Anti-VEGF commands volume leadership through established intravitreal protocols, while complement inhibitors capture premium positioning through first-in-class mechanism differentiation.
- Anti-VEGF:Intravitreal ranibizumab and aflibercept formulations dominate procedural volume across United States retinal networks. Medicare reimbursement stability and decades of safety data sustain preference despite limited efficacy in pure atrophy progression.
- Corticosteroids:Sustained-release dexamethasone implants address inflammatory components in mixed pathology presentations. Germany's statutory health insurance funds restrict coverage to combination therapy scenarios, constraining standalone adoption.
- Antioxidants:AREDS2 formulation derivatives occupy over-the-counter positioning with limited prescriptive authority.
- Nutritional Supplements:Lutein-zeaxanthin combinations target patient self-pay segments outside formal treatment pathways.
Today's leader: Anti-VEGF. Tomorrow's challenger: Corticosteroids.
End User:
Care setting determines reimbursement capture, with consolidated networks extracting superior economics compared to fragmented independent practice.
- Ophthalmology Clinics:Retinal specialty networks in the United States deploy integrated imaging-to-injection workflows that compress visit duration. Acquisition of independent practices by hospital systems since 2023 has concentrated procedure volume within fewer corporate entities.
- Hospitals:Academic medical centers in Japan manage complex cases requiring multimodal imaging coordination. PMDA reimbursement protocols favor inpatient designation for combination therapy administration, sustaining higher per-procedure yields.
- Homecare Settings:Self-administered supplement protocols dominate this channel with minimal prescriptive oversight.
- Research Laboratories:Biomarker stratification studies and companion diagnostic development occupy this segment.
Ophthalmology clinics extract the margin. Hospitals manage the complexity.
Technology:
Delivery mechanism innovation separates maintenance burden reduction from curative intent, with gene therapy representing the steepest expansion trajectory despite manufacturing constraints.
- Gene Therapy:Adeno-associated viral vectors targeting complement regulatory proteins promise single-administration efficacy. Viral vector production scale-up at contract manufacturing organizations is expanding investigational capacity, though cold chain logistics and biosafety containment limit site certification.
- Laser Therapy:Photocoagulation protocols for extrafoveal lesion containment retain utility in select European markets. EMA MDR compliance requirements for laser device recertification are compressing installed base renewal cycles.
- Photodynamic Therapy:Verteporfin-based protocols occupy niche positioning for polypoidal choroidal vasculopathy overlap cases.
- Microneedling:Trans-scleral delivery research programs target sustained-release depot formation without intravitreal injection burden.
Gene therapy climbs fastest. Laser therapy defends installed base.
Treatment Stage:
Intervention timing stratifies patient pools between presymptomatic screening capture and irreversible vision loss management, with early detection infrastructure determining addressable market expansion.
- Early Intervention:Automated OCT-A screening in United States integrated delivery systems identifies subclinical progression. FDA software-as-medical-device guidance for AI-assisted lesion segmentation is accelerating diagnostic platform deployment.
- Advanced Stage:Foveal-involved atrophy with preserved peripheral vision concentrates in tertiary referral centers. Japan's PMDA applies distinct reimbursement categories for bilateral versus unilateral involvement, shaping treatment sequencing decisions.
- Preventive Care:Risk-stratified monitoring protocols target intermediate AMD patients prior to atrophy onset.
- Palliative Care:Low-vision rehabilitation and adaptive technology provision dominate this terminal segment.
Early intervention expands the market. Advanced stage captures current spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained retinal specialists concentrate in urban academic medical centers across the United States, Germany, and Japan, anchoring procedure volume for intravitreal complement inhibitor administration. This talent distribution shapes where advanced therapy adoption accelerates versus where access constraints persist.
United States
Hospital systems acquire independent ophthalmology practices across metropolitan markets, consolidating imaging infrastructure and injection capacity within corporate entities. FDA breakthrough therapy designations compress Phase III timelines for novel complement inhibitors. Retinal specialty networks in Boston and Philadelphia deploy integrated diagnostic-to-treatment workflows that streamline patient throughput.
Germany
Statutory health insurance funds establish reimbursement corridors for first-in-class complement inhibitors through EMA accelerated assessment frameworks. Retinal clinics in Munich and Heidelberg standardize OCT-A imaging protocols for lesion progression monitoring. The country's statutory health insurance funds restrict corticosteroid coverage to combination therapy scenarios, shaping prescriber behavior.
Japan
PMDA reimbursement protocols favor inpatient designation for combination therapy administration, sustaining higher per-procedure yields in academic medical centers. Retinal specialists concentrate in Tokyo and Osaka, constraining rural treatment capacity. The regulator applies distinct reimbursement categories for bilateral versus unilateral atrophy involvement, directly shaping treatment sequencing decisions.
United Kingdom
NICE technology appraisals determine formulary placement for complement inhibitors within NHS England commissioning frameworks. Retinal treatment centers in London and Manchester concentrate advanced imaging infrastructure for early intervention screening. The country's National Institute for Health and Care Excellence evaluates cost-effectiveness thresholds that filter market access for premium-priced biologics.
India
Metro hospital systems in Mumbai and Delhi acquire independent retinal practices, creating concentrated demand pools for intravitreal injection services. The national pharmaceutical regulator reviews biosimilar pathways for follow-on complement inhibitors under accelerated assessment frameworks. Specialty clinic expansion in Maharashtra and Karnataka outpaces fellowship-trained specialist supply, creating training bottlenecks.
Geographic Atrophy Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the geographic atrophy landscape, creating tiered competitive dynamics. The market structure consolidates around pharmaceutical majors with retinal portfolios and biotechnology firms with complement pathway specialization. Three archetypes dominate: integrated diagnostics-to-therapeutics platforms, C3/C5 inhibition specialists, and anti-VEGF legacy incumbents extending into adjacent indications. Competitive moves center on retinal specialty network acquisition and diagnostic infrastructure integration with therapeutic delivery.
Within the complement inhibition archetype, Apellis Pharmaceuticals and Iveric Bio exemplify mechanism-focused development strategies. Roche anchors integrated care pathway positioning through diagnostics-to-therapeutics infrastructure. Novartis occupies the anti-VEGF legacy tier with portfolio extension into atrophy-adjacent retinal disease markets. These three entities represent distinct strategic postures that competitors must navigate.
| Leading Market Players |
|---|
| Roche |
| Astellas Pharma |
| Apellis Pharmaceuticals |
| Allegro Ophthalmics |
| Stealth BioTherapeutics |
| Iveric Bio |
| Novartis |
| Hemera Biosciences |
| Alkeus Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Consolidated procurement by hospital-owned ophthalmology networks across the United States and Germany is forcing manufacturers to reconfigure distribution models and compress margin structures for intravitreal biologics. This buyer concentration is reshaping how cold chain logistics providers negotiate service tiers and how contract manufacturing organizations price viral vector production capacity.
Pricing Analysis
Capacity additions in viral vector manufacturing at contract organizations across the United States and Switzerland are reshaping price floors for gene therapy candidates targeting complement regulatory proteins. Three-tier pricing structure across premium, standard, and economy levels stratifies by mechanism novelty and biomarker stratification capability, with FDA breakthrough-designated therapies commanding premium positioning. Cost compression in the anti-VEGF maintenance tier is intensifying because biosimilar ranibizumab entrants are eroding originator price persistence. Retinal specialty clinics in urban academic medical centers exhibit lowest price sensitivity due to integrated formulary control, while independent practices in rural India face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical procurement frameworks are reshaping sourcing patterns for complement inhibitor fill-finish operations previously concentrated in European facilities. Viral vector production draws from manufacturing bases in the United States, Germany, and South Korea, with plasmid DNA sourcing anchored in contract facilities across North America and Europe. Single-source vulnerability in adeno-associated viral serotype supply creates concentration risk for gene therapy developers advancing toward Phase III. Distribution runs through cold chain logistics networks certified for biologics handling, with retinal specialty clinics in metropolitan markets serving as the terminal delivery node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA accelerated assessment timelines compress regulatory costs relative to FDA standard review pathways, creating margin differential for European-first launch strategies.
For Market Incumbents: Anchor diagnostic infrastructure integration as the priority defensive move, locking retinal specialty networks into proprietary OCT-A and fundus autofluorescence workflows that complicate competitor switching. Complement pathway biomarker stratification capabilities represent the critical lever for formulary defense against biosimilar anti-VEGF erosion. Capacity addition in Swiss viral vector manufacturing secures gene therapy pipeline optionality against C3/C5 inhibition commoditization. For New Entrants and Emerging Players: The price-point gap between premium complement inhibitors and economy-tier anti-VEGF maintenance therapies creates white-space opportunity for sustained-release depot formulations that reduce injection burden. India's metro hospital system acquisition wave offers the most penetrable geography, where fellowship-trained specialist scarcity constrains incumbent service expansion. A go-to-market angle centered on AI-assisted lesion segmentation partnerships with acquired clinic networks bypasses direct therapeutic competition. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology firms possessing validated C3 or C5 mechanism data but lacking commercial infrastructure, as hospital system consolidation creates ready acquisition demand for integrated therapeutic platforms. Long-term viability hinges on gene therapy manufacturing scale-up execution across the analysis window. The inflection signal to watch is FDA confirmatory trial readouts for accelerated-approved complement inhibitors, which will separate viable mechanisms from placebo-drifting assets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA PRIME eligibility compresses European market entry timelines against FDA standard review. |
| Manufacturing Scale-Up | Viral vector production expansion at contract organizations enables gene therapy Phase III readiness. |
| Hospital System Partnership | Integrated delivery network contracts in Boston and Philadelphia lock in procedure volume concentration. |
| Software Companion Development | AI-assisted lesion segmentation tools secure FDA software-as-medical-device clearance for diagnostic anchoring. |
| Reimbursement Strategy | PMDA bilateral-atrophy reimbursement category navigation shapes Japan market sequencing decisions. |
Research Approach
Bottom-up retinal clinic procedure modeling reconciled against top-down pharmaceutical shipment tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Cross-referencing of intravitreal injection volume data against complement inhibitor prescription patterns enabled demand-side triangulation.
Input-output matrix framing connects patient population segmentation by treatment stage to manufacturing capacity utilization across viral vector and monoclonal antibody production facilities. Modeled dimensions span therapeutic mechanism, delivery technology, care setting, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and pricing evolution across the projection horizon, incorporating biomarker stratification adoption curves and retinal specialist workforce expansion constraints as industry-specific forecast inputs.
Caveats apply where FDA confirmatory trial outcomes, EMA post-authorization study results, or PMDA reimbursement category revisions could materially shift the outlook for complement inhibitor commercialization. Gene therapy manufacturing yield improvements or cold chain logistics disruptions represent additional revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market