
 Cervical Dystonia Market | 2026-2036
Cervical Dystonia Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Dystonia Market Analysis
The cervical dystonia treatment landscape is pivoting between premium botulinum toxin formulations and commodity oral medication tiers. AbbVie leverages its established neurology infrastructure to sustain dominance in high-purity toxin manufacturing. Ipsen Pharma anchors European supply chains through specialized distribution networks for movement disorder specialists.
Cervical dystonia is a focal dystonia characterized by involuntary, sustained contractions of neck muscles causing abnormal head postures and tremor, with botulinum toxin serotype A serving as the first-line intervention by blocking acetylcholine release at neuromuscular junctions. Botulinum toxin products command the largest revenue share within product type segmentation due to recurring injection cycles and premium pricing structures. Rehabilitation centers represent the fastest-growing end user segment as payors shift post-injection monitoring away from acute hospital settings.
FDA biologics licensing requirements and EMA good manufacturing practice standards for neurotoxin production shape product quality thresholds and market access timelines for new entrants. The EU MDR framework adds clinical evidence burdens for Class III devices used in surgical intervention pathways. Stakeholders must monitor evolving biosimilar pathways and reimbursement compression dynamics in major markets.
Market Dynamics
Botulinum toxin manufacturing consolidation is concentrating supply among three dominant producers, while FDA and EMA purity mandates force smaller competitors into costly facility upgrades or exit.
Growth Catalysts
- Specialty clinic expansion:Neurology-focused ambulatory centers in the United States and Germany are building dedicated injection suites for chronic movement disorder management, expanding addressable patient throughput.
- EMA neurotoxin GMP standards:Harmonized European manufacturing guidelines are accelerating cross-border product registration, reducing time-to-market for compliant manufacturers.
- Rehabilitation center networks:Post-acute care facilities in Japan are integrating botulinum toxin response monitoring into standard physical therapy protocols, creating new recurring revenue touchpoints.
Market Restraints
- Biologics cold chain complexity:Temperature-controlled distribution requirements from manufacturing sites to injection clinics impose 15-20% logistics premiums on neurotoxin products.
- Supply concentration risk:Active pharmaceutical ingredient production for type A toxin concentrates in two US-based fermentation facilities, creating single-point vulnerability.
- EU MDR Class III device barriers:Surgical intervention tools for refractory cervical dystonia face extended clinical evidence requirements, delaying market entry by 24-36 months.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil and Mexico lack established movement disorder specialist networks, presenting first-mover advantages for clinic-franchise models.
- Biosimilar regulatory pathways:FDA interchangeability guidelines for complex biologics are clarifying approval standards, opening routes for follow-on neurotoxin entrants.
- Telemedicine-integrated injection scheduling:Hybrid virtual-in-person care models are reducing specialist consultation backlogs in rural United States markets.
Industry Challenges
- Neurotoxin handling certification gaps:Licensed practical nurses in many jurisdictions lack authority to administer injections, constraining clinic capacity expansion.
- Patient response variability:Antibody formation in 5-10% of chronic recipients necessitates serotype switching protocols that complicate treatment algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Dystonia Market |
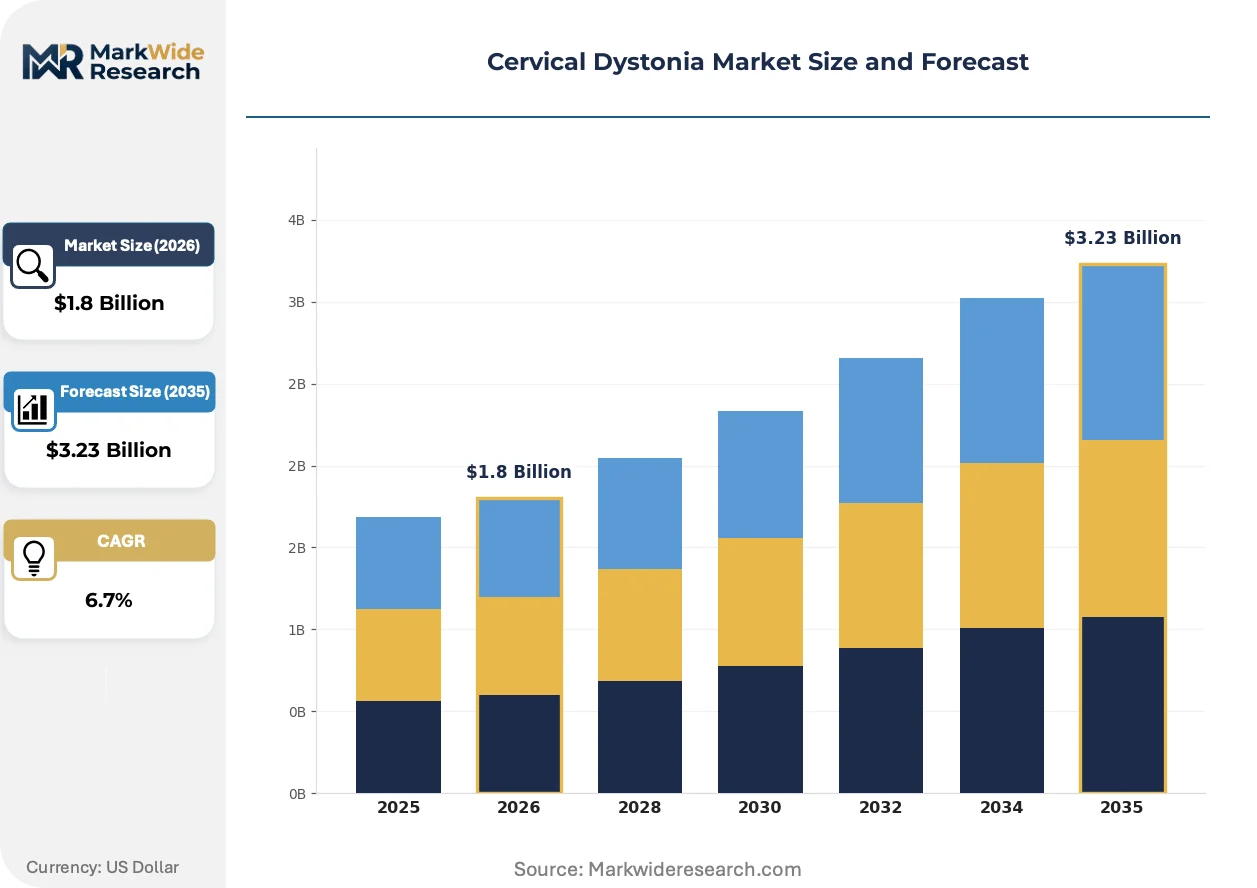
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Oral Medications, Physical Therapy, Surgery End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Treatment Method: Injection Therapy, Oral Therapy, Surgical Intervention, Alternative Therapies Severity Level: Mild, Moderate, Severe, Chronic |
| Companies Covered | AbbVie, Ipsen Pharma, Merz Pharma, Revance Therapeutics, Medy-Tox, Daewoong Pharmaceuticals, AEON Biopharma, Neurocrine Biosciences, Supernus Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Dystonia Market Emerging Trajectories
Digital guidance systems and refined injection protocols are compressing therapeutic response timelines while regulatory pressure on manufacturing transparency intensifies.
Ultrasound-guided injection delivery is rewriting precision standards in cervical dystonia care. Movement disorder specialists in academic medical centers are adopting real-time imaging for 60-70% of complex cases. This capability is compressing dose optimization cycles from months to weeks, reducing cumulative toxin exposure.
EMA good manufacturing practice updates for neurotoxin biologics are mandating enhanced purity testing and batch traceability. European manufacturers must now document endotoxin levels below 0.5 EU per vial. High-purity toxin suppliers are capturing preferential formulary placement in German and French hospital purchasing consortia.
Patient-directed care navigation is fragmenting traditional referral pathways. Direct-to-specialist scheduling platforms are displacing primary care gatekeeping in United States commercial insurance markets. Self-referral rates exceed 40% in Texas and Florida markets where neurology clinic density supports geographic convenience.
Cervical Dystonia Market Segmentation
Cervical dystonia treatment pathways fragment across therapeutic modalities, care settings, and disease progression stages. Understanding these divisions reveals where botulinum toxin manufacturers concentrate R&D investment and where rehabilitation providers are capturing post-acute patient volumes.
Product Type:
Purification grade and molecular formulation specifications differentiate competitive positioning across the therapeutic spectrum.
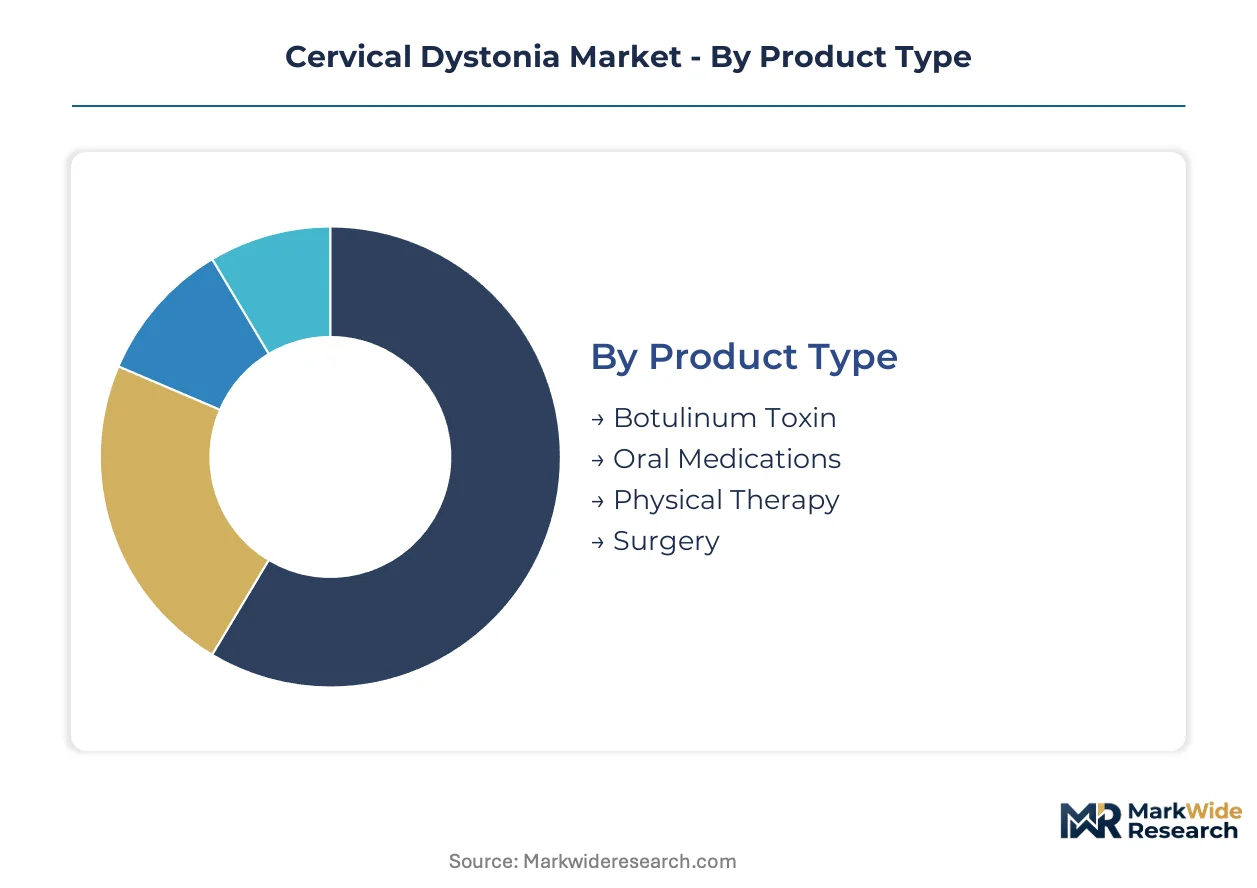
- Botulinum Toxin:High-purity serotype A formulations dominate first-line intervention through neuromuscular junction blockade. Recurring injection cycles and cold-chain distribution requirements sustain premium pricing in United States and German markets where FDA and EMA purity mandates have tightened.
- Oral Medications:Anticholinergics and muscle relaxants serve as adjunct or bridge therapy for patients with antibody-mediated toxin resistance. Demand concentrates in Japan's aging population cohorts where oral polypharmacy protocols remain culturally preferred.
- Physical Therapy:Targeted stretching and postural retraining programs address compensatory muscle hypertrophy.
- Surgery:Selective peripheral denervation and deep brain stimulation reserve for refractory cases failing conservative management.
Mature deployment sits with Botulinum Toxin. Newer deployment is concentrated in Surgery as deep brain stimulation protocols expand.
End User:
Care setting economics and reimbursement frameworks are redistributing patient touchpoints away from traditional hospital anchors.
- Hospitals:Academic medical centers retain complex surgical cases and initial diagnostic workups requiring multidisciplinary neurology-neurosurgery coordination. High fixed costs and bundled payment pressures are constraining expansion of elective injection services.
- Clinics:Neurology-focused ambulatory centers in Texas and Florida are building dedicated injection suites with ultrasound guidance capability. Direct-to-specialist scheduling platforms are displacing primary care gatekeeping in United States commercial insurance markets.
- Rehabilitation Centers:Post-acute facilities in Japan are integrating toxin response monitoring into standard physical therapy protocols.
- Home Care:Mobile nursing services are emerging for established patients with predictable dosing requirements.
Volume leadership remains with Hospitals. Rehabilitation Centers are climbing the fastest as payors shift post-injection monitoring away from acute settings.
Treatment Method:
Delivery mechanism selection tracks disease severity, patient antibody status, and specialist availability within regional markets.
- Injection Therapy:Intramuscular delivery of botulinum toxin requires electromyography or ultrasound guidance for precision targeting. German movement disorder specialists have achieved 60-70% adoption of real-time imaging in academic centers.
- Oral Therapy:Systemic pharmacologic management addresses tremor and pain symptoms without procedural requirements.
- Surgical Intervention:Deep brain stimulation and peripheral denervation target refractory cases with defined neuroanatomical targets.
- Alternative Therapies:Acupuncture and biofeedback serve patient populations seeking non-pharmacologic options.
Injection Therapy commands the dominant share. Alternative Therapies are gaining share fastest among younger patients in United States direct-pay wellness markets.
Severity Level:
Disease progression staging determines treatment intensity and long-term therapeutic resource allocation.
- Mild:Intermittent symptoms with preserved functional capacity respond to physical therapy and intermittent oral medication. Patient-directed care navigation is fragmenting traditional referral pathways in United States markets.
- Moderate:Sustained abnormal postures with functional impairment drive initial botulinum toxin enrollment.
- Severe:Disabling contractions with pain and social isolation require optimized injection protocols with serotype switching.
- Chronic:Long-standing disease with treatment complications including antibody formation necessitates surgical evaluation.
Moderate severity represents the largest addressable population. Severe cases are expanding most quickly as diagnostic delays in underpenetrated markets resolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors North American cervical dystonia treatment innovation, with Massachusetts General Hospital and Brigham and Women's Hospital driving ultrasound-guided injection protocol development. This clinical concentration shapes regional demand patterns across major economies.
United States
Commercial insurance reimbursement for botulinum toxin injections sustains specialty neurology clinic expansion in Texas and Florida markets. FDA biologics licensing requirements for neurotoxin purity standards have tightened manufacturing compliance burdens. The Mayo Clinic Rochester campus in Minnesota trains movement disorder specialists in electromyography-guided delivery techniques.
Germany
Hospital purchasing consortia in Bavaria and North Rhine-Westphalia negotiate preferential formulary placement for high-purity toxin suppliers. EMA good manufacturing practice standards mandate endotoxin documentation below 0.5 EU per vial for European market access. The Charité hospital network in Berlin coordinates multicenter injection response monitoring across federal state boundaries.
Japan
Aging population cohorts in Tokyo and Osaka metropolitan areas drive demand for chronic movement disorder management protocols. PMDA guidelines for biologics cold chain distribution enforce temperature-controlled logistics from manufacturing to injection sites. Rehabilitation centers in Kanagawa Prefecture integrate toxin response assessment into standardized physical therapy workflows.
United Kingdom
NHS England specialized commissioning frameworks concentrate cervical dystonia referrals to designated movement disorder centers in London and Manchester. MHRA post-Brexit regulatory alignment with EMA standards preserves cross-border manufacturing recognition for established suppliers. The National Hospital for Neurology and Neurosurgery in Queen Square maintains referral relationships with regional district general hospitals.
Brazil
Private health insurance expansion in São Paulo and Rio de Janeiro creates addressable demand for specialist injection services among affluent patient segments. ANVISA biologics registration pathways for neurotoxin products require local clinical trial data for market authorization. Hospital Israelita Albert Einstein in São Paulo develops training protocols for ultrasound-guided techniques adapted to Latin American patient populations.
Cervical Dystonia Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purification grade and cold-chain reliability dimensions in the cervical dystonia therapeutic space. Three manufacturers concentrate active pharmaceutical ingredient production for type A toxin, while formulation specialists compete on delivery device differentiation and injection protocol training. The competitive terrain separates into high-purity toxin incumbents, regional biosimilar aspirants, and surgical intervention device developers. Capacity expansion in fermentation facilities and strategic partnerships with academic medical centers constitute the dominant competitive moves.
Among North American biopharmaceutical incumbents, AbbVie and Revance Therapeutics occupy positions within the premium formulation tier, while Ipsen Pharma anchors European supply chain relationships with movement disorder specialist networks. These three entities exemplify contrasting strategic archetypes: AbbVie represents diversified neurology portfolio players, Revance Therapeutics sits within the specialized neurotoxin delivery innovation segment, and Ipsen Pharma embodies European-centric distribution-focused operators.
| Leading Market Players |
|---|
| AbbVie |
| Ipsen Pharma |
| Merz Pharma |
| Revance Therapeutics |
| Medy-Tox |
| Daewoong Pharmaceuticals |
| AEON Biopharma |
| Neurocrine Biosciences |
| Supernus Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Premium-purity toxin certification ladders in Germany and the United States bifurcate the cervical dystonia market into formulary-preferred suppliers and price-constrained alternatives, with EMA endotoxin thresholds and FDA biologics licensing requirements simultaneously elevating manufacturing costs and restricting supply base eligibility.
Pricing Analysis
Value-based pricing anchors botulinum toxin reimbursement through injection response durability and reduced hospitalization frequency. Three-tier pricing structure across premium, standard, and economy levels stratifies by purification grade and cold-chain reliability certification. Pricing pressure stems from biosimilar pathway clarity at FDA and EMA, compressing margins for non-differentiated entrants. Hospital purchasing consortia in Germany exhibit highest price sensitivity; academic medical centers in the United States show lowest sensitivity due to bundled outcome metrics.
Supply Chain Analysis
Temperature-controlled freight costs impose 15-20% logistics premiums on neurotoxin distribution from US-based fermentation facilities to injection clinics. Active pharmaceutical ingredient production concentrates in United States and South Korean biologics plants, with formulation finishing in Germany and Japan. Single-source vulnerability sits with type A toxin fermentation capacity. Distribution runs through specialty pharmacy channels and direct-to-clinic cold chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cervical dystonia market sits in a technology-transition phase as ultrasound-guided injection delivery displaces electromyography-dependent protocols, compressing dose optimization cycles and reshaping specialist training requirements.
For Market Incumbents: Anchor market position through backward integration into high-purity fermentation capacity and exclusive partnerships with academic medical centers for ultrasound protocol training. Biosimilar entrants from South Korean manufacturers threaten premium positioning. Certification investment in EMA good manufacturing practice compliance maintains formulary access in European hospital purchasing consortia. For New Entrants and Emerging Players: FDA interchangeability guidelines for complex biologics open a window for follow-on neurotoxin developers with demonstrated bioequivalence. White-space targets include Latin American clinic-franchise models in São Paulo and Mexico City, plus telemedicine-integrated injection scheduling platforms for rural United States markets. Go-to-market angle should emphasize specialist training bundled with product supply. For Investors and Strategic Acquirers: Re-rating potential sits with specialized neurotoxin delivery device developers given ultrasound guidance adoption acceleration in academic centers. Long-term viability favors platforms with regulatory dossiers across FDA, EMA, and PMDA jurisdictions. Signal to monitor: antibody-mediated serotype switching rates indicating chronic patient pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasound Protocol Training Partnerships | Mayo Clinic and Charité hospital networks establish specialist certification standards that lock in preferred supplier status. |
| Fermentation Capacity Expansion | Domestic API production in United States and South Korea reduces single-source vulnerability and secures supply continuity. |
| Biosimilar Interchangeability Pathway | FDA guidance clarity enables follow-on entrants to capture formulary share from established toxin manufacturers. |
| Rehabilitation Center Network Integration | Post-acute facilities in Kanagawa Prefecture and Texas create recurring revenue touchpoints beyond acute hospital settings. |
| Telemedicine-Injection Hybrid Platforms | Virtual specialist consultation reduces geographic access barriers and expands addressable patient throughput in underserved markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with movement disorder specialists, hospital formulary directors, biologics manufacturing executives, and rehabilitation center administrators. FDA biologics licensing applications, EMA good manufacturing practice inspection reports, PMDA cold chain distribution guidelines, and hospital procurement database extracts provided validation anchors. Bottom-up patient volume estimates and top-down manufacturer revenue triangulation cross-checked segmentation outputs.
Granularity-level modeling tracked botulinum toxin serotype, administration guidance technology, end-user facility type, and disease severity stage across the projection horizon. CAGRs derived from epidemiological prevalence trends, treatment penetration rates, and pricing trajectory assumptions. Forecast inputs included antibody formation incidence in chronic recipients, ultrasound equipment installation rates at academic medical centers, and biosimilar approval timeline probabilities.
Caveats apply where regulatory pathway delays, manufacturing contamination events, or reimbursement policy shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding specialist workforce expansion and cold chain infrastructure investment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Benign Positional Vertigo Market