
 PARP Inhibitors Market | 2026-2036
PARP Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
PARP Inhibitors Market Intelligence
The divergence between first-in-class monotherapies and next-generation combination regimens is rebalancing the competitive landscape. This shift places a premium on clinical data demonstrating efficacy beyond established indications. AstraZeneca leverages its first-mover advantage with Olaparib across multiple tumor types. GSK plc competes through its strategic focus on Niraparib in specific patient populations, while Pfizer specializes in developing its pipeline candidate, Talazoparib, for distinct genetic mutations in breast cancer.
PARP inhibitors are targeted therapies designed to exploit deficiencies in DNA repair pathways common in certain cancers. These drugs function by blocking the poly (ADP-ribose) polymerase enzyme, leading to cell death in tumors with mutations like BRCA1/2. Ovarian cancer and breast cancer represent the most established therapy areas, holding significant market share. The product landscape, while led by Olaparib, sees increasing competition from Niraparib and Rucaparib as they gain approvals for prostate and pancreatic cancer indications.
Regulatory approvals from agencies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) are primary determinants of market entry. Guidelines from China's NMPA are also critical for accessing its large patient base. These bodies' requirements for robust clinical trial data and companion diagnostic validation directly influence development timelines and commercialization strategies. Navigating the evolving reimbursement policies and demonstrating long-term value will be essential for sustained market penetration.
Market Dynamics
The co-development of companion diagnostics alongside novel drug candidates is the central force shaping the PARP inhibitors market. This dynamic links drug approval directly to biomarker identification, concentrating value in therapies with clear, genetically defined patient populations like those with BRCA mutations.
Growth Catalysts
- Companion Diagnostics Expansion:The increasing requirement for companion diagnostics to identify eligible patient populations, such as those with specific genetic mutations, is expanding the addressable market for these targeted therapies.
- Regulatory Pathways:Accelerated approval pathways from agencies like the US FDA and EMA for therapies targeting high unmet needs in cancers like ovarian and prostate cancer shorten development timelines.
- Indication Expansion:Successful clinical trials leading to label expansions beyond ovarian and breast cancer into areas like pancreatic and prostate cancer are opening new treatment paradigms and patient segments.
Market Restraints
- High Treatment Costs:The significant cost of PARP inhibitor therapies creates reimbursement hurdles and limits patient access, particularly in healthcare systems with strict budget controls or in emerging economies.
- Acquired Drug Resistance:The development of acquired resistance mechanisms in patients over time limits the long-term efficacy of monotherapies and necessitates complex, often more costly, combination strategies.
- Toxicity and Side Effects:Hematological toxicities and other adverse events associated with this drug class can lead to dose reductions or discontinuation, impacting treatment outcomes and patient quality of life.
Strategic Opportunities
- Neoadjuvant and Adjuvant Settings:Moving PARP inhibitors into earlier lines of treatment, such as neoadjuvant or adjuvant settings for early-stage cancers, could substantially broaden the eligible patient population before resistance develops.
- Novel Combination Therapies:Exploring synergies with other drug classes, such as immunotherapy agents or cell cycle inhibitors, offers a path to overcome resistance and improve efficacy in new indications.
- Untapped Patient Pools in Asia:Expanding access and securing reimbursement in large markets like China and Japan, where cancer incidence is high, presents a significant growth opportunity for established and new therapies.
Industry Challenges
- Complex Clinical Trial Design:Designing and executing global clinical trials for combination therapies is operationally complex and costly, requiring large patient cohorts and sophisticated biomarker stratification across diverse populations.
- Genetic Testing Infrastructure:Ensuring widespread, timely, and accurate genetic testing for mutations like BRCA1/2 remains an operational hurdle for optimal patient identification and treatment selection in many geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PARP Inhibitors Market |
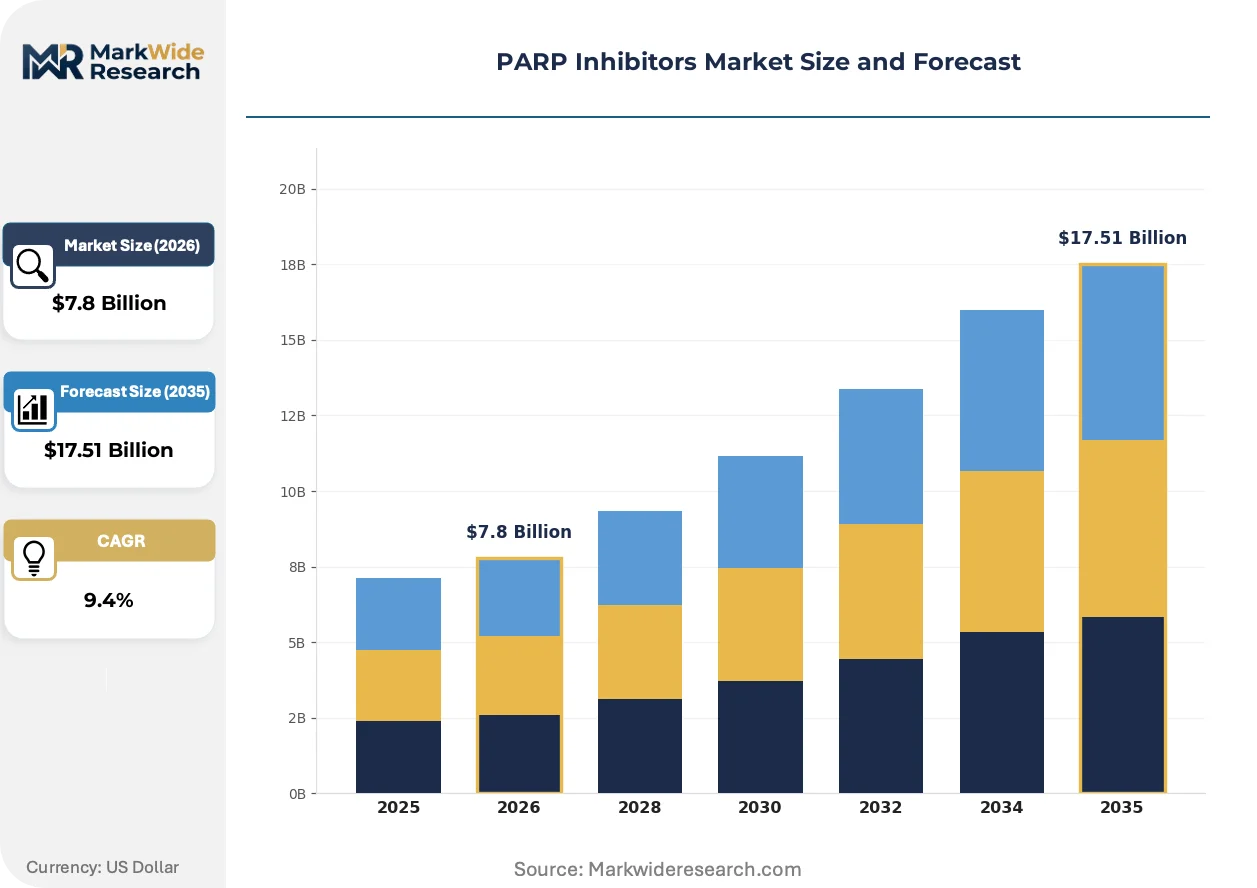
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olaparib, Niraparib, Rucaparib, Talazoparib Therapy Area: Ovarian Cancer, Breast Cancer, Prostate Cancer, Pancreatic Cancer Route of Administration: Oral, Intravenous, Subcutaneous, Intramuscular End User: Oncology Clinics, Research Centers, Specialized Hospitals, Diagnostic Laboratories |
| Companies Covered | AstraZeneca, Merck & Co., GSK plc, Pfizer, Johnson & Johnson Services, BeiGene, AbbVie, Clovis Oncology, Repare Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PARP Inhibitors Market Strategic Shifts & Innovations
The market's evolution is defined by a move from single-agent efficacy to a systems-level therapeutic approach. This shift prioritizes biomarker-driven patient selection and the development of rationally designed combination regimens to preemptively address or overcome therapeutic resistance mechanisms.
Next-generation sequencing (NGS) and liquid biopsy technologies serve as advanced companion diagnostics for patient screening. Oncology clinics and research hospitals are adopting these tools to test for homologous recombination deficiency (HRD) status. This adoption of advanced diagnostics is modularizing patient stratification, allowing for more precise application of specific PARP inhibitors based on unique tumor genetic profiles.
European Medicines Agency (EMA) guidance on real-world evidence (RWE) is influencing post-approval requirements for drug developers. This regulatory shift compels manufacturers to collect and analyze data on long-term safety and effectiveness from routine clinical practice. Prostate and pancreatic cancer indications are particularly affected, as companies must now build robust RWE generation programs to maintain market access and support reimbursement negotiations.
A transition towards value-based care models is altering how hospital systems and payers evaluate PARP inhibitors. Simple drug acquisition cost is being replaced by a total cost-of-care analysis that includes hospitalization, side-effect management, and long-term patient outcomes. This trend is most visible in the United States and parts of Western Europe, where payers increasingly demand outcome-based agreements from manufacturers.
PARP Inhibitors Market Segmentation
The PARP inhibitors market segmentation offers a detailed view of the therapeutic landscape, highlighting the distinct product types, patient populations, and treatment settings that define its commercial structure. This stratification is crucial for understanding demand drivers, competitive dynamics, and the evolving clinical utility of these targeted cancer therapies across various indications.
Product Type:
The market for PARP inhibitors exhibits a clear distinction between high-volume, established monotherapies and premium, next-generation candidates.
- Olaparib:This first-in-class PARP inhibitor holds a significant market share, approved for multiple tumor types including ovarian, breast, prostate, and pancreatic cancers. Its broad label across several indications solidifies its leading position in the therapeutic space.
- Niraparib:Focused on specific patient populations, this PARP inhibitor has gained traction, particularly with strategic approvals for ovarian and prostate cancer. Its differentiated profile supports sustained growth in targeted patient segments.
- Rucaparib:This PARP inhibitor is expanding its market presence through recent approvals for prostate and pancreatic cancer indications.
- Talazoparib:A pipeline candidate, this PARP inhibitor specializes in treating distinct genetic mutations in breast cancer.
Mature deployment sits with Olaparib. Newer deployment is concentrated in Niraparib.
Therapy Area:
Therapy area segmentation highlights the diverse patient needs addressed by PARP inhibitors across various cancer types.
- Ovarian Cancer:This represents the most established therapy area for PARP inhibitors, holding a substantial market share due to its proven efficacy in maintenance and treatment settings. Significant demand for PARP inhibitors originates from this patient population, especially those with BRCA mutations.
- Breast Cancer:Another established therapy area, breast cancer treatment with PARP inhibitors targets specific genetic mutations, particularly BRCA1/2-mutated HER2-negative metastatic breast cancer. Clinical adoption is high in the United States and parts of Europe.
- Prostate Cancer:This indication is expanding, driven by successful clinical trials and regulatory approvals for metastatic castration-resistant prostate cancer.
- Pancreatic Cancer:An emerging indication, PARP inhibitors offer new treatment paradigms for specific patient groups with germline BRCA-mutated metastatic pancreatic adenocarcinoma.
Ovarian cancer continues to drive significant market volume. Prostate and pancreatic cancer indications are expanding most quickly.
Route of Administration:
Route of administration differentiates PARP inhibitor delivery based on patient convenience and pharmacokinetic profiles.
- Oral:This route is preferred for long-term home-based treatment, enhancing patient compliance and quality of life by avoiding frequent clinic visits. Oral formulations dominate the market due to their ease of use.
- Intravenous:This administration method ensures rapid systemic delivery and precise dosing, often used in initial treatment phases or for specific patient conditions requiring immediate therapeutic effect. It is typically administered in specialized hospital settings.
- Subcutaneous:This route offers an alternative for reduced patient burden and potential for self-administration, improving convenience.
- Intramuscular:Less common for PARP inhibitors, this route provides sustained release for certain drug classes requiring slower absorption.
Oral administration remains the dominant method for PARP inhibitor delivery. Intravenous methods serve critical acute care needs.
End User:
End-user segmentation reflects the primary healthcare settings and specialized facilities utilizing PARP inhibitors.
- Oncology Clinics:These facilities are primary sites for outpatient cancer treatment, managing long-term patient care, and administering PARP inhibitor therapies. They provide continuous monitoring and support for patients.
- Specialized Hospitals:These institutions provide comprehensive cancer care, including complex surgical procedures, advanced therapeutic regimens, and inpatient management for patients receiving PARP inhibitors. They often handle more severe cases.
- Research Centers:These centers focus on clinical trials and novel drug development, contributing to the expansion of PARP inhibitor indications.
- Diagnostic Laboratories:These facilities are essential for companion diagnostic testing and patient stratification based on genetic mutations, enabling precise treatment selection.
Oncology clinics and specialized hospitals serve as the primary points of care for PARP inhibitor therapy. Diagnostic laboratories enable precise patient selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology cluster anchors significant PARP inhibitor research and development. This region drives innovation in targeted therapies for cancer treatment. Its academic institutions and pharmaceutical companies collaborate on advanced clinical trials.
United States
Demand for PARP inhibitors in the United States stems from high cancer incidence and advanced healthcare infrastructure. The US FDA's accelerated approval pathways facilitate market entry for novel therapies. Major pharmaceutical hubs like Research Triangle Park in North Carolina foster collaboration between industry and academia for drug discovery.
Germany
Europe's largest economy, Germany, experiences strong demand for PARP inhibitors due to its aging population and robust oncology research. The EMA's stringent regulatory framework ensures high standards for drug approval and market access. The Rhine-Main region, including Frankfurt, serves as a central hub for pharmaceutical distribution and clinical research activities.
Japan
Patient populations in Japan benefit from PARP inhibitors driven by increasing awareness of personalized medicine in oncology. Japan's PMDA rigorously evaluates new cancer treatments for efficacy and safety before market authorization. The Tokyo metropolitan area features numerous specialized hospitals and research centers focused on advanced cancer therapies.
China
Growth in China's PARP inhibitors market is propelled by a large patient base and expanding access to innovative cancer drugs. The NMPA's updated guidelines for drug registration streamline the approval process for targeted therapies. Shanghai's biomedical parks attract significant investment in R&D and manufacturing for advanced pharmaceutical products.
India
India shows increasing demand for PARP inhibitors, particularly for breast and ovarian cancer indications. The CDSCO regulates pharmaceutical products, ensuring quality and accessibility of cancer drugs. Hyderabad's Genome Valley emerges as a significant center for pharmaceutical research and development, supporting local and international drug manufacturing.
PARP Inhibitors Market Key Industry Players
Capital-heavy pharmaceutical producers compete with asset-light biotechnology firms in the PARP inhibitors market. This landscape features both established global players and specialized biopharmaceutical companies. The market structure exhibits tiered competition, with first-in-class monotherapies facing next-generation combination regimens. Strategic archetypes include broad-spectrum developers and niche-focused innovators. Portfolio diversification and strategic partnerships are dominant competitive moves among market participants.
On the premium-tier vector, AstraZeneca, a UK-Swedish multinational, exemplifies a global pharmaceutical leader with a broad portfolio of oncology treatments. Its first-mover advantage with Olaparib across multiple tumor types positions it prominently. GSK plc, another UK-based pharmaceutical giant, represents a strategic focus on specific patient populations, particularly with Niraparib. Pfizer, a US-based pharmaceutical corporation, occupies a position in developing pipeline candidates like Talazoparib for distinct genetic mutations. These companies anchor market activity through extensive research capabilities and global distribution networks, influencing treatment paradigms and patient access.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck & Co. |
| GSK plc |
| Pfizer |
| Johnson & Johnson Services |
| BeiGene |
| AbbVie |
| Clovis Oncology |
| Repare Therapeutics |
| Others |
Cost & Logistics Intelligence
Clinical trial execution costs significantly influence the downstream pricing tiers for PARP inhibitors. These substantial research and development investments must be recouped through market access strategies and reimbursement negotiations for novel therapies.
Pricing Analysis
Outcome-based agreements increasingly anchor PARP inhibitor pricing, particularly in Western markets. Price differentiation stems from the breadth of approved indications and the strength of clinical efficacy data. Pricing pressure stems from the high cost burden on healthcare systems and the emergence of combination therapies. Payers and government bodies demonstrate high price sensitivity, while patients with limited treatment options exhibit lower sensitivity.
Supply Chain Analysis
Specialized logistics costs are a critical factor in the PARP inhibitor supply chain, ensuring temperature-controlled transport for sensitive pharmaceutical products. Manufacturing concentrates in countries with advanced pharmaceutical infrastructure, such as Ireland, Switzerland, and the United States. The supply chain depends on active pharmaceutical ingredients (APIs) sourced from various global suppliers, including those in China and India. Single-source vulnerability for proprietary APIs presents a structural risk. Distribution runs through a network of specialty pharmacies and hospital systems, facilitating controlled access to these high-value oncology drugs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PARP inhibitors market is evolving into a consolidation play, where the complex clinical trial design for next-generation therapies forces out smaller, less capitalized players.
For Market Incumbents: Extend existing label indications into earlier lines of therapy for established cancers like ovarian and breast cancer. Develop novel combination therapies to overcome acquired drug resistance, leveraging R&D in biomarker discovery. Strategic partnerships with diagnostic firms can reinforce patient stratification capabilities against emerging competitive threats.
For New Entrants and Emerging Players: Patients with rare or complex genetic profiles represent an underserved buyer archetype. Target specific genetic mutations beyond BRCA1/2, particularly in underpenetrated geographies like parts of Asia. A strong go-to-market angle involves co-developing therapies with advanced companion diagnostics for precise patient selection.
For Investors and Strategic Acquirers: Successful Phase 3 trial readouts for novel combination therapies are the leading indicator that validates long-term market viability. The market exhibits sustained growth over the next 5-10 years, driven by indication expansion and therapeutic advancements. Target biotech firms with strong pipeline candidates or proprietary diagnostic platforms for strategic acquisition.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expands market access by demonstrating efficacy in new patient populations. |
| Regulatory Approval Pathway | Secures market entry and competitive advantage for novel drug candidates. |
| Licensing Agreement | Accelerates pipeline development and broadens geographic reach for therapies. |
| Pipeline Diversification | Mitigates risk by developing treatments for multiple cancer types. |
| Manufacturing Scale-Up | Ensures consistent supply to meet increasing global patient demand. |
Research Approach
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov data, and peer-reviewed academic journals, complemented by interviews with oncologists, regulatory affairs specialists, and hospital pharmacists. Patient advocacy groups also provided crucial insights into unmet needs. This approach enabled a robust bottom-up and top-down triangulation of market data.
The forecast framework cross-referenced historical market performance against expert panel input across the analysis window. Segmentation dimensions modeled included product type, therapy area, route of administration, end user, and regional regulatory cluster. Compound annual growth rates (CAGRs) were derived from a multi-factor analysis, incorporating incidence rates of target cancers and companion diagnostic adoption rates as key inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen clinical trial failures or shifts in reimbursement policy. Forecasts reflect assumptions regarding regulatory environments and therapeutic advancements. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Liquid Filled Hard Capsules Market