
 Vasomotor Symptoms Market | 2026-2036
Vasomotor Symptoms Market Size, Share, and Industry Trends Forecast 2026-2036
Vasomotor Symptoms Market Intelligence
Subscription-based patient monitoring programs are restructuring how pharmaceutical companies monetize menopausal care beyond one-time prescriptions. Eli Lilly and Company leverages its endocrinology infrastructure to sustain direct-to-clinic channels for hormone therapies. Pfizer Inc. anchors its position through manufacturing scale across North American distribution networks. Astellas Pharma differentiates via specialized urology-gynecology crossover formulations in Asian markets.
Vasomotor symptoms encompass the autonomic nervous system dysregulation manifesting as thermoregulatory instability, typically involving transient cutaneous vasodilation with core temperature elevation exceeding 0.5°C. These episodes drive clinical intervention primarily to preserve sleep architecture, cardiovascular stability, and occupational productivity in peri-menopausal populations. Hormone Replacement Therapy occupies the dominant margin pool due to established reimbursement pathways, while Transdermal Patch delivery is gaining fastest among patients with hepatic metabolism concerns. Telehealth Services is reshaping initial diagnosis routing as synchronous video platforms expand prescriptive authority for non-controlled substances.
FDA safety labeling requirements for menopausal hormone products shape clinical trial design and post-market surveillance obligations for all US-distributed therapies. EMA's MDR framework and REACH compliance standards govern biologic patch materials and active pharmaceutical ingredient purity across European manufacturing. Health Canada and WHO prequalification programs influence parallel import pathways for generic hormone formulations. Stakeholders must monitor evolving pharmacovigilance reporting thresholds as real-world evidence gains regulatory weight in label expansion decisions.
Market Dynamics
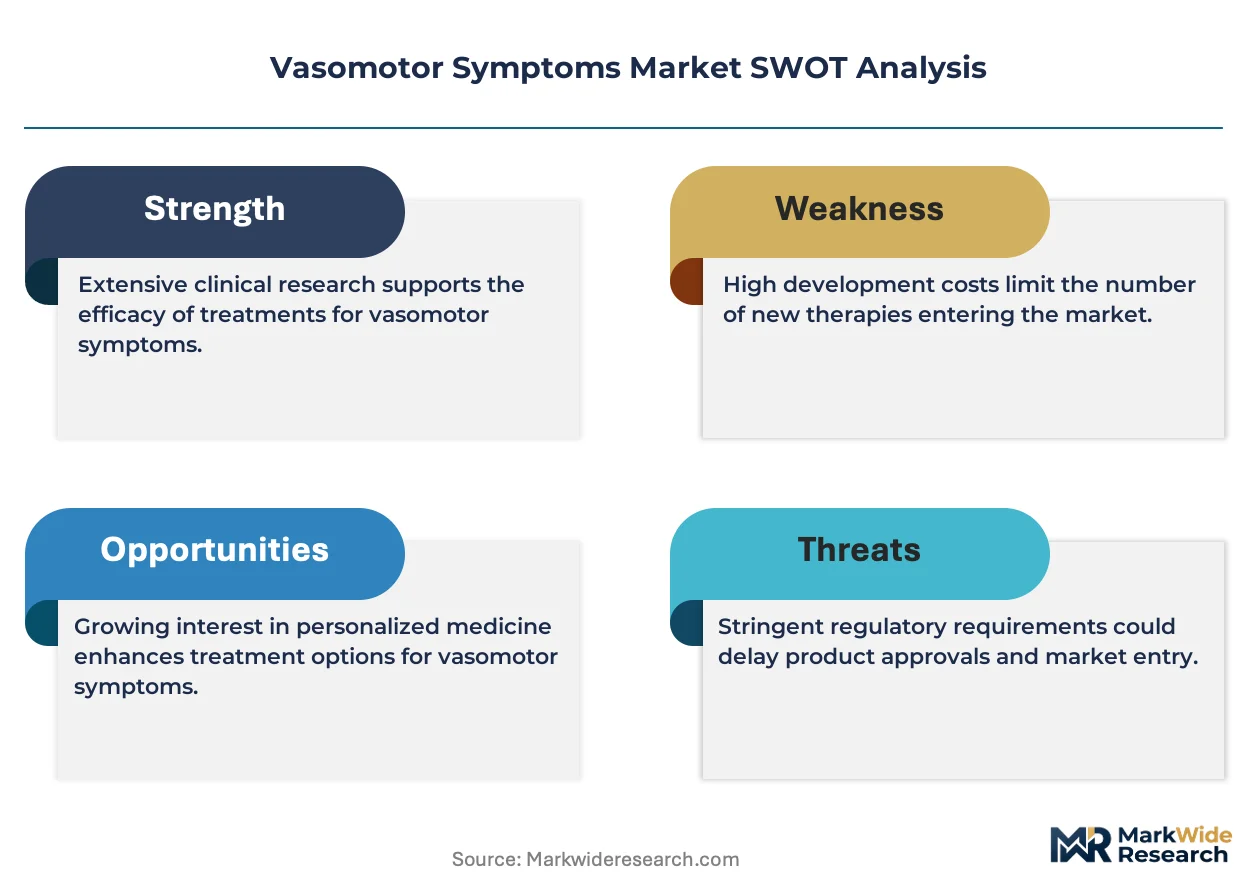
Non-hormonal therapeutic pipelines are redirecting clinical investment away from traditional estrogen-progesterone combinations, fragmenting prescriber loyalty and forcing reimbursement frameworks to accommodate novel mechanism categories without established safety histories.
Growth Catalysts
- FDA label expansion pathways:Accelerated approval designations for neurokinin-3 receptor antagonists compress development timelines for vasomotor symptom therapies, attracting venture capital into menopausal drug platforms previously deemed niche.
- Urban hospital network concentration:German metropolitan health systems are consolidating menopausal specialty services, creating captive prescription volumes that pharmaceutical manufacturers prioritize for pilot program deployment.
- Telehealth synchronous video platforms:Expanded prescriptive authority for non-controlled substances through virtual consultations removes geographic access barriers, capturing peri-menopausal patients in rural and underserved catchment areas.
Market Restraints
- Active pharmaceutical ingredient purity standards:EMA REACH compliance and MDR framework requirements for biologic patch materials inflate manufacturing qualification costs, squeezing margin structures for transdermal delivery formats.
- Hepatic metabolism contraindications:Oral hormone formulations face persistent safety labeling restrictions that limit addressable patient populations, preserving transdermal alternatives at premium price positions without volume scalability.
- Generic hormone parallel import pathways:WHO prequalification programs enable cross-border generic substitution, eroding branded formulation pricing power in price-sensitive reimbursement environments.
Strategic Opportunities
- Subscription-based patient monitoring programs:Recurring revenue models for menopausal symptom tracking and dose optimization create lifetime value capture beyond initial prescription fulfillment.
- Urology-gynecology crossover formulations:Specialized therapeutic positioning at the intersection of pelvic floor dysfunction and vasomotor symptoms opens access to dual-specialty prescribing networks in Asian markets.
- Real-world evidence integration:Pharmacovigilance reporting thresholds gaining regulatory weight in label expansion decisions reward manufacturers with robust post-market surveillance infrastructure.
Industry Challenges
- Endocrinology-trials recruitment:Competing demands for peri-menopausal participants across oncology and metabolic disease studies compress enrollment timelines and inflate site costs.
- Legacy distribution network reconfiguration:Direct-to-clinic channel investments require dismantling wholesale-dependent infrastructure without disrupting existing hospital formulary relationships.
- Cross-functional regulatory expertise:Simultaneous navigation of FDA safety labeling, EMA MDR technical documentation, and Health Canada biologic standards demands rare hybrid skill sets in quality assurance functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vasomotor Symptoms Market |
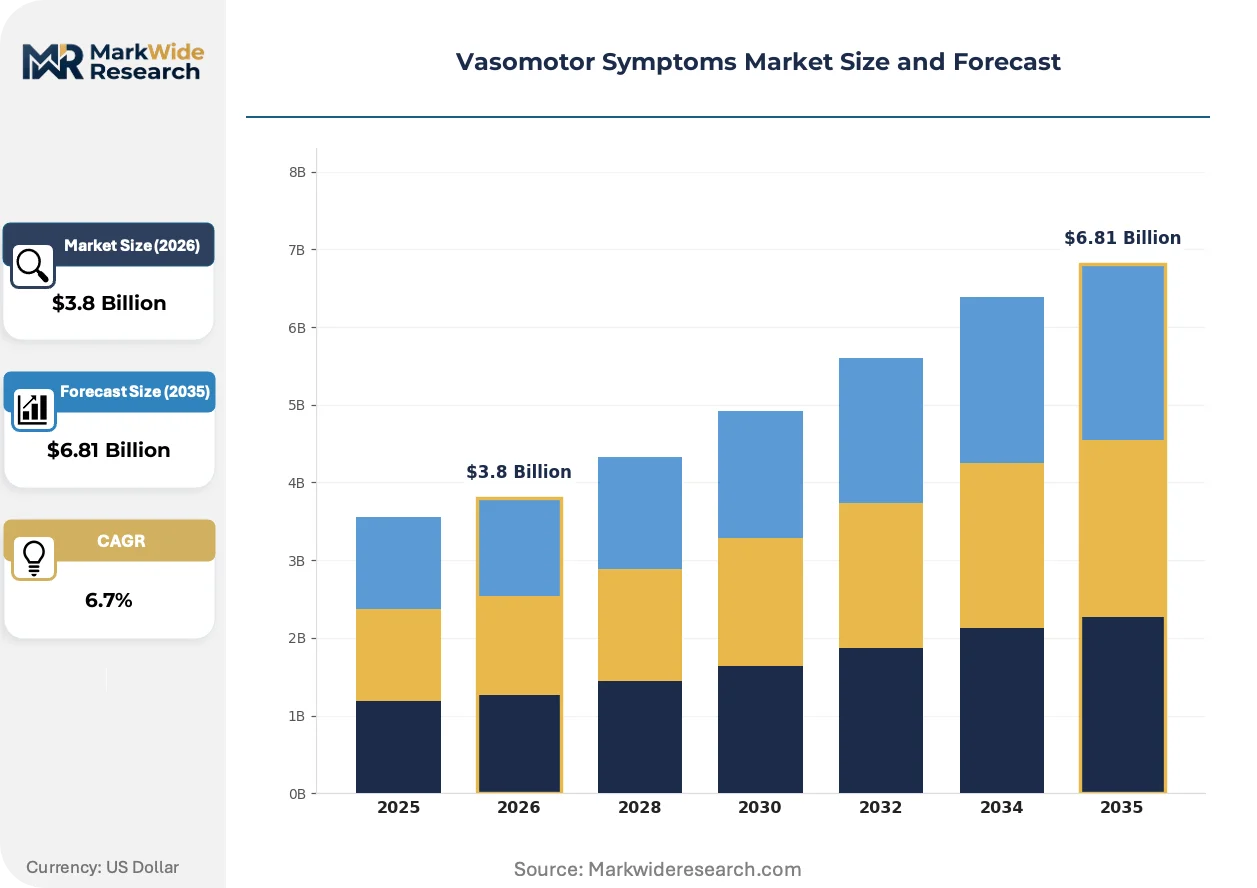
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Replacement Therapy, Antidepressants, Gabapentin, Lifestyle Modifications Delivery Mode: Oral, Transdermal Patch, Injectable, Herbal Remedies End User: Clinics, Hospitals, Home Care, Telehealth Services Symptom Type: Hot Flashes, Night Sweats, Sleep Disturbances, Mood Swings |
| Companies Covered | Eli Lilly and Company, Allergan, Bayer AG, Nerre Therapeutics Ltd., Mithra Pharmaceuticals, Astellas Pharma, Novartis AG, Mitsubishi Tanabe Pharma, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vasomotor Symptoms Market Strategic Shifts & Innovations
Digital biomarker capture and algorithmic symptom prediction are compressing the diagnostic-to-treatment interval, while regulatory acceptance of decentralized trial endpoints accelerates validation cycles for novel therapeutic mechanisms.
Wearable core temperature monitoring is decentralizing thermoregulatory episode documentation for clinical trial endpoints. Biopharmaceutical sponsors deploy these devices in peri-menopausal cohorts to generate objective efficacy data that satisfies FDA safety labeling requirements for non-hormonal alternatives. The technology compresses reliance on patient-reported outcome instruments, enabling faster dose-optimization protocols.
EMA MDR technical documentation requirements for biologic patch adhesives are forcing reformulation investments across European manufacturing footprints. Manufacturers must demonstrate cytotoxicity and sensitization profiles for novel polymer matrices, extending qualification timelines for transdermal hormone delivery systems. German notified bodies process these submissions with variable throughput, creating competitive advantage for firms with established regulatory affairs presence in Munich and Berlin clusters.
Patient-initiated switching between hormonal and non-hormonal modalities is fragmenting prescriber loyalty patterns. Telehealth platforms capture these transitions through direct-to-consumer marketing, bypassing traditional gynecology clinic gatekeepers. This behavioral shift concentrates in United States metropolitan markets where synchronous video prescription authority overlaps with high-deductible insurance plan prevalence.
Vasomotor Symptoms Market Segmentation
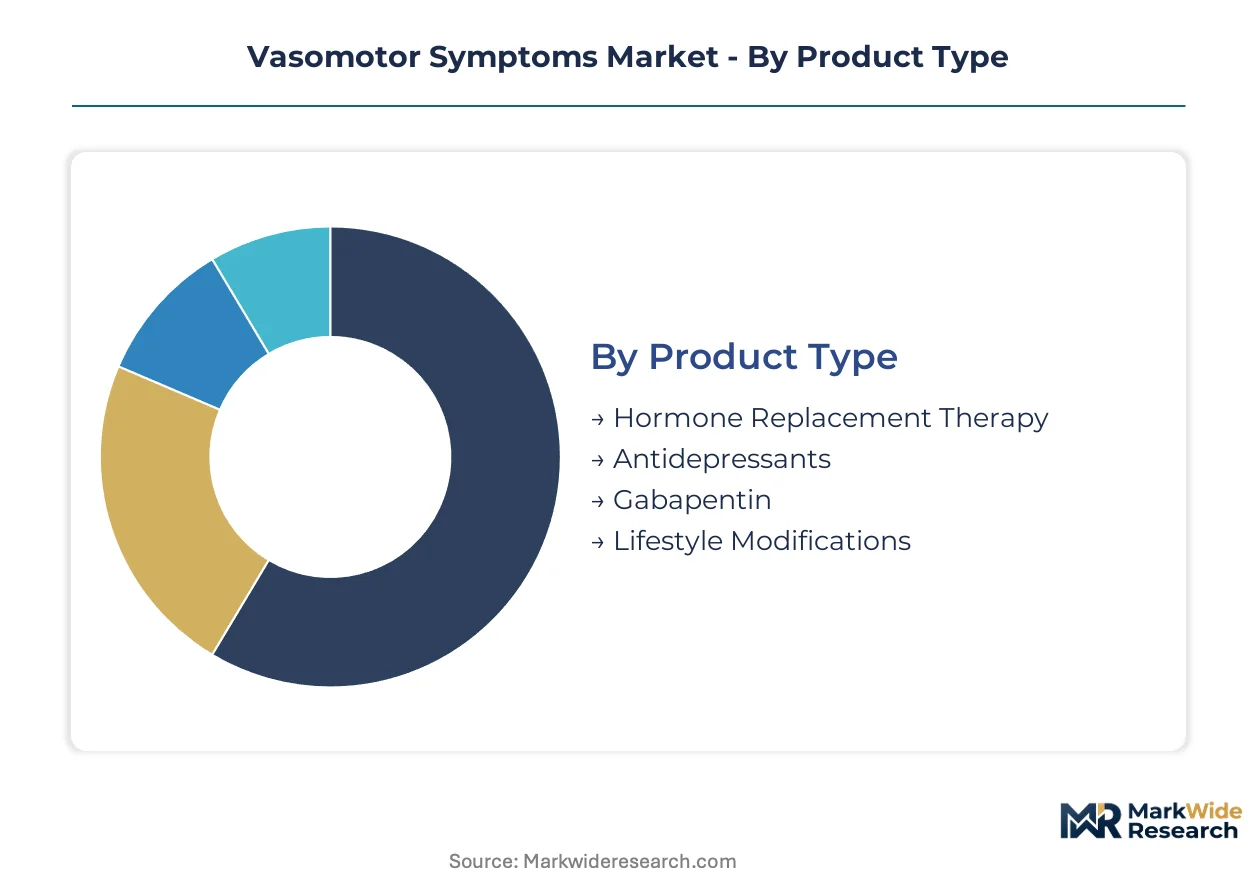
Vasomotor symptom treatment selection follows distinct clinical pathways shaped by hepatic risk profiles, reimbursement structures, and prescriber specialty training. Patient migration between modalities—particularly the shift from oral to transdermal formats—creates upgrade cycles that pharmaceutical manufacturers must anticipate in portfolio planning.
Product Type:
Upgrade cycles in this category accelerate when safety labeling changes prompt prescriber reassessment of first-line options, creating replacement demand for mechanism-diverse alternatives.
- Hormone Replacement Therapy:Estrogen-progesterone combinations remain the clinical default for patients without cardiovascular or oncologic contraindications. Demand concentrates in United States gynecology clinics where established reimbursement pathways preserve prescriber familiarity despite emerging non-hormonal competition.
- Antidepressants:Selective serotonin reuptake inhibitors and serotonin-norepinephrine reuptake inhibitors function through hypothalamic thermoregulatory modulation. German urban hospital networks prioritize these for patients with hepatic metabolism concerns or prior thromboembolic events, capturing volume from displaced oral hormone prescriptions.
- Gabapentin:Neuromodulator with off-label vasomotor symptom application in peri-menopausal populations with comorbid neuropathic pain conditions.
- Lifestyle Modifications:Behavioral cooling protocols and trigger avoidance strategies deployed as adjunctive or contraindicated-patient alternatives.
Hormone Replacement Therapy sits at the top of the volume ranking, with Antidepressants climbing the fastest.
Delivery Mode:
Cost tier differentiation separates premium transdermal systems from economy oral generics, with manufacturing qualification expenses driving the wedge.
- Oral:First-pass hepatic metabolism limits addressable populations through safety labeling restrictions. Volume concentrates in price-sensitive reimbursement environments where generic substitution erodes branded pricing power through WHO prequalification-enabled parallel imports.
- Transdermal Patch:Bypasses hepatic circulation to deliver steady-state hormone levels with lower thromboembolic risk profiles. EMA MDR technical documentation requirements for biologic patch adhesives inflate European manufacturing costs, preserving premium positioning without mass-market scalability.
- Injectable:Long-acting depot formulations for patients with adherence challenges or gastrointestinal absorption limitations.
- Herbal Remedies:Phytoestrogen and black cohosh preparations positioned outside formal pharmaceutical reimbursement frameworks.
Oral formulations retain volume leadership, though Transdermal Patch formats are expanding most quickly among patients with hepatic contraindications.
End User:
Application context determines prescribing authority boundaries and monitoring intensity, with telehealth platforms disrupting traditional site-of-care hierarchies.
- Clinics:Gynecology and primary care sites generate the majority of initial diagnoses and treatment initiations. United States clinic networks are consolidating menopausal specialty services, creating captive prescription volumes that manufacturers prioritize for pilot program deployment.
- Telehealth Services:Synchronous video platforms now hold prescriptive authority for non-controlled substances across multiple United States jurisdictions. This channel captures peri-menopausal patients in rural catchment areas, bypassing geographic access barriers that previously funneled demand through hospital networks.
- Hospitals:Acute and specialty settings manage complex cases with comorbid cardiovascular or oncologic conditions requiring multidisciplinary coordination.
- Home Care:Self-administered modalities for stabilized patients with established response profiles and minimal monitoring requirements.
Clinics sit at the top of the volume ranking, with Telehealth Services climbing the fastest.
Symptom Type:
Customer severity segmentation separates patients seeking sleep preservation from those managing occupational productivity impacts, driving differential treatment intensity.
- Hot Flashes:Transient cutaneous vasodilation with core temperature elevation exceeding 0.5°C represents the most visible vasomotor manifestation. Wearable core temperature monitoring devices now document these episodes objectively for clinical trial endpoints, compressing reliance on patient-reported instruments.
- Night Sweats:Nocturnal thermoregulatory episodes disrupt sleep architecture and drive functional impairment. German metropolitan health systems prioritize aggressive intervention for this segment due to occupational productivity impacts in peri-menopausal working populations.
- Sleep Disturbances:Secondary insomnia arising from nocturnal symptom burden or independent menopausal transition effects.
- Mood Swings:Affective lability with potential overlap between vasomotor symptom burden and independent psychiatric conditions.
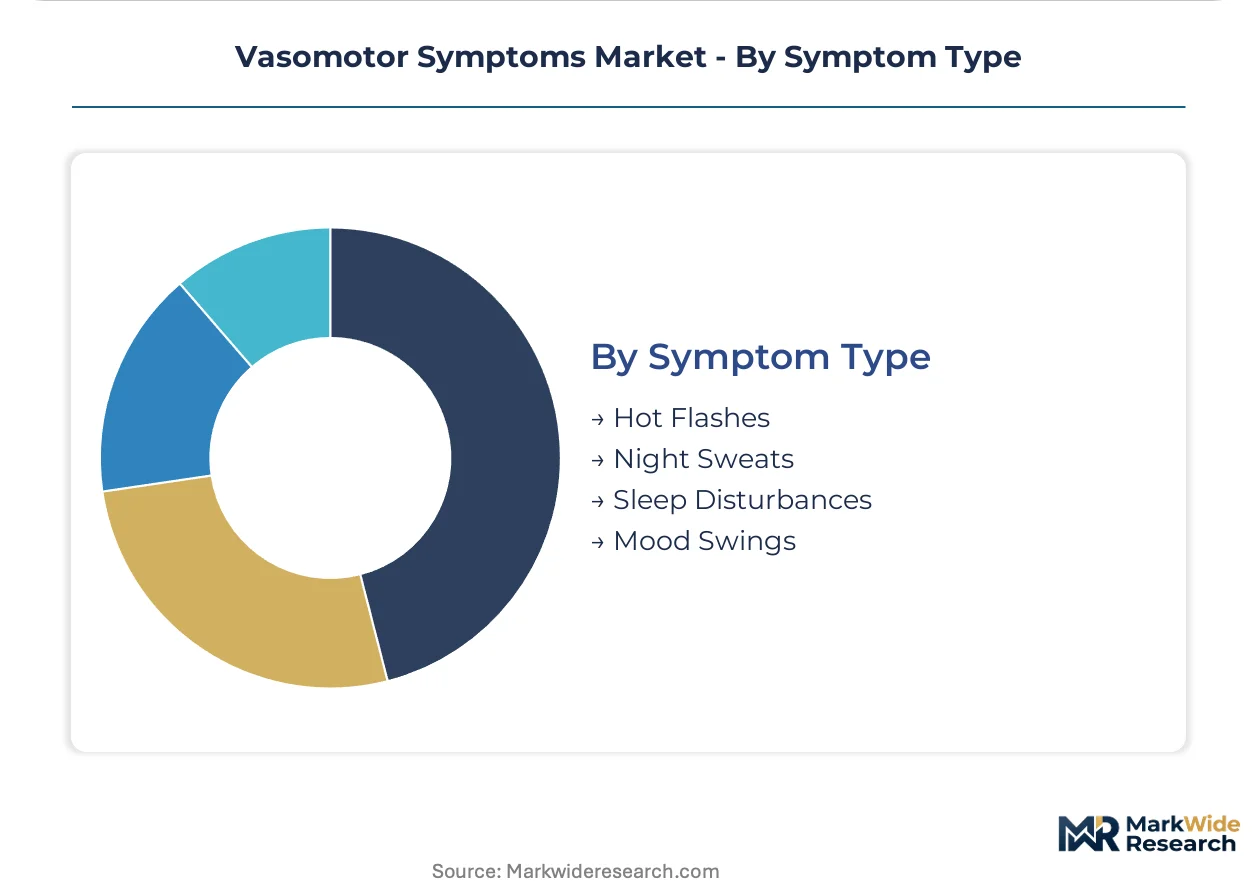
Hot Flashes sit at the top of the volume ranking, with Night Sweats climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German urban hospital networks concentrate menopausal specialty services more aggressively than United States gynecology clinics, creating divergent prescription volume capture strategies across these two markets.
United States
Telehealth synchronous video platforms expand prescriptive authority for non-controlled substances, capturing peri-menopausal patients in rural catchment areas. FDA safety labeling requirements for menopausal hormone products reshape clinical trial design and post-market surveillance obligations. Gynecology clinics across metropolitan networks are consolidating menopausal specialty services, creating captive prescription volumes that pharmaceutical manufacturers prioritize for pilot program deployment.
Germany
Urban hospital networks concentrate menopausal specialty services, generating captive prescription volumes for antidepressant alternatives to oral hormones. EMA MDR framework and REACH compliance standards govern biologic patch materials and active pharmaceutical ingredient purity across European manufacturing. Munich and Berlin regulatory clusters process technical documentation submissions with variable throughput, creating competitive advantage for firms with established regulatory affairs presence.
Japan
PMDA guidelines influence clinical trial endpoint selection for non-hormonal therapeutic candidates targeting vasomotor symptoms. METI industrial policy supports domestic pharmaceutical manufacturing capacity for hormone delivery systems. The Kanto region around Tokyo anchors specialist gynecology practice networks that drive initial diagnosis and treatment initiation patterns.
United Kingdom
NHS reimbursement frameworks prioritize cost-effective hormone replacement therapy formulations while evaluating emerging non-hormonal alternatives. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for novel menopausal therapies. The London-Southeast corridor concentrates specialist menopause clinics that generate referral volumes influencing national prescribing guidelines.
Canada
Health Canada biologic standards and WHO prequalification programs influence parallel import pathways for generic hormone formulations. Provincial formularies exhibit variable coverage for transdermal patch delivery systems relative to oral alternatives. Ontario and Quebec health systems anchor specialist gynecology networks that drive regional prescription pattern variation.
Vasomotor Symptoms Market Key Industry Players
Top-tier vendors anchor hormone replacement therapy through established reimbursement pathways, while mid-tier specialists pursue neurokinin-3 receptor antagonist development. The market structure reflects consolidation around endocrinology infrastructure and manufacturing scale, with fragmentation emerging in non-hormonal mechanism categories. Three archetypes dominate: legacy pharmaceutical conglomerates with distribution network depth, biotech ventures with accelerated approval designations, and regional specialists with urology-gynecology crossover positioning. Competitive moves concentrate on direct-to-clinic channel investments and real-world evidence infrastructure for pharmacovigilance reporting.
Among the named players, Eli Lilly and Company and Pfizer Inc. represent the scale-driven archetype with endocrinology infrastructure and North American distribution network dominance. Astellas Pharma occupies a position exemplifying the urology-gynecology crossover specialization vector in Asian markets. These three anchors illustrate how geographic origin and stated therapeutic focus map onto distinct competitive positioning strategies without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Allergan |
| Bayer AG |
| Nerre Therapeutics Ltd. |
| Mithra Pharmaceuticals |
| Astellas Pharma |
| Novartis AG |
| Mitsubishi Tanabe Pharma |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
United States gynecology clinic networks concentrate prescription volumes for branded hormone formulations, anchoring a subscription-based pricing model that pharmaceutical manufacturers deploy to capture lifetime patient value beyond initial prescription fulfillment. German urban hospital procurement committees negotiate transdermal patch contracts under EMA MDR compliance cost pass-throughs, fragmenting price uniformity across Atlantic markets.
Pricing Analysis
Capacity additions in Asian manufacturing zones are reshaping price floors for biologic patch adhesives and active pharmaceutical ingredients. Three-tier pricing structure across premium transdermal systems, standard oral generics, and economy parallel-import alternatives separates patients by hepatic risk profiles and reimbursement tier. Cost compression in European transdermal manufacturing intensifies because REACH compliance documentation inflates qualification timelines. Price-sensitive buyers cluster in generic-substitution environments with WHO prequalification-enabled parallel imports, while premium-insured populations in United States metropolitan markets exhibit lowest sensitivity.
Supply Chain Analysis
Specialized polymer chemist and regulatory affairs talent shortages in Munich and Berlin clusters constrain European biologic patch qualification throughput. Active pharmaceutical ingredient manufacturing concentrates in India, China, and United States pharmaceutical corridors. Transdermal patch production draws from specialty polymer substrates, estrogen and progesterone APIs, and medical-grade adhesives. Single-source vulnerability persists for neurokinin-3 receptor antagonist precursors. Distribution runs through direct-to-clinic channels in United States metropolitan networks and consolidated hospital procurement systems in German urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vasomotor Symptoms Market compounds steadily as peri-menopausal population demographics expand across developed economies, creating durable demand for both hormonal and non-hormonal therapeutic modalities. FDA accelerated approval pathways for novel mechanisms compress development timelines and attract sustained venture deployment.
For Market Incumbents: Cement formulary relationships through real-world evidence infrastructure investments that satisfy evolving pharmacovigilance reporting thresholds. Deepen backward integration into biologic patch polymer manufacturing to offset EMA MDR qualification cost inflation. Channel control through direct-to-clinic investments defends against telehealth platform disintermediation threatening traditional gynecology gatekeeper relationships. For New Entrants and Emerging Players: FDA accelerated approval designations in the United States open a window for neurokinin-3 receptor antagonist platforms to capture prescriber attention before incumbent label expansion. Target rural and underserved United States catchment areas where synchronous video telehealth platforms have removed geographic access barriers. Deploy patient-initiated switching campaigns through direct-to-consumer digital marketing to bypass established clinic formulary controls. For Investors and Strategic Acquirers: Large-cap pharmaceutical conglomerates with endocrinology infrastructure are the most active acquirer in this space, seeking pipeline diversification beyond mature hormone combinations. Mid-tier biotech ventures holding accelerated approval designations represent the optimal acquisition target archetype. Watch for FDA safety labeling changes that prompt prescriber reassessment of first-line options and trigger replacement demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Wearable core temperature monitoring devices generate objective efficacy data satisfying FDA safety labeling requirements. |
| Regulatory Approval Pathway | Accelerated approval designations compress development timelines for neurokinin-3 receptor antagonist platforms. |
| Manufacturing Scale-Up | EMA MDR technical documentation requirements force reformulation investments across European manufacturing footprints. |
| Pipeline Diversification | Non-hormonal therapeutic pipelines redirect clinical investment away from traditional estrogen-progesterone combinations. |
| Reimbursement Strategy | Subscription-based patient monitoring programs create lifetime value capture beyond initial prescription fulfillment. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and formulary directors; secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov records; and bottom-up prescription volume modeling reconciled against top-down epidemiological projections — were synthesized to construct market estimates. Conversations with hospital procurement managers and payer access specialists informed reimbursement pathway dynamics. Formulary databases and CMS Medicare data provided secondary anchor points.
Data-stream reconciliation across treatment line, delivery mode, end-user channel, and regional regulatory cluster dimensions produced volume and value outputs throughout the forecast period. CAGRs were derived from segmented growth trajectory analysis. Patient demographic shifts, prescriber specialty training patterns, and telehealth platform expansion rates served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA safety labeling revisions or EMA MDR documentation requirement amendments. Material deviation in accelerated approval pathway availability or telehealth synchronous video prescription authority expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Malabsorption Syndrome Market